
 Saudi Arabia Wearable and Audio Devices Market | 2026-2036
Saudi Arabia Wearable and Audio Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Wearable and Audio Devices Market Analytics
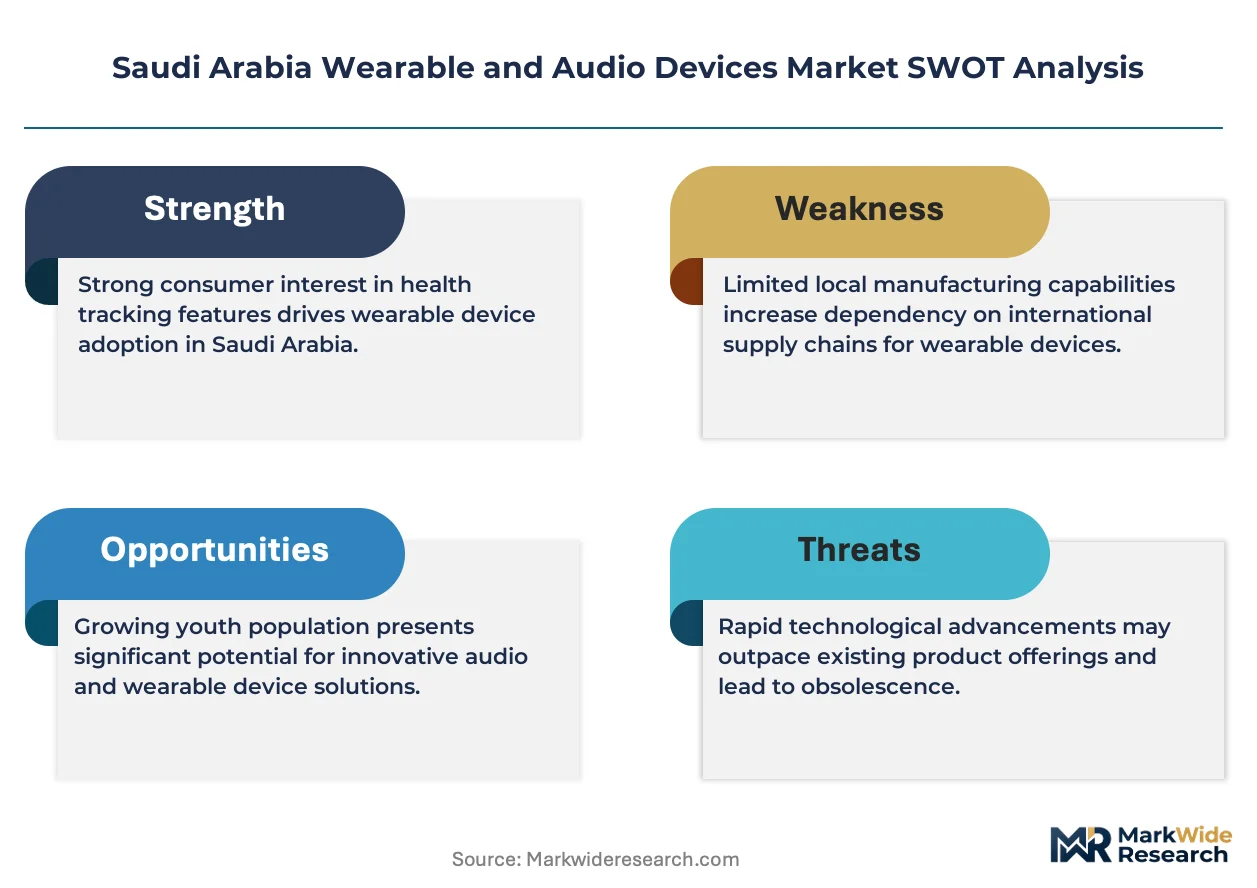
Electronics retail channels in Saudi Arabia is narrowing as e-commerce platforms capture higher-margin wearable transactions. Samsung Electronics Co Ltd anchors its position through deep integration with Android ecosystems across Gulf markets. Apple Inc differentiates via health-monitoring APIs that attract hospital system procurement. Huawei Technologies Co Ltd navigates trade restrictions by emphasizing localized software partnerships within the Kingdom.
Saudi Arabia wearable and audio devices encompass wrist-worn biometric sensors, in-ear acoustic transducers, and wireless neckband systems operating on Bluetooth Low Energy protocols with typical power consumption below 10 milliamps. These instruments serve continuous physiological monitoring, immersive media consumption, and hands-free communication for mobile-first populations. Smartwatches command the largest revenue pool due to premium average selling prices tied to sapphire crystal displays and medical-grade heart rate variability algorithms. Earbuds represent the fastest-expanding volume category as true wireless stereo chipsets displace wired alternatives among commuters and gym users. Fitness trackers retain durable demand among price-sensitive segments seeking step-count accuracy without subscription dependencies.
Saudi Standards, Metrology and Quality Organization (SASO) mandates electromagnetic compatibility testing for all wireless wearables prior to commercial distribution. The Communications and Information Technology Commission (CITC) regulates radio frequency allocations that constrain antenna design and transmission power thresholds. SFDA oversight extends to devices claiming clinical diagnostic functions, requiring substantiation of blood oxygen or electrocardiogram accuracy claims. Stakeholders must monitor evolving interoperability mandates between hospital information systems and consumer-grade biometric hardware.
Market Dynamics
SASO electromagnetic compatibility mandates and CITC radio frequency regulations are compressing product development timelines while elevating compliance costs for new market entrants.
Growth Catalysts
- SFDA clinical diagnostic oversight:Substantiation requirements for blood oxygen and ECG accuracy claims create defensible moats for certified manufacturers serving hospital procurement channels.
- Fitness-focused lifestyles in Riyadh and Jeddah:Young consumers prioritize biometric monitoring capabilities that integrate with mobile health applications and gym management systems.
- Bluetooth Low Energy protocols:Sub-10 milliamp power consumption standards enable multi-day battery life that sustains continuous physiological monitoring without daily recharging interruptions.
Market Restraints
- Sapphire crystal display input costs:Premium smartwatch face materials contribute disproportionately to bill-of-materials inflation that constrains mid-tier pricing flexibility.
- Antenna design constraints:CITC transmission power thresholds limit signal range and indoor penetration, degrading user experience in concrete-dense urban developments.
- Wired audio substitution persistence:Audiophile and professional studio segments continue favoring cabled connections for latency-critical applications, slowing total wireless conversion.
Strategic Opportunities
- Eastern Province industrial zones:Manufacturing clusters near Jubail and Dammam offer proximity to Gulf logistics corridors for regional export positioning.
- Hospital information system interoperability:Evolving mandates for consumer-grade biometric hardware integration with institutional EMR platforms create enterprise sales channels.
- True wireless stereo chipset convergence:Advanced acoustic processing and active noise cancellation integration enables premium feature migration into mid-price earbuds.
Industry Challenges
- Medical-grade algorithm validation:Heart rate variability accuracy requirements demand specialized biostatistical expertise scarce in regional talent pools.
- Legacy retail channel compression:Electronics storefront contraction accelerates working capital pressure on distributors adapting to platform-centric fulfillment models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Wearable and Audio Devices Market |
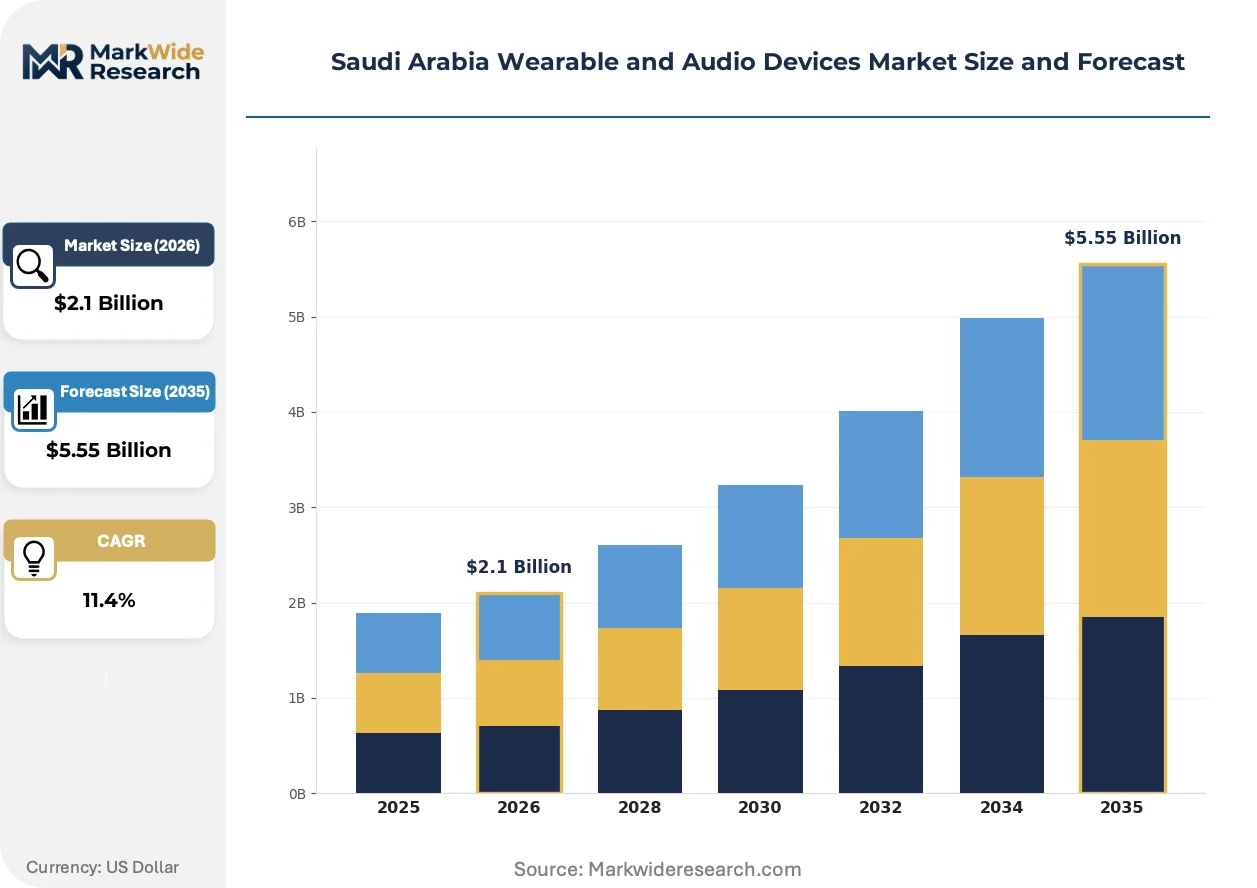
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Smartwatches, Earbuds, Fitness Trackers, Headphones Distribution Channel: Online Retail, Specialty Stores, Electronics Outlets, Department Stores Technology: Bluetooth, NFC, Wi-Fi, GPS End User: Consumers, Sports Enthusiasts, Healthcare Professionals, Gamers |
| Companies Covered | Garmin Inc, Samsung Electronics Co Ltd, United Matbouli Group, Nike Inc, Polar Electro Oy, Apple Inc, Fitbit Inc, Sony Corporation, Huawei Technologies Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Wearable and Audio Devices Market Evolving Landscape
Medical-grade sensor miniaturization and localized software partnerships are redefining competitive differentiation beyond hardware specifications in the Kingdom's wearable ecosystem.
Photoplethysmography sensors with clinical-grade signal-to-noise ratios now enable continuous blood pressure estimation without cuff inflation. Healthcare professionals in cardiology departments are piloting these capabilities for remote patient monitoring protocols. Conventional ambulatory blood pressure monitors are rendering obsolete for lifestyle management applications.
CITC device certification standards now mandate specific electromagnetic compatibility testing protocols prior to commercial distribution authorization. Manufacturers must redesign antenna architectures and shielding configurations to meet revised radio frequency allocation tables. Smartwatch categories with cellular connectivity face the steepest compliance timeline extensions.
Platform-centric fulfillment now dominates higher-margin wearable transactions previously captured by mall-based electronics retailers. Sports enthusiasts and healthcare professionals increasingly discover products through algorithmic recommendation engines rather than in-store demonstration. Riyadh and Jeddah metropolitan areas exhibit the most pronounced channel migration velocity.
Saudi Arabia Wearable and Audio Devices Market Segmentation
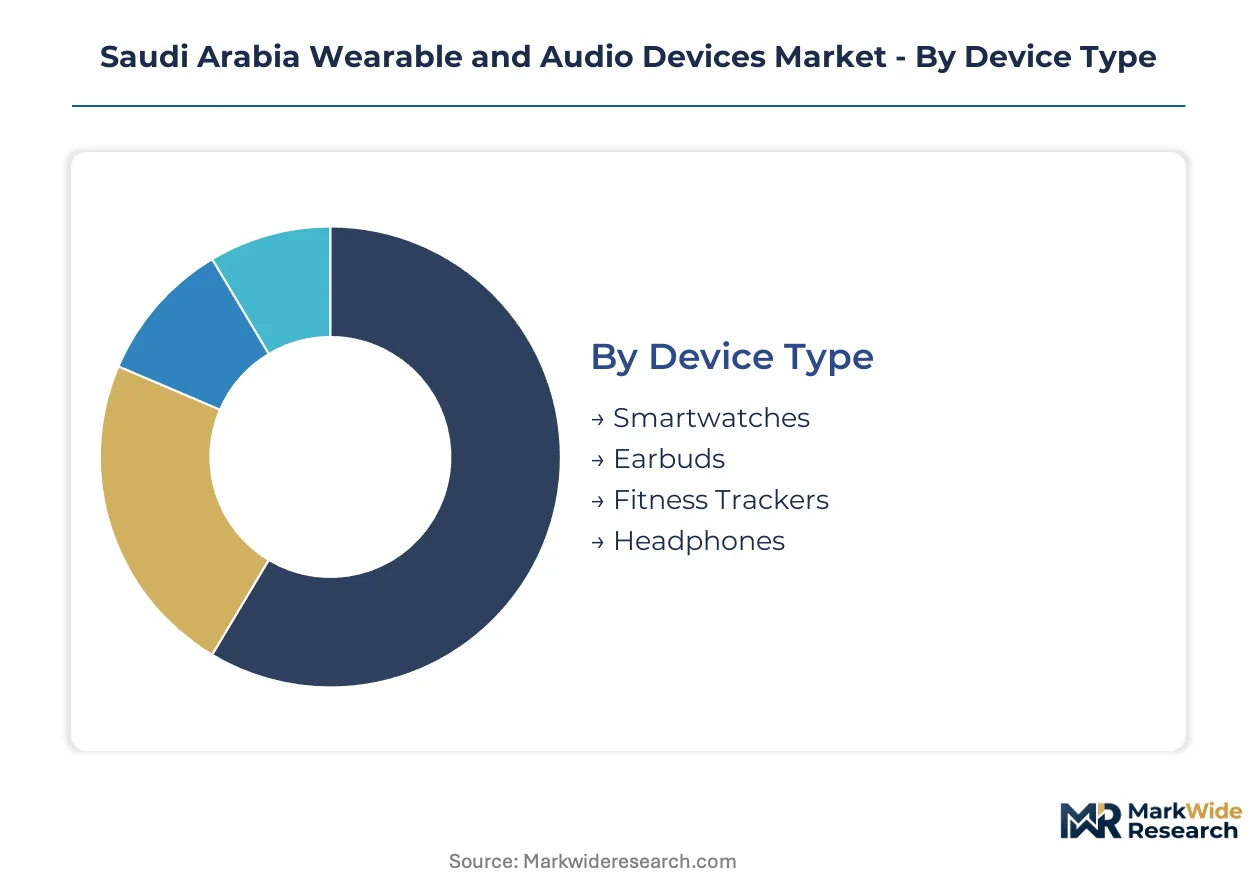
Segmentation patterns in Saudi Arabia's wearable and audio devices market reveal distinct service intensity profiles across hardware categories. After-sales support requirements vary dramatically between medical-grade smartwatches requiring calibration services and disposable earbuds with minimal touchpoints.
Device Type:
After-sales-service intensity escalates with clinical functionality, creating divergent margin structures across hardware tiers.
- Smartwatches:Sapphire crystal displays and medical-grade heart rate variability algorithms command premium average selling prices. Demand concentrates among healthcare professionals in Riyadh hospital systems seeking SFDA-certified diagnostic capabilities for remote patient monitoring protocols.
- Earbuds:True wireless stereo chipsets with sub-10 milliamp power consumption enable multi-day battery life. Sports enthusiasts in Jeddah fitness centers drive volume adoption for gym-integrated biometric tracking without subscription dependencies.
- Fitness Trackers:Step-count accuracy sensors serve price-sensitive segments seeking basic physiological monitoring without cellular connectivity premiums.
- Headphones:Active noise cancellation acoustic processing targets commuters and audiophile segments prioritizing immersive media consumption over biometric functions.
By volume, earbuds lead. By growth pace, smartwatches are ahead.
Distribution Channel:
Margin compression intensity separates platform-centric fulfillment from brick-and-mortar operations with fixed overhead burdens.
- Online Retail:Algorithmic recommendation engines capture higher-margin transactions previously dominated by mall-based electronics retailers. Riyadh and Jeddah metropolitan areas exhibit the most pronounced channel migration velocity among sports enthusiasts and healthcare professionals.
- Specialty Stores:In-store demonstration capabilities retain relevance for medical-grade device categories requiring hands-on calibration verification.
- Electronics Outlets:Working capital pressure accelerates as storefront contraction reduces foot traffic for mid-tier wearable categories.
- Department Stores:Impulse purchase positioning serves gift-market demand for entry-level fitness trackers and wireless neckband systems.
By transaction volume, online retail dominates. By margin preservation, specialty stores hold advantage.
Technology:
Power consumption profiles determine battery architecture costs and regulatory testing scope under CITC electromagnetic compatibility mandates.
- Bluetooth:Low Energy protocols operating below 10 milliamps sustain continuous physiological monitoring without daily recharging interruptions. Bluetooth anchors the dominant connectivity standard across wrist-worn and in-ear form factors.
- NFC:Contactless payment authentication enables mobile wallet integration for transit and retail applications in Riyadh and Jeddah urban corridors.
- Wi-Fi:Direct cloud synchronization bypasses smartphone tethering for standalone smartwatch categories with cellular connectivity premiums.
- GPS:Precise location tracking serves outdoor fitness segments and emergency response protocols for elderly monitoring applications.
By installed base, Bluetooth leads. By feature migration speed, NFC is climbing the fastest.
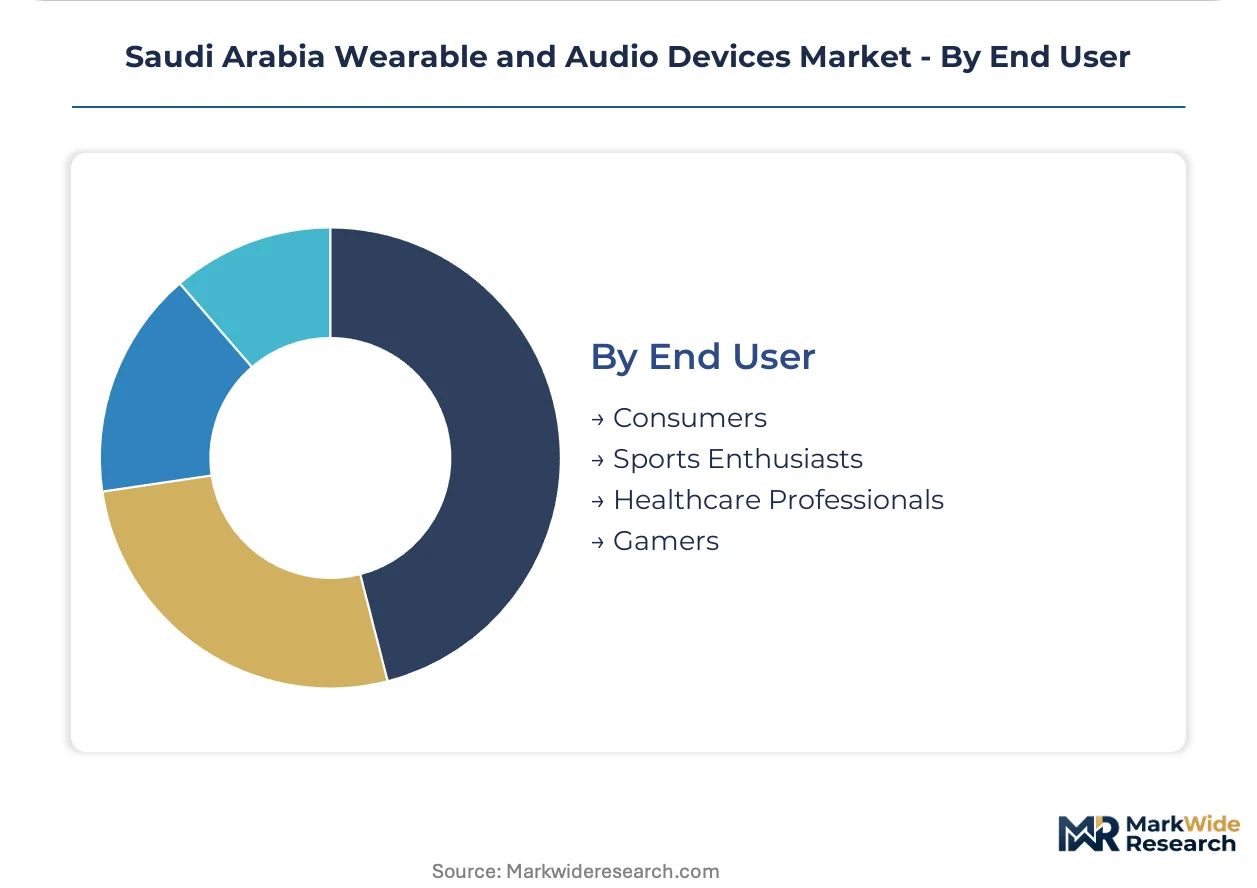
End User:
Procurement authority concentration varies sharply between institutional hospital buyers and dispersed consumer decision-making.
- Consumers:Mobile-first populations in Riyadh and Jeddah prioritize seamless ecosystem integration with Android and iOS platforms for media consumption and hands-free communication.
- Sports Enthusiasts:Gym management system integration drives demand for continuous heart rate variability monitoring during high-intensity interval training protocols.
- Healthcare Professionals:Cardiology departments pilot photoplethysmography sensors with clinical-grade signal-to-noise ratios for remote blood pressure estimation without cuff inflation.
- Gamers:Low-latency audio transmission requirements sustain wired connection preference for competitive esports applications despite wireless conversion trends.
By absolute volume, consumers lead. By average selling price expansion, healthcare professionals are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh commands pricing premiums for SFDA-certified diagnostic wearables that Eastern Province distributors cannot match. Western Region consumers absorb higher logistics costs for premium audio imports. NEOM's experimental regulatory sandbox creates localized price distortions for next-generation biometric hardware.
Riyadh
Hospital procurement networks concentrate demand for medical-grade smartwatches with photoplethysmography sensors. The Communications and Information Technology Commission enforces electromagnetic compatibility testing timelines that delay product launches. King Abdullah Financial District anchors pilot programs for NFC-enabled wearable payments in corporate wellness schemes.
Eastern Province
Industrial workforce monitoring drives adoption of ruggedized fitness trackers for occupational safety compliance. SASO mandates electromagnetic compatibility certification for all Bluetooth Low Energy devices prior to Jubail port clearance. Dammam logistics corridors position distributors for re-export into Bahrain and Kuwait markets.
Western Region
Pilgrimage-season demand spikes for multilingual audio guides and location-tracking wearables during Hajj and Umrah periods. SFDA oversight extends to devices claiming clinical diagnostic functions for elderly pilgrim monitoring. Jeddah Islamic Port customs processing creates inventory bottlenecks for seasonal product launches.
NEOM Northwest
Experimental smart city infrastructure enables early deployment of standalone cellular wearables bypassing smartphone tethering. CITC operates a regulatory sandbox with streamlined radio frequency allocation procedures for pilot programs. THE LINE linear city construction sites test industrial-grade biometric monitoring for worker safety protocols.
Saudi Arabia Wearable and Audio Devices Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensor modules and acoustic transducers. The vendor base clusters around three strategic archetypes: ecosystem-locked premium brands, price-aggressive volume manufacturers, and niche specialists in medical-grade diagnostics. Samsung Electronics Co Ltd and Apple Inc anchor the premium tier through deep Android and iOS integration. Competitive intensity concentrates on M&A activity targeting biostatistical algorithm startups and strategic partnerships with hospital information system vendors.
Among the named players, Samsung Electronics Co Ltd and Apple Inc exemplify ecosystem-locked platform integrators commanding premium average selling prices through sapphire crystal displays and health-monitoring APIs. Huawei Technologies Co Ltd occupies a position navigating trade restrictions via localized software partnerships. Garmin Inc and Polar Electro Oy represent specialists in medical-grade heart rate variability algorithms serving cardiology department procurement channels. United Matbouli Group anchors regional distribution infrastructure for multinational brands seeking CITC compliance support.
| Leading Market Players |
|---|
| Garmin Inc |
| Samsung Electronics Co Ltd |
| United Matbouli Group |
| Nike Inc |
| Polar Electro Oy |
| Apple Inc |
| Fitbit Inc |
| Sony Corporation |
| Huawei Technologies Co Ltd |
| Others |
Value Network & Pricing Analysis
Jeddah Islamic Port customs processing corridors impose inventory carrying cost premiums that cascade through distributor pricing tiers, concentrating margin capture among CITC-certified incumbents while fragmenting price-setting authority for new entrants seeking SFDA diagnostic certification.
Pricing Analysis
The customization-premium spread between standard Bluetooth Low Energy wearables and SFDA-certified diagnostic configurations exceeds threefold, with sapphire crystal display grades and medical-grade heart rate variability algorithms commanding the widest differentials. Pricing stratifies across premium, standard, and economy tiers based on certification level and after-sales calibration bundling. Cost compression in mid-tier earbuds is intensifying because true wireless stereo chipset commoditization erodes hardware differentiation. Healthcare professionals in Riyadh hospital systems exhibit the lowest price sensitivity, while fitness tracker buyers in Jeddah fitness centers resist subscription-dependent models.
Supply Chain Analysis
Tariff exposure between China and Saudi Arabia dominates supply chain risk calculations for antenna module and photoplethysmography sensor procurement. Component sourcing concentrates in China, South Korea, and Taiwan for Bluetooth chipsets, display panels, and acoustic transducers. Raw material dependencies include lithium-ion battery cells, sapphire crystal substrates, and medical-grade silicone housings. Single-source vulnerability persists for clinical-grade signal processing algorithms. Distribution runs through United Matbouli Group's CITC compliance infrastructure and platform-centric fulfillment networks serving Riyadh and Jeddah metropolitan demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA clinical diagnostic oversight is accelerating market disruption by erecting certification barriers that favor algorithm-validated incumbents over hardware-assemblers, compressing viable competitive positions to ecosystem-locked premium brands and medical-grade specialists.
For Market Incumbents: Pre-empt algorithm commoditization by acquiring biostatistical validation capabilities from regional talent pools and deepening backward integration into photoplethysmography sensor module production. Anchor hospital information system interoperability investments to defend procurement channel access against emerging platform-agnostic entrants.
For New Entrants and Emerging Players: Eastern Province industrial workforce monitoring presents the most penetrable white-space, with occupational safety compliance mandates creating institutional demand for ruggedized fitness trackers absent premium brand saturation. Pursue SASO electromagnetic compatibility certification as the primary go-to-market enabler for Jubail and Dammam logistics corridor positioning.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational consumer electronics parents seeking to divest non-core wearable divisions lacking SFDA clinical validation infrastructure. Long-term viability hinges on sustained hospital procurement channel access rather than consumer volume scale. Watch CITC regulatory sandbox expansion signals at NEOM as the inflection indicator for next-generation cellular wearable deployment economics.
| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Diagnostic Certification Investment | Creates defensible procurement moats in Riyadh hospital systems requiring blood oxygen accuracy substantiation. |
| Hospital Information System Partnership | Enables enterprise sales channels through EMR platform interoperability mandates for consumer-grade biometric hardware. |
| Localized Software Partnership | Navigates trade restriction headwinds via Kingdom-specific application ecosystem integration. |
| Photoplethysmography Sensor Module Acquisition | Secures upstream control over clinical-grade signal-to-noise ratio components for remote patient monitoring protocols. |
| Eastern Province Distribution Expansion | Positions for re-export into Bahrain and Kuwait markets through Dammam logistics corridor infrastructure. |
Research Methodology
Desk research of CITC device certification databases, SFDA clinical validation registries, and SASO electromagnetic compatibility standards preceded structured interviews with hospital procurement managers, biomedical engineers at Riyadh cardiology departments, fitness center operators in Jeddah, and electronics distribution executives. Primary fieldwork with these stakeholders combined with secondary validation against customs clearance records and platform transaction data. Bottom-up demand modeling and top-down supply capacity estimates were triangulated to derive market sizing.
Assumptions regarding CITC radio frequency allocation stability and SFDA clinical diagnostic oversight stringency were held fixed across the projection horizon, while Bluetooth Low Energy power consumption trajectories and true wireless stereo chipset cost curves were varied. Segmentation dimensions modeled include device type, distribution channel, connectivity technology, and end-user procurement authority. CAGRs were computed from annual value progression across hardware tiers. Forecast inputs incorporated hospital information system interoperability mandate timelines and NEOM regulatory sandbox expansion signals.
Practitioners should monitor CITC electromagnetic compatibility testing backlog durations and SFDA algorithm validation queue lengths for early signals of market entry friction. Forecasts reflect these documented assumptions regarding regulatory processing capacity and certification cost trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Systems and Devices
Microelectromechanical System (MEMS) Market
Electronic Systems and Devices
Vacuum Pulse System Market
Electronic Systems and Devices
Radio Dot System (RDS) Market
Electronic Systems and Devices
Global Embedded Systems Market
Electronic Systems and Devices
Electronic Prototyping Market
Electronic Systems and Devices
Nanoelectromechanical Systems (NEMS) Market
Electronic Systems and Devices
Cold Start System Market
Electronic Systems and Devices
Cognitive Systems Spending Market
Electronic Systems and Devices
Electronic-Nose Market
Electronic Systems and Devices
Embedded Computing Systems Market
Electronic Systems and Devices
Sound Reception System Market
Electronic Systems and Devices
AI Computing Hardware Market
Electronic Systems and Devices
Resist Strip System Market
Electronic Systems and Devices
Global Electronic Contract Assembly Market
Electronic Systems and Devices
Electronic Tongue Market
Electronic Systems and Devices
Embedded Controllers Market