
 Global Electronic Contract Assembly Market | 2026-2036
Global Electronic Contract Assembly Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electronic Contract Assembly Market Foresight
Aftermarket service revenue is reshaping margin distribution across the electronic contract assembly value chain. Foxconn Technology Group leverages its manufacturing scale to capture high-volume PCB assembly programs for consumer electronics brands. Jabil Inc. anchors its competitive position through deep specialization in healthcare and automotive electronics with stringent quality protocols. Flex Ltd. differentiates by controlling design-to-delivery workflows across aerospace systems and industrial automation verticals.
Electronic contract assembly encompasses the outsourced fabrication and integration of printed circuit boards, cable harnesses, and complete electromechanical enclosures according to customer specifications, typically involving surface mount technology placement accuracies below 50 microns and automated optical inspection protocols to ensure functional reliability. The primary commercial purpose is enabling original equipment manufacturers to convert fixed production costs into variable spend while accessing specialized manufacturing competencies. PCB Assembly occupies the largest revenue pool due to its ubiquity across virtually all electronic end products, while Testing Services commands premium margins as regulatory complexity intensifies in aerospace systems and defense electronics. Box Build Assembly is gaining share as OEMs push complete system integration risk onto contract partners.
EPA regulations governing hazardous substance restrictions in electronics, REACH chemical compliance protocols administered by ECHA, and FDA quality system requirements for medical device contract manufacturers collectively elevate operational barriers for new entrants. These frameworks shape demand by mandating traceability systems, restricted material substitutions, and validated manufacturing processes that favor established providers with compliance infrastructure. Stakeholders must monitor how divergent regional regulatory timelines affect capacity allocation decisions across multi-site manufacturing networks.
Market Dynamics
Automotive OEMs are converting fixed assembly infrastructure into variable spend as EV platforms multiply SKUs and compress product lifecycles, forcing contract manufacturers to absorb integration risk while maintaining traceability across multi-tier supplier networks.
Growth Catalysts
- Vehicle Electrification Mandates:NHTSA fuel economy standards and EPA emissions rules in the US are compelling automotive OEMs to outsource power electronics assembly to specialists with validated thermal management processes.
- REACH Chemical Compliance:ECHA enforcement of restricted substance protocols across Europe is disqualifying in-house assembly operations lacking material traceability systems, redirecting volume toward certified contract partners.
- Vietnam Manufacturing Expansion:Electronics brands are establishing captive capacity in northern industrial zones to diversify beyond China-dominant supply configurations and mitigate tariff exposure.
Market Restraints
- Substrate Material Volatility:Copper-clad laminate and advanced resin prices fluctuate with energy costs, compressing margins for mid-tier PCB assembly providers locked into annual customer contracts.
- Concentrated Component Sourcing:Advanced semiconductor packaging substrates depend on Taiwan and South Korea suppliers, creating geographic chokepoints that amplify disruption risk across automotive and aerospace programs.
- RoHS Substitution Limits:Lead-free solder alternatives impose higher reflow temperatures that stress component reliability, restricting process windows for high-density interconnect boards in medical devices.
Strategic Opportunities
- Mexico Nearshoring Acceleration:Electronics OEMs are qualifying contract assembly sites in Guadalajara and Tijuana to serve US demand with reduced logistics latency versus Asian supply chains.
- EU Battery Passport Mandates:CSRD disclosure requirements and proposed battery regulations are creating demand for assembly partners with embedded traceability software and blockchain-enabled component tracking.
- Industrial IoT Convergence:The intersection of edge computing hardware and predictive maintenance software is opening service-integrated assembly contracts for smart factory automation suppliers.
Industry Challenges
- IPC-A-610 Master Trainer Scarcity:Aerospace and defense programs require certified inspection personnel that command premium wages and extended recruitment cycles, constraining capacity expansion timelines.
- Cleanroom Capex Burden:FDA quality system requirements for medical device assembly mandate ISO 8 or better environments with continuous particle monitoring, requiring multi-million dollar facility investments that strain mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electronic Contract Assembly Market |
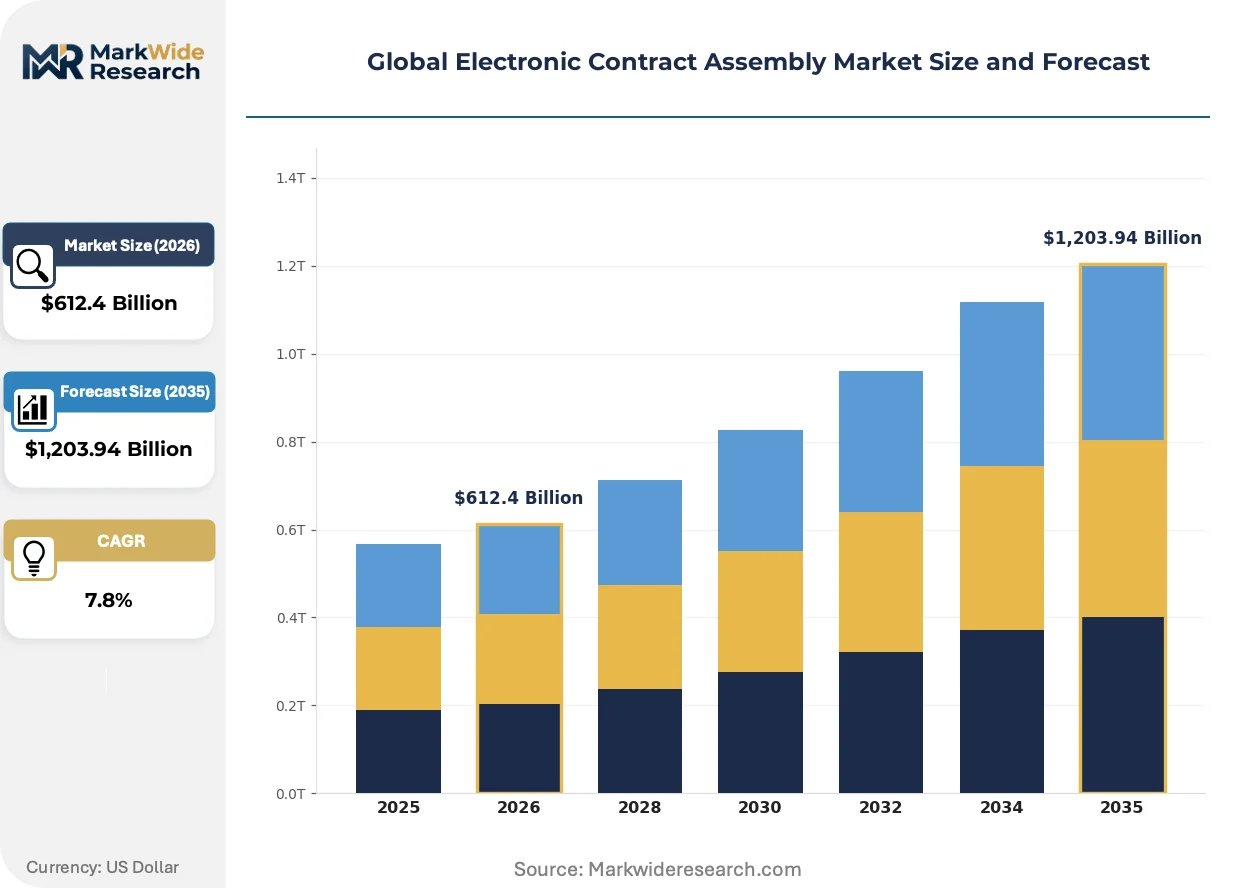
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $1,203.94 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: PCB Assembly, Box Build Assembly, Cable Harnessing, Testing Services, Prototyping Technology: Surface Mount Technology, Through-Hole Technology, Mixed Technology, Automated Optical Inspection, Functional Testing Application: Consumer Electronics, Telecommunications Equipment, Aerospace Systems, Industrial Automation, Defense Electronics End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, System Integrators |
| Companies Covered | Foxconn Technology Group, Jabil Inc., Flex Ltd., Celestica Inc., Sanmina Corporation, Benchmark Electronics Inc., Plexus Corp., Kimball Electronics, Venture Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electronic Contract Assembly Market Shifts & Advancements
Assembly workflows are converging with digital quality systems and automated inspection protocols that compress defect detection cycles while generating compliance documentation in real time.
Automated optical inspection augmented with machine vision algorithms is digitizing defect classification and dimensional verification across high-density PCB populations. Medical device and automotive electronics buyers are mandating AOI integration at multiple process stages. This capability is digitizing quality assurance from a batch-sampling discipline into continuous in-line monitoring that reduces escape rates and audit preparation burden.
REACH authorization timelines for restricted substances are tightening substitution deadlines for flame retardants and plasticizers in cable harness assemblies. Electronics brands serving European markets must validate alternative chemistries through ECHA notification procedures before volume deployment. Medical device and industrial automation verticals are absorbing the highest compliance costs as they balance biocompatibility requirements against material availability constraints.
Aftermarket service revenue is unbundling from hardware procurement contracts as OEMs seek recurring income streams from installed electronics bases. Aviation and automotive buyers are negotiating separate service-level agreements for repair, refurbishment, and obsolescence management. This bifurcation is most pronounced in Germany and Japan, where industrial equipment operators prioritize uptime guarantees over upfront capital expenditure minimization.
Global Electronic Contract Assembly Market Segmentation
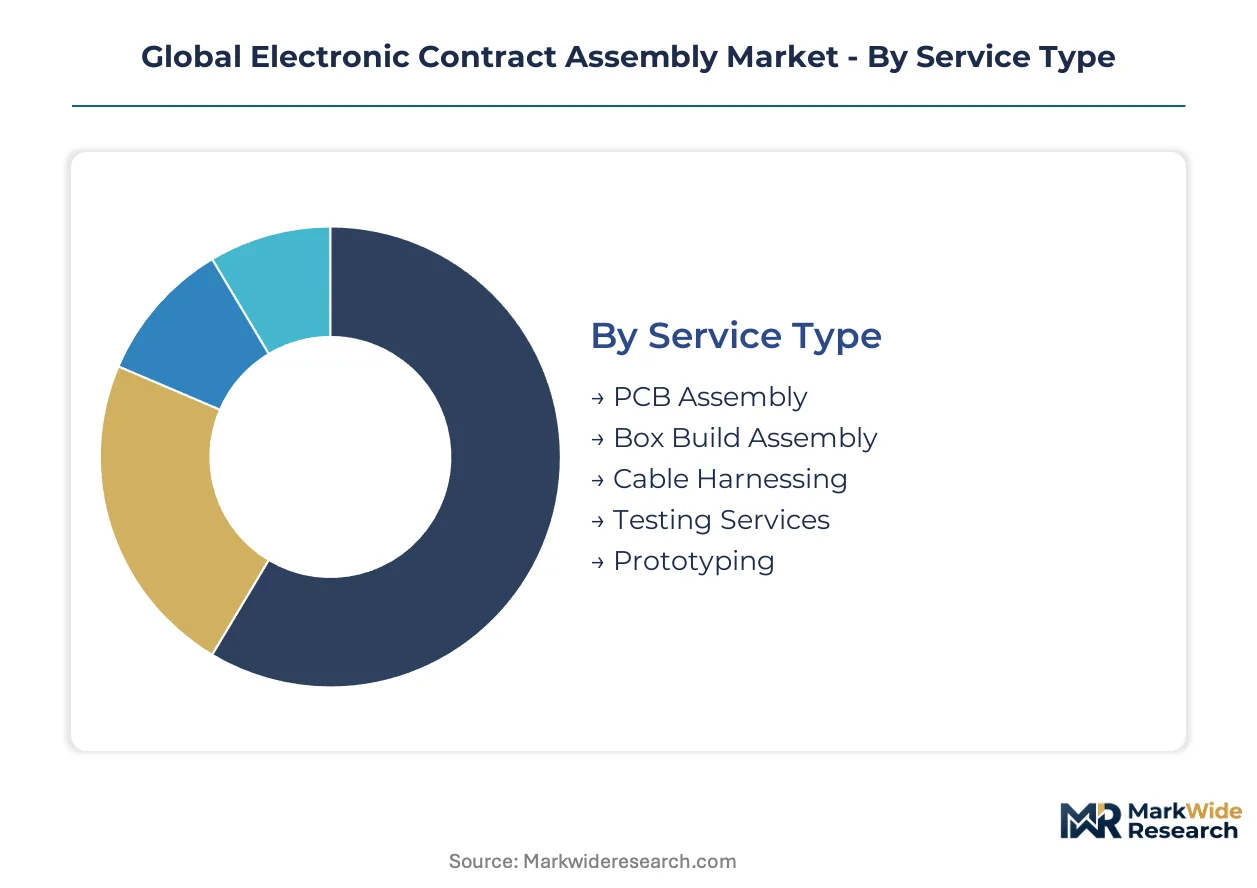
Segmentation in electronic contract assembly reveals how service intensity, technology sophistication, and end-use reliability requirements stratify provider capabilities and margin structures. Understanding these divisions exposes where aftermarket service revenue concentrates and which technology platforms command premium positioning.
Service Type:
Aftermarket service intensity varies dramatically across service categories, with repair and refurbishment programs creating recurring revenue streams that hardware-only contracts cannot match.
- PCB Assembly:Surface mount and through-hole fabrication of printed circuit boards with placement accuracies below 50 microns. Demand concentrates in automotive power electronics and medical device programs where FDA quality system requirements mandate validated thermal management processes and traceability systems.
- Testing Services:Functional verification, environmental stress screening, and regulatory compliance validation protocols. Aerospace systems and defense electronics buyers in Germany and Japan are mandating separate service-level agreements for continuous quality assurance, generating premium margins unavailable in standard assembly.
- Box Build Assembly:Complete electromechanical integration of enclosures, subassemblies, and system-level products. Industrial automation OEMs in Mexico and Vietnam are pushing integration risk onto contract partners to reduce fixed infrastructure exposure.
- Cable Harnessing:Fabrication of wire assemblies with validated crimp and termination processes. REACH chemical compliance in Europe is forcing material substitutions for flame retardants and plasticizers.
- Prototyping:Low-volume engineering validation builds with rapid turnaround requirements. Consumer electronics brands in Shenzhen and Seoul use prototyping services to compress product development cycles.
PCB Assembly holds the largest share; momentum sits with Testing Services.
Technology:
Cost tier stratification separates commodity placement equipment from precision platforms capable of automotive-grade reliability.
- Surface Mount Technology:Automated component placement on PCB substrates with high-speed pick-and-place systems. Telecommunications equipment manufacturers in Finland and South Korea specify SMT for 5G infrastructure builds requiring miniaturization and thermal performance.
- Through-Hole Technology:Manual or selective soldering of leaded components for high-reliability applications. Aerospace systems programs in France and the United States retain through-hole for mechanical stress tolerance in avionics.
- Mixed Technology:Hybrid assembly combining SMT and through-hole on single boards. Industrial automation controllers in Japan and Germany demand mixed technology for legacy component integration.
- Automated Optical Inspection:Machine vision-based defect detection with real-time classification algorithms. FDA-regulated medical device manufacturers mandate AOI at multiple process stages.
- Functional Testing:Electrical verification against design specifications with automated test equipment. Defense electronics programs require functional testing with documented traceability for audit compliance.
Surface Mount Technology dominates volume; Automated Optical Inspection is expanding most quickly as quality mandates tighten.
Application:
Volume concentration varies by application maturity, with emerging electrification platforms displacing established consumer electronics procurement patterns.
- Consumer Electronics:High-volume smartphone, tablet, and wearable assembly with compressed product lifecycles. Brands in Vietnam and Mexico are diversifying supply configurations to mitigate tariff exposure and logistics latency.
- Telecommunications Equipment:Base station, router, and optical network hardware assembly. 5G deployment timelines in India and Brazil are creating demand surges for qualified contract capacity.
- Aerospace Systems:Avionics, satellite, and unmanned vehicle electronics with IPC-A-610 Class 3 reliability standards. Certified inspection personnel scarcity constrains capacity expansion for Tier-1 suppliers in Toulouse and Seattle.
- Industrial Automation:Programmable logic controllers, robotics, and sensor systems. EU Battery Passport mandates are creating demand for assembly partners with embedded traceability software.
- Defense Electronics:Ruggedized systems with ITAR and EAR compliance requirements. Cleanroom capex burdens strain mid-cap balance sheets seeking FDA quality system alignment.
Consumer Electronics retains volume leadership; Industrial Automation shows the steepest expansion trajectory from IoT convergence.
End User:
Customer type determines contract structure, with OEMs converting fixed costs to variable spend while aftermarket providers capture recurring service revenue.
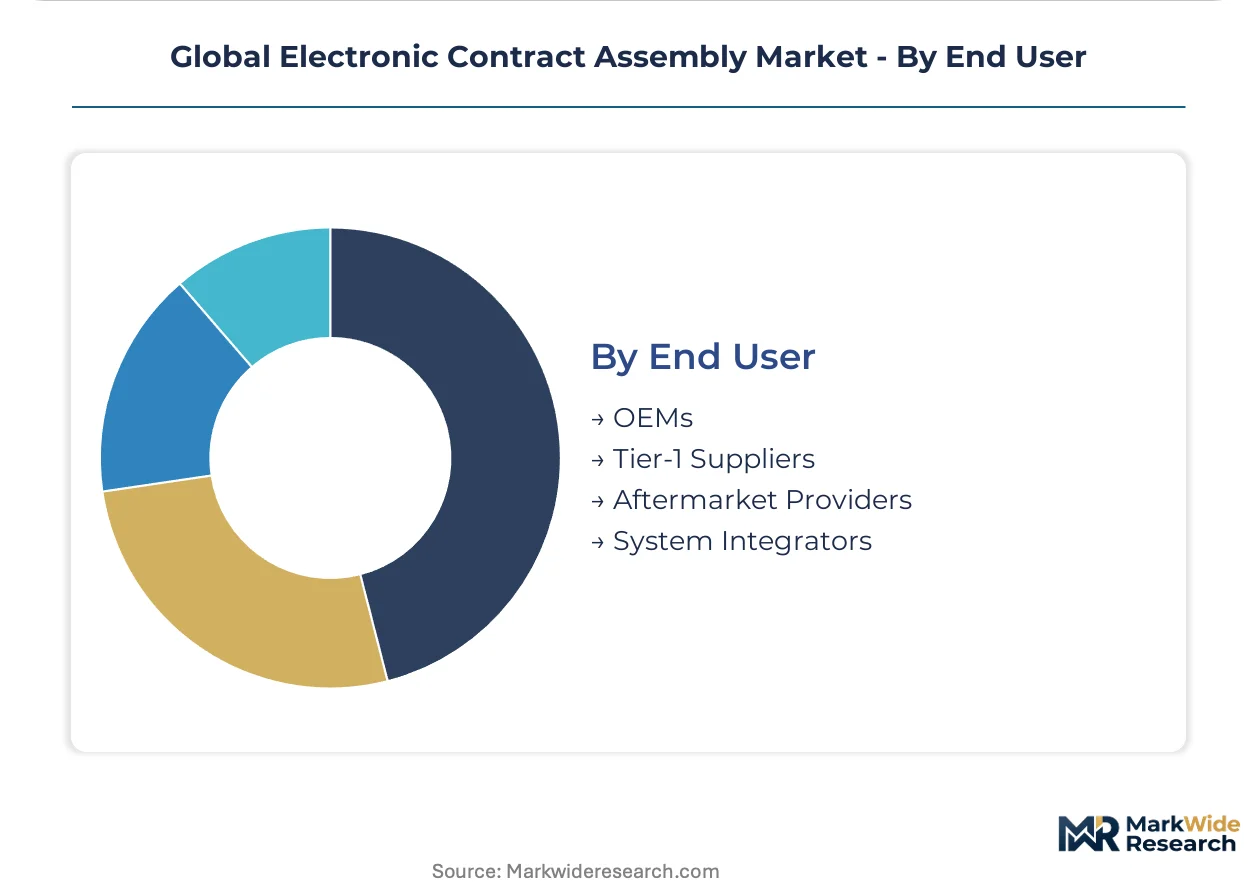
- OEMs:Original equipment manufacturers outsourcing entire production programs to convert fixed infrastructure into variable spend. Automotive OEMs in Stuttgart and Detroit are expanding outsourced assembly as EV platforms multiply SKUs.
- Tier-1 Suppliers:Direct automotive and aerospace subcontractors managing multi-tier supplier networks. Tier-1s in Guadalajara and Tijuana are qualifying nearshore capacity to serve US demand with reduced logistics latency.
- Aftermarket Providers:Independent service organizations capturing repair, refurbishment, and obsolescence management revenue. Aviation and automotive buyers in Germany and Japan prioritize uptime guarantees over upfront capital expenditure minimization.
- System Integrators:Engineering firms combining hardware procurement with software deployment and field service. Industrial IoT convergence is opening service-integrated assembly contracts for smart factory automation suppliers.
OEMs command the largest contract value; aftermarket providers are gaining share fastest as service revenue unbundles from hardware procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Vietnam and Mexico demonstrate the highest price elasticity as tariff-sensitive brands diversify supply chains, while aerospace and medical device purchasers in Germany and Japan absorb premium pricing for traceability assurance.
United States
Automotive OEMs in Detroit and Austin are outsourcing power electronics assembly for EV platforms as NHTSA fuel economy standards tighten. EPA hazardous substance restrictions elevate compliance costs for in-house operations. Contract manufacturers cluster in Silicon Valley and Greater Phoenix to serve defense electronics and semiconductor packaging demand.
Germany
Industrial automation OEMs in Stuttgart prioritize uptime guarantees over capital expenditure minimization, unbundling aftermarket service contracts from hardware procurement. ECHA REACH enforcement disqualifies uncertified assembly operations lacking material traceability. Bavaria hosts specialized providers serving medical device manufacturers with ISO 8 cleanroom capacity.
Vietnam
Consumer electronics brands establish captive capacity in northern industrial zones around Hanoi and Hai Phong to mitigate tariff exposure versus China-dominant configurations. The country's national electronics regulator enforces import substitution incentives for component sourcing. Samsung and Apple suppliers concentrate in Bac Ninh and Thai Nguyen provinces.
Mexico
Tier-1 automotive suppliers in Guadalajara and Tijuana qualify nearshore assembly sites to serve US demand with reduced logistics latency. Mexican environmental standards align with EPA electronics protocols for cross-border supply chain integration. Electronics manufacturing clusters expand across Baja California and Jalisco as OEMs convert fixed infrastructure to variable spend.
Japan
Aviation and automotive buyers in Nagoya and Tokyo negotiate separate service-level agreements for repair and obsolescence management. METI quality standards mandate IPC-A-610 Class 3 reliability for aerospace programs. Certified inspection personnel scarcity in the Chubu region constrains capacity expansion for defense electronics suppliers.
Global Electronic Contract Assembly Market Competitive Landscape
Scale-driven integrators and specialization-focused mid-caps split the market into distinct capability tiers. The vendor base concentrates around providers with validated thermal management processes for automotive power electronics and traceability infrastructure for FDA-regulated medical devices. Three archetypes dominate: diversified manufacturing conglomerates with captive component sourcing, healthcare-specialized providers with cleanroom certification, and regional nearshore operators serving tariff-sensitive brands. Competitive moves center on Mexico and Vietnam capacity expansion and M&A targeting traceability software capabilities.
Within the diversified manufacturing tier, Foxconn Technology Group and Jabil Inc. exemplify scale-driven positioning across consumer electronics and automotive verticals. Flex Ltd. occupies a position bridging design-to-delivery control with aerospace systems specialization. These three entities anchor the competitive structure by representing distinct geographic and capability vectors—Taiwanese manufacturing scale, US healthcare and automotive depth, and Singapore-based design integration.
| Leading Market Players |
|---|
| Foxconn Technology Group |
| Jabil Inc. |
| Flex Ltd. |
| Celestica Inc. |
| Sanmina Corporation |
| Benchmark Electronics Inc. |
| Plexus Corp. |
| Kimball Electronics |
| Venture Corporation |
| Others |
Supply & Pricing Matrix
Taiwan and South Korea's chokehold on advanced semiconductor packaging substrates funnels margin capture toward contract manufacturers with validated thermal management processes and FDA quality system alignment. Automotive power electronics buyers in Stuttgart and Detroit absorb premium pricing for traceability assurance, while consumer electronics brands in Vietnam and Mexico demonstrate acute price sensitivity as they diversify beyond China-dominant supply configurations.
Pricing Analysis
Aftermarket service revenue tiers—spanning repair, refurbishment, and extended service-level agreements—drive lifetime value differentiation across the electronic contract assembly value chain. Three-tier pricing structure across premium, standard, and economy levels separates aerospace systems with IPC-A-610 Class 3 certification from automotive power electronics and commodity consumer electronics assembly. Cost compression in mid-tier PCB assembly is intensifying because copper-clad laminate and advanced resin prices fluctuate with energy costs, locking providers into annual customer contracts. Medical device OEMs in Bavaria and Nagoya show the least price sensitivity, prioritizing uptime guarantees and regulatory compliance over capital expenditure minimization.
Supply Chain Analysis
ITAR and EAR export-control regimes restrict technology flows to defense electronics programs, constraining supplier qualification pools and amplifying geographic concentration risks. Component sourcing draws from Taiwan, South Korea, and Japan for advanced semiconductor packaging substrates, with Vietnam and Mexico capturing final assembly migration. Raw material dependencies center on copper-clad laminates, lead-free solder alternatives, and flame-retardant cable harness compounds. Single-source vulnerability runs through Taiwan's substrate fabrication capacity. Distribution runs through Tier-1 automotive and aerospace subcontractors managing multi-tier supplier networks in Guadalajara, Tijuana, and Detroit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electronic contract assembly market functions as a defensive-moat industry where regulatory entrenchment—REACH compliance infrastructure, FDA quality system validation, and ITAR certification—creates switching costs that protect incumbent positioning.
For Market Incumbents: Harden compliance infrastructure against emerging entrants lacking ECHA traceability systems and ISO 8 cleanroom certification. Expand captive capacity in northern Vietnam industrial zones and Baja California to serve tariff-sensitive automotive and consumer electronics brands. Deepen backward integration into component sourcing to mitigate Taiwan substrate chokepoint exposure. For New Entrants and Emerging Players: Mid-market medical device contract assembly in Eastern Europe represents the most penetrable entry point given REACH enforcement disqualifying uncertified operations. Industrial automation box build programs in Mexico's Jalisco corridor offer second-mover advantage as OEMs convert fixed infrastructure to variable spend. Pursue qualification partnerships with Tier-1 automotive suppliers seeking nearshore capacity alternatives. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed healthcare-specialized providers holding FDA quality system alignment and cleanroom certification. Five-to-ten-year viability hinges on traceability software capabilities embedded for EU Battery Passport mandates. Watch for inflection signals in ECHA REACH authorization timelines tightening substitution deadlines for restricted substances.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Vietnam | Captures tariff-sensitive consumer electronics brands diversifying beyond China-dominant supply configurations. |
| Traceability Software Integration | Positions assembly partners for EU Battery Passport mandates and CSRD disclosure requirements. |
| Healthcare Certification Investment | Unlocks medical device programs requiring FDA quality system alignment and ISO 8 cleanroom environments. |
| Nearshore Qualification in Mexico | Serves US automotive OEMs with reduced logistics latency versus Asian supply chains. |
| Aftermarket Service Unbundling | Generates recurring revenue streams from repair and obsolescence management contracts in Germany and Japan. |
Research Methodology
Operator-level perspectives from EMS plant managers, OEM procurement directors, Tier-1 supplier quality engineers, and aftermarket service heads anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, customs and trade data, EPA electronics standards documentation, and ECHA REACH authorization records. Bottom-up assembly volume estimates triangulated against top-down electronics end-market demand projections.
Scenario-bracketing around regulatory timeline divergence and substrate material price volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, technology platform, end-use application, and geographic production cluster. CAGRs derived from installed base growth, content-per-vehicle expansion in EV platforms, and outsourcing penetration rates among automotive and medical device OEMs.
Macroeconomic conditions sit as an overlay; deviation in energy costs, copper pricing, and cross-border tariff regimes would shift the trajectory. Forecasts reflect documented assumptions about REACH enforcement consistency and NHTSA fuel economy standard implementation. Material shifts in Taiwan semiconductor substrate availability or EPA hazardous substance restriction timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Systems and Devices
Cold Start System Market
Electronic Systems and Devices
Pre Terminated Systems Market
Electronic Systems and Devices
Electronic Prototyping Market
Electronic Systems and Devices
SONAR System Market
Electronic Systems and Devices
Video Encoder and Decoder Market
Electronic Systems and Devices
Global Broadcast Switcher Market
Electronic Systems and Devices
Resist Strip System Market
Electronic Systems and Devices
Embedded Computing Systems Market
Electronic Systems and Devices
AI Computing Hardware Market
Electronic Systems and Devices
Sound Reception System Market
Electronic Systems and Devices
Saudi Arabia Wearable and Audio Devices Market
Electronic Systems and Devices
Cognitive Systems Spending Market
Electronic Systems and Devices
Hi-Fi System Market
Electronic Systems and Devices
Radio Dot System (RDS) Market
Electronic Systems and Devices
Vacuum Pulse System Market
Electronic Systems and Devices
Microelectromechanical System (MEMS) Market