
 Plant Focused Dips Market | 2026-2036
Plant Focused Dips Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Focused Dips Market Analytics
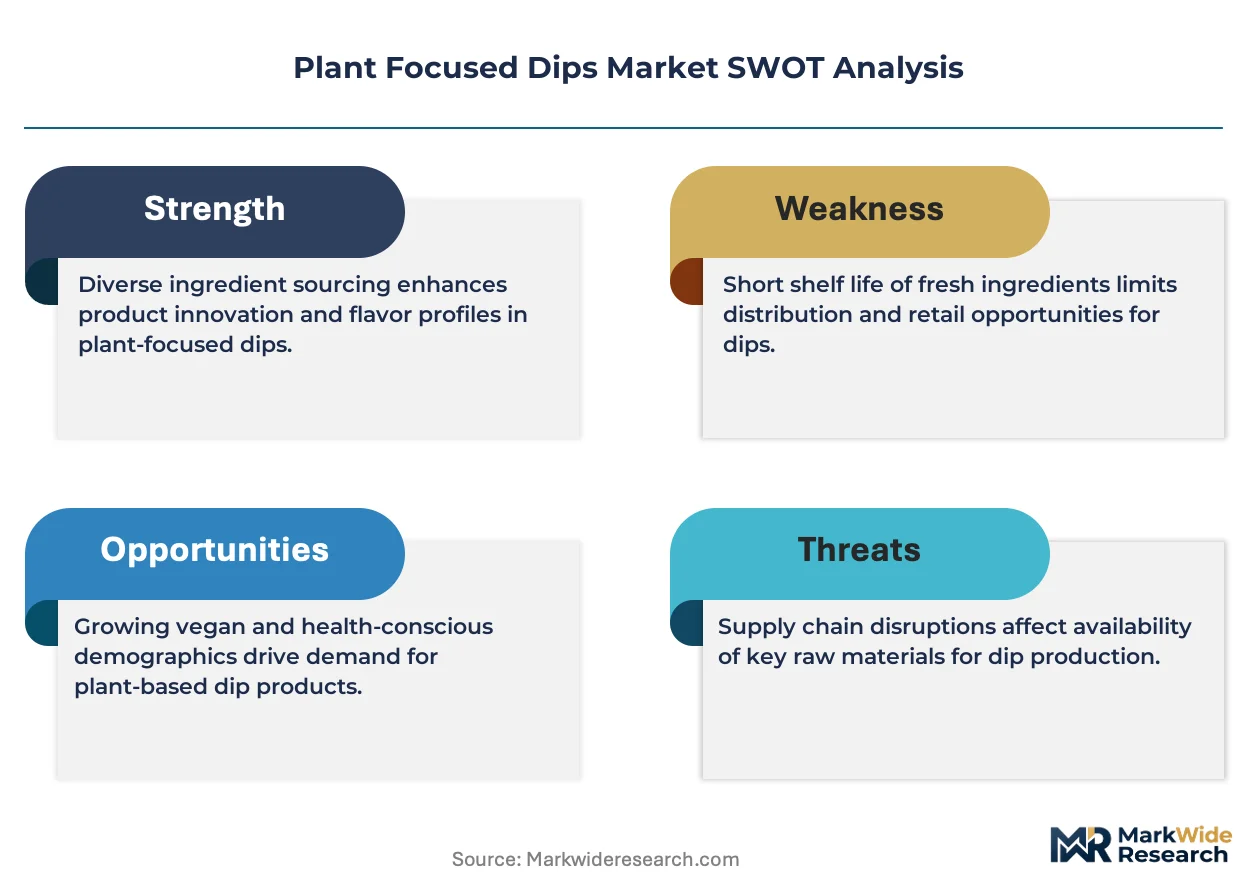
REACH compliance is realigning the cost-of-entry calculus for European plant-based dip manufacturers by mandating full substance registration and safety documentation for novel protein isolates and emulsifiers. SABRA DIPPING CO. LLC anchors its competitive stance through scale advantages in chickpea supply chains and Mediterranean flavor expertise. The Kraft Heinz Company leverages extensive retail distribution infrastructure to secure shelf placement across mainstream grocery channels. Good Foods Group differentiates through refrigerated clean-label positioning and plant-forward recipe development without artificial preservatives.
Plant focused dips are emulsified or pureed preparations derived from legumes, nuts, vegetables, or avocado, typically containing 60-85% plant matter by weight, processed through cold-grind or thermal-pasteurization methods to achieve spoonable viscosity and refrigerated shelf stability of 30-90 days. These products serve as condiments, meal accompaniments, and standalone snacking components in retail and food service environments. Bean dips and avocado dips currently occupy the largest volume positions due to established consumer familiarity and versatile application across cuisines. The pouches segment sustains above-average momentum as convenience-oriented formats gain traction in on-the-go consumption occasions and single-serve food service applications.
The European Food Safety Authority enforces novel food authorization requirements for emerging protein sources such as pea and fava bean isolates, while the FDA oversees GRAS self-determination pathways in the United States that influence cross-border formulation strategies. The EU Green Deal's Farm to Fork sustainability targets are pressuring manufacturers to document supply chain carbon intensity and shift toward domestically sourced legume inputs. Stakeholders must monitor evolving allergen labeling thresholds for tree nut and sesame contents as regulatory divergence between jurisdictions complicates unified product specifications and export compliance.
Market Dynamics
Clean-label formulation mandates and novel protein authorization protocols are compressing product development timelines while forcing manufacturers to revalidate ingredient portfolios across multiple regulatory jurisdictions simultaneously.
Growth Catalysts
- EU Green Deal Farm to Fork targets:Mandatory carbon intensity documentation accelerates domestic legume sourcing investments by manufacturers seeking preferential procurement status in European retail channels.
- Pouch format adoption:Food service operators and convenience retailers expand single-serve packaging deployment for on-premise and grab-and-go consumption occasions.
- Chickpea supply chain maturation:Mediterranean and North American growing regions achieve processing scale sufficient to stabilize input costs for hummus-centered product lines.
Market Restraints
- REACH substance registration costs:Novel protein isolates and emulsifiers require full safety documentation, elevating cost-of-entry for European market participation.
- Tree nut allergen thresholds:Divergent labeling requirements between EFSA and FDA jurisdictions complicate unified product specifications and cross-border export compliance.
- Thermal-pasteurization energy intensity:Cold-grind alternatives remain limited by shorter shelf stability windows, constraining distribution radius for clean-label formulations.
Strategic Opportunities
- German retail consolidation:Discounter and supermarket private-label expansion creates white space for co-manufacturing partnerships with established chickpea processing infrastructure.
- Fava bean protein authorization:EFSA novel food pathways for emerging legume isolates enable differentiated positioning beyond saturated chickpea and pea segments.
- Refrigerated direct-store-delivery:Cold-chain logistics investments by third-party distributors unlock food service penetration beyond traditional retail shelf-stable formats.
Industry Challenges
- Formulation scientist scarcity:Clean-label emulsifier replacement expertise remains concentrated among specialists with dairy and meat analog backgrounds, creating recruitment bottlenecks.
- Dual certification timelines:Simultaneous GRAS self-determination and EFSA novel food submissions extend time-to-market by 18-24 months for innovative protein sources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Focused Dips Market |
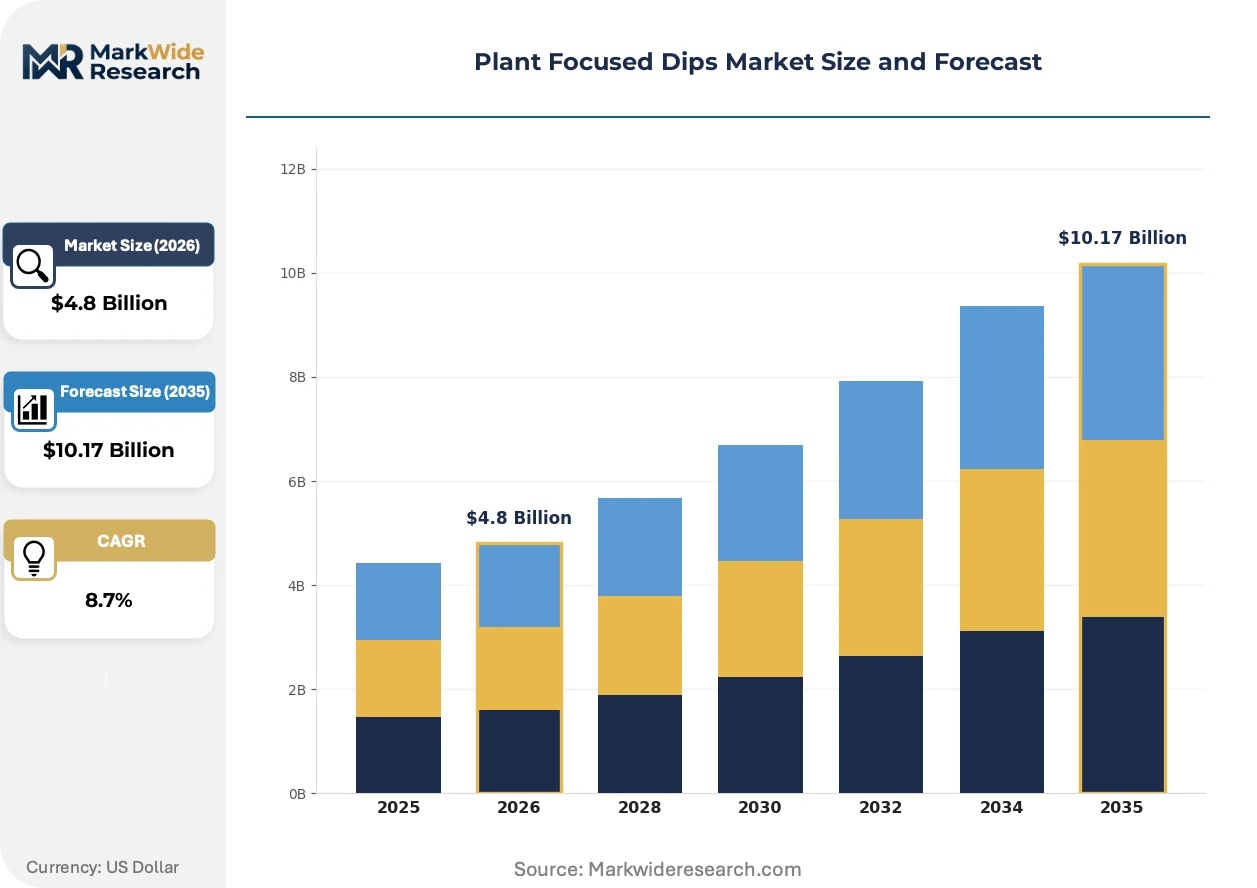
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bean Dips, Nut Dips, Vegetable Dips, Avocado Dips Flavor Profile: Spicy, Savory, Creamy, Sweet Packaging Type: Squeeze Bottles, Jars, Pouches, Cups Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Food Service |
| Companies Covered | The Kraft Heinz Company, SABRA DIPPING CO. LLC, Frito-Lay North America Inc., Bolthouse Farms Inc., Good Foods Group, Kite Hill, Galaxy Nutritional Foods Inc., DA IYA FOODS INC., Wingreen World, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Focused Dips Market Evolving Landscape
High-pressure processing technology and modified-atmosphere packaging are extending refrigerated shelf stability without synthetic preservatives, enabling broader retail distribution for clean-label plant-based dips.
Cold-grind emulsion systems are absorbing capital investment from manufacturers seeking to bypass thermal degradation of heat-sensitive bioactive compounds in avocado and nut-based formulations. Premium retailers and natural channel distributors are adopting these products at accelerating pace. The technology is absorbing market share from conventional pasteurized alternatives by preserving flavor intensity and nutrient density claims.
EFSA novel food authorization requirements for pea and fava bean protein isolates are extending regulatory review timelines and documentation burdens for European market entry. Manufacturers must submit comprehensive toxicological and compositional data before commercialization. Bean dip segments targeting functional protein positioning are most affected, with several applicants pursuing sequential US-EU launch strategies to manage compliance sequencing.
Buyer concentration among European retail alliances is compressing supplier negotiation cycles and demanding shorter innovation pipelines. National supermarket cooperatives in France and Germany now specify 90-day formulation turnaround for seasonal limited-edition lines. This pattern is most visible in the United Kingdom, where Tesco and Sainsbury's consolidated buying power has shifted procurement toward direct supplier development programs rather than traditional broker-mediated relationships.
Plant Focused Dips Market Segmentation
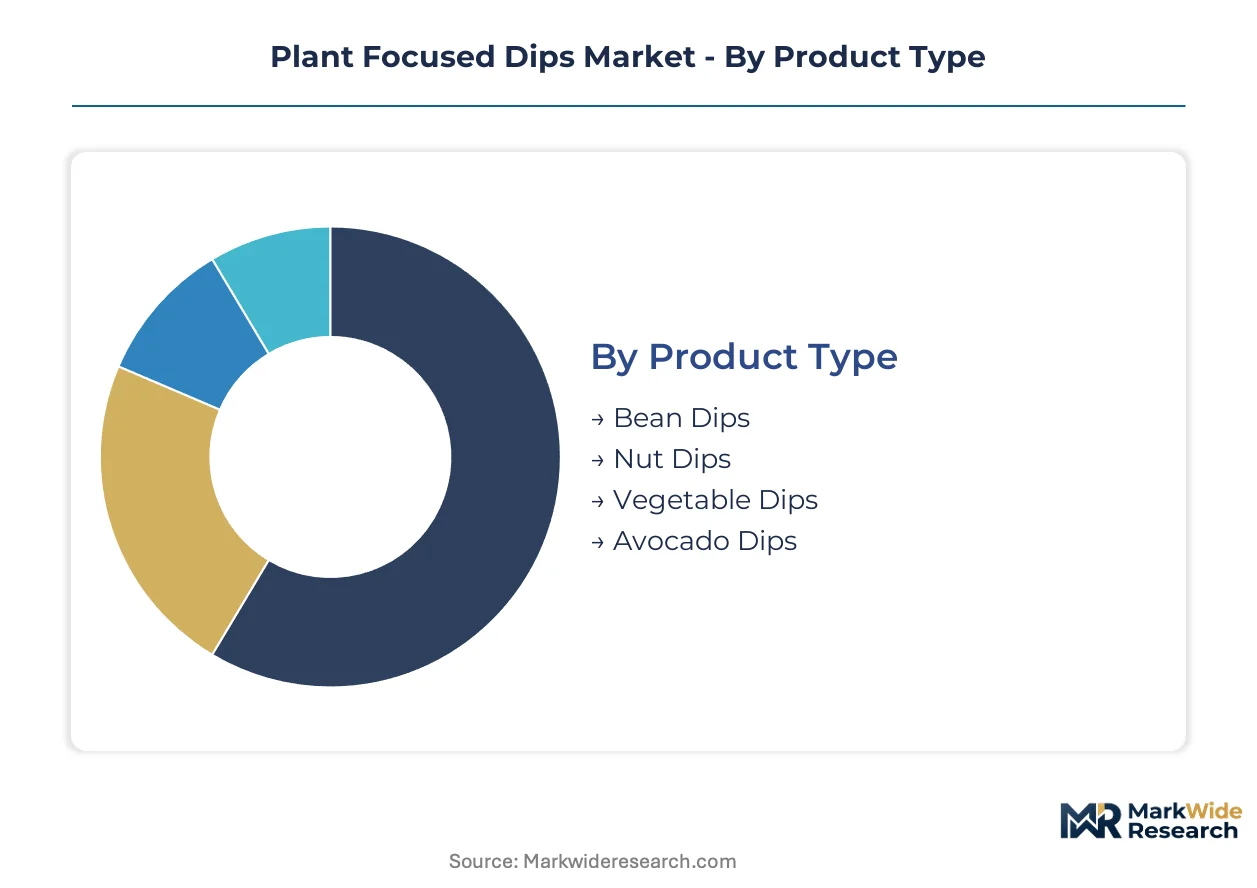
Plant focused dips manufacturers configure product portfolios across four intersecting dimensions that determine margin structure, shelf placement, and cold-chain requirements. Each segmentation axis carries distinct regulatory, formulation, and logistics implications that reshape competitive positioning.
Product Type:
Bean dips function as standalone meal centers with embedded protein claims, while nut and avocado variants demand more complex allergen management and shorter distribution radii.
- Bean Dips:Chickpea-based hummus formulations dominate volume through 60-85% legume content by weight and thermal-pasteurization stability extending 60-90 days refrigerated. German and French retail alliances concentrate procurement for private-label lines, squeezing formulation turnaround to 90-day cycles for seasonal variants.
- Avocado Dips:Cold-grind emulsion systems preserve heat-sensitive bioactive compounds but constrain shelf stability to 30-45 days, limiting distribution radius and privileging regional processors with direct-store-delivery infrastructure.
- Nut Dips:Almond and cashew bases carry elevated allergen labeling burdens under divergent EFSA and FDA thresholds, complicating unified specifications for cross-border export.
- Vegetable Dips:Roasted pepper, beet, and carrot purees occupy niche positioning in specialty retail channels with shorter production runs and higher per-unit packaging costs.
Volume placements concentrate in Bean Dips; the faster expansion belongs to Avocado Dips.
Flavor Profile:
Flavor positioning determines ingredient complexity, clean-label compliance burden, and the feasibility of natural preservative systems.
- Savory:Garlic, herb, and roasted vegetable formulations align with Mediterranean cuisine positioning and achieve broadest retail distribution through familiar taste profiles.
- Spicy:Chili-forward variants target on-trend heat-seeking demographics in UK and German convenience retail, requiring precise Scoville standardization for food service consistency.
- Creamy:Texture-modified formulations using pea protein isolates face EFSA novel food authorization delays, extending European time-to-market by 18-24 months.
- Sweet:Dessert-positioned dips with date or maple bases occupy emerging snacking occasions, constrained by sugar-content disclosure requirements in French retail.
Manufacturers anchor margin in Savory; Sweet applications are climbing the fastest as boundary-blurring snack formats proliferate.
Packaging Type:
Format selection governs cold-chain intensity, portion control economics, and food service penetration potential.
- Pouches:Single-serve flexible packaging sustains above-average momentum for grab-and-go consumption and airline catering applications, though modified-atmosphere sealing adds unit cost.
- Jars:Multi-serve rigid containers dominate household stock-up occasions in UK supermarkets, with glass formats commanding premium placement in natural channel sets.
- Cups:Portion-controlled rigid formats target food service operators and convenience retailers with limited refrigeration capacity.
- Squeeze Bottles:Dispensing convenience drives adoption in sandwich preparation lines and institutional food service, requiring higher viscosity formulations.
Procurement volumes stack in Jars; Pouch formats are gaining share fastest through food service expansion.
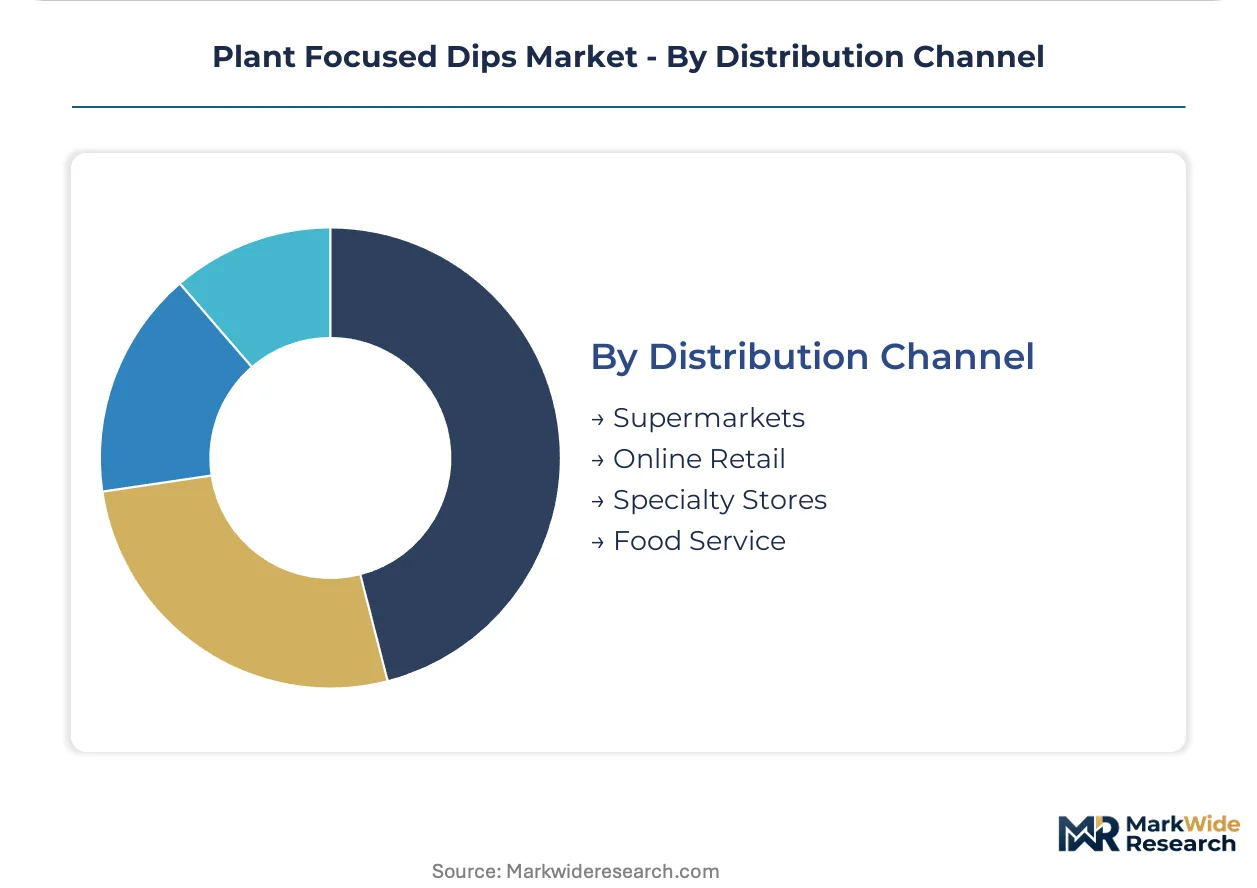
Distribution Channel:
Channel mix determines pricing architecture, promotional cadence, and the viability of direct-store-delivery versus warehouse distribution models.
- Supermarkets:National cooperative buying in France and Germany consolidates supplier negotiation power, shifting procurement toward direct development programs away from broker mediation.
- Food Service:Institutional and restaurant channels demand 90-day formulation cycles for limited-edition lines, compressing innovation pipelines.
- Specialty Stores:Natural channel distributors accelerate adoption of cold-grind, high-pressure-processed products with clean-label positioning.
- Online Retail:Direct-to-consumer and third-party marketplace channels require insulated cold-chain fulfillment, elevating last-mile logistics costs.
Revenue concentration sits with Supermarkets; Food Service penetration shows the steepest expansion trajectory as refrigerated logistics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal tax incentives and Farm to Fork sustainability credits are concentrating plant-based dip manufacturing investment in designated low-carbon economic zones across Germany, France, and the United Kingdom.
Germany
Discounter private-label expansion and chickpea supply chain maturation drive procurement concentration. REACH substance registration requirements for novel protein isolates elevate compliance costs for market entry. The Bavaria food processing corridor hosts co-manufacturing partnerships leveraging established Mediterranean ingredient import infrastructure.
France
Supermarket cooperative buying power and clean-label formulation mandates reshape supplier relationships. EFSA novel food authorization protocols delay fava bean protein commercialization by 18-24 months. The Île-de-France region anchors retail alliance headquarters directing 90-day formulation cycles for seasonal product lines.
United Kingdom
Tesco and Sainsbury's consolidated procurement shifts toward direct supplier development programs. Divergent EFSA-FDA allergen labeling thresholds complicate cross-border export specifications for tree nut formulations. Greater London distribution hubs prioritize refrigerated direct-store-delivery infrastructure for cold-grind avocado products.
United States
FDA GRAS self-determination pathways enable faster protein isolate commercialization than European counterparts. Hummus-centered product lines benefit from stabilized chickpea input costs across Mediterranean and North American growing regions. California's cold-chain logistics investments unlock food service penetration beyond traditional retail formats.
Canada
Health Canada oversight of novel food notifications creates intermediate regulatory timelines between US and EU pathways. Pouch format adoption accelerates in airline catering and convenience retail applications. Ontario food processing clusters develop modified-atmosphere packaging capabilities for extended shelf stability without synthetic preservatives.
Plant Focused Dips Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: multinational CPG houses with refrigerated distribution infrastructure, legume-centric Mediterranean specialists with captive supply chains, and clean-label challengers leveraging high-pressure processing technology. Dominant competitive moves include portfolio diversification into adjacent plant-based categories and backward integration into chickpea and pea protein processing assets.
Among North American market participants, The Kraft Heinz Company and Frito-Lay North America Inc. represent scale-driven conglomerate positions with established retail shelf access, while SABRA DIPPING CO. LLC occupies the specialist tier with Mediterranean flavor expertise and chickpea supply chain depth. Good Foods Group anchors the clean-label challenger archetype through refrigerated positioning and plant-forward formulation without artificial preservatives.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| SABRA DIPPING CO. LLC |
| Frito-Lay North America Inc. |
| Bolthouse Farms Inc. |
| Good Foods Group |
| Kite Hill |
| Galaxy Nutritional Foods Inc. |
| DA IYA FOODS INC. |
| Wingreen World |
| Others |
Value Network & Pricing Analysis
Backward integration into chickpea processing assets anchors supply position and pricing power for Mediterranean-specialist manufacturers competing against diversified conglomerates with outsourced ingredient sourcing. Captive supply chains insulate hummus-centered product lines from spot-market volatility while compressing procurement cycles for private-label discounter contracts in Germany.
Pricing Analysis
Short lead-time premiums command shelf placement in UK supermarket cooperatives demanding 90-day formulation cycles for seasonal limited-edition lines. Three-tier pricing structure across premium, standard, and economy levels separates cold-grind clean-label positioning from thermal-pasteurized mainstream variants and private-label economy tiers. Price differentiation rests on certification grade and volume scale, with clean-label EFSA novel food authorization status commanding retailer preference. Cost compression in economy tiers is intensifying because German discounter private-label expansion concentrates procurement leverage. Food service operators exhibit highest price sensitivity due to margin pressure in institutional catering contracts.
Supply Chain Analysis
Dual-sourcing requirements from Tesco and Sainsbury's procurement teams mandate multi-supplier qualification for chickpea protein isolates and Mediterranean ingredient imports. Geographic supply concentration centers on Turkey, Spain, and the United States for chickpea cultivation, with North American growing regions achieving processing scale sufficient for input cost stabilization. Raw material dependencies hinge on fava bean protein isolates, cold-pressed avocado oils, and modified-atmosphere packaging films. Single-source vulnerability persists for EFSA novel food authorized protein inputs pending broader supplier qualification. Distribution runs through refrigerated direct-store-delivery networks for cold-grind avocado products with 30-45 day shelf stability windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chickpea supply chain maturation lags refrigerated logistics capacity expansion, propping pricing for manufacturers with captive processing infrastructure and cold-chain control.
For Market Incumbents: Hedge against clean-label challenger encroachment by securing fava bean protein isolate supply agreements ahead of EFSA novel food authorization completion. Deepen backward integration into North American chickpea growing regions to defend margin position against spot-market volatility. Prioritize certification investment in high-pressure processing technology to extend shelf stability without synthetic preservatives. For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer white-space penetration for dessert-positioned sweet dips with date or maple bases targeting boundary-blurring snacking occasions. Target German discounter co-manufacturing partnerships leveraging established Mediterranean ingredient import infrastructure in the Bavaria food processing corridor. Pursue food service pouch format adoption for airline catering and grab-and-go convenience retail applications. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified CPG houses seeking refrigerated distribution infrastructure and Mediterranean flavor expertise. Long-term viability favors specialists with captive chickpea supply chains and clean-label formulation capabilities over commodity thermal-pasteurized producers. Watch EFSA fava bean protein authorization timelines as inflection indicator for differentiated positioning beyond saturated chickpea segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chickpea Processing | Captive supply chains stabilize input costs against Mediterranean harvest volatility. |
| High-Pressure Processing Technology Adoption | Extended refrigerated shelf stability unlocks broader retail distribution for clean-label formulations. |
| EFSA Novel Food Authorization Pursuit | Fava bean protein isolate approval enables differentiated positioning in functional protein segments. |
| Refrigerated Direct-Store-Delivery Expansion | Cold-chain logistics investments penetrate food service beyond traditional retail shelf-stable formats. |
| Pouch Format Manufacturing Scale-Up | Single-serve flexible packaging captures grab-and-go consumption and airline catering contracts. |
Research Methodology
Multi-period observation of chickpea input cost trajectories, EFSA novel food authorization timelines, and refrigerated logistics capacity expansion anchored the trend analysis, supplemented by interviews with category buyers at German and French supermarket cooperatives, formulation scientists at clean-label challengers, cold-chain logistics operators, and procurement directors at Mediterranean ingredient importers. Secondary validation drew from EU customs trade data, EFSA novel food application registers, SEC 10-K filings of diversified CPG houses, and Nielsen retail audit data. Bottom-up segment sizing triangulated against top-down market consolidation estimates.
Input-output matrix framing connected chickpea supply chain maturation indices, clean-label certification penetration rates, and pouch format adoption curves to revenue projections across the analysis window. Segmentation dimensions modeled included product type, flavor profile, packaging format, and distribution channel intersecting with regional regulatory cluster variations. CAGRs were derived from slope analysis of historical trajectory extension adjusted for structural shifts in procurement concentration. Industry-specific forecast inputs encompassed REACH substance registration cost inflation and high-pressure processing technology diffusion rates.
Inputs from EFSA novel food application disclosures and supermarket cooperative procurement specifications were available through the study window; gaps in private-label contract pricing transparency introduce uncertainty bands around margin compression estimates. Deviation in fava bean protein authorization timelines or EU Green Deal carbon intensity documentation enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
South America Breakfast Cereals Market
Packaged Foods
Cookie Pucks Market
Packaged Foods
North America Instant Noodles Market
Packaged Foods
Cookie Butter Spread Market
Packaged Foods
Ready-To-Eat Food Market
Packaged Foods
Air-Dried Food Market
Packaged Foods
Asia-Pacific Pasta and Noodles Market
Packaged Foods
Ready Meals Market
Packaged Foods
Europe Ready Meals Market
Packaged Foods
Protein Packed Foods Market
Packaged Foods
Bangladesh Instant Noodles Market
Packaged Foods
Quinoa Pasta Market
Packaged Foods
Packaged Zhug Market
Packaged Foods
Pastry Fillings Market
Packaged Foods
India Packaged Food Products Market
Packaged Foods
Packaged Sprouts Market