
 Breakfast Food Market | 2026-2036
Breakfast Food Market Size, Share, and Industry Trends Forecast 2026-2036
Breakfast Food Market Intelligence
The clean-label tier is collapsing the gap between premium nutrition claims and mainstream accessibility, forcing reformulation across conventional portfolios. General Mills dominates the North American cereal segment through in-house grain sourcing and scaled manufacturing infrastructure. Nestlé S.A. leverages its global R&D network to sustain innovation in plant-based breakfast extensions. Unilever PLC anchors the European market with specialized tea and spreads integration into morning routines.
Breakfast food encompasses ready-to-eat and ready-to-cook formulations designed for morning consumption, typically requiring reconstitution with milk, water, or direct consumption, with protein content and glycemic index serving as critical nutritional parameters for product positioning. The category serves industrial purposes spanning household pantry stocking, foodservice portion control, and on-the-go nutrition delivery. Cereals retain the largest revenue pool within product type segmentation, though oatmeal commands margin premiums among health-conscious consumers. Online retailers represent the fastest-growing distribution channel, displacing traditional supermarket dominance among students and professionals seeking subscription-based replenishment.
The FDA governs nutritional labeling and health claim substantiation for breakfast foods sold in the United States, while EFSA enforces novel food approvals and additive restrictions across European markets, collectively elevating barrier costs for new entrants lacking regulatory compliance infrastructure. The EU Green Deal's packaging waste directives are additionally reshaping material specifications for single-serve breakfast pouches and cups. Stakeholders must monitor evolving sodium and added-sugar thresholds across jurisdictions to anticipate reformulation mandates before they disrupt existing product lines.
Market Dynamics
Clean-label mandates from FDA and EFSA are forcing simultaneous reformulation across conventional and premium breakfast portfolios, collapsing the historical segmentation between mass-market and health-positioned products.
Growth Catalysts
- Protein fortification technology:Microencapsulation advances enable stable incorporation of plant and dairy proteins into ambient-stable cereals without texture degradation. Foodservice operators in the United States are accelerating adoption for grab-and-go morning programs.
- EU Green Deal packaging directives:Single-use plastic restrictions on breakfast cups and pouches are accelerating fiber-based barrier material development. Manufacturers achieving compliance capture preferential retail placement across German and French supermarket chains.
- Remote work normalization:Hybrid employment patterns in the United States and United Kingdom sustain demand for at-home breakfast occasions. Cereal and oatmeal brands report sustained pantry replenishment cycles among suburban households.
Market Restraints
- Wheat and oat input volatility:Climate-driven harvest variability across the North American plains elevates raw material cost unpredictability. Breakfast cereal margins compress during drought cycles without pricing elasticity to pass through costs.
- Additive approval timelines:EFSA novel food assessments for alternative proteins and natural preservatives extend 18-24 months. European launch schedules lag behind formulation completion, ceding first-mover advantage to compliant competitors.
- Refrigerated breakfast substitute encroachment:Yogurt parfaits and protein smoothies in convenience retail capture occasion share from shelf-stable cereals. Cold-chain infrastructure expansion enables this displacement in urban corridors.
Strategic Opportunities
- Subscription direct-to-consumer channels:Personalized nutrition algorithms paired with auto-replenishment models bypass traditional retail slotting fees. Young professionals in the United States demonstrate willingness to commit to 90-day breakfast plans.
- Regenerative agriculture certification:USDA Organic transitions toward soil health verification create premium positioning for grain suppliers. Early certifiers command shelf price premiums in natural grocery segments.
- Functional ingredient convergence:Probiotic and adaptogenic additions to oatmeal formats target stress-management positioning. Wellness-focused consumers in California and New York metro areas show trial willingness for elevated price points.
Industry Challenges
- Reformulation R&D talent scarcity:Food scientists capable of balancing clean-label compliance with sensory performance command premium compensation. Mid-tier manufacturers struggle to staff technical centers competitive with multinational R&D campuses.
- Legacy equipment retooling costs:Existing extrusion and coating lines require capital-intensive modification to handle alternative proteins and reduced sugar binders. Facility downtime during conversion strains quarterly output commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breakfast Food Market |
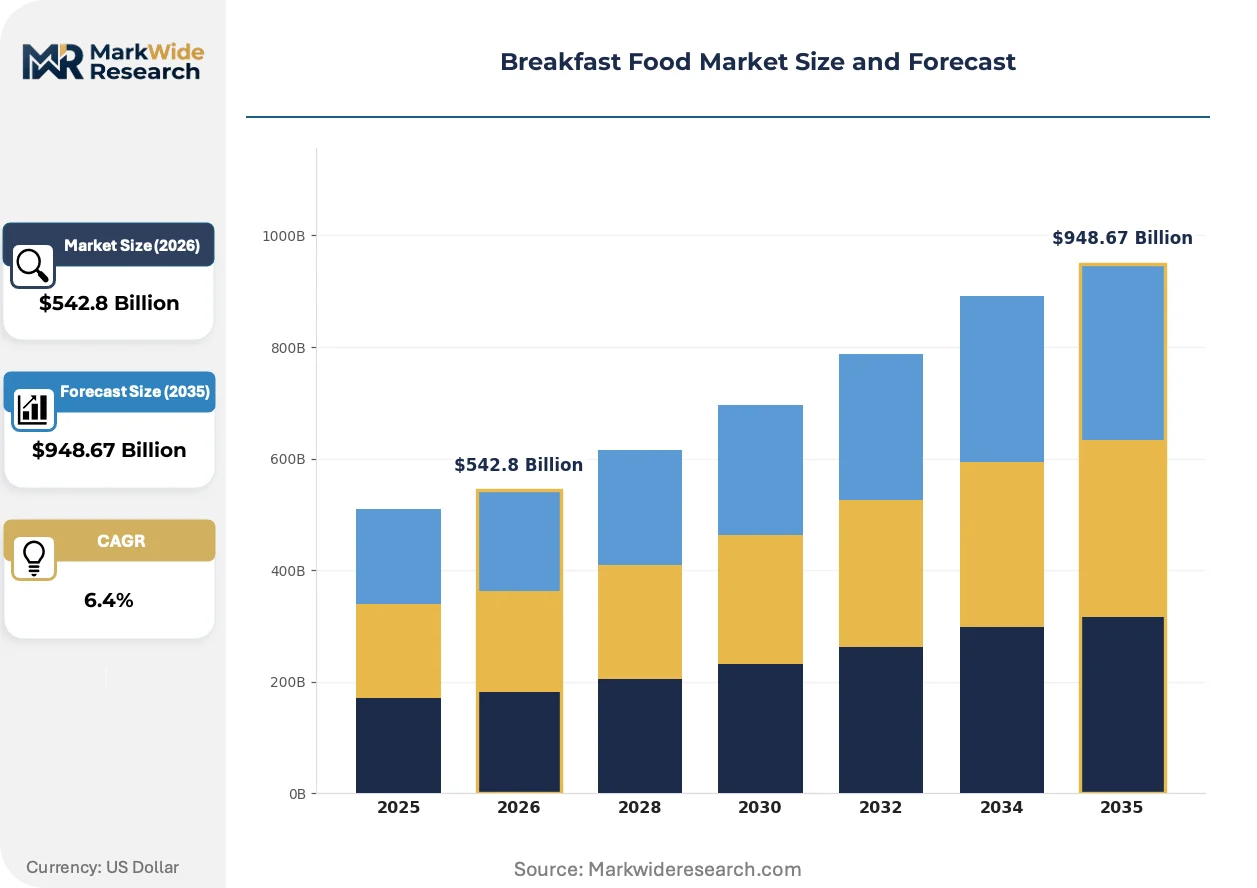
| Market Size in 2026 | $542.8 Billion |
| Market Size in 2035 | $948.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cereals, Granola Bars, Pancakes, Oatmeal Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Health Food Stores Customer Type: Families, Students, Professionals, Health Conscious Consumers Packaging Type: Bags, Boxes, Cups, Pouches |
| Companies Covered | The Kellogg Company, Mondelēz International, Nestlé S.A., Conagra Brands Inc., The Kraft Heinz Company, PepsiCo Inc., Unilever PLC, Dr. Oetker, General Mills Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breakfast Food Market Strategic Shifts & Innovations
Breakfast food production is experiencing simultaneous pressure from material science breakthroughs, regulatory packaging mandates, and channel fragmentation that collectively reshape competitive positioning.
Spray-dried protein isolates are decomposing the traditional cereal manufacturing stack by enabling high-protein formulations without conventional extrusion infrastructure. Specialty ingredient suppliers in the United States are licensing turnkey fortification systems to mid-tier brands. This technology is decomposing the capital barrier that historically separated mass-market and premium nutrition positioning.
EFSA's tightened additive approval thresholds under its 2023 re-evaluation program are accelerating natural preservative substitution across European breakfast portfolios. Manufacturers reformulating with cultured celery powder and rosemary extract face 12-18 month sensory validation cycles. Oatmeal and muesli segments in Germany and France absorb the highest compliance costs due to moisture sensitivity and extended shelf-life requirements.
Professional procurement through employer-subsidized breakfast programs is displacing individual household purchasing in United States urban centers. Technology and finance sector employers negotiate direct supply contracts with granola and protein bar manufacturers. This concentration is most visible in Seattle, San Francisco, and Austin where campus feeding operations rival traditional retail velocity.
Breakfast Food Market Segmentation
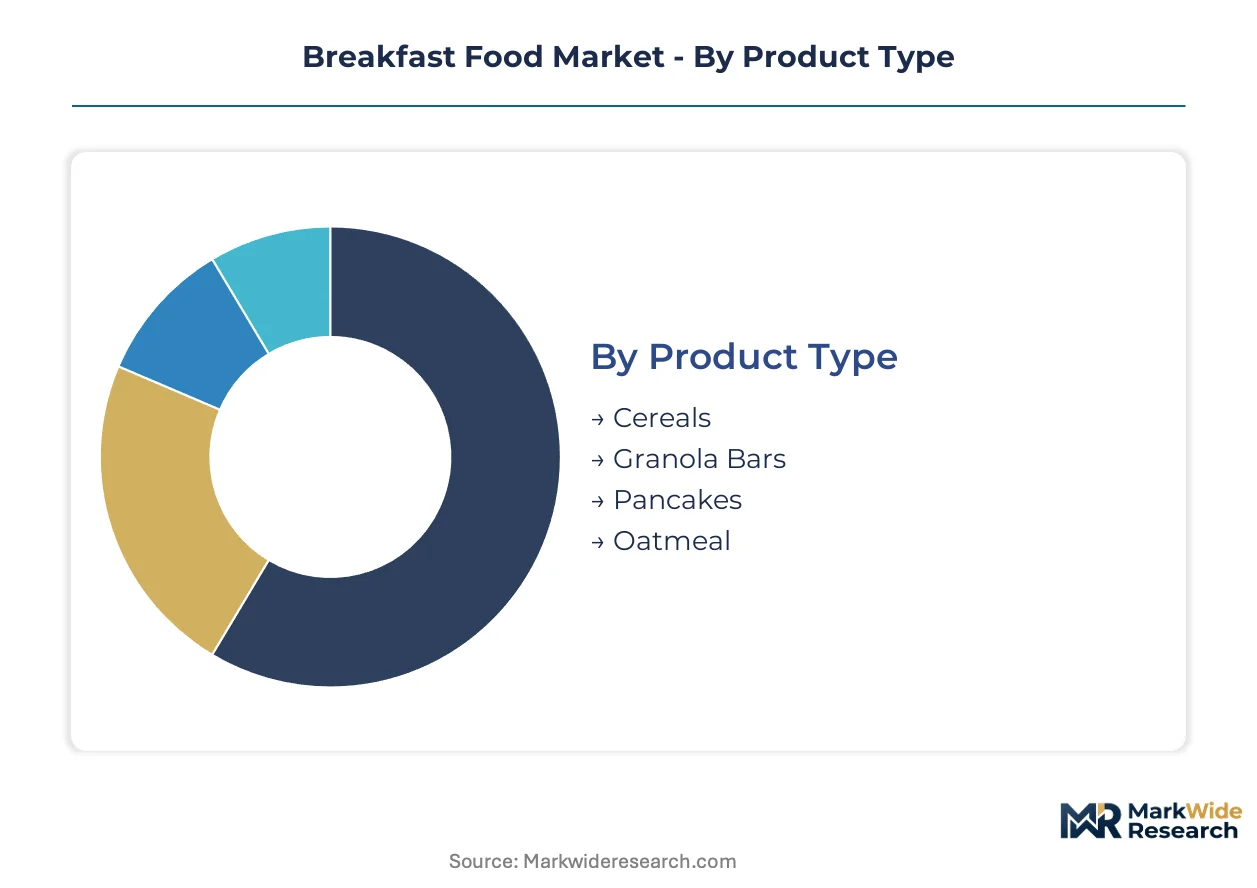
Breakfast food manufacturers navigate divergent margin structures across product formats and channel economics. Understanding where profitability concentrates within each dimension enables portfolio prioritization and resource allocation decisions.
Product Type:
Margin pools concentrate in formats where ingredient premiums translate directly to shelf price realization without proportional manufacturing cost escalation.
- Cereals:Extruded grain bases support high-volume production with established flavor coating infrastructure. Demand clusters among working professionals in the United States seeking grab-and-go morning solutions, though private-label compression constrains branded pricing power.
- Oatmeal:Steel-cut and rolled oat variants command health-positioning premiums through glycemic index claims and protein fortification flexibility. Health-conscious consumers in Germany and France absorb price increases for organic and regenerative-certified sourcing.
- Granola Bars:Binding technology and shelf-stability requirements elevate unit economics for ambient portable formats.
- Pancakes:Frozen and dry-mix variants serve weekend occasion expansion with lower per-occasion spend thresholds.
The dominant share belongs to Cereals, while Oatmeal is closing the gap fastest.
Distribution Channel:
Channel selection determines working capital intensity and promotional spend requirements, with direct-to-consumer formats offering margin recovery from retail slotting fee avoidance.
- Online Retailers:Subscription auto-replenishment models lock in 90-day purchase commitments from United States-based young professionals. Algorithms personalize assortment while bypassing traditional retail margin stacking.
- Supermarkets:End-cap placement and promotional calendar dependence sustain volume velocity for established brands. German and French chains increasingly prioritize EU Green Deal-compliant packaging for shelf access.
- Convenience Stores:Single-serve impulse formats capture occasion substitution from skipped sit-down breakfasts.
- Health Food Stores:Certification-driven curation supports premium price realization for organic and functional-positioned lines.
Supermarkets retain volume leadership, yet Online Retailers are expanding most quickly among digital-native demographics.
Customer Type:
Occasion frequency and price elasticity vary sharply across household structures and employment patterns, shaping formulation and pack size strategies.
- Professionals:Hybrid work schedules in the United States and United Kingdom sustain pantry stocking cycles for at-home breakfast occasions. Portability requirements drive protein bar and single-serve cereal cup adoption for office-bound days.
- Families:Multi-person household dynamics favor bulk formats with child-appeal flavor profiles and value-tier positioning.
- Students:Subscription willingness and digital-native purchasing patterns align with online retailer growth trajectories.
- Health Conscious Consumers:Clean-label scrutiny and functional ingredient demand support premium tier expansion in California and New York metro areas.
Professionals anchor current revenue contribution, though Health Conscious Consumers are gaining share fastest through elevated per-unit spend.
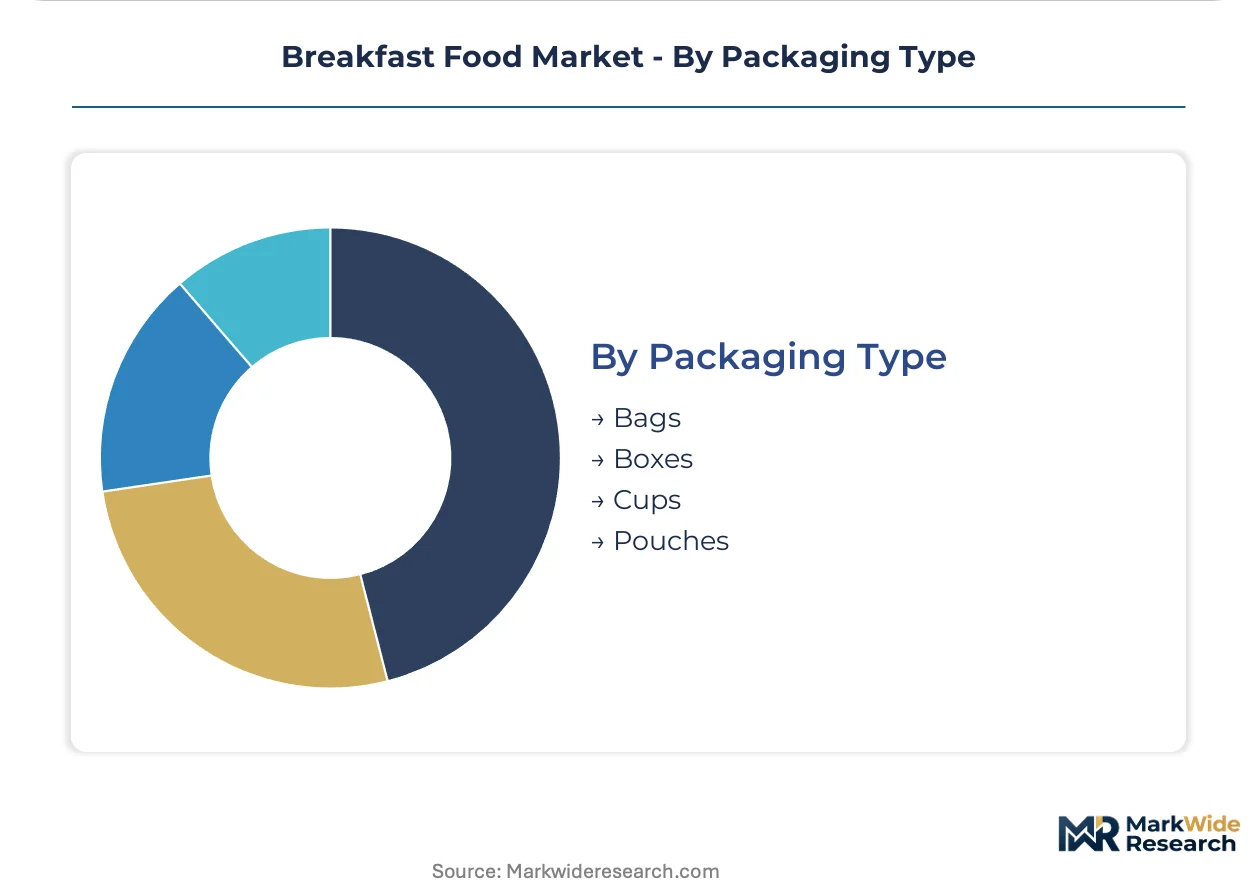
Packaging Type:
Material specifications face simultaneous pressure from regulatory mandates and operational efficiency requirements, with compliance costs reshaping competitive positioning.
- Pouches:Flexible barrier materials enable portion control and lightweight logistics for granola and oatmeal formats. EU Green Deal fiber-based substitution mandates are accelerating R&D spend across German manufacturing facilities.
- Boxes:Structural rigidity supports retail shelf presence and multi-serve cereal protection with established recycling infrastructure.
- Cups:Single-serve convenience aligns with foodservice and on-the-go demand, though plastic restriction timelines compress format viability windows.
- Bags:Cost-efficient bulk formats serve family and foodservice volume segments with minimal material overhead.
Boxes maintain installed base dominance, while Pouches are climbing the fastest on sustainability-aligned format conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Breakfast food trade flows reveal persistent export surpluses in grain-producing economies against import dependence in densely populated manufacturing hubs. Currency volatility and shipping cost fluctuations are redirecting procurement patterns across the analysis window.
United States
Hybrid work normalization sustains pantry replenishment cycles among suburban households in Texas and Illinois. The FDA enforces nutritional labeling and health claim substantiation standards that elevate compliance costs for reformulation. Minneapolis-St. Paul anchors North American cereal manufacturing through scaled extrusion infrastructure and grain sourcing networks.
Germany
Health-conscious consumers in Bavaria and North Rhine-Westphalia absorb price premiums for organic and regenerative-certified oatmeal. The EU Green Deal's packaging waste directives accelerate fiber-based barrier material development for single-serve formats. Cologne and Hamburg host manufacturing clusters specializing in muesli and granola bar production for European distribution.
China
Urbanization in the Yangtze River Delta and Pearl River Delta expands ready-to-eat breakfast penetration among time-constrained professionals. The country's national food safety regulator enforces additive and labeling standards that extend product approval timelines. Shanghai-based food manufacturers are scaling spray-dried protein fortification capabilities for domestic and export markets.
United Kingdom
Subscription auto-replenishment models lock in purchase commitments from young professionals in London and Manchester. EFSA-aligned novel food assessments govern alternative protein approvals with 18-24 month evaluation windows. The Midlands region concentrates oat processing and granola manufacturing serving both domestic and Irish export channels.
France
Clean-label scrutiny in Île-de-France and Auvergne-Rhône-Alpes supports premium positioning for low-sugar cereal variants. EFSA additive restrictions under its 2023 re-evaluation program accelerate natural preservative substitution. Lyon hosts specialized R&D facilities focused on probiotic and adaptogenic oatmeal formulations targeting wellness-positioned consumers.
Breakfast Food Market Key Industry Players
Listed leaders compete with private specialists across formulation and channel dimensions, creating a tiered structure where scale advantages clash with agility in regulatory compliance. The market fragments across multinational conglomerates with integrated grain sourcing, mid-tier private label manufacturers, and emerging direct-to-consumer specialists. Three archetypes dominate: diversified food conglomerates with cereal heritage, private-label contract manufacturers serving retail chains, and subscription-native brands built on personalized nutrition algorithms. Competitive moves concentrate on M&A for clean-label capability acquisition and geographic expansion into Asia-Pacific growth corridors.
Within the diversified conglomerate tier, General Mills Inc. and Nestlé S.A. occupy positions anchored by scaled manufacturing infrastructure and global R&D networks. PepsiCo Inc. exemplifies the snack-cereal convergence archetype, leveraging distribution density across convenience retail channels. These three entities represent the scale-driven end of competitive positioning, though their strategic responses to EFSA and FDA reformulation mandates vary by regional regulatory exposure.
| Leading Market Players |
|---|
| The Kellogg Company |
| Mondelēz International |
| Nestlé S.A. |
| Conagra Brands Inc. |
| The Kraft Heinz Company |
| PepsiCo Inc. |
| Unilever PLC |
| Dr. Oetker |
| General Mills Inc. |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between North American grain cooperatives and cereal manufacturers lock in both supply access and price visibility across multi-year procurement cycles. These arrangements insulate branded producers from spot-market volatility while binding working capital to inventory positions ahead of harvest cycles.
Pricing Analysis
Industrial OEM buyers anchor subscription-based pricing structures across employer-subsidized breakfast programs. Three-tier pricing structure across premium, standard, and economy levels separates regenerative-certified organic lines from conventional formulations and private-label alternatives. Cost compression in the standard tier is intensifying because private-label manufacturers are capturing shelf space through aggressive promotional calendars. Foodservice operators demonstrate the highest price sensitivity due to volume procurement and contract renegotiation cycles, while health-conscious consumers in California and New York metro areas absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Strait of Hormuz transit underwrites a small but critical share of palm oil and tropical ingredient flows for European breakfast spread manufacturing. Supply concentrates in the United States for wheat and oat inputs, Canada for pulse protein isolates, and Germany for specialized muesli ingredient processing. Raw material dependencies span heritage grain varieties, spray-dried protein isolates, and fiber-based barrier packaging substrates. Single-source vulnerability runs through concentrated organic oat sourcing from the North American plains. Distribution runs through hybrid models combining direct-to-consumer subscription fulfillment with traditional retail slotting agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated foodservice procurement teams and employer-subsidized program administrators, fragmenting individual household purchasing influence across urban United States corridors.
For Market Incumbents: Secure regenerative agriculture certification pipelines through backward integration into grain sourcing networks before USDA Organic transitions tighten supplier qualification windows. Invest in spray-dried protein fortification capabilities to defend against mid-tier brands licensing turnkey systems from specialty ingredient suppliers. Channel control through direct-to-consumer subscription platforms offers margin recovery from retail slotting fee compression. For New Entrants and Emerging Players: Anchor in the functional ingredient convergence segment targeting probiotic and adaptogenic oatmeal formats for wellness-positioned consumers in California and New York metro areas. White-space opportunity concentrates in personalized nutrition algorithms paired with auto-replenishment models for young professionals seeking 90-day breakfast commitments. Employer-subsidized breakfast programs represent the most penetrable channel through direct supply contract negotiation with technology and finance sector employers. For Investors and Strategic Acquirers: Direct-to-consumer subscription-native brands built on personalized nutrition algorithms offer the strongest acquisition target archetype for portfolio exposure to channel fragmentation. Long-term viability hinges on regulatory compliance infrastructure capable of navigating simultaneous FDA and EFSA reformulation mandates without launch schedule disruption. Signal to watch is EFSA novel food assessment timeline compression for alternative proteins, which would accelerate European market entry velocity for compliant portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Agriculture Certification | USDA Organic transitions toward soil health verification create shelf price premiums in natural grocery segments. |
| Direct-to-Consumer Subscription Launch | Auto-replenishment models bypass traditional retail slotting fees while locking in 90-day purchase commitments. |
| Protein Fortification Technology Licensing | Spray-dried protein isolates decompose capital barriers separating mass-market and premium nutrition positioning. |
| EU Green Deal Packaging Compliance | Fiber-based barrier material development captures preferential retail placement across German and French chains. |
| Functional Ingredient Convergence | Probiotic and adaptogenic oatmeal additions target stress-management positioning for wellness-focused consumers. |
Research Approach
Initial hypotheses were tested against primary input from brand managers, category buyers at retailers, supply planners, and channel sales heads and refined through secondary validation across Nielsen retail audit data, customs records, SEC 10-K filings, and FDA nutritional labeling submissions. Bottom-up volume modeling across product type, distribution channel, customer segment, and packaging format dimensions was triangulated against top-down macroeconomic indicators.
Variance decomposition across the projection horizon isolates drivers by segmentation dimension including product format, distribution channel, customer archetype, and regional regulatory cluster. CAGRs were derived from modeled volume and value outputs reflecting ingredient cost trajectories, pricing elasticity assumptions, and channel mix evolution. Industry-specific forecast inputs encompass wheat and oat harvest variability cycles, EFSA additive approval timelines, and employer-subsidized program adoption rates.
Underlying assumptions cover hybrid work normalization persistence, EU Green Deal packaging compliance deadlines, and protein fortification technology diffusion curves, with deviation risk concentrated in climate-driven input volatility and regulatory timeline compression. Practitioners should keep alternative scenarios live as clean-label threshold evolution and novel food assessment velocity shift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Man-Made Sausage Casing Market
Packaged Foods
Freekeh Market
Packaged Foods
Packaged Zhug Market
Packaged Foods
US Packaged Food Market
Packaged Foods
China Packaged Food Products Market
Packaged Foods
South America Breakfast Cereals Market
Packaged Foods
Mexico Packaged Food Products Market
Packaged Foods
United Kingdom Food Spreads Market
Packaged Foods
United Arab Emirates Food Products Market
Packaged Foods
Canned Pasta Market
Packaged Foods
Burritos Market
Packaged Foods
Reduced Salt Packaged Foods Market
Packaged Foods
Cocoa Fillings Market
Packaged Foods
Europe Noodles and Pasta Market
Packaged Foods
Global Aseptic Packaging in Food Market
Packaged Foods
Carbon Labeled Packaged Meal Market