
 North America Ready Meals Market | 2026-2036
North America Ready Meals Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ready Meals Market Analytics
Modular meal-kit bundling is broadening buyer choice across the North America ready meals landscape. Conagra Brands leverages its frozen-meal manufacturing scale to occupy value-tier retail slots. HelloFresh Group specializes in subscription-based ingredient modules that compete directly with conventional ready-to-eat formats. Tyson Foods anchors protein-forward ready meals through its captive poultry supply chain.
North America ready meals comprise pre-cooked, portioned food products requiring minimal preparation beyond heating, typically formulated with moisture content below seventy percent for shelf stability and packaged under modified atmosphere or vacuum-sealed conditions to inhibit microbial growth. Frozen meals retain the largest value share among product types due to extended distribution reach and established cold-chain infrastructure, while chilled meals capture premium margin pools through fresher ingredient positioning and shorter ingredient decks. Online retail distribution is accelerating fastest among channels as direct-to-consumer platforms bypass traditional grocery slotting fees and capture recurring revenue through subscription mechanics.
The FDA governs nutrition labeling, allergen declarations, and pathogen standards across US ready meal production, while Health Canada and the PMRA enforce parallel safety and pesticide residue thresholds for Canadian-market products. USDA inspection requirements for meat-containing ready meals create dual-jurisdiction compliance costs that favor larger producers with dedicated regulatory affairs capacity. Stakeholders must monitor evolving front-of-package labeling mandates and state-level sodium warning laws that could force rapid reformulation cycles or channel-specific product variants.
Market Dynamics
Single-person household formation in the United States and Canada is compressing traditional bulk-pack economics while pulling formulation toward single-serve portions and modular meal architectures that minimize waste and preparation time.
Growth Catalysts
- FDA Sodium Reduction Targets:The agency's voluntary sodium targets for packaged foods are accelerating reformulation investments that create cleaner-label positioning and premium price realization across frozen and chilled segments.
- Direct-to-Consumer Subscription Mechanics:Recurring revenue platforms are bypassing traditional grocery slotting fees and capturing lifetime value through predictive demand algorithms and flexible portion customization.
- Urban Coastal Corridor Clustering:Time-scarce professionals in Seattle, Boston, and Toronto are concentrating demand for premium chilled meals with shorter ingredient decks and transparent sourcing claims.
Market Restraints
- Cold-Chain Infrastructure Gaps:Rural distribution networks in the Canadian Prairies and US Mountain West impose temperature excursion risks that limit chilled meal penetration and elevate insurance costs.
- USDA Dual-Jurisdiction Compliance:Meat-containing ready meals trigger simultaneous FDA and USDA inspection requirements that favor large producers with dedicated regulatory affairs capacity and disadvantage regional entrants.
- Fresh Ingredient Substitution:Meal-kit ingredient modules and quick-service restaurant delivery apps are capturing occasion share from conventional frozen ready meals among younger demographic cohorts.
Strategic Opportunities
- Health Canada Front-of-Package Labeling:The proposed mandatory warning symbols for high-sodium and high-sugar products create first-mover advantage for reformulated SKUs that preempt compliance deadlines.
- Precision Fermentation Proteins:Cultured meat and dairy alternatives are converging with retort processing to enable novel premium positioning in ethical-consumption segments without conventional supply chain constraints.
- Retail Media Network Integration:Kroger and Walmart retail media platforms are enabling targeted shopper marketing that converts purchase-intent data into personalized ready meal recommendations at digital shelf edge.
Industry Challenges
- Reformulation Cycle Compression:Overlapping state-level sodium warning laws in New York and California are forcing parallel product variants that fragment production runs and complicate inventory planning.
- Modified Atmosphere Packaging Scale-Up:Transitioning from frozen to chilled formats requires capital-intensive MAP line investments and nitrogen supply contracts that strain mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ready Meals Market |
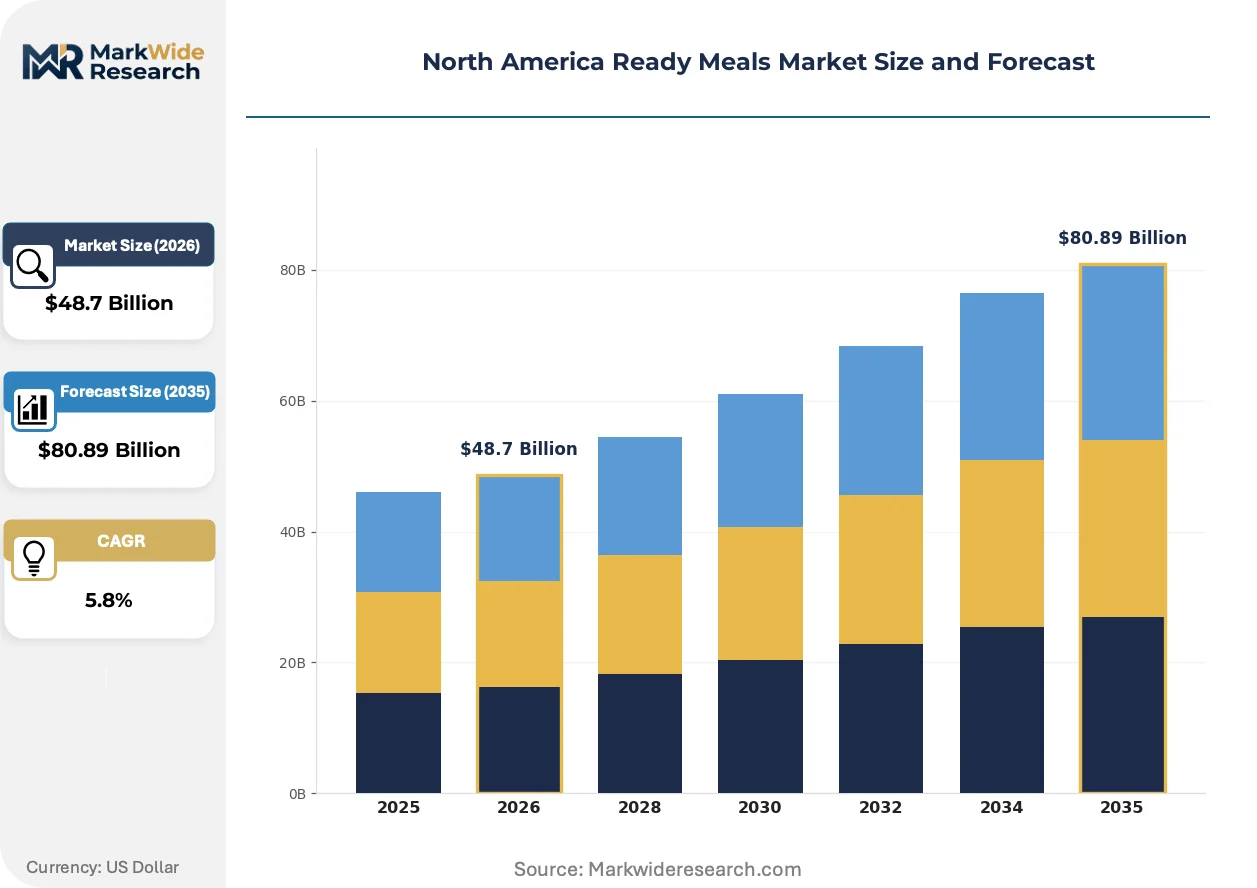
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $80.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Meals, Chilled Meals, Heat & Serve, Shelf-Stable Meals Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Foodservice Customer Type: Working Professionals, Families, Students, Health-Conscious Consumers Packaging Type: Plastic Containers, Boxed Meals, Cans, Pouches |
| Companies Covered | Nestle SA, Conagra Brands, The Kraft Heinz Company, General Mills Inc., Tyson Foods Inc., HelloFresh Group, Campbell Soup Company, Hormel Foods Corporation, Unilever PLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ready Meals Market Evolving Landscape
Technology convergence and regulatory pressure are simultaneously enabling cleaner-label positioning and compressing traditional formulation advantages across the North American ready meals landscape.
High-pressure processing is expanding into chilled ready meal preservation by inactivating pathogens without thermal degradation of sensory attributes. Urban professional households in Chicago and Vancouver are adopting HPP-treated bowls at accelerating rates, displacing traditional preservative-dependent shelf-stable formats. This technology is expanding into premium private-label programs that previously relied on frozen distribution economics.
The FDA updated Nutrition Facts labeling requirements mandate added sugar disclosure and revised serving size definitions that reshape portion architecture across all retail formats. Manufacturers must redesign packaging graphics and reformulate recipes to maintain permissible health claims under the new reference daily intake calculations. Chilled ethnic cuisine lines targeting Los Angeles and Miami Hispanic consumers face the steepest compliance timelines due to complex sauce matrices.
Subscription bundling with predictive customization is displacing conventional aisle-based discovery for time-constrained households. Direct-to-consumer platforms capture consumption-pattern data that enables dynamic menu rotation and waste-minimizing portion algorithms. This behavioral shift concentrates most visibly among dual-income households in Austin, Denver, and Montreal where meal planning friction peaks mid-week.
North America Ready Meals Market Segmentation
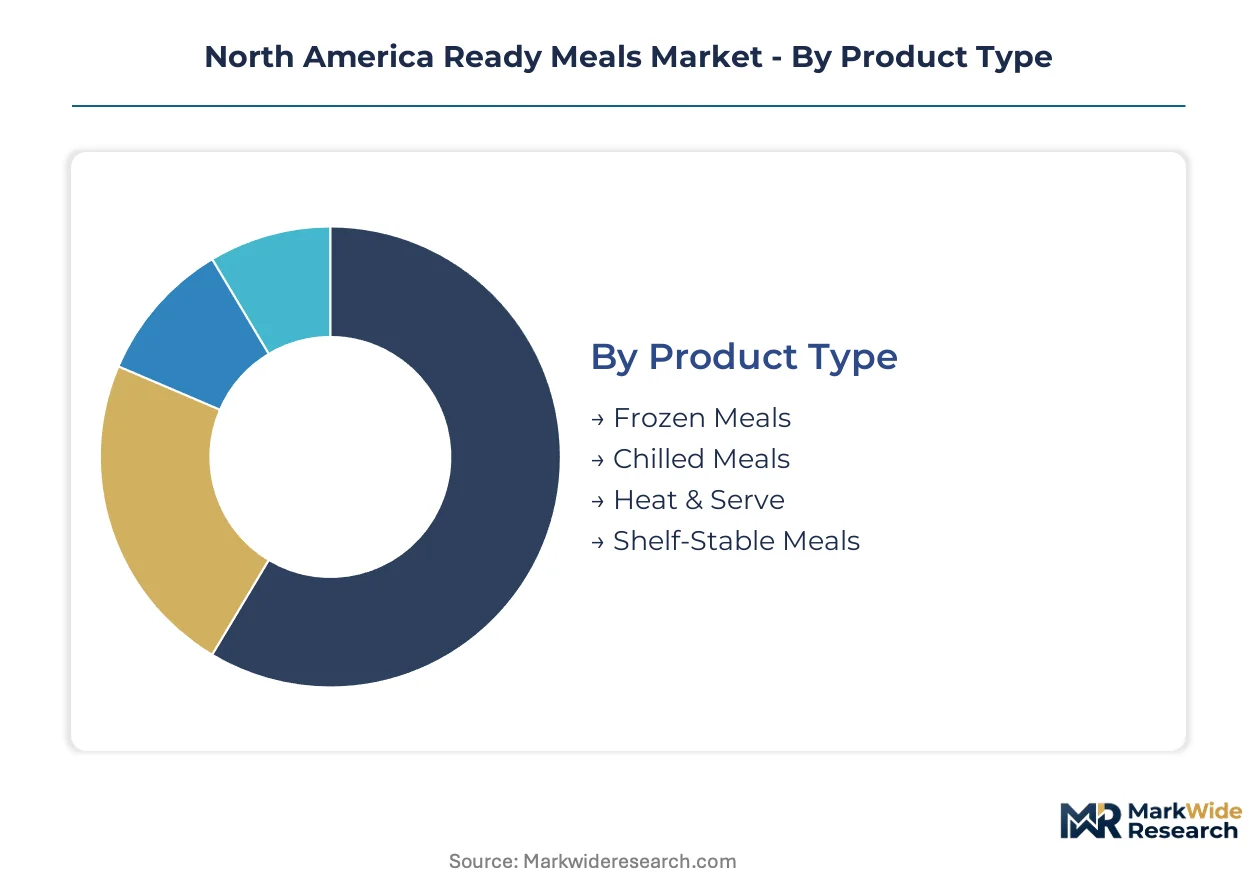
Ready meals in North America fragment across four distinct dimensions that determine formulation priorities, margin capture, and channel strategy. Each segmentation layer reveals divergent cost structures and regulatory exposure that shape competitive positioning.
Product Type:
Cost tier separates buyers seeking extended shelf life from those prioritizing sensory freshness and cleaner ingredient decks.
- Frozen Meals:These products undergo blast freezing at temperatures below minus eighteen degrees Celsius to arrest microbial activity and preserve texture. Demand concentrates among budget-conscious households in the US Midwest and Canadian Prairies where cold-chain infrastructure is mature and price elasticity is highest.
- Chilled Meals:Refrigerated formats rely on modified atmosphere packaging and high-pressure processing to achieve fourteen to twenty-one day shelf life without freezing damage. Urban coastal corridors from Seattle to Boston drive adoption as time-scarce professionals accept premium pricing for fresher ingredient positioning and transparent sourcing claims.
- Heat & Serve:These ambient-stable products utilize retort sterilization to eliminate pathogens while maintaining portability for institutional and emergency-preparedness applications.
- Shelf-Stable Meals:Canned and pouch formats serve military procurement, disaster relief stockpiles, and remote resource extraction camps where refrigeration is unavailable.
Volume sits with frozen formats across mass retail; growth tilts toward chilled meals in premium urban channels.
Distribution Channel:
Margin structure varies sharply by who controls the customer relationship and absorbs inventory risk.
- Supermarkets:Traditional grocery dominates unit velocity through established frozen aisles and promotional slotting programs. Kroger and Walmart capture the majority of working-family purchases in suburban Texas, Florida, and Ohio markets where weekly stock-up trips persist.
- Online Retail:Direct-to-consumer platforms bypass slotting fees and capture lifetime value through subscription mechanics. Predictive algorithms enable dynamic menu rotation that minimizes waste for dual-income households in Austin, Denver, and Montreal.
- Convenience Stores:Grab-and-go chilled formats serve impulse occasions and late-night demand in dense urban cores.
- Foodservice:Bulk prepared meals supply corporate cafeterias, hospital systems, and university dining halls with cost-controlled portion consistency.
Supermarkets retain transaction volume; online retail is climbing the fastest as subscription bundling displaces aisle-based discovery.
Customer Type:
Application context determines whether buyers prioritize speed, nutrition density, or unit economics.
- Working Professionals:Time-scarce households in Seattle, Boston, and Toronto concentrate demand for single-serve premium chilled bowls with sub-five-minute preparation requirements.
- Families:Multi-person households sustain frozen multi-pack economics and drive bulk-format purchasing across suburban retail corridors.
- Students:Campus-adjacent demand favors value-tier frozen entrees and shelf-stable formats with minimal kitchen equipment requirements.
- Health-Conscious Consumers:This cohort selects high-protein, low-sodium, and plant-forward formulations that comply with FDA sodium reduction targets and emerging front-of-package labeling mandates.
Working professionals anchor premium pricing power; health-conscious consumers are gaining share fastest as regulatory pressure accelerates reformulation investment.
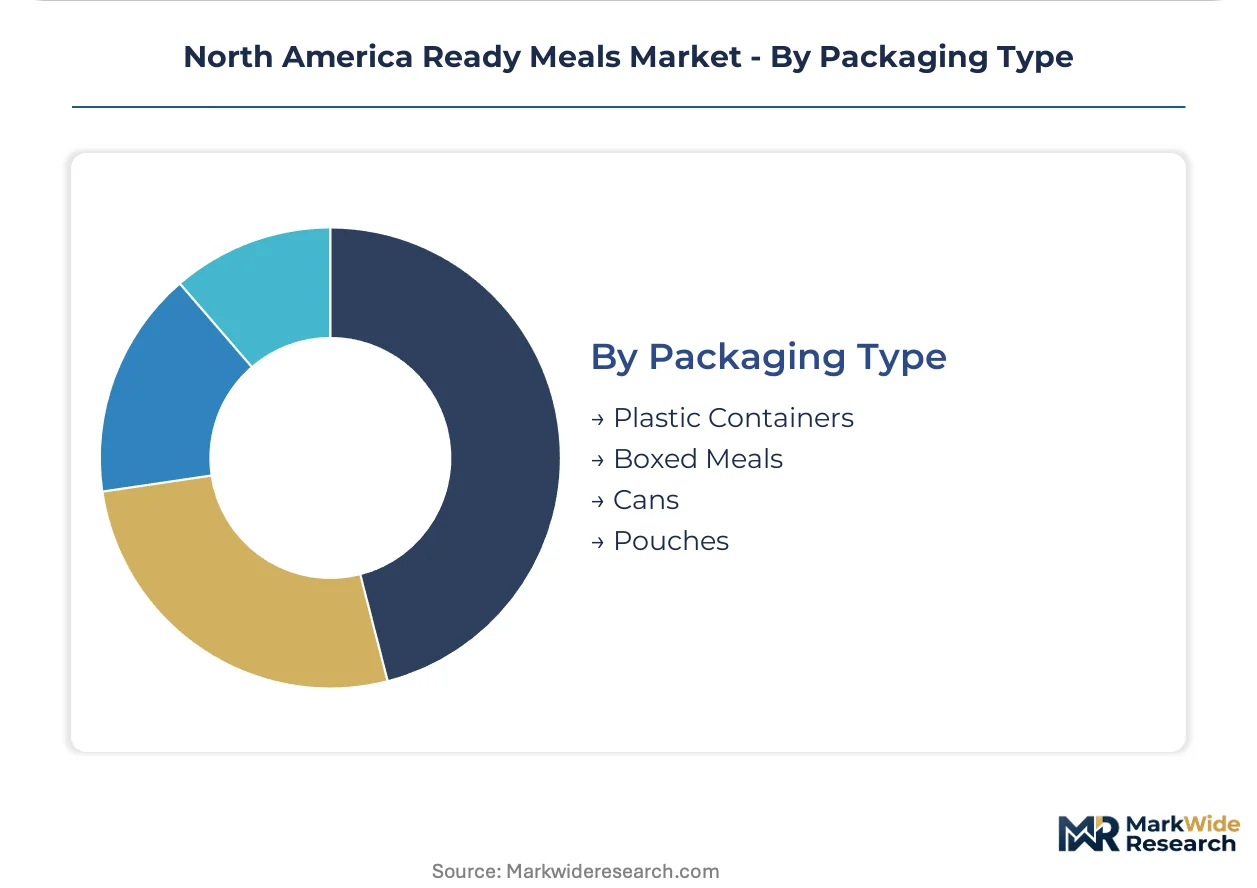
Packaging Type:
Supply concentration and sustainability exposure differentiate material choices across temperature requirements.
- Plastic Containers:Polypropylene and PET formats dominate frozen and chilled segments due to microwave compatibility and optical clarity for shelf appeal.
- Boxed Meals:Paperboard with polyethylene barriers serves shelf-stable and frozen applications where stackability and print surface for branding are prioritized.
- Cans:Metal packaging retains cost advantage for retort-processed shelf-stable formats in institutional procurement channels.
- Pouches:Flexible retort pouches reduce shipping cube and enable single-serve ambient products for outdoor recreation and emergency preparedness segments.
Plastic containers hold production scale; pouches show steepest expansion trajectory as sustainability pressures drive lightweighting and material reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign Trade Zones along the US-Mexico border and Canadian Prairie agri-processing corridors concentrate ready meal manufacturing capacity through tariff-advantaged ingredient sourcing and integrated cold-chain logistics.
United States
Single-person household formation in Seattle, Boston, and Austin compresses bulk-pack economics toward single-serve chilled formats. The FDA enforces updated Nutrition Facts labeling requirements with added sugar disclosure mandates that force packaging redesigns. Urban coastal corridors from Los Angeles to Miami concentrate premium chilled bowl adoption among time-scarce professionals.
Canada
Health Canada and the PMRA enforce pesticide residue thresholds and front-of-package labeling proposals that accelerate reformulation timelines. Toronto and Vancouver drive chilled meal demand through dual-income household density and subscription platform penetration. Prairie Provinces cold-chain infrastructure supports frozen meal distribution into rural markets.
Mexico
Manufacturing clusters in Nuevo León and Jalisco leverage USMCA tariff preferences for protein-forward ready meal exports. The country's federal consumer protection agency enforces evolving nutrition labeling standards that align with North American trade integration. Mexico City Metro concentrates domestic demand for shelf-stable retort formats.
North America Ready Meals Market Competitive Landscape
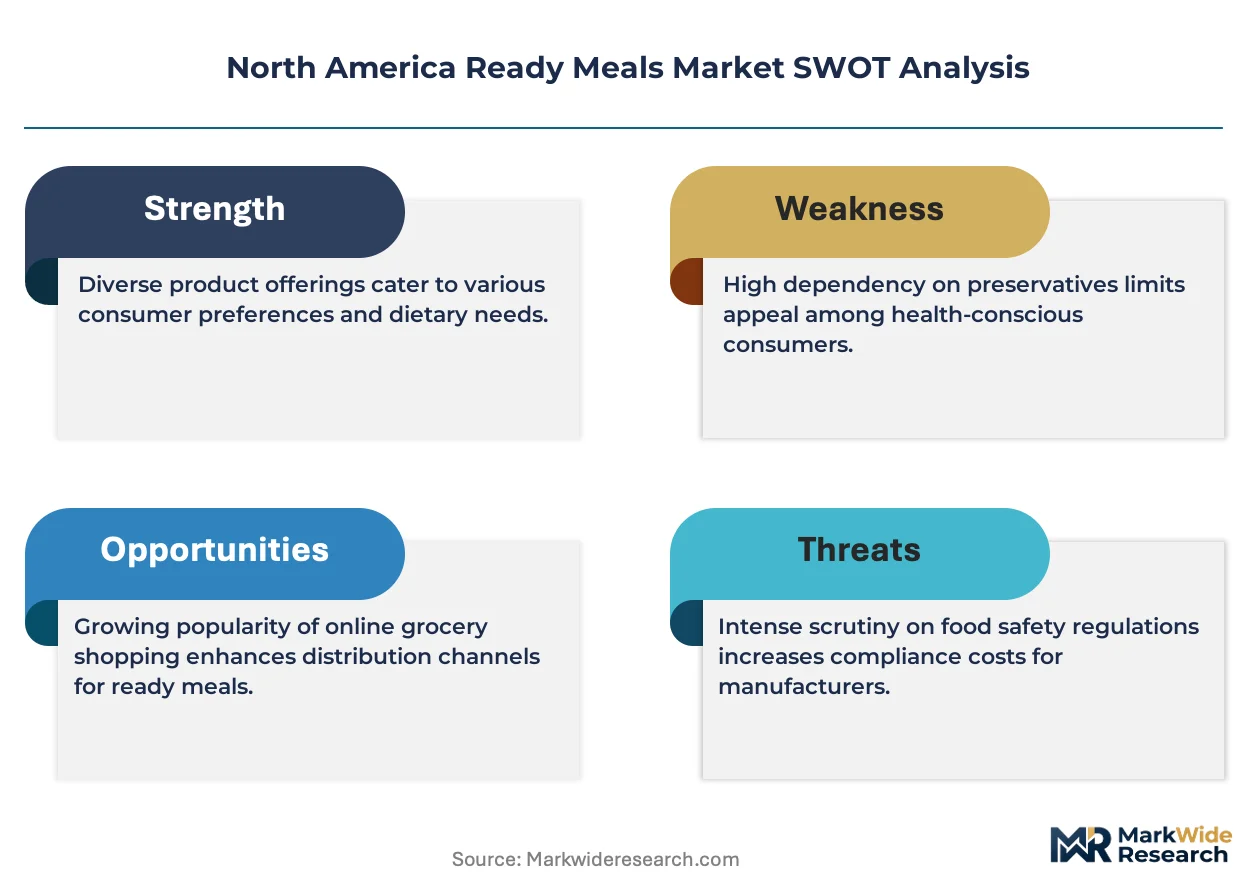
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressure favors multi-brand portfolios with regulatory affairs capacity and cold-chain scale. Three archetypes dominate: multinational CPG conglomerates with frozen manufacturing scale, subscription-native meal-kit platforms with predictive demand algorithms, and protein-integrated processors with captive supply chains. Competitive moves center on portfolio diversification into chilled formats and strategic partnerships with retail media networks.
Within the multinational CPG tier, Nestle SA and Conagra Brands exemplify scale-driven frozen manufacturing positions. HelloFresh Group occupies the subscription-native archetype with direct-to-consumer platform mechanics. Tyson Foods anchors the protein-integrated model through poultry supply chain control. Each represents distinct strategic positioning rather than interchangeable market presence.
| Leading Market Players |
|---|
| Nestle SA |
| Conagra Brands |
| The Kraft Heinz Company |
| General Mills Inc. |
| Tyson Foods Inc. |
| HelloFresh Group |
| Campbell Soup Company |
| Hormel Foods Corporation |
| Unilever PLC |
| Others |
Value Network & Pricing Analysis
Protein input costs cascade from Tyson Foods' captive poultry operations and Midwest grain-fed beef suppliers through three-tier pricing structure across premium, standard, and economy levels, with MAP line investments and nitrogen supply contracts compressing mid-tier manufacturer margins while subscription-native platforms capture recurring revenue premiums.
Pricing Analysis
Margin tightening in the chilled segment reflects capital-intensive MAP line investments and nitrogen supply contract escalations that strain mid-tier balance sheets. Three-tier pricing structure across premium, standard, and economy levels separates HPP-treated organic bowls from conventional frozen entrees and value-tier multi-packs. Price differentiation rests on certification grade for USDA organic and non-GMO verification plus geographic delivery cost differentials between urban coastal corridors and Prairie distribution networks. Cost-down pressure on frozen multi-packs accelerates because HelloFresh subscription mechanics and quick-service restaurant delivery apps capture occasion share among younger cohorts. Health-conscious consumers in Seattle and Boston show least price sensitivity; Midwest working families sustain highest elasticity.
Supply Chain Analysis
Reverse-logistics flows for temperature-compromised chilled products impose write-off costs that frozen formats avoid through extended shelf stability. Supply concentrates in the United States, Canada, and Mexico through USMCA-advantaged protein processing and integrated cold-chain logistics. Raw material dependencies center on Midwest grain-fed proteins, California vegetable inputs, and retort pouch aluminum laminates. Single-source vulnerability sits with nitrogen supply contracts for MAP operations and limited HPP tolling capacity in Prairie regions. Distribution runs through Kroger and Walmart retail media networks that convert purchase-intent data into personalized recommendations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modified atmosphere packaging capacity scarcity props pricing premiums for chilled formats, constraining mid-tier manufacturer expansion and favoring conglomerates with dedicated capital reserves.
For Market Incumbents: Lock in regulatory affairs capacity to navigate overlapping FDA sodium reduction targets and state-level warning laws in New York and California. Defend margin position through backward integration into captive poultry supply chains following Tyson Foods' model, while preempting Health Canada front-of-package labeling mandates with reformulated SKUs ahead of compliance deadlines. Counter subscription-native platforms by embedding predictive demand algorithms into retail media network partnerships. For New Entrants and Emerging Players: Enter via precision fermentation protein convergence with retort processing to bypass conventional supply chain constraints and capture ethical-consumption premiums. Target Canadian Prairie markets where cold-chain infrastructure gaps limit incumbent chilled penetration and frozen multi-pack economics dominate. Deploy direct-to-consumer subscription mechanics with waste-minimizing portion algorithms to dislodge established retail slotting arrangements. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier manufacturers with MAP line assets in Nuevo León and Jalisco corridors, where USMCA tariff preferences sustain export economics. Long-term viability hinges on regulatory affairs capacity and cold-chain scale rather than brand equity alone. Watch for Health Canada mandatory warning symbol implementation as inflection indicator for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Protein Supply | Tyson Foods' poultry supply chain control anchors cost position against feed price volatility. |
| Direct-to-Consumer Subscription Launch | HelloFresh predictive algorithms bypass Kroger slotting fees and capture lifetime value. |
| MAP Line Capacity Expansion | Nitrogen supply contracts and HPP tolling access determine chilled format market entry feasibility. |
| Retail Media Network Partnership | Walmart digital shelf-edge integration converts purchase-intent data into personalized recommendations. |
| Precision Fermentation Protein Integration | Cultured meat alternatives enable novel premium positioning without conventional supply chain constraints. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving brand managers at Conagra and Nestle, category buyers at Kroger and Walmart, supply planners at Tyson Foods, channel sales heads, and regulatory affairs leads. FDA sodium target documentation, Health Canada front-of-package labeling proposals, USDA inspection requirement filings, and Nielsen retail audit data provided validation layers. Bottom-up SKU-level modeling and top-down category sizing triangulated volume estimates.
Data-stream reconciliation across shipment volumes, retail velocity, and subscription platform disclosures stabilized baseline assumptions. Segmentation dimensions modeled include product type, distribution channel, customer archetype, and packaging format across the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology adoption curves. Forecast inputs incorporated cold-chain infrastructure buildout rates and precision fermentation protein cost curves.
Revisions become necessary when FDA sodium enforcement shifts from voluntary to mandatory, Health Canada warning symbol implementation accelerates, or HPP tolling capacity expansion outpaces demand. Practitioners should monitor state-level sodium warning law proliferation and nitrogen supply contract pricing for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Pastry Fillings Market
Packaged Foods
North America Breakfast Cereals Market
Packaged Foods
Packaged Currants Market
Packaged Foods
US Packaged Food Market
Packaged Foods
Morning Goods Market
Packaged Foods
Wet Pet Food Market
Packaged Foods
Sugar Free Cookies Market
Packaged Foods
US Packaged Salads Market
Packaged Foods
India Instant Noodles Market
Packaged Foods
Packaged Salad Market
Packaged Foods
Hummus Market
Packaged Foods
Chestnut Flour Market
Packaged Foods
Instant Soup Market
Packaged Foods
Europe Breakfast Cereals Market
Packaged Foods
Injectable Cocoa Fillings Market
Packaged Foods
Middle-East and Africa Ready-To-Eat Food Market