
 Asia-Pacific Pasta and Noodles Market | 2026-2036
Asia-Pacific Pasta and Noodles Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Pasta and Noodles Market Outlook
Single-serve cup packaging is hardening as the default configuration for urban convenience channels across East and Southeast Asia. Nissin Foods Holdings Co. Ltd. leverages its cup-noodle technology leadership to anchor premium positioning in Japan and export markets. Indofood CBP Sukses Makmur Tbk sustains manufacturing scale through backward integration into wheat milling and palm-oil processing. Tingyi (Cayman Islands) Holding Corp. dominates China's mass-market instant-noodle segment through deep distribution into lower-tier cities.
Asia-Pacific pasta and noodles encompass wheat-based dried pasta, alkaline wheat noodles, rice-vermicelli, and starch-based glass noodles manufactured through extrusion, sheeting, or hand-stretching processes, then dried, fried, or fresh-packed for shelf-stable or refrigerated distribution. The category serves household meal preparation, food-service batch cooking, and ready-to-eat convenience consumption. Spaghetti and macaroni segments hold mature volume positions in Australia and urban India where Italian-style home cooking has expanded. Udon and rice noodles represent faster-growing structural pockets as Southeast Asian restaurant chains standardize supply chains. Bags and boxes retain cost advantages for household bulk purchasing, while tubs capture food-service portion-control requirements.
Indonesia's BPOM and Badan POM enforce instant-noodle fortification mandates for micronutrient content, reshaping formulation R&D priorities for manufacturers serving the archipelago. China's SAMR and National Health Commission monitor sodium-limit guidelines that compress seasoning-sachet specifications across domestic brands. Australia's FSANZ maintains gluten-labeling strictness that filters import eligibility for wheat-based products. Stakeholders must track evolving fortification thresholds and sodium caps as these standards proliferate across ASEAN harmonization talks.
Market Dynamics
Urban convenience channels across East and Southeast Asia are hardening single-serve cup packaging as the default configuration, compressing bag-format shelf space while food-grade packaging standards from China's MIIT tighten shelf-life labeling requirements.
Growth Catalysts
- Quick-service restaurant expansion:Southeast Asian QSR chains are expanding noodle-centric menus, pulling volume through centralized procurement contracts with manufacturers.
- Fortification mandates:Indonesia's BPOM and Badan POM enforce instant-noodle micronutrient content rules, forcing formulation R&D investment that raises category quality floors.
- Backward integration:Wheat milling and palm-oil processing captive supply chains reduce input cost volatility for integrated manufacturers serving archipelago markets.
Market Restraints
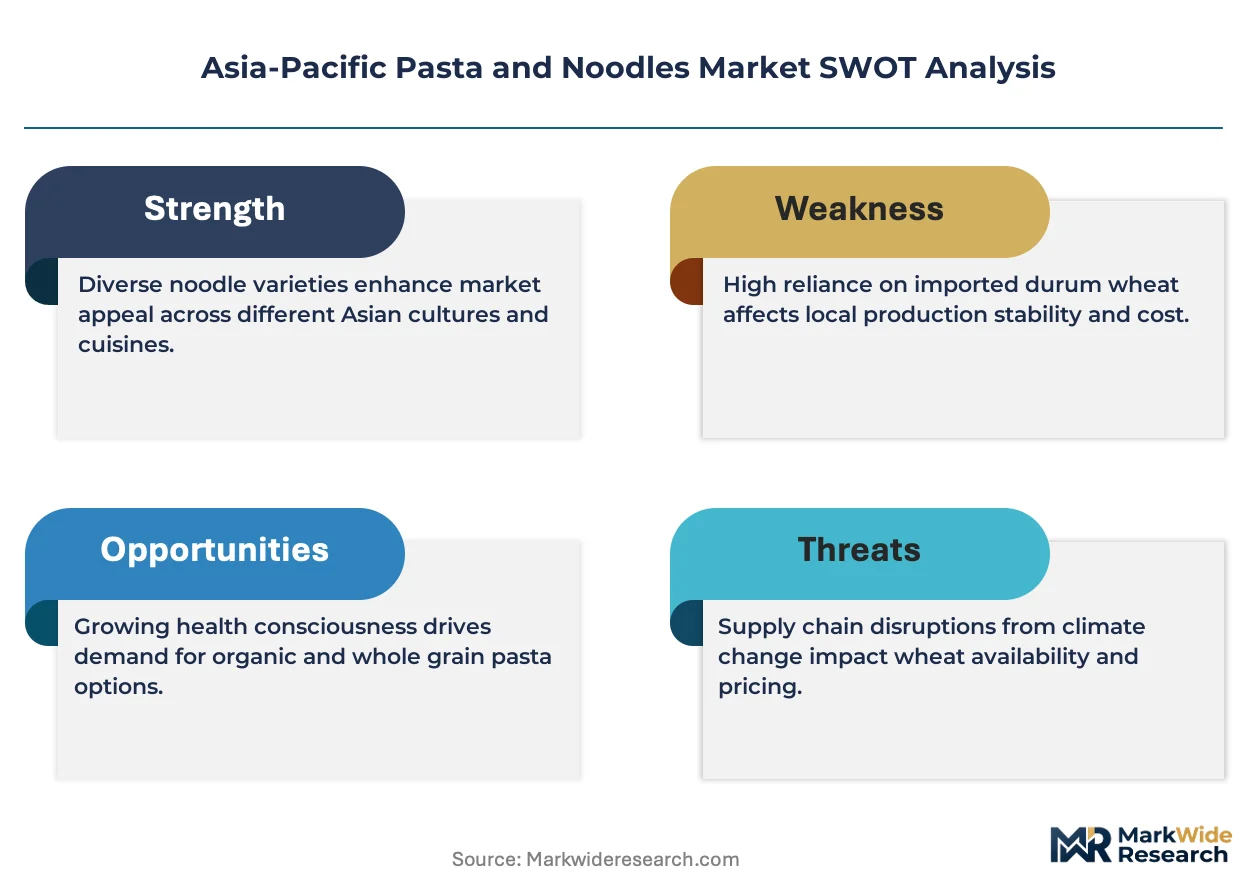
- Wheat price volatility:Input cost swings for wheat flour compress margin stability for non-integrated processors lacking captive milling capacity.
- Sodium-limit guidelines:China's SAMR and National Health Commission seasoning-sachet specifications constrain flavor intensity that drives repeat purchase in mass-market segments.
- Gluten-labeling strictness:Australia's FSANZ standards filter import eligibility for wheat-based products, raising compliance costs for regional exporters.
Strategic Opportunities
- Lower-tier city penetration:China's inland provinces and county-level cities remain underpenetrated for premium cup-noodle formats relative to coastal saturation.
- Udon and rice noodle standardization:Southeast Asian restaurant chain supply chain consolidation creates volume contracts for standardized fresh-packed and frozen formats.
- ASEAN harmonization talks:Emerging regulatory alignment on fortification thresholds and sodium caps will reduce multi-jurisdiction compliance fragmentation for regional portfolios.
Industry Challenges
- Seasoning-sachet reformulation timelines:Sodium reduction targets require R&D cycles that lag procurement contract renewal windows, creating specification mismatches with food-service buyers.
- Packaging line reconfiguration:Shelf-life labeling upgrades to meet MIIT standards force capital deployment into printing and tracking systems mid-contract.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Pasta and Noodles Market |
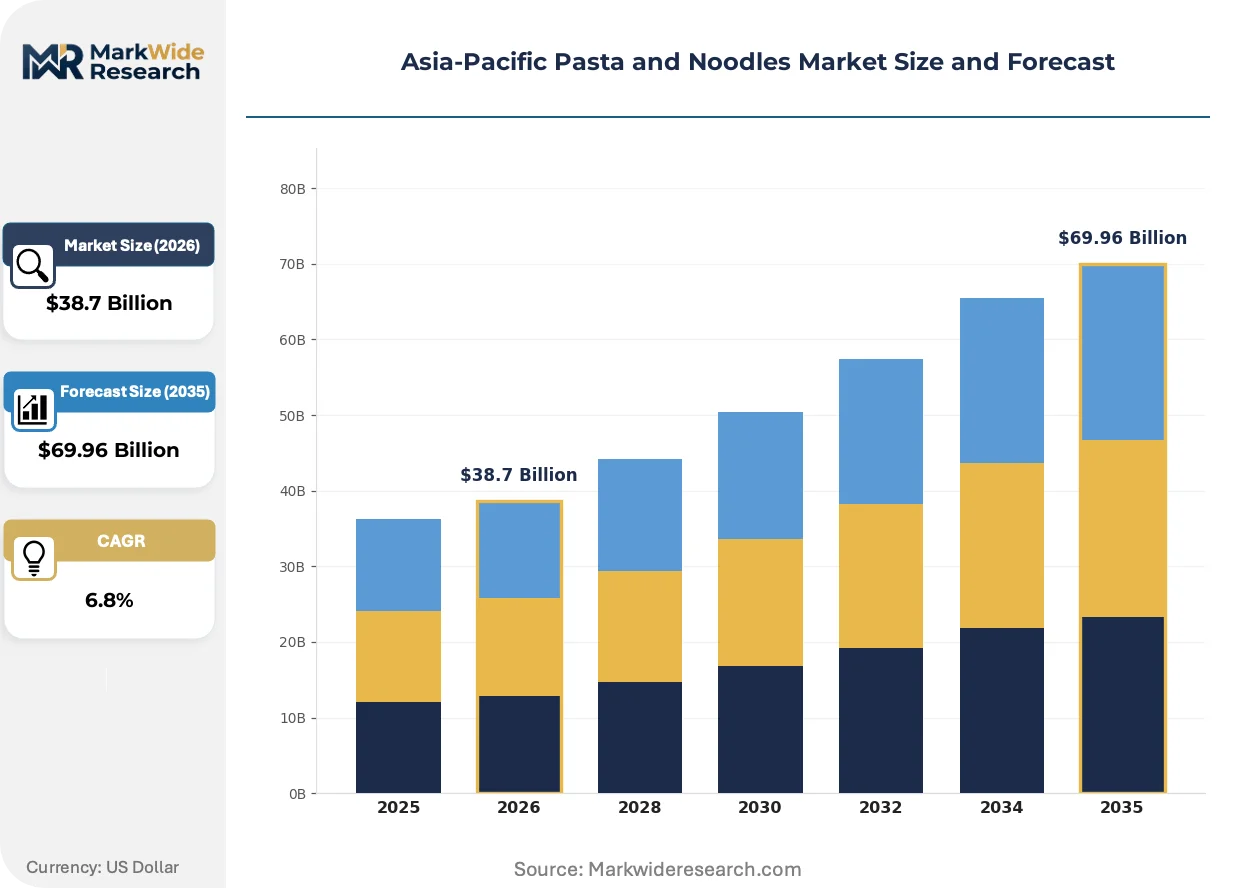
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spaghetti, Macaroni, Udon, Rice Noodles End User: Households, Restaurants, Cafes, Catering Services Packaging Type: Bags, Boxes, Cartons, Tubs Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Wholesale |
| Companies Covered | Samyang Foods Inc., Indofood CBP Sukses Makmur Tbk, Nestlé S.A., Nongshim Holdings, Tingyi (Cayman Islands) Holding Corp., Unilever PLC, ITC Limited, Uni-President Enterprises Corporation, Nissin Foods Holdings Co. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Pasta and Noodles Market Strategic Shifts
Extrusion and sheeting process refinements are absorbing automation investment while regulatory sodium ceilings and fortification floors reshape formulation priorities across the region's manufacturing corridors.
Non-fried noodle production technology is absorbing capital allocation from traditional fried-line expansion as health-positioned segments gain shelf space in Japan and urban China. Mid-tier manufacturers in Thailand and Vietnam are adopting air-drying and hot-air drying systems to access premium channel placement previously captured by Japanese imports. This shift is compressing oil-intensive processing capacity utilization while raising energy input requirements per unit output.
China's SAMR sodium-limit guidelines are forcing seasoning-sachet downsizing across domestic instant-noodle brands, compressing flavor intensity specifications that historically drove repeat purchase. Manufacturers are responding with umami-boosting yeast extracts and hydrolyzed protein alternatives to maintain sensory satisfaction within regulatory bounds. Mass-market segments in lower-tier Chinese cities face the steepest reformulation pressure given their dependence on seasoning-heavy consumption occasions.
Food-service procurement consolidation is concentrating volume among centralized buyers for Southeast Asian restaurant chains, displacing fragmented distributor relationships with direct manufacturer contracts. This channel shift is visible in Vietnam and Indonesia where noodle-centric QSR expansion is standardizing supply chains around frozen and fresh-packed formats rather than dried alternatives. Procurement teams now specify consistency metrics and traceability documentation previously absent from traditional wholesale arrangements.
Asia-Pacific Pasta and Noodles Market Segmentation
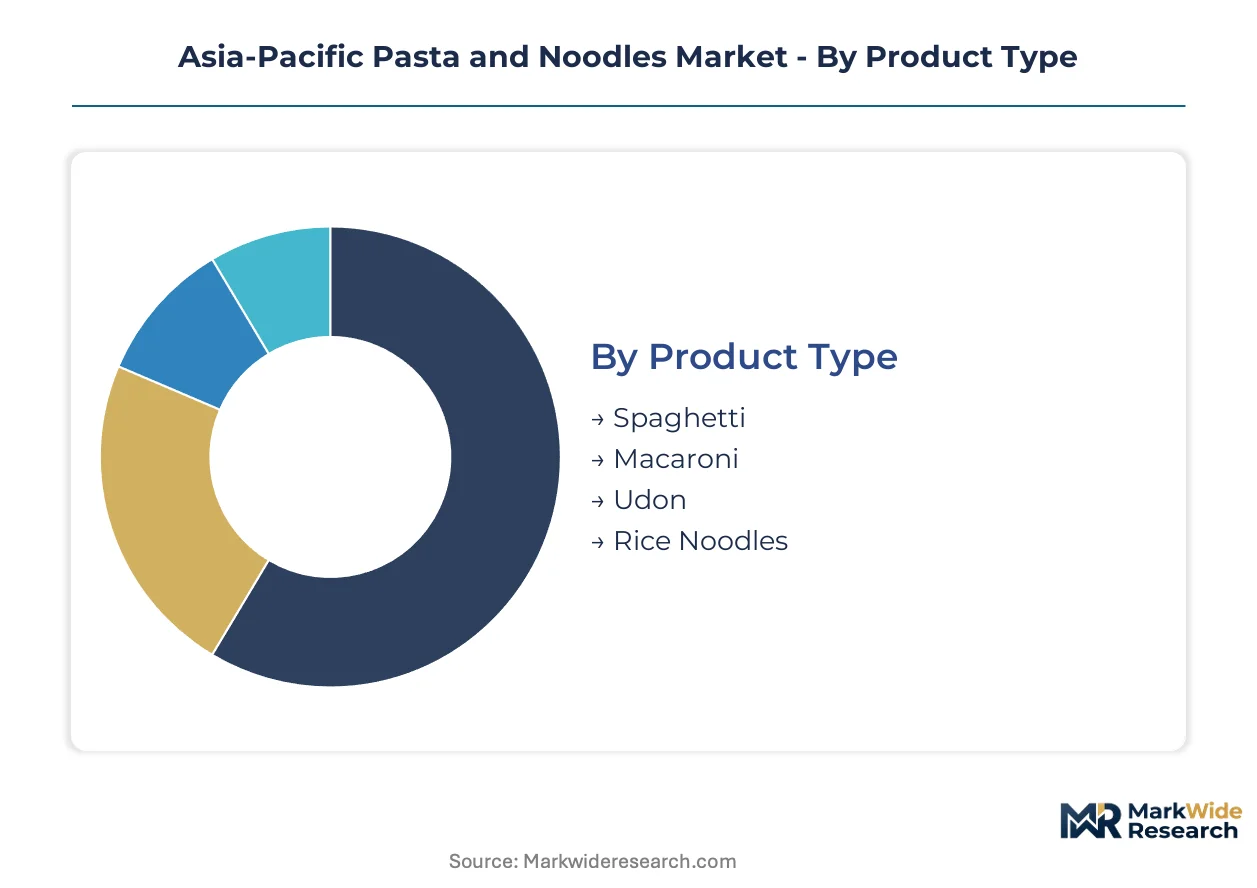
Segmentation in Asia-Pacific pasta and noodles reveals how capital deployment, regulatory exposure, and channel economics split across distinct manufacturing and consumption configurations. Each dimension carries different margin profiles and compliance burdens that reshape competitive positioning.
Product Type:
Extrusion and sheeting equipment intensity varies sharply across wheat-based and starch-based formats, with alkaline noodle lines demanding specialized fermentation infrastructure.
- Spaghetti:Durum wheat extrusion through bronze or Teflon dies produces surface texture variations that anchor premium Italian-style positioning in Australia and urban India. Australian FSANZ gluten-labeling strictness filters import eligibility, compressing shelf space for non-compliant regional suppliers.
- Udon:Alkaline wheat noodles require controlled fermentation tanks and resting chambers that extend production cycles versus standard extrusion. Southeast Asian restaurant chains are standardizing supply chains around frozen and fresh-packed formats, pulling volume through centralized procurement contracts.
- Macaroni:Short-cut extruded shapes serve food-service batch cooking and institutional catering with portion-control advantages.
- Rice Noodles:Starch gelatinization and steam-sheeted processing dominate Vietnam and Thailand manufacturing corridors for pho and pad thai applications.
Most installed capacity flows through spaghetti and macaroni lines given mature demand in Australia and India. Expansion is steepest in udon as Southeast Asian QSR chains consolidate supply chains.
End User:
Volume concentration and specification stringency diverge sharply between fragmented household purchasing and consolidated food-service procurement.
- Households:Bag and box formats dominate bulk purchasing for meal preparation, with seasoning-sachet intensity driving repeat purchase in mass-market Chinese cities. China's SAMR sodium-limit guidelines are forcing downsizing that compresses flavor specifications.
- Restaurants:Noodle-centric QSR expansion across Vietnam and Indonesia is standardizing supply chains around frozen and fresh-packed formats with consistency metrics and traceability documentation.
- Cafes:Single-serve cup configurations capture urban convenience consumption with premium positioning in Japan and export markets.
- Catering Services:Tubs and bulk bags serve institutional portion-control requirements with cost advantages over individually packaged alternatives.
Procurement consolidation is concentrating volume among restaurant chains. Household segments retain the widest SKU diversification.
Packaging Type:
Food-grade packaging standards and shelf-life labeling requirements from China's MIIT are forcing capital deployment into printing and tracking systems.
- Bags:Polypropylene and laminated film configurations retain cost advantages for household bulk purchasing across lower-tier Chinese cities and Indonesian archipelago markets.
- Boxes:Paperboard cartons with window features serve premium retail placement in Japanese and Australian supermarkets where visual product inspection drives selection.
- Cartons:Multi-pack configurations capture warehouse club and wholesale channel economics with palletization efficiency.
- Tubs:Injection-molded and thermoformed containers capture food-service portion-control requirements and single-serve convenience channel placement across East Asian urban centers.
Single-serve cup packaging is hardening as the default configuration for urban convenience channels. Bag-format shelf space is compressing accordingly.
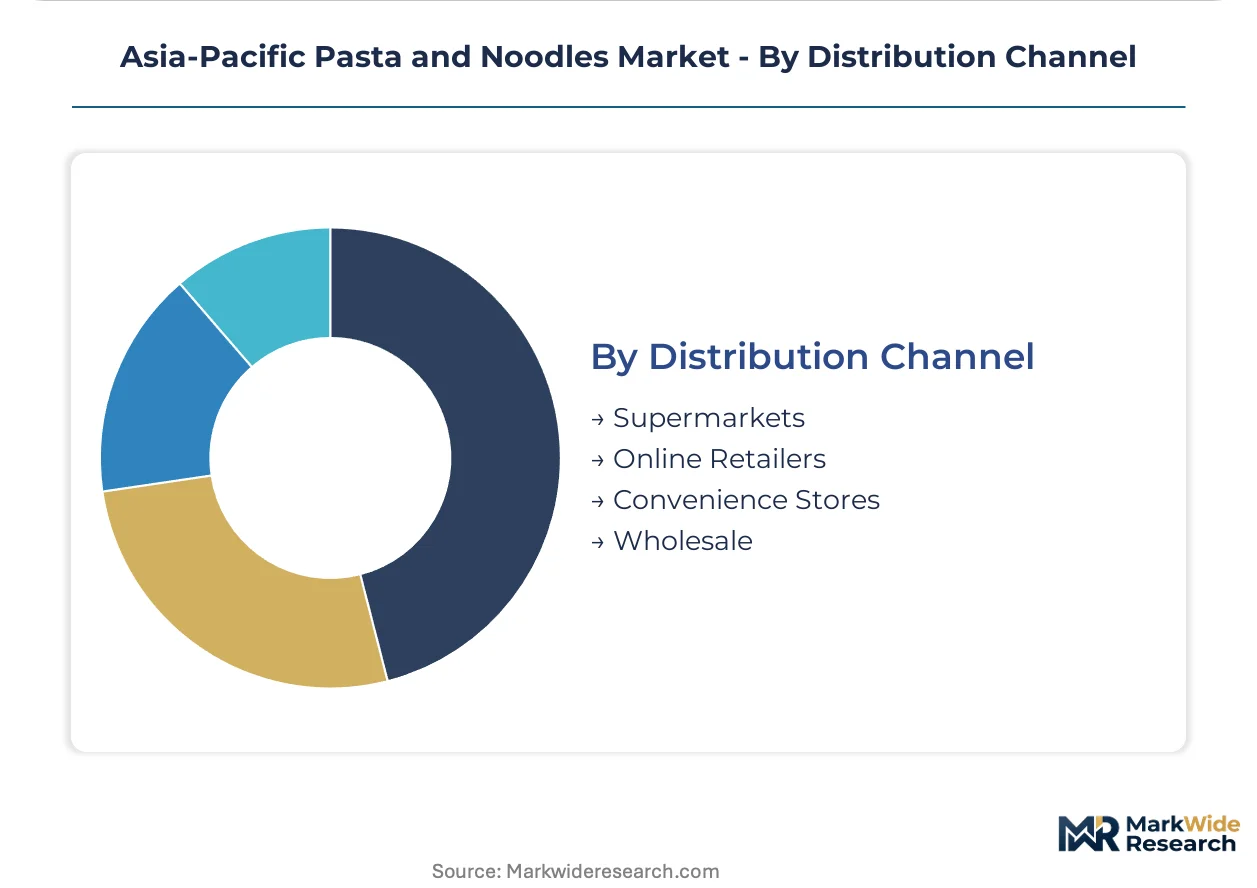
Distribution Channel:
Channel mix determines working capital intensity and traceability documentation burdens, with direct manufacturer contracts displacing fragmented distributor relationships.
- Supermarkets:Modern trade shelf-space fees and promotional calendar compliance dominate Australia, Japan, and coastal Chinese cities where category management practices are most advanced.
- Online Retailers:E-commerce platforms capture premium and imported noodle sales in urban China and Japan with delivery-speed competition reshaping packaging durability specifications.
- Convenience Stores:High-turnover single-serve cup placement dominates East Asian urban corridors with refrigerated and ambient shelf-space optimization.
- Wholesale:Traditional distributor networks retain cost advantages for rural Indonesian and Vietnamese markets with fragmented last-mile logistics.
Direct manufacturer contracts are displacing wholesale fragmentation in restaurant procurement. Supermarket and convenience channels retain household volume concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Instant-noodle manufacturing scaled from post-war Japan through 1950s Osaka before dispersing across East and Southeast Asian manufacturing corridors. Contemporary production gravity concentrates in five national markets where regulatory frameworks and channel economics diverge sharply.
China
Mass-market instant-noodle consumption concentrates in lower-tier cities and inland provinces where Tingyi anchors distribution density. SAMR sodium-limit guidelines compress seasoning-sachet specifications, forcing umami-boosting reformulation with yeast extracts. Manufacturing clusters in Henan and Guangdong provinces supply domestic volume while navigating MIIT shelf-life labeling upgrades.
Japan
Premium cup-noodle formats dominate urban convenience channels with non-fried production technology absorbing capital allocation from traditional fried-line expansion. METI standards govern food-grade packaging integrity for export-bound production. Osaka and Tokyo metropolitan manufacturing bases supply both domestic premium positioning and regional export markets.
Indonesia
Archipelago-scale demand flows through instant-noodle manufacturing corridors serving household bulk purchasing and QSR procurement consolidation. BPOM fortification mandates enforce micronutrient content floors, reshaping formulation R&D priorities. Java-based production clusters leverage backward integration into wheat milling and palm-oil processing to reduce input cost volatility.
Vietnam
Rice-vermicelli and pho-format production dominates manufacturing investment with steam-sheeted processing technology scaling in Mekong Delta and Red River Delta corridors. Restaurant chain supply chain standardization pulls volume through centralized procurement contracts with traceability documentation requirements. Mid-tier manufacturers adopt air-drying systems to access premium channel placement.
Australia
Italian-style durum wheat pasta holds mature volume positions in household meal preparation with spaghetti and macaroni segments anchored in supermarket modern trade. FSANZ gluten-labeling strictness filters import eligibility for wheat-based regional suppliers. Melbourne and Sydney distribution hubs manage compliance documentation for both domestic retail and selective export positioning.
Asia-Pacific Pasta and Noodles Market Competitive Environment
The competitive structure tilts toward integrated conglomerates with captive agricultural inputs and deep distribution infrastructure. Tiered concentration separates multinational packaged-food divisions from national champions with archipelago-scale manufacturing footprints. Three archetypes dominate: wheat-to-noodle integrated processors, brand-anchored distribution specialists, and QSR supply-chain contractors. Capacity expansion and backward integration into milling and oil processing represent the dominant competitive moves as input cost volatility compresses margin stability for non-integrated processors.
Among Asia-Pacific-based integrated manufacturers, Indofood CBP Sukses Makmur Tbk exemplifies the wheat-to-noodle archetype with archipelago-scale vertical control, while Tingyi (Cayman Islands) Holding Corp. occupies the mass-market distribution density position in China's lower-tier cities. Nissin Foods Holdings Co. Ltd. anchors premium cup-noodle technology leadership originating from Japanese manufacturing innovation. These three represent distinct strategic endpoints: agricultural integration, channel penetration depth, and product-format premiumization.
| Leading Market Players |
|---|
| Samyang Foods Inc. |
| Indofood CBP Sukses Makmur Tbk |
| Nestlé S.A. |
| Nongshim Holdings |
| Tingyi (Cayman Islands) Holding Corp. |
| Unilever PLC |
| ITC Limited |
| Uni-President Enterprises Corporation |
| Nissin Foods Holdings Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Alkaline noodle production specialists concentrated in Japan's Osaka corridor and Thailand's central plains command wage premiums that widen spreads between premium udon formats and economy instant-noodle tiers. Labor-cost differentials between fermented-noodle craftsmanship and standardized extrusion operations translate directly into pricing stratification across urban convenience channels and rural household markets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs category economics, with quality-grade differentiation separating bronze-die spaghetti from Teflon-extruded macaroni and fortification-certification tiers anchoring Indonesian import premiums. Price differentiation stems from backward integration depth and geographic delivery cost to archipelago markets. Pricing pressure runs through mass-market instant-noodle segments as China's SAMR sodium-limit guidelines compress seasoning-sachet value. Household buyers in lower-tier Chinese cities exhibit highest price sensitivity, while Japanese convenience-channel consumers show lowest elasticity for premium cup formats.
Supply Chain Analysis
Direct-to-restaurant channels handle consolidated QSR procurement across Vietnam and Indonesia, displacing fragmented wholesale relationships with manufacturer contracts specifying traceability documentation. Geographic supply concentration centers on China, Indonesia, and Vietnam, with Henan and Guangdong provinces, Java-based corridors, and Mekong Delta clusters anchoring installed capacity. Raw material dependencies draw from Australian and Canadian wheat imports, Indonesian palm-oil processing, and Thai rice-starch supplies. Single-source vulnerability in wheat milling equipment creates procurement risk for non-integrated processors. Distribution runs through supermarket modern trade in Australia and Japan, convenience-store networks across East Asian urban centers, and traditional wholesale in rural Indonesian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific pasta and noodles market represents a late-cycle quality story as Southeast Asian QSR chains shift procurement specifications toward standardized fresh-packed and frozen formats with consistency metrics previously absent from wholesale arrangements.
For Market Incumbents: Deploy backward integration into wheat milling and palm-oil processing to defend margin stability against input cost volatility threatening non-integrated processors. Deepen channel control through direct manufacturer contracts with restaurant chains consolidating procurement in Vietnam and Indonesia, while investing in non-fried production technology to meet health-positioned segment requirements in Japan and urban China. For New Entrants and Emerging Players: Begin with premium air-dried noodle production targeting mid-tier placement in Thai and Vietnamese retail channels, where Japanese import premiums have created accessible white space. Underpenetrated lower-tier Chinese cities for premium cup formats offer second entry point. Lead with umami-boosting formulation expertise to differentiate within sodium-constrained regulatory environments. For Investors and Strategic Acquirers: Packaged-food conglomerates seeking Asia-Pacific expansion are the most active acquirer in this space, targeting integrated manufacturers with captive agricultural inputs and archipelago-scale distribution infrastructure. Long-term viability hinges on regulatory compliance capabilities across multiple ASEAN jurisdictions. Monitor ASEAN harmonization progress on fortification thresholds as inflection indicator for portfolio consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wheat Milling | Captive flour supply reduces exposure to Australian and Canadian wheat price volatility for Indonesian manufacturers. |
| Non-Fried Production Technology Deployment | Air-drying systems access premium channel placement in Japan and urban China previously captured by imports. |
| Direct Restaurant Chain Contracting | Centralized procurement relationships with Vietnamese and Indonesian QSRs displace fragmented wholesale margins. |
| Umami-Boosting Formulation R&D | Yeast extract alternatives maintain sensory satisfaction within China's SAMR sodium-limit guidelines. |
| ASEAN Regulatory Harmonization Preparation | Unified compliance frameworks reduce multi-jurisdiction fragmentation for regional portfolio operators. |
Study Parameters
Coverage spans East Asia, Southeast Asia, and Oceania, with primary inputs from each region combining interviews with noodle manufacturing plant managers, QSR procurement directors, wheat milling operations heads, and retail category buyers alongside secondary validation. Secondary sources include China MIIT food-grade packaging standards documentation, Indonesia BPOM fortification mandate filings, Australian FSANZ gluten-labeling determinations, customs and trade flow data, and SEC filings from listed manufacturers. Bottom-up capacity and production estimates triangulate against top-down consumption surveys and channel audit data.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon, with analytical framework modeling product type, end-user segment, packaging format, and distribution channel dimensions alongside regional regulatory cluster variations. CAGRs derive from segment-level growth trajectory assessments incorporating input cost elasticity, channel shift velocities, and compliance cost absorption capacity. Forecast inputs include wheat futures price correlation models and restaurant chain expansion pipeline tracking.
Several conditions sit outside the modeled scope, including abrupt trade policy disruptions affecting Australian wheat export flows, force majeure events in palm-oil processing corridors, and unanticipated regulatory acceleration beyond current ASEAN harmonization timelines. Forecasts reflect assumptions about sodium-limit guideline enforcement intensity and fortification mandate compliance cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Pre-Packaged Food Market
Packaged Foods
Wet Pet Food Market
Packaged Foods
Instant Beverage Premix Market
Packaged Foods
Global Gluten-Free Breakfast Cereals Market
Packaged Foods
Injectable Cocoa Fillings Market
Packaged Foods
Dinner Ready-To-Eat (RTE) Food Market
Packaged Foods
Packaged Currants Market
Packaged Foods
Asia-Pacific Ready Meals Market
Packaged Foods
Instant Soup Market
Packaged Foods
Asia-Pacific Sweet Biscuits Market
Packaged Foods
North America Ready Meals Market
Packaged Foods
Chocolate Based Spreads Market
Packaged Foods
Eco Bowls Market
Packaged Foods
Europe Ready Meals Market
Packaged Foods
Cereal Flakes Market
Packaged Foods
Iran Breakfast Cereals Market