
 Global Biopharmaceutical Fermentation Systems Market | 2026-2036
Global Biopharmaceutical Fermentation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biopharmaceutical Fermentation Systems Market Intelligence
Supply-side capacity for large-scale stainless steel fermenters is shifting towards modular, single-use systems. Sartorius Stedim Biotech specializes in single-use bioreactors and consumables, capturing a significant portion of this transition. Thermo Fisher Scientific Inc. leverages its broad portfolio to offer integrated solutions from cell culture to purification. Merck KGaA differentiates through its advanced process monitoring and control technologies for fermentation.
Biopharmaceutical fermentation systems are highly controlled environments for cultivating microorganisms or mammalian cells to produce therapeutic proteins and other biologics. These systems, often operating at volumes up to 2,000 liters, precisely regulate parameters like pH, temperature, and dissolved oxygen to optimize cell growth and product yield. Single-use technology is displacing traditional clean-in-place systems due to flexibility and reduced cross-contamination risk. While monoclonal antibodies production remains the primary application, demand from contract development organizations is accelerating as biopharma companies outsource manufacturing.
Good Manufacturing Practices (GMP) enforced by regulators like the US FDA and the EMA set stringent standards for system design and process validation. ISO standards for single-use systems and bioprocessing equipment also influence material selection and manufacturing protocols across China and other markets. Navigating the evolving requirements for continuous manufacturing and process analytical technology (PAT) integration is a key strategic consideration for system developers.
Market Dynamics
The biopharmaceutical fermentation systems market is defined by the transition from traditional stainless steel infrastructure to flexible single-use technologies. This shift impacts capital expenditure strategies, facility design, and supply chain management for biologics manufacturers, especially for monoclonal antibody production.
Growth Catalysts
- Single-Use Technology:The adoption of disposable bioreactors and consumables reduces facility setup times, lowers cross-contamination risks, and provides operational flexibility for multi-product manufacturing campaigns, particularly for contract development organizations.
- Monoclonal Antibody Demand:Expanding therapeutic pipelines for oncology, autoimmune disorders, and infectious diseases are driving significant volume requirements for monoclonal antibodies, the primary product class manufactured using these fermentation systems.
- Regulatory Support for Modernization:The US FDA's guidance on Process Analytical Technology (PAT) and continuous manufacturing encourages investment in advanced, automated fermentation systems with integrated sensors and control loops to improve process understanding and product quality.
Market Restraints
- High Capital Investment:The initial procurement and installation costs for large-scale, GMP-compliant stainless steel fermentation systems remain a significant barrier for emerging biopharmaceutical companies and academic research institutions.
- Leachables and Extractables:Concerns over chemical compounds leaching from single-use plastic components into the process fluid necessitate extensive and costly validation studies to ensure product safety and purity, a key focus for regulators like the EMA.
- Consumable Supply Chain Risk:The reliance on a concentrated group of suppliers for proprietary single-use bags, tubing, and connectors creates vulnerability to supply disruptions, as seen in recent bioprocessing component shortages.
Strategic Opportunities
- Cell and Gene Therapy:Adapting fermentation system designs for the specific requirements of viral vector production and cell expansion presents a significant growth avenue beyond traditional protein-based biologics.
- Process Intensification:Developing systems that support high-density perfusion cultures allows manufacturers to achieve higher product titers in smaller bioreactor volumes, reducing facility footprint and operational costs.
- Biopharma Expansion in Asia:Growing government investment and policy support for domestic biologics manufacturing in countries like China and South Korea create new market entry points for fermentation system providers.
Industry Challenges
- Skilled Workforce Scarcity:A shortage of bioprocess engineers and data scientists with expertise in operating and optimizing advanced fermentation systems and analyzing the resulting complex datasets constrains efficient scale-up and manufacturing.
- System Interoperability:A lack of standardization for connectors and sensors between different vendors' single-use components complicates the integration of a truly open-architecture bioprocessing train, creating vendor lock-in.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biopharmaceutical Fermentation Systems Market |
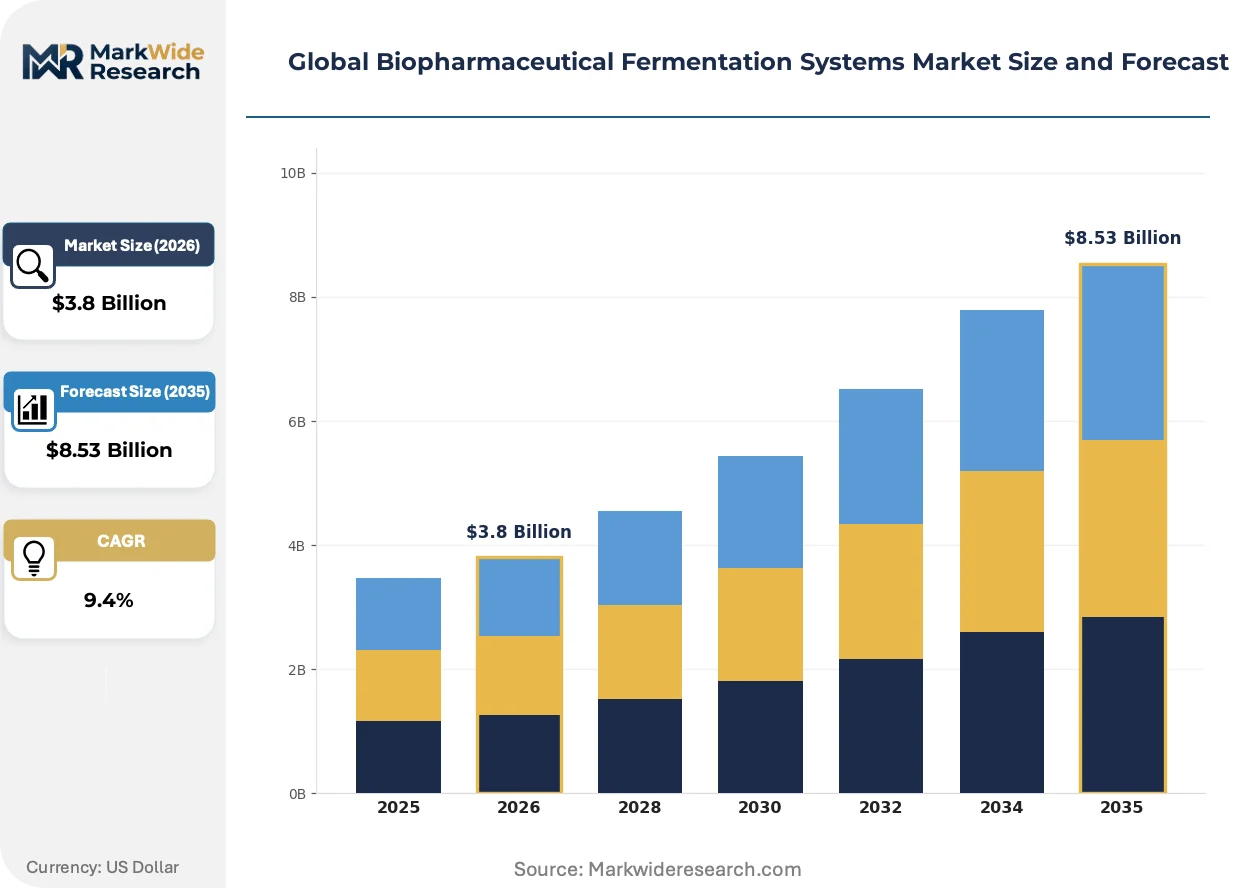
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stirred Tank Bioreactors, Airlift Bioreactors, Wave Bioreactors, Packed Bed Bioreactors, Hollow Fiber Bioreactors Technology: Single-Use Systems, Clean-in-Place, Continuous Fermentation, Fed-Batch Fermentation, Microcarrier Technology Application: Monoclonal Antibodies Production, Vaccine Manufacturing, Enzyme Synthesis, Gene Therapy Development, Hormone Production End User: Biotech Companies, Pharmaceutical Manufacturers, Contract Development Organizations, Academic Research Institutes, Biosimilar Producers |
| Companies Covered | Thermo Fisher Scientific Inc., Sartorius Stedim Biotech, Danaher Corporation, Merck KGaA, Eppendorf AG, Lonza Group AG, GE HealthCare Technologies, Inc., Agilent Technologies, Inc., Becton, Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biopharmaceutical Fermentation Systems Market Strategic Shifts & Innovations
The industrialization of bioprocessing is the central theme, with a clear movement toward integrated, data-rich manufacturing platforms. This evolution prioritizes process control, automation, and lifecycle management to support the production of increasingly complex biologic therapies.
Single-use bioreactors and their associated fluid management assemblies provide a sterile, closed environment for cell culture. Contract Development and Manufacturing Organizations (CDMOs) and clinical-stage biotech firms are the fastest adopters due to the need for rapid campaign changeovers. This technology is modularizing the biomanufacturing workflow, enabling plug-and-play facility configurations and simplifying technology transfer between global sites.
International Council for Harmonisation (ICH) Q12 guidelines on pharmaceutical product lifecycle management are influencing system design. This framework provides a structured approach for managing post-approval chemistry, manufacturing, and controls (CMC) changes, promoting continual improvement without extensive regulatory resubmission. Fermentation system developers are most impacted, as they must now build equipment with data logging and validation packages that support this lifecycle approach.
A notable behavioral change is the move from purchasing discrete equipment to sourcing fully integrated, end-to-end bioprocessing solutions. This model disrupts the traditional procurement cycle of sourcing fermenters, chromatography skids, and filters from separate specialist vendors. The pattern is most pronounced in established biopharma clusters in the United States and Ireland, where companies seek to simplify vendor management and accelerate facility commissioning.
Global Biopharmaceutical Fermentation Systems Market Segmentation
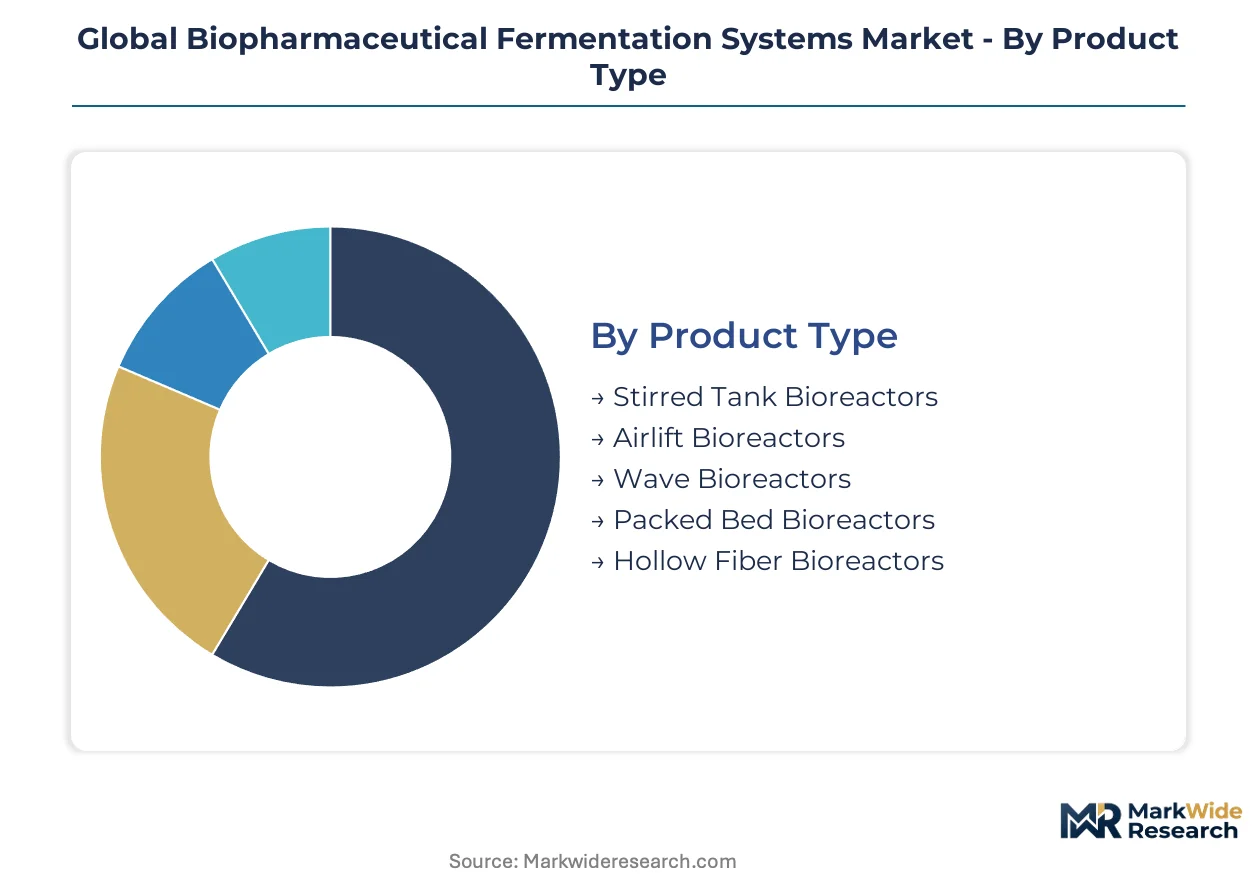
The biopharmaceutical fermentation systems market is diverse, reflecting varied biological production needs and operational scales. Segmentation provides a granular view of distinct product designs, technological approaches, therapeutic applications, and end-user requirements. This detailed breakdown highlights specific growth pockets and evolving investment patterns across the global landscape.
Product Type:
The capital intensity of biopharmaceutical fermentation systems varies significantly by product type, influencing initial investment and operational flexibility for manufacturers.
- Stirred Tank Bioreactors:These systems feature mechanical agitation for homogeneous mixing and efficient mass transfer, crucial for large-scale cell culture. Demand concentrates in established biopharma manufacturing hubs like the United States and Ireland, driven by high-volume monoclonal antibody production.
- Wave Bioreactors:Utilizing a rocking motion for gentle mixing in disposable bags, these systems offer flexibility and reduced cleaning validation. Clinical-stage biotech firms and Contract Development Organizations globally adopt wave bioreactors for rapid campaign changeovers and multi-product facilities.
- Airlift Bioreactors:Airlift bioreactors use gas sparging for mixing and oxygen transfer, suitable for shear-sensitive cells in vaccine manufacturing.
- Packed Bed Bioreactors:Packed bed systems immobilize cells on a solid matrix, enabling high cell densities for continuous bioprocessing applications.
- Hollow Fiber Bioreactors:Hollow fiber bioreactors provide a high surface area for cell growth, often used for small-scale, high-value protein production.
Stirred tank bioreactors absorb the bulk of installed capacity; wave bioreactors are expanding most quickly.
Technology:
Different fermentation technologies cater to specific application requirements, impacting process efficiency, product quality, and regulatory compliance across the biopharmaceutical pipeline.
- Single-Use Systems:These disposable systems, including bioreactors and associated components, eliminate cleaning and sterilization steps, reducing turnaround times. Biotech companies and CDMOs in Europe and North America increasingly adopt single-use technology for multi-product facilities and clinical trial material production.
- Continuous Fermentation:Continuous fermentation maintains cells in a steady state, enabling higher volumetric productivity and smaller facility footprints. Pharmaceutical manufacturers pursue continuous bioprocessing for cost reduction and enhanced product consistency, particularly in established biologics markets.
- Clean-in-Place:Clean-in-place (CIP) technology integrates automated cleaning and sterilization cycles into fixed stainless steel bioreactors, a standard for traditional large-scale manufacturing.
- Fed-Batch Fermentation:Fed-batch fermentation involves nutrient additions during the culture period, optimizing cell growth and product yield for various biologics.
- Microcarrier Technology:Microcarrier technology uses small beads for cell attachment, expanding surface area for adherent cell culture in vaccine and viral vector production.
Single-use systems demonstrate a high concentration of specialized suppliers; continuous fermentation is gaining share fastest due to efficiency gains.
Application:
The choice of fermentation system application is often dictated by the specific needs and production scales of different customer types within the biopharmaceutical industry.
- Monoclonal Antibodies Production:This application constitutes the largest segment, requiring precise control over cell growth and product quality for therapeutic proteins. Pharmaceutical manufacturers globally invest heavily in systems optimized for monoclonal antibody titers, especially in the US and Switzerland.
- Gene Therapy Development:Gene therapy applications demand specialized systems for viral vector production, often at smaller scales but with stringent purity requirements. Biotech companies and academic research institutes drive demand for flexible, contained systems in gene therapy clusters across the United States.
- Vaccine Manufacturing:Vaccine manufacturing utilizes fermentation systems for antigen production, requiring high sterility and scalability for global health initiatives.
- Enzyme Synthesis:Enzyme synthesis employs fermentation for industrial enzyme production, serving various sectors beyond biopharma, including diagnostics and food processing.
- Hormone Production:Hormone production, including insulin and growth hormones, relies on controlled fermentation processes for recombinant protein expression.
Monoclonal antibodies production represents a mature application with established protocols; gene therapy development is rapidly maturing with evolving system requirements.
End User:
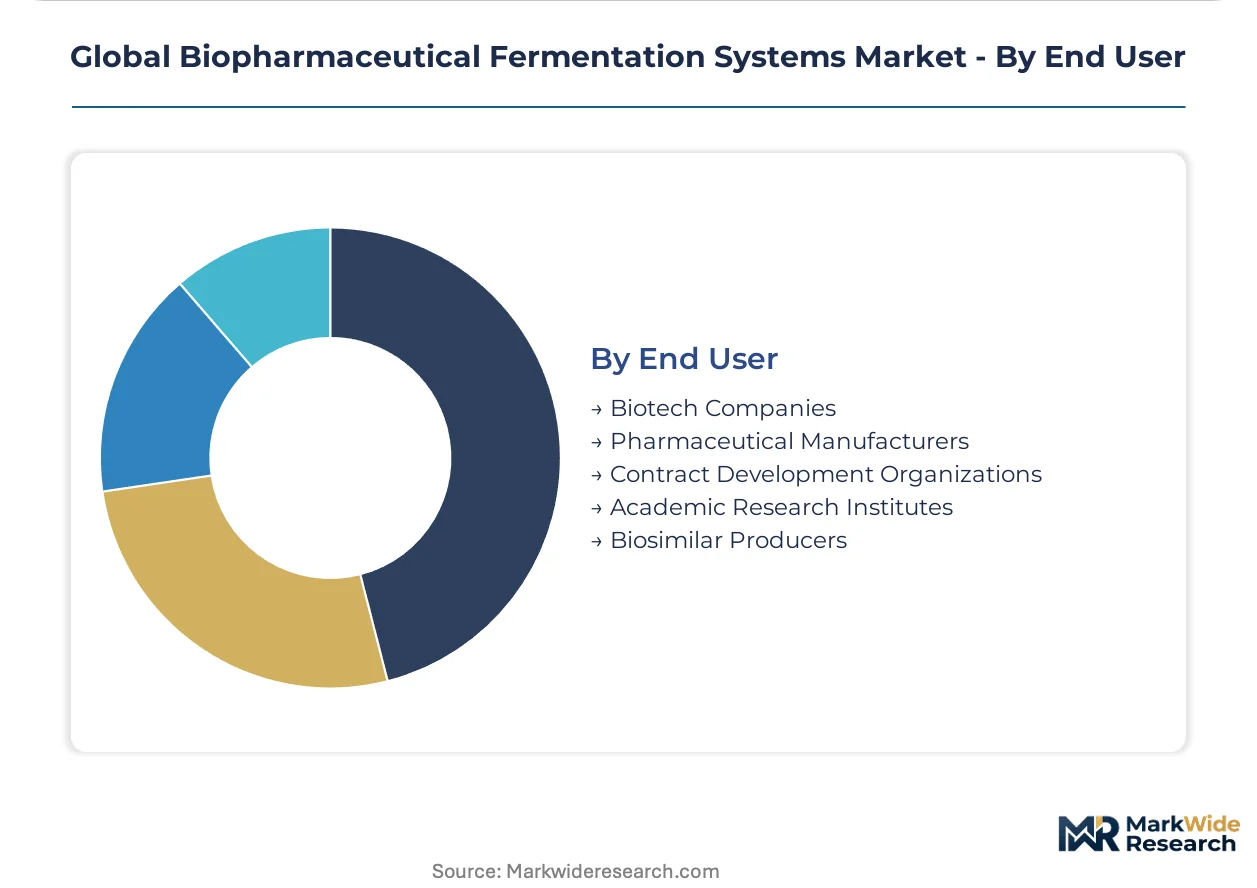
The end-user segment significantly influences market dynamics, with varying margin pressures and procurement strategies shaping demand for fermentation system features and services.
- Pharmaceutical Manufacturers:These large enterprises demand robust, GMP-compliant systems for high-volume commercial production of biologics, prioritizing reliability and scale. Their procurement often involves long-term contracts and integrated solutions, particularly in established markets like Germany and Japan.
- Contract Development Organizations:CDOs require flexible, multi-product capable systems to support diverse client projects, emphasizing rapid changeover and cost-efficiency. They are key adopters of single-use technologies to manage multiple campaigns and accelerate time to market for biopharma clients globally.
- Biotech Companies:Emerging biotech companies seek cost-effective and scalable fermentation solutions for early-stage drug development and clinical trials.
- Academic Research Institutes:Academic research institutes use fermentation systems for fundamental biological studies and early-stage proof-of-concept work, often prioritizing versatility and ease of use.
- Biosimilar Producers:Biosimilar producers require cost-efficient and high-performance fermentation systems to compete with originator biologics, focusing on process optimization.
Pharmaceutical manufacturers navigate high operational complexity for commercial scale; academic research institutes prioritize versatility for diverse experimental needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharmaceutical manufacturing hubs anchor demand for fermentation systems across several key geographies. These regions benefit from established research ecosystems, robust regulatory frameworks, and significant capital investment in biologics production. The global market's expansion is closely tied to the growth of these localized biopharma clusters.
United States
The United States drives substantial demand for biopharmaceutical fermentation systems, particularly for monoclonal antibody production and gene therapy development. The US FDA's guidance on continuous manufacturing encourages investment in advanced systems with integrated process analytical technologies. Biopharma clusters in Greater Boston and California's Bay Area consistently lead in adopting novel fermentation solutions.
Germany
Germany represents a strong market for biopharmaceutical fermentation systems, driven by its robust pharmaceutical manufacturing sector and a focus on high-quality biologics. The EMA's stringent Good Manufacturing Practices (GMP) influence system design and validation requirements for European production. Bavaria and North Rhine-Westphalia house significant bioprocessing facilities, concentrating demand for advanced bioreactors.
Ireland
Ireland has become a critical hub for biopharmaceutical manufacturing, attracting major investments from global pharmaceutical manufacturers. Favorable tax policies and a skilled workforce support the expansion of large-scale biologics production facilities. Dublin and Cork are prominent biopharma clusters, continuously upgrading fermentation capacity for export-oriented manufacturing.
China
China demonstrates rapid growth in biopharmaceutical fermentation systems, fueled by government support for domestic biologics innovation and manufacturing. The NMPA's efforts to streamline drug approvals stimulate local production of biosimilars and novel therapies. Shanghai and Suzhou are emerging as key biopharma centers, investing in both traditional and single-use fermentation technologies.
South Korea
South Korea is a significant market for biopharmaceutical fermentation systems, with strong capabilities in biosimilar and vaccine manufacturing. The MFDS's regulatory framework supports the development and production of advanced biologics for both domestic and international markets. Incheon and Songdo host major biomanufacturing facilities, driving demand for high-throughput fermentation solutions.
Global Biopharmaceutical Fermentation Systems Market Key Industry Players
Global majors compete with regional champions across the biopharmaceutical fermentation systems market, creating a tiered structure. The market sees a mix of large, diversified technology providers and specialized vendors focusing on niche segments. Strategic archetypes include integrated solution providers, single-use technology specialists, and advanced process control innovators. Dominant competitive moves involve portfolio diversification and geographic expansion to tap into emerging biopharma hubs.
Diversified global players like Thermo Fisher Scientific Inc. exemplify comprehensive offerings spanning instrumentation and consumables, catering to a broad client base. Sartorius Stedim Biotech represents a specialist in single-use bioprocessing solutions, anchoring its position with disposable bioreactors and associated fluid management systems. Merck KGaA occupies a position as a technology-driven innovator, differentiating through its advanced process monitoring and control technologies for fermentation applications.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Sartorius Stedim Biotech |
| Danaher Corporation |
| Merck KGaA |
| Eppendorf AG |
| Lonza Group AG |
| GE HealthCare Technologies, Inc. |
| Agilent Technologies, Inc. |
| Becton, Dickinson and Company |
| Others |
Cost & Logistics Intelligence
Single-use plastic component costs influence downstream system pricing, particularly for contract development organizations that prioritize operational flexibility. This dynamic shapes procurement strategies for biopharmaceutical manufacturers seeking cost-effective solutions.
Pricing Analysis
Warranty and service bundles significantly influence the perceived value and total cost of ownership for biopharmaceutical fermentation systems. The dominant pricing structure is contract-based long-term offtake, especially for large pharmaceutical manufacturers. Price differentiation stems from customization levels for specific bioprocesses and the certification level of single-use components. Pricing pressure intensifies for standard, high-volume systems due to increased competition from Asian suppliers. Emerging biotech companies demonstrate the highest price sensitivity, while established pharmaceutical manufacturers prioritize reliability over initial cost.
Supply Chain Analysis
Logistics and freight costs for sterile, single-use components impact the global supply chain for biopharmaceutical fermentation systems. Supply concentration for critical components like specialized bags and tubing is in China, the United States, and Europe. Raw material dependencies include medical-grade plastics and advanced sensor technologies. Single-source vulnerability for proprietary single-use bags represents a significant structural risk. Distribution runs through a network of specialized distributors and direct sales channels, particularly for integrated solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
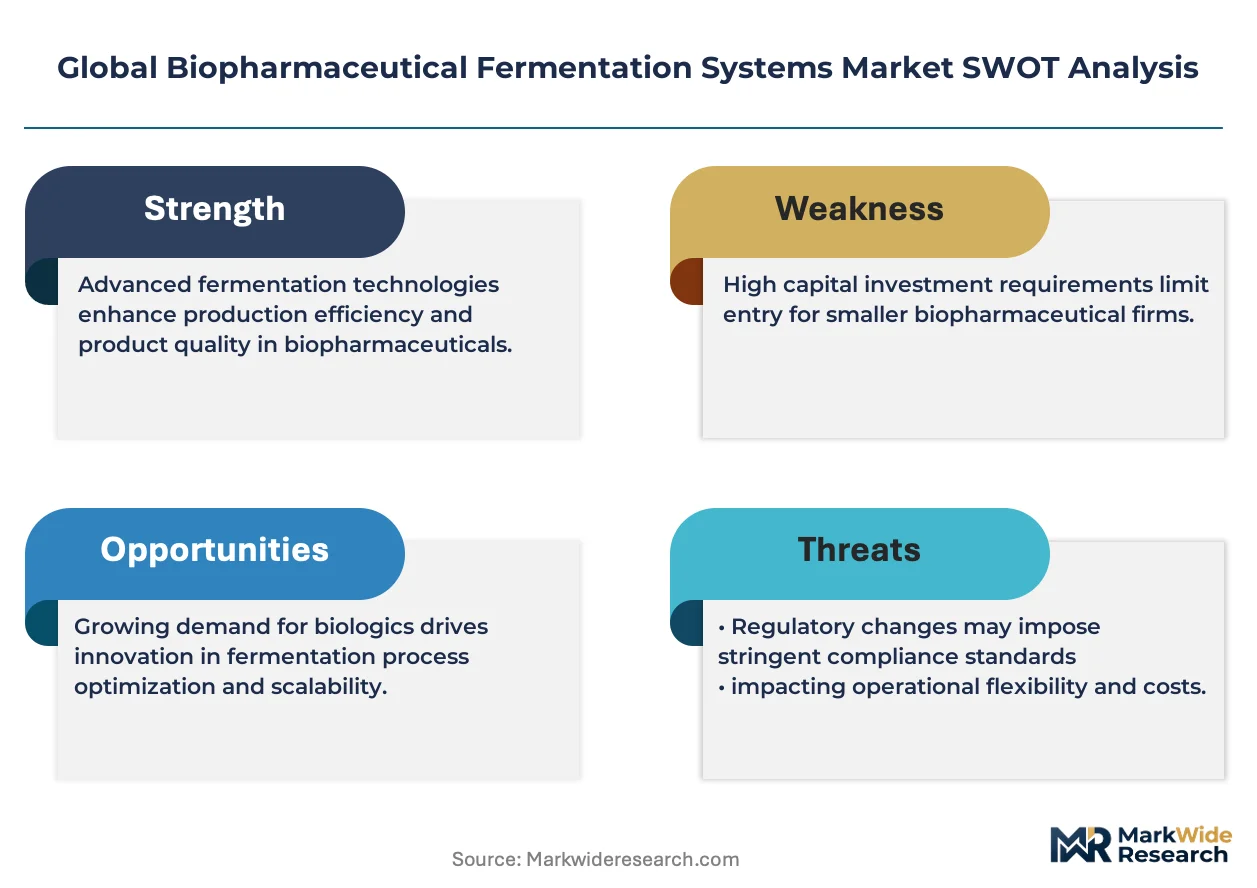
The increasing demand for monoclonal antibodies and gene therapies creates a capacity bottleneck in advanced bioprocessing equipment, sustaining pricing power for system providers.
For Market Incumbents: Deepen R&D investment in continuous manufacturing and process analytical technology to outpace emerging competitors. Consolidate market share through strategic acquisitions of specialized component manufacturers, mitigating single-source supply risks. Focus on integrated solutions, offering end-to-end bioprocessing platforms to counter component-level price erosion from new entrants. Expand manufacturing footprints in key biopharma clusters like Ireland and Singapore.
For New Entrants and Emerging Players: Underserved clinical-stage biotech firms represent a prime target for flexible, modular fermentation systems. Focus on niche applications like viral vector production for gene therapies, which require specialized, smaller-scale solutions. A go-to-market angle emphasizing rapid deployment and reduced validation burden for single-use technologies can capture market share. Target geographies with nascent biopharma manufacturing, such as Southeast Asia, with localized support.
For Investors and Strategic Acquirers: Increased regulatory clarity for continuous manufacturing is the leading indicator that will unlock substantial investment in advanced bioprocessing. The market offers long-term viability over a 5-10 year window due to the expanding biologics pipeline. Acquisition targets should include specialized single-use component providers or software firms offering advanced process control and data analytics for fermentation. Monitor intellectual property filings for novel bioreactor designs.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Bioprocess Automation | Enhances operational efficiency and data integrity across diverse biopharmaceutical manufacturing workflows. |
| Expand Single-Use Consumable Production | Addresses supply chain vulnerabilities and supports the growing demand for flexible manufacturing platforms. |
| Develop AI-Driven Process Optimization Tools | Improves product yield and consistency by leveraging complex fermentation data for real-time adjustments. |
| Form Strategic Partnerships with CDMOs | Secures preferred supplier status and expands market reach within the outsourced biomanufacturing sector. |
| Acquire Gene Therapy Bioreactor Specialists | Positions the company to capitalize on the rapidly evolving and high-growth viral vector production market. |
Research Approach
Document review covered SEC filings, FDA guidance documents, EMA submissions, and biopharmaceutical industry association reports, complemented by interviews with bioprocess engineers and procurement managers. This primary and secondary research provided a comprehensive view of market dynamics. We engaged R&D directors and regulatory affairs specialists to understand technological and compliance trends. Bottom-up data aggregation and top-down market sizing validated the findings.
The model produced volume and value forecasts across the analysis window, integrating various market segmentation dimensions. These dimensions included product type, technology, application, end user, and regional manufacturing capacity. Compound annual growth rates were derived from historical data analysis and projected market trends. Forecast inputs included biologics pipeline growth and contract development and manufacturing organization expansion plans.
Revisions become necessary when significant supply chain disruptions or major shifts in regulatory guidance materialize. Forecasts reflect assumptions regarding technological advancements and market adoption rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Akabane Vaccines Market
Biopharmaceuticals
Global Topical Antibiotics Market
Biopharmaceuticals
Biopharmaceutical Fermentation Market
Biopharmaceuticals
Oncology Drugs Market
Biopharmaceuticals
Asia-Pacific Plant-Based Biologics Market
Biopharmaceuticals
Tyrosine Kinase Inhibitors Market
Biopharmaceuticals
Rhu Albumin Market
Biopharmaceuticals
Rapid Acting Insulin Market
Biopharmaceuticals
Global Staphylococcal Infection Drugs Market
Biopharmaceuticals
Erythropoietin Drugs Market
Biopharmaceuticals
Triptorelin Market
Biopharmaceuticals
Antibody Drug Conjugates Market
Biopharmaceuticals
Liposomal Doxorubicin Market
Biopharmaceuticals
Tamiflu (Oseltamivir Phosphate) Market
Biopharmaceuticals
NF-KB Inhibitors Market
Biopharmaceuticals
Global Protein Expression Market