
 Global Bovine Blood Plasma Derivatives Market | 2026-2036
Global Bovine Blood Plasma Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bovine Blood Plasma Derivatives Market Foresight
Market Context with Strategic Players
The EU Green Deal is repositioning animal-derived raw material sourcing standards across European pharmaceutical supply chains. Proliant Health & Biologicals leverages vertically integrated abattoir partnerships to sustain consistent immunoglobulin yields for diagnostic applications. Thermo Fisher Scientific anchors its plasma derivatives portfolio through controlled temperature logistics networks spanning North America and Western Europe. Merck KGaA differentiates via pharmaceutical-grade fractionation capabilities that meet evolving EMA purity benchmarks for cell culture media.
Technical Definition and Structural Segments
Bovine blood plasma derivatives comprise fractionated proteins, immunoglobulins, albumin, and fibrinogen extracted from cattle serum through cold ethanol precipitation or chromatographic separation, serving as essential growth media supplements, vaccine stabilizers, and diagnostic assay components. Spray-dried plasma dominates volume throughput due to cost-efficient thermal processing and extended shelf stability, while freeze-dried plasma commands premium positioning in biopharmaceutical applications where endotoxin thresholds are most stringent. Diagnostic reagents represent the fastest-expanding application channel as multiplex immunoassay platforms multiply, though animal nutrition still occupies the largest absolute volume share through feed-grade plasma protein incorporation.
Regulatory Frame and Forward-Looking Close
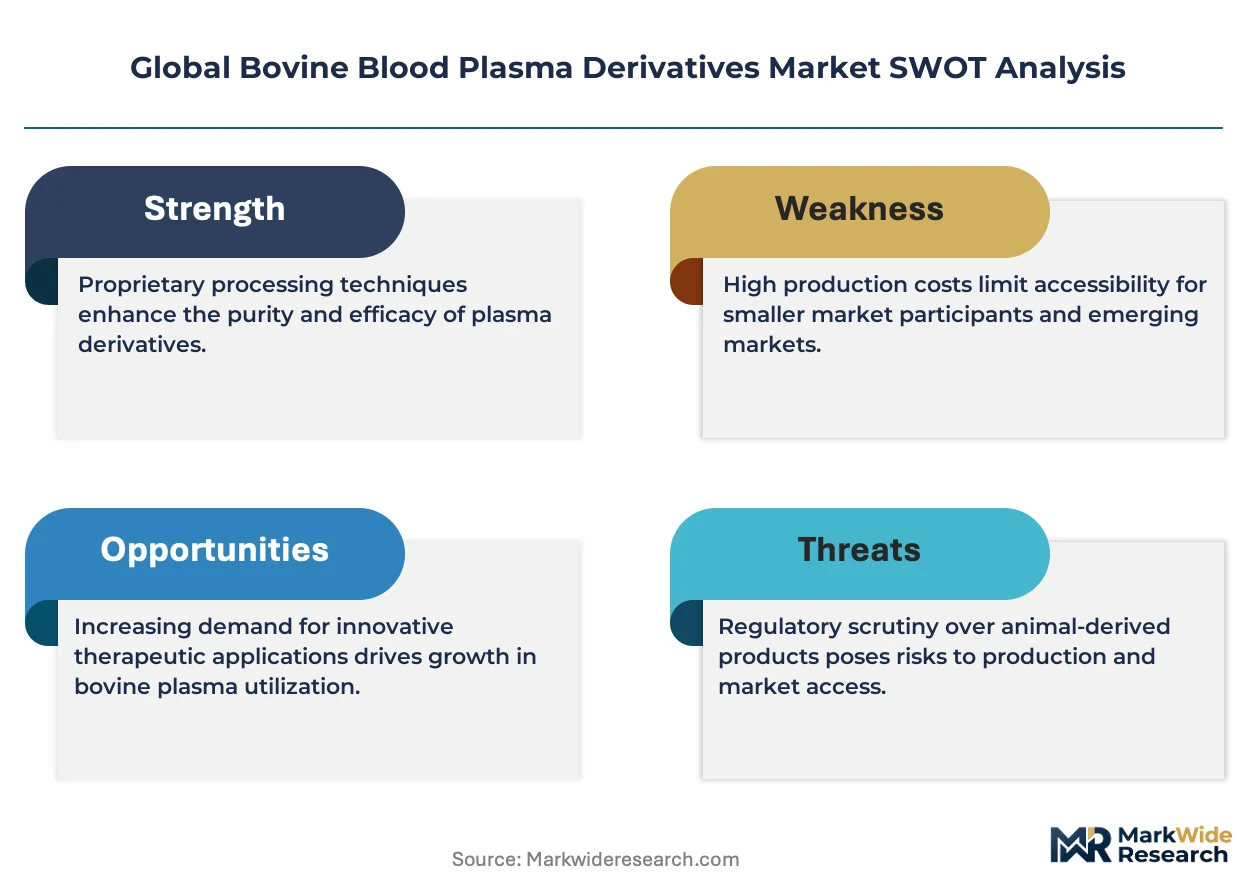
FDA guidance on animal-derived materials in medical products, EMA viral safety standards, and USDA biologics oversight collectively elevate documentation burdens for plasma traceability from slaughterhouse to final formulation. ISO 22442 biocompatibility testing for medical devices utilizing animal tissues further constrains supplier qualification timelines in transatlantic trade. Stakeholders must monitor how dual carbon goals in Brazil and Argentina reshape rendering industry economics and, by extension, raw plasma availability for derivative manufacturers.
Market Dynamics
Fractionation technology maturation is compressing batch-to-batch variability while regulatory traceability mandates from FDA and EMA simultaneously extend qualification timelines for new plasma sourcing contracts.
Growth Catalysts
- Cell culture media expansion:Biologics manufacturers are absorbing larger immunoglobulin volumes as serum-free formulations reach technical limits in complex protein production.
- REACH traceability mandates:EU Green Deal sourcing standards are formalizing documentation requirements that favor established plasma processors with vertically controlled supply chains.
- Multiplex diagnostic platforms:Clinical laboratories are scaling automated immunoassay throughput, multiplying consumption of bovine-derived blocking reagents and assay stabilizers.
Market Restraints
- Rendering economics volatility:Brazilian and Argentine carbon reduction policies are reshaping abattoir byproduct economics, compressing raw plasma availability for derivative manufacturers.
- Endotoxin specification tightening:EMA viral safety standards and ISO 22442 biocompatibility thresholds are extending supplier qualification timelines by twelve to eighteen months.
- Serum-free media substitution:Recombinant protein and plant-derived hydrolysate alternatives are capturing share in vaccine production and stem cell applications.
Strategic Opportunities
- Indian biopharmaceutical manufacturing:CDSCO regulatory harmonization and PLI scheme incentives are attracting contract manufacturing investment that will multiply local plasma derivative demand.
- Spray-dried feed-grade plasma:Precision livestock farming adoption in Denmark and the Netherlands is creating specification-grade demand for pathogen-tested nutritional additives.
- Chromatographic fractionation convergence:Continuous processing and membrane separation integration is enabling real-time quality monitoring that reduces batch rejection rates.
Industry Challenges
- Fractionation biochemistry expertise scarcity:Cold ethanol precipitation and chromatographic separation require specialized protein chemistry training that outpaces university pipeline output.
- Captive supply chain integration complexity:Abattoir-to-laboratory cold chain documentation systems must interface with legacy ERP platforms at diagnostic reagent manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bovine Blood Plasma Derivatives Market |
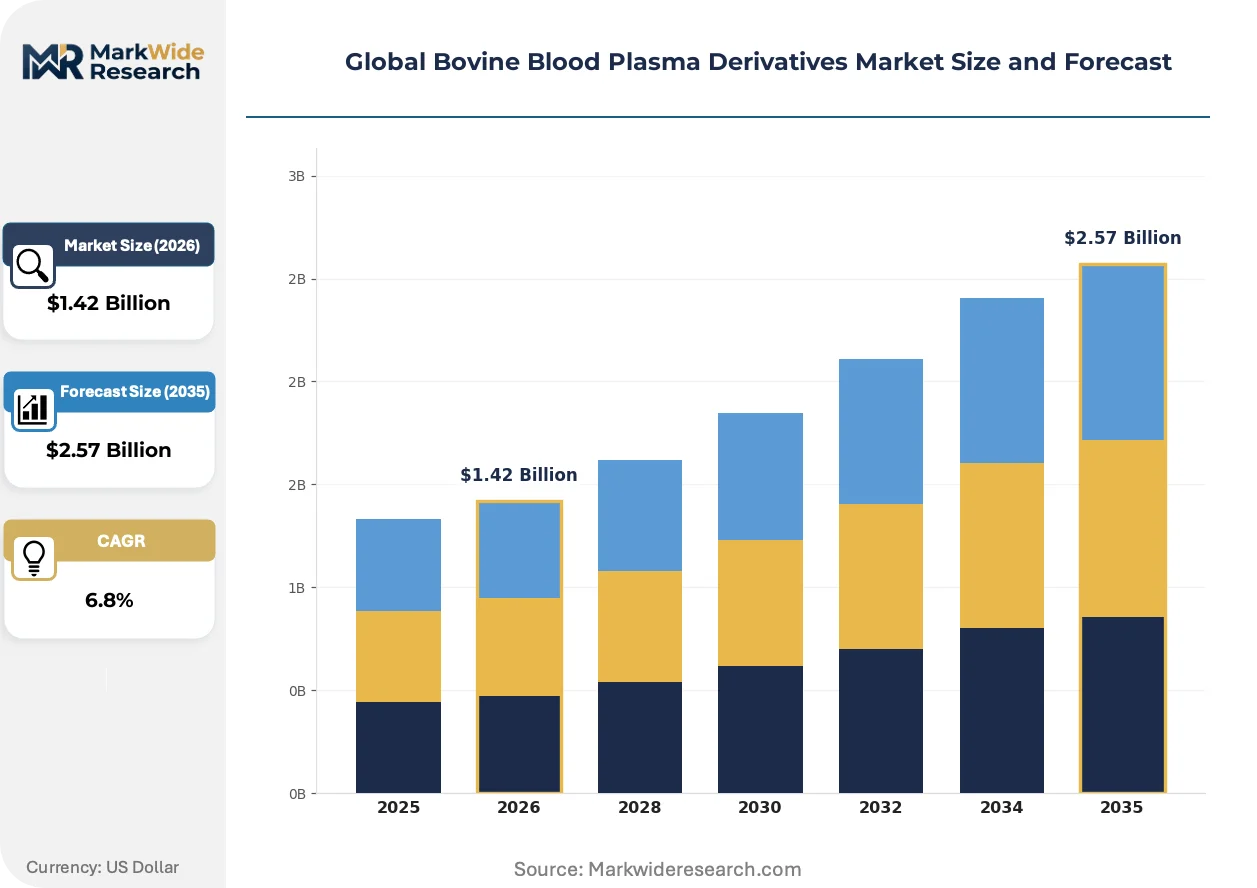
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spray-Dried Plasma, Freeze-Dried Plasma, Liquid Plasma, Granulated Plasma, Plasma Powder Application: Animal Nutrition, Pharmaceutical Formulations, Diagnostic Reagents, Cosmetic Industry, Biopharmaceuticals End User: Feed Manufacturers, Pharma Companies, Diagnostic Labs, Cosmetic Producers, Biotech Firms Packaging Type: Bulk Bags, Sealed Drums, Vacuum Packs, Pouches, Plastic Containers |
| Companies Covered | Bovogen Biologicals, Proliant Health & Biologicals, Thermo Fisher Scientific, SeraCare, Kraeber & Co GmbH, Merck KGaA, Rocky Mountain Biologicals, TCS Biosciences, LAMPIRE Biological Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bovine Blood Plasma Derivatives Market Shifts & Advancements
Plasma derivative processing is bifurcating between commodity spray-dried volumes and precision freeze-dried grades, with automation and regulatory technology investments determining competitive position.
Continuous chromatographic separation systems are replacing batch cold ethanol precipitation in premium-grade manufacturing. Biopharmaceutical contract manufacturers in Germany and Switzerland are adopting these platforms to compress cycle times. This convergence is unifying quality control and production workflows into single automated lines that reduce human handling and endotoxin introduction points.
EMA viral safety guidance updates are mandating nucleic acid testing at multiple fractionation stages. Plasma processors are reconfiguring quality laboratories to accommodate PCR and next-generation sequencing capacity. Diagnostic reagent manufacturers sourcing EU-certified materials are absorbing extended release timelines as suppliers validate new detection protocols.
Consolidated procurement through sole-source plasma supply agreements is displacing spot-market purchasing among large diagnostic reagent producers. Multinational assay manufacturers in the United States are negotiating multi-year contracts with captive abattoir partnerships. This concentration is visible most acutely in North American multiplex platform supply chains where batch consistency directly determines assay reproducibility.
Global Bovine Blood Plasma Derivatives Market Segmentation
Bovine blood plasma derivatives fragment across four functional dimensions that determine procurement workflows, certification burdens, and margin structures. Product form dictates thermal processing investment and shelf stability, while application channels separate feed-grade commodity volumes from pharmaceutical-grade premium tiers.
Product Type:
Spray-dried plasma carries minimal regulatory documentation for feed applications, whereas freeze-dried and liquid grades trigger FDA and EMA viral safety protocols for pharmaceutical use.
- Spray-Dried Plasma:Thermal dehydration at controlled temperatures preserves immunoglobulin activity for extended storage. Feed manufacturers in the United States absorb the largest volumes as pathogen-tested nutritional additives for weaning diets. Cost-efficient processing and twelve-month shelf stability sustain its commodity positioning.
- Freeze-Dried Plasma:Lyophilization removes moisture under vacuum to achieve endotoxin thresholds below 5 EU/mL for cell culture media. Biopharmaceutical contract manufacturers in Germany and Switzerland specify this grade for serum-free formulation supplements. Premium positioning reflects batch-level PCR documentation and cold chain integrity requirements.
- Liquid Plasma:Refrigerated distribution limits geographic reach to abattoir-proximate processors with same-day fractionation capacity.
- Granulated Plasma:Agglomerated particles improve flow characteristics for automated feed milling systems in Denmark and the Netherlands.
- Plasma Powder:Fine particle sizing targets cosmetic protein hydrolysate applications with solubility specifications.
Spray-dried plasma sits at the top of the volume ranking, with freeze-dried plasma climbing the fastest.
Application:
Cost tiers separate commodity feed incorporation from precision diagnostic and pharmaceutical applications where batch certification drives procurement budgets.
- Animal Nutrition:Feed-grade plasma protein incorporation dominates absolute tonnage through early-weaning piglet diets and aquaculture starter feeds. Precision livestock farming adoption in the Netherlands and Denmark is creating specification-grade demand for Salmonella-negative certificates and immunoglobulin concentration guarantees.
- Diagnostic Reagents:Multiplex immunoassay platforms multiply consumption of bovine-derived blocking reagents and assay stabilizers. Clinical laboratories in the United States scale automated throughput, absorbing larger immunoglobulin fractions for ELISA and chemiluminescence systems. This segment is expanding most quickly.
- Pharmaceutical Formulations:Vaccine stabilizers and cell culture media supplements require EMA viral safety documentation and ISO 22442 biocompatibility testing.
- Biopharmaceuticals:Recombinant protein production and stem cell culture applications specify low-endotoxin grades with nucleic acid testing at multiple fractionation stages.
- Cosmetic Industry:Protein hydrolysates for skin conditioning represent niche volume with emerging regulatory scrutiny under REACH cosmetic ingredient standards.
Animal nutrition commands the largest absolute volume, while diagnostic reagents gain share fastest.
End User:
Customer type determines contract structure, with feed manufacturers purchasing on spot markets and pharma companies locking multi-year captive supply agreements.
- Feed Manufacturers:Consolidated procurement through rendering industry partnerships supplies weaning diet formulators in Iowa and North Carolina. Spot-market purchasing dominates with quarterly price negotiations tied to abattoir slaughter volumes.
- Pharma Companies:Merck KGaA and Thermo Fisher Scientific anchor demand through controlled temperature logistics networks spanning North America and Western Europe. Multi-year sole-source contracts with vertically integrated abattoir partnerships displace spot purchasing. This customer category is expanding most quickly.
- Diagnostic Labs:Multinational assay manufacturers negotiate batch consistency guarantees for multiplex platform reproducibility.
- Biotech Firms:Cell culture media developers in Germany and Switzerland specify pharmaceutical-grade fractionation with real-time quality monitoring.
- Cosmetic Producers:Formulators source protein hydrolysates with solubility and molecular weight specifications for topical applications.
Feed manufacturers sit at the top of the volume ranking, with pharma companies climbing the fastest.
Packaging Type:
Volume scale and contamination risk separate bulk agricultural distribution from sealed pharmaceutical containment systems.
- Bulk Bags:One-ton flexible intermediate bulk containers serve feed mill direct delivery with moisture-barrier liners. Rendering facilities in Brazil and Argentina ship containerized volumes to European compound feed processors. Lowest unit cost per kilogram sustains commodity positioning.
- Sealed Drums:Pharmaceutical-grade stainless steel containers with nitrogen backflushing preserve immunoglobulin stability for biopharmaceutical manufacturers. German and Swiss cell culture media producers specify drum-level batch documentation and tamper-evident sealing. This format is expanding most quickly.
- Vacuum Packs:Barrier film pouches with oxygen scavengers target diagnostic reagent manufacturers requiring extended shelf stability.
- Pouches:Small-format flexible packaging serves cosmetic protein hydrolysate sampling and pilot-scale biopharmaceutical development.
- Plastic Containers:HDPE drums with gamma-irradiation certificates support veterinary vaccine production in emerging manufacturing clusters.
Bulk bags sit at the top of the volume ranking, with sealed drums climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized protein chemists and cold-chain logistics specialists concentrate in Germany, Switzerland, and the United States, anchoring high-grade fractionation capacity. Rendering infrastructure and feed-grade processing clusters dominate Brazil, Argentina, and the American Midwest. Regulatory divergence between FDA viral safety protocols and EMA traceability mandates is fragmenting procurement strategies across these talent and production poles.
United States
Diagnostic reagent manufacturers in Massachusetts and North Carolina sustain captive abattoir partnerships for multiplex immunoassay platforms. FDA guidance on animal-derived materials in medical products mandates lot-level documentation from slaughterhouse to final formulation. Iowa and Nebraska rendering facilities supply pathogen-tested spray-dried plasma to weaning diet formulators under USDA biologics oversight.
Germany
Biopharmaceutical contract manufacturers in Bavaria and Baden-Württemberg specify low-endotoxin freeze-dried grades for serum-free cell culture media. EMA viral safety standards require nucleic acid testing at multiple fractionation stages, extending release timelines. The Rhine-Main cluster anchors continuous chromatographic separation adoption for real-time quality monitoring in premium-grade production.
Brazil
Carbon reduction policies under the national climate commitment are reshaping abattoir byproduct economics in São Paulo and Paraná states. ANVISA traceability requirements for imported biological raw materials intersect with EU Green Deal sourcing standards affecting export-oriented processors. Southern Brazilian rendering facilities face compressed raw plasma availability as dual carbon goals alter livestock waste valorization incentives.
Switzerland
Swissmedic pharmaceutical-grade certification anchors demand for precision fractionation serving German and French biotech customers. Basel-area cell culture media developers specify batch-level PCR documentation with endotoxin thresholds below 5 EU/mL. The country's controlled temperature logistics networks preserve immunoglobulin stability for transalpine distribution to diagnostic manufacturers.
India
CDSCO regulatory harmonization and PLI scheme incentives are attracting contract manufacturing investment in Maharashtra and Telangana. Biopharmaceutical developers in Hyderabad and Pune are scaling serum-free formulation production, multiplying local plasma derivative demand for process development. National pharmaceutical regulators are aligning viral safety documentation with EMA benchmarks to accelerate export qualification timelines.
Global Bovine Blood Plasma Derivatives Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the bovine blood plasma derivatives sector, with integrated abattoir-to-laboratory operators facing specialized fractionation houses. The market structure consolidates around three to five dominant processors with vertically controlled supply chains, while regional rendering specialists capture feed-grade commodity volumes. Strategic archetypes include captive supply chain integrators, pharmaceutical-grade fractionation specialists, and diversified life science conglomerates. Competitive moves center on multi-year sole-source procurement contracts and continuous chromatography technology licensing.
Within the captive supply chain integrator tier, Proliant Health & Biologicals and Rocky Mountain Biologicals exemplify North American operators with abattoir-proximate processing infrastructure. Among diversified life science conglomerates, Thermo Fisher Scientific and Merck KGaA occupy positions spanning controlled temperature logistics networks and pharmaceutical-grade fractionation capabilities. SeraCare represents the diagnostic-focused archetype, sitting within the assay component supply tier without vertical integration into upstream rendering operations.
| Leading Market Players |
|---|
| Bovogen Biologicals |
| Proliant Health & Biologicals |
| Thermo Fisher Scientific |
| SeraCare |
| Kraeber & Co GmbH |
| Merck KGaA |
| Rocky Mountain Biologicals |
| TCS Biosciences |
| LAMPIRE Biological Laboratories |
| Others |
Supply & Pricing Matrix
EU Green Deal sourcing standards gate both qualified supply and premium-tier pricing access, compressing spot-market availability for pharmaceutical-grade fractions while elevating contract-based procurement premiums for processors with vertically controlled abattoir partnerships. Buyers without captive supply agreements face extended qualification timelines and price volatility as carbon reduction policies reshape rendering economics in major cattle-producing regions.
Pricing Analysis
Service bundling separates pharmaceutical-grade processors from commodity feed-grade suppliers, with the former commanding premiums for viral safety documentation and cold chain integrity. Pricing stratifies across freeze-dried pharmaceutical tiers, spray-dried feed grades, and liquid plasma for regional distribution, with EMA viral safety certification and ISO 22442 biocompatibility testing as the primary price differentiation drivers. Cost compression in feed-grade spray-dried plasma is intensifying because Brazilian carbon policies are altering abattoir byproduct economics. Feed manufacturers exhibit the highest price sensitivity due to quarterly spot-market negotiations tied to slaughter volumes, while biopharmaceutical contract manufacturers accept premium pricing for batch consistency guarantees.
Supply Chain Analysis
Direct-to-biopharma channels handle pharmaceutical-grade demand through controlled temperature logistics networks spanning Germany, Switzerland, and the United States. Raw plasma availability draws from abattoir rendering operations in Brazil, Argentina, and the American Midwest, with fractionation chemistry expertise concentrated in German and Swiss processing clusters. Supply chain risk centers on single-source vulnerability as consolidated procurement through sole-source agreements displaces spot-market purchasing among large diagnostic reagent producers. Distribution runs through rendering facility partnerships for feed-grade volumes and pharmaceutical-grade drum shipments for cell culture media applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EMA viral safety documentation requirements in Europe create cost and timeline differentials against FDA-regulated US processing, rewarding processors with dual-certification capabilities.
For Market Incumbents: Deepen captive abattoir partnerships to secure immunoglobulin-rich raw material streams before Brazilian carbon policies further compress availability. Invest in continuous chromatographic separation platforms to reduce batch rejection rates and defend margin position against serum-free media substitution threats. Prioritize CDSCO regulatory harmonization in India to capture contract manufacturing growth multiplying local plasma derivative demand.
For New Entrants and Emerging Players: Precision livestock farming adopters in Denmark and the Netherlands represent an underserved buyer archetype demanding specification-grade pathogen-tested feed additives with Salmonella-negative certificates. Enter through spray-dried feed-grade plasma with immunoglobulin concentration guarantees, leveraging spot-market pricing flexibility against incumbents locked in long-term pharmaceutical contracts. Target diagnostic reagent manufacturers seeking alternative suppliers as EMA nucleic acid testing mandates extend release timelines from established processors.
For Investors and Strategic Acquirers: Roll-up economics work for regional rendering specialists with abattoir-proximate infrastructure because carbon policy shifts are fragmenting raw plasma supply and favoring processors with backward-integrated sourcing control. Long-term viability over a multi-year horizon rests on securing fractionation biochemistry talent pipelines and PCR validation capacity. Monitor ANVISA traceability alignment with EU Green Deal standards as the inflection signal for Brazilian export-oriented processor consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Abattoir Partnership Expansion | Secures immunoglobulin-rich raw plasma streams ahead of Brazilian carbon policy compression. |
| Continuous Chromatography Technology Licensing | Enables real-time quality monitoring for German and Swiss biopharmaceutical contract manufacturers. |
| EMA-FDA Dual Certification Investment | Unlocks geographic arbitrage between European traceability mandates and US diagnostic demand. |
| Indian CDSCO Regulatory Harmonization | Accelerates export qualification timelines for Maharashtra and Telangana manufacturing clusters. |
| Precision Livestock Farming Specification Development | Captures Danish and Dutch demand for pathogen-tested weaning diet additives. |
Research Methodology
Direct dialogue with fractionation biochemists, diagnostic reagent procurement managers, feed manufacturer supply planners, and pharmaceutical regulatory affairs specialists grounded qualitative findings in operational reality. Secondary validation drew from FDA guidance documents on animal-derived materials, EMA viral safety standards, USDA biologics oversight records, and ISO 22442 biocompatibility testing protocols. Bottom-up demand modeling across spray-dried, freeze-dried, liquid, and granulated plasma forms converged with top-down rendering industry capacity assessments.
Segment-level projections across product type, application channel, end user category, and packaging format generated volume and value trajectories across the analysis window. CAGRs emerged from regression analysis against cell culture media expansion rates, multiplex diagnostic platform adoption curves, and precision livestock farming penetration data. Modeled inputs incorporated REACH traceability mandate implementation timelines and CDSCO regulatory harmonization progress in India.
Underlying measurement precision varies by segment; freeze-dried pharmaceutical grades carry tighter precision than commodity feed-grade spray-dried volumes due to documented batch-level certification. Forecasts reflect assumptions regarding carbon policy implementation pace in Brazil and Argentina, EMA nucleic acid testing protocol adoption rates, and serum-free media substitution thresholds in stem cell applications. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Pegylated Protein Therapeutics Market
Biopharmaceuticals
Glycosylated Peptide Market
Biopharmaceuticals
Global Biopharma Buffer Market
Biopharmaceuticals
Human Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Disease-Modifying Antirheumatic Drug (DMARD) Market
Biopharmaceuticals
Fenbendazole Market
Biopharmaceuticals
Antibody Pair Kits Market
Biopharmaceuticals
Clindamycin Phosphate Market
Biopharmaceuticals
Plasma Protein System Market
Biopharmaceuticals
Bio-Active Peptides Market
Biopharmaceuticals
Large Macrolide Drugs Market
Biopharmaceuticals
Insulin Pens Market
Biopharmaceuticals
Global Drug Discovery Market
Biopharmaceuticals
Italy Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Resistant Pseudomonas Aeruginosa Infections Drugs Market
Biopharmaceuticals
Ovarian Cancer Drugs Market