
 Still Wine Market | 2026-2036
Still Wine Market Size, Share, and Industry Trends Forecast 2026-2036
Still Wine Market Intelligence
The direct-to-consumer sales channel is rewriting the traditional three-tier distribution system for wineries. This shift allows producers greater margin control and direct customer engagement. E. & J. Gallo Winery leverages its vast portfolio and distribution network to compete across multiple price points. Treasury Wine Estates differentiates through its focus on premium and luxury brands, building strong brand equity in key export markets like China and the United States.
Still wine is a non-effervescent alcoholic beverage produced through the fermentation of grape must, with alcohol content typically ranging from 9% to 16% ABV. Its primary purpose is for consumption as a beverage, often paired with food. Red wine, particularly from the Cabernet Sauvignon grape variety, continues to dominate value share due to its aging potential and premium positioning. The Rosé segment and alternative packaging formats like cans represent the fastest-growing categories, appealing to new consumer demographics.
Labeling and appellation standards are governed by bodies like the US Alcohol and Tobacco Tax and Trade Bureau (TTB) and the European Union's Protected Designation of Origin (PDO) framework. These regulations, alongside national bodies such as Wine Australia, dictate market access and define quality tiers for consumers. Producers must now navigate evolving sustainability certification demands alongside traditional geographic indication rules to maintain market relevance and consumer trust.
Market Dynamics
The still wine market is defined by a central tension between traditional, geographically-based quality systems like Europe's PDO and rising consumer demand for verifiable sustainability credentials. This dynamic forces producers to navigate dual compliance frameworks to maintain market access and brand relevance.
Growth Catalysts
- Trade Liberalization:Recent bilateral trade agreements are reducing tariffs on wine imports in key Asian markets, improving the price competitiveness of producers from Australia and Chile.
- On-Trade Channel Expansion:The growth of fine dining and hotel restaurant beverage programs, particularly in major metropolitan hubs, is driving demand for premium and super-premium wine lists.
- E-commerce Platform Adoption:The proliferation of direct-to-consumer online sales platforms allows wineries to bypass traditional distribution tiers, capturing higher margins and building direct customer relationships.
Market Restraints
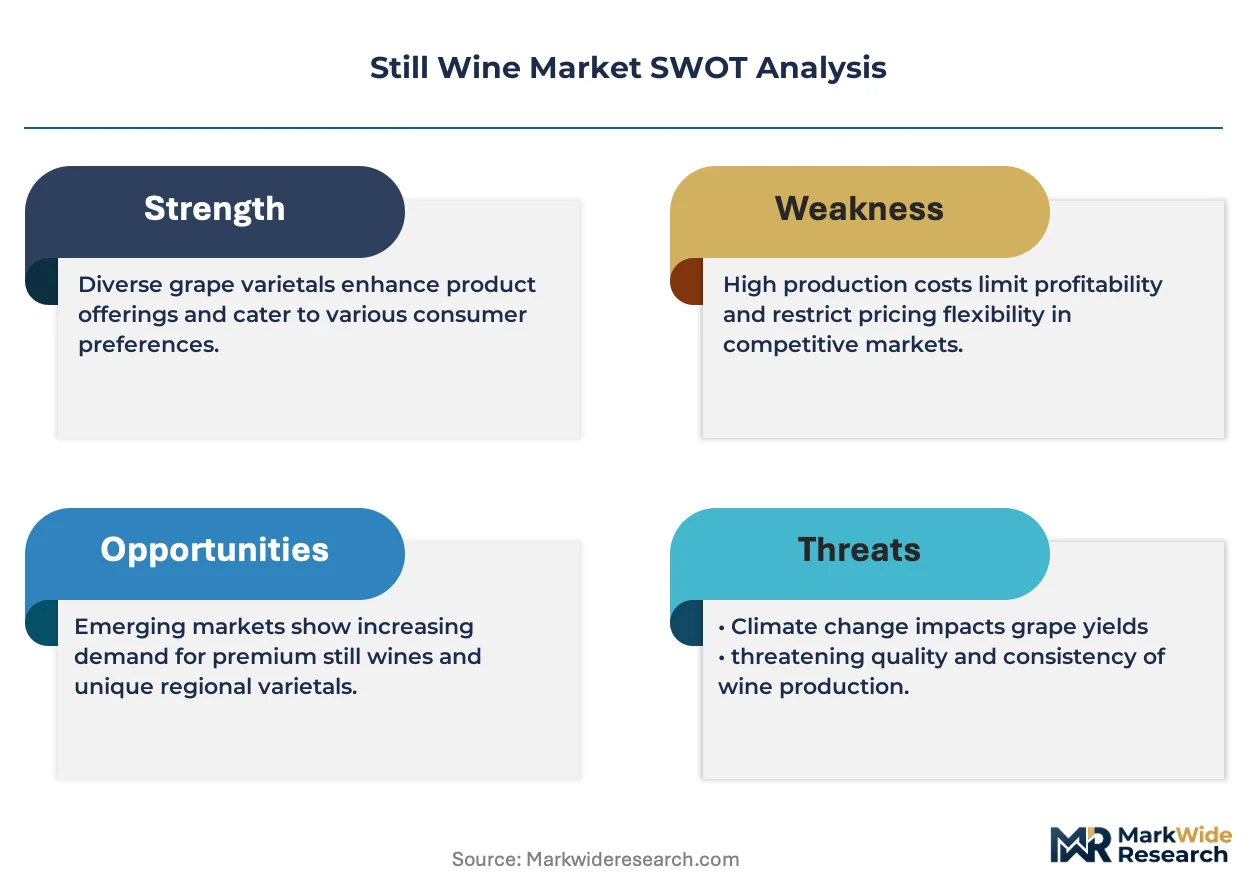
- Climate Volatility:Increasingly unpredictable weather patterns, including frost and drought, are affecting grape yields and quality in established European viticultural areas, leading to supply instability.
- Regulatory Heterogeneity:Disparate labeling and import requirements between major markets, such as the US TTB and the EU's PDO system, create significant compliance costs and logistical hurdles for exporters.
- Competition from Alternatives:The rise of craft spirits, hard seltzers, and non-alcoholic premium beverages presents a significant substitution threat, particularly among younger consumer demographics.
Strategic Opportunities
- Alternative Packaging Formats:Developing wine-in-can and wine-on-tap programs offers a path to access new consumption occasions and appeal to consumers seeking convenience and sustainability.
- Emerging Market Penetration:There is significant white space for market entry and brand building in Southeast Asian nations like Vietnam and Thailand, where wine consumption is nascent but growing.
- Precision Viticulture Technology:Investing in drone imaging and soil sensor technology allows for optimized vineyard management, improving grape quality and yield while reducing water and pesticide inputs.
Industry Challenges
- Sustainability Certification Complexity:Producers face a fragmented landscape of environmental certifications, each with different costs and requirements, making it difficult to choose which standards will resonate with consumers.
- Direct-to-Consumer Logistics:Managing the complexities of cold-chain shipping, state-specific shipping laws, and last-mile delivery for D2C sales channels presents a significant operational hurdle for many wineries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Still Wine Market |
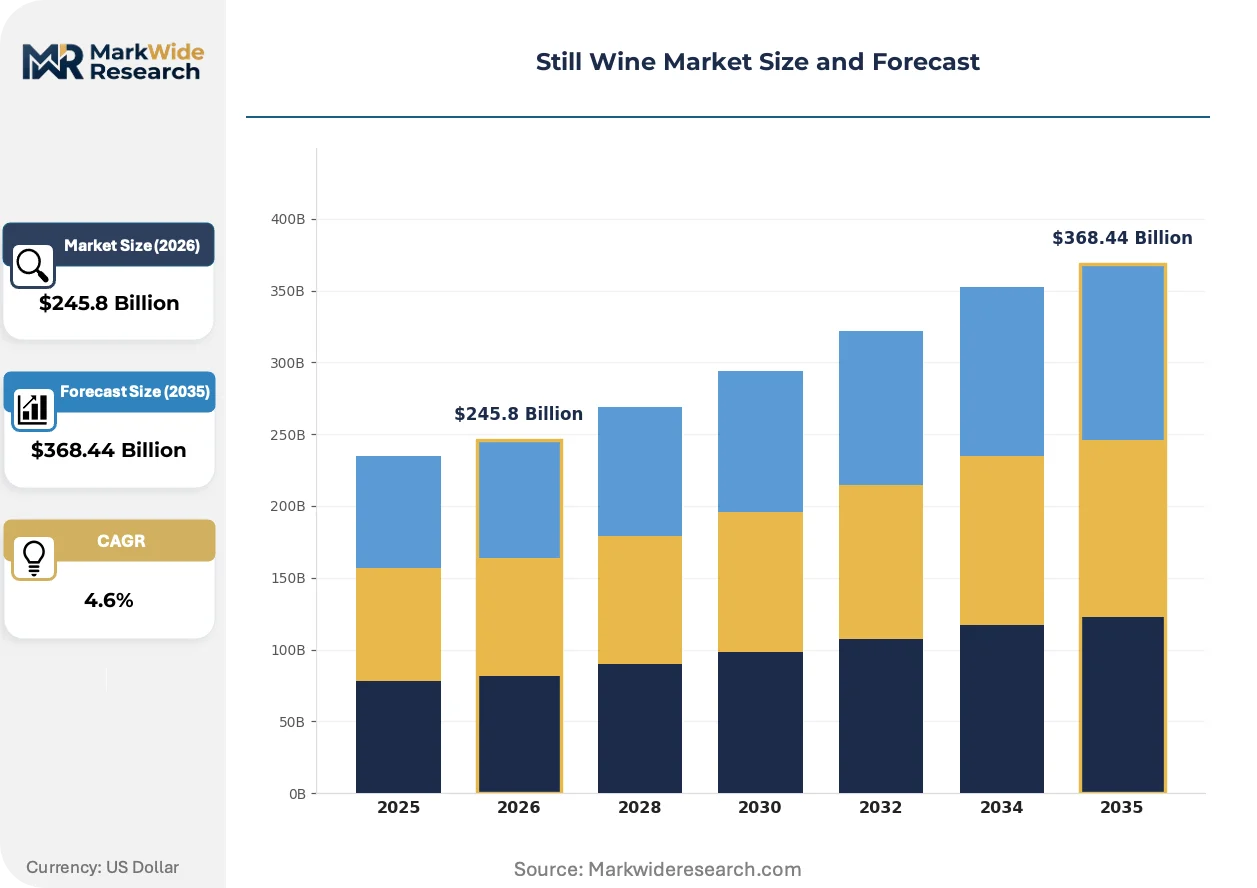
| Market Size in 2026 | $245.8 Billion |
| Market Size in 2035 | $368.44 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Wine, White Wine, Rosé, Sparkling Wine Grape Variety: Cabernet Sauvignon, Merlot, Chardonnay, Pinot Noir Packaging Type: Bottle, Box, Keg, Can Sales Channel: Retail Stores, Online, Restaurants, Wholesalers |
| Companies Covered | Diageo, Constellation Brands, E. & J. Gallo Winery, Pernod Ricard, Treasury Wine Estates, The Wine Group, Accolade Wines, Jackson Family Wines, Castel Frères, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Still Wine Market Strategic Shifts & Innovations
Technological advancements and shifting consumer values are reshaping the still wine industry's production and marketing paradigms. Data-driven viticulture and digital engagement are becoming as critical as terroir and tradition for achieving commercial success in a crowded marketplace.
Precision agriculture, utilizing AI-powered analytics from drone and sensor data, provides real-time insights into vine health and soil conditions. Large-scale wineries in regions like California and Australia are rapidly adopting these systems to optimize irrigation and pest control. This data-driven approach is rendering obsolete the traditional, experience-based methods of vineyard management, leading to more consistent yields and quality.
The European Union's Farm to Fork strategy mandates significant reductions in pesticide use, promoting a systemic shift towards organic farming. This policy increases operational costs for compliance and certification across the continent's viticultural practices. Wineries in protected appellations like Bordeaux and Tuscany are most impacted, accelerating transitions to organic and biodynamic methods to maintain premium positioning.
Consumers are demanding radical transparency regarding a wine's provenance, from farming practices to production methods. This shift favors digital platforms using QR codes and blockchain to provide detailed product stories, disrupting traditional marketing. The trend is most pronounced in the premium segment, where D2C sales in North America and Europe leverage transparency to build loyalty.
Still Wine Market Segmentation
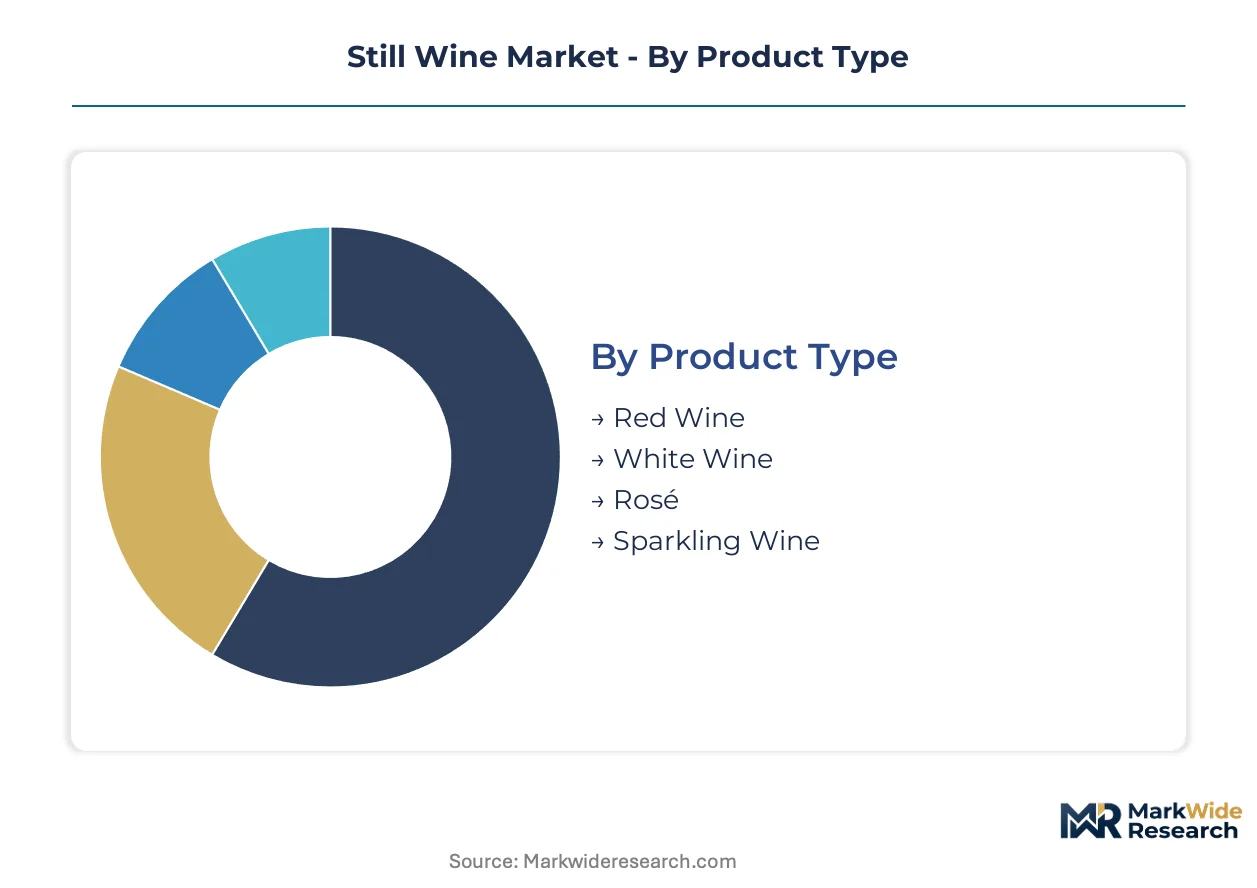
Understanding the still wine market through segmentation is critical for producers to tailor product offerings and distribution strategies effectively. Each segment represents distinct consumer preferences and operational considerations, influencing everything from vineyard management to retail placement. This granular view allows wineries to identify niches and allocate resources strategically.
Product Type:
The differentiation of still wine by product type heavily influences the post-purchase care and knowledge required by consumers.
- Red Wine:This category encompasses wines made from dark-skinned grapes, fermented with their skins to impart color and tannins, often aged in oak barrels. Demand concentrates in premium segments across major metropolitan areas in China, driven by its aging potential and food-pairing versatility.
- Rosé:Produced by brief skin contact with red grape varieties, resulting in a pink hue, these wines are typically fresh and consumed young. This segment is appealing to new consumer demographics seeking lighter styles and convenience, particularly in North America and Europe.
- White Wine:Fermented without grape skins, these wines range from dry to sweet, offering diverse flavor profiles. This type maintains broad consumer appeal across all major markets due to its versatility.
- Sparkling Wine:Characterized by its effervescence from a secondary fermentation, this product type is often associated with celebratory occasions. Specific regions like Champagne and Prosecco drive significant market volume.
Red Wine holds the largest share; momentum sits with Rosé.
Grape Variety:
Grape variety segmentation highlights the profound impact of terroir and cultivation practices on the final wine profile and consumer perception.
- Cabernet Sauvignon:A thick-skinned, tannic grape known for producing full-bodied red wines with aging potential, often displaying notes of blackcurrant and cedar. This variety dominates value share in premium red wine markets, especially in China and the United States.
- Pinot Noir:A delicate, thin-skinned grape requiring cool climates, yielding elegant, aromatic red wines with subtle fruit and earthy notes. Demand for this variety is strong in fine dining establishments and specific appellations like Burgundy and Oregon.
- Merlot:Softer and less tannic than Cabernet Sauvignon, Merlot produces approachable, medium-bodied red wines with plum and chocolate characteristics. It is frequently used in blends and as a standalone varietal for its smooth texture.
- Chardonnay:A versatile white grape that can produce a wide range of styles, from crisp and unoaked to rich and buttery with oak aging. This variety is a global benchmark for white wine quality and consumption.
Cabernet Sauvignon maintains its market dominance, while Chardonnay offers significant versatility across global markets.
Packaging Type:
The evolution of packaging types reflects shifting consumer priorities, balancing traditional presentation with demands for convenience and environmental responsibility.
- Bottle:The traditional glass bottle, typically 750ml, remains the standard for still wine, often sealed with corks or screw caps, and is crucial for aging premium wines. This format is preferred for fine dining and gifting occasions, particularly in established European markets.
- Can:Lightweight aluminum cans, usually single-serving, offer convenience, portability, and sustainability benefits due to recyclability. This alternative format is gaining share rapidly among younger demographics and for outdoor consumption occasions in North America.
- Box:Bag-in-box packaging provides larger volumes of wine, typically 3-5 liters, offering value and extended freshness after opening. This format appeals to consumers seeking cost-effective options for everyday consumption.
- Keg:Large format kegs are used for wine-on-tap systems, primarily in restaurants and bars, reducing waste and offering efficient service. This packaging type supports on-trade channel expansion and sustainability goals.
Traditional bottle formats still command the majority of sales, but alternative packaging like cans is rapidly expanding.
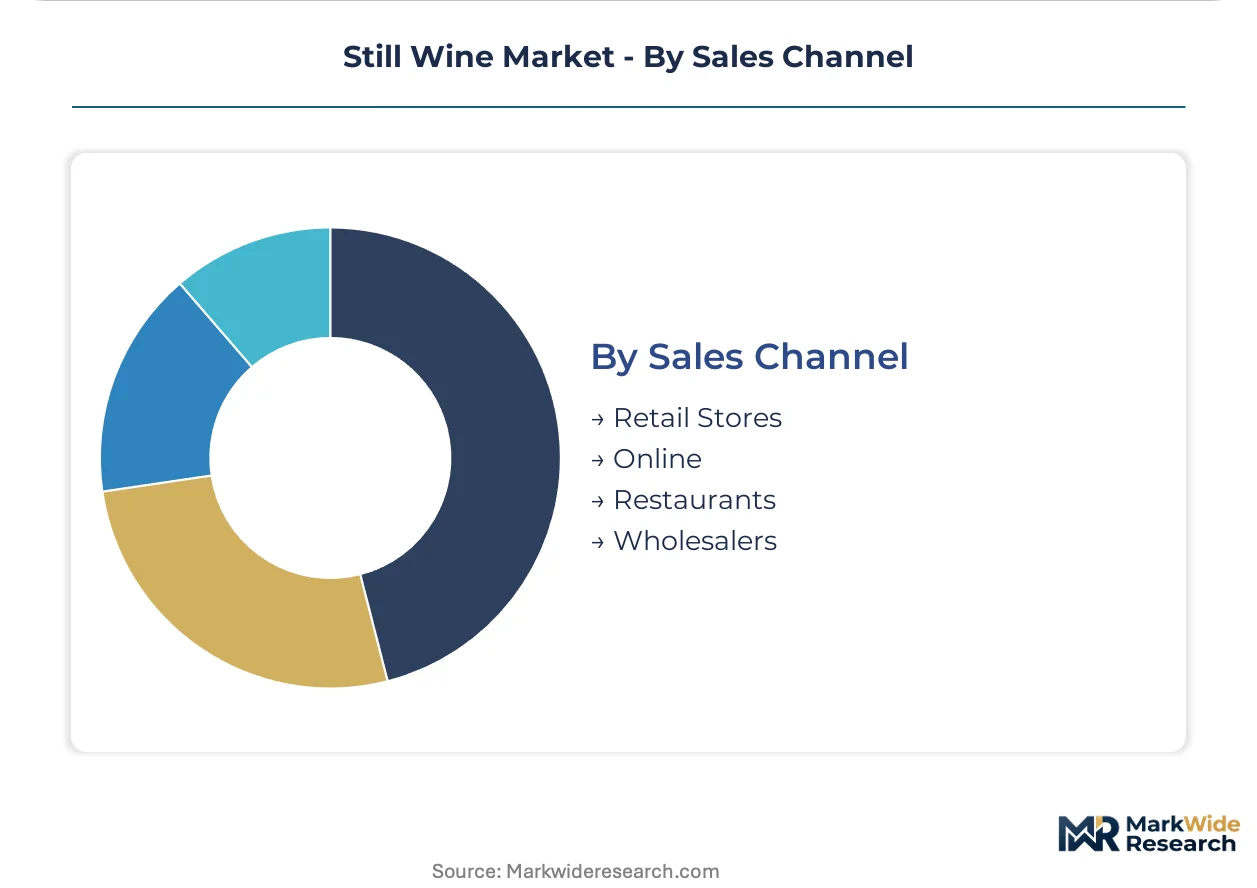
Sales Channel:
Segmentation by sales channel reveals the diverse pathways through which still wine reaches consumers, each with distinct logistical and engagement requirements.
- Online:E-commerce platforms, including winery-direct websites and third-party retailers, enable direct-to-consumer (D2C) sales models. This channel allows wineries greater margin control and direct customer engagement, particularly in North America and Europe.
- Restaurants:The on-trade channel, encompassing fine dining establishments, hotels, and casual eateries, focuses on curated wine lists and expert service. This channel drives demand for premium and super-premium wines, especially in major metropolitan hubs.
- Retail Stores:This segment includes supermarkets, hypermarkets, and specialized liquor stores, offering a broad selection of wines for off-premise consumption. Retail stores serve as a primary channel for volume sales and broad consumer accessibility.
- Wholesalers:These intermediaries manage bulk distribution from producers to various retail and on-trade outlets, handling logistics and inventory management. Wholesalers play a critical role in ensuring efficient supply chain operations for large-scale distribution.
While retail stores remain a primary channel, online sales are fundamentally reshaping distribution dynamics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade liberalization agreements are reshaping market access and competitiveness for still wine producers globally. These agreements reduce tariffs on wine imports, particularly benefiting key Asian markets. Such policy shifts encourage market penetration and brand building across diverse geographies.
China
Demand for premium, single-vineyard wines concentrates in China's major metropolitan areas. The country's customs regulations and import tariffs influence market access for international brands. Cities like Shanghai and Beijing exhibit significant consumption growth, driven by an expanding affluent consumer base.
United States
Consumers in the United States increasingly seek Rosé wines and convenient alternative packaging formats. The US TTB governs labeling and appellation standards, while state-specific laws complicate direct-to-consumer shipping logistics. California's Napa Valley remains a hub for premium wine production, alongside burgeoning D2C sales channels.
France
France maintains strong demand for wines from its established appellations, particularly in fine dining settings. The European Union's PDO framework strictly defines quality tiers and geographic indications for French wines. Wineries in regions like Bordeaux and Burgundy are transitioning to organic methods to meet new sustainability mandates.
Australia
Australian producers benefit from trade liberalization, enhancing price competitiveness in key Asian markets. Wine Australia oversees national standards and export regulations, supporting market access for its diverse offerings. Vineyards in South Australia's Barossa Valley are adopting precision viticulture to optimize yields and grape quality.
Italy
Italy's still wine market is driven by its rich tradition and strong brand equity in premium segments. The EU's PDO system rigorously enforces quality and origin standards for Italian wines, ensuring consumer trust. Producers in Tuscany, particularly Chianti, are investing in sustainability certifications to reinforce their market relevance.
Still Wine Market Key Industry Players
On the supply side, the industry is characterized by a mix of large, established global players and numerous smaller, regional wineries. Strategic archetypes include diversified beverage conglomerates competing across multiple price points, premium brand specialists focusing on luxury segments, and direct-to-consumer innovators leveraging e-commerce. Dominant competitive moves involve portfolio diversification to capture new consumer demographics and strategic acquisitions to expand market reach globally.
At the scale-driven end, E. & J. Gallo Winery exemplifies a diversified portfolio approach, competing across various price points with its extensive distribution network. This California-based winery has a strong presence across retail and on-trade channels. Treasury Wine Estates represents a premium brand specialist, building strong equity in key export markets like China and the United States with its luxury offerings. Constellation Brands, a New York-based company, occupies a significant position through its broad beverage alcohol portfolio, including established wine brands, and actively pursues market expansion.
| Leading Market Players |
|---|
| Diageo |
| Constellation Brands |
| E. & J. Gallo Winery |
| Pernod Ricard |
| Treasury Wine Estates |
| The Wine Group |
| Accolade Wines |
| Jackson Family Wines |
| Castel Frères |
| Others |
Cost & Logistics Intelligence
California's Napa Valley, a major hub for premium wine production, significantly influences downstream pricing power through its limited capacity and established brand equity. This concentration of high-quality vineyards and winemaking expertise creates a premium floor for comparable wines globally.
Pricing Analysis
Appellation standards and quality grade create the primary spread in still wine pricing. The market operates with a three-tier pricing structure across premium, standard, and economy levels, reflecting grape origin, aging potential, and brand reputation. Price differentiation also stems from unique varietal characteristics and sustainable farming certifications. Pricing softness runs through the economy segment due to competition from alternative beverages and private labels. Younger consumer demographics seeking convenience and value in alternative packaging formats exhibit the highest price sensitivity.
Supply Chain Analysis
Regulatory heterogeneity between major markets acts as a control, shaping still wine supply flows. Global supply concentration centers in established wine-producing nations like France, Italy, and Australia, which draw from their indigenous grape varieties and traditional winemaking practices. The supply chain relies on raw material inputs such as specific grape varietals, oak barrels for aging, and glass bottles. Regulatory complexity, particularly disparate labeling and import requirements, presents a significant structural risk for exporters. Distribution typically runs through a multi-tiered system involving wholesalers, retailers, and increasingly, direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The still wine market offers fragmentation opportunities as demand for sustainable and transparent products creates distinct niches. This allows for targeted strategies across various consumer segments.
For Market Incumbents: Entrench existing market share by diversifying product portfolios to include alternative packaging formats like cans and boxes. Invest in advanced precision viticulture technologies to mitigate climate volatility and enhance grape quality. Strategic acquisitions of smaller, sustainability-focused wineries can counter the threat from emerging craft beverage alternatives. Control over direct-to-consumer channels strengthens brand loyalty against traditional distribution pressures.
For New Entrants and Emerging Players: Establish a beachhead in rapidly growing segments such as Rosé wines and alternative packaging formats. Emerging markets in Southeast Asia present white-space opportunities for market entry and brand building. A go-to-market angle focusing on radical transparency, utilizing digital platforms with QR codes and blockchain, can build trust and loyalty among new consumer demographics. Target the convenience-seeking consumer segment with accessible, sustainably produced offerings.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors wineries actively integrating precision viticulture and digital D2C platforms. The long-term viability of the market is anchored in premiumization trends and verifiable sustainability credentials. Acquisition targets should include mid-sized producers with strong regional appellations, established D2C capabilities, or advanced sustainability certifications. A key signal to watch is the rate of consumer adoption for transparent product information and eco-friendly packaging solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification | Expands market reach by offering varied product types and packaging formats to new consumer demographics. |
| Sustainability Certification Program | Builds consumer trust and meets evolving regulatory demands for environmentally conscious production practices. |
| Direct-to-Consumer Platform Investment | Increases margin control and fosters direct customer relationships, bypassing traditional distribution tiers. |
| Precision Viticulture Adoption | Optimizes vineyard management, improving grape quality and yields while reducing environmental impact. |
| Emerging Market Entry | Captures nascent but growing wine consumption in regions with significant white space for brand development. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade publications, and established industry reports. Primary data collection involved structured interviews with winery owners, vineyard managers, distribution channel executives, and retail buyers. This approach ensures a comprehensive understanding of market dynamics, triangulating insights from both industry participants and expert sources.
The forecast inputs considered include historical market performance, technological advancements in viticulture, and evolving consumer preferences across the analysis window. The analytical framework modeled segmentation dimensions such as product type, grape variety, packaging format, sales channel, and regional consumption patterns. Compound annual growth rates were derived from a detailed analysis of market drivers and restraints, incorporating industry-specific inputs like grape harvest yields and trade policy shifts.
Stress conditions across climate change impacts and trade policy shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding economic stability and regulatory continuity. Unforeseen global economic downturns or significant shifts in consumer behavior represent key risk factors. Material shifts in global trade agreements or climate patterns would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Gluten-Free Beer Market
Alcoholic Beverages
Global Malted Barley Market
Alcoholic Beverages
Organic Alcoholic Beverages Market
Alcoholic Beverages
White Wine Market
Alcoholic Beverages
Global TCD Alcohol DM Market
Alcoholic Beverages
Cocktail Mixers Market
Alcoholic Beverages
CBD Wine Market
Alcoholic Beverages
Guerbet Alcohols Market
Alcoholic Beverages
South America Beer Market
Alcoholic Beverages
Global Hard Seltzers Market
Alcoholic Beverages
Tea Beer Market
Alcoholic Beverages
Honey Wine Market
Alcoholic Beverages
North America Spirits Market
Alcoholic Beverages
Global Wine Market
Alcoholic Beverages
Mushroom Beer Market
Alcoholic Beverages
Italy Alcohol E-Commerce Market