
 Indonesia Nitric Acid Market | 2026-2036
Indonesia Nitric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Nitric Acid Market Foresight
Indonesia's Ministry of Industry chemical sector modernization roadmap is expanding domestic nitric acid capacity requirements. Yara leverages its integrated ammonia-nitrate supply chain to dominate fertilizer-grade production in East Java. PT. Perdana Chemindo Perkasa anchors local manufacturing with captive feedstock access near Cilegon's petrochemical cluster. BASF SE competes through specialized industrial-grade formulations serving Sumatra's palm oil processing sector.
Nitric acid is a highly corrosive mineral acid with the chemical formula HNO3, typically produced via Ostwald process oxidation of ammonia over platinum-rhodium catalysts at temperatures exceeding 800°C, yielding concentrations from 50-70% for commercial applications. The strong product variant occupies the largest volume share due to its dominance in ammonium nitrate fertilizer synthesis. Dilute grades lead pharmaceutical and laboratory applications where lower concentration requirements reduce handling hazards. Fertilizer manufacturers represent the deepest end-user margin pool, absorbing over half of domestic offtake through direct sales contracts tied to seasonal planting cycles.
BIS standards alignment through Indonesia's national standardization body (BSN) governs product purity and packaging specifications, while the Ministry of Environment and Forestry enforces wastewater discharge limits on nitric acid plants. The Ministry of Industry's downstream chemical incentives condition licensing on energy efficiency benchmarks and local content thresholds. Stakeholders must monitor BSN's anticipated harmonization with ASEAN chemical safety protocols and the Ministry of Energy's clean production mandates affecting ammonia feedstock sourcing.
Market Dynamics
Indonesia's Ministry of Industry chemical sector modernization is forcing domestic nitric acid producers to retrofit aging Ostwald process plants with energy recovery systems and platinum-rhodium catalyst regeneration capabilities. This structural pressure concentrates investment among integrated ammonia-nitrate operators with captive feedstock access.
Growth Catalysts
- Fertilizer-grade demand surge:Indonesia's food security agenda drives ammonium nitrate absorption through seasonal planting contracts tied to Ministry of Agriculture distribution programs.
- BSN standardization alignment:Harmonization with ASEAN chemical safety protocols reduces cross-border certification friction for export-oriented producers.
- East Java industrial corridor expansion:Surabaya's port infrastructure upgrades enable larger vessel handling for concentrated acid shipments to palm oil processing clusters.
Market Restraints
- Ammonia feedstock volatility:Natural gas price fluctuations at Cilegon's petrochemical cluster transmit directly to nitric acid production economics.
- Platinum-rhodium catalyst supply concentration:South African and Russian refinery output constraints create bottleneck risk for high-temperature oxidation capacity expansion.
- Wastewater discharge compliance:Ministry of Environment and Forestry NOx effluent limits require capital-intensive abatement retrofits at legacy plants.
Strategic Opportunities
- Sumatra palm oil derivatives:Industrial-grade formulations for oleochemical processing remain underpenetrated relative to Java's saturated fertilizer corridor.
- Clean production mandates:Ministry of Energy renewable ammonia pilot programs offer first-mover positioning for green feedstock sourcing.
- Dilute-grade pharmaceutical channel:Laboratory and reagent applications bypass seasonal fertilizer demand cycles through year-round offtake agreements.
Industry Challenges
- Specialized catalyst technician scarcity:Platinum-rhodium gauze maintenance and regeneration expertise concentrates among retiring workforce cohorts at state-owned chemical complexes.
- Legacy plant energy efficiency gaps:Pre-2010 Ostwald installations lack heat recovery integration required for Ministry of Industry licensing benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Nitric Acid Market |
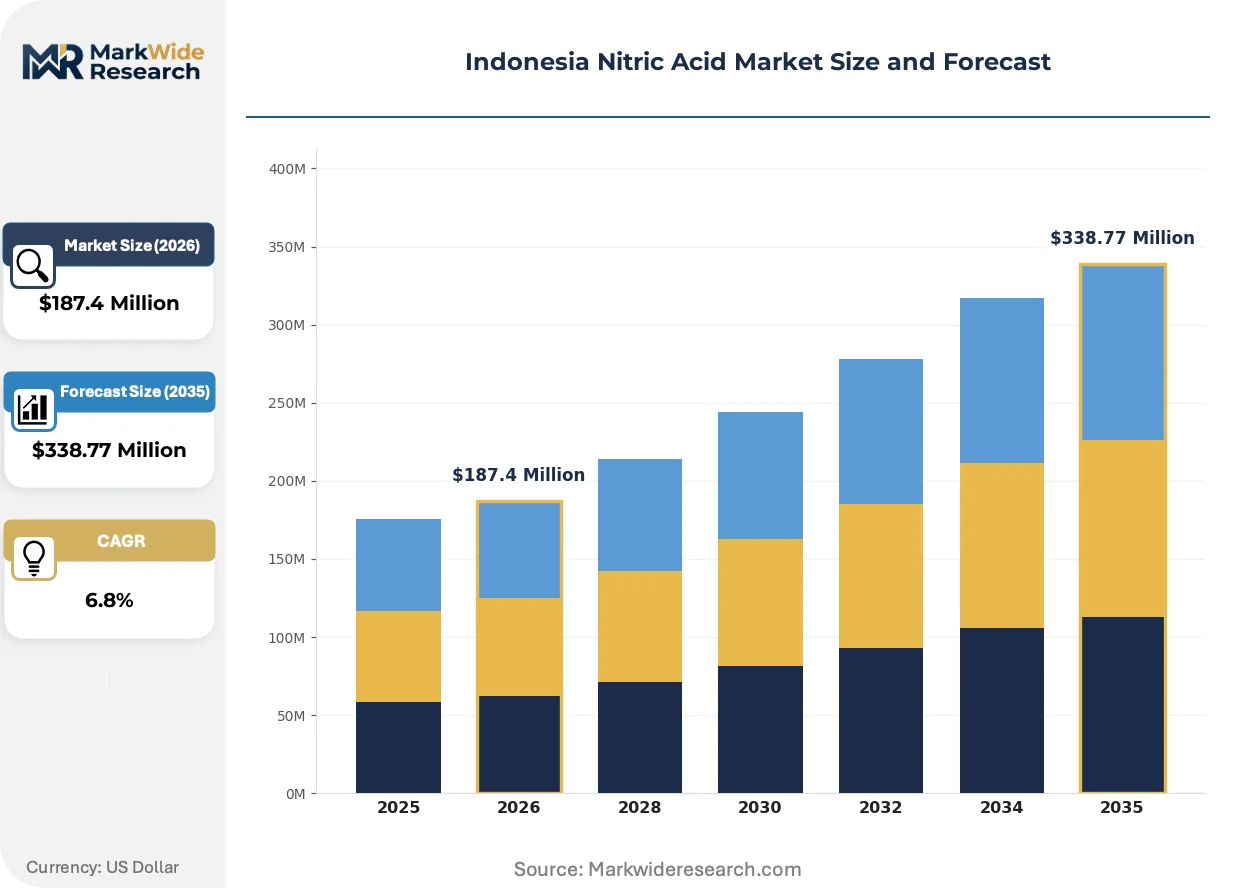
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Strong, Dilute, Anhydrous, Aqueous Application: Agriculture, Pharmaceuticals, Explosives, Chemicals End User: Fertilizer Manufacturers, Chemical Producers, Research Labs, Industrial Users Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Yara, Thermo Fisher Scientific, BASF SE, Sumitomo Chemical Co Ltd, PT. Perdana Chemindo Perkasa, Mitsubishi Chemical Corporation, Hanwha Corporation, Sasol Ltd, Merck KGaA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Nitric Acid Market Shifts & Advancements
Digital process control systems are penetrating Indonesia's nitric acid sector as producers face mounting pressure to optimize platinum catalyst consumption and reduce unplanned outages. Automation investments concentrate among integrated operators seeking to defend margin positions against feedstock volatility.
Distributed control systems with real-time catalyst activity monitoring are automating oxidation temperature regulation at Cilegon and Surabaya facilities. Fertilizer-grade producers with captive ammonia supply deploy these systems fastest, compressing maintenance intervals from quarterly to predictive schedules based on pressure-drop analytics.
BSN's anticipated adoption of ASEAN chemical safety protocols is tightening packaging and labeling specifications for cross-border shipments. Industrial-grade exporters to Malaysian and Thai oleochemical buyers face reformulation costs to meet harmonized purity thresholds, driving consolidation among multi-plant operators with centralized quality laboratories.
Long-term offtake contracting is displacing spot market transactions as palm oil processors seek supply security amid feedstock volatility. Major consumers in North Sumatra's Medan corridor now lock eighteen-month volumes directly with producers, bypassing traditional distributor networks and compressing working capital cycles for integrated manufacturers.
Indonesia Nitric Acid Market Segmentation
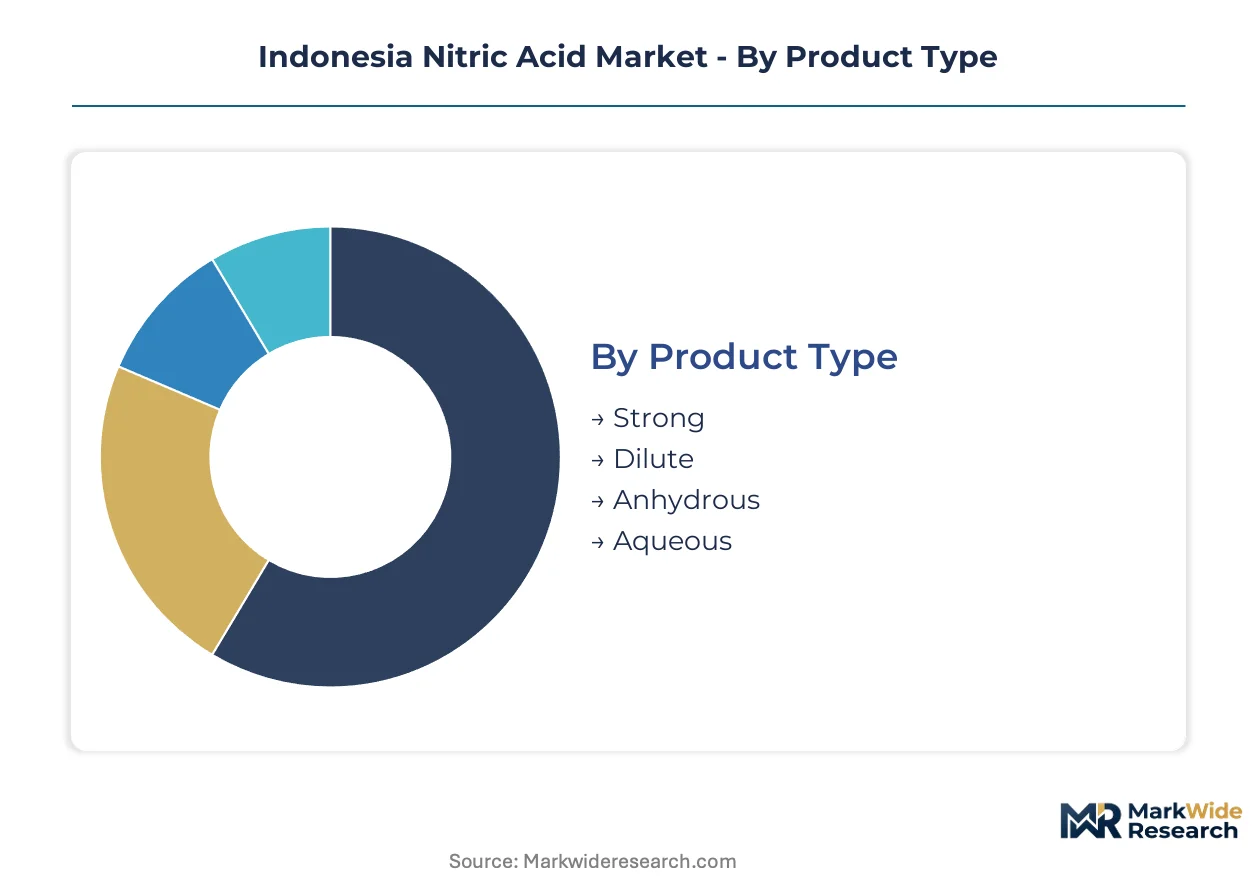
Segmentation in Indonesia's nitric acid market reveals how product specifications, application requirements, and procurement channels create distinct competitive arenas. Producers must align manufacturing configurations with the divergent purity, volume, and delivery demands of fertilizer-grade bulk buyers versus pharmaceutical and laboratory customers.
Product Type:
Standardization dominates at the commodity end while specialty grades command formulation premiums based on concentration thresholds and impurity controls.
- Strong:Concentrations of 50-70% HNO3 serve ammonium nitrate synthesis and industrial oxidation processes. Fertilizer manufacturers in East Java's Surabaya corridor absorb the largest volumes through direct procurement contracts tied to seasonal planting cycles.
- Dilute:Lower concentration variants reduce handling hazards for laboratory and pharmaceutical applications. Research institutions and reagent distributors in Jakarta and Bandung concentrate demand for analytical-grade formulations requiring precise impurity specifications.
- Anhydrous:Water-free nitric acid serves specialized nitration reactions in pharmaceutical and fine chemical synthesis. Limited domestic production capacity creates import dependence for high-purity requirements.
- Aqueous:Water-diluted solutions offer flexible concentration blending for metal processing and surface treatment applications. Industrial users in Cilegon's manufacturing cluster favor this grade for cost-sensitive etching and pickling operations.
Leading the category by volume: Strong. Growing fastest: Dilute.
Application:
Cost tier stratification separates commodity-scale absorption from premium-priced specialty channels.
- Agriculture:Ammonium nitrate fertilizer production consumes the deepest volume pool, with Ministry of Agriculture distribution programs driving seasonal demand spikes. Fertilizer manufacturers in Java maintain captive acid production or lock long-term supply agreements.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis and laboratory reagent applications require BSN-certified purity grades. Jakarta's pharmaceutical manufacturing belt generates concentrated demand for dilute and high-purity variants.
- Explosives:Mining and construction blasting applications absorb industrial-grade nitric acid for ammonium nitrate fuel oil production. Sumatra's coal and mineral extraction corridors represent the primary geography.
- Chemicals:Intermediate synthesis for dyes, plastics, and specialty chemicals spans diverse concentration requirements. Cilegon's petrochemical cluster anchors domestic demand for multi-grade supply contracts.
Volume leadership: Agriculture. Steepest expansion trajectory: Pharmaceuticals.
End User:
Customer type determines contract structure, with integrated producers favoring direct supply and fragmented buyers relying on distributor networks.
- Fertilizer Manufacturers:Integrated ammonia-nitrate operators with captive feedstock access dominate procurement, locking multi-year volumes through direct sales agreements. Seasonal planting cycles create predictable offtake patterns.
- Chemical Producers:Oleochemical and specialty chemical manufacturers require flexible grade switching and just-in-time delivery. North Sumatra's palm oil processing belt generates growing industrial-grade demand.
- Research Labs:Universities, government testing facilities, and private analytical laboratories purchase small-batch dilute grades through distributor channels. Jakarta and Surabaya concentrate institutional procurement.
- Industrial Users:Metal processing, electronics, and surface treatment operations absorb mid-tier concentrations via wholesaler networks. Batam's electronics manufacturing zone represents an emerging demand pocket.
Deepest margin pool: Fertilizer Manufacturers. Fastest contract growth: Chemical Producers.
Distribution Channel:
Supply concentration favors direct relationships for volume buyers while fragmentation characterizes small-lot procurement.
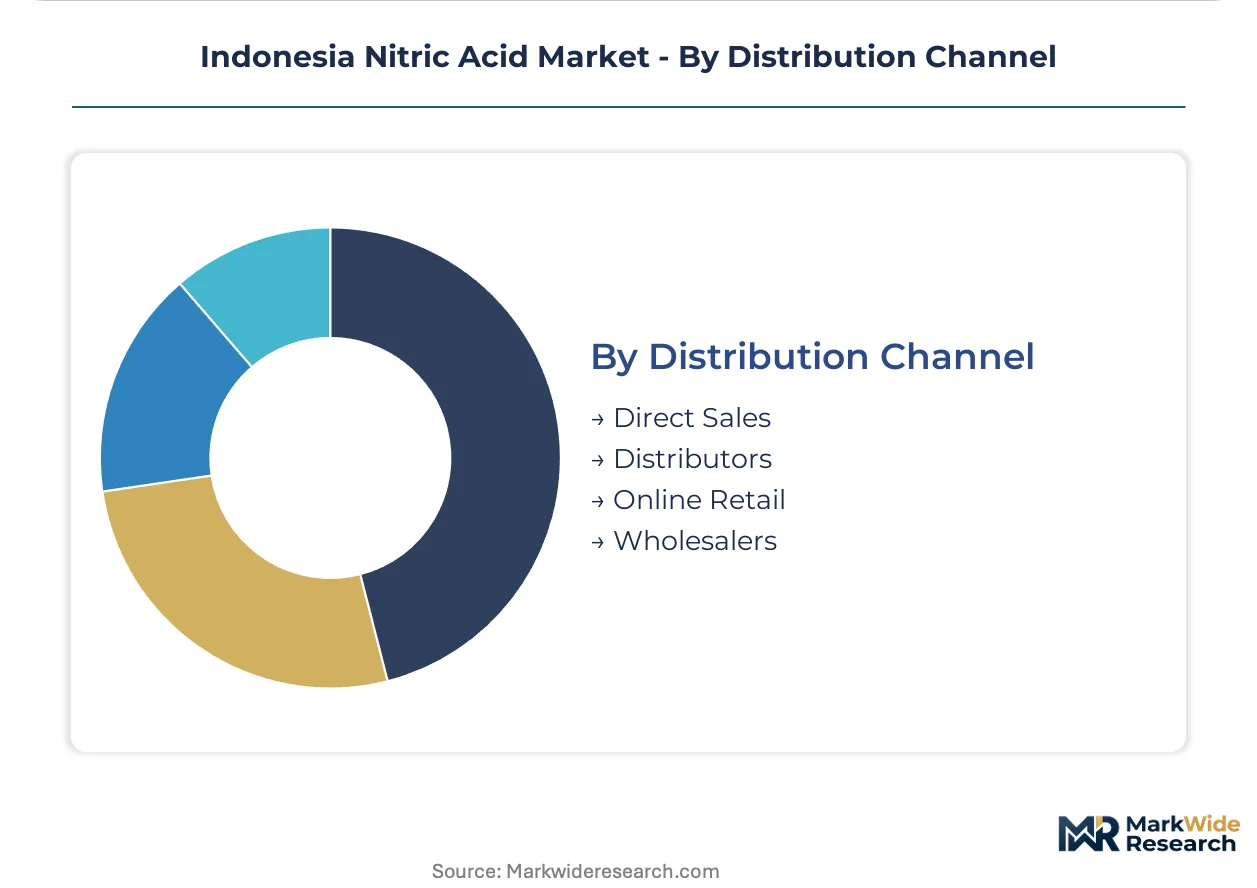
- Direct Sales:Producers with integrated ammonia-nitrate capacity bypass intermediaries for fertilizer-grade volumes. Long-term offtake agreements predominate in East Java's industrial corridor.
- Distributors:Regional chemical distributors aggregate fragmented demand from laboratories and small industrial users. Java's dense manufacturing geography supports distributor profitability.
- Online Retail:E-commerce platforms penetrate laboratory reagent and small-batch industrial supply. Jakarta-based distributors lead digital channel development for dilute-grade products.
- Wholesalers:Bulk break-bulk operations serve secondary cities and outer island markets with limited producer presence. Sulawesi and Kalimantan rely heavily on wholesaler intermediation.
Channel leadership by volume: Direct Sales. Fastest digital adoption: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's nitric acid production concentrates in Java's industrial corridor while consumption spreads across archipelago processing clusters. Domestic capacity expansion lags behind fertilizer-grade demand growth from Ministry of Agriculture distribution programs. Regional development strategies prioritize captive ammonia-nitrate integration over standalone acid production.
Java
East Java's Surabaya corridor anchors national production through integrated ammonia-nitrate facilities serving seasonal fertilizer contracts. BSN standardization alignment with ASEAN chemical safety protocols tightens packaging specifications for cross-border shipments to Malaysian oleochemical buyers. Cilegon's petrochemical cluster hosts PT. Perdana Chemindo Perkasa's captive feedstock operations near integrated refinery complexes.
Sumatra
North Sumatra's Medan corridor generates industrial-grade demand from palm oil processing and mining explosives applications. Ministry of Environment and Forestry wastewater discharge limits apply to planned acid plant investments in the region's developing chemical zones. Long-term offtake contracting now dominates procurement as processors seek supply security amid feedstock volatility.
Kalimantan
Coal and mineral extraction corridors absorb ammonium nitrate fuel oil production for blasting operations across East and South Kalimantan. Ministry of Industry downstream chemical incentives condition licensing on energy efficiency benchmarks for prospective acid plant developments. Wholesaler intermediation remains essential due to limited producer presence in outer island markets.
Sulawesi
Nickel processing and emerging battery material investments create nascent industrial-grade demand in Southeast Sulawesi's Morowali industrial park. Clean production mandates from Ministry of Energy renewable ammonia pilot programs attract first-mover positioning for green feedstock sourcing. Port infrastructure limitations constrain concentrated acid shipment volumes from Java-based suppliers.
Batam and Riau Islands
Electronics manufacturing zones in Batam generate small-batch demand for metal processing and surface treatment applications. BIS-equivalent national standards govern product purity specifications for laboratory and reagent applications serving cross-border trade flows. Distributor networks aggregate fragmented demand from industrial users lacking direct producer relationships.
Indonesia Nitric Acid Market Competitive Landscape
The competitive structure tilts toward integrated ammonia-nitrate operators with captive feedstock access. Fertilizer-grade production concentrates among state-affiliated and multinational chemical complexes holding long-term Ministry of Agriculture supply contracts. Three archetypes dominate: integrated fertilizer manufacturers, diversified industrial chemical conglomerates, and specialty reagent distributors. Capacity expansion and strategic partnerships represent the primary competitive vectors as producers retrofit aging Ostwald process installations.
Among integrated fertilizer specialists, Yara anchors the premium tier through its East Java supply chain dominance. BASF SE occupies a position within the diversified industrial chemical archetype, while PT. Perdana Chemindo Perkasa exemplifies local manufacturing integration near Cilegon's petrochemical cluster. Thermo Fisher Scientific and Merck KGaA sit within the laboratory reagent distribution tier, serving analytical-grade requirements through established distributor networks.
| Leading Market Players |
|---|
| Yara |
| Thermo Fisher Scientific |
| BASF SE |
| Sumitomo Chemical Co Ltd |
| PT. Perdana Chemindo Perkasa |
| Mitsubishi Chemical Corporation |
| Hanwha Corporation |
| Sasol Ltd |
| Merck KGaA |
| Others |
Supply & Pricing Matrix
Captive ammonia-nitrate integration anchors both supply positioning and pricing power across Indonesia's nitric acid corridor. Fertilizer manufacturers with backward integration into ammonia feedstock command premium contract terms through Ministry of Agriculture distribution programs, while non-integrated buyers absorb spot market volatility.
Pricing Analysis
Margin tightening in fertilizer-grade contracts reflects natural gas price transmission from Cilegon's petrochemical cluster. Contract-based long-term offtake dominates procurement, with price differentiation hinging on volume scale and BSN certification tier. Cost-down pressure on dilute-grade laboratory supply accelerates because distributor networks compete for Jakarta's research institution procurement. Fertilizer manufacturers show lowest price sensitivity due to captive integration, while small-batch industrial users in Batam exhibit highest sensitivity.
Supply Chain Analysis
Direct-to-fertilizer-producer channels handle bulk ammonium nitrate demand through East Java's Surabaya corridor. Geographic supply concentration centers on Indonesia, with platinum-rhodium catalyst sourcing drawing from South Africa and Russian refinery output. Raw material dependencies include natural gas feedstock, specialized catalyst gauze, and corrosion-resistant alloy equipment. Single-source vulnerability in catalyst technician expertise creates bottleneck risk. Distribution runs through integrated producer networks for volume buyers and regional chemical distributors for fragmented laboratory demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's nitric acid market operates as a supply-constrained system where platinum-rhodium catalyst regeneration capacity limits effective output expansion, propping contract pricing for integrated operators.
For Market Incumbents: Anchor defensive positioning through captive ammonia feedstock expansion near Cilegon's petrochemical cluster and predictive catalyst maintenance systems that compress unplanned outages. Emerging digital process control specialists threaten technical service margins, making technician training pipelines a critical lever for sustaining oxidation capacity utilization.
For New Entrants and Emerging Players: Laboratory and pharmaceutical buyers in Jakarta's manufacturing belt remain underserved by domestic anhydrous-grade production, creating white-space entry through import-substitution partnerships with Malaysian or Thai specialty chemical suppliers. Clean production mandates from Ministry of Energy renewable ammonia pilots offer regulatory-aligned positioning for green feedstock sourcing.
For Investors and Strategic Acquirers: Exit pathways concentrate in integrated ammonia-nitrate operators with Ministry of Agriculture contract backlogs. Long-term viability favors producers with Ostwald process retrofit completion and wastewater abatement compliance. Watch for BSN-ASEAN harmonization implementation as inflection signal for export-oriented capacity valuation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia Feedstock | Cilegon petrochemical cluster proximity reduces natural gas price transmission exposure for nitric acid producers. |
| Catalyst Regeneration Capability Investment | Platinum-rhodium gauze maintenance expertise addresses workforce scarcity constraining oxidation capacity expansion. |
| Long-term Supply Agreement with Fertilizer Manufacturers | Ministry of Agriculture distribution programs provide predictable offtake patterns bypassing spot market volatility. |
| Green Manufacturing Transition | Ministry of Energy renewable ammonia pilot programs enable first-mover positioning for clean feedstock sourcing. |
| Joint Venture for Anhydrous-Grade Production | Import-dependent pharmaceutical synthesis demand in Jakarta creates partnership opportunity with ASEAN specialty chemical producers. |
Research Methodology
Multi-period observation of ammonia feedstock pricing, catalyst consumption rates, and Ministry of Agriculture contract awards anchored the trend analysis, supplemented by interviews with plant managers at integrated ammonia-nitrate facilities, procurement leads at fertilizer manufacturers, distribution channel partners in Java's chemical corridor, and technical R&D directors overseeing Ostwald process optimization. Secondary validation drew from customs and trade data, Indonesian Ministry of Industry sector reports, BSN standardization documentation, and SEC filings of multinational chemical conglomerates active in Southeast Asia. Bottom-up capacity utilization modeling and top-down demand projection from agricultural planting cycles were triangulated.
Segment-weighting across product type, application, and end-user categories shaped the analytical framework over the projection horizon. Grade tier distinctions between strong, dilute, anhydrous, and aqueous formulations were modeled alongside end-use industry segmentation spanning agriculture, pharmaceuticals, explosives, and specialty chemicals. CAGRs were derived from regression analysis of historical capacity expansion against Ministry of Industry licensing benchmarks. Forecast inputs incorporated seasonal planting cycle patterns and clean production mandate implementation timelines.
Revisions become necessary when platinum-rhodium catalyst supply disruptions, natural gas price shocks, or BSN-ASEAN harmonization delays materialize beyond baseline assumptions. Forecasts reflect documented expectations for feedstock cost trajectories and regulatory implementation schedules. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Asia-Pacific Methanol Market
Chemicals
Whitening Ingredients Market
Chemicals
Spirodiclofen Market
Chemicals
Linear Mercaptans Market
Chemicals
Scouring Agents Market
Chemicals
Nonaisoprenol Market
Chemicals
Leather Tanning Chemicals Market
Chemicals
Desalination Chemicals Market
Chemicals
Uranyl Carbonate Market
Chemicals
3-Fluoro-5-Nitrotoluene Market
Chemicals
North America Construction Chemicals Market
Chemicals
Valeryl Chloride Market
Chemicals
Global Diphenylmethane Diisocyanate Market
Chemicals
Amyl Nitrite Market
Chemicals
Guaiacol Market
Chemicals
Photographic Film Processing Chemicals Market