
 Etching Chemicals Market | 2026-2036
Etching Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Etching Chemicals Market Analysis
Electronic-grade purity specifications is redrawing competitive boundaries across the etching chemicals landscape. BASF SE leverages its integrated precursor chemistry platform to secure supply relationships with leading wafer fabs. Stella Chemifa Corporation anchors Asia-Pacific supply chains through ultra-high-purity fluoride production. Honeywell International Inc. competes on fluoropolymer-derived etchant portfolios tailored to sub-7nm processes.
Etching chemicals comprise formulated acids, alkaline solutions, solvents, and salts engineered to selectively remove material layers during microfabrication, with electronic-grade variants demanding metallic impurity levels below one part per billion. These formulations enable precise pattern transfer in semiconductor manufacturing, where etch uniformity directly determines device yield. Acids dominate volume consumption in wet etching benches, while alkaline solutions capture expanding share in gallium nitride and silicon carbide processing. Electronic-grade specifications command premium positioning as foundries advance to angstrom-scale nodes.
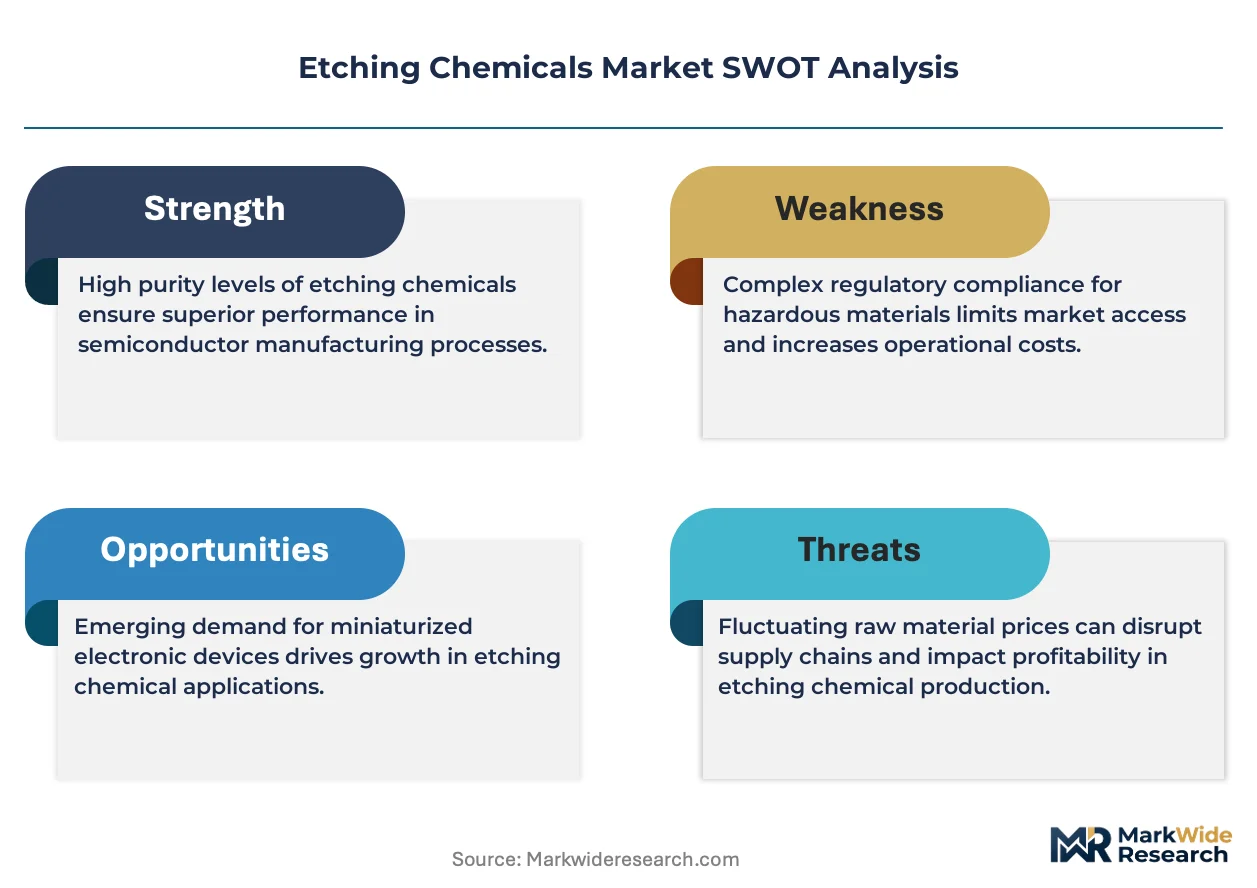
EPA regulations in the United States restrict perfluorinated compound emissions from etching operations, compelling reformulation investments. REACH registration requirements in Europe mandate full substance toxicity documentation for imported etchants. Semiconductor fabrication stakeholders must monitor evolving PFAS restrictions across multiple jurisdictions while qualifying next-generation low-global-warming-potential chemistries.
Market Dynamics
Angstrom-scale node transitions are compressing etchant qualification cycles while fragmenting supplier bases across multiple geographic clusters. Foundries now demand simultaneous compliance with EPA PFAS restrictions, REACH substance documentation, and emerging MEE emission protocols in China.
Growth Catalysts
- Sub-7nm Semiconductor Nodes:Taiwan Semiconductor Manufacturing and Samsung Foundry are expanding captive etchant consumption for gate-all-around transistor architectures. This process node transition demands fluoride-based formulations with metallic impurity thresholds below 0.1 parts per billion.
- REACH Registration Mandates:European ECHA requirements for full toxicity dossiers on imported etchants are accelerating substitution toward documented chemistries. German chemical distributors report qualification backlogs extending eighteen months for non-registered substances.
- Silicon Carbide Power Devices:Automotive inverter manufacturers in South Korea and Japan are scaling wet etching capacity for wide-bandgap substrates. Alkaline etchant formulations tailored to silicon carbide crystal planes are capturing foundry qualification slots.
Market Restraints
- Hydrofluoric Acid Supply Concentration:Mexican and Chinese fluorspar concentrate exports dominate precursor supply chains. Geopolitical friction around critical mineral access threatens input cost stability for North American etchant blenders.
- PFAS Regulatory Fragmentation:Divergent EPA state-level enforcement, EU F-Gas phase-down schedules, and emerging Chinese MEE restrictions create formulation compliance conflicts. Multi-jurisdictional operators face duplicative testing expenditures.
- Aqueous Etching Rate Limitations:Isotropic wet chemistries cannot achieve the vertical sidewall profiles required for 3D NAND string stacking. Dry etching alternatives are capturing share in high-aspect-ratio memory fabrication.
Strategic Opportunities
- Indian Semiconductor Mission Incentives:PLI scheme allocations for domestic fab construction are creating first-mover advantages for etchant suppliers establishing local blending capacity. Gujarat and Tamil Nadu state governments are fast-tracking environmental clearances for electronic-grade chemical parks.
- Copper Interconnect Reflow:Hybrid etching sequences combining wet chemical removal with electrochemical planarization are emerging for back-end-of-line metallization. Equipment-agnostic formulation suppliers can capture process integration value.
- Green Chemistry Certification:EU Green Deal taxonomy alignment for low-global-warming-potential etchants is unlocking preferential procurement scoring. Formulations replacing nitrogen trifluoride process gases with liquid-phase alternatives qualify for accelerated ESG-linked financing.
Industry Challenges
- Cleanroom Chemist Talent Scarcity:Formulation scientists capable of correlating etch rate data with atomic-scale surface roughness measurements command premium compensation. Singapore and Hsinchu foundry clusters report thirty-percent vacancy rates in analytical chemistry roles.
- Multi-Customer Qualification Burden:Each foundry maintains proprietary metrology protocols for metallic contamination detection. Etchant suppliers must replicate identical purity certifications across incompatible customer test matrices.
- Legacy Wet Bench Retrofit Costs:Existing semiconductor fabrication facilities require plumbing material upgrades to handle next-generation low-pH, high-oxidant formulations. Capital allocation conflicts delay etchant transitions at mature nodes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Etching Chemicals Market |
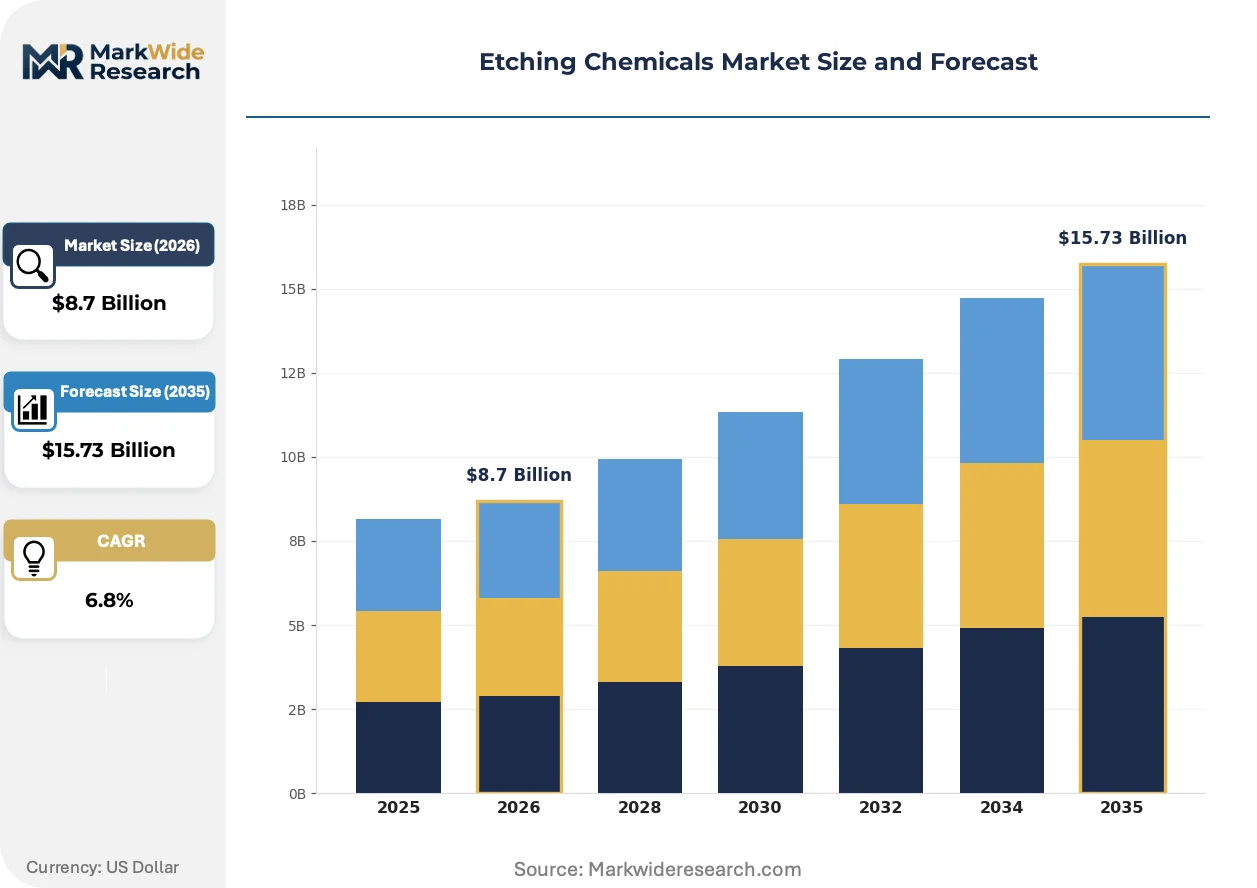
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acids, Alkaline Solutions, Solvents, Salts End Use Industry: Electronics, Aerospace, Automotive, Healthcare Grade: Industrial Grade, Laboratory Grade, Reagent Grade, Electronic Grade Application: PVD, CVD, Semiconductor Fabrication, Photolithography |
| Companies Covered | Merck KGaA, Kanto Chemical Co., Inc., BASF SE, Solvay SA, Mitsubishi Chemical Group Corporation, Stella Chemifa Corporation, Honeywell International Inc., Avantor Inc., The Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Etching Chemicals Market Emerging Trajectories
Process equipment convergence with real-time chemical monitoring is collapsing the traditional separation between etchant supply and process control functions. Formulation houses now compete on sensor-integrated delivery systems rather than standalone chemical purity.
Supercritical carbon dioxide-based dry cleaning chemistries are displacing aqueous hydrofluoric acid sequences in sensitive MEMS release steps. Bosch Sensortec and STMicroelectronics manufacturing lines in Dresden and Crolles have qualified these processes for accelerometer fabrication. The displacement is compressing wastewater treatment infrastructure requirements while extending equipment depreciation schedules.
EPA enforcement of Clean Air Act amendments targeting fluorinated greenhouse gases is forcing foundry requalification of etchant process emissions. Intel's Arizona and Oregon facilities have submitted revised Title V permits incorporating alternative chemistries. Memory manufacturers in Japan's Yokkaichi cluster face parallel METI reporting obligations on perfluorinated compound inventories.
Direct chemical management contracts are consolidating procurement authority at the parent-company level rather than individual fab sites. SK Hynix and Micron Technology have centralized global etchant sourcing decisions in Seoul and Boise headquarters respectively. Taiwan remains the exception where TSMC maintains site-specific supplier relationships tied to individual process technology divisions.
Etching Chemicals Market Segmentation
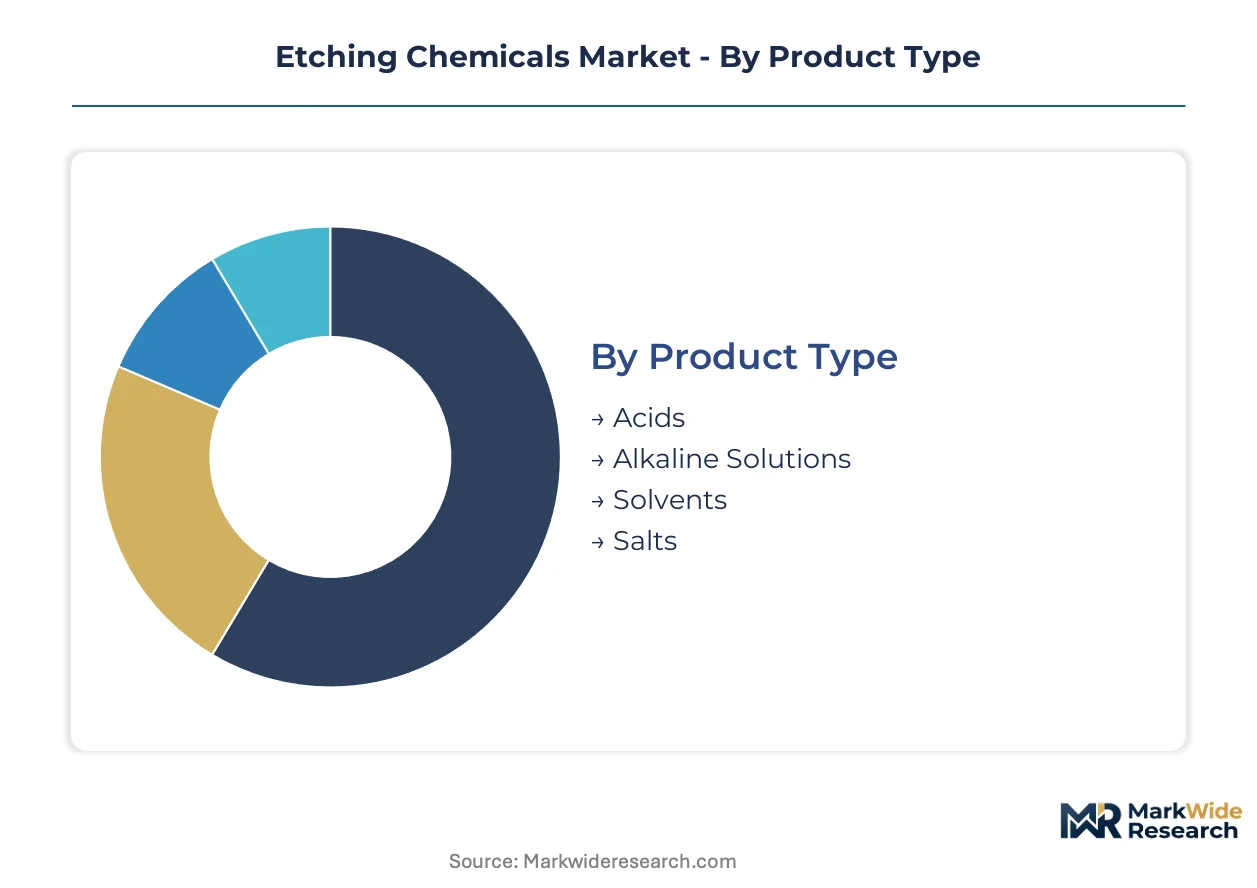
Etching chemicals segment along purity thresholds, chemical families, and process integration depth. Each dimension determines qualification barriers, pricing power, and supplier switching costs for semiconductor and industrial end-users.
Product Type:
Margin pools concentrate in fluoride-based acids where electronic-grade purification commands the steepest premiums over industrial formulations.
- Acids:Hydrofluoric, sulfuric, and phosphoric formulations dominate wet etching benches for silicon oxide and metal layer removal. Taiwan Semiconductor Manufacturing and Samsung Foundry consume captive volumes for sub-7nm gate-all-around transistor production, where metallic impurity thresholds sit below 0.1 parts per billion.
- Alkaline Solutions:Potassium hydroxide and tetramethylammonium hydroxide chemistries enable anisotropic etching of gallium nitride and silicon carbide crystal planes. Automotive inverter manufacturers in South Korea and Japan are scaling dedicated wet etching capacity for wide-bandgap power devices.
- Solvents:Organic formulations including N-methyl-2-pyrrolidone and dimethyl sulfoxide serve photoresist stripping and post-etch residue removal. These chemistries face substitution pressure from supercritical carbon dioxide alternatives in MEMS release applications.
- Salts:Ammonium fluoride and buffered oxide etch compounds provide controlled silicon dioxide removal rates. These formulations capture share in mature node fabs where equipment compatibility limits acid transition costs.
The dominant share belongs to Acids, while Alkaline Solutions is closing the gap fastest.
End Use Industry:
Application complexity determines formulation specification tiers, with semiconductor-adjacent sectors demanding the most intensive supplier qualification protocols.
- Electronics:Semiconductor fabrication, printed circuit board manufacturing, and display panel processing consume the highest-purity etchant volumes. Foundries in Hsinchu, Dresden, and Chandler run 24-hour wet etching operations with real-time chemical monitoring systems.
- Aerospace:Precision component cleaning and surface preparation for turbine blades utilize controlled etch rate chemistries. Boeing and Airbus supply chains specify Nadcap-accredited chemical processing for flight-critical aluminum and titanium alloys.
- Automotive:Power module substrates and sensor housings require alkaline etching for silicon carbide and glass passivation layers. Hyundai Motor Group and Toyota Motor Corporation have qualified dedicated etchant supply lines for inverter manufacturing.
- Healthcare:Medical device texturing and implant surface modification employ citric and nitric acid sequences. These applications face FDA 21 CFR Part 820 quality system documentation requirements that extend supplier onboarding timelines.
Electronics captures the largest volume allocation, though Automotive is expanding most quickly through electrification-driven power semiconductor demand.
Grade:
Purity certification tiers separate commodity chemical suppliers from electronic-grade specialists capable of angstrom-scale contamination control.
- Electronic Grade:Metallic impurity specifications below one part per billion enable sub-7nm node production. BASF SE and Stella Chemifa Corporation maintain dedicated purification trains and cleanroom packaging operations for wafer fab direct delivery.
- Reagent Grade:ACS-certified formulations serve analytical laboratories and pharmaceutical quality control with parts-per-million contamination limits. These chemistries trade at intermediate premiums between electronic and industrial tiers.
- Laboratory Grade:Research institutions and pilot-scale process development utilize these formulations where absolute purity is secondary to experimental flexibility. Universities in Singapore and Zurich purchase through consolidated chemical management contracts.
- Industrial Grade:Bulk metal finishing, printed circuit board etching, and decorative surface treatment consume high-volume, lower-specification acids. Chinese and Mexican fluorspar-derived hydrofluoric acid concentrates feed this segment through distributed blending networks.
Electronic Grade commands the steepest price premiums, while Industrial Grade retains the highest absolute tonnage through metal processing applications.
Application:
Process integration depth determines whether etchants function as standalone chemistries or as coordinated sequences within multi-step fabrication modules.
- Semiconductor Fabrication:Front-end-of-line transistor gate etching and back-end-of-line interconnect patterning consume the most stringent purity formulations. Intel, TSMC, and Samsung Foundry maintain proprietary metrology protocols that force suppliers to replicate identical certifications across incompatible customer test matrices.
- Photolithography:Post-exposure development and hard mask removal steps utilize buffered hydrofluoric acid and solvent blends. These applications are converging with real-time chemical monitoring systems that collapse traditional separations between etchant supply and process control functions.
- PVD:Physical vapor deposition chamber cleaning and target conditioning employ aggressive acid sequences for metal residue removal. These chemistries face EPA Clean Air Act restrictions on fluorinated greenhouse gas emissions that force foundry requalification cycles.
- CVD:Chemical vapor deposition reactor maintenance utilizes remote plasma cleaning chemistries and liquid-phase alternatives to nitrogen trifluoride. EU Green Deal taxonomy alignment unlocks preferential procurement scoring for low-global-warming-potential formulations in this category.
Semiconductor Fabrication holds the dominant position, while CVD is gaining share fastest through emissions-driven chemistry substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fluorspar concentrate exports from Mexico and China anchor precursor supply chains for hydrofluoric acid production. East Asian foundry clusters in Taiwan and South Korea consume the highest-purity etchant volumes for sub-7nm node manufacturing. Regulatory divergence across EPA, REACH, and MEE jurisdictions forces multi-jurisdictional operators into duplicative compliance expenditures.
United States
Intel's Arizona and Oregon facilities drive captive consumption of fluoride-based formulations for gate-all-around transistor production. EPA Clean Air Act amendments targeting fluorinated greenhouse gases force foundry requalification of etchant process emissions. The Chandler fabrication cluster operates 24-hour wet etching operations with real-time chemical monitoring systems.
Germany
Bosch Sensortec's Dresden manufacturing lines qualify supercritical carbon dioxide alternatives for MEMS release steps. ECHA REACH registration requirements mandate full toxicity dossiers on imported etchants, extending qualification backlogs to eighteen months for non-registered substances. The Saxony semiconductor cluster compresses wastewater treatment infrastructure through dry cleaning chemistry adoption.
Japan
Automotive inverter manufacturers scale wet etching capacity for silicon carbide power devices. METI reporting obligations on perfluorinated compound inventories apply to Yokkaichi memory manufacturers. Stella Chemifa Corporation anchors ultra-high-purity fluoride production for Asia-Pacific supply chains.
South Korea
SK Hynix centralizes global etchant sourcing decisions in Seoul headquarters. Hyundai Motor Group qualifies dedicated etchant supply lines for inverter manufacturing. The Busan-Ulsan cluster scales alkaline etchant formulations tailored to silicon carbide crystal planes.
China
MEE emission protocols create emerging restrictions on fluorinated compound releases from etching operations. Domestic fluorspar concentrate exports dominate precursor supply chains for regional acid blenders. Yangtze River Delta foundries face parallel compliance with EPA-inspired technical standards and indigenous regulatory frameworks.
Etching Chemicals Market Vendor Landscape
Concentration sits with diversified chemical conglomerates and electronic-grade specialists. The vendor base separates into three tiers: integrated multinational suppliers with precursor chemistry platforms, Asia-Pacific purity specialists with captive cleanroom packaging, and regional blenders serving industrial-grade applications. Strategic moves center on qualification cycle acceleration and geographic proximity to foundry clusters.
Among diversified chemical conglomerates, BASF SE and Solvay SA exemplify the integrated precursor chemistry archetype. Honeywell International Inc. occupies a position within the fluoropolymer-derived etchant tier. Stella Chemifa Corporation anchors the Asia-Pacific purity specialist segment with ultra-high-purity fluoride production capabilities.
| Leading Market Players |
|---|
| Merck KGaA |
| Kanto Chemical Co., Inc. |
| BASF SE |
| Solvay SA |
| Mitsubishi Chemical Group Corporation |
| Stella Chemifa Corporation |
| Honeywell International Inc. |
| Avantor Inc. |
| The Dow Chemical Company |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Mexican and Chinese fluorspar concentrate facilities shapes both input cost floors and regional blending margins, with electronic-grade purification investments establishing price premiums that industrial-grade suppliers cannot replicate. Foundry consolidation in Taiwan and South Korea concentrates procurement leverage, compressing margins for non-specialized blenders while rewarding purity specialists with long-term offtake security.
Pricing Analysis
REACH registration mandates dictate the pricing tier structure across European import channels, separating documented electronic-grade formulations from unregistered industrial alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects metallic impurity thresholds, with sub-0.1 ppb specifications commanding multiples over 1-ppb reagent grades. Cost compression in industrial-grade hydrofluoric acid is intensifying because Chinese fluorspar export quotas tighten precursor availability. Automotive inverter manufacturers exhibit highest price sensitivity due to volume scaling pressures, while sub-7nm foundries prioritize purity over unit cost.
Supply Chain Analysis
Port congestion at Busan and Kaohsiung container terminals elevates inbound logistics costs for European and North American etchant blenders serving East Asian foundry clusters. Mexican, Chinese, and Mongolian fluorspar concentrate exports anchor precursor supply chains for hydrofluoric acid production. Formulated chemistries draw from electronic-grade acids, alkaline solutions, and solvent blends. Single-source vulnerability concentrates in Stella Chemifa Corporation's ultra-high-purity fluoride train. Distribution runs through direct chemical management contracts consolidating procurement at parent-company headquarters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The etching chemicals market sits in a cyclical recovery phase as semiconductor capital expenditure rebounds from node-transition pauses, with sub-7nm gate-all-around transistor ramp-ups driving formulation demand.
For Market Incumbents: Fortify qualification-cycle advantages by embedding real-time chemical monitoring systems into customer wet benches, creating switching costs that emerging blenders cannot match. Deepen backward integration into fluorspar concentrate offtake agreements in Mexico and China to secure input cost stability against export quota volatility. Accelerate REACH dossier completion for next-generation low-global-warming-potential chemistries ahead of EU F-Gas phase-down deadlines. For New Entrants and Emerging Players: Anchor in India's Gujarat and Tamil Nadu electronic-grade chemical parks, where PLI scheme allocations for domestic fab construction create first-mover procurement relationships before incumbent qualification backlogs solidify. Target silicon carbide power device etching as the most penetrable segment, with automotive inverter manufacturers scaling dedicated alkaline formulation capacity. Pursue equipment-agnostic hybrid etching sequence partnerships with copper interconnect reflow specialists. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors Asia-Pacific purity specialists with captive cleanroom packaging and established foundry qualification slots. Five-to-ten-year viability hinges on substitution resilience against supercritical carbon dioxide dry cleaning alternatives in MEMS applications. Watch EPA Clean Air Act enforcement intensity on fluorinated greenhouse gas emissions as the inflection indicator for liquid-phase chemistry requalification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar Concentrate | Mexican and Chinese export quotas threaten input cost stability for North American blenders. |
| Green Chemistry Certification Program | EU Green Deal taxonomy alignment unlocks preferential procurement scoring for low-global-warming-potential formulations. |
| Long-term Supply Agreement with Foundry | SK Hynix and Micron Technology centralized sourcing decisions reward qualified suppliers with volume commitments. |
| Capacity Expansion in Electronic-Grade Chemical Park | Gujarat and Tamil Nadu state governments fast-track environmental clearances for domestic fab construction. |
| Joint Venture for Real-Time Monitoring Integration | Process equipment convergence collapses traditional separations between etchant supply and process control functions. |
Methodological Framework
A spread of perspectives from wet bench process engineers, foundry procurement directors, fluorspar concentrate traders, chemical distribution channel partners, and ECHA regulatory affairs consultants converged on the working assumptions. Primary interview insights combined with secondary validation from customs trade data, SEC 10-K chemical segment disclosures, ACC and Cefic specialty chemical reports, and EPA Clean Air Act enforcement records. Bottom-up etchant volume estimates by grade tier and end-use industry triangulated against top-down semiconductor capital expenditure forecasts.
Segmentation dimensions modeled include purity certification grade, chemical family, end-use industry vertical, process integration depth, and regional production hub concentration across the analysis window. CAGRs derived from weighted average of historical demand elasticity, node-transition timing, and regulatory phase-in schedules. Forecast inputs incorporated foundry capacity buildout announcements, PFAS restriction legislative tracking, and wide-bandgap substrate adoption curves in automotive power electronics.
Decision-makers should treat outputs as directional under assumptions of continued East Asian foundry cluster dominance and REACH registration timeline adherence; material deviation in fluorspar export policy or EPA enforcement intensity would warrant model refresh. Practitioners should keep alternative scenarios live as MEE emission protocol stringency and supercritical carbon dioxide displacement rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global E Series Glycol Ether Market
Chemicals
Italy Laboratory Chemicals Market
Chemicals
Aluminum Ammonium Sulfate Market
Chemicals
Paint Remover Market
Chemicals
Carcinogenic Chemical Alternatives Market
Chemicals
Chemical Distribution Market
Chemicals
Azodicarbonamide (ADC) Market
Chemicals
Global Oxo Alcohols Market
Chemicals
China Inorganic Iodide Market
Chemicals
Copper Oxychloride Market
Chemicals
Hydrazine Hydrate Market
Chemicals
Methanol to Gasoline Market
Chemicals
Superplasticizer Market
Chemicals
Global Syringaldehyde Market
Chemicals
Coal Tar Market
Chemicals
Negative Photoresist Chemicals Market