
 Global Chemotherapy Devices Market | 2026-2036
Global Chemotherapy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chemotherapy Devices Market Foresight
Hospital procurement channels for chemotherapy devices is reconfiguring around value-based contracting and bundled care agreements. ICU Medical leverages its closed-system transfer device portfolio to anchor relationships with integrated delivery networks. Becton, Dickinson and Company sustains manufacturing scale across multiple pump platforms while competing on safety-engineered features. Baxter International differentiates through global service infrastructure that supports long-term equipment leases.
Chemotherapy devices encompass infusion pumps, implantable ports, syringe pumps, wearable delivery systems, and nebulizers engineered for precise cytotoxic drug administration with flow accuracy typically measured in milliliters per hour and biocompatibility requirements for repeated exposure to alkylating agents and antimetabolites. These systems serve primarily to enable controlled parenteral delivery of oncologic pharmaceuticals while minimizing occupational exposure and dosing errors. Infusion pumps occupy the largest installed base due to their versatility across solid tumor and hematologic malignancy protocols, while wearable devices represent the fastest-expanding category as ambulatory surgical centers and home healthcare settings adopt continuous subcutaneous delivery for regimens requiring extended infusion durations. Multi-channel delivery technology commands premium positioning where complex combination chemotherapy requires simultaneous administration of vesicants and protective agents.
The FDA regulates chemotherapy devices as Class II medical devices under 21 CFR requirements with escalating emphasis on closed-system transfer device compliance to prevent hazardous drug exposure. EMA's MDR framework and REACH substance restrictions shape material selection and biocompatibility testing protocols for European market access. ISO 80601-2-24 standards for infusion pump accuracy and IEC 62304 software lifecycle requirements create baseline compliance thresholds that filter smaller competitors from institutional procurement lists. Stakeholders must monitor evolving reimbursement pathways for home-based chemotherapy administration as these will determine capital allocation between clinic-installed and patient-worn delivery platforms.
Market Dynamics
The chemotherapy devices market is reconfiguring around FDA's escalating closed-system transfer device mandates, which are compressing vendor qualification timelines while elevating biocompatibility testing burdens for alkylating agent exposure protocols.
Growth Catalysts
- Wearable infusion systems:Ambulatory surgical centers in Germany are deploying continuous subcutaneous delivery platforms for extended-duration regimens, compressing hospital bed utilization and enabling same-day discharge protocols.
- REACH substance restrictions:ECHA's evolving material safety frameworks are accelerating replacement of legacy pump housings with medical-grade polymers certified for repeated cytotoxic exposure cycles.
- Home healthcare infrastructure:Japan's reimbursement pathways for patient-worn delivery devices are expanding addressable volume beyond clinic-installed systems into residential settings.
Market Restraints
- ISO 80601-2-24 compliance costs:Milliliter-per-hour accuracy validation requirements demand capital-intensive metrology equipment that filters smaller manufacturers from institutional procurement lists.
- Specialty polymer supply concentration:Medical-grade thermoplastic elastomers for pump tubing face sourcing bottlenecks concentrated among German and US chemical compounders.
- IEC 62304 software lifecycle burdens:Embedded control system documentation requirements extend product development timelines by 14-18 months for programmable infusion platforms.
Strategic Opportunities
- Underpenetrated Indian oncology infrastructure:CDSCO's streamlined Class II medical device registration pathways are opening procurement channels for closed-system transfer devices in tier-2 hospital networks.
- Multi-channel delivery convergence:Simultaneous administration of vesicants and protective agents through integrated pump architectures commands premium positioning in combination chemotherapy protocols.
- Service unbundling models:Long-term equipment leases with predictive maintenance telemetry are displacing outright capital purchases among United States integrated delivery networks.
Industry Challenges
- Biocompatibility testing capacity:Repeated alkylating agent exposure validation requires specialized toxicology laboratory partnerships that face 9-12 month queue times.
- Legacy pump integration friction:Software architecture from pre-MDR devices lacks interoperability with modern closed-system transfer device monitoring networks, forcing parallel infrastructure investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chemotherapy Devices Market |
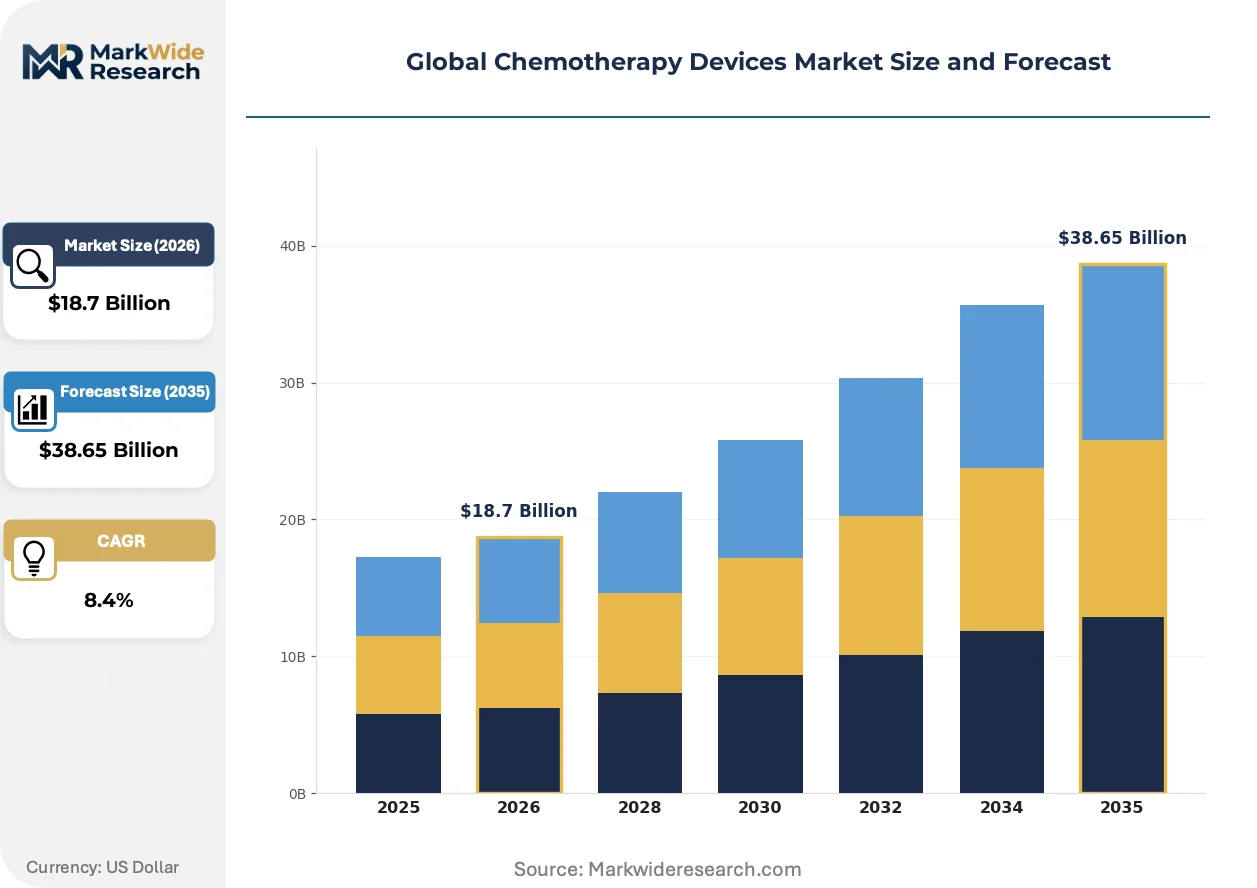
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infusion Pumps, Implantable Port Systems, Syringe Pumps, Wearable Devices, Nebulizers Technology: Flow Rate Control, Multi-Channel Delivery, Safety Locks, Wireless Connectivity, Dose Monitoring Application: Solid Tumors, Hematologic Malignancies, Pediatric Oncology, Geriatric Oncology, Rare Cancers End User: Oncology Clinics, Research Institutes, Dialysis Centers, Ambulatory Surgical Centers, Home Healthcare |
| Companies Covered | ICU Medical, Baxter International, Becton, Dickinson and Company, B. Braun SE, Halyard Health, Moog Inc., Terumo Corporation, Smiths Medical, Zyno Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chemotherapy Devices Market Shifts & Advancements
Device architectures are fragmenting between high-precision clinic-installed systems and patient-worn platforms, with regulatory pressure on hazardous drug exposure protocols accelerating material and software obsolescence cycles simultaneously.
Closed-system transfer device technology is migrating from passive mechanical barriers toward active pressure-balanced designs with integrated filtration membranes. Oncology clinics in the United States are adopting these platforms at replacement-cycle pace of 36-48 months. The shift is compressing market share for legacy open-system components while elevating service revenue attachment rates for sealed-device maintenance protocols.
EMA's Medical Device Regulation framework is tightening post-market surveillance requirements for infusion pump software updates. Manufacturers must now submit cybersecurity validation documentation for each firmware revision, extending patch deployment timelines. European hospital procurement committees are responding by consolidating vendor lists around suppliers with dedicated regulatory affairs teams in Brussels.
Hospital buying committees are unbundling after-sales service from equipment capital costs, negotiating standalone multi-year maintenance agreements with performance uptime guarantees. United States integrated delivery networks are leading this shift, with Germany's university hospital systems following 18-24 months behind. The model is compressing upfront capital outlays while locking in predictable recurring revenue streams for device manufacturers with field service density in target metros.
Global Chemotherapy Devices Market Segmentation
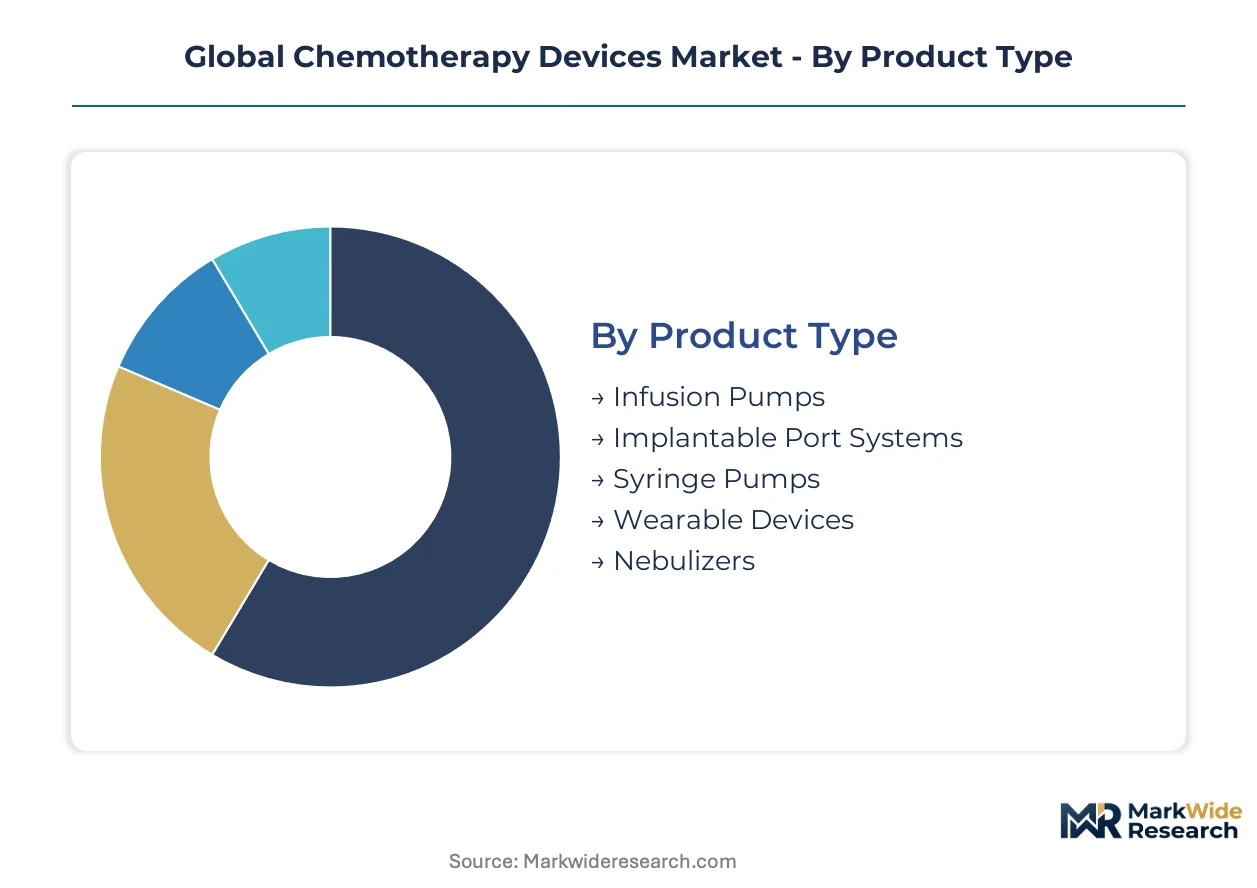
Chemotherapy device segmentation reveals divergent service economics across product architectures. After-sales revenue attachment rates vary dramatically between capital-intensive clinic-installed systems and patient-worn platforms requiring remote monitoring infrastructure.
Product Type:
After-sales-service intensity peaks with programmable infusion platforms demanding continuous calibration and preventive maintenance protocols.
- Infusion Pumps:These programmable electromechanical systems deliver cytotoxic agents at milliliter-per-hour precision through peristaltic or syringe-driven mechanisms. Demand concentrates in United States academic medical centers where multi-channel configurations support complex combination regimens. Service contracts typically extend across 60-72 month lifecycles with quarterly preventive maintenance intervals.
- Wearable Devices:Patient-worn subcutaneous delivery platforms incorporate MEMS flow sensors and Bluetooth telemetry for remote dose verification. Germany's ambulatory surgical centers are deploying these systems for extended-duration 5-FU regimens, compressing hospital bed utilization while shifting service responsibility to home healthcare networks.
- Implantable Port Systems:Titanium or plastic reservoir devices with silicone septa enable repeated venous access for vesicant administration.
- Syringe Pumps:Compact piston-driven units target low-volume precision delivery in pediatric and neonatal oncology settings.
- Nebulizers:Aerosolization systems for intratumoral or intrapleural chemotherapy delivery occupy niche application profiles.
By volume, infusion pumps lead. By growth pace, wearable devices are expanding most quickly.
Technology:
Technology segmentation tracks capital allocation between hardware precision engineering and software-dependent connectivity layers.
- Flow Rate Control:Pressure-feedback algorithms with real-time occlusion detection maintain delivery accuracy within 5% variance across viscosity ranges. Japan's PMDA has tightened validation requirements for alkylating agent exposure protocols, extending certification timelines for new pump architectures.
- Multi-Channel Delivery:Synchronized independent pumping channels enable simultaneous administration of vesicants, hydration, and protective agents. United States comprehensive cancer centers command these configurations for dose-dense chemotherapy protocols, with procurement committees prioritizing interoperability with electronic health record systems.
- Safety Locks:Mechanical and electronic barriers preventing unauthorized flow rate modifications or drug library overrides.
- Wireless Connectivity:Cellular and Wi-Fi telemetry enabling remote dose verification and pump status monitoring.
- Dose Monitoring:Integrated load cell gravimetric verification comparing programmed versus delivered volumes.
By installed base, flow rate control dominates. By replacement-cycle velocity, wireless connectivity is gaining share fastest.
Application:
Application segmentation aligns device specifications with protocol intensity and patient population acuity.
- Solid Tumors:Extended infusion durations for colorectal, breast, and lung malignancies drive demand for ambulatory-compatible delivery platforms. Germany's statutory health insurance funds have expanded reimbursement for home-based 5-FU administration, accelerating wearable device penetration.
- Hematologic Malignancies:High-dose chemotherapy with stem cell rescue requires multi-channel precision for conditioning regimens. United States bone marrow transplant centers specify pump platforms with validated biocompatibility for busulfan and melphalan exposure cycles.
- Pediatric Oncology:Weight-based dosing algorithms and micro-volume delivery capabilities define specialized device requirements.
- Geriatric Oncology:Simplified user interfaces and enhanced safety interlocks address polypharmacy and cognitive load considerations.
- Rare Cancers:Ultra-low volume production runs and protocol-specific drug library configurations.
By procedure volume, solid tumors lead. By device specialization premium, hematologic malignancies command the steepest expansion trajectory.
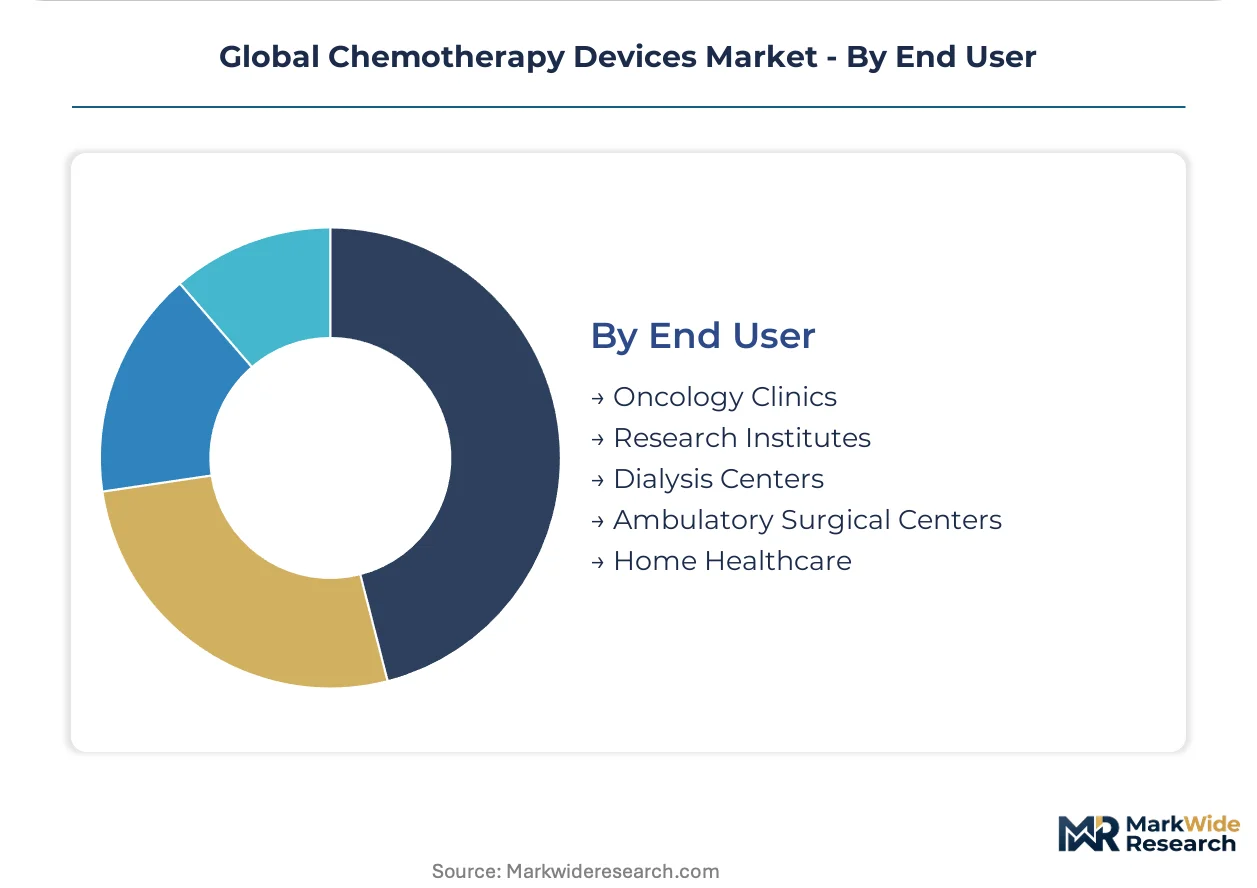
End User:
End-user segmentation captures divergent procurement authority and capital allocation cycles across care settings.
- Oncology Clinics:Dedicated cancer treatment facilities with concentrated infusion chair capacity and specialized pharmacy compounding infrastructure. Japan's hospital procurement consortia negotiate multi-year equipment leases with bundled service agreements, compressing upfront capital requirements while locking in predictable maintenance revenue.
- Ambulatory Surgical Centers:Same-day discharge protocols in Germany and the United States are driving adoption of wearable delivery platforms with remote monitoring capabilities, displacing traditional hospital admission models for extended chemotherapy regimens.
- Home Healthcare:Patient-worn devices with telehealth integration for residential administration.
- Research Institutes:Investigational device exemption platforms for early-phase clinical trials.
- Dialysis Centers:Repurposed infusion infrastructure for concurrent chemotherapy and renal support.
By equipment value, oncology clinics lead. By addressable market expansion, ambulatory surgical centers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where hospital procurement budgets for oncology infrastructure remain elevated, while Japanese reimbursement pathways compress margins on patient-worn delivery platforms.
United States
Academic medical centers in Boston and Houston drive demand for multi-channel infusion configurations supporting dose-dense chemotherapy protocols. FDA's escalating closed-system transfer device mandates are compressing vendor qualification timelines for new market entrants. Integrated delivery networks in Texas and California negotiate multi-year equipment leases with bundled service agreements.
Germany
Ambulatory surgical centers in Bavaria and North Rhine-Westphalia deploy wearable subcutaneous delivery platforms for extended 5-FU regimens. EMA's MDR framework tightens post-market surveillance requirements for infusion pump software updates. University hospital systems in Heidelberg and Munich consolidate vendor lists around suppliers with dedicated regulatory affairs teams.
Japan
PMDA has tightened validation requirements for alkylating agent exposure protocols, extending certification timelines for new pump architectures. METI's reimbursement pathways for patient-worn delivery devices expand addressable volume beyond clinic-installed systems. Hospital procurement consortia in Tokyo and Osaka negotiate equipment leases with predictive maintenance telemetry.
India
CDSCO's streamlined Class II medical device registration pathways open procurement channels for closed-system transfer devices in tier-2 hospital networks. Maharashtra and Karnataka oncology clinics expand adoption of wearable infusion systems for cost-containment. Mumbai and Bangalore medical device distributors anchor relationships with integrated delivery networks seeking ambulatory-compatible platforms.
United Kingdom
NHS England's cancer strategy drives consolidation of chemotherapy delivery infrastructure around closed-system transfer device compliance. MHRA alignment with EMA post-market surveillance requirements filters smaller manufacturers from institutional procurement lists. London and Manchester comprehensive cancer centers specify pump platforms with validated biocompatibility for repeated cytotoxic exposure cycles.
Global Chemotherapy Devices Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying medical-grade polymers and MEMS flow sensors. The vendor base fragments across three tiers: multinational conglomerates with dedicated oncology divisions, mid-cap device specialists with regional service density, and emerging entrants targeting price-sensitive ambulatory segments. Dominant competitive moves include long-term equipment lease arrangements with predictive maintenance telemetry and backward integration into specialty polymer compounding for pump tubing.
Among diversified healthcare conglomerates, ICU Medical, Baxter International, and Becton, Dickinson and Company exemplify platform integrators anchoring relationships with integrated delivery networks through closed-system transfer device portfolios and global service infrastructure. These entities occupy positions where manufacturing scale across multiple pump platforms intersects with safety-engineered feature differentiation, representing the consolidated tier that filters smaller competitors from institutional procurement lists.
| Leading Market Players |
|---|
| ICU Medical |
| Baxter International |
| Becton, Dickinson and Company |
| B. Braun SE |
| Halyard Health |
| Moog Inc. |
| Terumo Corporation |
| Smiths Medical |
| Zyno Medical |
| Others |
Supply & Pricing Matrix
The Rotterdam-Frankfurt pharmaceutical freight corridor carries medical-grade polymer shipments from German compounders to device assembly plants, with container rates fluctuating in tandem with REACH compliance certification costs. This logistics artery funnels specialty thermoplastic elastomers toward pump tubing manufacturers while downstream price differentiation widens between FDA-validated closed-system transfer devices and standard infusion platforms.
Pricing Analysis
The customization-premium spread between configured-to-order multi-channel infusion systems and standard single-channel pumps now exceeds three-to-one in United States academic medical centers. Pricing stratifies across premium, standard, and economy tiers based on ISO 80601-2-24 certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying because German ambulatory surgical centers are consolidating procurement around lease-based models. Pediatric oncology clinics demonstrate the highest price sensitivity due to constrained reimbursement for micro-volume delivery platforms.
Supply Chain Analysis
Contract manufacturing for MEMS flow sensors concentrates among Taiwanese foundries and German precision engineering houses, with final device assembly anchored in United States, Ireland, and Malaysia facilities. Raw material dependencies center on medical-grade polycarbonate resins, platinum-cured silicone tubing, and rare-earth magnet assemblies for peristaltic pump mechanisms. Single-source vulnerability in specialty polymer compounding creates exposure to ECHA substance restriction updates. Distribution runs through integrated delivery network procurement consortia and regional medical device distributors with GPO contract access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chemotherapy devices market sits in early-cycle expansion as wearable infusion platforms penetrate home healthcare settings beyond traditional clinic-installed systems. Japan's reimbursement pathway expansion for patient-worn delivery devices signals sustained penetration tailwinds.
For Market Incumbents: Build regulatory affairs moats by embedding dedicated Brussels and Tokyo compliance teams to compress EMA MDR and PMDA certification timelines. Deepen backward integration into medical-grade polymer compounding to secure captive supply of REACH-compliant pump housings against German chemical compounder bottlenecks. Anchor hospital procurement relationships through predictive maintenance telemetry bundled into long-term equipment leases. For New Entrants and Emerging Players: Pursue tier-2 hospital networks in Maharashtra and Karnataka where CDSCO's streamlined Class II registration creates procurement access without legacy vendor lock-in. Target ambulatory surgical centers in Germany seeking cost-containment through same-day discharge protocols for extended 5-FU regimens. Lead with wireless connectivity-enabled wearable platforms that shift service responsibility to home healthcare networks. For Investors and Strategic Acquirers: Regional device specialists with dedicated regulatory affairs infrastructure in Brussels and Tokyo represent the most defensible acquisition archetype for medium-term consolidation. These mid-cap players command premium positioning in European and Japanese procurement committees that filter smaller competitors. Monitor FDA closed-system transfer device guidance updates as the inflection signal for accelerated replacement cycles and vendor list consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR compliance accelerates European hospital procurement access for sealed-device platforms. |
| Hospital System Partnership | Integrated delivery network leases with predictive telemetry lock in recurring revenue streams. |
| Software Companion Development | Bluetooth-enabled dose verification expands wearable device reimbursement in Japanese home healthcare. |
| Backward Integration | In-house medical-grade polymer compounding secures supply against REACH substance restriction volatility. |
| Reimbursement Strategy | Home-based chemotherapy administration pathways determine capital allocation between clinic and patient-worn platforms. |
Research Methodology
A spread of perspectives from hospital procurement managers, biomedical engineers, GPO contracts specialists, and regulatory affairs directors converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EMA MDR submissions, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Demand-supply-balance framing anchored the quantitative framework, with installed base estimates for infusion pumps, wearable devices, and implantable ports cross-referenced against replacement-cycle velocity and ambulatory surgical center expansion rates. Segmentation dimensions spanned product architecture, technology layer, application intensity, and end-user procurement authority. CAGRs were derived from regression analysis of historical adoption curves calibrated to regulatory inflection points and reimbursement pathway expansions.
Sensitivities concentrate around FDA closed-system transfer device mandate timing, ECHA REACH substance restriction scope expansion, and Japanese METI reimbursement rate revisions for patient-worn platforms. Forecasts reflect documented assumptions regarding ambulatory surgical center penetration and home healthcare infrastructure buildout. Quarterly review of FDA guidance dockets, EMA MDR submission queues, and Japanese reimbursement fee schedule updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Sharps Destruction Device Market
Medical Devices
Gracey Curette Market
Medical Devices
Oxygen Conserving Devices Market
Medical Devices
Ultrasonic Diathermy Market
Medical Devices
Capsular Tension Rings Market
Medical Devices
Medical Device Trays Market
Medical Devices
Interspinous Process Decompression Devices Market
Medical Devices
Transcutaneous Electrical Nerve Stimulation Market
Medical Devices
Hip Kits Market
Medical Devices
Active Implantable Devices Market
Medical Devices
Venous Procedure Devices Market
Medical Devices
Thoracolumbar Stabilization Devices Market
Medical Devices
Portable Ultrasound Devices Market
Medical Devices
Electrosurgery Accessories Market
Medical Devices
Large Volume Nebulizers Market
Medical Devices
Active Humidifier Devices Market