
 2-Octyl Cyanoacrylate Adhesives Market | 2026-2036
2-Octyl Cyanoacrylate Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
2-Octyl Cyanoacrylate Adhesives Market Outlook
High-purity monomer synthesis is tilting toward solvent-free manufacturing pathways that reduce residual formaldehyde in finished 2-octyl cyanoacrylate formulations. Ethicon leverages its vertically integrated ethyl-cyanoacrylate platform to extend quality systems into octyl-grade production. 3M anchors its position through proprietary stabilizer packages that extend shelf life under variable storage conditions. Chemence Medical specializes in custom viscosity grades for laparoscopic applicators, differentiating its catalog from standard topical skin adhesive formats.
2-Octyl cyanoacrylate is a longer-chain alkyl ester derivative of cyanoacrylate monomer, polymerizing on contact with tissue moisture to form a flexible, microbial-resistant bond with tensile strength typically exceeding 500 psi; it serves primarily as a topical skin adhesive for wound closure and as a hemostatic sealant in surgical settings. Medical adhesives dominate current value generation due to premium pricing tied to biocompatibility certification and sterilization validation requirements. Surgical procedures represent the fastest-growing application dimension as ambulatory surgical centers expand their use of tissue adhesives for incision closure in place of sutures or staples. Hospitals command the largest end-user share, though manufacturing industries are emerging as a secondary demand node for industrial-grade octyl cyanoacrylate in electronics potting and temporary fixturing.
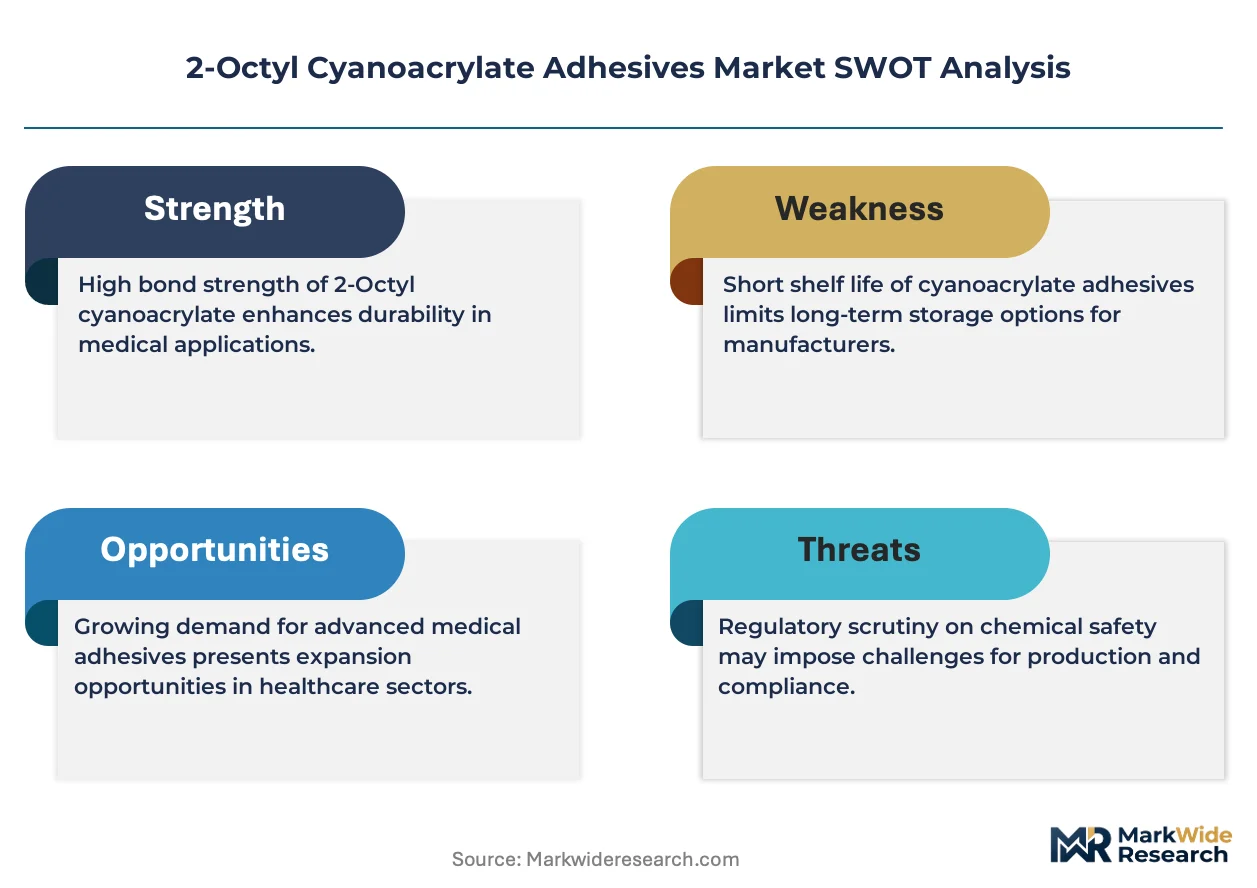
FDA 510(k) premarket notification requirements govern medical-grade formulations in the United States, while the EU Medical Device Regulation mandates notified body involvement for cyanoacrylate-based wound closure products sold in Europe. ISO 10993 biocompatibility testing series shapes the evidentiary baseline that manufacturers must satisfy before commercializing skin-contact adhesives across jurisdictions. Stakeholders should monitor evolving FDA guidance on cyanoacrylate degradation byproducts, as future toxicological thresholds could force reformulation investments or narrow the acceptable monomer purity window for Class II device classification.
Market Dynamics
FDA 510(k) clearance pathways are compressing product development cycles while simultaneously elevating biocompatibility validation costs, forcing manufacturers to consolidate quality systems around solvent-free monomer synthesis platforms.
Growth Catalysts
- Ambulatory Surgical Center Expansion:United States outpatient facilities are replacing sutures with tissue adhesives for incision closure, accelerating volume uptake in minimally invasive procedures.
- ISO 10993-5 Cytotoxicity Testing Harmonization:Standardized biocompatibility protocols reduce redundant validation costs across EU and US jurisdictions, streamlining multi-market entry.
- Solvent-Free Manufacturing Scale-Up:Germany's chemical processing sector is deploying continuous flow reactors that eliminate residual formaldehyde in octyl-grade monomer production.
Market Restraints
- Specialized Monomer Feedstock Concentration:Pharmaceutical-grade cyanoacrylate precursors rely on a limited supplier base in China's Shandong province, exposing formulations to input volatility.
- Degradation Byproduct Toxicology Thresholds:Evolving FDA guidance on formaldehyde release from polymerized films may narrow acceptable purity windows for Class II device classification.
- Butyl-2-Cyanoacrylate Substitution in Cost-Sensitive Settings:Shorter-chain analogues with lower tensile strength capture price-sensitive applications in veterinary and industrial bonding.
Strategic Opportunities
- Japan's Aging Surgical Population:METI reimbursement incentives for rapid wound closure technologies are opening hospital procurement channels for premium octyl formulations.
- Laparoscopic Applicator Customization:Viscosity-graded adhesives matched to robotic surgical platforms address unmet needs in minimally invasive internal sealing.
- EU MDR Notified Body Fast-Track Pathways:Streamlined conformity assessment for cyanoacrylate-based wound closure products reduces time-to-market for innovative sterilization methods.
Industry Challenges
- Polymer Chemistry Specialization Gap:Formulation scientists with expertise in anionic polymerization kinetics remain scarce relative to demand from medical adhesive developers.
- Shelf-Life Validation Infrastructure:Accelerated aging studies for stabilizer packages require capital-intensive climate chamber investments that strain mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2-Octyl Cyanoacrylate Adhesives Market |
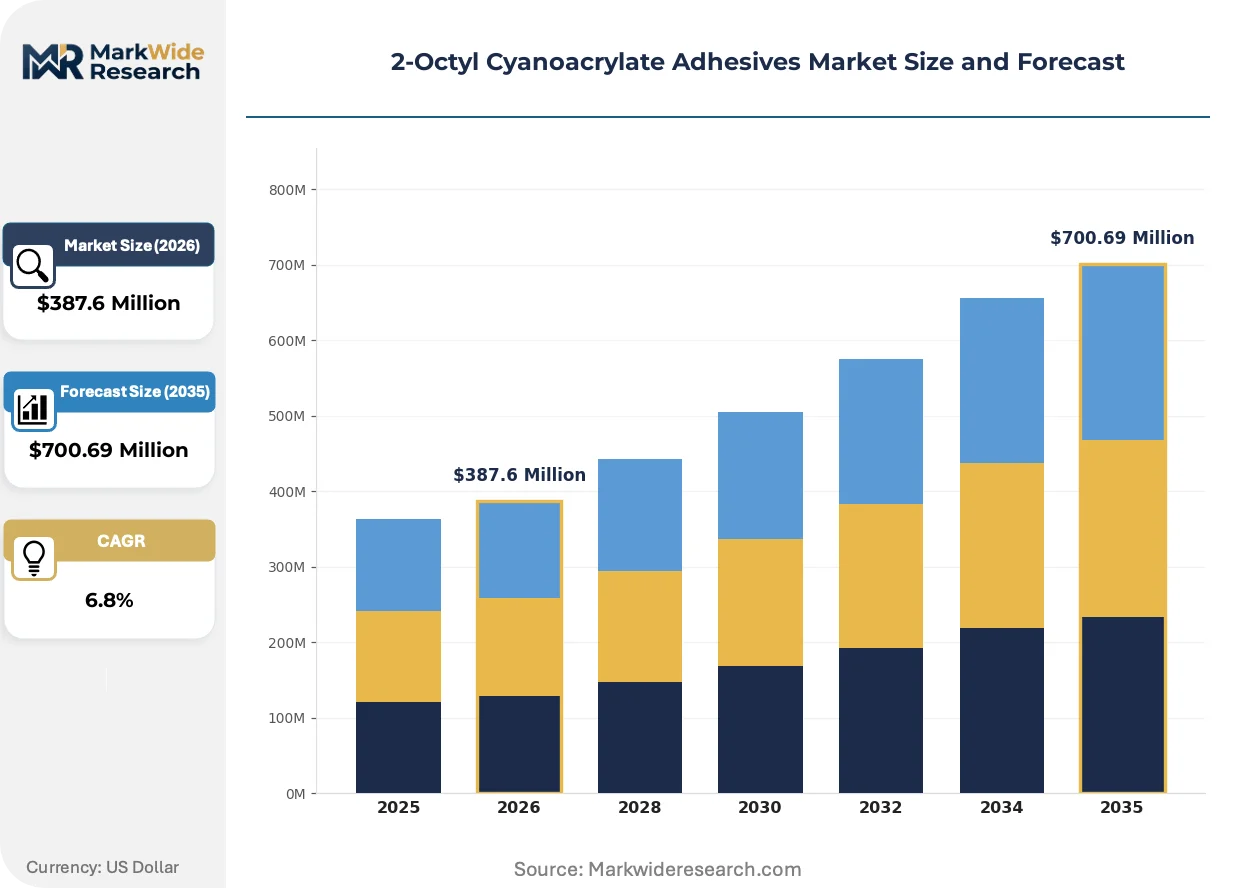
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Adhesives, Industrial Adhesives, Consumer Adhesives, Specialty Adhesives Application: Surgical Procedures, Automotive Repair, Packaging, Electronics End User: Hospitals, Manufacturing Industries, DIY Consumers, Research Laboratories Distribution Channel: Online Retail, Distributors, Direct Sales, Wholesale |
| Companies Covered | Ethicon, 3M, Medline Industries, Chemence Medical, Adhezion Biomedical, B. Braun Melsungen AG, GluStitch, Meyer-Haake, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2-Octyl Cyanoacrylate Adhesives Market Strategic Shifts
Formulation science is pivoting toward reactive compatibility with moist tissue environments while regulatory science tightens evidentiary requirements for degradation kinetics. These shifts are compressing traditional development timelines and reshaping competitive positioning around validation capabilities.
Photoinitiator-integrated octyl cyanoacrylate systems are enabling controlled polymerization rates in high-moisture surgical fields. Academic medical centers in Germany and Japan are piloting these formulations for cardiac and neurological procedures where exothermic reactions must be minimized. Conventional moisture-activated curing is rendering obsolete for applications requiring sub-millimeter precision in tissue approximation.
EU MDR Article 10 technical documentation requirements now mandate clinical performance data for cyanoacrylate wound closure products previously grandfathered under the Medical Device Directive. Notified bodies in Germany and the Netherlands are enforcing stricter scrutiny of degradation byproduct profiles. Manufacturers are responding by commissioning ISO 10993-18 chemical characterization studies earlier in development cycles to preempt regulatory holds.
Hospital procurement committees are consolidating adhesive purchasing through centralized formulary committees rather than individual surgeon preference cards. United States health systems are replacing brand-agnostic tenders with sole-source agreements tied to comprehensive wound closure portfolios. This concentration is most visible in integrated delivery networks across Texas and California, where standardization incentives override individual clinician preferences.
2-Octyl Cyanoacrylate Adhesives Market Segmentation
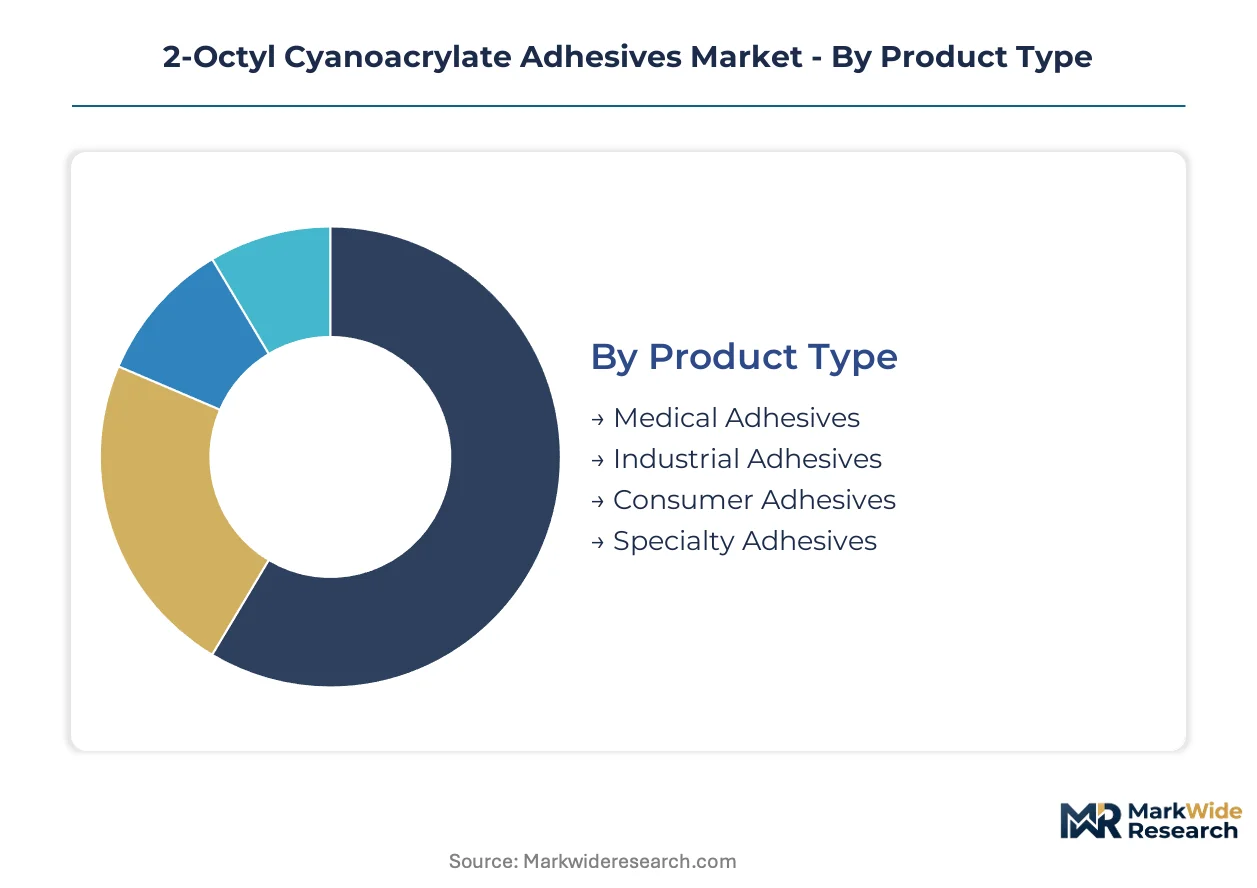
Segmentation in 2-octyl cyanoacrylate adhesives reveals distinct service intensity profiles across product tiers. Medical-grade formulations demand intensive technical support for FDA 510(k) navigation and sterilization validation, while industrial segments prioritize volume logistics over after-sales engagement.
Product Type:
After-sales-service intensity varies sharply across product tiers, with medical adhesives requiring regulatory compliance support and industrial grades emphasizing bulk supply reliability.
- Medical Adhesives:These formulations incorporate pharmaceutical-grade monomers with residual formaldehyde levels below regulatory thresholds and undergo ISO 10993 biocompatibility validation. Demand concentrates in United States hospital systems replacing sutures with tissue adhesives for incision closure, driven by ambulatory surgical center expansion and Medicare reimbursement alignment for rapid wound closure.
- Industrial Adhesives:Electronics potting and temporary fixturing applications utilize lower-purity monomer grades with relaxed biocompatibility requirements. Germany's automotive component manufacturers represent the primary demand node, where supply chain integration with chemical processors reduces lead time volatility for high-volume assembly operations.
- Consumer Adhesives:Retail skin closure products for minor wound management carry minimal service overhead beyond packaging compliance.
- Specialty Adhesives:Custom viscosity grades for laparoscopic applicators serve robotic surgical platform OEMs with formulation co-development requirements.
Medical Adhesives holds the largest share; momentum sits with Specialty Adhesives.
Application:
Cost tier stratification separates premium surgical applications from price-sensitive industrial bonding, with reimbursement dynamics governing medical demand and commodity resin cycles shaping industrial uptake.
- Surgical Procedures:Incision closure and internal tissue sealing command premium pricing tied to Class II device classification and sterilization validation. United States ambulatory surgical centers are displacing sutures and staples in minimally invasive procedures, supported by hospital procurement committee standardization across integrated delivery networks in Texas and California.
- Automotive Repair:Cosmetic panel bonding and trim attachment utilize industrial-grade octyl cyanoacrylate for its flexibility and weather resistance. German OEM supplier parks near Stuttgart and Wolfsburg anchor regional demand, with just-in-time delivery requirements favoring localized chemical processing capabilities.
- Packaging:High-speed carton sealing and label attachment represent volume-driven, price-sensitive applications with minimal technical differentiation.
- Electronics:Temporary component fixturing and conformal coating applications prioritize rapid cure speed and low outgassing characteristics.
Surgical Procedures commands the premium tier; Electronics climbs the fastest on miniaturization trends.
End User:
Customer type determines procurement modality, with hospitals consolidating through formulary committees while manufacturing industries negotiate direct supply agreements.
- Hospitals:Centralized purchasing committees in United States integrated delivery networks are consolidating adhesive procurement around comprehensive wound closure portfolios, displacing individual surgeon preference cards. Sole-source agreements with tiered pricing structures now dominate in Texas and California health systems.
- Manufacturing Industries:Electronics and automotive producers negotiate direct supply contracts with chemical processors, prioritizing volume pricing and technical co-development for application-specific formulations.
- DIY Consumers:Retail pharmacy and home improvement channels serve minor wound closure and household repair applications with minimal technical support requirements.
- Research Laboratories:Academic medical centers in Germany and Japan pilot photoinitiator-integrated formulations for cardiac and neurological procedures, requiring custom synthesis capabilities and regulatory pre-submission consultation.
Hospitals holds the largest share; Research Laboratories gains share fastest on experimental formulation demand.
Distribution Channel:
Supply concentration in chemical processing clusters dictates channel efficiency, with direct sales favored for high-volume industrial accounts and distributor networks serving fragmented medical procurement.
- Online Retail:Consumer-grade skin closure products and small-volume industrial adhesives move through pharmacy and marketplace platforms with standardized logistics.
- Distributors:Medical supply distributors maintain cold-chain infrastructure and regulatory documentation for hospital formulary compliance across United States health systems.
- Direct Sales:High-volume automotive and electronics manufacturers in Germany negotiate direct contracts with Shandong province monomer suppliers, bypassing intermediary margins.
- Wholesale:Industrial chemical wholesalers aggregate demand from mid-tier manufacturing facilities with irregular purchase patterns.
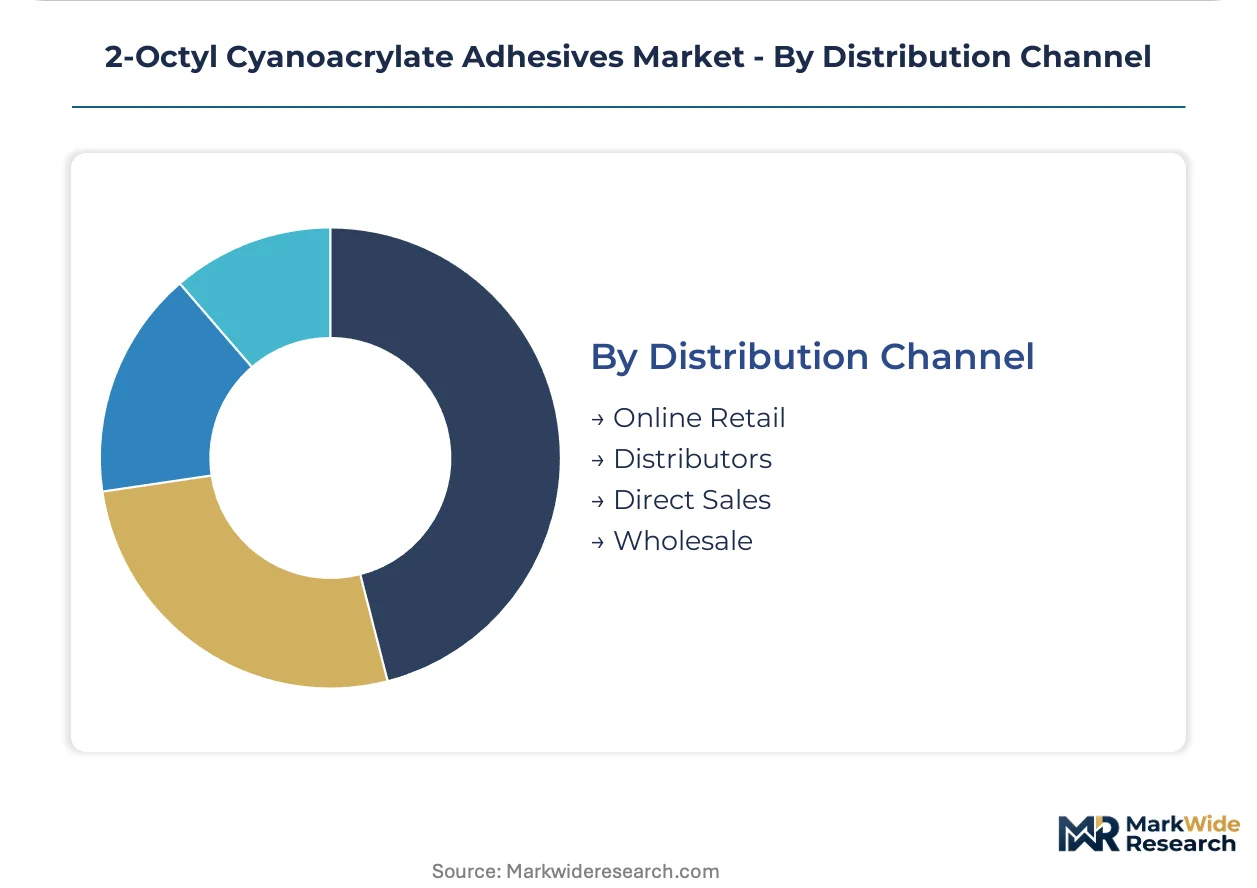
Direct Sales holds the largest share; Online Retail shows steepest expansion trajectory on consumer segment growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States, Germany, and Japan concentrate demand for medical-grade formulations, while industrial applications cluster near chemical processing hubs in Shandong province and the Rhine-Ruhr region.
United States
Ambulatory surgical centers in Texas and California displace sutures with tissue adhesives for incision closure. FDA 510(k) premarket notification requirements govern medical-grade formulations, compressing product development cycles while elevating validation costs. Integrated delivery networks in Houston and Los Angeles consolidate purchasing through centralized formulary committees.
Germany
Automotive OEM supplier parks near Stuttgart and Wolfsburg anchor industrial-grade demand for electronics potting and temporary fixturing. EU Medical Device Regulation mandates notified body involvement for cyanoacrylate-based wound closure products, with German notified bodies enforcing stricter scrutiny of degradation byproduct profiles. Continuous flow reactors in the Rhine-Ruhr chemical corridor eliminate residual formaldehyde in octyl-grade monomer production.
Japan
METI reimbursement incentives for rapid wound closure technologies open hospital procurement channels for premium octyl formulations. PMDA consultation pathways guide biocompatibility validation for novel sterilization methods. Academic medical centers in Tokyo and Osaka pilot photoinitiator-integrated systems for cardiac and neurological procedures.
China
Pharmaceutical-grade cyanoacrylate precursors concentrate production in Shandong province, exposing formulations to input volatility. NMPA medical device registration requirements align with ISO 10993 biocompatibility testing series for skin-contact adhesives. Chemical processors in Qingdao and Weifang supply monomer feedstock to international formulators.
2-Octyl Cyanoacrylate Adhesives Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered service intensity profiles. Medical-grade formulations demand intensive technical support for regulatory navigation and sterilization validation, while industrial segments prioritize volume logistics. Three archetypes dominate: vertically integrated chemical processors with captive monomer supply, application-focused specialists with custom viscosity capabilities, and diversified health care conglomerates with hospital formulary access. Competitive moves concentrate on solvent-free manufacturing scale-up and strategic partnerships with robotic surgical platform OEMs.
Among diversified health care conglomerates, Ethicon and 3M occupy positions anchored by quality system integration and proprietary stabilizer technology. Chemence Medical exemplifies the application-specialist archetype with formulation co-development capabilities for laparoscopic applicators. These three companies represent distinct competitive vectors: backward integration into monomer synthesis, shelf-life extension through package engineering, and viscosity grading for minimally invasive platforms.
| Leading Market Players |
|---|
| Ethicon |
| 3M |
| Medline Industries |
| Chemence Medical |
| Adhezion Biomedical |
| B. Braun Melsungen AG |
| GluStitch |
| Meyer-Haake |
| Cardinal Health |
| Others |
Value Chain & Pricing Dynamics
The Qingdao-Shanghai freight corridor carries pharmaceutical-grade cyanoacrylate monomers from Shandong province processing clusters to export terminals, with container rate volatility transmitting directly into formulation costs and amplifying price spreads between ISO-certified medical grades and industrial-tier alternatives.
Pricing Analysis
Cost-plus contracts with cyanide feedstock indexation dominate long-term supply agreements between Shandong monomer producers and international formulators. Price differentiation rests on FDA 510(k) certification tier and sterilization validation depth, with hospital formulary committees in Texas and California health systems showing lowest sensitivity due to bundled procurement. Cost compression in industrial-grade segments intensifies as butyl-2-cyanoacrylate substitutes capture veterinary and electronics potting applications.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for medical-grade octyl cyanoacrylate formulators. Production gravity centers on Shandong province for pharmaceutical-grade monomers, Germany's Rhine-Ruhr corridor for solvent-free continuous flow processing, and Japan's Kanto region for photoinitiator-integrated specialty grades. Raw material dependencies span cyanide precursors, stabilizer packages, and sterilization-grade packaging films. Distribution runs through direct sales contracts for high-volume automotive and electronics accounts, with medical supply distributors maintaining cold-chain infrastructure for hospital formulary compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network procurement committees across United States health systems, fragmenting individual surgeon preference and consolidating adhesive purchasing around comprehensive wound closure portfolios.
For Market Incumbents: Pre-empt butyl-2-cyanoacrylate substitution in cost-sensitive tiers by accelerating solvent-free manufacturing scale-up in Germany's chemical processing corridor. Anchor hospital formulary position through sole-source agreements with tiered pricing structures that bundle medical adhesives with complementary closure technologies. FDA guidance evolution on formaldehyde degradation thresholds represents the critical regulatory threat requiring preemptive ISO 10993-18 chemical characterization investment.
For New Entrants and Emerging Players: Custom viscosity grades for robotic surgical platform OEMs represent the most penetrable entry point, with laparoscopic applicator co-development requirements creating formulation partnership opportunities unavailable to standardized topical adhesive producers. Japan's METI reimbursement incentives for rapid wound closure technologies open procurement channels where premium octyl formulations command price premiums. Target academic medical center pilot programs in Germany and Japan as reference accounts for photoinitiator-integrated system adoption.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with captive monomer supply but limited medical device regulatory infrastructure. Long-term viability hinges on backward integration into pharmaceutical-grade monomer synthesis or forward integration into sterilization validation capabilities. The signal to watch is FDA pre-submission consultation volume for novel cyanoacrylate degradation profiles, indicating pipeline maturity and regulatory risk exposure across the competitive set.
| Strategic Initiative | Industry Significance |
|---|---|
| Solvent-Free Manufacturing Scale-Up | Continuous flow reactors in Germany's Rhine-Ruhr corridor eliminate residual formaldehyde for EU MDR compliance. |
| Robotic Surgical Platform Partnership | Custom viscosity grades for laparoscopic applicators address unmet needs in minimally invasive internal sealing. |
| FDA 510(k) Pre-Submission Pathway | Early engagement on degradation byproduct toxicology preempts regulatory holds for Class II device classification. |
| Hospital System Sole-Source Agreement | Integrated delivery networks in Texas and California consolidate procurement around comprehensive wound closure portfolios. |
| Photoinitiator-Integrated Formulation Development | Controlled polymerization rates enable cardiac and neurological applications where exothermic reactions must be minimized. |
Study Parameters
Initial hypotheses were tested against primary input from biomedical engineers at academic medical centers, hospital purchasing committee chairs, chemical processing plant managers, and regulatory affairs leads at medical device manufacturers, then refined through secondary validation against FDA 510(k) filings, EU MDR notified body guidance documents, ISO 10993 biocompatibility testing protocols, and customs trade data for cyanoacrylate monomer flows. Bottom-up volume estimates from ambulatory surgical center adhesive consumption were triangulated with top-down market sizing from chemical processor capacity disclosures.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by product grade tier, application intensity, end-user procurement modality, and regional regulatory cluster. CAGRs were derived from installed base growth in ambulatory surgical centers, reimbursement alignment trajectories, and substitution elasticity between tissue adhesives and mechanical closure methods. Forecast inputs incorporated METI incentive program enrollment rates, EU MDR notified body capacity constraints, and Shandong province monomer production utilization trends.
Stress conditions across FDA guidance stringency evolution, cyanide feedstock price volatility, and tariff regime shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding sterilization validation timeline compression and solvent-free manufacturing adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Windscreen Adhesive Market
Adhesives & Sealants
Optically Clear Adhesives Market
Adhesives & Sealants
US Pressure Sensitive Adhesives Market
Adhesives & Sealants
Malaysia Adhesives and Sealants Market
Adhesives & Sealants
Gasket and Seal Material Market
Adhesives & Sealants
Electrical Insulation Tape Market
Adhesives & Sealants
South America Adhesives Market
Adhesives & Sealants
Japan Sealants Market
Adhesives & Sealants
Silane Coupling Agents Market
Adhesives & Sealants
Global Ceramic Adhesives Market
Adhesives & Sealants
Acrylate Market
Adhesives & Sealants
North America Adhesives and Sealants Market
Adhesives & Sealants
Mirror Adhesive Market
Adhesives & Sealants
Foam Adhesive Market
Adhesives & Sealants
Dispersion Adhesives Market
Adhesives & Sealants
Italy Adhesives Market