
 Lymphopenia Therapeutics Market | 2026-2036
Lymphopenia Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Lymphopenia Therapeutics Market Outlook
Oncology hospital networks is rotating demand toward prophylactic lymphocyte recovery protocols rather than reactive rescue therapies. Sanofi leverages its biologics manufacturing scale to supply filgrastim across major cancer centers in North America and Europe. Pfizer Inc competes through integrated hospital contracting that bundles supportive care agents with oncology portfolios. GSK plc anchors its position in cytokine therapy through sustained R&D investment in granulocyte-colony stimulating factor analogs.
Lymphopenia therapeutics comprise biologic and cellular interventions designed to restore absolute lymphocyte counts below defined clinical thresholds, typically administered via intravenous infusion or subcutaneous injection with dosing calibrated to neutrophil and lymphocyte kinetics. These therapies serve the primary commercial purpose of preventing infectious complications and treatment delays in immunosuppressed patient populations. Immunoglobulin replacement commands established margin pools in autoimmune-related lymphopenia, while gene therapy represents the fastest-expanding technology segment despite manufacturing complexity. Monoclonal antibodies occupy a maturing niche in transplant conditioning regimens, with pricing power constrained by biosimilar entry.
The FDA enforces Current Good Manufacturing Practice standards for lymphocyte infusion products, directly shaping facility investment and batch release timelines for domestic suppliers. EMA's Advanced Therapy Medicinal Products framework governs gene therapy approaches in Europe, creating divergent approval pathways that fragment market access strategies. WHO prequalification standards for immunoglobulin sourcing influence procurement decisions in emerging health systems. Stakeholders must monitor how evolving manufacturing requirements for personalized cellular therapies reshape capital allocation between centralized bioproduction and distributed hospital-based compounding models.
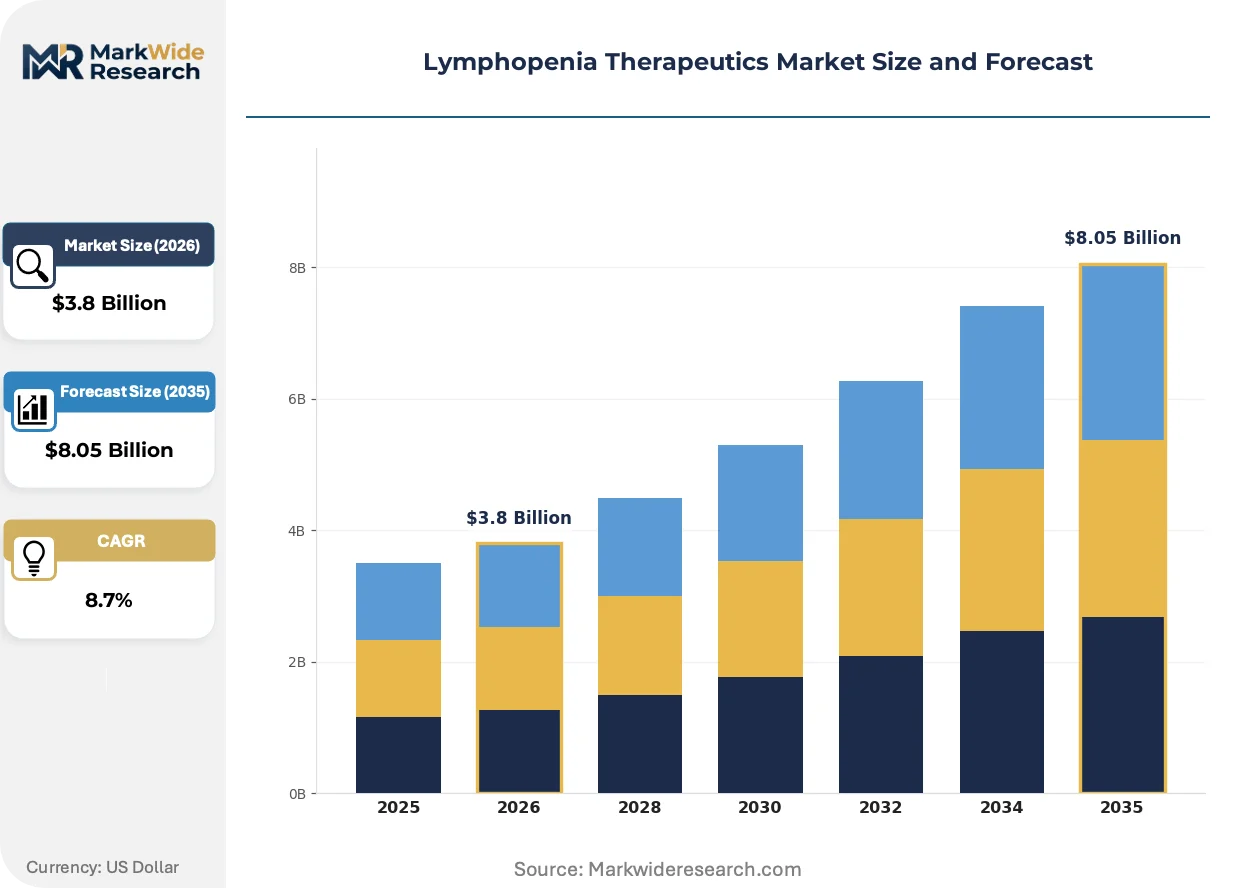
Market Dynamics
Oncology hospital networks are rotating demand toward prophylactic lymphocyte recovery protocols rather than reactive rescue therapies, compressing the window between diagnosis and therapeutic intervention. This shift is forcing manufacturers to reconfigure supply chains around just-in-time cytokine delivery systems calibrated to chemotherapy cycle timing.
Growth Catalysts
- EMA Advanced Therapy Medicinal Products framework:Gene therapy developers gain accelerated assessment pathways for lymphocyte engineering products in Europe, reducing time-to-market for novel cellular interventions.
- Academic medical centers in the United States:Protocol standardization at major cancer institutes creates template adoption across affiliated community hospitals, expanding addressable patient populations.
- Subcutaneous cytokine delivery devices:Self-administration technology reduces infusion center burden and enables outpatient lymphopenia management, extending therapy access beyond tertiary care settings.
Market Restraints
- Plasma-derived immunoglobulin supply volatility:Fractionation facility concentration in the United States and Europe creates geographic supply risk for autoimmune-related lymphopenia therapies.
- FDA Current Good Manufacturing Practice batch release timelines:Extended quality verification for personalized cellular products constrains production throughput and inventory turnover.
- Autologous stem cell collection limitations:Patient-specific starting material variability reduces manufacturing yield predictability for gene-modified lymphocyte therapies.
Strategic Opportunities
- India's expanding oncology infrastructure:CDSCO streamlined biologics licensing creates entry pathway for cytokine manufacturers serving chemotherapy-induced lymphopenia in emerging hospital networks.
- Gene therapy-cytokine combination protocols:Convergent engineering of lymphocyte expansion factors with CAR-T conditioning regimens opens combination therapy positioning.
- WHO prequalification for immunoglobulin:Emerging health system procurement alignment with international sourcing standards creates volume aggregation opportunities for qualified suppliers.
Industry Challenges
- Cell therapy manufacturing workforce scarcity:Aseptic processing and vector production expertise gaps constrain facility expansion timelines for personalized lymphocyte products.
- ISO 14644 cleanroom certification complexity:Multi-year facility qualification processes delay commercial launch for gene therapy developers targeting immune reconstitution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lymphopenia Therapeutics Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filgrastim, Epoetin, Lymphocyte Infusion, Immunoglobulins Technology: Gene Therapy, Monoclonal Antibodies, Cytokine Therapy, Immune Checkpoint Inhibitors Application: Cancer Treatment, Autoimmune Disorders, Transplantation, Bone Marrow Suppression End User: Hospitals, Ambulatory Surgical Centers, Research Laboratories, Specialty Clinics |
| Companies Covered | Sanofi, Pfizer Inc, GSK plc, Novartis AG, Bayer AG, F. Hoffmann-La Roche Ltd, Merck & Co., Inc, AbbVie Inc, Gilead Sciences Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lymphopenia Therapeutics Market Strategic Shifts
Technology convergence between automated cell processing and real-time lymphocyte monitoring is compressing therapeutic decision cycles. These developments are simultaneously expanding precision medicine capabilities and fragmenting traditional hospital-based care models.
Next-generation cytokine analog engineering is bifurcating the lymphopenia therapeutics landscape between short-acting rescue agents and sustained-release prophylactic formulations. Academic medical centers in the United States are piloting pharmacokinetic-guided dosing protocols that match cytokine half-life to individual patient lymphocyte recovery kinetics. This technology is bifurcating reimbursement pathways between episodic rescue therapy codes and chronic prophylaxis coverage categories.
EMA's tightened contamination control guidelines for ATMP manufacturing are extending facility validation timelines for European gene therapy suppliers. The industrial consequence is capital reallocation toward centralized bioproduction hubs with dedicated lymphocyte processing suites rather than distributed hospital-based compounding. Gene-modified cellular therapies for primary immunodeficiency are most affected, with developers consolidating manufacturing at single-site facilities to satisfy batch consistency requirements.
Hospital procurement for supportive oncology care is consolidating through integrated health system formularies that bundle lymphopenia therapeutics with chemotherapy portfolios. Specialty distributors are losing direct hospital access as pharmacy benefit managers embed cytokine protocols within oncology pathway contracts. This concentration is most visible in United States payer networks, where academic medical center purchasing alliances negotiate multi-year supply agreements spanning prophylactic and rescue therapy categories.
Lymphopenia Therapeutics Market Segmentation
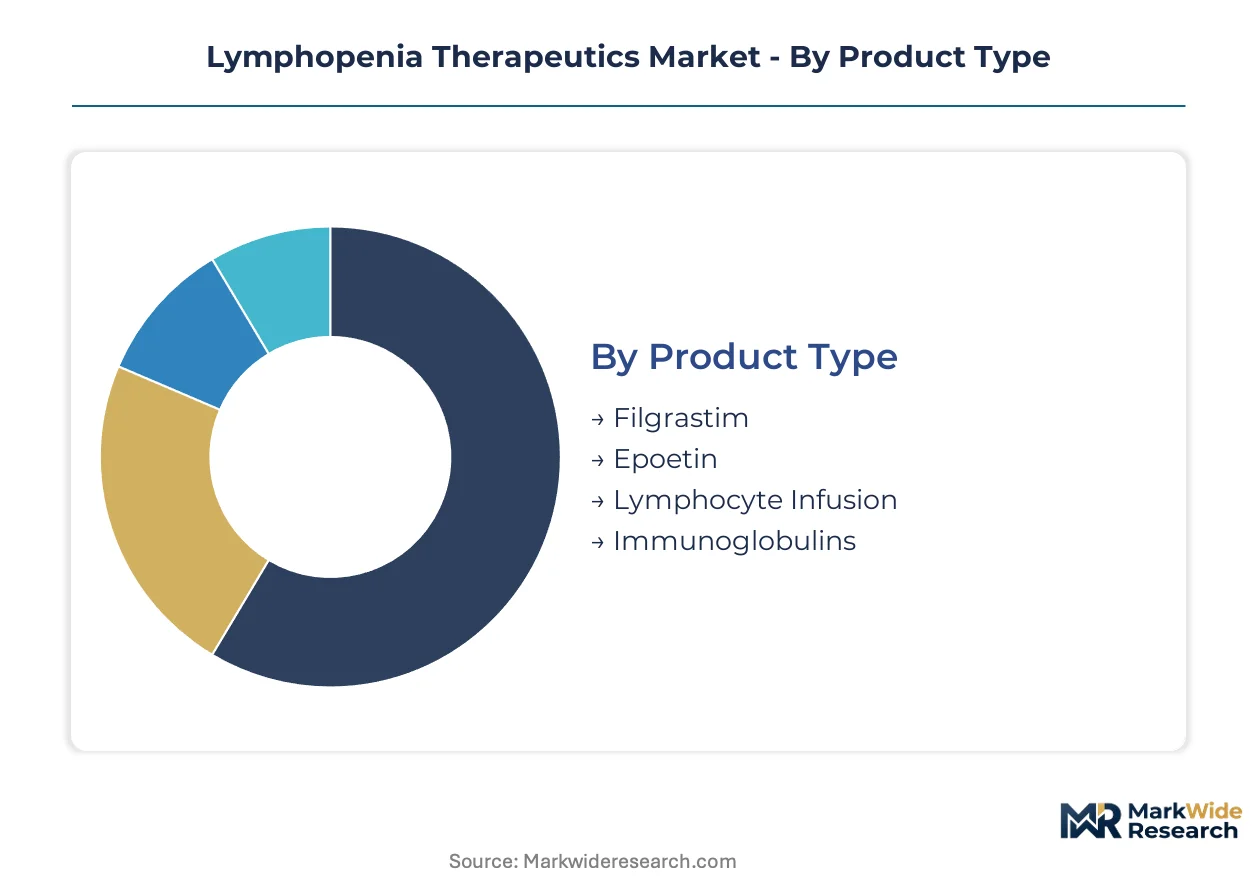
Lymphopenia therapeutics span distinct biological mechanisms and care settings that command divergent pricing power and reimbursement pathways. Segment boundaries are blurring as gene therapy-cytokine combinations and hospital-at-home delivery models reshape traditional category definitions.
Product Type:
Margin pools concentrate in recombinant cytokines with established manufacturing scale and immunoglobulins with plasma supply scarcity premiums.
- Filgrastim:Recombinant granulocyte-colony stimulating factor administered via subcutaneous injection to accelerate neutrophil recovery. Demand clusters in United States academic medical centers where prophylactic protocols now precede chemotherapy cycles. Biosimilar entry has compressed pricing but expanded volume through pathway bundling.
- Immunoglobulins:Polyclonal antibody preparations derived from pooled human plasma for passive immune reconstitution. Supply constraints at fractionation facilities in the United States and Europe sustain premium pricing for autoimmune-related lymphopenia indications. WHO prequalification requirements are reshaping procurement in emerging health systems.
- Epoetin:Erythropoietin analog stimulating red blood cell production in bone marrow suppression settings.
- Lymphocyte Infusion:Adoptive transfer of ex vivo expanded or donor-derived lymphocyte populations.
Filgrastim holds installed capacity. Lymphocyte Infusion is rotating up the share rankings.
Technology:
Volume leadership sits with cytokine platforms while gene therapy commands the steepest expansion trajectory despite manufacturing bottlenecks.
- Cytokine Therapy:Engineered signaling proteins regulating lymphocyte proliferation and differentiation, spanning IL-2 analogs to next-generation half-life extended constructs. United States hospital networks are standardizing pharmacokinetic-guided dosing protocols that match agent selection to individual recovery kinetics. Subcutaneous delivery devices are extending access beyond infusion centers.
- Gene Therapy:Ex vivo genetic modification of autologous or allogeneic lymphocytes to restore immune function in primary immunodeficiency. EMA's Advanced Therapy Medicinal Products framework provides accelerated assessment pathways in Europe. FDA Current Good Manufacturing Practice standards for batch release constrain production throughput and consolidate manufacturing at centralized bioproduction hubs.
- Monoclonal Antibodies:Targeted immunomodulatory agents depleting or activating specific lymphocyte subsets.
- Immune Checkpoint Inhibitors:Antibodies blocking PD-1/PD-L1 or CTLA-4 pathways with lymphopenia as a recognized adverse event requiring management.
Cytokine Therapy anchors current revenue. Gene Therapy is gaining share fastest through CAR-T conditioning convergence.
Application:
Customer concentration varies sharply: oncology commands protocol standardization while transplantation retains specialist-driven purchasing.
- Cancer Treatment:Chemotherapy-induced lymphopenia management across solid tumor and hematologic malignancy protocols. Hospital procurement consolidation through integrated health system formularies is bundling supportive care agents with oncology portfolios. Specialty distributors are losing direct access as pharmacy benefit managers embed cytokine protocols within pathway contracts.
- Autoimmune Disorders:Lymphocyte depletion and reconstitution in conditions such as systemic lupus erythematosus and multiple sclerosis. Immunoglobulin replacement dominates this segment with established margin pools sustained by plasma supply concentration.
- Transplantation:Immune reconstitution following hematopoietic stem cell or solid organ transplantation.
- Bone Marrow Suppression:Myelosuppressive therapy recovery spanning radiation, chemotherapy, and aplastic anemia settings.
Cancer Treatment holds protocol standardization. Autoimmune Disorders is rotating up the share rankings.
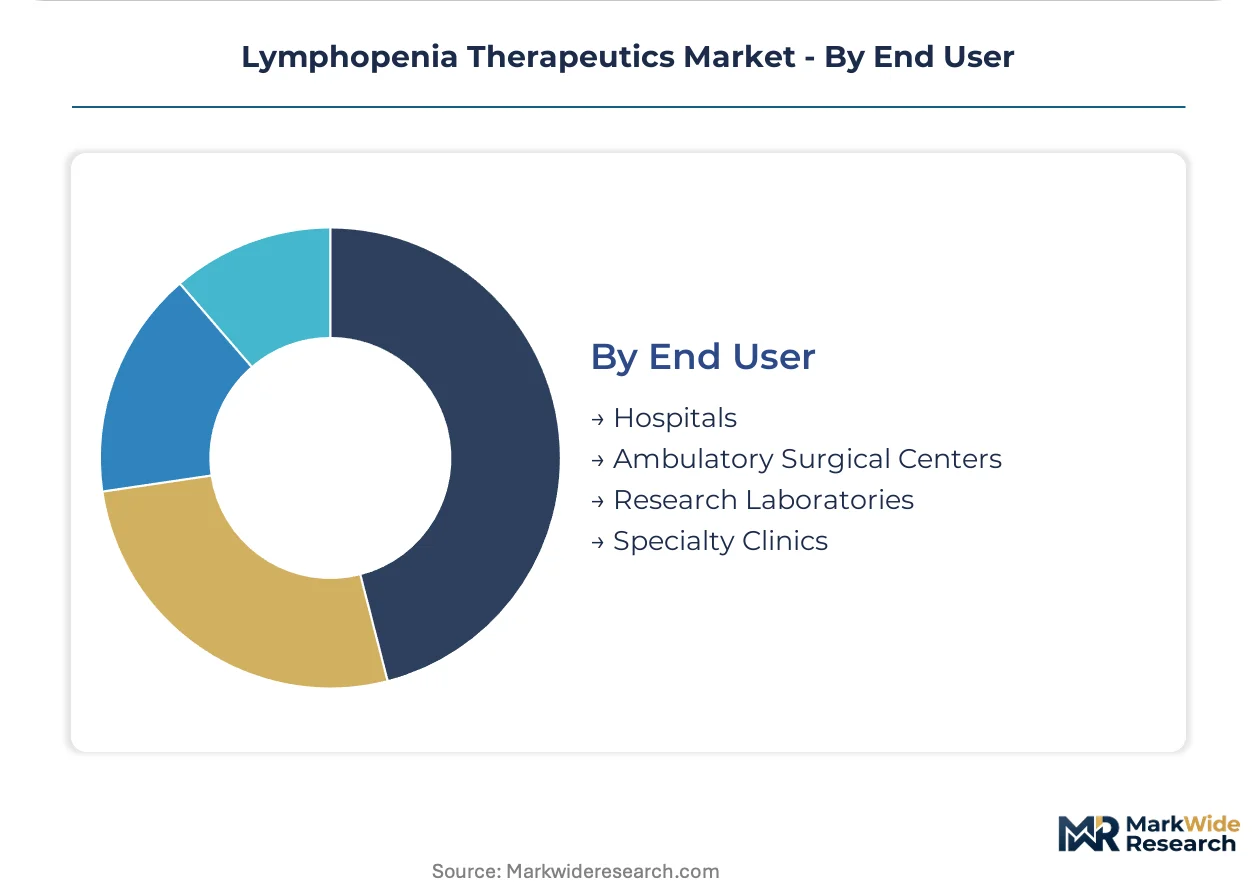
End User:
Care site economics are fragmenting as subcutaneous delivery enables outpatient migration from tertiary centers.
- Hospitals:Tertiary and quaternary centers with integrated oncology pathways and on-site compounding capabilities. Academic medical centers in the United States drive protocol development that cascades to affiliated community hospitals through purchasing alliances. EMA contamination control guidelines for ATMP manufacturing are extending facility validation timelines and consolidating processing at dedicated suites.
- Specialty Clinics:Focused infusion and immune reconstitution centers with concentrated lymphopenia patient volumes. Self-administration technology for cytokine delivery is expanding the addressable footprint beyond traditional hospital-based models.
- Ambulatory Surgical Centers:Outpatient settings capturing low-complexity lymphocyte recovery monitoring.
- Research Laboratories:Academic and commercial sites conducting clinical trials and manufacturing process development.
Hospitals hold installed capacity. Specialty Clinics is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics infrastructure underwrites Europe's dominance in plasma-derived immunoglobulin distribution, while direct flights from Memphis and Louisville anchor United States biologics distribution networks.
United States
Academic medical centers at MD Anderson, Memorial Sloan Kettering, and Dana-Farber drive protocol standardization for prophylactic cytokine administration. FDA Current Good Manufacturing Practice standards for lymphocyte infusion products extend batch release timelines and consolidate manufacturing at centralized bioproduction hubs. The Research Triangle Park cluster in North Carolina hosts vector production facilities supplying gene-modified cellular therapies to transplant centers nationwide.
Germany
University hospitals in Heidelberg, Munich, and Berlin pilot pharmacokinetic-guided dosing protocols matching cytokine half-life to individual patient recovery kinetics. EMA's Advanced Therapy Medicinal Products framework provides accelerated assessment pathways for lymphocyte engineering products. The Rhine-Main biotech corridor concentrates contract development and manufacturing organizations serving European gene therapy developers.
China
NMPA streamlined biologics licensing under the 2020 Drug Registration Regulation accelerates cytokine manufacturer entry into chemotherapy-induced lymphopenia management. The Yangtze River Delta biopharma cluster in Shanghai and Suzhou expands contract manufacturing capacity for recombinant protein production. Domestic hospital networks in Beijing and Guangzhou adopt subcutaneous delivery devices for outpatient immune reconstitution.
India
CDSCO's 2022 biologics pathway simplification creates regulatory entry for filgrastim manufacturers serving expanding oncology infrastructure. The Hyderabad-Visakhapatnam pharmaceutical corridor concentrates active pharmaceutical ingredient and formulation capacity for supportive care agents. Tata Memorial Centre in Mumbai and AIIMS in Delhi drive protocol adoption across affiliated regional cancer centers.
Japan
PMDA's regenerative medicine product designation accelerates lymphocyte infusion product review timelines for primary immunodeficiency indications. METI's healthcare technology export initiative promotes cytokine therapy platform licensing to Southeast Asian hospital networks. The Kansai biomedical cluster in Osaka hosts cell processing facilities supplying transplant centers across the archipelago.
Lymphopenia Therapeutics Market Competitive Environment
Concentration sits with diversified pharmaceutical conglomerates commanding biologics manufacturing scale and hospital contracting infrastructure. The vendor base spans three tiers: global innovators with integrated oncology portfolios, regional biosimilar specialists capturing volume through price competition, and emerging cell therapy developers targeting gene-modified lymphocyte niches. Dominant competitive moves include strategic partnerships between cytokine manufacturers and gene therapy developers for combination protocols, plus capacity expansion at centralized bioproduction hubs to satisfy EMA contamination control guidelines.
Within the diversified pharmaceutical tier, Sanofi, Pfizer Inc, and GSK plc exemplify contrasting strategic positions. Sanofi anchors European supply relationships through biologics manufacturing scale. Pfizer Inc occupies a position shaped by integrated hospital contracting that bundles supportive care agents. GSK plc represents sustained R&D investment in granulocyte-colony stimulating factor analogs. These three entities collectively illustrate how installed manufacturing infrastructure and payer network access determine competitive positioning in prophylactic lymphopenia management.
| Leading Market Players |
|---|
| Sanofi |
| Pfizer Inc |
| GSK plc |
| Novartis AG |
| Bayer AG |
| F. Hoffmann-La Roche Ltd |
| Merck & Co., Inc |
| AbbVie Inc |
| Gilead Sciences Inc |
| Others |
Value Chain & Pricing Dynamics
Plasma fractionation scale economies at United States and European facilities anchor immunoglobulin price floors while constraining supply elasticity for autoimmune-related lymphopenia therapies. This concentration creates divergent margin pools between scarce plasma-derived products and recombinant cytokines with established manufacturing throughput.
Pricing Analysis
Volume-discount tiering structures separate academic medical center purchasing alliances from community hospital spot procurement. Three-tier pricing structure across premium, standard, and economy levels reflects FDA Current Good Manufacturing Practice certification grade and plasma sourcing provenance. Cost compression in biosimilar filgrastim is intensifying because of pathway bundling with oncology portfolios. Community hospitals exhibit highest price sensitivity due to constrained formulary budgets, while quaternary centers prioritize supply security over unit cost.
Supply Chain Analysis
Strait of Hormuz transit vulnerability for cold-chain logistics underwrites distribution risk for plasma-derived immunoglobulins sourced from United States fractionators. Manufacturing concentrates in the United States, Germany, and Switzerland for cytokine active pharmaceutical ingredients. Production draws from recombinant cell lines, plasma donor pools, and viral vector substrates. Single-source vulnerability at specialized aseptic filling sites constrains gene-modified lymphocyte product availability. Distribution runs through specialty pharmaceutical distributors with hospital-direct relationships for oncology pathway contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lymphopenia therapeutics represent an early-cycle expansion story as prophylactic cytokine protocols displace reactive rescue therapies across United States oncology networks. Gene therapy-cytokine convergence in CAR-T conditioning regimens accelerates addressable patient population expansion.
For Market Incumbents: Secure centralized bioproduction hub capacity to satisfy EMA contamination control guidelines for Advanced Therapy Medicinal Products manufacturing. Lock multi-year supply agreements with academic medical center purchasing alliances before biosimilar filgrastim commoditization erodes pathway bundling leverage. Gene therapy developers pose substitution threat through combination protocol positioning. For New Entrants and Emerging Players: CDSCO's biologics fast-track certification creates regulatory entry pathway into India's expanding oncology infrastructure. Target subcutaneous cytokine delivery device segments where self-administration technology fragments traditional hospital-based care models. Pursue WHO prequalification for immunoglobulin sourcing to capture emerging health system procurement aggregation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors contract development and manufacturing organizations with vector production and aseptic processing capabilities. Long-term viability rests on consolidation of gene-modified lymphocyte manufacturing at single-site facilities to satisfy batch consistency requirements. Watch FDA Current Good Manufacturing Practice batch release timeline extensions as inflection indicator for production throughput constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Centralized Bioproduction Hub Expansion | EMA contamination control guidelines consolidate manufacturing at dedicated lymphocyte processing suites. |
| Pharmacokinetic-Guided Dosing Protocol Development | Academic medical centers in the United States standardize cytokine half-life matching to individual recovery kinetics. |
| Subcutaneous Delivery Device Licensing | Self-administration technology extends lymphopenia management beyond tertiary infusion centers. |
| WHO Prequalification Pathway Pursuit | Immunoglobulin sourcing alignment creates volume aggregation opportunities in emerging health systems. |
| Gene Therapy-Cytokine Combination Partnership | Convergent engineering opens positioning in CAR-T conditioning regimens. |
Study Parameters
Initial hypotheses were tested against primary input from regulatory affairs leads, hospital procurement managers, formulary directors, and payer access specialists and refined through secondary validation. Sources included FDA filings, EMA submissions, ClinicalTrials.gov, and hospital procurement databases. Bottom-up patient population modeling triangulated against top-down manufacturer capacity assessments.
Variance decomposition across product type, technology platform, application setting, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level volume trajectories and pricing elasticity assumptions. Forecast inputs incorporated cytokine protocol adoption curves and gene therapy manufacturing yield improvements throughout the projection horizon.
Decision-makers should treat outputs as directional under base assumptions of stable FDA Current Good Manufacturing Practice enforcement and EMA Advanced Therapy Medicinal Products pathway continuity; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as plasma supply volatility and autologous stem cell collection limitations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Global Hematology Diagnostics Market
Hematology
Global Hodgkin Lymphoma Treatment Market
Hematology
Warm Autoimmune Hemolytic Anemia Market
Hematology
Hypereosinophilic Syndrome Market
Hematology
Pancytopenia Market
Hematology
Global Immunohematology Market
Hematology
Chronic Immune Thrombocytopenia Treatment Market
Hematology
Aplastic Anemia Treatment Market
Hematology
Polycythemia Vera Treatment Market
Hematology
Neutropenia Treatment Market
Hematology
Peripheral T-Cell Lymphoma Treatment Market
Hematology
Marginal Zone Lymphoma Treatment Market
Hematology
Polycythemia Vera Market
Hematology
Thalassemia Treatment Market
Hematology
At-Home Hematology Testing Market
Hematology
Sickle Cell Treatment Market