
 Bioadhesives for Packaging Market | 2026-2036
Bioadhesives for Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Bioadhesives for Packaging Market Outlook
Petroleum-derived synthetic adhesives is repositioning toward bio-based feedstocks as resin volatility and Extended Producer Responsibility laws compress margins on conventional formulations. Henkel AG & Co. KGaA leverages its European formulation network to supply certified compostable hotmelts to multinational food brands. H.B. Fuller Company anchors North American capacity with plant-based polymer production for corrugated and flexible packaging lines. Danimer Scientific differentiates through microbial fermentation of polyhydroxyalkanoates tailored to high-moisture packaging environments.
Bioadhesives for packaging comprise bonding agents formulated from renewable biological sources—starches, proteins, plant-derived polymers, or microbial polyesters—engineered to achieve peel strengths of 2–8 N/25mm and compostability under industrial or home conditions per ASTM D6400 and EN 13432 protocols. Their primary commercial purpose is to replace fossil-based adhesives in sealing, labeling, and laminating operations where end-of-life biodegradability determines brand compliance and retailer acceptance. Starch-based formulations dominate volume in corrugated case sealing and paper bag manufacturing where cost parity with dextrin glues has already been achieved. Polymer-based bioadhesives represent the fastest-expanding margin pool, particularly in flexible food packaging where oxygen barrier requirements previously excluded natural binders. Protein-based variants occupy niche positions in medical packaging where cytotoxicity standards restrict synthetic options.
EU Green Deal packaging regulations and REACH restrictions on petrochemical monomers are redirecting formulation investments toward verified bio-based content, while FDA food-contact substance notifications govern adhesive migration limits in US food packaging applications. ECHA's microplastics restriction proposal threatens conventional synthetic adhesive fragments in wash-off labels, amplifying substitution pressure. Stakeholders must monitor evolving compostability certification requirements across jurisdictions and align R&D portfolios with the divergence between industrial composting infrastructure availability and home-compostable product claims.
Market Dynamics
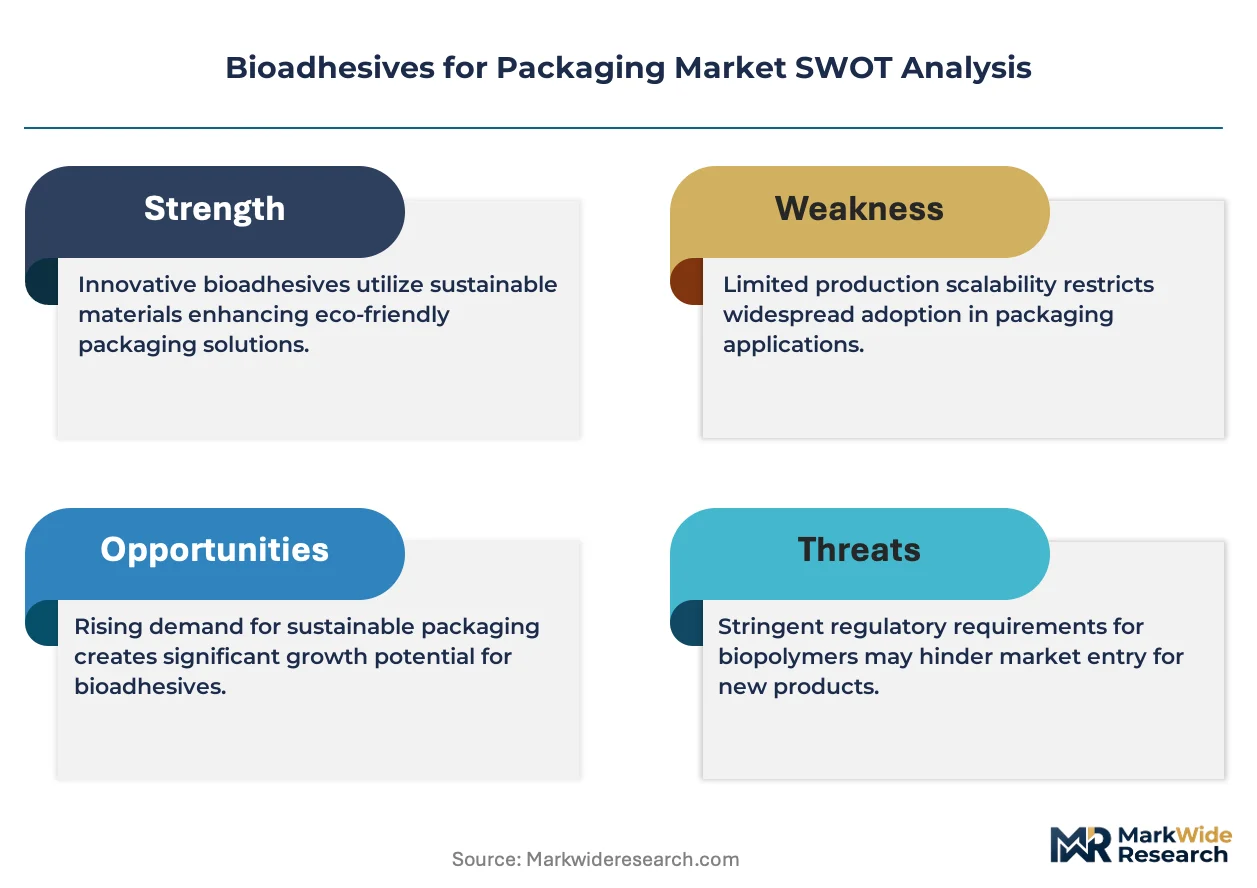
EU Green Deal mandates are compressing the transition timeline for petroleum-derived adhesive replacement, forcing converters to secure certified compostable formulations before infrastructure readiness catches up with regulatory deadlines.
Growth Catalysts
- Extended Producer Responsibility frameworks:France's AGEC law and Germany's Verpackungsgesetz impose end-of-life accountability on brand owners, redirecting procurement toward verified compostable sealing solutions.
- Starch-based hotmelt cost parity:Dextrin glue replacement in corrugated case sealing has crossed the threshold where bio-based options match synthetic pricing at volume scale.
- Flexible food packaging oxygen barrier breakthroughs:Polymer-based bioadhesives now achieve the hermeticity standards previously exclusive to fossil-derived laminates.
Market Restraints
- Agricultural feedstock volatility:Corn and potato starch prices fluctuate with climate-driven crop yields, compressing margin predictability for formulation houses.
- Industrial composting infrastructure gaps:Home-compostable claims face verification challenges where municipal anaerobic digestion capacity remains concentrated in Northern European clusters.
- Polyhydroxyalkanoate production bottlenecks:Microbial fermentation capacity for high-moisture packaging grades remains captive to a limited supplier base.
Strategic Opportunities
- Medical packaging cytotoxicity compliance:Protein-based variants command premium positioning where FDA food-contact notifications and ISO 10993 biocompatibility standards exclude synthetic alternatives.
- ECHA microplastics restriction anticipation:Wash-off label adhesive substitution demand will accelerate as the proposal advances toward enforceable thresholds.
- Corrugated e-commerce secondary packaging:Paper bag and shipper box sealing volumes are scaling with fulfillment center automation requiring cold-tack starch formulations.
Industry Challenges
- ASTM D6400 and EN 13432 dual certification complexity:Divergent industrial composting temperature and duration protocols force redundant testing expenditure for pan-European distribution.
- Legacy hotmelt equipment retrofit requirements:Plant-based polymer viscosity profiles demand heated hose and tank modifications that extend converter qualification timelines.
- Adhesive migration limit documentation:FDA food-contact substance notification dossiers require extensive extraction study investment for novel bio-based monomers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioadhesives for Packaging Market |
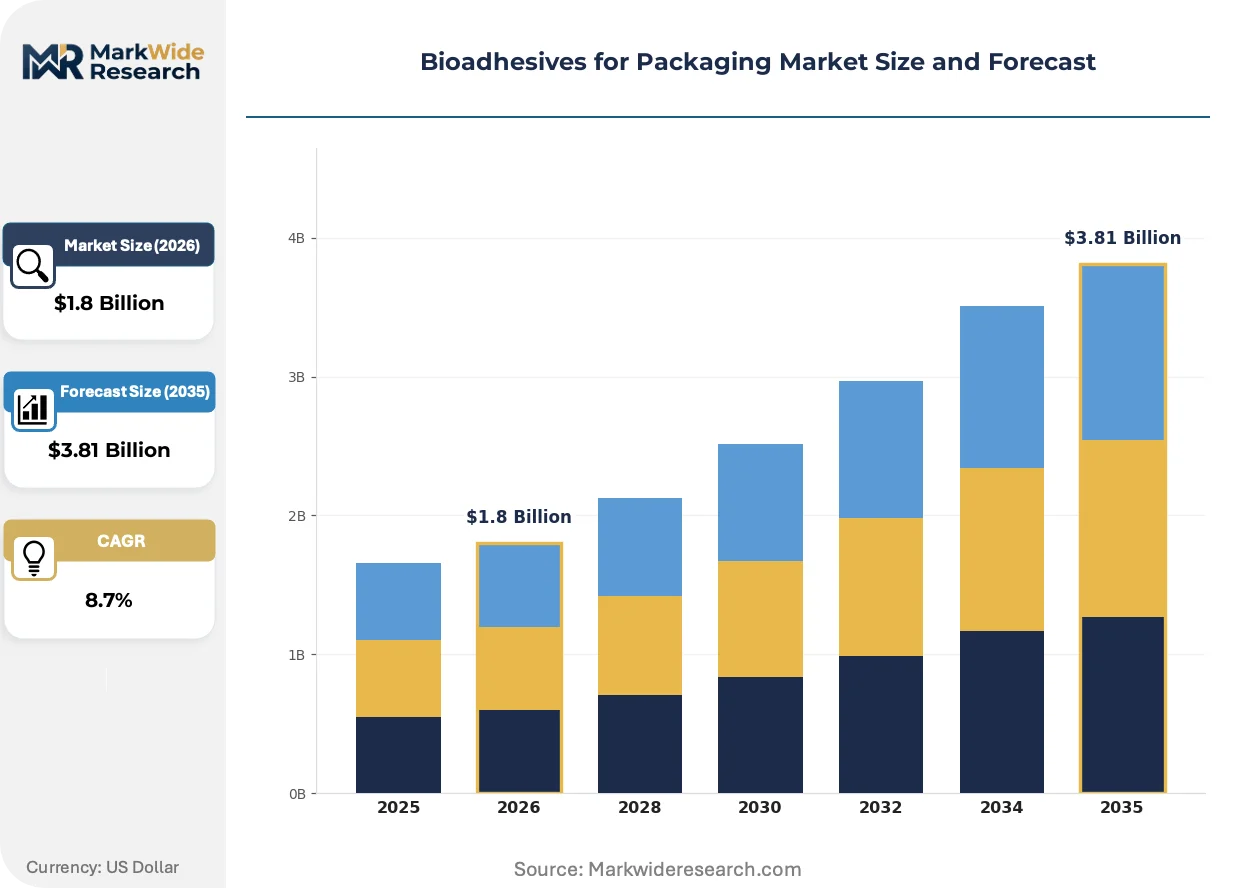
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer-Based, Starch-Based, Protein-Based, Synthetic Application: Food Packaging, Medical Packaging, Consumer Goods, Industrial Use Formulation: Liquid, Powder, Gel, Film End User: Manufacturers, Distributors, Retailers, End Consumers |
| Companies Covered | Henkel AG & Co. KGaA, Arkema S.A., H.B. Fuller Company, DuPont de Nemours, Inc., Danimer Scientific, EcoSynthetix Inc., Ashland Global Holdings, Ingredion Incorporated, Jowat SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioadhesives for Packaging Market Strategic Shifts
Formulation chemistry is pivoting from incremental bio-content blending toward engineered microbial polymers that replicate synthetic performance profiles without fossil-derived building blocks.
Polyhydroxyalkanoate-based laminating adhesives is overtaking conventional polyurethane systems in high-barrier flexible food packaging. Multinational brand owners in Germany and the Netherlands are qualifying these grades for retort pouch applications. The shift is compressing the addressable market for petroleum-derived moisture-cure systems in premium snack and ready-meal segments.
REACH restrictions on petrochemical monomers are redirecting European formulation investments toward verified bio-based content thresholds. ECHA's evolving substance evaluation roadmap threatens existing synthetic adhesive building blocks with authorization requirements. Flexible packaging converters in Italy and Spain are accelerating supplier audits to preempt supply disruption.
Brand-owner sustainability scorecards are reshaping procurement qualification criteria. Major food retailers in France and the UK now require compostability certification as a listing prerequisite for private-label packaging. This preference shift is disintermediating uncertified adhesive suppliers from approved vendor lists regardless of unit cost position.
Bioadhesives for Packaging Market Segmentation
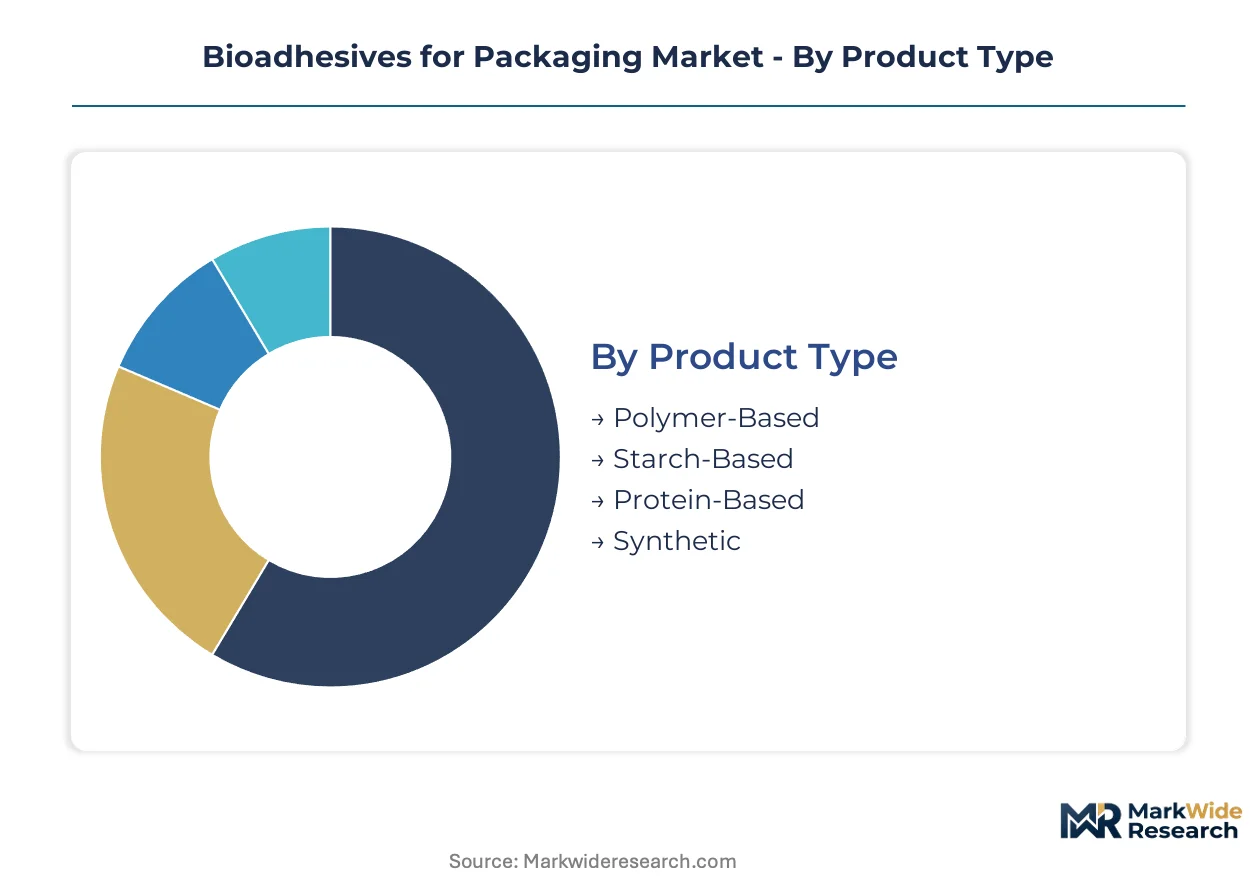
Segmentation in bioadhesives for packaging reveals how formulation chemistry, application requirements, and supply chain position determine margin capture. Manufacturers configure production assets around feedstock access and certification complexity rather than chasing uniform scale economies.
Product Type:
Standardization dominates commodity starch grades while polymer-based variants demand bespoke molecular engineering for barrier performance.
- Polymer-Based:Engineered from polylactic acid, polyhydroxyalkanoates, and bio-polyurethanes achieving oxygen transmission rates below 0.1 cc/m²/day. Flexible food packaging converters in Germany and the Netherlands are qualifying these grades for retort pouch applications where hermeticity standards previously excluded natural binders.
- Starch-Based:Derived from corn, potato, and cassava starches with dextrin and modified starch variants dominating corrugated case sealing. Cost parity with synthetic dextrin glues has already been achieved at volume scale, concentrating demand among European e-commerce fulfillment centers requiring cold-tack formulations for automated lines.
- Protein-Based:Collagen, casein, and soy protein isolates serve medical packaging where ISO 10993 biocompatibility standards restrict synthetic alternatives.
- Synthetic:Petroleum-derived hotmelts and moisture-cure systems face phased replacement under EU Green Deal mandates.
Leading the category by volume: Starch-Based. Growing fastest: Polymer-Based.
Application:
Regulatory intensity separates premium-certified segments from price-sensitive industrial tiers.
- Food Packaging:Encompasses flexible laminates, rigid containers, and labeling where FDA food-contact substance notifications and EU 10/2011 migration limits govern adhesive selection. Major French and UK retailers now require compostability certification as a listing prerequisite, disintermediating uncertified suppliers from approved vendor lists.
- Medical Packaging:Sterile barrier systems and device packaging where cytotoxicity testing under ISO 10993 excludes most synthetic options. Protein-based adhesives command premium positioning here due to inherent biocompatibility.
- Consumer Goods:Cosmetics and personal care packaging with moderate performance requirements and shorter certification pathways.
- Industrial Use:Secondary packaging and palletizing applications where cost minimization outweighs end-of-life credentials.
Highest margin concentration: Medical Packaging. Steepest volume expansion: Food Packaging.
Formulation:
Physical state determines equipment compatibility and supply chain logistics cost structures.
- Liquid:Water-based dispersions and solvent-free systems requiring heated tanks and recirculation systems. Corrugated converters favor these for high-speed flute bonding where open time and tack development must synchronize with line speeds.
- Powder:Dry starch and protein adhesives reconstituted on-site with controlled water addition. Bag-in-box and paper sack manufacturers prefer powder logistics for reduced transport weight and extended shelf stability.
- Gel:Semi-solid preparations for manual application and repair operations.
- Film:Pre-cast adhesive layers for heat-activated lamination in multilayer flexible packaging.
Dominant by installed base: Liquid. Expanding most quickly: Film.
End User:
Procurement sophistication varies dramatically across the value chain, from technical specification ownership to passive price acceptance.
- Manufacturers:Brand-owning converters and packaging producers with direct formulation specification authority. These stakeholders manage ASTM D6400 and EN 13432 dual certification complexity for pan-European distribution.
- Distributors:Regional adhesive resellers aggregating demand from smaller converters and providing technical service support.
- Retailers:Supermarket chains and e-commerce platforms imposing sustainability scorecards on upstream suppliers.
- End Consumers:Home composters and environmentally motivated purchasers whose awareness drives brand-owner marketing claims but who lack direct procurement influence.
Specification control concentrates with: Manufacturers. Fastest-growing procurement sophistication: Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converters in Germany command the largest share of bioadhesive specification authority, serving pan-European brand owners with certified compostable sealing solutions. France and the United Kingdom follow with retailer-driven procurement mandates that accelerate substitution timelines. Asia-Pacific markets concentrate demand in Japan and Australia where industrial composting infrastructure supports premium-grade adoption.
Germany
Flexible food packaging converters in the Rhine-Ruhr and Stuttgart regions specify polymer-based bioadhesives for retort pouch applications. The Verpackungsgesetz imposes end-of-life accountability that redirects procurement toward EN 13432-certified formulations. Henkel AG maintains formulation network capacity in Düsseldorf to supply multinational food brands with compostable hotmelts.
France
AGEC law mandates compel brand owners to secure verified compostable sealing solutions ahead of infrastructure readiness. ECHA substance evaluation roadmaps threaten synthetic adhesive building blocks with authorization requirements. Converters around Lyon and Paris accelerate supplier audits to preempt supply disruption from REACH restrictions.
United Kingdom
Major food retailers require compostability certification as a listing prerequisite for private-label packaging. The British Standards Institution aligns with EN 13432 protocols for industrial composting verification. Flexible packaging clusters in Manchester and Birmingham disintermediate uncertified adhesive suppliers from approved vendor lists.
Japan
METI circular economy targets drive adoption of bio-based laminating adhesives in premium snack packaging. JIS standards for compostability testing create parallel certification pathways alongside ASTM D6400. Osaka-based converters qualify polyhydroxyalkanoate grades for high-moisture food environments.
United States
FDA food-contact substance notifications govern adhesive migration limits in food packaging applications. California and New York procurement policies amplify demand for ASTM D6400-certified formulations. H.B. Fuller anchors North American plant-based polymer production for corrugated and flexible packaging lines.
Bioadhesives for Packaging Market Competitive Environment
Capacity expansion dominates the current landscape as formulation houses retrofit assets for bio-based polymer production. The vendor base organizes around three tiers: multinational chemical conglomerates with European formulation networks, mid-cap adhesive specialists with regional certification expertise, and microbial fermentation entrants with PHA production capabilities. Strategic archetypes include feedstock-integrated players securing agricultural supply contracts and equipment-aligned suppliers offering converter retrofit services. M&A activity concentrates on microbial fermentation capacity acquisition while strategic partnerships link formulation houses with industrial composting verification bodies.
Within the multinational tier, Henkel AG & Co. KGaA and H.B. Fuller Company exemplify divergent geographic anchoring strategies. Henkel occupies a position tied to European regulatory momentum and Green Deal compliance frameworks. H.B. Fuller represents North American capacity concentration around plant-based polymer supply chains. Danimer Scientific sits within the fermentation-specialist archetype, occupying a position defined by microbial production of polyhydroxyalkanoates rather than conventional formulation chemistry.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Arkema S.A. |
| H.B. Fuller Company |
| DuPont de Nemours, Inc. |
| Danimer Scientific |
| EcoSynthetix Inc. |
| Ashland Global Holdings |
| Ingredion Incorporated |
| Jowat SE |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up adhesive specialists have consolidated regional formulation assets across Germany and the Netherlands, concentrating supply-side discipline while compressing procurement leverage for mid-sized European converters. This ownership pattern tightens pricing coordination among starch-based producers and amplifies margin pressure on polymer-grade entrants competing for certified compostable contracts.
Pricing Analysis
Volume concentrates in commodity starch grades while margin pools accrue to polymer-based variants engineered for oxygen barrier performance. Three-tier pricing structure across premium, standard, and economy levels separates EN 13432-certified formulations from uncertified alternatives and industrial-grade dextrin glues. Price differentiation hinges on compostability verification tier and volume scale commitments from pan-European brand owners. Cost compression in standard starch segments is intensifying because agricultural feedstock volatility has narrowed formulation house margins. Small-scale Italian and Spanish converters exhibit highest price sensitivity, while German multinational food brands prioritize certification compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements mandated by French AGEC law and German Verpackungsgesetz compel converters to qualify multiple adhesive suppliers for each formulation grade, fragmenting procurement concentration despite geographic supply clustering. Feedstock supply concentrates in Germany, the Netherlands, and Belgium where corn and potato starch processing infrastructure anchors European production. Raw material dependencies center on agricultural starch crops, microbial fermentation feedstocks, and bio-polymer catalysts. Single-source vulnerability threatens polyhydroxyalkanoate grades where Danimer Scientific's Kentucky fermentation capacity remains the primary qualified source for high-moisture packaging applications. Distribution runs through regional adhesive resellers providing technical service support to smaller converters lacking in-house formulation expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over microbial fermentation capacity and agricultural feedstock contracts determines long-term margin capture. Players are pursuing upstream control over PHA production to escape polymer-grade supply bottlenecks.
For Market Incumbents: Hedge against REACH authorization risks by accelerating EN 13432 dual certification investments ahead of ECHA's evolving substance evaluation roadmap. Secure long-term potato and corn starch supply contracts in Poland and Ukraine to buffer agricultural feedstock volatility. Build captive microbial fermentation partnerships to reduce reliance on external PHA suppliers for high-moisture flexible packaging grades. For New Entrants and Emerging Players: Regional adhesive resellers represent the most accessible channel partner type for penetrating mid-cap converter segments lacking technical specification expertise. Target Italian and Spanish flexible packaging clusters where industrial composting infrastructure gaps have slowed incumbent certification timelines. Qualify protein-based formulations for medical packaging applications where ISO 10993 biocompatibility standards exclude synthetic alternatives and command premium positioning. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap fermentation specialists with captive PHA production in North America and validated ASTM D6400 certification dossiers. Five-to-ten-year viability hinges on industrial composting infrastructure buildout keeping pace with regulatory mandate acceleration. Watch ECHA microplastics restriction enforcement thresholds as the inflection indicator for wash-off label adhesive substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microbial Fermentation | Captive PHA production escapes polyhydroxyalkanoate supply bottlenecks threatening high-moisture packaging grades. |
| Dual Certification Investment | ASTM D6400 and EN 13432 alignment secures pan-European distribution access under divergent composting protocols. |
| Long-term Agricultural Supply Agreement | Corn and potato starch contracts in Poland buffer climate-driven yield volatility compressing formulation margins. |
| Joint Venture with Industrial Composting Operator | Partnership with Northern European anaerobic digestion facilities validates home-compostable product claims. |
| Capacity Expansion in Medical Packaging Grade | Protein-based adhesive production for ISO 10993-compliant sterile barrier systems captures premium margin pools. |
Study Parameters
Multi-period observation of EU Green Deal regulatory implementation timelines, REACH authorization proceedings, and compostability certification volumes anchored the trend analysis, supplemented by interviews with formulation chemists at multinational adhesive suppliers, procurement directors at German flexible packaging converters, technical service managers at regional distributors, and sustainability officers at French retail chains. Secondary validation drew from ECHA substance evaluation databases, EU Packaging and Packaging Waste Directive implementation reports, ASTM D6400 and EN 13432 certification registries, and SEC filings of listed adhesive manufacturers. Bottom-up triangulation across product-grade volume estimates and top-down reconciliation against end-use application demand completed the analytical framework.
Segment-weighting approaches applied differential growth assumptions across polymer-based, starch-based, protein-based, and synthetic formulation categories, with further disaggregation by liquid, powder, gel, and film physical states. Food packaging, medical packaging, consumer goods, and industrial use applications were modeled separately with distinct regulatory compliance intensity factors. Geographic clusters reflected Germany's Verpackungsgesetz enforcement trajectory, France's AGEC law mandate acceleration, and Japan's METI circular economy target progression. CAGRs were derived from fitted growth curves calibrated to certification volume trajectories and converter qualification pipeline data.
Caveats apply where ECHA microplastics restriction final thresholds, industrial composting infrastructure buildout delays, or agricultural feedstock price spikes could materially shift the outlook. Forecasts embed assumptions regarding regulatory deadline adherence and certification body capacity expansion. Deviation in EU Green Deal packaging regulation enforcement timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
North America Biodegradable Plastic Market
Biodegradable Packaging
Biopolymer Packaging Market
Biodegradable Packaging
Asia-Pacific Biodegradable Film Market
Biodegradable Packaging
North America Biodegradable Film Market
Biodegradable Packaging
Biodegradable Lidding Films Market
Biodegradable Packaging
Bioplastic Packaging Market
Biodegradable Packaging
Asia-Pacific Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Global Biodegradable Films Market
Biodegradable Packaging
Biodegradable Cups Market
Biodegradable Packaging
Biodegradable Packing Peanuts Market
Biodegradable Packaging
Biofoam Packaging Market
Biodegradable Packaging
Bioplastic Packaging Bag Market
Biodegradable Packaging
Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Global Bioplastic Multi-Layer Films Market
Biodegradable Packaging
Biodegradable Cutlery Market
Biodegradable Packaging
Botanical Packaging Market