
 Biodegradable Cups Market | 2026-2036
Biodegradable Cups Market Size, Share, and Industry Trends Forecast 2026-2036
Biodegradable Cups Market Analysis
Polylactic acid is restructuring cost-performance trade-offs across the biodegradable cups sector as petrochemical resin prices fluctuate and brand owners face Scope 3 emissions targets. Huhtamaki leverages its integrated fiber-pulp network across Nordic production hubs to secure raw material continuity. Eco-Products, Inc. anchors North American distribution through direct partnerships with institutional foodservice operators. Stora Enso specializes in molded fiber engineering, converting renewable wood fibers into high-barrier cup stock without polyethylene liners.
Biodegradable cups are single-use beverage containers engineered to decompose through microbial action in industrial composting or soil environments, typically manufactured from polylactic acid biopolymer, bagasse pulp, or plant fibers with heat-seal coatings rated to 85-100°C liquid contact. Their primary commercial purpose is to replace conventional plastic-lined paper cups and polystyrene vessels in foodservice settings where municipal composting infrastructure exists. Pulp-based cups dominate current volume due to lower unit costs and established thermoforming equipment compatibility, while PLA grades capture premium positioning where clarity and printability matter. Plant fiber variants represent the fastest-growing category as manufacturers eliminate synthetic binders to meet home-compostable certifications. The wholesale distribution channel concentrates margin pools through long-term supply agreements with national restaurant chains, whereas direct sales to event operators exhibit higher per-unit pricing but greater order volatility.
The U.S. FDA governs food-contact substances in biodegradable cups through 21 CFR notification pathways, while the EPA's emerging per- and polyfluoroalkyl substances restrictions are forcing coating reformulations away from fluorinated oil-and-grease barriers. The EU Green Deal and F-Gas Regulation indirectly shape material economics by penalizing petrochemical-intensive alternatives and channeling R&D subsidies toward bio-based polymers. Stakeholders must monitor composting infrastructure build-out rates against production capacity expansion, as mismatches between certified product availability and actual industrial composting access determine real environmental performance and consumer willingness to pay premiums.
Market Dynamics
Extended producer responsibility laws in Germany, the United States, and Japan are forcing foodservice operators to internalize end-of-life packaging costs, restructuring procurement criteria toward certified compostable materials with verified decomposition pathways.
Growth Catalysts
- EU Green Deal packaging mandates:The EU Green Deal and F-Gas Regulation penalize petrochemical-intensive alternatives, channeling foodservice procurement toward bio-based polymers with lower Scope 3 emissions profiles.
- Bagasse pulp thermoforming:Sugarcane fiber processing advances enable heat-seal coatings rated to 100°C without synthetic binders, capturing institutional foodservice volume through home-compostable certification pathways.
- Quick-service restaurant procurement pivots:North American and European QSR chains are converting serveware specifications to compostable formats ahead of municipal polystyrene bans expanding across city jurisdictions.
Market Restraints
- Industrial composting access gaps:Mismatches between certified product availability and actual municipal composting infrastructure limit real environmental performance and consumer willingness to pay premiums.
- PLA resin price volatility:Polylactic acid biopolymer costs fluctuate with agricultural feedstock markets and petrochemical resin price movements, compressing margin stability for converters.
- Fluorinated barrier phase-out:EPA restrictions on per- and polyfluoroalkyl substances force coating reformulations, creating temporary supply interruptions as manufacturers validate alternative oil-and-grease barriers.
Strategic Opportunities
- Japanese extended producer responsibility expansion:METI enforcement of food-contact safety standards and packaging recycling mandates creates premium positioning for PLA grades with clarity and printability advantages.
- Event operator direct channels:Stadium and festival operators represent underdeveloped accounts with higher per-unit pricing tolerance and shorter decision cycles than national chain procurement.
- Wood fiber molded engineering convergence:Integration of renewable pulp networks with high-barrier coating technologies enables polyethylene-free cup stock for hot-fill applications previously reserved to plastic-lined paper.
Industry Challenges
- Composting certification timeline compression:Multi-jurisdiction standards including home-compostable, industrial-compostable, and marine-biodegradable require parallel testing protocols, extending product launch cycles.
- Thermoforming equipment reconfiguration:Legacy paper cup manufacturing assets require capital-intensive retrofits to process bagasse pulp and plant fiber formulations with different moisture and density profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Cups Market |
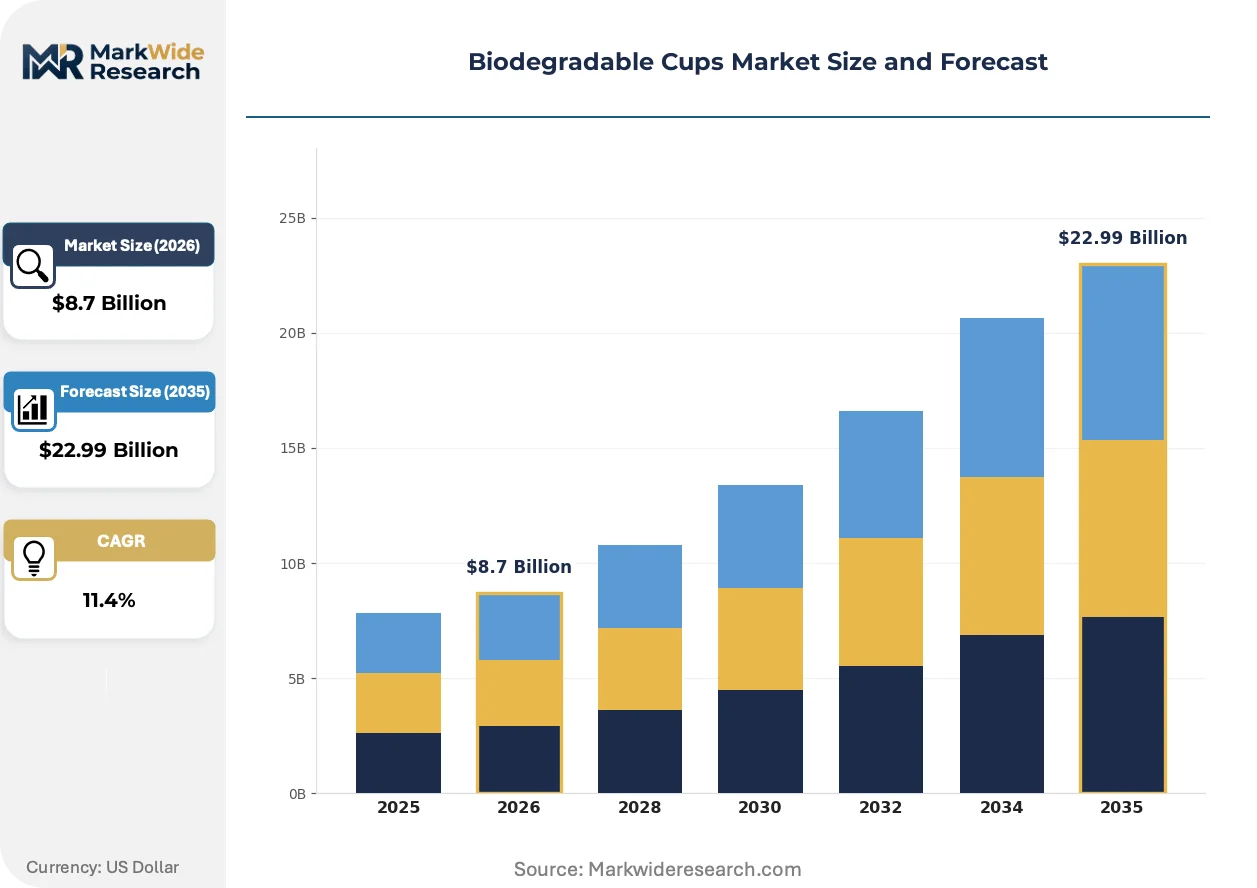
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pulp, PLA, Paper, Plant Fiber End User: Restaurants, Cafes, Events, Catering Distribution Channel: Online, Retail, Wholesale, Direct Sales Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Duni Group, Eco-Products, Inc., Sumkoka, Stora Enso, BioPak Pty Ltd, Pactiv Evergreen, Dart Container Corporation, Berry Global, Huhtamaki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Cups Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are converging to eliminate synthetic liners from hot beverage containers, while procurement centralization among institutional buyers accelerates specification consolidation.
Molded fiber engineering with renewable wood pulp is overtaking conventional polyethylene-lined paper cups in premium foodservice segments. Nordic production hubs are scaling thermoformed fiber capacity to serve quick-service chains with heat-seal coatings rated to 85-100°C liquid contact. This technology is overtaking legacy cup construction by enabling full industrial compostability without performance trade-offs in structural integrity or barrier function.
EPA per- and polyfluoroalkyl substances restrictions are forcing coating chemistry transitions across North American supply chains. Fluorinated oil-and-grease barriers face phase-out timelines, compelling manufacturers to validate silicone and clay-based alternatives through 21 CFR food-contact notification pathways. Hot-fill cup categories with extended hold times are experiencing the most intensive reformulation activity as brand owners preempt regulatory enforcement.
Institutional foodservice operators are consolidating supplier relationships around vertically integrated fiber-pulp networks. National restaurant chains are awarding multi-year supply agreements to converters with captive raw material sourcing, displacing fragmented distributor-mediated procurement. Germany and the United States exhibit the most pronounced concentration, where extended producer responsibility compliance costs favor partners with certified composting infrastructure partnerships.
Biodegradable Cups Market Segmentation
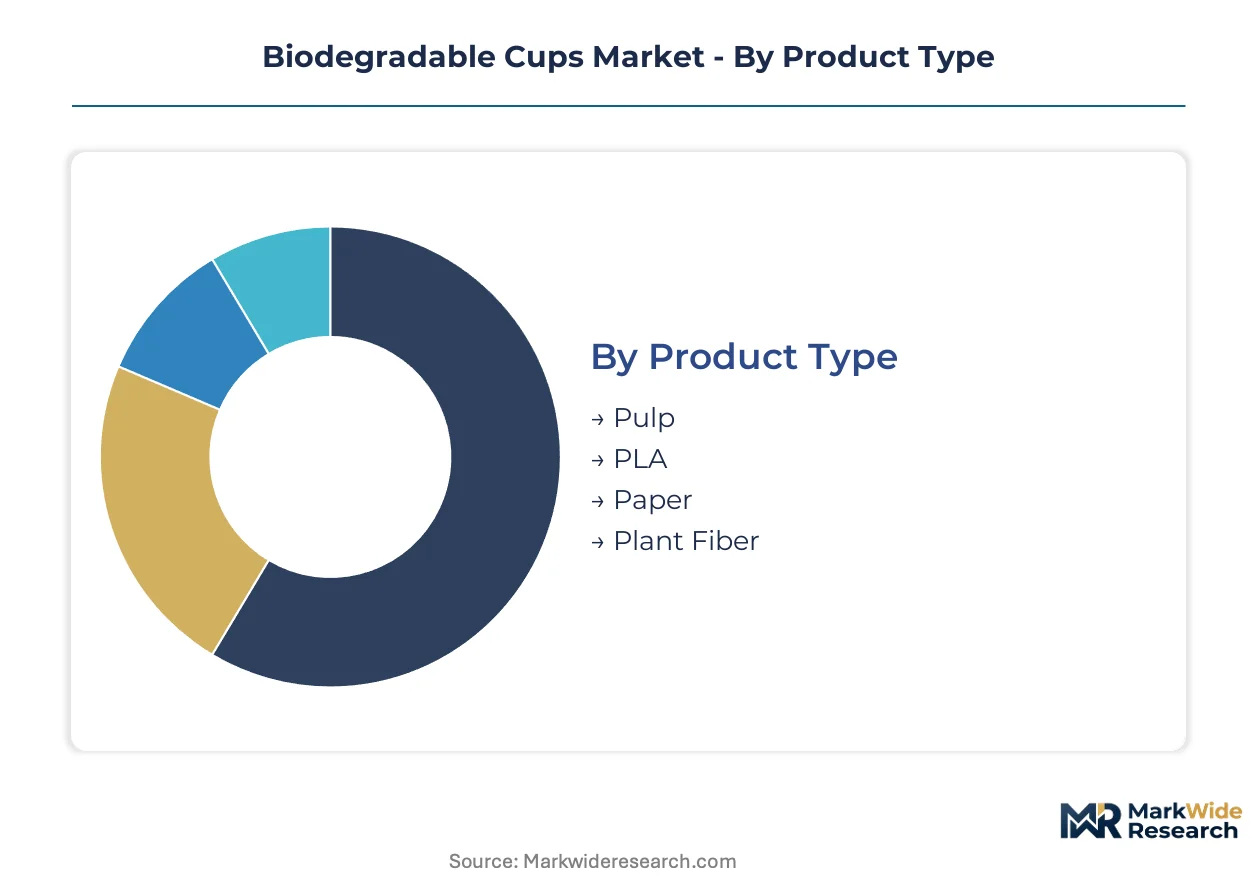
Material composition and distribution economics create divergent margin profiles across the biodegradable cups sector. Procurement specifications from quick-service chains and event operators are compressing supplier portfolios around certified compostable formats with verified heat tolerance.
Product Type:
Capital requirements vary sharply by formulation, with thermoforming equipment for plant fiber demanding the most substantial upfront investment versus legacy paper cup assets.
- Pulp:Bagasse and molded fiber formulations dominate current volume through established thermoforming infrastructure. Demand concentrates in German institutional foodservice where extended producer responsibility laws mandate certified compostable pathways.
- PLA:Polylactic acid biopolymer delivers clarity and printability advantages for premium positioning. Japanese quick-service chains favor PLA grades under METI enforcement of food-contact safety standards and packaging recycling mandates.
- Paper:Conventional paper cups with synthetic liners face coating reformulation pressure as EPA restrictions on fluorinated barriers take effect.
- Plant Fiber:Emerging formulations eliminate synthetic binders to capture home-compostable certification, though thermoforming equipment reconfiguration extends launch timelines.
Most installed capacity flows through Pulp. Expansion is steepest in Plant Fiber.
End User:
Customer procurement scale determines contract structure, with national chains extracting volume discounts unavailable to fragmented operators.
- Restaurants:Quick-service chains in the United States are consolidating supplier relationships around multi-year supply agreements with converters holding captive raw material sourcing.
- Cafes:Independent coffee shops exhibit higher per-unit pricing tolerance but greater order volatility than institutional accounts.
- Events:Stadium and festival operators represent underdeveloped accounts with shorter decision cycles and premium positioning for heat-seal coated formats.
- Catering:Contract foodservice providers face compressed margins from centralized procurement at parent hospitality groups.
Volume concentrates in Restaurants. Margin expansion is strongest in Events.
Distribution Channel:
Channel selection directly shapes working capital intensity and customer concentration risk for converters.
- Online:E-commerce penetration remains limited by bulk shipping economics and food-contact certification verification requirements.
- Retail:Consumer packaged goods formats face shelf-space competition from conventional disposables with lower unit costs.
- Wholesale:Distributor-mediated procurement concentrates margin pools through long-term agreements with national restaurant chains in Germany and the United States.
- Direct Sales:Converter-to-operator relationships eliminate intermediary margins but require dedicated account management infrastructure.
Revenue concentrates in Wholesale. Channel shift is most pronounced toward Direct Sales.
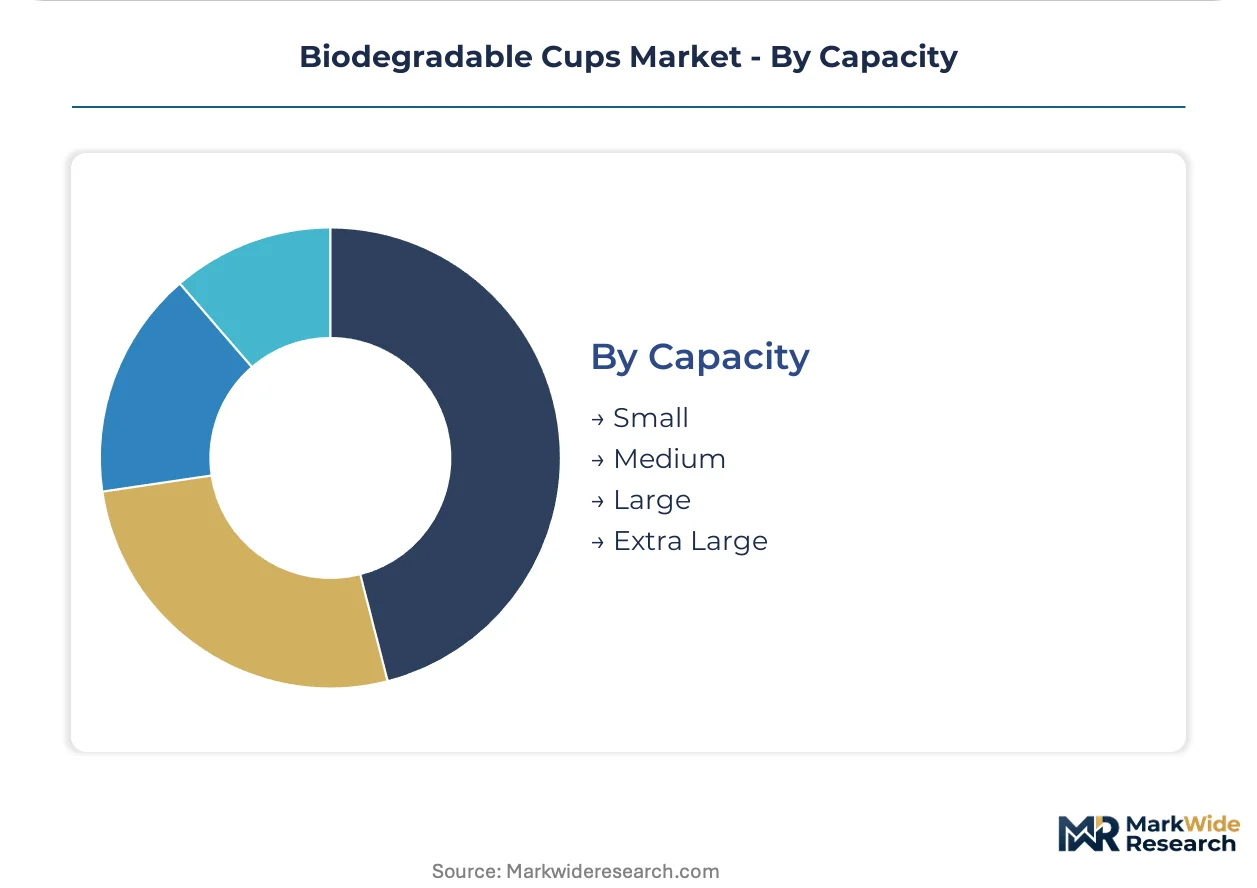
Capacity:
Size specification correlates with application heat-load and holding-time requirements, driving coating chemistry selection.
- Small:Espresso and sampling formats prioritize material cost minimization over extended barrier performance.
- Medium:Standard coffee servings represent the most contested specification tier with multiple certified suppliers.
- Large:Hot-fill applications with extended hold times experience intensive reformulation activity as brand owners preempt EPA enforcement on fluorinated barriers.
- Extra Large:Limited demand concentration in stadium and cinema concessions with specific vented-lid compatibility requirements.
Production volume peaks in Medium. Specification innovation is most active in Large.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German institutional foodservice operators anchor procurement volume for certified compostable serveware as extended producer responsibility laws restructure packaging cost allocation across municipal jurisdictions.
Germany
Quick-service chains and contract caterers drive specification consolidation toward bagasse pulp and molded fiber formats. The Packaging Act (VerpackG) mandates licensed disposal pathways for single-use foodservice items, creating compliance premiums for certified compostable alternatives. Industrial composting infrastructure in North Rhine-Westphalia and Bavaria processes high volumes of food-contaminated packaging, enabling closed-loop collection systems for national restaurant operators.
United States
Coastal municipalities with polystyrene bans accelerate converter demand for PLA and plant fiber cups. EPA restrictions on per- and polyfluoroalkyl substances force coating reformulations, particularly affecting hot-fill applications in the Northeast corridor. California's extended producer responsibility framework and Washington State's compostable product standards create dual compliance thresholds that favor suppliers with multi-certification capabilities.
Japan
METI enforcement of food-contact safety standards and packaging recycling mandates positions PLA grades for premium quick-service applications. Tokyo and Osaka metropolitan areas concentrate demand for clarity-optimized biopolymer cups in convenience store and café channels. The country's industrial composting network remains limited, creating reliance on certified incineration-compatible pathways for end-of-life management.
United Kingdom
London's foodservice density and municipal waste diversion targets sustain demand for home-compostable certified formats. The Environment Act's extended producer responsibility provisions phase in during the forecast window, restructuring procurement toward verified decomposition pathways. Scotland's separate collection requirements for food waste create regional specification divergence from English standards.
France
Parisian institutional catering and event operators exhibit elevated per-unit pricing tolerance for heat-seal coated fiber formats. The AGEC Law's plastic packaging reduction targets and reparability index requirements channel R&D investment toward polyethylene-free barrier technologies. Lyon and Marseille port logistics facilitate Nordic pulp import flows for molded fiber production serving Southern European markets.
Biodegradable Cups Market Vendor Landscape
Capacity expansion dominates the current landscape as converters retrofit legacy thermoforming assets for bagasse pulp and plant fiber processing. The supplier base organizes around three strategic archetypes: Nordic integrated pulp-fiber networks, North American distributor-anchored converters, and Asian mold specialists. M&A activity concentrates on captive raw material sourcing, while technology licensing partnerships accelerate coating chemistry transitions away from fluorinated barriers.
Within the integrated fiber-pulp tier, Huhtamaki and Stora Enso exemplify upstream control strategies that secure raw material continuity through Nordic production hub networks. Eco-Products, Inc. occupies a position in the North American distributor-mediated segment, anchoring procurement relationships with institutional foodservice operators. Duni Group represents the European specialist archetype with concentrated exposure to German and Scandinavian extended producer responsibility compliance markets.
| Leading Market Players |
|---|
| Duni Group |
| Eco-Products, Inc. |
| Sumkoka |
| Stora Enso |
| BioPak Pty Ltd |
| Pactiv Evergreen |
| Dart Container Corporation |
| Berry Global |
| Huhtamaki |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap converters across Germany and the Nordic region anchor pricing discipline through multi-year supply agreements with institutional foodservice operators, insulating margin pools from spot-market volatility in agricultural feedstocks while concentrating procurement leverage around certified compostable specifications.
Pricing Analysis
Agricultural feedstock volatility passes through directly to PLA resin quotations, compressing converter margins when corn or sugarcane prices spike. Pricing stratifies across premium PLA grades with FDA food-contact clearance, standard bagasse pulp formats with industrial-compostable certification, and economy paper cups facing coating reformulation costs. Price differentiation centers on certification tier and volume scale, with national restaurant chains extracting steep discounts through captive sourcing agreements. Cost compression in the economy tier is intensifying as fluorinated barrier phase-outs force chemistry transitions, while premium positioning holds firm in Japanese quick-service channels under METI enforcement.
Supply Chain Analysis
Bagasse pulp supply rests on Brazilian and Indian sugarcane processing capacity, while Nordic wood fiber networks feed molded fiber engineering hubs in Finland and Sweden. PLA biopolymer production concentrates in Nebraska and Thailand, drawing from corn starch and cassava feedstocks respectively. Single-source vulnerability runs through specialty heat-seal coating chemicals facing EPA restriction timelines. Distribution runs through wholesale distributor networks in Germany and the United States, with direct converter-to-operator relationships gaining share in event catering channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biodegradable cups market compounds steadily as extended producer responsibility laws across Germany, the United States, and Japan permanently restructure packaging cost allocation toward verified compostable pathways.
For Market Incumbents: Cement raw material security through backward integration into Nordic pulp networks or captive bagasse sourcing partnerships in Brazil. Fortify certification moats by accelerating multi-jurisdiction testing for home-compostable standards ahead of competitor launch timelines, as coating chemistry transitions away from fluorinated barriers threaten legacy product lines. For New Entrants and Emerging Players: The premium-to-economy price gap in Japanese convenience store channels offers white-space positioning for clarity-optimized PLA grades with printability advantages. Stadium and festival operators represent the most penetrable segment, with shorter procurement cycles and higher per-unit pricing tolerance than national chain accounts. Pursue direct sales infrastructure bypassing wholesale distributor margins. For Investors and Strategic Acquirers: Valuations sit cheapest among European specialists with concentrated German Packaging Act compliance exposure but limited Nordic pulp network control. The five-to-ten year viability window favors targets with captive raw material sourcing and multi-certification capabilities. Watch industrial composting infrastructure build-out rates in target metropolitan areas as the critical inflection signal for realized environmental performance and consumer premium willingness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Networks | Huhtamaki's Nordic hub model secures raw material continuity against agricultural price spikes. |
| Multi-Jurisdiction Certification Investment | Parallel home-compostable and industrial-compostable testing extends product launch timelines but locks out competitors. |
| Coating Chemistry Transition | Silicone and clay-based barrier validation through FDA 21 CFR pathways preempts EPA enforcement on fluorinated alternatives. |
| Direct Channel Development | Eco-Products' institutional foodservice partnerships eliminate distributor margins and accelerate specification consolidation. |
| Event Operator Penetration | Stadium and festival accounts offer premium positioning with shorter decision cycles than national chain procurement. |
Methodological Framework
Direct dialogue with foodservice procurement directors, packaging converters, composting facility operators, and regulatory compliance officers grounded the qualitative foundation, cross-referenced against secondary sources including FDA 21 CFR notification databases, EPA chemical restriction dockets, EU Green Deal implementation reports, and German Packaging Act licensing records. Bottom-up and top-down triangulation validated volume estimates across material formulations and end-use segments.
Bottom-up modeling built from individual converter capacity announcements and foodservice chain procurement specifications, while top-down analysis cross-checked against municipal composting infrastructure deployment rates and extended producer responsibility fee schedules. Segmentation dimensions included material composition, end-user category, distribution channel, and capacity specification, with CAGRs derived from trend extrapolation in regulatory enforcement timelines and procurement contract durations. Feedstock price elasticity and coating chemistry transition costs informed margin projections.
Caveats apply where industrial composting access gaps, PLA resin price volatility, or fluorinated barrier phase-out delays could materially shift the outlook. A small set of named triggers—municipal infrastructure build-out rates, agricultural commodity movements, and EPA enforcement timing—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Biofoam Packaging Market
Biodegradable Packaging
Global Biodegradable Tableware Market
Biodegradable Packaging
Biodegradable Plastic Bags and Sacks Market
Biodegradable Packaging
Global Bioplastic Multi-Layer Films Market
Biodegradable Packaging
Compostable Shrink Wrap Market
Biodegradable Packaging
Biodegradable Meal Trays Market
Biodegradable Packaging
Starch-Based Bioplastics Packaging Market
Biodegradable Packaging
Asia-Pacific Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Biopolymer Packaging Market
Biodegradable Packaging
Biodegradable Food Packaging Market
Biodegradable Packaging
Asia-Pacific Biodegradable Film Market
Biodegradable Packaging
Botanical Packaging Market
Biodegradable Packaging
Biodegradable Packaging Market
Biodegradable Packaging
North America Biodegradable Film Market
Biodegradable Packaging
Middle East and Africa Biodegradable Film Market
Biodegradable Packaging
Bioadhesives for Packaging Market