
 Bioplastic Packaging Bag Market | 2026-2036
Bioplastic Packaging Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Bioplastic Packaging Bag Market Outlook
Food service distributors and quick-service restaurant chains is redrawing procurement priorities away from conventional plastic. Novamont S.p.A. anchors European supply through vertically integrated starch-based resin production. BASF SE leverages polymer research infrastructure to compete in high-performance barrier films. NatureWorks LLC dominates North American PLA feedstock capacity with captive corn sugar sourcing.
Bioplastic packaging bags are thermoformed or blown films derived from renewable feedstocks such as polylactic acid, polyhydroxyalkanoates, or thermoplastic starch, engineered to meet ASTM D6400 or EN 13432 compostability standards while providing moisture and oxygen barrier performance for perishable containment. Stand-up pouches lead value contribution due to premium positioning in organic and specialty food segments. Starch-based materials sustain volume leadership in cost-sensitive garbage bag applications across municipal collection contracts. PLA competes in refrigerated food packaging where clarity and seal integrity match petrochemical benchmarks.
The EU Green Deal, EN 13432 compostability certification, and FDA food contact notifications collectively determine which formulations gain shelf placement in regulated channels. ECHA bio-based content verification under the EU Taxonomy is forcing reformulation investments among film converters. Stakeholders must monitor whether post-consumer composting infrastructure expansion keeps pace with mandated biodegradable packaging quotas.
Market Dynamics
The EU Green Deal and F-Gas Regulation are forcing food packaging chains to replace conventional polyethylene with compostable alternatives, creating procurement urgency across European retail and food service channels.
Growth Catalysts
- Extended Producer Responsibility schemes:Germany, France, and Italy mandate biodegradable content thresholds in single-use packaging, compelling brand owners to reformulate film specifications.
- Organic and specialty food retail expansion:Stand-up pouch demand concentrates in premium grocery segments where compostable certification commands shelf placement.
- Polylactic acid clarity performance:PLA film seal integrity now matches petrochemical benchmarks in refrigerated food packaging, unlocking dairy and fresh produce applications.
Market Restraints
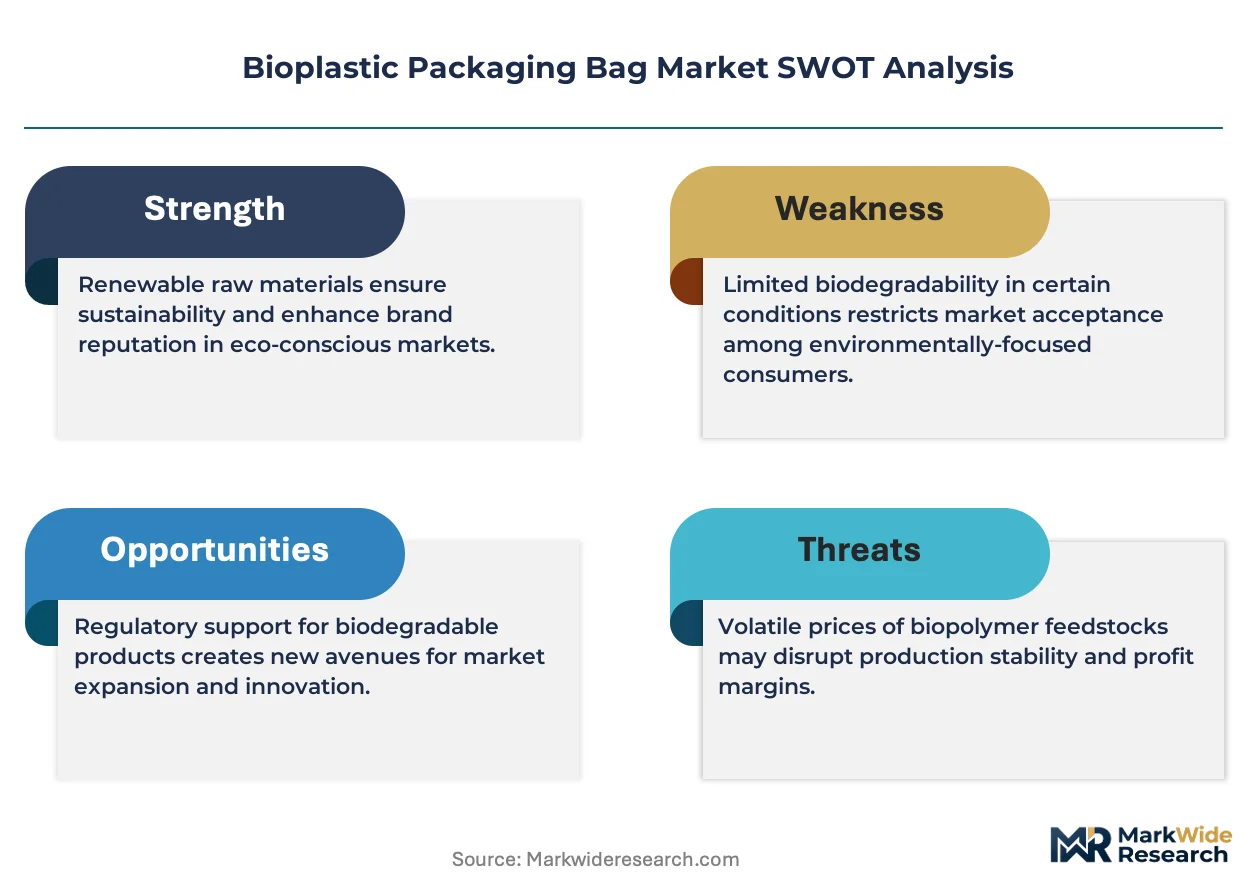
- Corn sugar feedstock volatility:PLA resin costs fluctuate with agricultural commodity markets, compressing converter margins during harvest disruptions.
- European resin supply concentration:Starch-based biopolymer production clusters in Northern Italy, exposing buyers to regional logistics bottlenecks.
- Post-consumer composting infrastructure gaps:Municipal collection systems in Eastern Europe lack industrial composting capacity, undermining EN 13432 compliance claims.
Strategic Opportunities
- North American PLA capacity expansion:Corn belt proximity to resin plants enables cost-competitive supply for quick-service restaurant chains seeking packaging conversions.
- ECHA bio-based content verification:EU Taxonomy alignment creates premium positioning for film converters with third-party certified supply chains.
- Barrier coating convergence:Combining thermoplastic starch substrates with bio-based oxygen scavengers opens modified-atmosphere packaging for protein applications.
Industry Challenges
- ASTM D6400 and EN 13432 dual certification timelines:Film converters face 18-24 month validation cycles to access both North American and European regulated channels simultaneously.
- Polymer processing skill scarcity:Thermoforming and blown film technicians trained on conventional PE/PP equipment require retraining for bioplastic melt rheology and temperature sensitivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioplastic Packaging Bag Market |
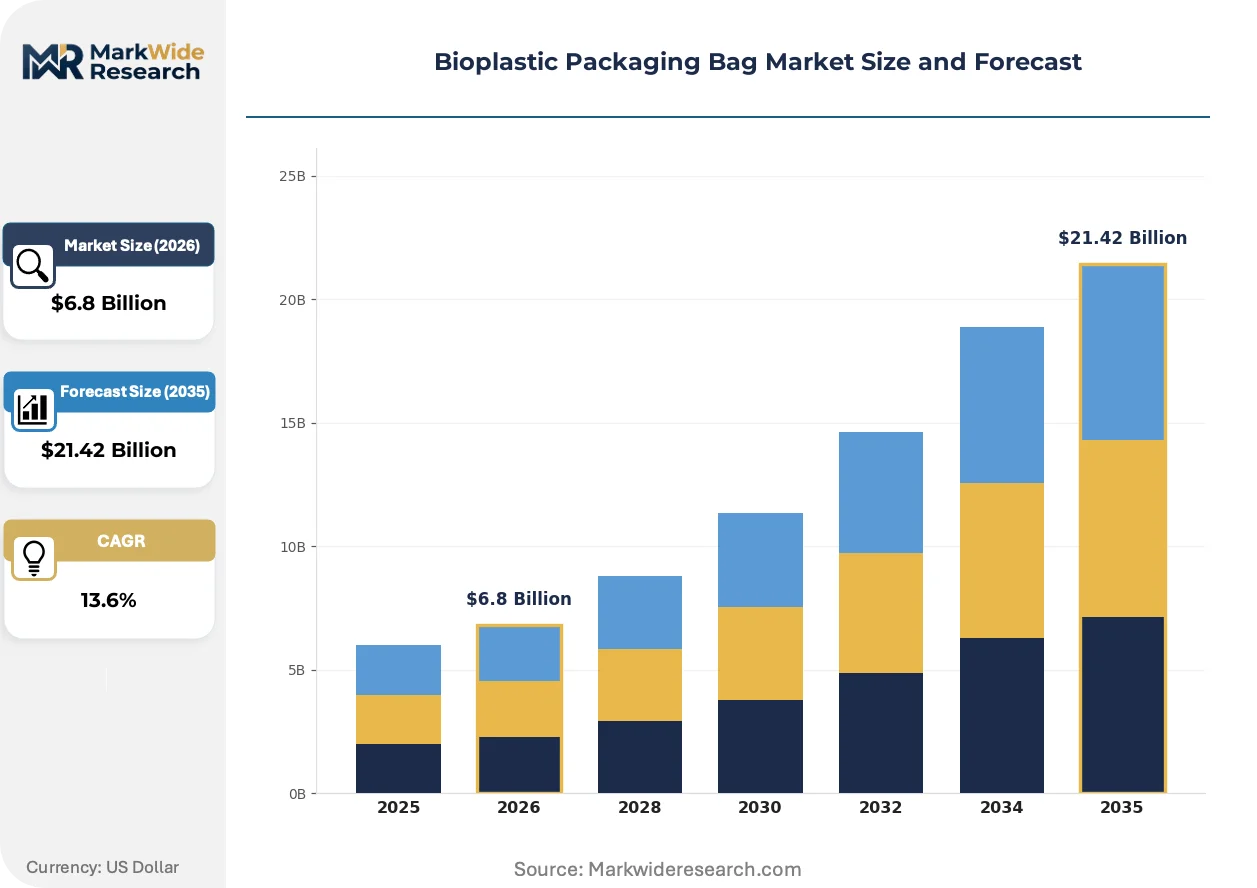
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.42 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Stand-Up Pouches, Roll Bags, Garbage Bags Material: PLA, PHA, Starch-Based, Cellulose End User: Food Packaging, Retail Sector, Healthcare, Consumer Goods Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Novamont S.p.A., BASF SE, NatureWorks LLC, Mitsubishi Chemical Holdings, Biome Bioplastics, Braskem S.A., Amcor plc, TotalEnergies Corbion, BioBag International A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioplastic Packaging Bag Market Strategic Shifts
Active barrier technologies and feedstock diversification are compressing performance gaps between bioplastics and petrochemical films while regulatory verification systems reshape competitive access.
Multilayer coextrusion with bio-based tie layers is decomposing the traditional trade-off between compostability and moisture protection. European fresh produce distributors are adopting these structures for breathable lidding films. The technology is decomposing incumbent monolayer PLA specifications in premium salad packaging.
REACH bio-based content thresholds under the EU Taxonomy are forcing reformulation investments among film converters. ECHA verification protocols now determine institutional procurement eligibility. German retail cooperatives are prioritizing suppliers with completed ECHA dossiers for private-label organic lines.
Certification-driven supplier qualification is compressing vendor selection cycles. Food service distributors now require ASTM D6400 or EN 13432 documentation before contract negotiation rather than post-qualification. This pattern is most visible in French and Italian quick-service restaurant chain procurement, where sustainability scorecards determine approved vendor lists.
Bioplastic Packaging Bag Market Segmentation
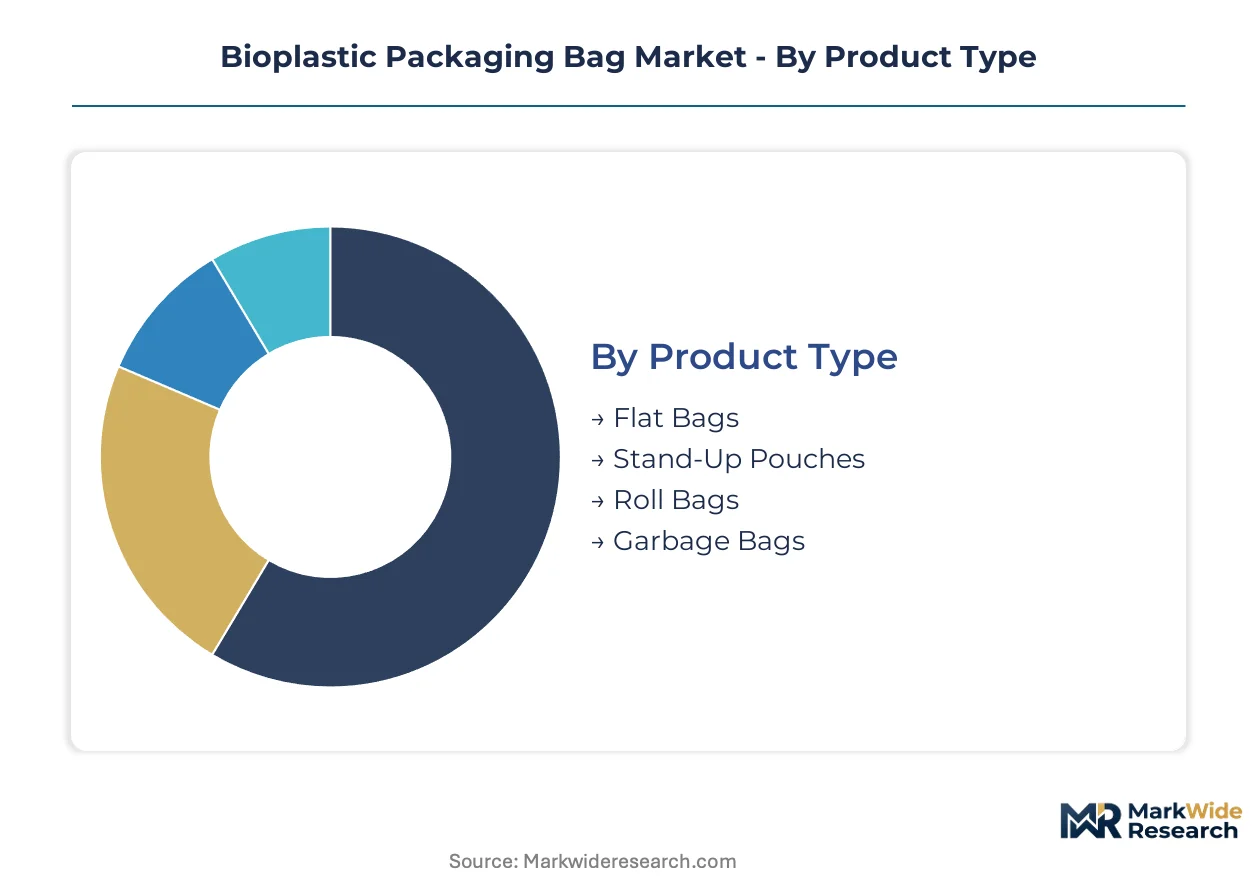
Bioplastic packaging bags fragment across four structural dimensions that determine pricing power, certification requirements, and supply chain configuration. Each segment carries distinct technical specifications and regulatory obligations that reshape procurement patterns for film converters and brand owners.
Product Type:
Flat bags dominate domestic consumption in municipal waste collection contracts across Germany and Italy, while stand-up pouches anchor export-oriented premium food packaging demand.
- Flat Bags:Thermoformed or side-sealed films engineered for high-volume, low-margin applications. German municipal procurement mandates EN 13432 certification, locking in starch-based formulations for organic waste diversion programs.
- Stand-Up Pouches:Multilayer coextruded structures with resealable zipper closures and bottom gussets. French organic food retailers specify these for premium private-label lines where compostable certification commands shelf placement and price premiums.
- Roll Bags:Continuous perforated films on cores for industrial and food service dispensing. Italian fresh produce distributors favor these for breathable lidding applications.
- Garbage Bags:Heavy-duty starch-based films for organic waste collection. Cost-sensitive specifications concentrate volume in municipal contracts across Northern Europe.
Flat bags hold the largest share; momentum sits with stand-up pouches.
Material:
Cost tiers separate commodity starch resins from performance-grade PLA and PHA, with cellulose occupying a narrow specialty niche for moisture-sensitive applications.
- PLA:Corn-derived polylactic acid offering optical clarity and heat sealability comparable to petrochemical films. Refrigerated dairy packaging in France and Belgium drives specification, though corn sugar price volatility compresses converter margins during harvest disruptions.
- PHA:Microbially produced polyhydroxyalkanoates with marine biodegradability credentials. Marine and soil-compostable claims attract premium outdoor and agricultural film applications where ASTM D6400 alone proves insufficient.
- Starch-Based:Thermoplastic starch blends with synthetic aliphatic polyesters. Lowest unit cost positions these for high-volume garbage bag and retail carryout bag segments.
- Cellulose:Regenerated wood pulp films with high moisture vapor transmission rates. Narrow demand in breathable produce packaging and medical sterilization wraps.
Starch-based materials command volume leadership; PLA exhibits the steepest expansion trajectory in food-contact applications.
End User:
Application maturity varies sharply: food packaging carries the most stringent regulatory burden, while healthcare penetration remains constrained by sterilization validation timelines.
- Food Packaging:Modified-atmosphere and refrigerated containment requiring oxygen barrier performance. EU Green Deal procurement mandates and EFSA food contact notifications dominate supplier qualification.
- Retail Sector:Branded carryout bags and merchandise sacks. Extended Producer Responsibility schemes in France and Italy mandate minimum bio-based content thresholds.
- Healthcare:Sterile barrier packaging for medical devices and pharmaceutical components. FDA 510(k) and MDR compliance cycles extend qualification timelines beyond standard film procurement.
- Consumer Goods:Personal care and household product overwraps. Lower regulatory barriers attract cost-optimized starch formulations.
Food packaging absorbs the dominant share; retail sector specifications are expanding most quickly under EPR enforcement.
Distribution Channel:
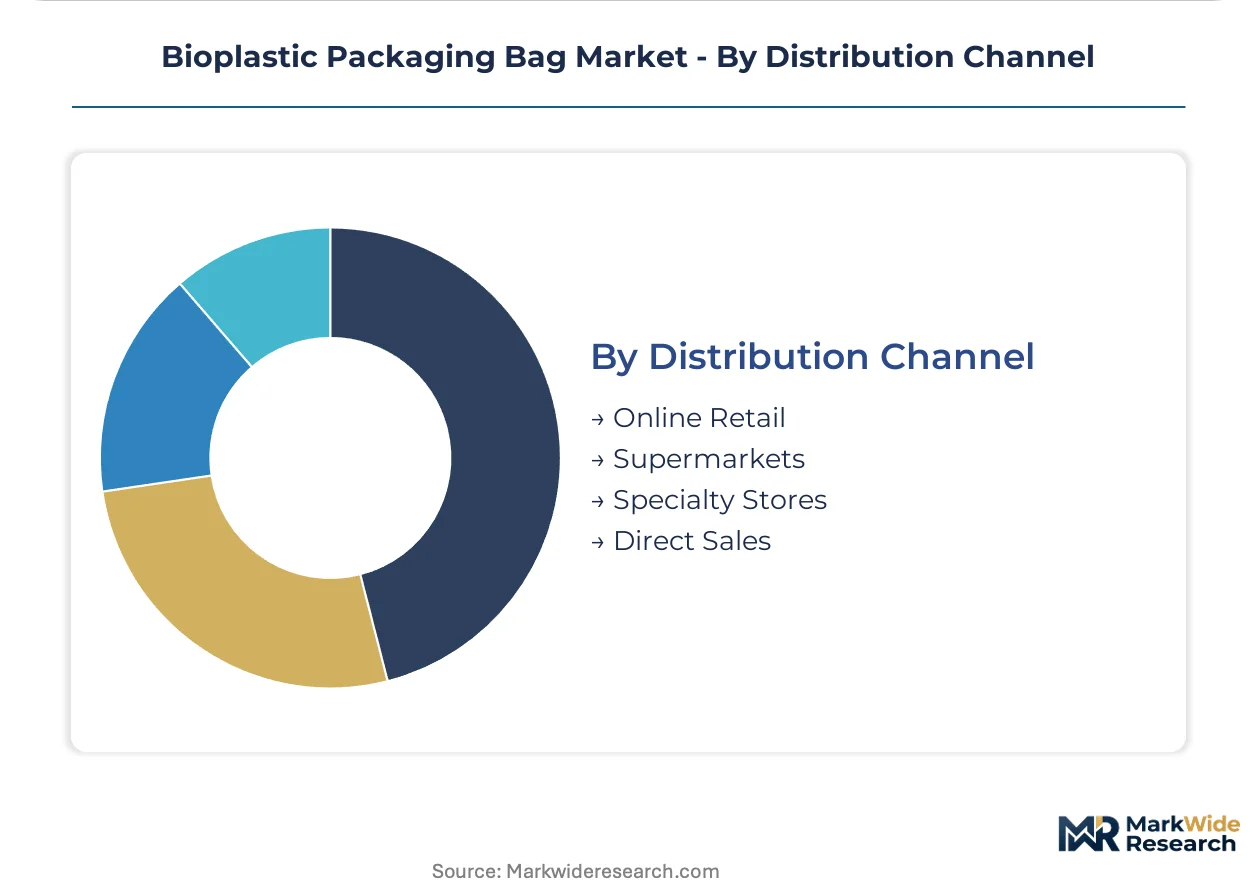
Channel concentration reflects customer scale: direct sales capture institutional volume, while specialty stores serve fragmented artisanal food producers.
- Online Retail:E-commerce platforms serving small-batch food producers and sustainability-focused consumers. Certificate transparency requirements favor suppliers with completed ECHA dossiers.
- Supermarkets:Centralized procurement for private-label organic lines. German retail cooperatives prioritize vendors with dual ASTM D6400 and EN 13432 certification.
- Specialty Stores:Independent organic grocers and zero-waste shops. Smaller order quantities and SKU proliferation favor regional film converters.
- Direct Sales:Long-term supply contracts with quick-service restaurant chains and food service distributors. French and Italian chains now require compostable documentation before contract negotiation.
Direct sales secure the largest volume commitments; online retail is gaining share fastest among emerging food brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian starch-based resin exports supply German and French converters under EU Green Deal procurement mandates. Cross-border film trade flows through Northern Italian production clusters toward Central European packaging distributors.
Germany
Municipal organic waste collection contracts drive flat bag specifications across Bavaria and North Rhine-Westphalia. Extended Producer Responsibility enforcement under the Packaging Act mandates minimum bio-based content thresholds. The Rhine-Main industrial corridor hosts film converters retraining thermoforming technicians for starch-based melt rheology.
France
Quick-service restaurant chains specify compostable carryout bags under national plastic ban extensions. ECHA bio-based content verification determines institutional procurement eligibility for private-label organic lines. The Lyon-Grenoble cluster concentrates multilayer coextrusion capacity for breathable produce lidding films.
Italy
Extended Producer Responsibility schemes in Lombardy and Emilia-Romagna lock in biodegradable garbage bag demand. Novamont S.p.A. anchors European supply through captive starch resin production in Northern Italy. The Po Valley industrial belt faces logistics bottlenecks exposing buyers to regional supply concentration risk.
United States
Corn belt proximity to PLA feedstock plants enables cost-competitive supply for food service distributors. FDA food contact notifications govern refrigerated dairy packaging specifications in Wisconsin and California. NatureWorks LLC dominates North American resin capacity with integrated corn sugar sourcing.
China
Domestic biopolymer production scales under dual carbon goals targeting petrochemical substitution. SAMR standards and GB certification frameworks reshape film converter qualification requirements. The Yangtze River Delta concentrates blown film equipment manufacturing for export-oriented packaging machinery.
Bioplastic Packaging Bag Market Competitive Environment
Listed leaders compete with private specialists across resin production and film conversion capabilities. The vendor base fragments vertically: upstream biopolymer manufacturers supply downstream converters with certified feedstock. Three archetypes dominate—integrated resin-to-film producers, specialist converters, and petrochemical diversifiers. Capacity expansion and ECHA dossier completion represent the dominant competitive moves securing procurement eligibility.
Within the integrated production tier, Novamont S.p.A. and BASF SE exemplify European anchoring positions through upstream resin control. NatureWorks LLC represents North American PLA specialization. Specialist converters including BioBag International A/S occupy certification-driven niche positions. Mitsubishi Chemical Holdings and TotalEnergies Corbion exemplify petrochemical incumbent diversification strategies. Amcor plc and Braskem S.A. represent packaging conglomerate and regional chemical player archetypes respectively.
| Leading Market Players |
|---|
| Novamont S.p.A. |
| BASF SE |
| NatureWorks LLC |
| Mitsubishi Chemical Holdings |
| Biome Bioplastics |
| Braskem S.A. |
| Amcor plc |
| TotalEnergies Corbion |
| BioBag International A/S |
| Others |
Value Chain & Pricing Dynamics
Eighteen-month EN 13432 certification cycles lock converter working capital into inventory-heavy positions, concentrating pricing power with upstream resin producers in Northern Italy while squeezing film converter margins across German and French procurement channels.
Pricing Analysis
Current-generation PLA films command premium positioning against incumbent starch-based formulations and next-generation PHA marine-biodegradable alternatives. Three-tier pricing structure across premium, standard, and economy levels separates ECHA-verified multilayer films from single-specification commodity grades, with certification grade and volume scale driving price differentiation. Pricing pressure stems from corn sugar feedstock volatility compressing converter margins during harvest disruptions. Municipal procurement offices exhibit highest price sensitivity, while quick-service restaurant chains prioritize certification compliance over unit cost.
Supply Chain Analysis
Port congestion on Rotterdam-Antwerp container routes elevates inbound logistics costs for Asian biopolymer equipment, exposing European film converters to delivery uncertainty. Resin production concentrates in Italy, the United States, and Thailand, drawing from corn sugar, cassava starch, and sugarcane bagasse feedstocks. Supply chain risk centers on single-source vulnerability in Novamont's Northern Italian starch resin cluster. Distribution runs through direct long-term contracts with food service distributors and centralized supermarket procurement cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bioplastic packaging functions as a platform economy where ECHA verification protocols and composting infrastructure interoperability determine ecosystem access, with EU Taxonomy alignment serving as the critical network-effect enabler.
For Market Incumbents: Compound certification advantages by completing ASTM D6400 and EN 13432 dual dossiers before procurement qualification windows close, defending against specialty converter entrants through captive starch resin supply in Northern Italy. Priority levers include multilayer coextrusion R&D investment and backward integration into corn sugar sourcing. For New Entrants and Emerging Players: Post-consumer composting infrastructure gaps in Eastern Europe represent the most penetrable service-layer gap, where industrial composting capacity lags mandated biodegradable packaging quotas. Target Polish and Romanian municipal collection contracts with lower certification barriers, deploying mobile composting unit partnerships as the go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because EU Green Deal enforcement and EPR scheme expansion create structural demand inelasticity. Acquisition targets should display completed ECHA dossiers and multilayer film capabilities. Watch composting infrastructure buildout rates in Eastern Europe as the inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | ASTM D6400 and EN 13432 completion unlocks German and French institutional procurement channels simultaneously. |
| Backward Integration into Feedstock | Corn sugar sourcing control insulates PLA resin margins from agricultural commodity volatility. |
| Multilayer Coextrusion Capacity | Bio-based oxygen barrier films penetrate modified-atmosphere protein packaging previously closed to bioplastics. |
| ECHA Dossier Completion | EU Taxonomy alignment secures premium positioning with German retail cooperatives and French organic lines. |
| Eastern European Infrastructure Partnership | Industrial composting facility joint ventures close the compliance gap for EN 13432 claims in Poland and Romania. |
Study Parameters
Operator-level perspectives from film converter plant managers, quick-service restaurant procurement directors, supermarket category buyers, and municipal waste collection contract officers anchored the qualitative base. Primary interview insights combined with secondary validation from EU customs trade data, ECHA bio-based content registries, EN 13432 certification databases, and SEC filings of listed packaging conglomerates. Bottom-up resin capacity modeling and top-down food packaging demand estimation were triangulated across the analysis window.
Sensitivity analysis tested forecast outputs against feedstock price volatility bands and composting infrastructure deployment scenarios. Segmentation dimensions modeled include product structure, material chemistry, end-use application, and distribution channel, with regional regulatory cluster and certification tier as additional bioplastic-specific variables. CAGRs were derived from installed resin capacity trajectories and EPR mandate enforcement schedules, incorporating corn sugar price elasticity and multilayer film adoption curves.
Forecasts assume regulatory continuity in EU Green Deal implementation and EPR scheme enforcement; material policy shifts would require re-modeling. Corn harvest disruption frequency, PLA resin plant commissioning delays, and municipal composting facility permitting timelines represent specific risk factors that could revise projections. Practitioners should keep alternative scenarios live as Eastern European infrastructure buildout and ECHA verification protocol updates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Global Biodegradable Tableware Market
Biodegradable Packaging
Biodegradable Meal Trays Market
Biodegradable Packaging
Botanical Packaging Market
Biodegradable Packaging
Asia-Pacific Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Biofoam Packaging Market
Biodegradable Packaging
Biodegradable Food Packaging Market
Biodegradable Packaging
Biodegradable Plastic Bags and Sacks Market
Biodegradable Packaging
Biodegradable Packaging Materials Market
Biodegradable Packaging
Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Europe Biodegradable Film Market
Biodegradable Packaging
Europe Biodegradable Cups Market
Biodegradable Packaging
Biodegradable Packaging Market
Biodegradable Packaging
North America Biodegradable Plastic Market
Biodegradable Packaging
Oxo Biodegradable Bags Market
Biodegradable Packaging
Biodegradable Packing Peanuts Market
Biodegradable Packaging
Bioplastic Packaging Market