
 Biodegradable Packaging Materials Market | 2026-2036
Biodegradable Packaging Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Biodegradable Packaging Materials Market Analysis
The gap between certified compostable films and basic starch-based loose fill is repositioning tier strategy across the value chain. Huhtamäki sustains leadership in molded fiber formats for foodservice applications. Stora Enso leverages its integrated pulp-to-packaging pipeline to control fiber sourcing. TIPA specializes in flexible barrier films that match conventional plastic performance.
Biodegradable packaging materials are polymers and fiber-based substrates engineered to decompose through microbial action under composting conditions, typically achieving breakdown within 180 days in industrial facilities and serving to replace petroleum-derived packaging across consumer and industrial supply chains. PLA dominates current production volumes due to mature fermentation infrastructure and thermal processability, while PHA commands premium positioning because of marine biodegradability and broader composting compatibility. Rigid containers anchor the form segment in food and beverage applications where dimensional stability protects perishables, whereas films represent the fastest-expanding category as e-commerce brands seek lightweight protective wraps with end-of-life credentials.
The EU Green Deal and F-Gas Regulation shape material innovation targets and carbon accounting requirements across European manufacturing bases, while FDA food-contact notifications govern PLA and PHA substrate approvals in United States distribution channels. Stakeholders must track how composting infrastructure buildout pace in target markets aligns with certification claims and consumer disposal behavior.
Market Dynamics
EU Green Deal enforcement timelines are compressing substitution cycles across food-contact applications, forcing material suppliers to validate compostability claims against industrial facility availability before product launch.
Growth Catalysts
- EU Single-Use Plastics Directive:France and Germany mandate minimum recycled and renewable content thresholds for foodservice items, redirecting procurement budgets toward certified compostable alternatives.
- Extended Producer Responsibility schemes:Netherlands packaging levies penalize non-recyclable formats, creating direct cost incentives for biodegradable material adoption in e-commerce fulfillment.
- PHA fermentation scale-up:Marine-biodegradable polymer production is automating quality control protocols, reducing batch-to-batch variation that previously limited food-contact approvals.
Market Restraints
- Industrial composting infrastructure gaps:Facility concentration in Northern Europe leaves Southern and Eastern European markets without adequate end-of-life pathways for certified materials.
- Feedstock cost volatility:Corn starch and sugarcane bagasse prices fluctuate with agricultural commodity cycles, compressing margins for PLA and molded fiber producers during harvest shortfalls.
- Performance limitations in high-moisture environments:Barrier properties of uncoated cellulose degrade above 85% relative humidity, restricting shelf-life extension for fresh-produce applications.
Strategic Opportunities
- Underpenetrated cold-chain logistics:Poland and Romania lack temperature-controlled biodegradable insulation standards, creating first-mover space for PHA-based foam replacements.
- Reuse-system integration:Deposit-return schemes in Denmark and Sweden are automating collection infrastructure that can accommodate compostable single-use liners for reusable container pools.
- CSRD-aligned carbon accounting:Scope 3 disclosure requirements are automating supplier audits, favoring packaging vendors with certified lifecycle data over conventional plastic competitors.
Industry Challenges
- Composting certification timeline compression:TÜV Austria and DIN CERTCO review queues extend 14-18 months for novel multilayer films, delaying market entry beyond customer contract windows.
- Legacy equipment retrofit costs:Thermoforming lines engineered for PET and PP require screw, barrel, and cooling modifications to process PLA without thermal degradation, demanding capital commitments many mid-tier converters avoid.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Packaging Materials Market |
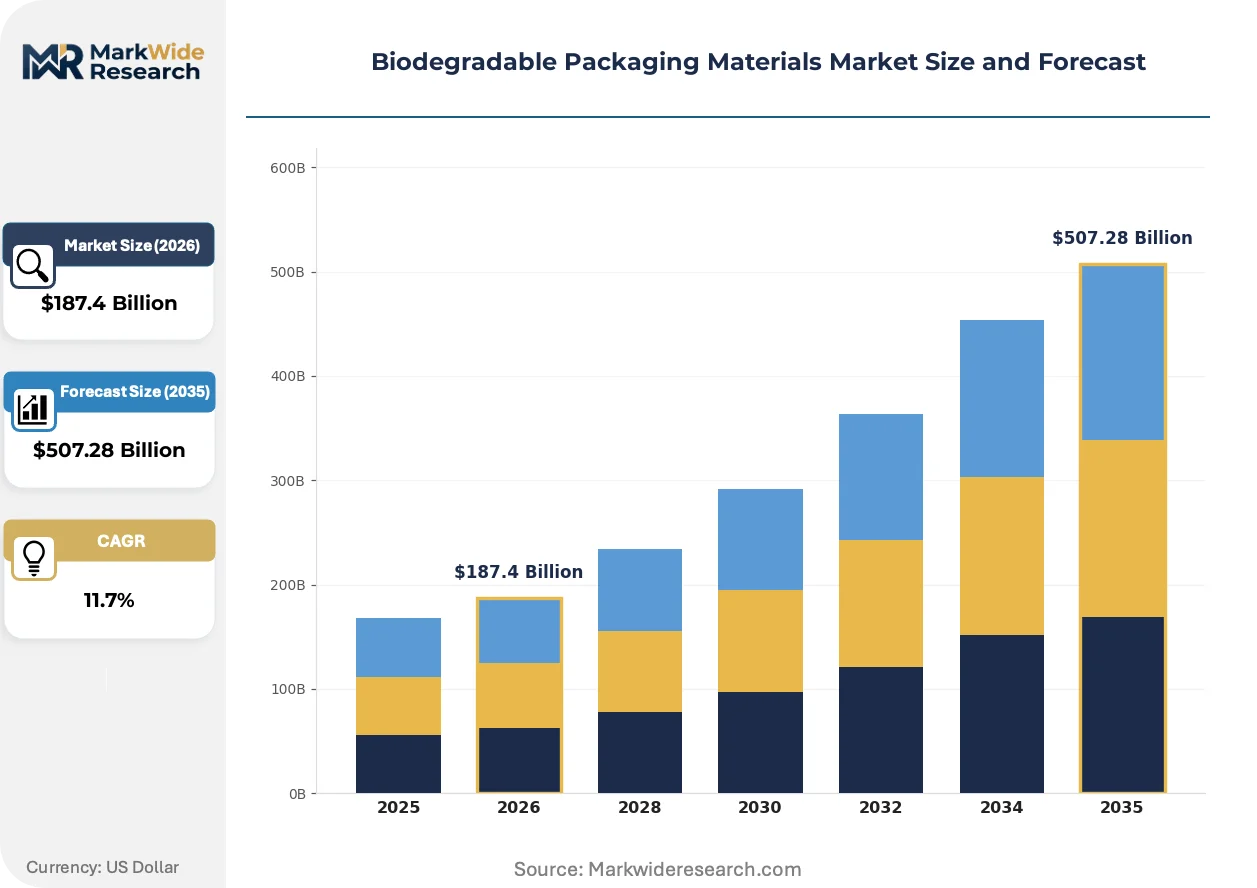
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $507.28 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLA, PHA, Starch-based, Paper End Use Industry: Food & Beverage, Healthcare, Personal Care, Electronics Form: Films, Rigid Containers, Bags, Trays Distribution Channel: Online, Hypermarkets, Supermarkets, Specialty Stores |
| Companies Covered | Xiamen Bioleader, Stora Enso, Huhtamäki, Tetra Pak, TIPA, BioPak, Pactiv Evergreen, Amcor, Vegware, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Packaging Materials Market Emerging Trajectories
Material science advances are collapsing the performance gap between biodegradable substrates and petroleum-derived barriers, while regulatory pressure accelerates validation timelines for compostability claims across European supply chains.
Barrier-coated molded fiber is automating grease and moisture resistance in ready-meal trays. Major foodservice distributors in Germany and France specify these formats for hot-fill applications above 85°C. The technology is automating specification capture from polypropylene incumbents by matching seal integrity and stack strength without fossil-derived content.
F-Gas Regulation phase-down schedules are accelerating investment in fiber-based insulation for temperature-controlled shipping. Cold-chain operators face refrigerant containment costs that make biodegradable vacuum-insulated panels economically competitive. Pharmaceutical and fresh-produce logistics in Belgium and the Netherlands now prioritize cellulose-based thermal protection in vendor scorecards.
Direct-to-consumer subscription models are compressing packaging specification cycles. Beauty and nutrition brands in the United Kingdom and Ireland now refresh outer carton designs quarterly, favoring suppliers with rapid-tooling molded fiber capabilities over injection-molded plastic alternatives with 12-week mold lead times. This purchasing pattern concentrates volume with converters maintaining in-house CNC pattern capabilities.
Biodegradable Packaging Materials Market Segmentation
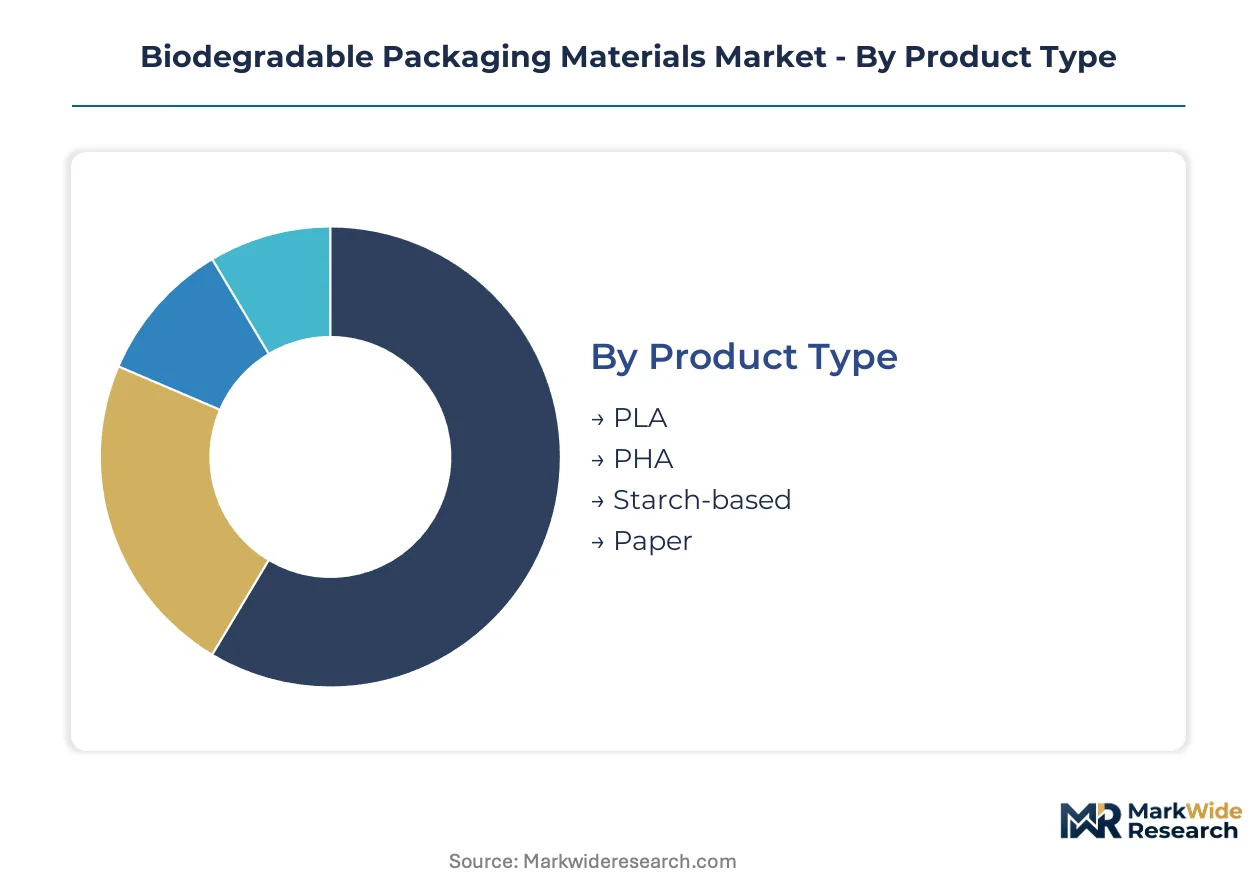
Material composition, end-use specifications, and form factor requirements create distinct supply chain configurations across biodegradable packaging. Each dimension carries different certification burdens, equipment investments, and margin structures that reshape procurement patterns.
Product Type:
Standardization dominates commodity grades while specialty polymers command customization premiums across fermentation and extrusion workflows.
- PLA:Polylactic acid derives from corn starch fermentation and processes on conventional thermoforming equipment with modified temperature profiles. Food and beverage brands in Germany and France specify PLA for ready-meal trays where EU Green Deal mandates accelerate substitution timelines.
- PHA:Polyhydroxyalkanoates offer marine biodegradability and broader composting compatibility than PLA, commanding premium positioning in pharmaceutical and marine-exposed applications. Fermentation scale-up is automating quality control, reducing batch variation that previously limited food-contact approvals.
- Starch-based:Loose-fill cushioning and molded protective formats serve e-commerce fulfillment with lower barrier performance but cost-competitive positioning.
- Paper:Fiber-based substrates leverage existing pulp infrastructure with grease-resistant coatings for hot-fill foodservice applications.
Most installed capacity flows through PLA. Expansion is steepest in PHA.
End Use Industry:
Regulatory pressure intensity varies by sector, with food-contact applications facing the most compressed substitution deadlines.
- Food & Beverage:Ready-meal trays, fresh-produce wraps, and foodservice items drive volume concentration. Extended Producer Responsibility schemes in the Netherlands and France penalize non-recyclable formats, redirecting procurement budgets toward certified compostable alternatives.
- Healthcare:Sterile barrier requirements and pharmaceutical cold-chain logistics create specialized demand for PHA-based thermal protection with validated biodegradation pathways.
- Personal Care:Direct-to-consumer subscription models in the United Kingdom compress packaging specification cycles, favoring rapid-tooling molded fiber capabilities.
- Electronics:Static-dissipative and moisture-buffering requirements limit biodegradable penetration to outer transit packaging rather than device-contact layers.
Food and beverage anchors current volume. Healthcare is gaining share fastest.
Form:
Dimensional stability requirements versus lightweight flexibility dictates equipment investment and material selection tradeoffs.
- Films:Flexible barrier layers for e-commerce protective wraps and fresh-produce packaging represent the most rapidly expanding category. TIPA and similar specialists engineer multilayer structures matching conventional plastic seal integrity.
- Rigid Containers:Molded fiber and thermoformed PLA trays protect perishables with dimensional stability. Hot-fill applications above 85°C in Germany specify barrier-coated molded fiber with grease resistance.
- Bags:Carry-out and liner applications face performance limitations in high-moisture environments above 85% relative humidity.
- Trays:Ready-meal and produce presentation formats concentrate demand in France and Netherlands retail channels.
Rigid containers hold the most installed capacity. Films are expanding most quickly.
Distribution Channel:
Specification authority resides differently across channel types, reshaping supplier relationship investments.
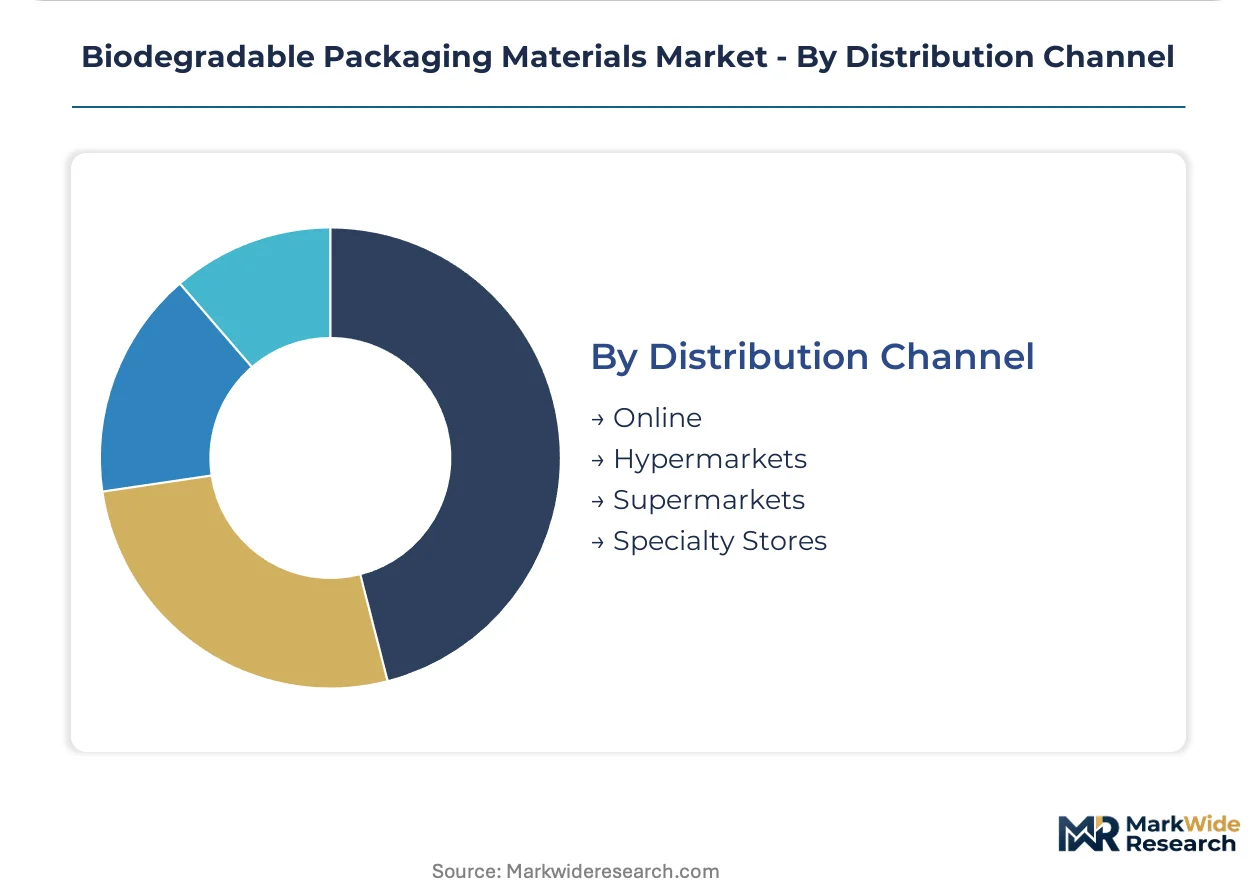
- Online:E-commerce fulfillment concentrates volume with platform operators who specify outer transit and protective inner packaging. Netherlands packaging levies create direct cost incentives for biodegradable material adoption in this channel.
- Hypermarkets:Private-label procurement teams in Germany and France mandate minimum recycled and renewable content thresholds, redirecting shelf-ready packaging specifications.
- Supermarkets:Regional chains lag central procurement sophistication but face identical regulatory compliance deadlines.
- Specialty Stores:Premium positioning and smaller batch requirements favor suppliers with rapid tooling capabilities and CSRD-aligned carbon accounting data.
Hypermarkets channel the most installed capacity. Online is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Materials scientists and polymer engineers concentrate in Northern European pulp hubs and Chinese biotech corridors. These talent clusters anchor pilot-scale fermentation and fiber-molding capabilities that smaller markets cannot replicate.
Germany
Ready-meal manufacturers in Bavaria and Baden-Württemberg specify barrier-coated molded fiber for hot-fill applications above 85°C. The country's national packaging regulator enforces extended producer responsibility levies that penalize non-recyclable formats. Berlin-Brandenburg hosts pilot composting facilities testing multilayer film disintegration rates under industrial conditions.
France
Foodservice distributors in Île-de-France mandate minimum renewable content thresholds for single-use items. ANSM and environmental agencies coordinate food-contact safety reviews with compostability certification timelines. The Auvergne-Rhône-Alpes corridor concentrates PLA thermoforming capacity serving pan-European retail chains.
Netherlands
E-commerce fulfillment operators in the Randstad face packaging levies that create direct cost incentives for biodegradable adoption. The country's national environmental agency administers collection targets that redirect procurement budgets toward certified compostable alternatives. Rotterdam's port logistics cluster integrates cellulose-based thermal protection into pharmaceutical cold-chain vendor scorecards.
United States
FDA food-contact notifications govern PLA and PHA substrate approvals for distribution channels serving California and New York Metro markets. The EPA coordinates with state regulators on composting infrastructure standards that vary by municipality. Midwest agricultural processing corridors supply corn starch feedstock to fermentation facilities near Chicago and Des Moines.
China
Dual carbon goals and national standards administration directives accelerate material substitution mandates across Yangtze River Delta manufacturing bases. The Ministry of Ecology and Environment monitors biopolymer production emissions alongside conventional plastic capacity. Zhejiang and Jiangsu provinces host integrated pulp-to-molded-fiber operations leveraging existing paper industry infrastructure.
Biodegradable Packaging Materials Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures. Integrated pulp and paper conglomerates control fiber sourcing through backward integration into forestry assets, while specialty polymer houses license fermentation technology without captive bioreactor capacity. The market exhibits tiered concentration: multinational packaging groups anchor foodservice volumes, regional converters serve subscription-commerce niches, and agricultural cooperatives supply starch feedstock. Dominant competitive moves include strategic partnerships between brand owners and composting facility operators, plus capacity expansion in marine-biodegradable polymer fermentation.
Among Nordic-heritage integrated producers, Stora Enso anchors fiber-based substrate supply through captive pulp operations. Huhtamäki occupies a position within the molded foodservice tier exemplifying rapid-tooling capabilities for quarterly design refresh cycles. TIPA represents the flexible film specialization vector, matching conventional plastic barrier performance in multilayer structures. These three archetypes illustrate how geographic integration, equipment flexibility, and material science depth respectively defend margin position across distinct procurement channels.
| Leading Market Players |
|---|
| Xiamen Bioleader |
| Stora Enso |
| Huhtamäki |
| Tetra Pak |
| TIPA |
| BioPak |
| Pactiv Evergreen |
| Amcor |
| Vegware |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap converters across Germany and the Netherlands anchor supply discipline through conservative capital allocation and long-term feedstock contracts, insulating pricing from agricultural commodity swings while limiting aggressive capacity expansion.
Pricing Analysis
Bundled certification-and-logistics services command premiums over unbundled resin supply, with TÜV Austria and DIN CERTCO validation packaged alongside technical support. Three-tier pricing structure across premium, standard, and economy levels separates marine-biodegradable PHA grades from basic PLA and loose-fill starch. Pricing pressure stems from corn starch cost volatility compressing margins for thermoformed tray producers. Hypermarket procurement teams exhibit highest price sensitivity, while pharmaceutical cold-chain operators prioritize validated biodegradation pathways over unit economics.
Supply Chain Analysis
Polymer engineering talent shortages in Bavaria and Zhejiang constrain fermentation scale-up velocity, forcing automation investments that reshape workforce composition at bioreactor facilities. Supply concentrates in Germany, China, and the Netherlands, with Zhejiang pulp-to-molded-fiber operations and Rotterdam logistics clusters anchoring regional flows. Corn starch, sugarcane bagasse, and wood pulp constitute critical raw material inputs. Single-source vulnerability runs through Chinese biopolymer fermentation capacity. Distribution runs through brand-owner direct contracts and foodservice distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications are tightening as EU Green Deal enforcement compresses substitution timelines, with food-contact certification becoming a non-negotiable procurement filter rather than a premium option.
For Market Incumbents: Hedge against PHA fermentation scale-up by securing long-term bagasse supply agreements in Southeast Asian agricultural corridors. Invest in rapid-tooling CNC capabilities to capture quarterly design refresh cycles from United Kingdom subscription-commerce brands. Barrier-coated molded fiber capacity expansion in France and Germany defends position against PLA tray incumbents. For New Entrants and Emerging Players: Begin with cold-chain logistics insulation for Poland and Romania, where temperature-controlled biodegradable standards remain undefined. Target pharmaceutical secondary packaging in Belgium and the Netherlands, where CSRD-aligned carbon accounting favors vendors with certified lifecycle data. Lead with marine-biodegradability claims to differentiate from established PLA suppliers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional converters with rapid-tooling capabilities but limited certification depth. Long-term viability hinges on composting infrastructure buildout pace aligning with material claims. Acquisition targets should demonstrate validated food-contact approvals and captive fiber sourcing. Watch TÜV Austria review queue compression as an inflection signal for market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Composting Certification Investment | TÜV Austria and DIN CERTCO validation accelerates food-contact approvals in EU Green Deal compliance windows. |
| Backward Integration into Pulp Supply | Captive fiber sourcing in Nordic forestry assets insulates margin from agricultural commodity volatility. |
| Rapid-Tooling Capacity Expansion | In-house CNC pattern capabilities capture quarterly design refresh cycles from United Kingdom beauty brands. |
| PHA Fermentation Scale-Up | Automated quality control protocols reduce batch variation limiting pharmaceutical and marine-exposed applications. |
| Cold-Chain Logistics Partnership | Cellulose-based thermal protection integration into Rotterdam pharmaceutical vendor scorecards opens premium positioning. |
Methodological Framework
Direct dialogue with packaging procurement managers, composting facility operators, polymer R&D directors, and EU regulatory affairs specialists grounded qualitative findings in operational reality. Secondary validation drew from ECHA substance registrations, EU Green Deal implementation trackers, FDA food-contact notification databases, and customs trade flows for biopolymer resin categories. Bottom-up and top-down triangulation cross-checked fermentation capacity announcements against end-use demand signals.
Bottom-up modeling aggregated segment-level volume assumptions across material type, form factor, and end-use industry dimensions, while top-down analysis benchmarked against EU EPR levy revenue trajectories and national packaging waste reporting. CAGRs derived from regression of historical substitution elasticities against regulatory enforcement timelines. Industry-specific inputs included industrial composting facility commissioning rates and PLA thermoforming equipment retrofit cycles.
Several conditions sit outside the modeled scope, including unannounced biopolymer fermentation capacity additions, sudden shifts in agricultural commodity prices, and composting infrastructure buildout delays in Southern and Eastern European markets. Forecasts reflect documented assumptions on regulatory enforcement consistency and certification timeline stability. Material deviation in EU Green Deal implementation pace or TÜV Austria review queue duration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Biofoam Packaging Market
Biodegradable Packaging
Biodegradable Cups Market
Biodegradable Packaging
Bioplastic Packaging Market
Biodegradable Packaging
Biodegradable Packaging Products Market
Biodegradable Packaging
North America Biodegradable Film Market
Biodegradable Packaging
Starch-Based Bioplastics Packaging Market
Biodegradable Packaging
Global Bioplastic Multi-Layer Films Market
Biodegradable Packaging
Biodegradable Lidding Films Market
Biodegradable Packaging
North America Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Biopolymer Packaging Market
Biodegradable Packaging
India Biodegradable Tableware & Packaging Products Market
Biodegradable Packaging
Biodegradable Cutlery Market
Biodegradable Packaging
North America Biodegradable Plastic Market
Biodegradable Packaging
Global Biodegradable Tableware Market
Biodegradable Packaging
Biodegradable Plastic Packaging Market
Biodegradable Packaging
Biodegradable Paper and Plastic Packaging Market