
 Textile Implants Market | 2026-2036
Textile Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Implants Market Outlook
Biocompatibility-grade polymer specifications are redrawing competitive boundaries in textile implants. W.L. Gore & Associates leverages its fluoropolymer expertise to dominate high-performance vascular and hernia applications. Medtronic anchors its position through deep R&D intensity across biodegradable and permanent mesh platforms. Johnson & Johnson competes through extensive channel control and brand strength in sutures and fixation devices.
Textile implants are woven or knitted fibrous structures manufactured from synthetic or resorbable polymers, typically with pore sizes ranging from sub-micron to several millimeters, designed to reinforce tissue, close wounds, or provide scaffolds for cellular ingrowth. Surgical mesh leads product type revenue due to its irreplaceable role in hernia and pelvic floor reconstruction, while biodegradable implants represent the fastest-expanding segment as resorption timelines improve. Hospitals command the largest end-user share through centralized procurement of high-volume procedures, though ambulatory surgical centers are capturing procedural migration for simpler implantations.
The FDA enforces Class II and Class III device pathways with rigorous 510(k) and PMA requirements that filter market entrants by clinical evidence burden. The EU Medical Device Regulation and ISO 10993 biocompatibility standards further tighten material qualification protocols across export markets. Stakeholders must monitor evolving resorbable polymer degradation profiles and associated long-term clinical data requirements as regulatory scrutiny intensifies for permanent implantable textiles.
Market Dynamics
Biodegradable polymer degradation profiles are forcing manufacturers to rebuild clinical evidence packages as FDA PMA pathways tighten for long-term implantable textiles. The shift from permanent to resorbable mesh platforms demands new manufacturing capabilities and extended follow-up data.
Growth Catalysts
- EU MDR Implementation:Stricter CE marking requirements for Class III implantable textiles are filtering out marginal suppliers and consolidating market share among qualified manufacturers with established quality management systems.
- Ambulatory Surgical Centers:Procedural migration toward outpatient hernia and pelvic floor repairs is expanding addressable procedure volumes beyond traditional hospital settings.
- Polyglycolic Acid-Lactide Copolymers:Improved resorption timeline predictability is opening orthopedic and soft tissue applications previously reserved for permanent synthetic meshes.
Market Restraints
- High-Purity Monomer Supply:Medical-grade caprolactone and glycolide feedstock concentrates among three specialty chemical suppliers, creating input cost volatility and qualification bottlenecks.
- FDA 510(k) Substantial Equivalence:Predicate device requirements for textile implants limit innovation pathways and extend development timelines for novel mesh architectures.
- Surgical Glue and Sealants:Advanced tissue adhesives from cardiovascular and general surgery applications threaten mesh volume in select wound closure indications.
Strategic Opportunities
- Japan's Aging Demographics:PMDA accelerated review pathways for priority medical devices create faster market access for hernia and pelvic organ prolapse mesh manufacturers.
- 3D Knitting with Bioactive Coating:Convergence of textile engineering and surface modification technologies enables localized drug delivery from implantable scaffolds.
- Direct-to-Hospital Contracting:Bypassing traditional distributor networks in Germany and France captures margin and builds procedural volume commitments with integrated delivery systems.
Industry Challenges
- Bioengineer Talent Scarcity:Cross-trained professionals combining polymer science, textile manufacturing, and clinical knowledge command premium compensation and extend hiring timelines.
- ISO 10993-18 Testing Burden:Chemical characterization requirements for extractables and leachables add six to twelve months to material qualification cycles.
- Legacy ERP Integration:Medical device quality management systems struggle to interface with modern manufacturing execution platforms for lot traceability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Implants Market |
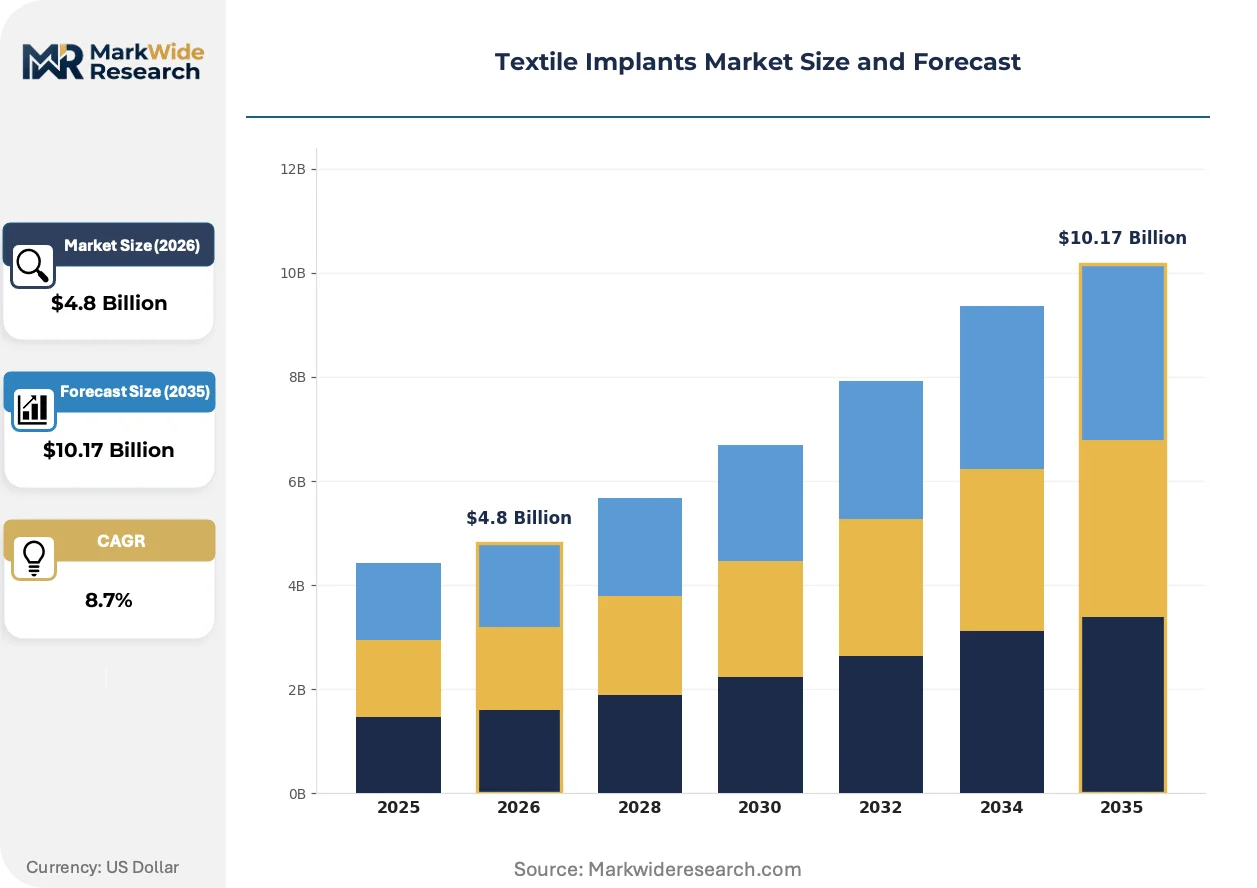
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Mesh, Sutures, Fixation Devices, Biodegradable Implants Application: Wound Closure, Hernia Repair, Pelvic Floor Reconstruction, Orthopedic Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Laboratories Material: Polypropylene, Polyester, Polyglycolic Acid, Nylon |
| Companies Covered | Boston Scientific Corporation, W.L. Gore & Associates Inc., Medtronic plc, Integra LifeSciences Corporation, Cook Medical, Johnson & Johnson, Smith & Nephew plc, ATEX Technologies, B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Implants Market Strategic Shifts
Material science breakthroughs are compressing the performance gap between synthetic permanence and bioresorbable functionality. Three developments are restructuring competitive positioning in implantable textiles.
Electrospun nanofiber matrices are fragmenting traditional woven and knitted mesh architectures in hernia repair applications. Leading surgical centers in the United States and Germany are piloting these sub-micron pore structures for improved tissue integration and reduced foreign body response. The technology is fragmenting established supply relationships as specialized electrospinning equipment vendors capture value previously held by conventional textile machinery suppliers.
The FDA's updated guidance on permanent surgical mesh for transvaginal pelvic organ prolapse has triggered voluntary market withdrawals and redirected R&D investment toward resorbable alternatives. Manufacturers must now generate five-year follow-up data for novel mesh designs, compressing development pipelines and elevating capital requirements. Vaginal mesh products face the most stringent evidence thresholds, while abdominal hernia applications maintain clearer regulatory pathways.
Hospital value analysis committees now mandate head-to-head economic evidence against existing mesh standards before adding novel implants to formularies. Device manufacturers must deliver bundled cost-outcome data that includes operating time, readmission rates, and explant frequency. This behavioral shift is most pronounced in United States integrated delivery networks and Netherlands hospital procurement cooperatives, where centralized purchasing authority concentrates buyer power.
Textile Implants Market Segmentation
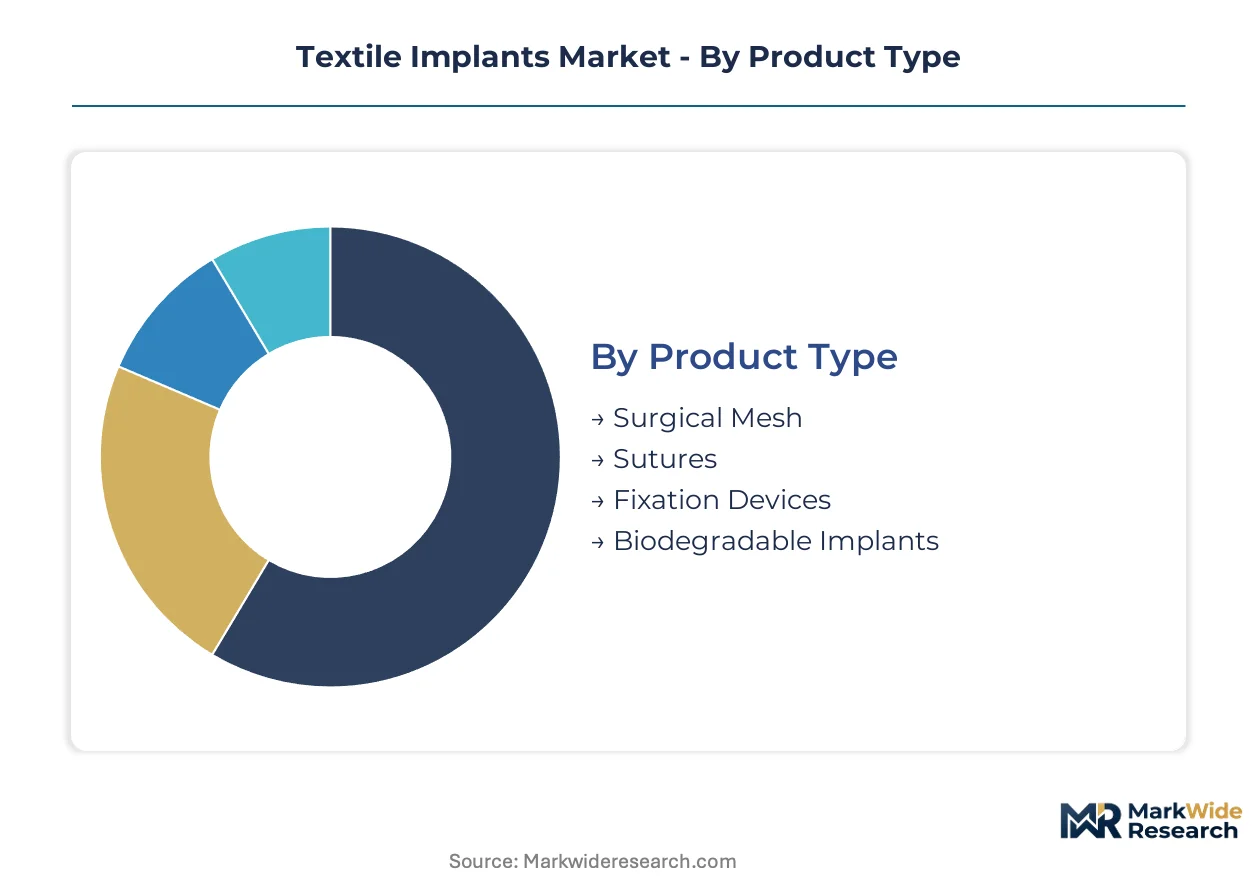
Textile implant manufacturers navigate divergent regulatory pathways and clinical evidence requirements across each product category. Segmentation reveals where FDA PMA burdens concentrate versus where 510(k) substantial equivalence offers faster commercialization timelines.
Product Type:
FDA Class II and Class III designations split this category by long-term implantation risk and biocompatibility testing intensity.
- Surgical Mesh:Woven or knitted polypropylene and polyester structures with calibrated pore architecture for tissue ingrowth. Demand clusters in hernia repair procedures across United States hospital systems, where value analysis committees now mandate five-year safety data before formulary inclusion.
- Sutures:Braided or monofilament fiber configurations for wound approximation with absorbable and non-absorbable variants. Ambulatory surgical centers in Germany and France drive procedural volume for synthetic absorbable platforms as outpatient migration accelerates.
- Biodegradable Implants:Resorbable polymer scaffolds with engineered degradation timelines matching tissue regeneration phases. Polyglycolic acid-lactide copolymer improvements are expanding orthopedic applications previously reserved for permanent meshes.
- Fixation Devices:Anchoring systems combining textile tethers with mechanical fixation elements for soft tissue reattachment.
Established volume favors surgical mesh; emerging adoption favors biodegradable implants.
Application:
Procedure reimbursement rates and complication liability profiles determine manufacturer investment prioritization across clinical indications.
- Hernia Repair:Abdominal wall reinforcement using synthetic or biologic mesh substrates. United States Medicare reimbursement stability supports consistent demand, though transvaginal pelvic organ prolapse restrictions have redirected R&D toward abdominal applications.
- Wound Closure:Primary closure and secondary intention healing support across surgical disciplines. Japan's aging demographics and PMDA accelerated review pathways are expanding addressable procedure volumes for advanced closure technologies.
- Pelvic Floor Reconstruction:Mesh-based suspension systems for stress urinary incontinence and pelvic organ prolapse. FDA guidance restrictions have triggered voluntary market withdrawals and intensified clinical evidence requirements.
- Orthopedic Surgery:Ligament augmentation, tendon repair, and soft tissue reconstruction applications. Bioresorbable textile development is climbing fastest as degradation predictability improves for load-bearing indications.
Revenue concentration sits with hernia repair; steepest expansion trajectory belongs to orthopedic surgery.
End User:
Procurement authority and capital equipment requirements fragment demand across institutional settings with diverging supply chain access.
- Hospitals:Centralized purchasing departments managing high-volume implant inventories for complex procedures. Integrated delivery networks in the United States leverage consolidated buying power to extract bundled pricing concessions from manufacturers.
- Ambulatory Surgical Centers:Outpatient facilities capturing migrated hernia and wound closure procedures. Netherlands hospital procurement cooperatives and German day-clinic networks are expanding addressable volumes for standardized mesh products.
- Specialty Clinics:Focused surgical practices with direct-to-physician distribution relationships for premium fixation devices.
- Research Laboratories:Academic and commercial R&D settings driving preclinical evaluation of novel textile architectures and surface modifications.
Procurement scale favors hospitals; volume growth velocity favors ambulatory surgical centers.
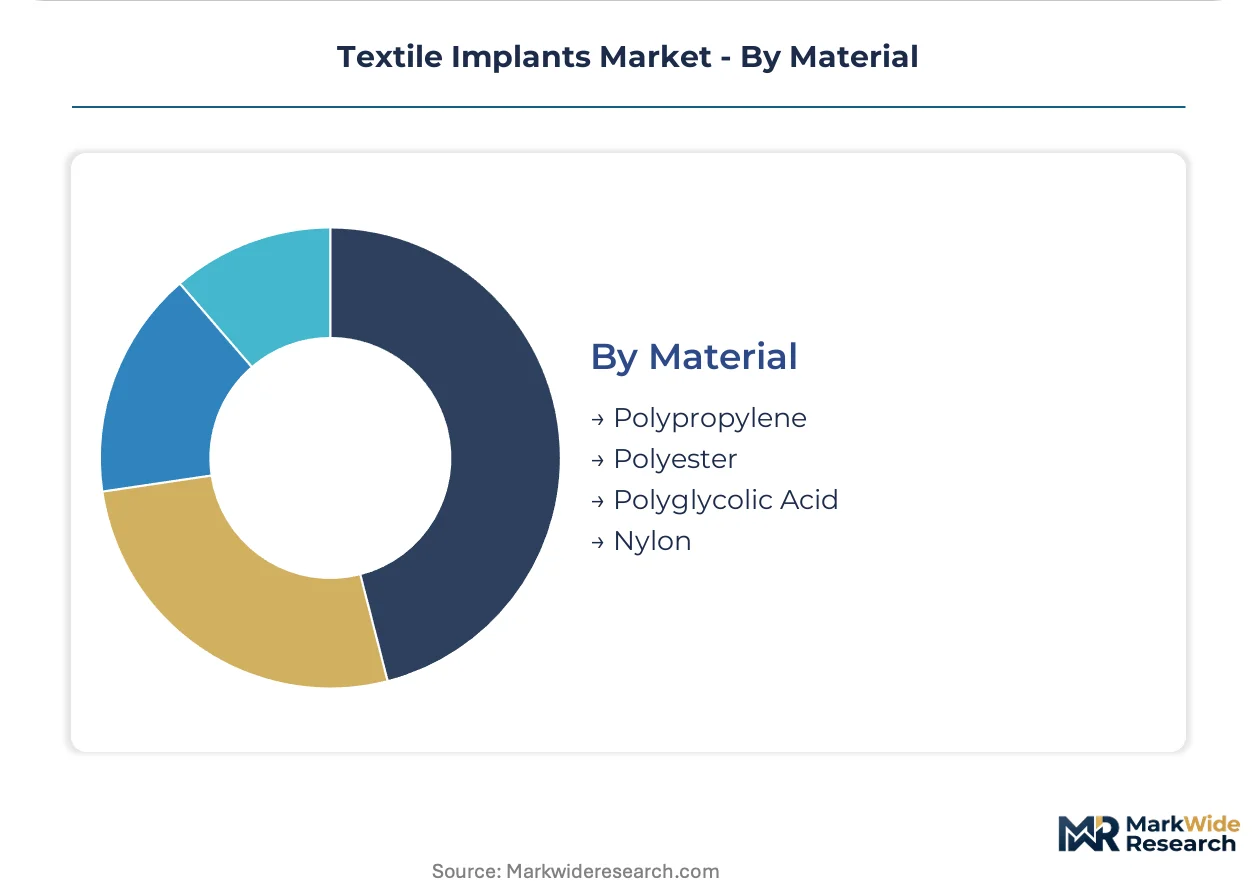
Material:
Monomer purity specifications and supply chain qualification timelines differentiate competitive positioning among polymer categories.
- Polypropylene:Isotactic polymer with chemical inertness and permanent implantation durability. Medical-grade feedstock concentrates among three specialty chemical suppliers, creating qualification bottlenecks for new market entrants.
- Polyglycolic Acid:Rapidly resorbable aliphatic polyester with predictable hydrolytic degradation. Improved copolymer formulations with lactide are opening orthopedic applications requiring intermediate resorption timelines.
- Polyester:Polyethylene terephthalate fiber systems with tensile strength for cardiovascular and hernia applications.
- Nylon:Polyamide structures with elasticity characteristics for suture and temporary support applications.
Clinical history favors polypropylene; technology evolution favors polyglycolic acid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement networks in the United States extract steep volume discounts for standardized mesh products, while Japanese buyers prioritize degradation predictability over unit cost, creating a sharp demand-elasticity divide across major markets.
United States
Medicare reimbursement stability for abdominal hernia procedures sustains consistent surgical mesh consumption, though transvaginal pelvic organ prolapse restrictions have compressed pelvic floor reconstruction volumes. FDA PMA pathway tightening for permanent implants extends qualification timelines for novel biodegradable platforms. Minneapolis-based integrated delivery networks and Boston's surgical device clusters concentrate procurement authority and R&D investment respectively.
Germany
Ambulatory surgical center networks in Bavaria and North Rhine-Westphalia capture migrated hernia repair procedures from inpatient settings, expanding addressable volumes for resorbable polymer platforms. EU MDR Class III implantable textile requirements filter marginal suppliers and consolidate share among established quality management system holders. Stuttgart's medical textile engineering corridor and Munich's hospital procurement cooperatives drive standardization and direct-to-hospital contracting adoption.
Japan
PMDA accelerated review pathways for priority medical devices reduce time-to-market for hernia and pelvic organ prolapse mesh manufacturers targeting aging demographic demand. METI industrial policy supports domestic biodegradable polymer scaffold development to reduce import dependence. Osaka's medical device manufacturing belt and Tokyo's university hospital networks anchor clinical evaluation and commercial distribution infrastructure.
China
NMPA medical device registration reform streamlines Class II implantable textile approvals while intensifying biocompatibility documentation requirements for Class III permanent meshes. Domestic hospital procurement centralization in tier-one cities compresses pricing for imported synthetic mesh products. Suzhou's biomedical materials industrial park and Shanghai's surgical device distribution hubs concentrate manufacturing scale and import channel control.
India
CDSCO medical device rules implementation elevates quality system expectations for imported surgical mesh while creating regulatory pathways for domestic biodegradable implant manufacturers. Government hospital procurement through centralized tenders prioritizes cost-competitive polypropylene mesh for high-volume hernia programs. Ahmedabad's textile engineering cluster and Chennai's medical device manufacturing corridor develop indigenous resorbable polymer capabilities.
Textile Implants Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the textile implants market. Fluoropolymer specialists and diversified medical device conglomerates occupy distinct competitive tiers, with mid-scale polymer science firms occupying intermediate positions. Three archetypes dominate: integrated device conglomerates with deep R&D pipelines, specialized textile engineering houses with polymer expertise, and regional fabricators serving price-sensitive procurement channels. Strategic moves concentrate on biodegradable platform diversification and direct-to-hospital contracting bypass of traditional distributor networks.
Among diversified medical technology conglomerates, Boston Scientific Corporation and Medtronic plc exemplify scale-driven archetypes with extensive regulatory affairs infrastructure and multi-therapy portfolio breadth. W.L. Gore & Associates Inc. occupies a specialized position reflecting fluoropolymer material science depth. Johnson & Johnson represents channel control archetypes leveraging brand strength and hospital system relationships across sutures and fixation device categories. ATEX Technologies and Integra LifeSciences Corporation sit within mid-tier specialist positions emphasizing textile engineering and regenerative medicine platforms respectively.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| W.L. Gore & Associates Inc. |
| Medtronic plc |
| Integra LifeSciences Corporation |
| Cook Medical |
| Johnson & Johnson |
| Smith & Nephew plc |
| ATEX Technologies |
| B. Braun Melsungen AG |
| Others |
Value Chain & Pricing Dynamics
FDA biocompatibility certification requirements for Class II and Class III implantable textiles simultaneously gate supplier qualification and stratify price tiers across the value chain. Manufacturers must absorb extended ISO 10993 testing cycles and PMA pathway costs, forcing price differentiation between certified incumbents and marginal competitors.
Pricing Analysis
After-sales service contracts and explant warranty coverage drive lifetime value capture for permanent mesh manufacturers. Three-tier pricing structure across premium, standard, and economy levels reflects FDA PMA tier, ISO 13485 certification status, and five-year clinical data packages. Cost compression in standard-grade polypropylene mesh intensifies as hospital value analysis committees demand bundled outcome guarantees. Ambulatory surgical centers exhibit highest price sensitivity; integrated delivery networks prioritize total cost-of-ownership over unit price.
Supply Chain Analysis
Strategic stockpiling of medical-grade caprolactone and glycolide monomers dominates inventory strategy as qualification timelines stretch procurement lead times. Manufacturing concentrates in United States, Germany, and China, with specialty polymer feedstock drawing from three dominant chemical suppliers. Single-source vulnerability pervades high-purity monomer inputs. Distribution runs through GPO contracts and direct-to-hospital agreements in mature markets, with distributor networks retaining relevance in emerging procurement environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biodegradable polymer degradation predictability represents a high-growth disruption as resorbable platforms displace permanent meshes in orthopedic and soft tissue applications. FDA PMA pathway tightening for long-term implants accelerates this inflection by compressing development pipelines for conventional synthetic architectures.
For Market Incumbents: Consolidate biodegradable platform capabilities through targeted R&D intensity in polyglycolic acid-lactide copolymer formulations. Defend against electrospun nanofiber substitutes by securing hospital formulary lock-in with five-year safety data packages. Prioritize backward integration into medical-grade monomer supply to offset feedstock cost volatility from concentrated chemical suppliers. For New Entrants and Emerging Players: Direct-to-hospital contracting gaps in Germany and France present white-space targets where established distributors extract margin without delivering value-added services. Penetrate ambulatory surgical center networks in Netherlands procurement cooperatives with standardized resorbable mesh platforms priced below PMA-burdened incumbent offerings. Lead with explant warranty coverage and localized technical support as differentiated go-to-market anchors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with under-monetized medical polymer divisions and stranded textile manufacturing assets. Long-term viability hinges on resorbable platform pipelines and regulatory affairs infrastructure capable of navigating evolving PMA evidence requirements. Watch FDA guidance updates on permanent pelvic organ prolapse mesh as inflection signal for resorbable investment prioritization.| Strategic Initiative | Industry Significance |
|---|---|
| FDA PMA Submission | Five-year follow-up data requirements filter marginal competitors from permanent implant markets. |
| CE Marking Pathway | EU MDR Class III implantable textile standards consolidate share among quality system holders. |
| Hospital System Partnership | Direct contracting with United States integrated delivery networks captures margin from distributor layers. |
| Biodegradable Platform Diversification | Polyglycolic acid-lactide copolymer development opens orthopedic applications previously reserved for permanent meshes. |
| Reimbursement Strategy | Medicare coding stability for abdominal hernia procedures sustains volume visibility for mesh manufacturers. |
Study Parameters
Desk research of FDA 510(k) and PMA filings, EU MDR technical documentation, and hospital procurement database records preceded structured interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at implantable textile manufacturers. Secondary validation drew from ISO 10993 biocompatibility standards, CMS Medicare reimbursement schedules, and specialty chemical supplier qualification protocols. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchored market sizing.
Variance decomposition across product type, application, end user, material, and regional regulatory cluster dimensions structured the analytical framework. CAGRs were derived from segmented procedure volume trajectories and average selling price evolution across the projection horizon. Forecast inputs incorporated PMDA accelerated review pathway utilization rates, ambulatory surgical center migration coefficients, and resorbable polymer degradation timeline improvements.
Underlying assumptions cover Medicare reimbursement stability, EU MDR implementation continuity, and medical-grade monomer supply availability, with deviation risk concentrated in FDA guidance shifts for permanent pelvic organ prolapse mesh and hospital value analysis committee behavioral changes. Revision becomes warranted when biodegradable platform clinical evidence thresholds cross regulatory acceptance boundaries.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
Examination Gloves Market
Medical and Hygiene Textiles
Period Patch Market
Medical and Hygiene Textiles
Sanitary Napkin Market
Medical and Hygiene Textiles
GCC Sanitary Napkin Market
Medical and Hygiene Textiles
Pant Type Adult Diaper Market
Medical and Hygiene Textiles
Medical Non-Woven Disposables Market
Medical and Hygiene Textiles
Washable and Reusable Mask Market
Medical and Hygiene Textiles
Sleeping Masks Market
Medical and Hygiene Textiles
Medical Fabrics Market
Medical and Hygiene Textiles
Global Maternity Support Product Market
Medical and Hygiene Textiles
Examination Gowns Market
Medical and Hygiene Textiles
Global Biomedical Textiles Market
Medical and Hygiene Textiles
Medical Textiles Market
Medical and Hygiene Textiles
Antimicrobial Polyamide Textiles Market
Medical and Hygiene Textiles
Europe Sanitary Napkin Market
Medical and Hygiene Textiles
Global Surgical Drapes and Gowns Market