
 Global Maternity Support Product Market | 2026-2036
Global Maternity Support Product Market Size, Share, and Industry Trends Forecast 2026-2036
Global Maternity Support Product Market Outlook
The EU Medical Device Regulation is realigning the cost-of-entry calculus for compression garment manufacturers seeking European market access. Medela LLC leverages its clinical channel relationships to sustain premium positioning across hospital procurement networks. Lansinoh Laboratories anchors its portfolio in lactation support while extending into adjacent postpartum recovery categories. Frida competes through direct-to-consumer packaging innovation that dominates pharmacy shelf placement in North American retail.
Maternity support products encompass engineered compression garments, structural belts, ergonomic pillows, and therapeutic bracelets designed to redistribute mechanical load, stabilize the lumbar-pelvic region, and facilitate circulatory function during gestation and postpartum recovery. Medical-grade maternity belts typically incorporate multi-layer laminates of cotton-spandex blends with adjustable closure systems calibrated to provide 15-25 mmHg graduated compression for sacroiliac joint stabilization. Compression garments lead the product type segment due to established reimbursement pathways and repeat purchase cycles, while bamboo fiber materials represent the fastest-growing material category as sustainability credentials reshape premium consumer preferences across online distribution channels.
The FDA regulates maternity support belts as Class I medical devices under 510(k) exemption pathways, while the EU MDR now mandates clinical evaluation reports for compression garments claiming therapeutic benefit. Japan's PMDA and South Korea's MFDS maintain distinct material biocompatibility testing protocols that create fragmented compliance burdens for multinational suppliers. Stakeholders must monitor evolving reimbursement eligibility criteria from private insurers and national health systems, as coverage expansion or contraction will directly reshape volume distribution between retail pharmacy and institutional procurement channels.
Market Dynamics
The EU Medical Device Regulation is compressing market access timelines for compression garment manufacturers while simultaneously elevating material safety standards that reshape procurement criteria across European hospital systems.
Growth Catalysts
- Employer-sponsored maternity benefit expansion:United States corporations now routinely include postpartum recovery garment reimbursement in health benefit packages, creating institutional demand pull.
- REACH-compliant bamboo fiber innovation:Sustainable material alternatives are capturing premium positioning across direct-to-consumer channels as environmental credentials reshape purchase decisions.
- Japan's PMDA biocompatibility pathway harmonization:Streamlined testing protocols for medical-grade textiles are accelerating product registration for multinational suppliers targeting East Asian markets.
Market Restraints
- EU MDR clinical evaluation burden:Compression garments claiming therapeutic benefit now require extensive documentation that extends time-to-market by 18-24 months for European access.
- Cotton-spandex laminate supply concentration:Medical-grade elastic textile production clusters in a limited number of specialized manufacturing regions, creating input vulnerability.
- Reimbursement pathway fragmentation:Private insurers maintain inconsistent coverage criteria across state lines, forcing manufacturers to navigate multiple prior-authorization frameworks.
Strategic Opportunities
- Underpenetrated Indian maternity care infrastructure:India's expanding hospital network and rising cesarean rates create demand for post-surgical compression garments with limited domestic supply.
- South Korea MFDS fast-track designation:Regulatory incentives for women's health devices offer accelerated review timelines for products meeting biocompatibility benchmarks.
- Subscription-based replenishment models:Direct-to-consumer platforms are capturing repeat purchase cycles through automated sizing adjustments across pregnancy trimesters.
Industry Challenges
- Clinical evidence generation capacity:Manufacturers lack sufficient in-house biostatistics functions to design trials meeting EU MDR clinical evaluation report requirements.
- Multi-jurisdiction labeling complexity:Compression garment instructions must reconcile FDA 510(k) exemption language with PMDA and MFDS material disclosure mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Maternity Support Product Market |
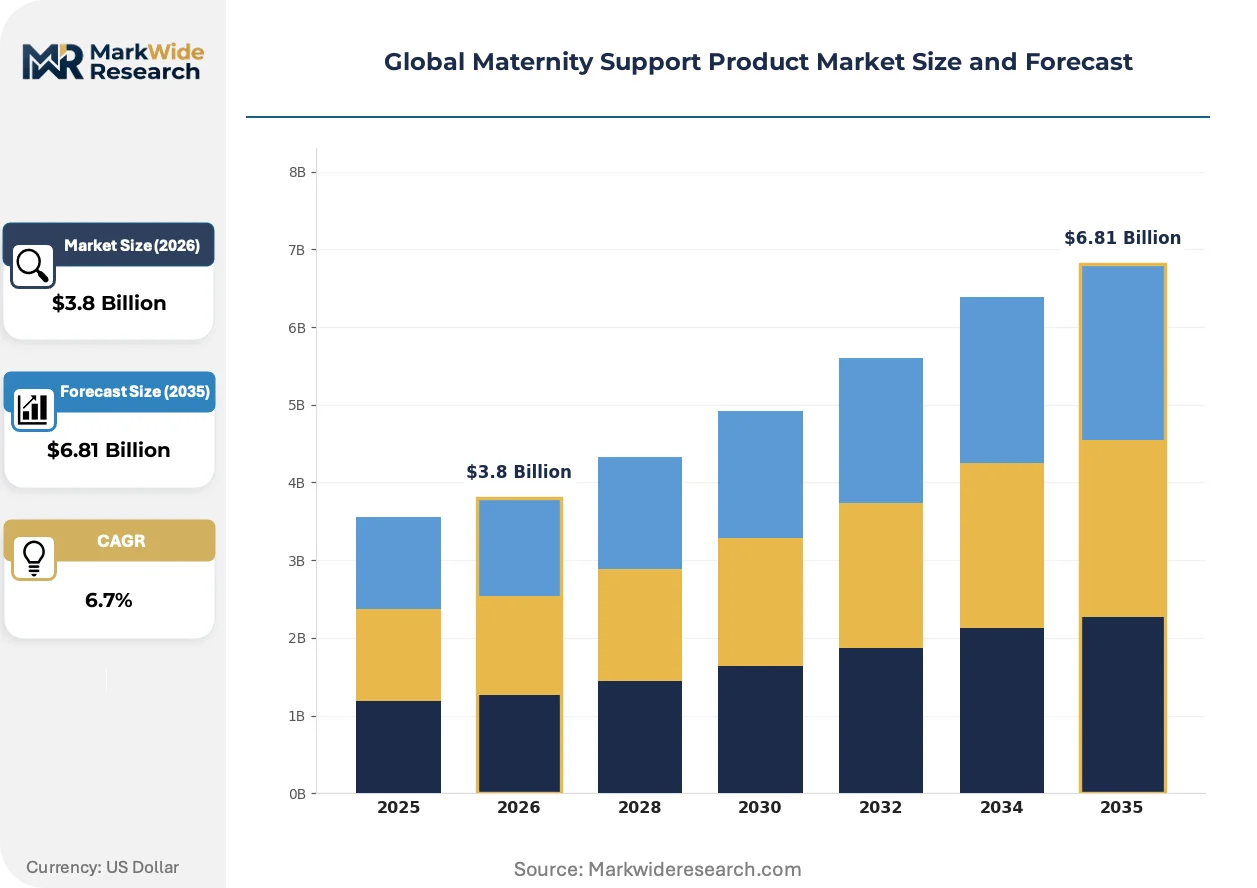
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Belts, Pillows, Compression Garments, Bracelets End User: Pregnant Women, Postpartum Recovery, Healthcare Providers, Retailers Material: Cotton, Spandex, Nylon, Bamboo Fiber Distribution Channel: Online Stores, Pharmacies, Specialty Shops, Others |
| Companies Covered | Amoralia Ltd, Izzie & Ollie Ltd, Mothercare, PinkBlush Maternity, Lohmann & Rauscher GmbH & Co., Frida, Medela LLC, Lansinoh Laboratories, HATCH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Maternity Support Product Market Strategic Shifts
Material science convergence with digital health integration is redefining product functionality boundaries, while regulatory harmonization pressures are forcing consolidation in supplier bases.
Graduated compression monitoring technology is consolidating around integrated sensor arrays that track pressure distribution across the lumbar-pelvic region. Hospital maternity wards in Germany and France are piloting these systems for postoperative recovery protocols. This consolidation is compressing the gap between consumer wellness devices and clinical-grade monitoring equipment.
The EU MDR's clinical evaluation report mandate is forcing manufacturers to redesign evidence-generation strategies for compression garments claiming therapeutic benefit. European notified bodies are rejecting legacy biocompatibility data, requiring fresh testing under updated ISO 10993 standards. Products targeting sacroiliac stabilization now face the steepest compliance burden, with several manufacturers withdrawing economy-tier lines rather than absorbing certification costs.
Consumer purchasing is fragmenting across channel types as pharmacy retail loses ground to specialized maternity e-commerce platforms. Direct-to-consumer brands are capturing sizing accuracy through AI-driven fit prediction tools that reduce return rates. This behavioral shift is most pronounced in North American urban markets where subscription-based replenishment models now account for a significant share of repeat garment purchases.
Global Maternity Support Product Market Segmentation
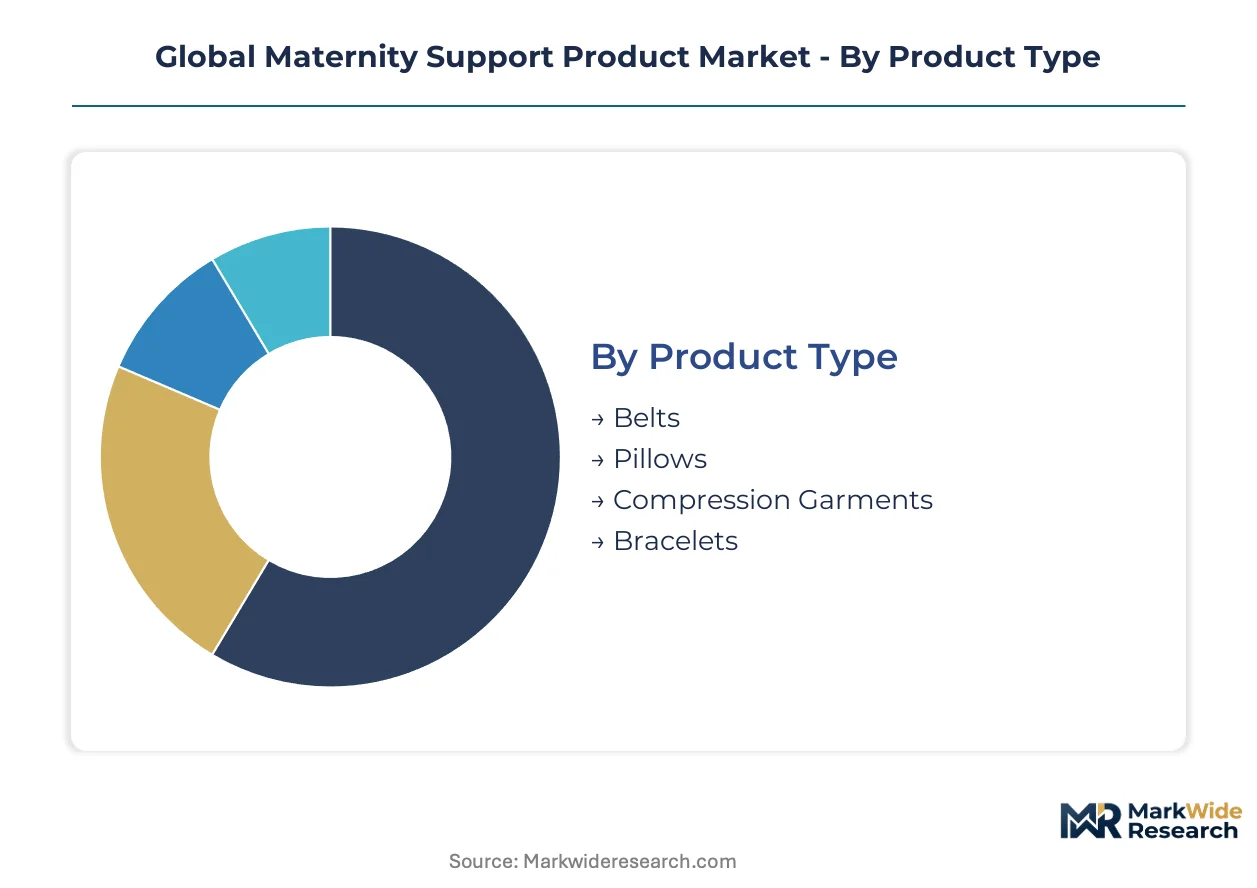
Product architecture in maternity support spans engineered compression systems to ergonomic positioning devices, each carrying distinct reimbursement codes and material certification requirements. Segmentation reveals how clinical validation pathways and consumer purchasing behaviors create divergent margin profiles across categories.
Product Type:
Compression technology and structural support mechanisms define the engineering axis across this category, with calibration precision determining clinical versus retail positioning.
- Compression Garments:Multi-layer laminates deliver 15-25 mmHg graduated pressure for sacroiliac stabilization and circulatory support. Hospital maternity wards in Germany and France are piloting integrated sensor arrays for postoperative recovery protocols, tightening the gap between consumer wellness and clinical-grade equipment.
- Belts:Adjustable closure systems with cotton-spandex blends provide mechanical load redistribution across the lumbar-pelvic region. FDA 510(k) exemption pathways enable faster US market entry compared to EU MDR clinical evaluation requirements.
- Pillows:Ergonomic positioning systems designed for sleep support and nursing alignment.
- Bracelets:Therapeutic wrist and ankle supports targeting edema management and joint stabilization.
Mature deployment sits with Compression Garments. Newer deployment is concentrated in Belts with integrated monitoring capabilities.
End User:
Procurement authority and reimbursement eligibility create distinct customer archetypes with divergent price sensitivity and volume predictability.
- Pregnant Women:Direct purchasers navigating trimester-specific sizing requirements and insurance prior-authorization frameworks.
- Postpartum Recovery:Patients requiring surgical-grade compression following cesarean delivery. India's expanding hospital network and rising cesarean rates are creating concentrated demand for post-surgical garments with limited domestic supply.
- Healthcare Providers:Hospital maternity wards and birthing centers expanding procurement of recovery garments through group purchasing organizations.
- Retailers:Pharmacy chains and specialty maternity stores managing inventory turnover across seasonal demand cycles.
Volume concentration rests with Postpartum Recovery. Margin expansion is occurring fastest in Healthcare Providers.
Material:
Biocompatibility certification and sustainability credentials are reshaping supplier qualification criteria across regulatory jurisdictions.
- Bamboo Fiber:REACH-compliant sustainable alternatives capturing premium positioning across direct-to-consumer channels. Environmental credentials are reshaping purchase decisions in North American urban markets where subscription-based replenishment models now dominate repeat purchases.
- Cotton:Natural fiber base layer providing breathability and skin contact safety for extended wear periods.
- Spandex:Elastic recovery component enabling graduated compression calibration and garment longevity.
- Nylon:Structural backbone material delivering tensile strength for belt and brace applications.
Established supply sits with Cotton-Spandex laminates. Steepest expansion trajectory belongs to Bamboo Fiber.
Distribution Channel:
Channel selection determines sizing accuracy, return rates, and customer lifetime value through replenishment capture.
- Online Stores:AI-driven fit prediction tools reducing return rates while enabling automated sizing adjustments across pregnancy trimesters. Direct-to-consumer platforms are capturing repeat purchase cycles through subscription-based replenishment models.
- Pharmacies:Shelf placement dominated by packaging innovation from direct-to-consumer brands in North American retail.
- Specialty Shops:Consultative fitting services providing clinical guidance for compression garment selection.
- Others:Hospital discharge kits and employer-sponsored benefit program fulfillment channels.
Traditional strength resides with Pharmacies. Channel shift is accelerating fastest in Online Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Employer-sponsored maternity benefit programs in the United States now routinely cover postpartum recovery garment reimbursement, establishing concentrated demand pull. Hospital procurement networks in Germany and France are piloting integrated sensor arrays for postoperative protocols. India's expanding hospital infrastructure and rising cesarean rates are creating supply gaps for post-surgical compression garments.
United States
Private insurers and employer benefit programs are expanding coverage eligibility for compression garments and structural belts. The FDA regulates maternity support belts as Class I medical devices under 510(k) exemption pathways. Greater Boston and the Pacific Northwest host birthing center networks that are standardizing postpartum recovery garment protocols.
Germany
Hospital maternity wards are consolidating procurement through group purchasing organizations for compression garments with integrated monitoring capabilities. The EU Medical Device Regulation mandates clinical evaluation reports for therapeutic compression claims. The Rhine-Ruhr metropolitan region anchors medical textile manufacturing clusters serving European hospital systems.
India
Rising cesarean delivery rates and expanding private hospital networks are driving demand for post-surgical compression garments with limited domestic manufacturing capacity. The Central Drugs Standard Control Organization maintains biocompatibility testing requirements for medical-grade textiles. Maharashtra and Karnataka host emerging domestic suppliers targeting tier-1 city hospital procurement.
Japan
The Pharmaceuticals and Medical Devices Agency has streamlined biocompatibility testing protocols for medical-grade textiles, accelerating product registration timelines. Premium consumer segments are adopting bamboo fiber alternatives through specialized maternity e-commerce platforms. The Kanto region around Tokyo concentrates retail pharmacy chains and direct-to-consumer distribution infrastructure.
South Korea
The Ministry of Food and Drug Safety offers fast-track designation incentives for women's health devices meeting biocompatibility benchmarks. Subscription-based replenishment models are capturing repeat purchase cycles through AI-driven fit prediction tools. The Seoul Capital Area dominates online maternity platform concentration and consumer technology adoption.
Global Maternity Support Product Market Competitive Environment
United States-based producers anchor the premium-tier clinical channel; European specialists hold regulatory compliance advantages under EU MDR frameworks. The vendor base fragments across direct-to-consumer innovators, hospital procurement incumbents, and material science specialists. Three strategic archetypes dominate: clinical channel relationship builders, direct-to-consumer packaging innovators, and sustainable material technology developers. Portfolio diversification into adjacent postpartum recovery categories and backward integration into specialized textile manufacturing represent the dominant competitive moves.
Within the clinical channel tier, Medela LLC and Lansinoh Laboratories exemplify incumbents leveraging established hospital procurement relationships. Frida occupies a position among direct-to-consumer packaging innovators dominating North American pharmacy shelf placement. Lohmann & Rauscher GmbH & Co. anchors the European specialist archetype with regulatory compliance capabilities under German corporate structure. These three company profiles represent the spectrum from clinical institutional sales through retail consumer capture to European regulatory navigation.
| Leading Market Players |
|---|
| Amoralia Ltd |
| Izzie & Ollie Ltd |
| Mothercare |
| PinkBlush Maternity |
| Lohmann & Rauscher GmbH & Co. |
| Frida |
| Medela LLC |
| Lansinoh Laboratories |
| HATCH |
| Others |
Value Chain & Pricing Dynamics
Backward integration into specialized cotton-spandex laminate production anchors both supply security and pricing power for premium-tier manufacturers navigating EU MDR compliance costs. Captive control over medical-grade elastic textile manufacturing insulates margin structures from raw material volatility while enabling faster certification turnaround for compression garment lines targeting hospital procurement networks.
Pricing Analysis
Volume concentrates in standard-tier cotton-spandex garments sold through pharmacy retail, while margin expansion accrues to premium-tier sensor-integrated compression systems piloted in German and French hospital wards. Three-tier pricing structure across premium, standard, and economy levels separates clinical-grade certification holders from direct-to-consumer brands and private-label suppliers. Cost compression in economy-tier lines is intensifying because several manufacturers are withdrawing products rather than absorbing EU MDR clinical evaluation report costs. Employer-sponsored benefit programs demonstrate lowest price sensitivity; uninsured direct purchasers in online channels exhibit highest sensitivity.
Supply Chain Analysis
Returns processing for AI-driven fit prediction tools in direct-to-consumer channels is compressing working capital cycles and forcing redesign of sizing algorithms to reduce garment exchange volumes. Medical-grade elastic textile production clusters in Germany, China, and South Korea, with cotton-spandex laminate finishing concentrated in the Rhine-Ruhr region and select East Asian manufacturing zones. Finished goods distribution runs through hospital group purchasing organizations in Europe, pharmacy retail chains in North America, and specialized maternity e-commerce platforms in East Asian urban markets. Single-source vulnerability sits with REACH-compliant bamboo fiber suppliers serving premium sustainability positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor-integrated compression monitoring technology is displacing legacy mechanical belts in European hospital procurement, compressing the window for manufacturers to reposition existing product architectures.
For Market Incumbents: Deepen clinical channel relationships through integrated monitoring pilot programs in German and French hospital systems before EU MDR compliance costs fully phase in. Prioritize backward integration into specialized textile manufacturing to defend margin position against raw material supply concentration. Accelerate biostatistics function buildout to address clinical evidence generation capacity gaps threatening European market access. For New Entrants and Emerging Players: Enter via underpenetrated Indian hospital networks where rising cesarean rates and limited domestic compression garment supply create procurement gaps. Target post-surgical recovery segments in tier-1 Indian cities through partnerships with Maharashtra and Karnataka-based emerging suppliers. Pursue South Korea MFDS fast-track designation as regulatory proof point for East Asian expansion. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by clinical channel incumbents seeking European regulatory compliance capabilities and integrated monitoring technology. Long-term viability favors manufacturers with captive textile production and established notified body relationships under EU MDR frameworks. Monitor EU notified body rejection rates for legacy biocompatibility data as inflection indicator for certification cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evaluation reports now mandate fresh ISO 10993 testing for therapeutic claims. |
| Hospital System Partnership | German and French maternity wards pilot sensor-integrated compression for postoperative protocols. |
| Backward Integration | Captive cotton-spandex laminate production insulates margins from specialized textile supply concentration. |
| Direct-to-Consumer Launch | AI-driven fit prediction tools reduce return rates in subscription-based replenishment models. |
| Reimbursement Strategy | US employer-sponsored benefit expansion creates institutional demand pull for premium-tier garments. |
Study Parameters
Independent corroboration across hospital procurement managers, biomedical engineers at maternity wards, GPO contracts administrators, and regulatory affairs leads at compression garment manufacturers underwrites the qualitative findings. Secondary validation draws from FDA 510(k) filings, EU notified body guidance documents, hospital procurement databases, and trade data for medical-grade textile imports. Bottom-up sizing across product type, material certification tier, and distribution channel segments triangulates against top-down macroeconomic indicators for maternal health expenditure.
Comparable-period anchoring to historical maternity benefit program expansion and cesarean rate trajectories establishes the forecast baseline across the analysis window. Segmentation modeling spans compression technology tier, end-user procurement authority, material biocompatibility certification, and regional regulatory cluster. CAGRs derive from volume trajectory analysis incorporating reimbursement pathway evolution and hospital infrastructure expansion rates. Forecast inputs include EU MDR implementation timelines and PMDA/MFDS harmonization progress for medical-grade textile registration.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU notified body enforcement or sudden cotton-spandex supply disruption. Practitioners should monitor employer-sponsored benefit program coverage criteria and EU clinical evaluation report rejection rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
Europe Sanitary Napkin Market
Medical and Hygiene Textiles
Feminine Wipes Market
Medical and Hygiene Textiles
Sleeping Masks Market
Medical and Hygiene Textiles
United States Sanitary Napkin Market
Medical and Hygiene Textiles
Global Antimicrobial Medical Textiles Market
Medical and Hygiene Textiles
Textile Based Ph Controllers Market
Medical and Hygiene Textiles
Period Panties Market
Medical and Hygiene Textiles
Global Diabetic Socks Market
Medical and Hygiene Textiles
Tissue Towel Market
Medical and Hygiene Textiles
GCC Sanitary Napkin Market
Medical and Hygiene Textiles
Medical Fabrics Market
Medical and Hygiene Textiles
Sanitary Napkin Market
Medical and Hygiene Textiles
Compressed Towel Market
Medical and Hygiene Textiles
Europe Adult Diaper Market
Medical and Hygiene Textiles
Global Biomedical Textiles Market
Medical and Hygiene Textiles
Absorbent Mats Market