
 Medical Smart Textile Market | 2026-2036
Medical Smart Textile Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Smart Textile Market Outlook
ISO 13485 certification cycles for wearable medical devices is collapsing from twenty-four months to under fourteen months at leading suppliers. DuPont de Nemours leverages its materials science heritage to anchor conductive fiber supply for implantable monitoring patches. Hexoskin competes on algorithmic differentiation, sustaining proprietary cardiac signal processing that reduces clinician review time. Schoeller Textil AG dominates European production of antimicrobial smart fabrics, extending its textile finishing expertise into FDA-registered cleanroom garments.
Medical smart textiles integrate conductive polymers, piezoelectric sensors, or printed circuit elements into woven, knitted, or non-woven substrates to enable continuous physiological monitoring, therapeutic delivery, or surgical navigation. Fabric conductivity thresholds typically range from 10^-1 to 10^-3 S/cm for reliable electrocardiographic signal acquisition across wash cycles. Wearable Devices and Monitoring Systems command the largest revenue pools today, though Surgical Textiles capture premium pricing due to sterilization validation requirements and shorter replacement cycles. Conductive Fibers and Biocompatible Materials form the structural backbone of supply, with Nanofibers representing the fastest-expanding material class for wound-healing applications requiring sub-micron porosity control.
FDA 510(k) premarket notification and the EU Medical Device Regulation shape product development roadmaps, with MDR's expanded clinical evidence requirements forcing manufacturers to rebuild technical documentation for legacy e-textile portfolios. The EPA regulates antimicrobial claims on treated fabrics, while ISO 10993 biocompatibility testing governs skin-contact duration classifications. Stakeholders must decide whether to pursue vertical control over sensor fabrication or rely on qualified component suppliers as regulatory scrutiny intensifies on software-enabled garments.
Market Dynamics
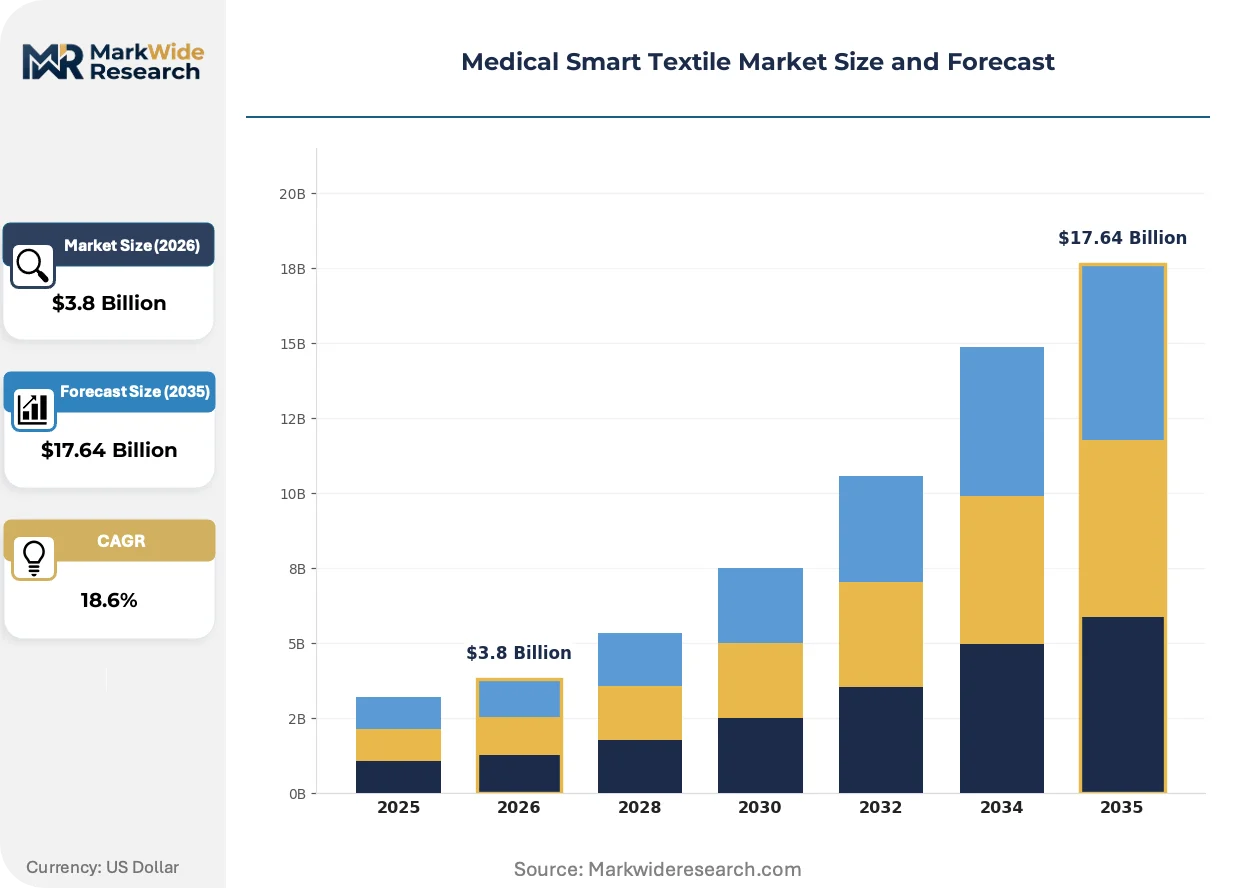
FDA 510(k) clearance compression and EU MDR clinical evidence expansion are forcing manufacturers to rebuild technical documentation for legacy e-textile portfolios while ISO 13485 certification timelines collapse at leading suppliers.
Growth Catalysts
- Remote Patient Monitoring:Hospitals and clinics are expanding procurement of connected care garments as reimbursement frameworks for continuous physiological monitoring mature in the United States, Germany, and Japan.
- Conductive Polymer Advancement:Fabric conductivity thresholds reaching 10^-1 to 10^-3 S/cm now enable reliable electrocardiographic signal acquisition across repeated wash cycles.
- EU Medical Device Regulation:MDR's expanded clinical evidence requirements, while burdensome, are accelerating consolidation among qualified suppliers and elevating barrier-to-entry for subscale competitors.
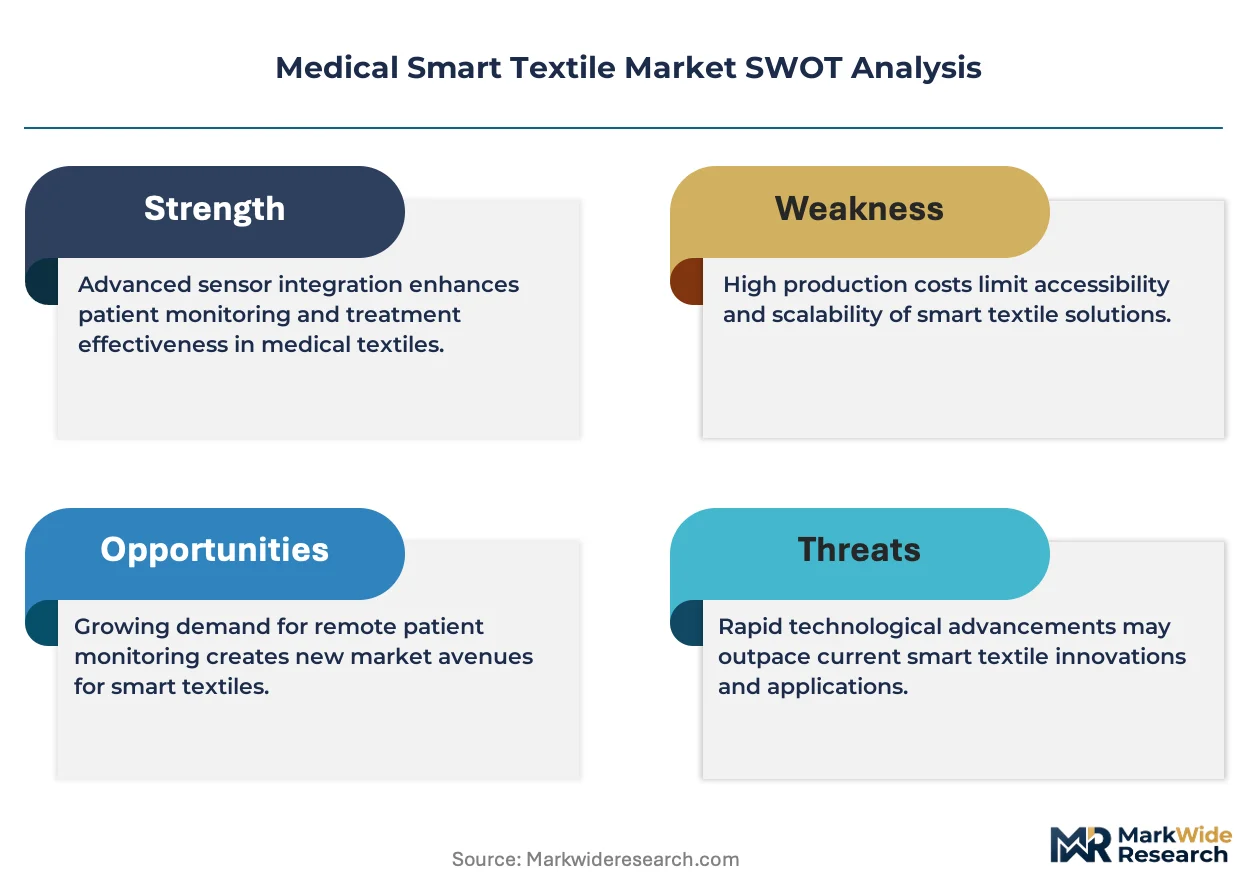
Market Restraints
- Silver Nanowire Cost Volatility:Conductive fiber inputs face price instability due to concentrated mining supply from Peru and Mexico, compressing margins on disposable monitoring patches.
- Sterilization Validation Burden:Surgical textiles require gamma or ethylene oxide cycle verification that adds eighteen to thirty-six months to product launch timelines.
- Antimicrobial Claim Friction:EPA registration requirements for treated fabrics create documentation bottlenecks that delay commercialization of infection-control garments.
Strategic Opportunities
- Wound-Healing Nanofibers:Sub-micron porosity control in electrospun materials opens acute care and chronic wound management applications previously served by traditional dressings.
- Algorithmic Differentiation:Proprietary cardiac signal processing reduces clinician review time and creates stickiness with hospital IT procurement committees.
- Cleanroom Garment Expansion:FDA-registered antimicrobial finishing expertise transfers directly into pharmaceutical manufacturing apparel with premium pricing structures.
Industry Challenges
- Software-Enabled Garment Scrutiny:FDA premarket notification requirements for algorithm-driven diagnostics force textile manufacturers to acquire or partner for software quality management capabilities.
- Biocompatibility Testing Bottlenecks:ISO 10993 skin-contact duration classifications require extended cytotoxicity and sensitization studies that strain in-house laboratory capacity.
- Legacy System Integration:Hospital electronic health record connectivity demands HL7 FHIR compliance that few heritage textile suppliers possess natively.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Smart Textile Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Wearable Devices, Monitoring Systems, Surgical Textiles, Rehabilitation Material: Conductive Fibers, Biocompatible Materials, Textiles with Sensors, Nanofibers Technology: Smart Fabrics, E-textiles, Electronic Textiles, Biomedical Wearables End User: Healthcare Providers, Patients, Research Institutions, Sports Teams |
| Companies Covered | DuPont de Nemours, Inc., Hexoskin, Schoeller Textil AG, Medtronic, 3M Company, Sensoria Inc., Toray Industries, Johnson & Johnson, AiQ Smart Clothing Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Smart Textile Market Strategic Shifts
Printed circuit integration into woven substrates is compressing the boundary between apparel and medical device, while regulatory frameworks scramble to classify software-enabled garments that deliver both monitoring and therapeutic functions.
Printed piezoelectric sensors embedded directly into knitted textiles are replacing discrete hardware modules for motion and pressure monitoring. Rehabilitation centers and eldercare facilities in Japan are piloting these systems for fall-risk assessment. The technology is miniaturizing power requirements and enabling week-long continuous wear without battery replacement.
EU MDR Article 10 clinical evaluation requirements now mandate post-market surveillance data for all Class IIa and above e-textiles, forcing manufacturers to establish European Authorized Representatives and quality management systems. Surgical navigation textiles with integrated RFID tracking face the steepest compliance burden, with German and Swiss suppliers investing in dedicated regulatory affairs teams to manage technical documentation rebuilds.
Hospital procurement committees are unbundling after-sales service from capital equipment purchases, instead demanding software-enabled textiles with predictive maintenance algorithms and remote calibration support. This shift concentrates purchasing power with integrated health systems in the United States that can negotiate enterprise-wide monitoring garment contracts. Independent community hospitals respond by joining group purchasing organizations to access equivalent pricing tiers.
Medical Smart Textile Market Segmentation
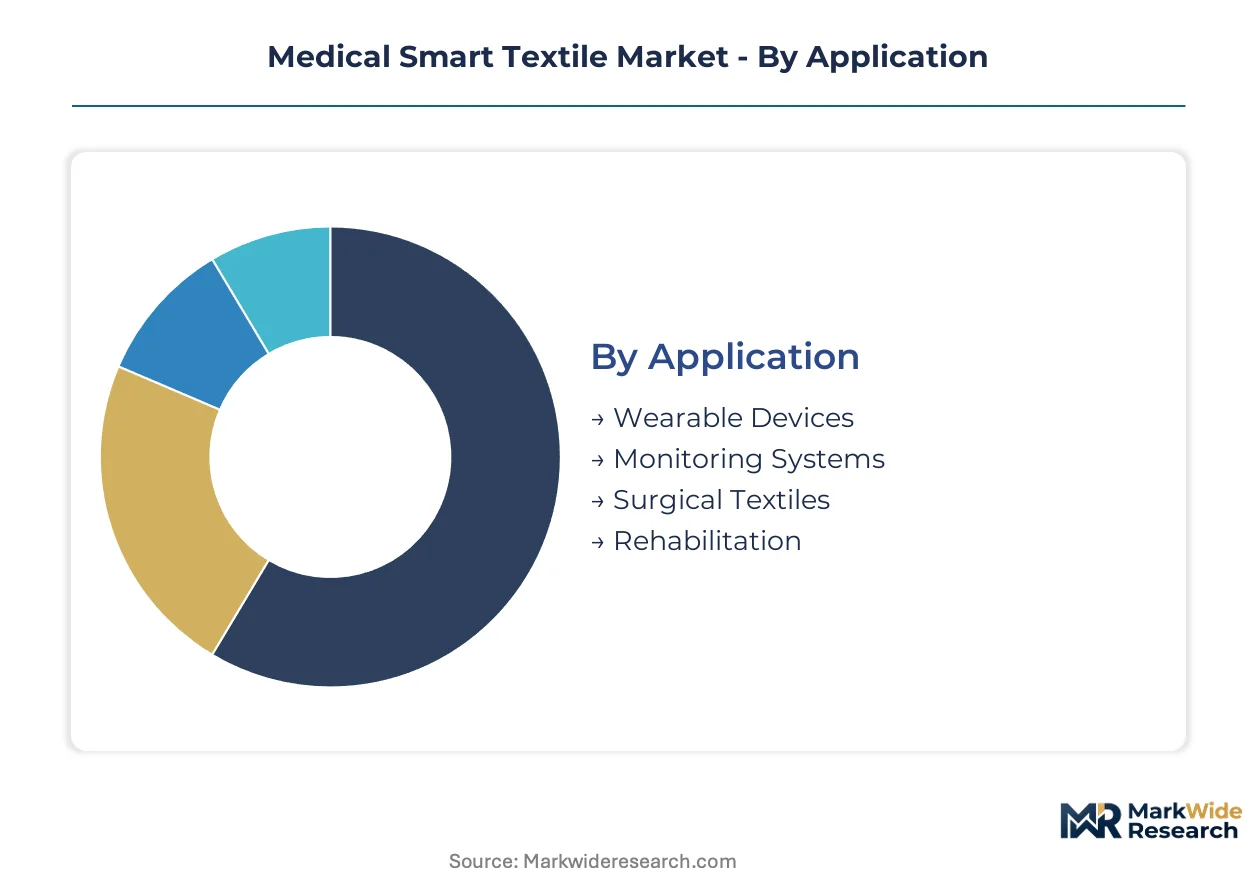
Segmentation in medical smart textiles reveals how regulatory pathways, material properties, and end-use requirements fragment commercial opportunity. Each dimension carries distinct certification burdens and margin structures that shape supplier strategy.
Application:
FDA 510(k) and EU MDR classify these applications differently, with surgical textiles facing the steepest sterilization validation requirements and wearable devices navigating software-enabled garment scrutiny.
- Wearable Devices:These integrate conductive polymers and printed circuit elements into woven or knitted substrates for continuous physiological monitoring. Demand concentrates in United States hospital systems where reimbursement frameworks for remote patient monitoring are maturing fastest, though FDA premarket notification timelines for algorithm-driven diagnostics compress development schedules.
- Monitoring Systems:Fabric-based systems achieve reliable electrocardiographic signal acquisition through conductivity thresholds of 10^-1 to 10^-3 S/cm across repeated wash cycles. German and Japanese procurement committees prioritize these garments for connected care programs, with ISO 13485 certification cycles collapsing from twenty-four months to under fourteen months at leading suppliers.
- Surgical Textiles:Gamma or ethylene oxide sterilization validation adds eighteen to thirty-six months to product launch timelines, capturing premium pricing due to shorter replacement cycles.
- Rehabilitation:Printed piezoelectric sensors embedded in knitted textiles enable motion and pressure monitoring for fall-risk assessment in Japanese eldercare facilities.
Established volume favors Wearable Devices; emerging adoption favors Rehabilitation.
Material:
Cost tiers separate commodity conductive inputs from specialized nanostructured materials with sub-micron porosity control.
- Conductive Fibers:Silver nanowire and conductive polymer threads form the structural backbone of electrocardiographic signal acquisition systems. Supply concentrates in materials science heritage suppliers serving United States implantable monitoring patch manufacturers, though price volatility from concentrated mining supply in Peru and Mexico compresses margins on disposable formats.
- Nanofibers:Electrospun materials with sub-micron porosity control enable wound-healing applications requiring precise moisture management and cell permeability. Acute care and chronic wound management demand in Germany and Japan is climbing the fastest as these materials displace traditional dressings.
- Biocompatible Materials:ISO 10993 skin-contact duration classifications govern cytotoxicity and sensitization testing requirements for extended wear applications.
- Textiles with Sensors:Printed circuit integration compresses the boundary between apparel and medical device, with EPA antimicrobial claim registration creating documentation bottlenecks for infection-control garments.
Supply concentration favors Conductive Fibers; technology differentiation favors Nanofibers.
Technology:
Application maturity separates established fabric-integrated electronics from emerging biomedical formats with therapeutic delivery capabilities.
- Smart Fabrics:Antimicrobial finishing expertise from European textile suppliers transfers directly into FDA-registered cleanroom garments for pharmaceutical manufacturing. German and Swiss suppliers dominate this segment, extending heritage finishing capabilities into premium-priced medical applications.
- Biomedical Wearables:Algorithmic differentiation in cardiac signal processing reduces clinician review time and creates procurement stickiness with United States hospital IT committees. EU MDR Article 10 clinical evaluation requirements now mandate post-market surveillance data, forcing manufacturers to establish European Authorized Representatives.
- E-textiles:Rehabilitation centers in Japan pilot knitted piezoelectric systems for week-long continuous wear without battery replacement.
- Electronic Textiles:RFID-integrated surgical navigation textiles face the steepest MDR compliance burden, with dedicated regulatory affairs teams managing technical documentation rebuilds.
Procurement scale favors Smart Fabrics; regulatory acceleration favors Biomedical Wearables.
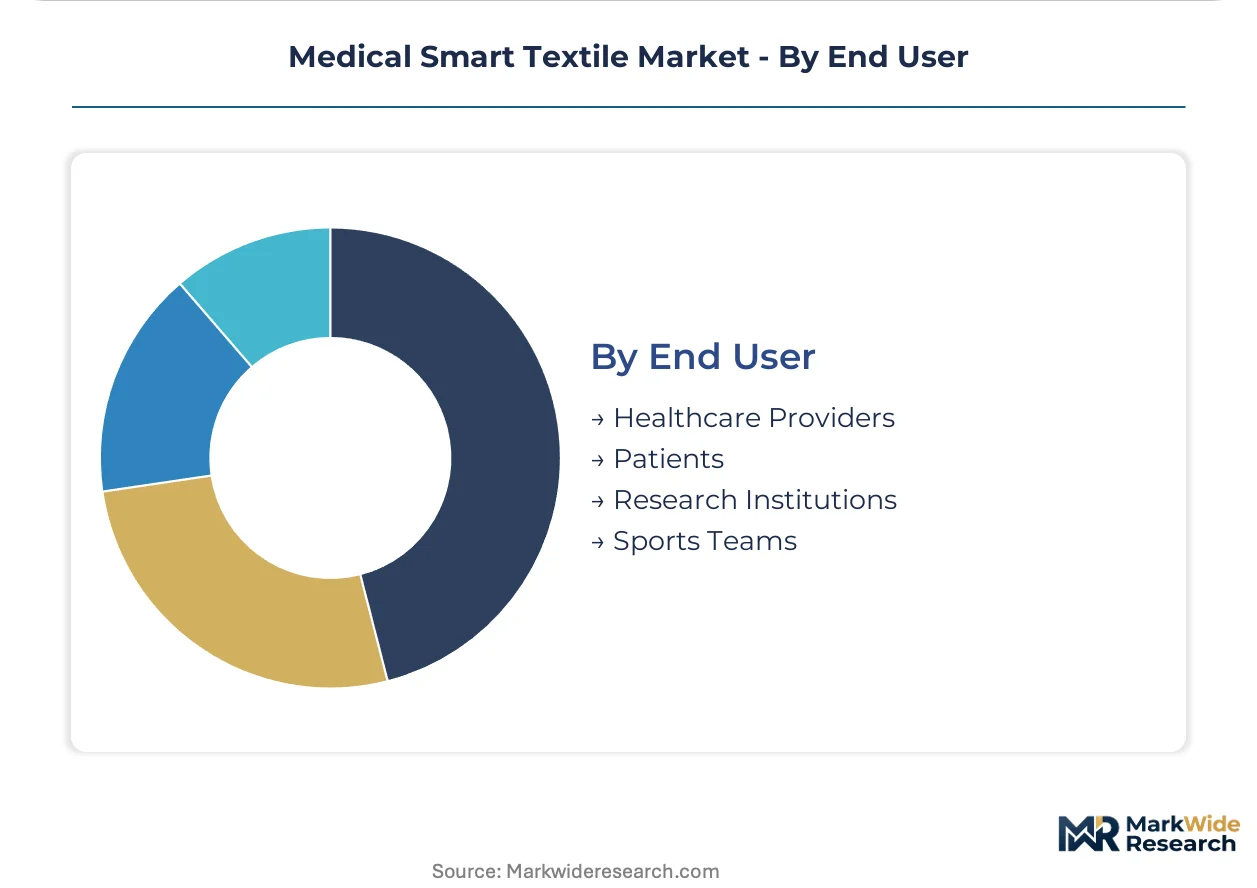
End User:
Customer type determines purchasing authority, with healthcare providers negotiating enterprise contracts and patients driving direct-to-consumer channels.
- Healthcare Providers:United States integrated health systems unbundle after-sales service from capital equipment, demanding predictive maintenance algorithms and remote calibration support. This concentrates purchasing power with systems capable of negotiating enterprise-wide monitoring garment contracts.
- Patients:Direct-to-consumer channels expand as reimbursement frameworks mature, though HL7 FHIR compliance requirements for hospital electronic health record connectivity strain heritage textile suppliers lacking native software capabilities.
- Research Institutions:Clinical evidence generation for EU MDR technical documentation rebuilds drives demand for validated sensor platforms.
- Sports Teams:Performance monitoring applications leverage cardiac signal processing algorithms originally developed for clinical settings.
Contract value favors Healthcare Providers; volume expansion favors Patients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical logistics infrastructure underwrites Europe's distribution dominance for FDA-registered cleanroom garments, while the Trans-Pacific fiber optic cables enable real-time data transmission for United States remote patient monitoring networks.
United States
Integrated health systems in Texas and California negotiate enterprise-wide monitoring garment contracts worth millions annually. FDA 510(k) premarket notification pathways compress development timelines for algorithm-driven diagnostics. Boston's medical device cluster anchors cardiac signal processing innovation, with Massachusetts General Hospital piloting week-long continuous wear systems.
Germany
The statutory health insurance system's reimbursement frameworks for connected care mature fastest in Bavaria and North Rhine-Westphalia. EU MDR Article 10 clinical evaluation requirements mandate post-market surveillance data, forcing manufacturers to establish European Authorized Representatives. Stuttgart's textile engineering corridor dominates antimicrobial finishing expertise for pharmaceutical manufacturing apparel.
Japan
Rehabilitation centers and eldercare facilities in Kanagawa Prefecture pilot knitted piezoelectric systems for fall-risk assessment. METI's aging society technology subsidies accelerate procurement of continuous physiological monitoring garments. Osaka's medical textiles cluster specializes in biocompatible materials for extended skin-contact applications.
Switzerland
Swissmedic's streamlined device registration attracts surgical navigation textile developers to the Basel-Zurich corridor. Precision manufacturing heritage from watchmaking transfers into RFID-integrated cleanroom garments with premium pricing structures. Geneva's biomedical research institutions generate clinical evidence for EU MDR technical documentation rebuilds.
United Kingdom
NHS England's remote patient monitoring procurement frameworks concentrate demand in London and the Southeast. MHRA's post-Brexit regulatory autonomy creates parallel compliance pathways distinct from EU MDR. Manchester's advanced materials cluster develops conductive polymer threads for implantable monitoring patches.
Medical Smart Textile Market Competitive Environment
Listed leaders compete with private specialists across certification velocity and algorithmic differentiation. The vendor base stratifies into three tiers: multinational conglomerates with materials science heritage, mid-cap textile specialists with regulatory affairs capabilities, and venture-backed algorithm developers. Two strategic archetypes dominate: suppliers pursuing backward integration into sensor fabrication, and platform players licensing predictive maintenance software to hospital systems. M&A activity concentrates on software quality management acquisitions, while capacity expansion targets FDA-registered cleanroom garment production.
Within the materials heritage tier, DuPont de Nemours, Inc. anchors conductive fiber supply for implantable formats, while Toray Industries exemplifies Asian precision manufacturing scale. Hexoskin occupies a specialist position in algorithmic cardiac signal processing, reducing clinician review time through proprietary analytics. These three represent distinct competitive vectors: chemical conglomerate, diversified industrial, and pure-play software-enabled textile developer.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| Hexoskin |
| Schoeller Textil AG |
| Medtronic |
| 3M Company |
| Sensoria Inc. |
| Toray Industries |
| Johnson & Johnson |
| AiQ Smart Clothing Inc |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at ISO 13485-certified facilities in Germany and the United States shapes both supply concentration and price floors for medical smart textiles, with sterilization-validated surgical textile production commanding premium positioning over disposable monitoring patches.
Pricing Analysis
Certification level creates the primary spread between premium FDA-registered cleanroom garments and economy-tier disposable monitoring patches. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 10993 biocompatibility testing depth and algorithmic software enablement. Cost compression in economy-tier conductive fiber inputs is intensifying because silver nanowire supply volatility from Peru and Mexico concentrates margin pressure. Hospital group purchasing organizations exhibit highest price sensitivity, while integrated health systems negotiating enterprise contracts demonstrate lowest sensitivity due to bundled service demands.
Supply Chain Analysis
Strait of Malacca transit routes anchor silver nanowire feedstock movement from Peruvian mining operations to Asian conductive fiber processors. Manufacturing concentrates in Germany for antimicrobial finishing, the United States for implantable monitoring patch assembly, and Japan for biocompatible nanofiber electrospinning. Raw material dependencies span silver nanowires, piezoelectric polymer films, and medical-grade silicone substrates. Single-source vulnerability in gamma sterilization facility access creates bottleneck risk for surgical textile launches. Distribution runs through pharmaceutical logistics hubs at the Port of Rotterdam for European cleanroom garment deployment and regional hospital distribution centers for North American remote patient monitoring networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among United States integrated health systems has shifted negotiating leverage toward buyers capable of demanding predictive maintenance algorithms and remote calibration support at scale.
For Market Incumbents: Shield algorithmic differentiation advantages by deepening proprietary cardiac signal processing capabilities that reduce clinician review time. Acquire software quality management competencies to address FDA premarket notification requirements for diagnostic-enabled garments. Backward integration into conductive polymer fabrication secures supply continuity against silver nanowire price volatility from concentrated mining sources. For New Entrants and Emerging Players: Differentiate on wound-healing nanofiber applications requiring sub-micron porosity control, where traditional dressing displacement creates white-space opportunity in German and Japanese acute care settings. Target rehabilitation centers and eldercare facilities in Japan piloting piezoelectric knitted systems for fall-risk assessment. Pursue direct-to-consumer channels as reimbursement frameworks mature, leveraging HL7 FHIR compliance partnerships with health IT specialists to bypass heritage textile supplier limitations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors algorithm-enabled textile developers with established European Authorized Representative infrastructure for EU MDR Article 10 compliance. Long-term viability rests on software-enabled garment capabilities rather than commodity conductive fiber production. Acquisition target archetype: mid-cap specialists with regulatory affairs teams managing technical documentation rebuilds. Signal to watch: FDA 510(k) clearance velocity for algorithm-driven diagnostics as inflection indicator for platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Premarket Notification | Compresses development timelines for algorithm-enabled diagnostic garments in United States hospital systems. |
| EU MDR Technical Documentation Rebuild | Forces manufacturers to establish European Authorized Representatives and quality management systems for legacy portfolios. |
| Hospital System Partnership | Concentrates purchasing power with integrated health systems negotiating enterprise-wide monitoring garment contracts. |
| Software Companion Development | Enables predictive maintenance algorithms and remote calibration support demanded by procurement committees. |
| Reimbursement Strategy | Aligns product positioning with maturing frameworks for connected care in Germany, Japan, and United States markets. |
Study Parameters
Operator-level perspectives from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and ISO certification registries. Bottom-up segment sizing triangulated against top-down market estimates across application, material, technology, and end-user dimensions.
Sensitivity analysis tested forecast robustness across regulatory approval velocity scenarios and reimbursement framework maturation patterns. Segmentation modeling incorporated application type, material class, technology format, and end-user purchasing authority. CAGRs derived from historical trajectory analysis and forward-looking adoption curve projections. Industry-specific inputs included ISO 13485 certification cycle compression rates and FDA premarket notification timeline trends.
The analysis sits within stated boundaries; outcomes outside assumed regulatory pathway efficiencies and reimbursement framework maturation would require recalibration. Forecasts reflect documented assumptions regarding silver nanowire supply stability and sterilization validation capacity expansion. Practitioners should keep alternative scenarios live as EU MDR enforcement intensity and FDA software-enabled garment scrutiny evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
Global Biomedical Textiles Market
Medical and Hygiene Textiles
Antimicrobial Polyamide Textiles Market
Medical and Hygiene Textiles
Period Panties Market
Medical and Hygiene Textiles
Global Surgical Drapes and Gowns Market
Medical and Hygiene Textiles
Global Antimicrobial Medical Textiles Market
Medical and Hygiene Textiles
Arm Pouches Market
Medical and Hygiene Textiles
Europe Adult Diaper Market
Medical and Hygiene Textiles
Global Maternity Support Product Market
Medical and Hygiene Textiles
Global Feminine Hygiene Wash Market
Medical and Hygiene Textiles
Compressed Towel Market
Medical and Hygiene Textiles
Medical Non-Woven Disposables Market
Medical and Hygiene Textiles
Global Healthcare Fabrics Market
Medical and Hygiene Textiles
Tissue Towel Market
Medical and Hygiene Textiles
Washable and Reusable Mask Market
Medical and Hygiene Textiles
Sleeping Masks Market
Medical and Hygiene Textiles
Breast Pads Market