
 Global Diabetic Socks Market | 2026-2036
Global Diabetic Socks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Diabetic Socks Market Foresight
Hospital procurement departments are redrawing demand patterns for diabetic socks, shifting volume toward clinically validated compression and seamless designs. SIGVARIS leverages its vascular therapy heritage to anchor premium positioning in European clinical channels. 3M competes through materials science leadership, sustaining R&D intensity in moisture-wicking synthetic blends. Orthofeet specializes in orthopedic integration, dominating the overlap between diabetic foot care and broader mobility support categories.
Diabetic socks are engineered textile garments incorporating graduated compression zones, moisture-wicking fibers, and seamless toe closures to mitigate neuropathic ulcer risk and circulatory impairment in diabetic patients. Manufacturing specifications typically specify 15-20 mmHg compression gradients and silver-ion antimicrobial treatments to meet clinical hygiene protocols. Compression socks and non-binding socks represent the mature revenue core, with margin pools concentrating in silver-infused fabric variants where material differentiation commands pricing premiums. Online retailers and medical supply stores are expanding fastest as distribution channels, though pharmacies retain structural importance for prescription-integrated reimbursement pathways.
The FDA regulates diabetic compression garments under medical device quality standards, while the EU MDR and CE marking requirements enforce biocompatibility testing for skin-contact textiles across European markets. Japan's PMDA and METI coordinate standards alignment for imported therapeutic textiles, creating layered compliance burdens for cross-border suppliers. Stakeholders must monitor evolving reimbursement classifications for preventive foot care products as healthcare systems recalibrate spending toward complication avoidance.
Market Dynamics
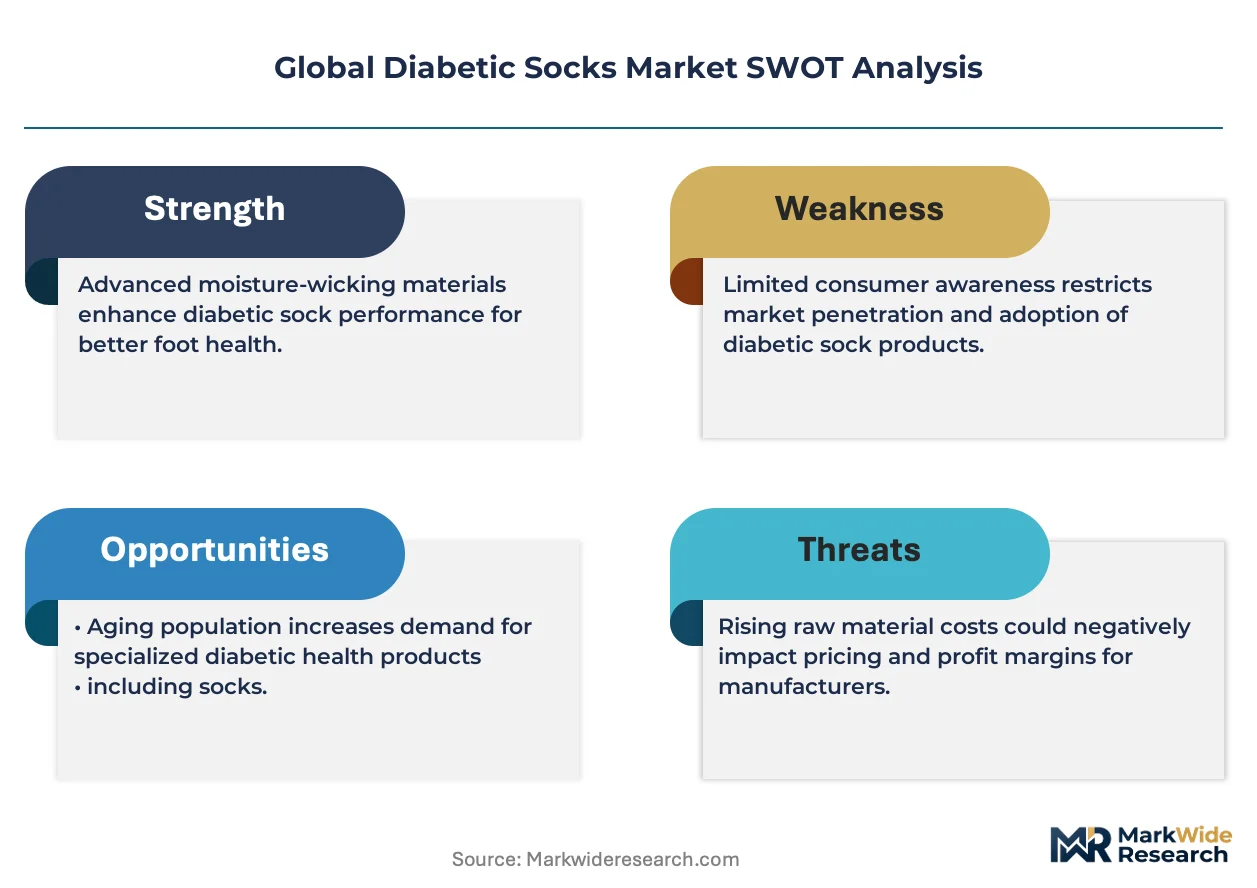
Hospital procurement departments are consolidating vendor relationships around clinically validated compression garments, forcing manufacturers to absorb EU MDR biocompatibility testing costs while maintaining price competitiveness against generic imports.
Growth Catalysts
- FDA Medical Device Classification:Updated guidance for compression garments elevates quality benchmarks, filtering out non-compliant suppliers and expanding addressable market share for certified manufacturers in US hospital channels.
- Silver-ion antimicrobial integration:Material science advances in fiber treatment protocols meet clinical hygiene standards, enabling premium pricing in wound care and post-surgical recovery applications.
- Brazil:Standardization of diabetic foot care protocols in public health systems is accelerating institutional procurement of graduated compression socks through SUS reimbursement pathways.
Market Restraints
- Synthetic fiber cost volatility:Nylon and spandex input prices fluctuate with petrochemical feedstock markets, compressing margins for moisture-wicking blend manufacturers without long-term supply contracts.
- China concentration risk:Bulk textile weaving and antimicrobial finishing capacity clusters in Zhejiang and Jiangsu provinces, exposing supply chains to regional logistics disruptions and tariff exposure.
- Compression gradient precision limits:Current knitting machinery struggles to maintain consistent 15-20 mmHg pressure distribution across size ranges, generating quality control rejections and inventory write-downs.
Strategic Opportunities
- Japan:METI's preventive healthcare subsidies for diabetic complications create reimbursement tailwinds for therapeutic socks distributed through home healthcare agencies and eldercare facilities.
- Smart textile convergence:Integration of conductive yarn sensors with graduated compression designs enables continuous temperature and pressure monitoring, opening remote patient monitoring revenue streams.
- Direct-to-patient subscription models:Online retailers bypass pharmacy markups and insurance pre-authorization delays, capturing recurring revenue from insulin-dependent patients managing chronic foot conditions.
Industry Challenges
- ISO 13485 certification timelines:Medical device quality management system audits for compression garment manufacturers extend 12-18 months, delaying market entry for new product variants.
- Seamless toe closure engineering:Specialized knitting technician shortages constrain production scaling for neuropathy-optimized designs, creating order backlogs during seasonal demand spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Diabetic Socks Market |
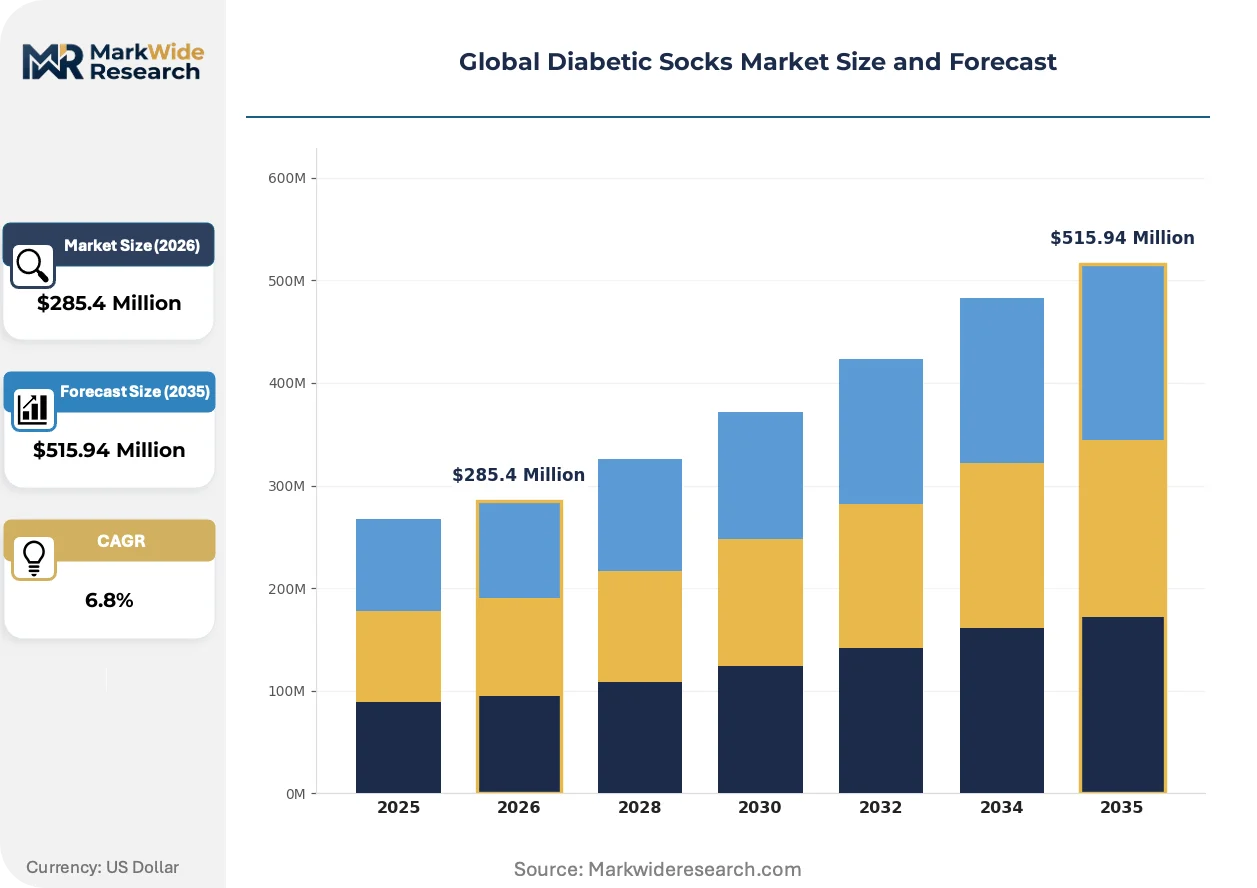
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compression Socks, Seamless Socks, Non-binding Socks, Moisture-wicking Socks, Thermal Socks Material: Cotton, Bamboo Fiber, Wool, Synthetic Blends, Silver-infused Fabrics End User: Adults, Elderly, Athletes, Post-operative Patients, Diabetic Patients Distribution Channel: Online Retailers, Pharmacies, Medical Supply Stores, Specialty Clinics, Supermarkets |
| Companies Covered | SIGVARIS, 3M, BSN Medical, Thorlo, Cupron, Orthofeet, Syounaa, Therafirm, DJO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Diabetic Socks Market Shifts & Advancements
Material science and regulatory harmonization are reshaping competitive differentiation in diabetic sock manufacturing, with functional performance claims now requiring documented clinical validation rather than marketing assertion.
Graduated compression engineering is bifurcating between hospital-grade precision garments and consumer wellness variants with loosely calibrated pressure zones. German vascular clinics specify millimeter-accurate gradient mapping for post-ulcer recovery protocols. Japanese home healthcare agencies accept wider tolerance ranges for preventive daily wear, segmenting manufacturing standards and pricing architecture.
EU MDR biocompatibility testing mandates for skin-contact textiles enforce ISO 10993 cytotoxicity and sensitization protocols across all CE-marked compression garments. Manufacturers must submit technical documentation for silver-ion antimicrobial treatments and synthetic fiber compositions. French and Italian clinical distributors now require batch-level traceability certificates, elevating compliance costs for non-European suppliers seeking market access.
Hospital procurement teams are consolidating annual contracts around outcome-validated suppliers, displacing fragmented spot purchasing from multiple vendors. Integrated delivery networks in the US negotiate multi-year agreements with guaranteed ulcer-prevention performance metrics. German Krankenkassen regional associations direct reimbursement toward contracted manufacturers with documented amputation-reduction data, concentrating volume among clinically proven brands.
Global Diabetic Socks Market Segmentation
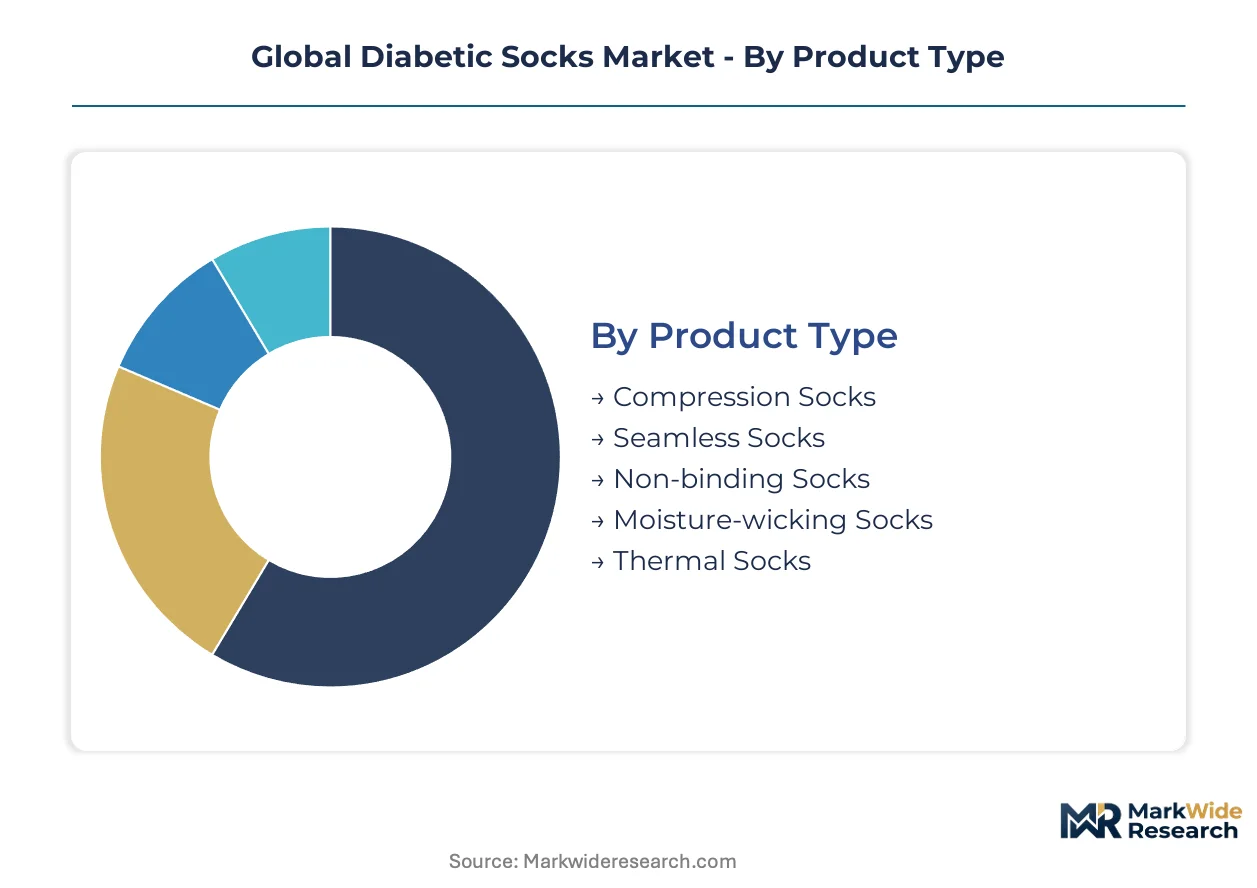
Segmentation in diabetic socks reveals how clinical validation requirements and reimbursement pathways fragment demand across product architectures. Material specifications and distribution channel economics create distinct margin pools that reward specialized manufacturing capabilities over commodity production.
Product Type:
Domestic hospital procurement concentrates in precision-engineered compression variants, while export-led demand favors consumer-accessible seamless and non-binding designs for home healthcare channels.
- Compression Socks:Graduated 15-20 mmHg pressure zones engineered through circular knitting machines with calibrated needle density. German vascular clinics and US integrated delivery networks specify millimeter-accurate gradient mapping for post-ulcer recovery protocols, absorbing premium pricing for ISO 13485-certified output.
- Seamless Socks:Flat-knit toe closures eliminate friction points that trigger neuropathic ulceration in diabetic patients with advanced peripheral neuropathy. Japanese home healthcare agencies and Brazilian SUS-contracted distributors prioritize this architecture for preventive daily wear, driving volume through eldercare facility procurement.
- Non-binding Socks:Loose-top cuffs prevent tourniquet effects on compromised lower-limb circulation.
- Moisture-wicking Socks:Synthetic fiber blends transport perspiration away from skin surfaces to reduce maceration risk.
- Thermal Socks:Insulated constructions maintain foot temperature stability for patients with autonomic neuropathy affecting thermoregulation.
Compression socks hold the largest share; momentum sits with seamless variants as home healthcare agencies expand preventive procurement.
Material:
Cost tier stratification separates premium silver-infused and bamboo fiber constructions from volume-standard cotton and synthetic alternatives.
- Silver-infused Fabrics:Ion-impregnated fibers deliver continuous antimicrobial action against Staphylococcus aureus and Pseudomonas aeruginosa colonization in wound-adjacent skin. EU MDR biocompatibility testing under ISO 10993 cytotoxicity protocols elevates compliance costs, filtering supplier participation to capitalized manufacturers with technical documentation capabilities.
- Synthetic Blends:Nylon-spandex compositions enable graduated compression engineering with dimensional stability through repeated laundering. Petrochemical feedstock volatility compresses margins for producers without long-term polymer supply contracts, concentrating production among vertically integrated textile groups.
- Cotton:Natural fiber base for non-binding casual wear segments with limited compression functionality.
- Bamboo Fiber:Cellulose-derived material with inherent moisture absorption and thermal regulation properties.
- Wool:Merino variants provide temperature buffering for cold-climate diabetic populations.
Silver-infused fabrics command premium positioning; synthetic blends scale fastest through hospital contract manufacturing.
End User:
Application severity divides the market between acute clinical recovery segments and chronic condition management populations.
- Diabetic Patients:Core addressable population with diagnosed peripheral neuropathy or circulatory impairment requiring daily preventive foot care. Medicare Advantage plans and German Krankenkassen regional associations direct reimbursement toward documented amputation-reduction suppliers, concentrating volume among clinically validated brands.
- Elderly:Aging demographics with comorbid diabetes and mobility limitations drive institutional procurement through nursing home and assisted living facility channels. Japan's METI preventive healthcare subsidies accelerate therapeutic sock distribution through home healthcare agencies.
- Adults:Working-age diabetics managing foot health alongside occupational demands.
- Post-operative Patients:Surgical recovery populations requiring graduated compression for edema management.
- Athletes:Insulin-dependent recreational competitors seeking performance-oriented moisture management.
Diabetic patients represent the foundational volume base; elderly segments are expanding most quickly through institutional procurement centralization.
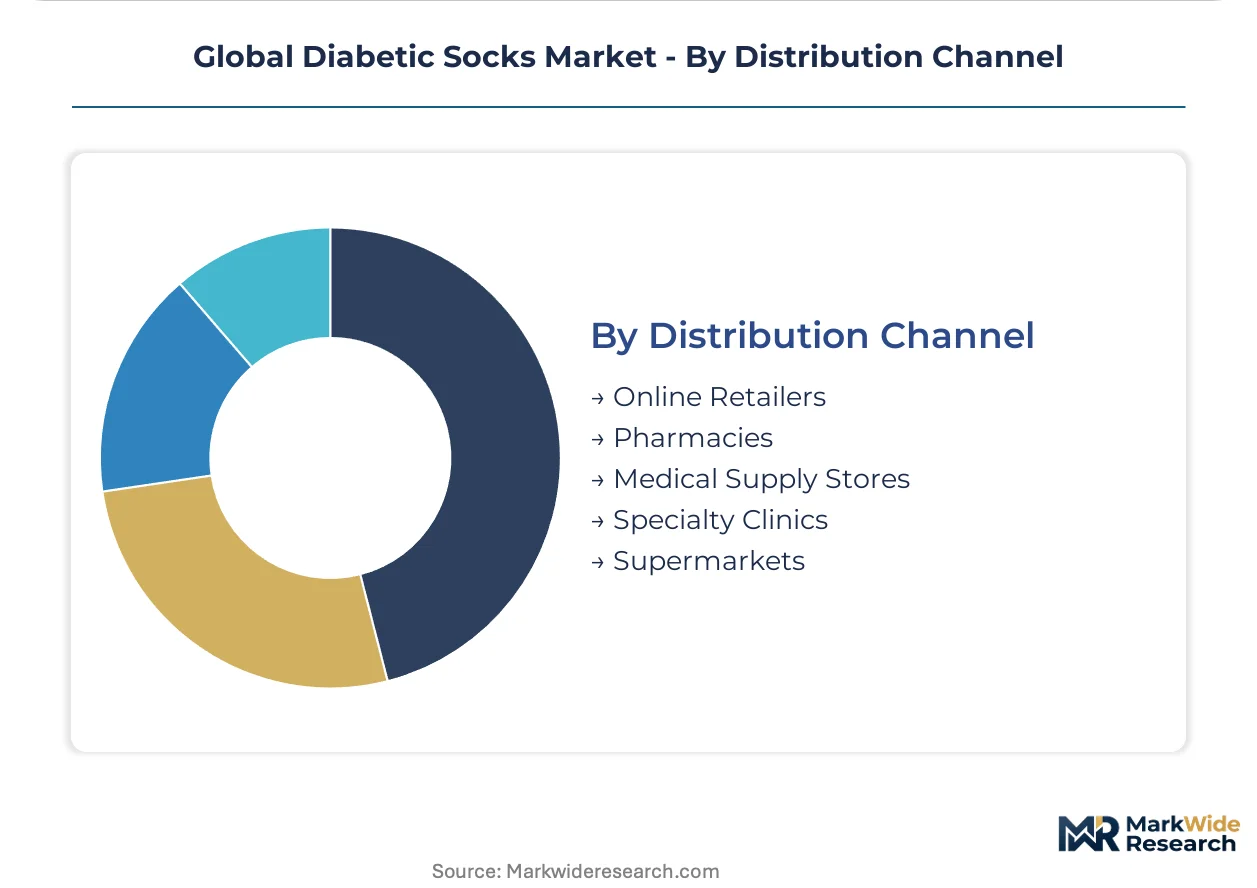
Distribution Channel:
Customer type fragmentation separates prescription-integrated reimbursement pathways from direct-to-consumer accessibility.
- Online Retailers:Direct-to-patient platforms bypass pharmacy markups and insurance pre-authorization delays through subscription-based recurring revenue models. Specialized diabetic footwear e-commerce operators capture insulin-dependent patients managing chronic foot conditions with educational content and fit-guarantee policies.
- Pharmacies:Brick-and-mortar dispensaries retain structural importance for prescription-integrated reimbursement pathways and pharmacist consultation on compression gradient selection. US retail pharmacy chains negotiate preferred supplier arrangements with major compression garment manufacturers.
- Medical Supply Stores:Durable medical equipment distributors serve hospital discharge planning and home health agency procurement.
- Specialty Clinics:Vascular and podiatry practices provide clinical fitting services for precision compression garments.
- Supermarkets:Mass-market retailers stock basic non-binding cotton socks for undiagnosed prediabetic populations.
Pharmacies retain the largest transaction volume; online retailers gain share fastest through subscription model penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's European distribution networks enable German manufacturers to reach vascular clinics across the continent within 48 hours, cementing the country's central logistics role in diabetic sock supply chains.
United States
Medicare Advantage plans and integrated delivery networks consolidate procurement around ISO 13485-certified suppliers with documented amputation-reduction data. The FDA's updated medical device classification guidance for compression garments elevates quality benchmarks and filters non-compliant suppliers from hospital channels. Boston's medical device corridor anchors R&D activity in smart textile convergence for remote patient monitoring applications.
Germany
Krankenkassen regional associations direct reimbursement toward manufacturers with clinically validated outcomes, concentrating volume among proven brands. The EU MDR enforces biocompatibility testing under ISO 10993 cytotoxicity protocols for all CE-marked compression garments. The Ruhr Valley textile engineering cluster hosts precision knitting operations serving vascular clinics specifying millimeter-accurate gradient mapping.
Japan
METI's preventive healthcare subsidies for diabetic complications accelerate therapeutic sock distribution through home healthcare agencies and eldercare facilities. The PMDA coordinates standards alignment with METI for imported therapeutic textiles, creating layered compliance requirements for foreign suppliers. Osaka's medical textile manufacturers specialize in seamless toe closure designs for aging populations with advanced peripheral neuropathy.
Brazil
Standardization of diabetic foot care protocols within the SUS public health system accelerates institutional procurement of graduated compression socks through reimbursement pathways. ANVISA regulates therapeutic textiles as medical devices, requiring in-country registration for market access. São Paulo's industrial textile belt concentrates antimicrobial finishing capacity serving domestic hospital networks and export markets.
China
Domestic diabetes prevalence drives hospital procurement of compression garments, though export manufacturing dominates production volumes. The NMPA's medical device classification system governs therapeutic textile imports, with GB standards applying to domestic manufacture. Zhejiang and Jiangsu provinces cluster bulk textile weaving and silver-ion antimicrobial finishing capacity, exposing supply chains to regional logistics concentration risks.
Global Diabetic Socks Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with publicly traded medical device conglomerates leveraging balance sheet capacity to absorb EU MDR compliance costs while family-owned textile firms defend niche positioning through orthopedic specialization. The vendor base stratifies into three archetypes: vascular therapy heritage brands, materials science conglomerates, and orthopedic integration specialists. Dominant competitive moves include ISO 13485 certification acceleration and direct-to-patient subscription model deployment through specialized e-commerce platforms.
Within the vascular therapy tier, SIGVARIS anchors premium positioning through clinical channel relationships, while 3M exemplifies materials science leverage in moisture-wicking synthetic fiber development. Orthofeet occupies a position at the intersection of diabetic foot care and broader mobility support, representing the orthopedic integration archetype that dominates overlap categories between therapeutic garments and assistive devices.
| Leading Market Players |
|---|
| SIGVARIS |
| 3M |
| BSN Medical |
| Thorlo |
| Cupron |
| Orthofeet |
| Syounaa |
| Therafirm |
| DJO |
| Others |
Supply & Pricing Matrix
Antimicrobial finishing capacity utilization in Zhejiang and Jiangsu provinces shapes both supply concentration and price floors, as silver-ion treatment throughput constraints limit premium-grade output expansion while EU MDR compliance costs harden entry barriers for lower-tier competitors.
Pricing Analysis
Volume-discount tiering structures separate hospital system annual contracts from spot purchases through medical supply distributors. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification status and silver-ion antimicrobial integration depth. Pricing pressure stems from synthetic fiber cost volatility tied to petrochemical feedstock markets, compressing margins for moisture-wicking blend manufacturers lacking long-term nylon and spandex supply contracts. Home healthcare agencies exhibit highest price sensitivity due to reimbursement rate caps, while German vascular clinics absorb premium pricing for millimeter-accurate gradient mapping.
Supply Chain Analysis
China anchors bulk textile weaving and antimicrobial finishing capacity, with Zhejiang and Jiangsu provinces hosting the majority of silver-ion treatment lines serving global demand. Manufacturing draws from petrochemical-derived nylon and spandex polymers, copper-based antimicrobial agents, and precision circular knitting machinery. Single-source vulnerability concentrates in Chinese antimicrobial finishing capacity, exposing downstream buyers to regional logistics disruptions and tariff exposure. Distribution runs through Rotterdam's European distribution networks for German and French clinical channels, while direct-to-patient platforms bypass traditional pharmacy and medical supply store intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generic compression garment imports and consumer wellness variants with loosely calibrated pressure zones threaten to commoditize the diabetic sock category, forcing incumbents to defend clinical validation moats.
For Market Incumbents: Consolidate hospital procurement relationships through multi-year outcome-guaranteed contracts with documented ulcer-prevention performance metrics. Accelerate ISO 13485 certification maintenance to filter non-compliant competitors from integrated delivery network vendor pools. Deepen backward integration into silver-ion fiber treatment capacity to secure antimicrobial supply against Zhejiang province concentration risk.
For New Entrants and Emerging Players: Differentiate on smart textile convergence by integrating conductive yarn sensors with graduated compression designs for remote patient monitoring revenue streams. Target Japan's home healthcare agency channel where METI preventive healthcare subsidies create reimbursement tailwinds for therapeutic sock newcomers. Deploy direct-to-patient subscription models through specialized diabetic footwear e-commerce platforms to bypass pharmacy markup structures.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with hospital system annual contracts and eldercare facility procurement relationships. Five-to-ten year viability favors capitalized players with EU MDR technical documentation capabilities and batch-level traceability systems. Monitor FDA medical device classification guidance revisions as inflection indicators for US hospital channel access barriers.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Acceleration | ISO 10993 biocompatibility testing opens CE-marked access to German Krankenkassen reimbursement pathways. |
| Smart Textile Sensor Integration | Conductive yarn convergence enables continuous pressure monitoring for remote patient monitoring revenue streams. |
| Direct-to-Patient Subscription Launch | Online platforms bypass pharmacy markups and insurance pre-authorization delays for insulin-dependent populations. |
| Hospital System Partnership | Integrated delivery network contracts guarantee volume through outcome-validated ulcer-prevention performance metrics. |
| Antimicrobial Fiber Backward Integration | In-house silver-ion treatment capacity secures supply against Zhejiang province logistics concentration risk. |
Research Methodology
Cross-validation between primary interviews with vascular clinic procurement managers, hospital purchasing committee members, biomedical engineers, and GPO contracts managers anchors the qualitative findings against secondary validation from FDA medical device classification guidance documents, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up and top-down triangulation reconciles manufacturer shipment data with end-user consumption patterns across compression sock, seamless sock, and non-binding sock product architectures.
Sensitivity analysis across material cost scenarios, regulatory compliance timelines, and reimbursement rate assumptions tests forecast robustness over the projection horizon. Segmentation dimensions modeled include product type, material specification, end user severity tier, and distribution channel economics. CAGRs derive from fitted growth curves calibrated against historical procurement volume trajectories in German, Japanese, Brazilian, and US hospital systems, with silver-ion antimicrobial adoption curves and smart textile penetration rates as industry-specific forecast inputs.
Material uncertainties — synthetic fiber cost volatility, EU MDR audit timeline extensions, and SUS reimbursement pathway modifications in Brazil — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued standardization of diabetic foot care protocols and stable antimicrobial treatment capacity utilization. Recalibration cycles align with material shifts in FDA guidance revisions, METI subsidy program adjustments, and ANVISA medical device registration requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
GCC Sanitary Napkin Market
Medical and Hygiene Textiles
Medical Non-Woven Disposables Market
Medical and Hygiene Textiles
Global Antimicrobial Medical Textiles Market
Medical and Hygiene Textiles
Examination Gowns Market
Medical and Hygiene Textiles
Textile Implants Market
Medical and Hygiene Textiles
Intestinal Wash Bags Market
Medical and Hygiene Textiles
Sanitary Napkin Market
Medical and Hygiene Textiles
Breast Pads Market
Medical and Hygiene Textiles
Medical Textiles Market
Medical and Hygiene Textiles
Antimicrobial Textiles Market
Medical and Hygiene Textiles
North America Sanitary Napkin Market
Medical and Hygiene Textiles
Sanitary Napkins Machine Market
Medical and Hygiene Textiles
Textile Based Ph Controllers Market
Medical and Hygiene Textiles
Latin America Sanitary Napkin Market
Medical and Hygiene Textiles
United States Sanitary Napkin Market
Medical and Hygiene Textiles
Examination Gloves Market