
 Battery Cases Market | 2026-2036
Battery Cases Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Cases Market Analysis
Subscription-based battery health monitoring and software-defined charge management is pivoting how vendors monetize protective power accessories. Mophie leverages its brand heritage in premium power accessories to sustain direct-to-consumer loyalty. Anker competes through aggressive R&D intensity in gallium nitride charging circuits that extend to case-integrated architectures. OtterBox dominates rugged compatibility certifications for industrial and military-spec device protection.
Battery cases are detachable protective enclosures incorporating lithium-polymer cells, typically rated between 2,000 mAh and 5,000 mAh, with integrated power management ICs regulating pass-through charging and thermal dissipation; their commercial purpose centers on extending operational uptime for mobile devices where wall access is unreliable. Plastic remains the volume leader due to cost-efficient injection molding, yet aluminum is capturing margin pools as thermal conductivity becomes a purchase criterion for gaming and video-streaming users. Compatibility with smartphones anchors revenue, while tablet-oriented cases represent a narrower but higher-average-selling-price niche where slim-style designs command premium positioning.
The EU's REACH and RoHS frameworks restrict hazardous substances in battery case polymers and solder joints, while the CSRD pushes brands to disclose circular-economy metrics that affect supplier qualification. In the United States, the FAA's lithium battery carriage rules shape product labeling and retail packaging for air-travel retail channels. Stakeholders must monitor whether emerging right-to-repair mandates in multiple jurisdictions will force modular battery architectures that alter case thickness and material selection trade-offs.
Market Dynamics
The EU's Ecodesign for Sustainable Products Regulation is forcing material-recovery redesigns across battery case supply chains, compressing design cycles and elevating circular-economy compliance as a procurement gate for OEM partnerships.
Growth Catalysts
- Smartphone power users in outdoor and field-service roles:Extended uptime requirements from logistics, construction, and emergency-response professionals are pulling high-capacity cases into enterprise procurement catalogs.
- REACH and RoHS frameworks:European substance restrictions are accelerating substitution of halogenated flame retardants with phosphorus-based alternatives in polymer housings.
- Gallium nitride charging circuits:Thermal efficiency gains from GaN ICs are enabling thinner case profiles without sacrificing mAh density, opening premium positioning for gaming and streaming segments.
Market Restraints
- Lithium-polymer cell supply concentration:Shenzhen-based cell manufacturers control over 70% of global pouch cell output, creating single-source vulnerability for Western case assemblers.
- FAA lithium battery carriage rules:Air-travel retail channels face packaging and labeling complexity that elevates logistics costs and limits impulse-purchase placement.
- Wireless charging pad substitution:Stationary Qi infrastructure expansion in offices and vehicles is reducing dependency on portable power augmentation for urban professionals.
Strategic Opportunities
- Software-defined charge management:Subscription-based battery health analytics are expanding into enterprise fleet management, creating recurring revenue streams detached from hardware refresh cycles.
- Tablet-oriented slim-style designs:Higher average selling prices in the narrower tablet accessory niche reward thermal engineering precision for creative professionals and medical field staff.
- Right-to-repair mandates:Emerging modular battery architecture requirements across multiple jurisdictions are favoring vendors with in-house industrial design capabilities over pure contract manufacturers.
Industry Challenges
- Thermal engineering talent scarcity:Cross-disciplinary expertise combining polymer science, power electronics, and RF interference mitigation commands premium compensation and extends hiring timelines.
- CSRD circular-economy disclosure timelines:Supplier qualification audits for Scope 3 emissions and material provenance are compressing product development schedules and elevating documentation overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Cases Market |
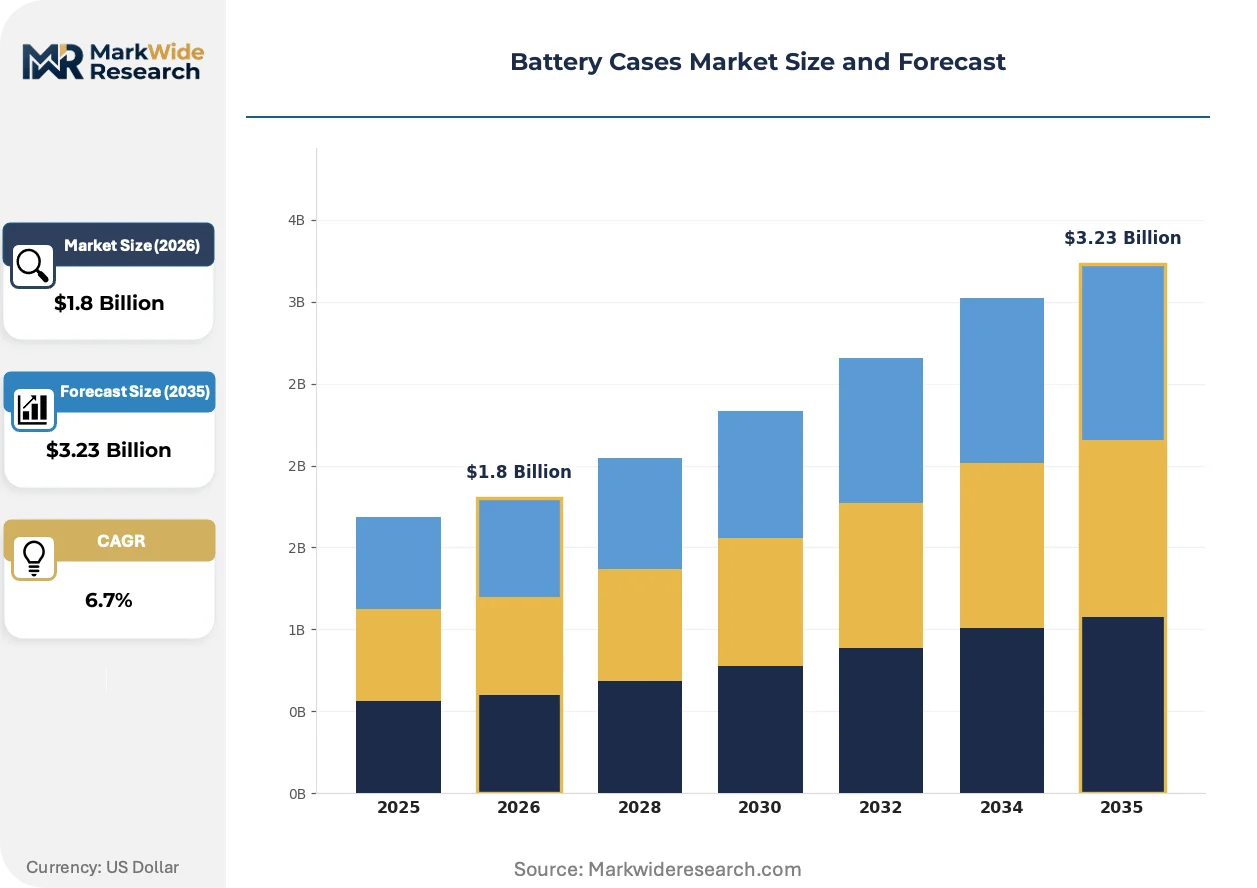
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Silicone, Aluminum, Leather Compatibility: Smartphones, Tablets, Laptops, Cameras Style: Rugged, Slim, Wallet, Folio Market Type: Retail, Online, Wholesale, Direct |
| Companies Covered | ZAGG, ZeroLemon, Mophie, RAVPower, Mophie Powerstation, Belkin, OtterBox, Spigen, Anker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Cases Market Emerging Trajectories
Active materials substitution and embedded intelligence architectures are redefining competitive differentiation in protective power accessories, shifting value capture toward thermal performance and predictive analytics capabilities.
Aluminum unibody construction is expanding into mid-tier battery case portfolios as gaming and video-streaming users prioritize heat dissipation over injection-molded plastic cost advantages. Mobile esports competitors and content creators now specify thermal conductivity metrics in purchase decisions, compressing margins for pure polycarbonate suppliers. This material migration is expanding into enterprise ruggedization specifications where aluminum's EMI shielding properties satisfy military-grade compatibility requirements.
The EU's Ecodesign for Sustainable Products Regulation is mandating minimum recycled content thresholds and end-of-life take-back infrastructure for electronics accessories sold in member states. Battery case manufacturers must now integrate material-passport documentation and disassembly-friendly adhesive selection into design-for-environment protocols. Chinese export-oriented suppliers are responding by qualifying domestic recycling partners to maintain EU market access without customs detention risk.
Enterprise procurement teams are consolidating vendor relationships around integrated power ecosystem providers, displacing fragmented accessory purchasing across multiple SKUs. Field-service departments in utilities and telecommunications now specify single-source contracts covering cases, cables, and charging stations to simplify support logistics and volume pricing negotiation. This concentration is most visible in North American and Western European fleet rollouts where total-cost-of-ownership modeling favors bundled service agreements over transactional component sourcing.
Battery Cases Market Segmentation
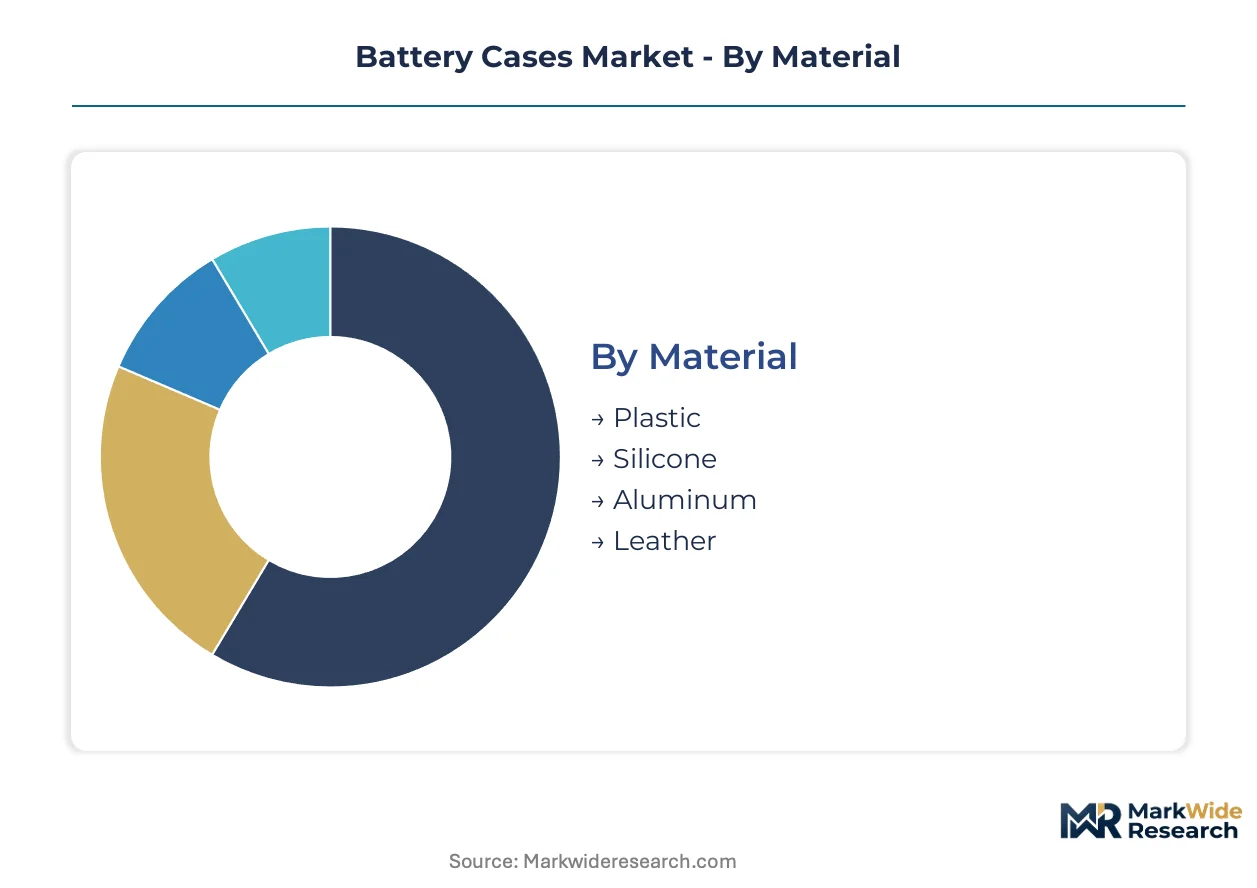
Segmentation in battery cases reveals how material science, device compatibility, and distribution economics create distinct profit pools. Upgrade cycles vary dramatically across these dimensions, with some segments refreshing annually while others persist across multiple device generations.
Material:
Upgrade cycles in protective accessories accelerate when thermal performance becomes a purchase trigger rather than a durability consideration.
- Plastic:Injection-molded polycarbonate and ABS blends dominate unit economics through high-throughput manufacturing. Logistics fleets and construction field services in China source plastic cases for cost-efficient fleet refresh programs where breakage rates justify quarterly procurement.
- Aluminum:CNC-machined unibody construction delivers thermal conductivity exceeding 200 W/m·K for gaming and video-streaming power users. Mobile esports competitors in South Korea and Japan specify aluminum housings to sustain peak processor performance during extended sessions.
- Silicone:Thermoset elastomer formulations provide drop protection through energy-dissipating Shore A durometers. Medical field staff prefer silicone for chemical resistance against disinfectant protocols.
- Leather:Full-grain and bonded hide constructions target executive and luxury positioning. Corporate gifting channels in Germany and Italy drive seasonal demand for embossed leather finishes.
Plastic sits at the top of the volume ranking, with aluminum climbing the fastest as thermal engineering becomes a premium differentiator.
Compatibility:
Application-specific power demands reshape how case architectures align with device thermal envelopes and port configurations.
- Smartphones:Lithium-polymer cells between 2,000 mAh and 5,000 mAh integrate through Lightning, USB-C, or proprietary pogo-pin interfaces. Field-service professionals in United States utilities and telecommunications sectors specify smartphone cases for single-device workflow continuity.
- Tablets:Higher-capacity pouch cells exceeding 8,000 mAh serve creative professionals and medical imaging specialists. Slim-style thermal engineering commands price premiums in Japan's design-centric procurement channels.
- Laptops:USB-C Power Delivery compatibility extends to 100W pass-through for ultrabook form factors. Remote work deployments in Canada favor laptop cases for co-working space flexibility.
- Cameras:MIL-STD-810G ruggedization meets content creator durability requirements. Wildlife photographers in Australia and New Zealand prioritize weather-sealing over capacity specifications.
Smartphone compatibility captures the widest installed base, while tablet-oriented designs gain share fastest among professional creative segments.
Style:
Margin structures diverge sharply between protection-grade certifications and aesthetic-driven consumer preferences.
- Rugged:Multi-layer TPU-polycarbonate sandwiches with IP68 ingress protection satisfy military-spec drop testing. Industrial procurement in Germany's automotive manufacturing sector mandates rugged cases for shop-floor device protection.
- Slim:Minimalist profiles below 15mm thickness prioritize pocketability over maximum capacity. Urban professionals in France and Netherlands accept capacity trade-offs for commuter-friendly form factors.
- Wallet:Integrated card slots and folio covers consolidate EDC carry for convenience-oriented segments. Business travelers in Singapore and Hong Kong favor wallet cases for transit pass integration.
- Folio:Front-cover protection with sleep-wake magnet functionality serves productivity-focused tablet users. Legal and financial services in United Kingdom specify folio cases for client-facing presentation contexts.
Rugged styling leads enterprise procurement volume, with slim designs expanding most quickly as GaN thermal efficiency enables thinner profiles.
Market Type:
Channel economics determine how subscription services and bundled ecosystem plays penetrate different buyer segments.
- Retail:Big-box electronics and carrier store placements depend on packaging compliance with FAA lithium battery carriage rules. Airport retail in United States faces impulse-purchase friction from labeling complexity.
- Online:Direct-to-consumer and marketplace platforms enable software-defined charge management subscriptions. Amazon and brand.com channels in United Kingdom and Germany capture power users seeking specification transparency.
- Wholesale:Enterprise fleet aggregation and distributor relationships serve volume procurement for utilities and logistics. North American telecommunications consolidators negotiate multi-year case-cable-charger bundles.
- Direct:OEM accessory ecosystems and enterprise single-source contracts bypass channel margin stacking. Shenzhen-based manufacturers sell direct to EU retailers navigating Ecodesign material-recovery documentation.
Online channels dominate consumer volume, with direct enterprise contracting showing the steepest expansion trajectory as fleet management consolidates around integrated power ecosystems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's domestic OEM accessory ecosystems dominate volume production, while Germany's industrial procurement channels drive premium ruggedization specifications for field-service deployments.
China
Shenzhen-based manufacturing clusters control over 70% of global lithium-polymer pouch cell output, supplying both domestic brands and Western assemblers. The Ministry of Industry and Information Technology enforces GB standards for battery safety and recycling that shape export documentation requirements. Dongguan and Shenzhen municipal governments subsidize advanced materials R&D centers where gallium nitride thermal management solutions undergo accelerated commercialization.
United States
Field-service professionals in utilities and telecommunications sectors specify high-capacity cases for single-device workflow continuity across remote infrastructure sites. The FAA's lithium battery carriage rules impose packaging and labeling requirements that elevate logistics costs for airport retail channels. California's right-to-repair legislation is pressuring case manufacturers toward modular battery architectures that alter thickness trade-offs in design-for-manufacturing protocols.
Germany
Automotive manufacturing shop floors mandate rugged IP68-certified cases for shop-floor device protection against coolant exposure and mechanical shock. The EU's Ecodesign for Sustainable Products Regulation forces material-recovery redesigns and end-of-life take-back infrastructure qualification for EU market access. Bavarian industrial clusters around Munich and Nuremberg concentrate procurement decision-making for enterprise fleet rollouts across DACH region telecommunications providers.
Japan
Mobile esports competitors and content creators specify aluminum unibody constructions to sustain peak processor performance during extended streaming sessions. METI's circular economy roadmaps align with EU CSRD disclosure timelines, accelerating supplier qualification audits for Scope 3 emissions documentation. Tokyo and Osaka metropolitan procurement channels reward slim-style thermal engineering precision for creative professional segments.
South Korea
Gaming power users prioritize thermal conductivity metrics in purchase decisions, compressing margins for polycarbonate suppliers serving this performance-sensitive segment. The Ministry of Trade, Industry and Energy coordinates domestic battery recycling infrastructure development that affects case end-of-life compliance costs. Seoul Capital Area electronics retail clusters concentrate premium positioning for GaN-enabled thin-profile case architectures.
Battery Cases Market Vendor Landscape
Top-tier vendors anchor premium thermal engineering and rugged certification tiers, while mid-scale fabricators compete on injection-molding cost efficiency and regional distribution reach. The vendor base stratifies across three archetypes: integrated power ecosystem providers bundling cases with charging infrastructure, pure-play protective accessory specialists, and Shenzhen-based contract manufacturers supplying white-label OEM programs. Dominant competitive moves include enterprise fleet single-source contracting and backward integration into gallium nitride power IC design capabilities.
Among North American heritage brands, Mophie and OtterBox occupy positions at opposite ends of the specialization spectrum—one exemplifying premium direct-to-consumer loyalty, the other anchoring military-spec ruggedization certification authority. Anker represents the scale-driven ecosystem archetype, leveraging R&D intensity across charging categories to extend into case-integrated architectures. These three names illustrate how competitive positioning fragments across brand heritage, certification authority, and vertical technology control rather than converging on uniform scale advantages.
| Leading Market Players |
|---|
| ZAGG |
| ZeroLemon |
| Mophie |
| RAVPower |
| Mophie Powerstation |
| Belkin |
| OtterBox |
| Spigen |
| Anker |
| Others |
Supply Flow & Price Mechanics
Gallium nitride thermal management migration simultaneously compresses bill-of-materials costs for premium-tier manufacturers and concentrates design-capability ownership among Shenzhen-based R&D clusters with captive GaN foundry relationships. This technology shift reshapes margin pools by enabling thinner aluminum unibody constructions that command price premiums from gaming power users while displacing polycarbonate suppliers from the fastest-growing segment.
Pricing Analysis
Capacity additions in South Korea and Japan are reshaping price floors for lithium-polymer pouch cells, intensifying cost compression in economy-tier plastic cases while aluminum thermal-performance variants sustain premium positioning. Pricing stratifies across premium, standard, and economy tiers where GaN-enabled slim profiles and MIL-STD-810G rugged certifications drive differentiation. Price erosion runs through injection-molded polycarbonate segments as Chinese contract manufacturers compete on volume scale. Enterprise fleet buyers in North American utilities show least price sensitivity due to total-cost-of-ownership modeling, while Southeast Asian retail consumers exhibit highest elasticity.
Supply Chain Analysis
Reverse-logistics flows for EU Ecodesign compliance—mandating material-passport documentation and end-of-life take-back—increasingly determine supplier qualification timelines and working-capital requirements for Western assemblers. Manufacturing concentrates in China, South Korea, and Vietnam, with Shenzhen-based cell fabricators controlling over seventy percent of global pouch-cell output. Supply chains draw from lithium-cobalt oxide cathodes, aluminum unibody extrusions, and GaN power ICs. Single-source vulnerability in Shenzhen cell manufacturing creates tariff-exposure risk amid US-China trade friction. Distribution runs through direct enterprise contracting for fleet rollouts, online marketplaces for consumer specification transparency, and wholesale distributor relationships for logistics fleet aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery case manufacturing presents a geographic-arbitrage opportunity where EU circular-economy compliance costs exceed Chinese domestic production by margins sufficient to justify nearshoring qualification investments for premium-tier suppliers.
For Market Incumbents: Anticipate right-to-repair mandate acceleration across multiple jurisdictions by pre-positioning modular battery architectures that satisfy thickness trade-offs without sacrificing mAh density. Defend margin position through backward integration into GaN power IC design capabilities that lock thermal-performance differentiation, while consolidating enterprise fleet relationships around single-source contracts covering cases, cables, and charging infrastructure to displace fragmented accessory purchasing. For New Entrants and Emerging Players: The mid-tier price-point gap between Mophie-level premium positioning and white-label economy sourcing creates white-space opportunity for thermal-engineering specialists with industrial design capabilities. Target tablet-oriented slim-style segments where higher average selling prices reward precision engineering for creative professionals and medical field staff. Pursue direct-to-consumer channels with software-defined charge management subscriptions that generate recurring revenue detached from hardware refresh cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale fabricators competing on injection-molding cost efficiency without captive GaN or aluminum thermal-engineering capabilities. Long-term viability over the next decade hinges on circular-economy compliance infrastructure and in-house industrial design rather than pure contract manufacturing scale. Monitor EU Ecodesign enforcement intensity and California right-to-repair legislative progression as inflection indicators for modular architecture mandate timing.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Power IC Backward Integration | Captive thermal-management design locks premium-tier differentiation against polycarbonate competitors. |
| Enterprise Fleet Single-Source Contracting | North American telecommunications consolidators bundle cases, cables, and charging stations under multi-year agreements. |
| EU Material-Passport Documentation Investment | Ecodesign compliance qualifies suppliers for customs-cleared market access without detention risk. |
| Modular Battery Architecture Development | Right-to-repair mandate preparation enables thickness-optimized designs that satisfy emerging regulatory requirements. |
| Direct-to-Consumer Subscription Launch | Software-defined charge management generates recurring revenue streams detached from hardware refresh cycles. |
Methodological Framework
Multiple input streams—executive interviews with power-accessory brand managers and industrial procurement leads, technical discussions with Shenzhen-based contract manufacturers, and validation sessions with thermal-engineering specialists—were reconciled against customs trade records, SEC filings from publicly traded ecosystem vendors, and EU regulatory documentation databases. Primary fieldwork captured procurement decision-making criteria from utilities, telecommunications fleets, and logistics operators across North America, Western Europe, and East Asia. Secondary sources included FAA lithium battery carriage rule filings, ECHA REACH substance restriction updates, and MIIT GB standard enforcement notices. Bottom-up unit-economics modeling and top-down market sizing triangulated volume and value estimates.
Data-stream reconciliation across material segmentation, device compatibility tiers, and distribution channel economics shaped the analytical framework applied throughout the projection horizon. Segmentation dimensions modeled include material construction, compatibility form factor, styling category, and market channel type. CAGRs were derived from installed-base growth curves, replacement-cycle compression factors, and premium-tier share expansion dynamics. Industry-specific forecast inputs incorporated GaN thermal-efficiency adoption rates and EU circular-economy compliance cost trajectories.
Caveats apply where regulatory enforcement intensity, lithium-polymer cell supply disruptions, or wireless charging infrastructure substitution could materially shift the outlook. Forecasts reflect assumptions regarding right-to-repair mandate timing and Ecodesign material-recovery threshold implementation. Practitioners should monitor EU customs detention patterns for non-compliant shipments and enterprise fleet RFP specifications for bundled ecosystem requirements as early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
South Europe Battery Market
Batteries
East Africa Battery Market
Batteries
Power-Sports Batteries Market
Batteries
Grid-Scale Flow Battery Stack Endurance Test Benches Market
Batteries
Dry Cell Battery Market
Batteries
United Kingdom Rechargeable Battery Market
Batteries
Middle East and Africa Battery Market
Batteries
Norway Rechargeable Battery Market
Batteries
Nas Battery Market
Batteries
China Rechargeable Battery Market
Batteries
Middle East Rechargeable Battery Market
Batteries
Second-Life EV Battery Module Qualification Test Systems Market
Batteries
HIT Battery Market
Batteries
Asia-Pacific NMC Battery Pack Market
Batteries
France Rechargeable Battery Market
Batteries
GCC Rechargeable Battery Market