
 Automotive Advanced Seating System Market | 2026-2036
Automotive Advanced Seating System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Advanced Seating System Market Outlook
Market Context with Strategic Players
China is narrowing its technology gap with European seat suppliers through accelerated domestic capacity expansion. Adient leverages its global manufacturing footprint to sustain just-in-time delivery contracts with premium vehicle programs. Lear Corporation anchors its position through in-house production of seat frame assemblies and electronic control modules. Toyota Boshoku competes by integrating heating and ventilation systems directly into its seating platforms.
Technical Definition and Structural Segments
Automotive advanced seating systems integrate electromechanical actuators, climate-control elements, sensor arrays, and programmable memory modules into vehicle occupant platforms engineered for safety, comfort, and ergonomic adjustability. These systems typically incorporate steel or aluminum frame structures with polyurethane foam densities ranging from 40 to 80 kilograms per cubic meter, bonded textile or leather surface materials, and LIN-bus or CAN-bus electronic architectures for synchronized cabin control. Luxury seats and performance seats command the highest margin pools as OEMs bundle climate and massage functions into premium trim packages. Heated seats and ventilated seats lead technology penetration in temperate-climate vehicle markets, while adjustable seats with memory function represent the fastest-growing feature set among mid-range vehicle segments.
Regulatory Frame and Forward-Looking Close
NHTSA Federal Motor Vehicle Safety Standards govern seat strength, head restraint geometry, and occupant protection in the United States, while EU-type approval frameworks under the EU Green Deal push suppliers toward recyclable foam chemistries and reduced volatile organic compound emissions. EPA corporate average fuel economy requirements and ECHA REACH restrictions on flame retardants are reshaping material selection decisions across the supplier base. Stakeholders must monitor evolving crash-test protocols and carbon-border adjustment mechanisms to anticipate compliance-driven redesign cycles.
Market Dynamics
Electric vehicle cabin redesigns are compressing seat development cycles as OEMs integrate thermal management and structural battery protection into seating architectures. NHTSA crashworthiness mandates and EPA lightweighting requirements create simultaneous pressure on frame engineering and material selection.
Growth Catalysts
- EV Platform Redesigns:Battery-electric vehicle architectures eliminate transmission tunnels and exhaust routing, freeing cabin space for extended seat travel and recline functions. Premium EV manufacturers in the United States are specifying full-flat seating configurations.
- NHTSA FMVSS 202a:Upgraded head restraint performance standards are accelerating adoption of active headrest systems with pyrotechnic or motor-driven deployment mechanisms. Suppliers with integrated electronics capabilities capture specification upgrades.
- Polyurethane Foam Recycling:Chemical recycling pathways for post-industrial foam scrap are reducing virgin material costs and satisfying ECHA REACH compliance for reduced volatile organic compound emissions. European suppliers lead process development.
Market Restraints
- Steel and Aluminum Volatility:Seat frame material costs fluctuate with energy-intensive smelting economics. European foundry capacity constraints amplify input price swings for structural seat components.
- Semiconductor Dependency:LIN-bus and CAN-bus motor controllers require automotive-grade microcontrollers with extended temperature ratings. Foundry allocation to powertrain electronics limits seating system chip supply.
- Manual Seat Substitution:Entry vehicle segments in emerging markets retain manually adjusted benches. Cost-sensitive OEMs defer electromechanical actuation to preserve price positioning.
Strategic Opportunities
- India Passenger Vehicle Premiumization:Domestic OEMs and joint ventures are introducing ventilated seating in mid-size SUVs. Local component sourcing requirements favor joint ventures with established climate-system suppliers.
- Wearable Biometric Integration:Seat-embedded heart rate and stress sensors are converging with smartwatch data streams. Wellness-focused fleet operators pilot driver monitoring through seating interfaces.
- EU Green Deal Material Mandates:Recyclability quotas for vehicle interior components create specification windows for bio-based foam chemistries and dismantlable textile bonding. First-mover suppliers secure long-term platform contracts.
Industry Challenges
- Embedded Software Validation:Seat control modules require ASIL-rated functional safety certification under ISO 26262. Development timelines extend 18-24 months for complex memory and massage algorithms.
- Legacy Platform Integration:Electrified seating systems must interface with 12V electrical architectures in vehicle lines spanning multiple model years. Voltage compatibility engineering consumes engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Advanced Seating System Market |
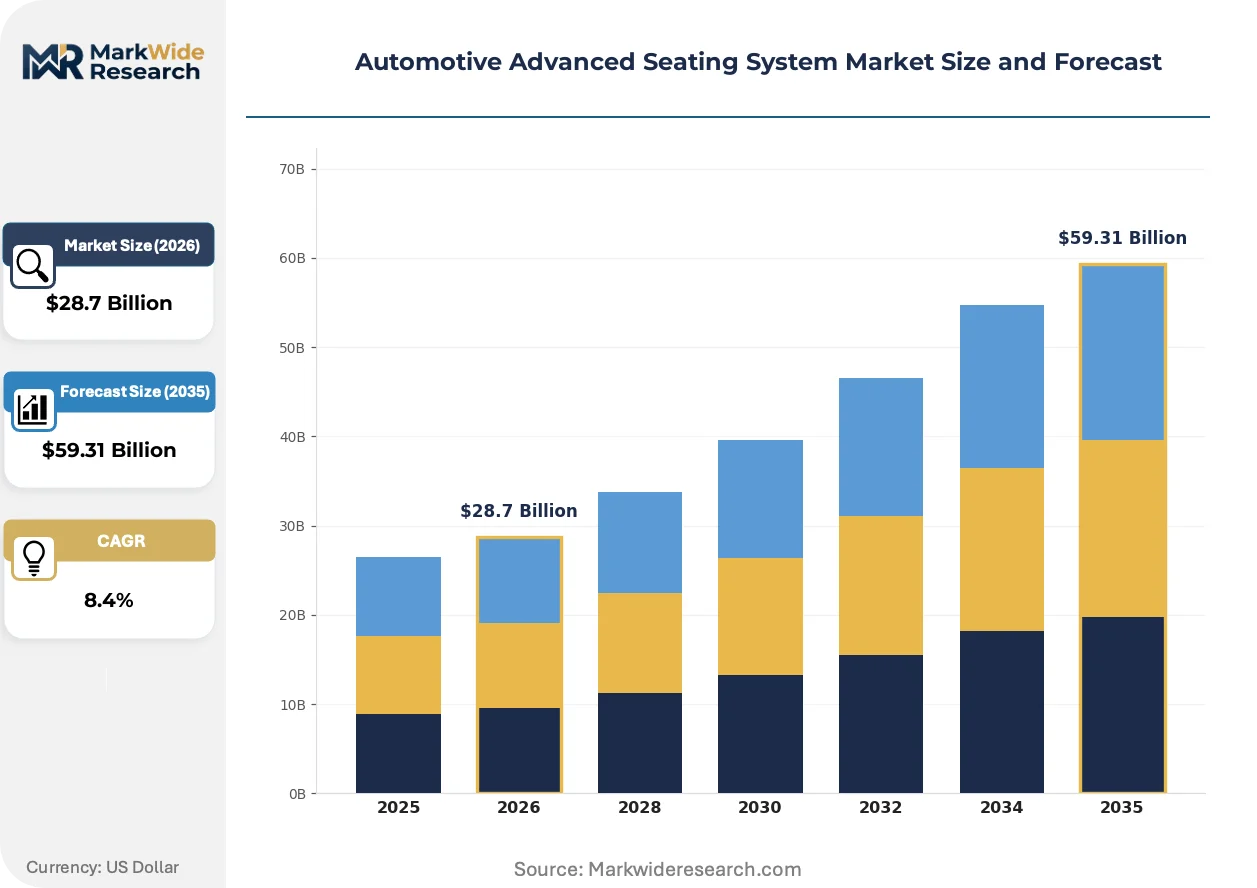
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $59.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury Seats, Performance Seats, Standard Seats, Ergonomic Seats Technology: Heated Seats, Ventilated Seats, Massage Seats, Adjustable Seats End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Features: Memory Function, Safety Sensors, Reclining Mechanism, Power Adjustment |
| Companies Covered | Toyota Boshoku, Adient, Lear Corporation, NHK Springs, Grammer AG, Faurecia, Continental AG, Johnson Controls, Magna International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Advanced Seating System Market Strategic Shifts
Seat architectures are converging with thermal management and occupant sensing systems, transforming historically mechanical assemblies into integrated electromechanical platforms. Material science advances and software-defined functionality are rewriting supplier capability requirements.
Structural seat frames manufactured from carbon-fiber-reinforced thermoplastics are rendering obsolete traditional steel stamp-and-weld assemblies for performance vehicle applications. Porsche and BMW M-division programs specify composite-intensive seating structures to offset battery mass. The shift is compressing supplier margins on conventional frame production while rewarding plastics processors with automotive crash certification.
REACH restrictions on halogenated flame retardants are forcing reformulation of polyurethane foam catalyst systems across European supply chains. ECHA substance evaluation timelines create 18-month compliance windows that disrupt just-in-time material flows. German seat suppliers accelerate partnerships with specialty chemical firms to secure qualified foam chemistries ahead of authorization deadlines.
Fleet operators are unbundling seating specification from vehicle purchase, contracting direct with suppliers for durability-tested configurations with standardized service protocols. Rental and ride-hail operators in the United States negotiate volume-based refresh cycles independent of OEM trim packages. This disintermediation pressures traditional tiered supply relationships and opens direct aftermarket channels for replacement seating systems.
Automotive Advanced Seating System Market Segmentation
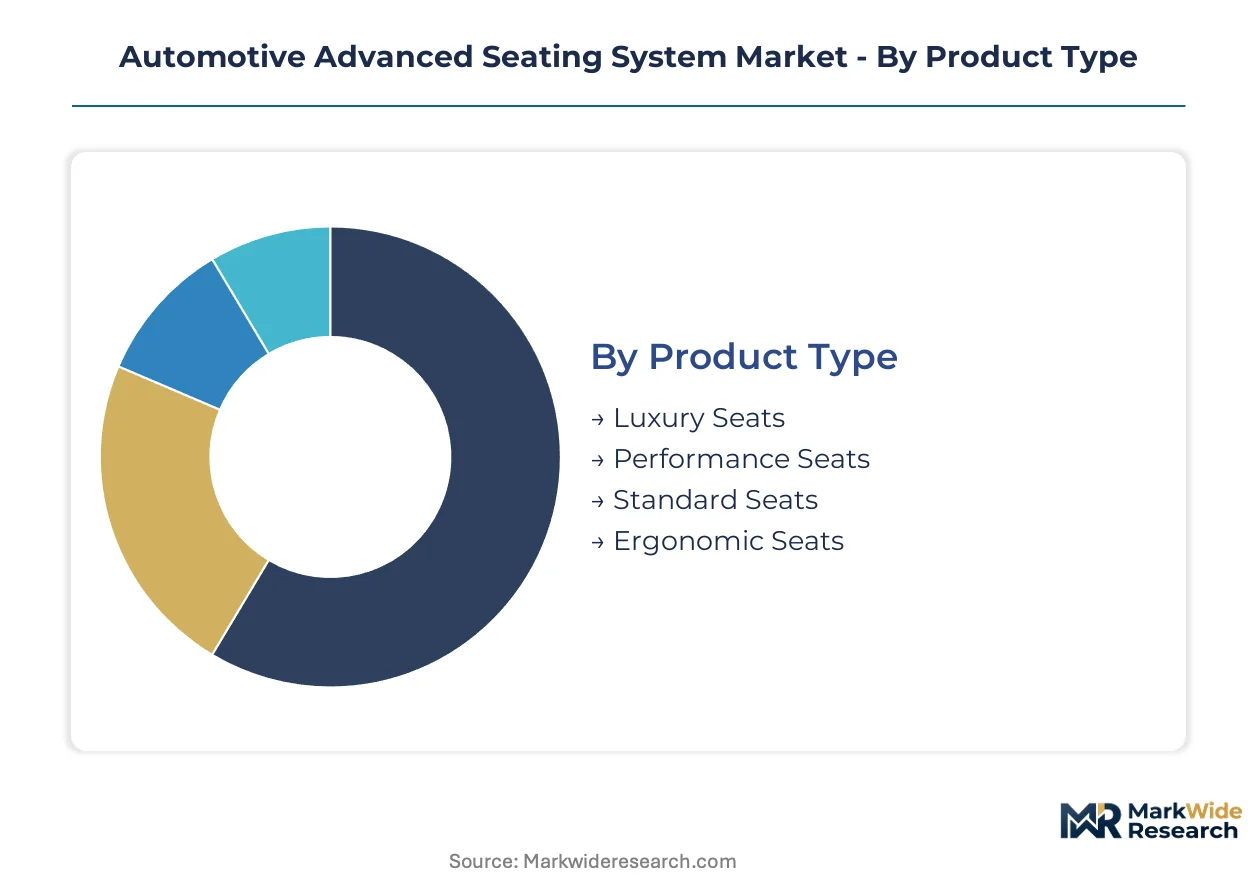
Seating system segmentation reflects divergent engineering priorities across price tiers and regulatory environments. Product architecture, thermal technology integration, and supply chain position each create distinct competitive arenas with unique margin structures and specification requirements.
Product Type:
Cost tier stratification separates frame materials, foam densities, and electronic content across vehicle price bands.
- Luxury Seats:Multi-density polyurethane foam layers with integrated climate modules and massage actuators command specification from German premium OEMs and United States EV manufacturers. NHTSA FMVSS 202a head restraint mandates accelerate active headrest deployment mechanisms in this tier.
- Performance Seats:Carbon-fiber-reinforced thermoplastic frames replace steel stampings to offset battery mass in Porsche and BMW M-division programs. Bolster inflation systems and integrated harness pass-throughs satisfy track-day durability requirements.
- Standard Seats:Steel frame assemblies with fixed headrests dominate high-volume compact and mid-size vehicle production across North American and European assembly plants.
- Ergonomic Seats:Extended travel rails and multi-way power adjustment address aging demographic preferences in Japanese domestic market vehicles.
Luxury seats command the established base. The steepest expansion runs through performance seats.
Technology:
Application-specific thermal and kinetic functions align with climate zones and vehicle usage patterns.
- Heated Seats:Resistive wire elements embedded in seat cushions and backrests achieve rapid warm-up times through 12V or 48V electrical architectures. Cold-climate markets in Canada and Scandinavia mandate this feature even in entry trim levels.
- Ventilated Seats:Perforated leather surfaces with suction-blower modules manage occupant thermal comfort in humid subtropical regions. United States domestic EV manufacturers specify full-perforation patterns for battery-electric cabin redesigns.
- Massage Seats:Pneumatic bladder arrays with programmable wave patterns concentrate in Chinese premium vehicle joint ventures and German luxury exports.
- Adjustable Seats:Memory-position actuators with LIN-bus synchronization represent the fastest-growing feature penetration in mid-range vehicle segments.
Heated seats retain volume leadership. Ventilated seats gain share fastest.
End User:
Supply chain position determines specification authority, development cycle timing, and aftermarket access.
- OEMs:Vehicle manufacturers with captive seating divisions control platform architecture decisions and electronic system integration timelines.
- Tier-1 Suppliers:Independent seating specialists compete for just-in-time assembly contracts through modular frame and climate-system integration capabilities.
- Aftermarket Providers:Fleet operators and ride-hail services in the United States negotiate direct refresh cycles bypassing traditional OEM trim packages.
- Vehicle Assemblers:Contract manufacturers in emerging markets source complete seating modules for knock-down assembly operations.
Tier-1 suppliers anchor production volume. Aftermarket providers are climbing the fastest.
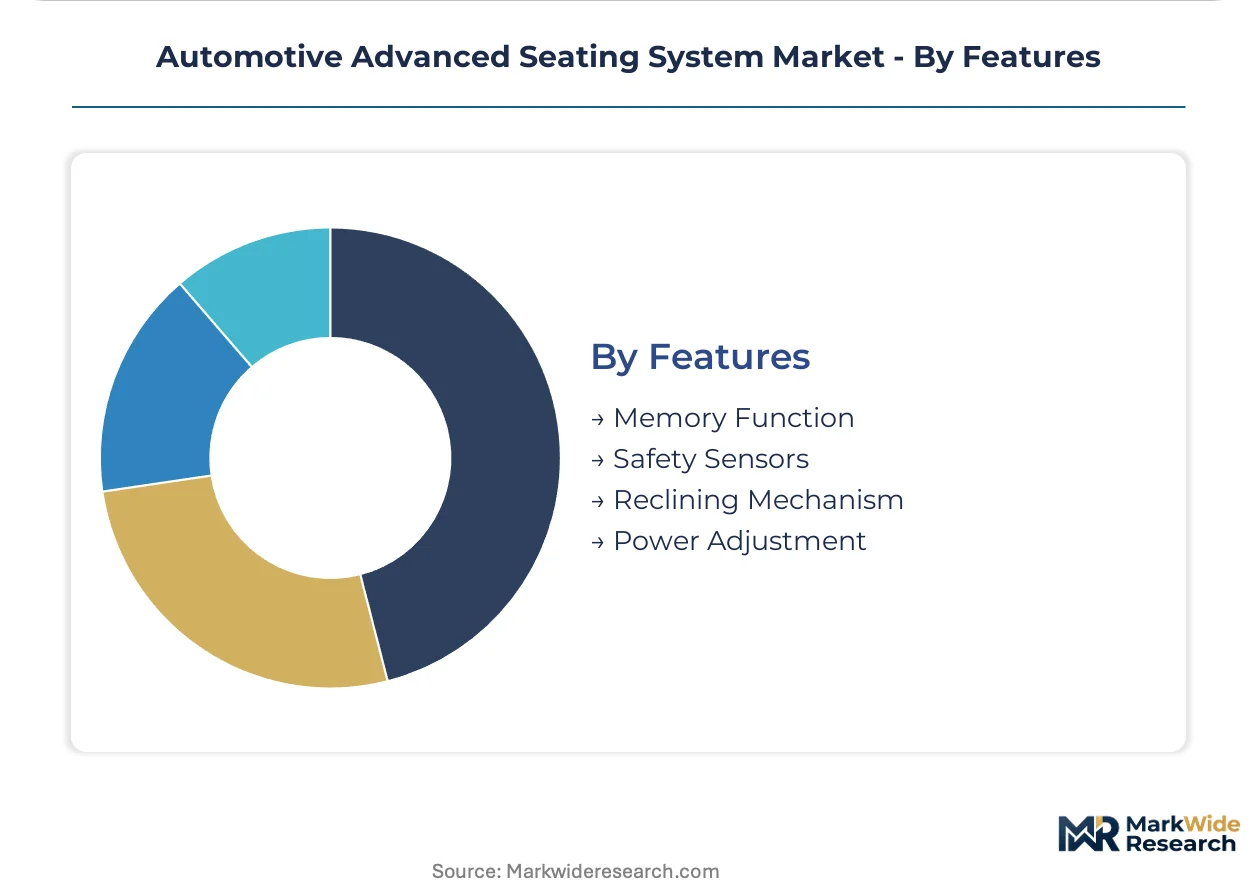
Features:
Electronic content differentiation separates premium configurations from base equipment through sensor integration and actuation sophistication.
- Memory Function:Position recall modules with driver profile storage satisfy multi-operator household and fleet vehicle requirements.
- Safety Sensors:Occupant classification and presence detection enable adaptive airbag deployment algorithms under NHTSA FMVSS 208.
- Reclining Mechanism:Full-flat articulation with structural battery protection integration addresses premium EV cabin redesigns in the United States.
- Power Adjustment:Multi-way motor packs with anti-pinch certification represent baseline equipment in developed market vehicle segments.
Power adjustment commands the established base. Safety sensors gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seating system fabrication concentrates in automotive manufacturing clusters where OEM final assembly plants anchor supplier investment. Germany, the United States, China, Japan, and India host the dominant engineering centers and just-in-time production networks.
United States
Domestic EV manufacturers in Michigan and California are redesigning cabin architectures around full-flat seating configurations with extended travel rails. NHTSA FMVSS 202a head restraint standards accelerate active headrest system adoption across premium vehicle programs. Detroit-Warren-Dearborn MSA anchors frame stamping and foam molding operations for North American vehicle assembly.
Germany
Premium OEMs in Bavaria and Baden-Württemberg specify multi-density foam layers with integrated massage actuators for luxury trim packages. ECHA REACH restrictions on halogenated flame retardants force 18-month foam chemistry reformulation cycles. Stuttgart metropolitan area concentrates seat electronics development and climate-module integration engineering.
China
Joint ventures in Shanghai and Guangzhou are narrowing technology gaps with European suppliers through accelerated domestic capacity expansion. MIIT new energy vehicle mandates drive thermal management integration into seating platforms. Yangtze River Delta cluster hosts the fastest-growing ventilated seat module production base.
Japan
Domestic market aging demographics fuel ergonomic seat demand with extended power adjustment travel. METI carbon neutrality roadmaps push suppliers toward recyclable foam chemistries and lightweight frame materials. Toyota City-Nagoya corridor maintains integrated seating division capabilities from frame welding to final assembly.
India
Mid-size SUV premiumization in Maharashtra and Tamil Nadu introduces ventilated seating into mass-market segments. PLI scheme incentives for automotive component manufacturing attract joint venture seating module investments. Chennai-Sriperumbudur belt emerges as the primary export-oriented seating fabrication hub for compact vehicle platforms.
Automotive Advanced Seating System Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in frame, foam, and electronics supply. The supplier base organizes around three structural tiers: multinational seating divisions with captive OEM relationships, independent Tier-1 module assemblers, and regional component fabricators. Two dominant competitive moves reshape positioning: backward integration into frame stamping and foam molding, and strategic partnerships for climate-system technology access.
Within the multinational integrator tier, Adient and Lear Corporation exemplify platform-scale capabilities spanning frame engineering through electronic control module production. Toyota Boshoku occupies a position as a captive supplier archetype with integrated heating and ventilation system expertise. These three companies represent the dominant competitive anchors against which independent specialists and regional challengers benchmark capability investments.
| Leading Market Players |
|---|
| Toyota Boshoku |
| Adient |
| Lear Corporation |
| NHK Springs |
| Grammer AG |
| Faurecia |
| Continental AG |
| Johnson Controls |
| Magna International |
| Others |
Value Chain & Pricing Dynamics
Semiconductor dependency in motor controller supply determines both the premium tier spreads between climate-enabled and manual seating configurations and the geographic clustering of just-in-time assembly networks. NHTSA crashworthiness mandates and EPA lightweighting requirements simultaneously inflate engineering costs and compress supplier margins, forcing tier-1 integrators to recalibrate material sourcing strategies across steel, aluminum, and emerging composite feedstocks.
Pricing Analysis
NHTSA FMVSS 202a dictates the pricing tier structure by mandating active headrest systems that bifurcate luxury seating premiums from standard equipment. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade for ASIL-rated electronics and volume scale of frame stamping operations. Cost compression in mid-range segments is intensifying because OEMs defer electromechanical actuation to preserve price positioning in entry vehicle markets. Fleet operators exhibit the highest price sensitivity, while German premium OEMs and United States EV manufacturers demonstrate minimal elasticity for full-flat configurations with integrated thermal management.
Supply Chain Analysis
Extended payment terms from United States domestic EV manufacturers strain working capital for European foam chemistry suppliers facing ECHA REACH reformulation cycles. Production gravity centers on Germany, the United States, and China, with the Yangtze River Delta and Detroit-Warren-Dearborn MSA anchoring just-in-time module assembly. Raw material dependencies draw from steel and aluminum frame stampings, polyurethane foam catalyst systems, and automotive-grade microcontrollers with extended temperature ratings. Single-source vulnerability in LIN-bus and CAN-bus motor controllers creates specification bottlenecks when foundry allocation prioritizes powertrain electronics. Distribution runs through OEM captive seating divisions, tier-1 modular assemblers, and direct aftermarket channels for fleet refresh cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive seating demand follows the cyclical recovery of passenger vehicle production, with EV platform redesigns compressing development cycles and accelerating specification upgrades across premium trim packages.
For Market Incumbents: Insulate margin pools by securing captive supply of carbon-fiber-reinforced thermoplastic frame structures before composite-intensive seating architectures displace conventional steel stampings. Deepen backward integration into foam molding operations to capture ECHA REACH compliance premiums and reduce virgin material cost exposure. Prioritize ASIL-rated functional safety certification investments to extend development timeline advantages over challengers lacking ISO 26262 validation capabilities.
For New Entrants and Emerging Players: India's mid-size SUV premiumization offers the most penetrable white-space for ventilated seating modules, with PLI scheme incentives reducing joint venture capital requirements against established climate-system suppliers. Target aftermarket fleet refresh cycles in the United States ride-hail and rental segments where operators negotiate direct supplier relationships independent of OEM trim packages. Pursue wellness-focused biometric integration partnerships with smartwatch manufacturers to differentiate seat-embedded sensor offerings.
For Investors and Strategic Acquirers: EU Green Deal material mandates reshape the acquisition landscape by creating specification windows for bio-based foam chemistries and dismantlable textile bonding that first-mover suppliers will lock into long-term platform contracts. Target tier-1 module assemblers with integrated electronics capabilities and established just-in-time delivery relationships with premium vehicle programs. Monitor ECHA substance evaluation timelines as the signal to watch for compliance-driven redesign cycles that will disrupt material flows and create distressed asset opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | OEMs consolidate seat architectures across EV and ICE vehicle lines to amortize ASIL certification costs. |
| Battery Supply Agreement | Seating suppliers negotiate thermal management integration contracts with cell manufacturers for cabin climate optimization. |
| Software-Defined Vehicle Investment | LIN-bus and CAN-bus module producers acquire embedded software firms to compress ISO 26262 validation timelines. |
| Geographic Manufacturing Footprint | Joint ventures in the Yangtze River Delta and Chennai-Sriperumbudur belt capture local content requirements. |
| Charging Infrastructure Partnership | Fleet operators specify durability-tested seating configurations with standardized service protocols for ride-hail refresh cycles. |
Study Parameters
Desk research of vehicle production databases, IHS Markit registration data, and SEC filings from tier-1 suppliers preceded structured interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and dealership operations managers. Secondary validation drew from NHTSA FMVSS documentation, ECHA REACH substance evaluations, and EPA corporate average fuel economy disclosures. Bottom-up triangulation across component-level bill-of-materials analysis and top-down reconciliation against OEM program volumes anchored market sizing.
Assumptions held fixed include NHTSA regulatory enforcement timelines, ECHA authorization deadlines, and OEM electrification program commitments, while semiconductor availability and steel-aluminum price volatility were modeled as scenario variables. Segmentation dimensions spanned vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs were derived from regression analysis of historical specification penetration rates against OEM program launch cadences, with EV adoption curves and demographic aging patterns as automotive-specific forecast inputs.
Practitioners should monitor ECHA substance evaluation timelines, foundry allocation announcements for automotive-grade microcontrollers, and NHTSA crash-test protocol revisions for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Overhead Console Market
Automotive Interior & Exterior
Automotive Sealants Market
Automotive Interior & Exterior
Automotive Flock Market
Automotive Interior & Exterior
Automotive Solar Film Market
Automotive Interior & Exterior
Automotive Door Sills Market
Automotive Interior & Exterior
Automotive Air Purifier Market
Automotive Interior & Exterior
United Kingdom Automotive Sunroof Market
Automotive Interior & Exterior
Smart Automotive Headlight Market
Automotive Interior & Exterior
Automotive Inside Rearview Mirrors (IRVM) Market
Automotive Interior & Exterior
Automotive Underbody Coatings Market
Automotive Interior & Exterior
Train Seat Materials Market
Automotive Interior & Exterior
Ventilated Seats Market
Automotive Interior & Exterior
Global Automotive Carpeting Market
Automotive Interior & Exterior
North America Automotive Flooring Market
Automotive Interior & Exterior
Automotive Seat Recliners Market
Automotive Interior & Exterior
Automotive Floor Carpet Market