
 Global Automotive Fog Lights Market | 2026-2036
Global Automotive Fog Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Fog Lights Market Analysis
Mexico is reshaping North American fog light supply chains through dedicated automotive lighting clusters serving Detroit and southern US assembly plants. Valeo S.A. leverages its full-system integration capability to dominate OEM channels for LED fog modules. Koito Manufacturing Co., Ltd. anchors Asian supply through its Thailand and China facilities, sustaining cost-competitive halogen production alongside premium LED development. Robert Bosch GmbH competes on electronic control integration, bundling fog activation with sensor-driven visibility systems.
Automotive fog lights are auxiliary forward-illumination devices, typically rated between 35W and 55W for halogen variants or 15W to 30W for LED equivalents, engineered to project a wide, low beam pattern beneath the optical cutoff of standard headlamps for improved short-range visibility in precipitation and aerosol conditions. Their primary purpose is to reduce foreground glare and backscatter while illuminating road edges and lane markings in meteorological opacity events. LED fog lights command the fastest expansion trajectory across the product type dimension as thermal management advances and lumen-per-watt efficiency climbs past halogen benchmarks. SUVs and crossovers represent the densest vehicle type demand pool, driven by elevated ride heights that amplify fog penetration requirements and consumer preference for stacked lighting aesthetics. OEM installation channels capture the dominant value share, though aftermarket replacement cycles accelerate in high-corrosion climates where housing degradation outlamp electronics.
FDA vehicle visibility guidelines, ECE Regulation 19 beam-pattern standards, and China's GB 4785 automotive lighting rules collectively govern fog light photometric performance, color temperature limits, and activation interlocks with high-beam systems. These frameworks elevate compliance costs for new entrants while rewarding incumbents with certified testing infrastructure and homologation expertise. Stakeholders must monitor divergence between UN-ECE and FMVSS certification pathways as electrification architectures rewrite 12V distribution standards and enable intelligent fog activation through camera-based visibility sensing.
Market Dynamics
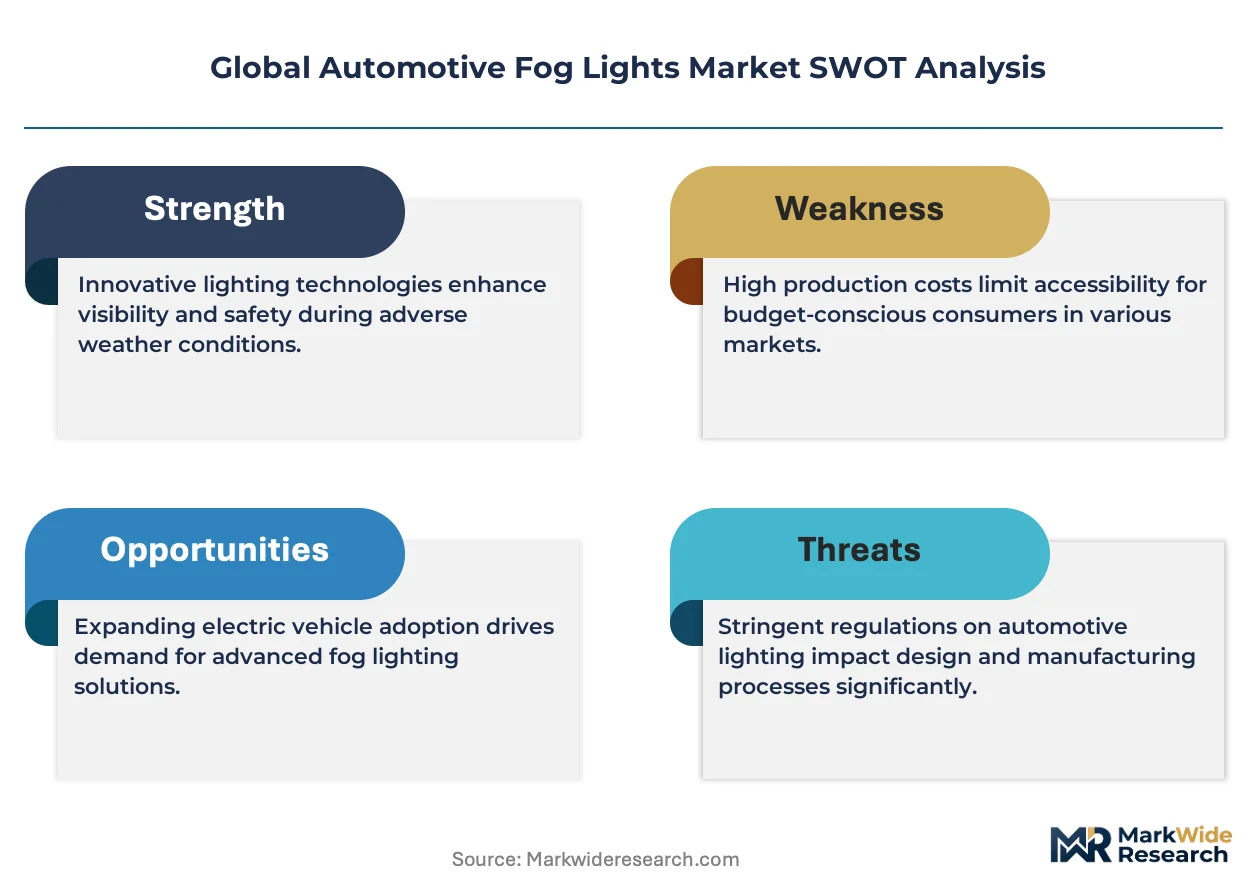
LED thermal management breakthroughs are compressing unit economics and forcing halogen foundries into specialty aftermarket niches, while dual-homologation requirements for UN-ECE and FMVSS certification are fragmenting supplier bases into regional compliance specialists.
Growth Catalysts
- ANVISA fleet mandates:Brazil's commercial vehicle visibility regulations are accelerating fog light fitment rates across heavy-duty truck platforms operating in high-humidity corridors.
- LED lumen-per-watt gains:Solid-state thermal substrates now deliver halogen-comparable output at half the wattage, opening 48V mild-hybrid electrical architectures to fog integration.
- KBA beam-pattern enforcement:Germany's stringent OEM certification standards are elevating barrier-to-entry for uncertified suppliers and concentrating premium volume with homologated incumbents.
Market Restraints
- Aluminum housing cost volatility:Die-cast enclosure materials face price swings from energy-intensive smelting, compressing margin buffers for mid-tier LED module assemblers.
- Dual-certification friction:Divergent UN-ECE and FMVSS photometric test protocols force redundant tooling investments, disadvantaging smaller suppliers without captive testing labs.
- Camera-based visibility substitution:Forward-facing sensor arrays with infrared enhancement are displacing auxiliary lighting in premium electrified platforms.
Strategic Opportunities
- Mexico lighting cluster proximity:Dedicated automotive supplier parks in Querétaro and Guanajuato offer tariff-advantaged export positioning to Detroit and southern US assembly plants.
- Sensor-fog convergence:Integration of fog activation with camera-based meteorological detection creates intelligent lighting modules commanding premium positioning.
- GB 4785 compliance services:China's automotive lighting standards are creating advisory revenue streams for testing houses navigating type-approval for domestic OEMs.
Industry Challenges
- Thermal engineer scarcity:LED junction temperature management expertise is concentrating among tier-one lighting specialists, constraining second-tier module design capabilities.
- Homologation timeline compression:Accelerated vehicle development cycles are squeezing the 18-24 month certification window, forcing parallel rather than sequential testing workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Fog Lights Market |
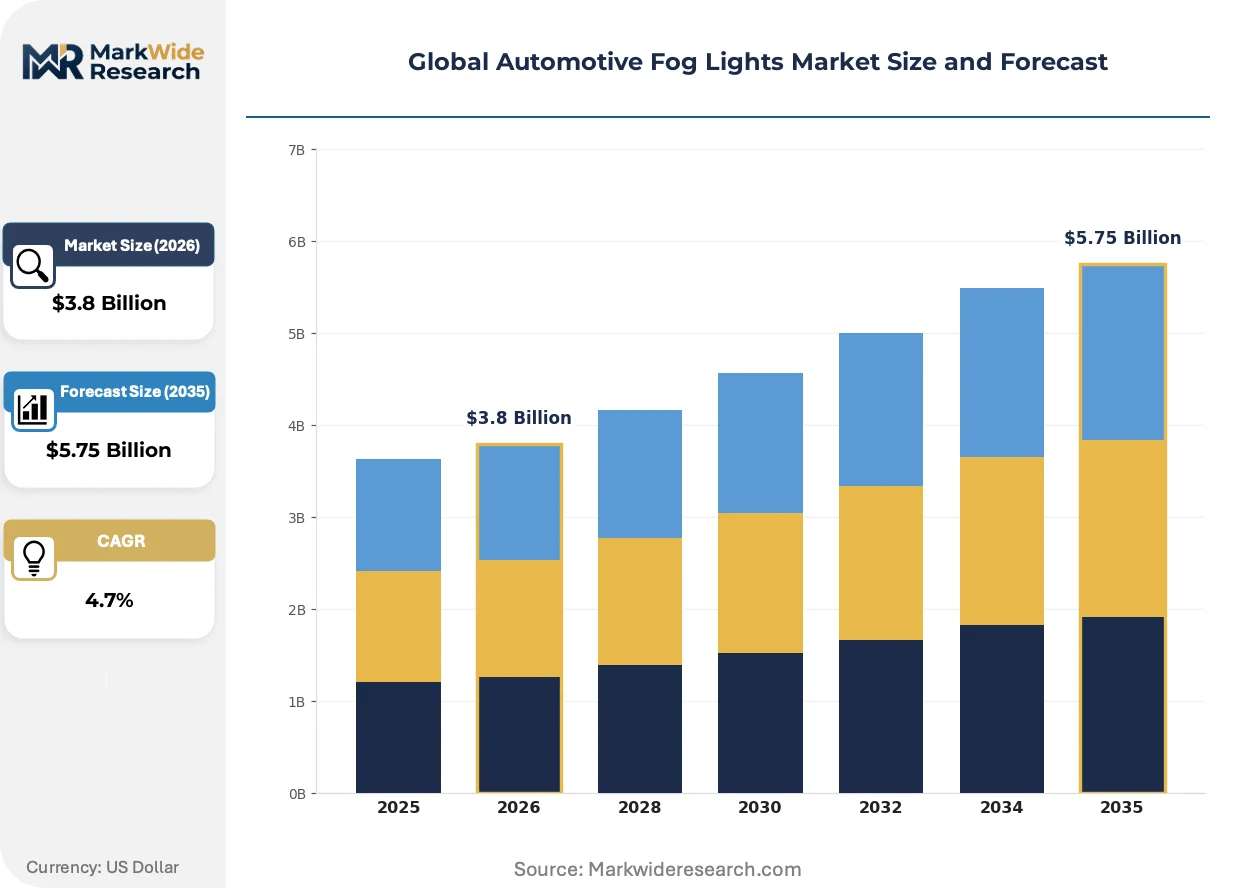
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Halogen, LED, Xenon, Incandescent Vehicle Type: SUVs, Sedans, Trucks, Crossovers Installation Type: OEM, Aftermarket, Integrated, Custom Power Source: 12V, 24V, Rechargeable, Battery-operated |
| Companies Covered | Valeo S.A., Koito Manufacturing Co., Ltd., Robert Bosch GmbH, ZKW Group GmbH, Hyundai Mobis, Magneti Marelli S.p.A., OSRAM GmbH, Stanley Electric Co., Ltd., Hella KGaA Hueck & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Fog Lights Market Emerging Trajectories
Active matrix LED arrays and intelligent beam-shaping algorithms are redefining fog light functionality beyond static illumination, while supply chain regionalization is shortening development feedback loops between module designers and vehicle integration teams.
Chip-on-board LED architectures with integrated phosphor conversion are migrating from premium German SUV platforms to mass-market crossover segments as thermal interface materials drop below critical cost thresholds. Tier-one suppliers in Thailand and China are adopting these designs for regional OEM programs, compressing the technology diffusion cycle from six years to under three.
REACH substance restrictions on halogenated flame retardants are forcing housing material substitutions toward glass-filled polyamides, raising mold tooling costs but enabling thinner wall sections and weight reduction. European suppliers are absorbing these transitions fastest, while Asian manufacturers face reformulation lag in export-bound product lines.
Fleet procurement departments are consolidating lighting spend through direct OEM negotiations rather than aftermarket distributors, unbundling traditional wholesaler relationships. This concentration is most visible in Germany and Brazil, where large commercial operators negotiate multi-year fitment contracts with Valeo and Koito for standardized LED modules across vehicle generations.
Global Automotive Fog Lights Market Segmentation
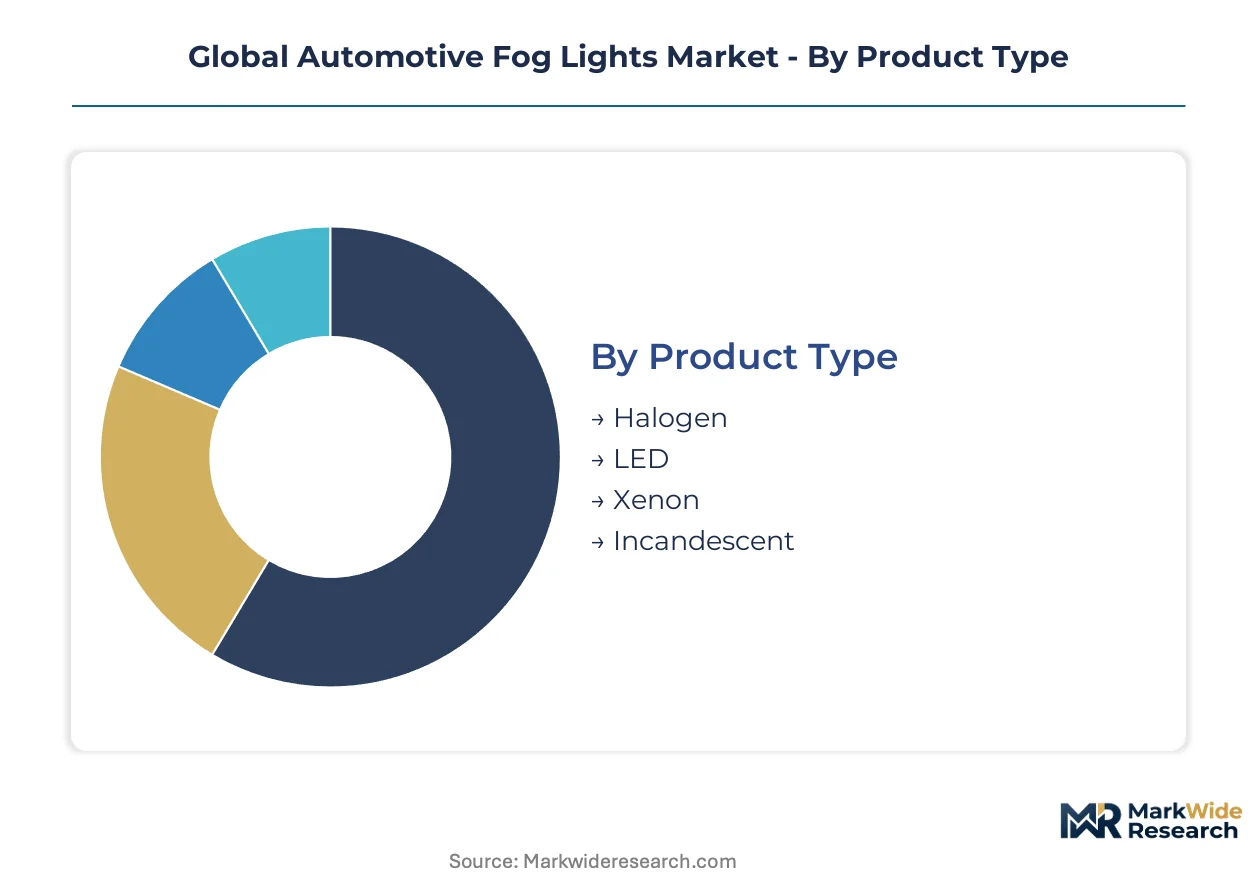
Segmentation in automotive fog lights reveals how technology transitions, regulatory pressures, and vehicle electrification reshape procurement patterns across distinct buyer groups. Understanding these divides exposes where margin pools concentrate and which technology platforms command investment priority.
Product Type:
Mature incumbent technologies face displacement as emerging solid-state platforms capture engineering attention and capital allocation.
- Halogen:Tungsten-filament technology operating at 35W-55W dominates Brazil's ANVISA-mandated commercial fleet retrofits due to low unit cost and established supply chains. Demand concentrates in cost-sensitive emerging markets where thermal substrate premiums for LED remain prohibitive.
- LED:Solid-state arrays with 15W-30W draw and integrated thermal management substrates are displacing halogen across German SUV platforms governed by KBA beam-pattern certification. Premium OEM channels in Stuttgart and Munich anchor volume as lumen-per-watt efficiency crosses critical adoption thresholds.
- Xenon:High-intensity discharge systems with arc-tube ignition remain confined to specialty aftermarket applications requiring extreme lumen output.
- Incandescent:Legacy filament technology persists only in vintage vehicle restoration and developing-market replacement cycles where regulatory enforcement remains limited.
LED handles the majority of throughput; LED is the fastest mover on share.
Vehicle Type:
Application intensity varies with ride height, aerodynamic drag, and consumer aesthetic preferences across passenger and commercial platforms.
- SUVs:Elevated body structures amplify fog penetration requirements while stacked lighting aesthetics drive dual-module front fascia designs. German premium manufacturers specify integrated LED fog and cornering light combinations.
- Crossovers:Unibody architectures with SUV styling cues represent densest volume growth as C-segment platforms proliferate from Thailand and China assembly plants.
- Sedans:Lower ride heights reduce fog penetration urgency; fitment concentrates in luxury tiers with all-weather lighting packages.
- Trucks:Heavy-duty platforms in Brazil's humidity corridors drive ANVISA-mandated visibility upgrades across fleet procurement programs.
SUVs capture the dominant value position; crossovers are climbing the fastest on unit volume.
Installation Type:
Channel structure reflects certification barriers, warranty integration, and development cycle compression in vehicle programs.
- OEM:Factory-fitment through tier-one module suppliers requires 18-24 month homologation cycles with KBA, NHTSA, or GB 4785 certification. Valeo and Koito dominate through captive testing infrastructure and parallel validation workflows.
- Aftermarket:Replacement demand accelerates in coastal US states and northern European markets where housing corrosion outlamp electronics; distribution runs through specialized automotive lighting retailers.
- Integrated:Fog activation bundled with ADAS visibility sensors commands premium positioning in electrified platforms.
- Custom:Specialty vehicle modifiers and restomod builders specify non-homologated units for aesthetic differentiation.
OEM channels handle the majority of throughput; integrated installations are gaining share fastest.
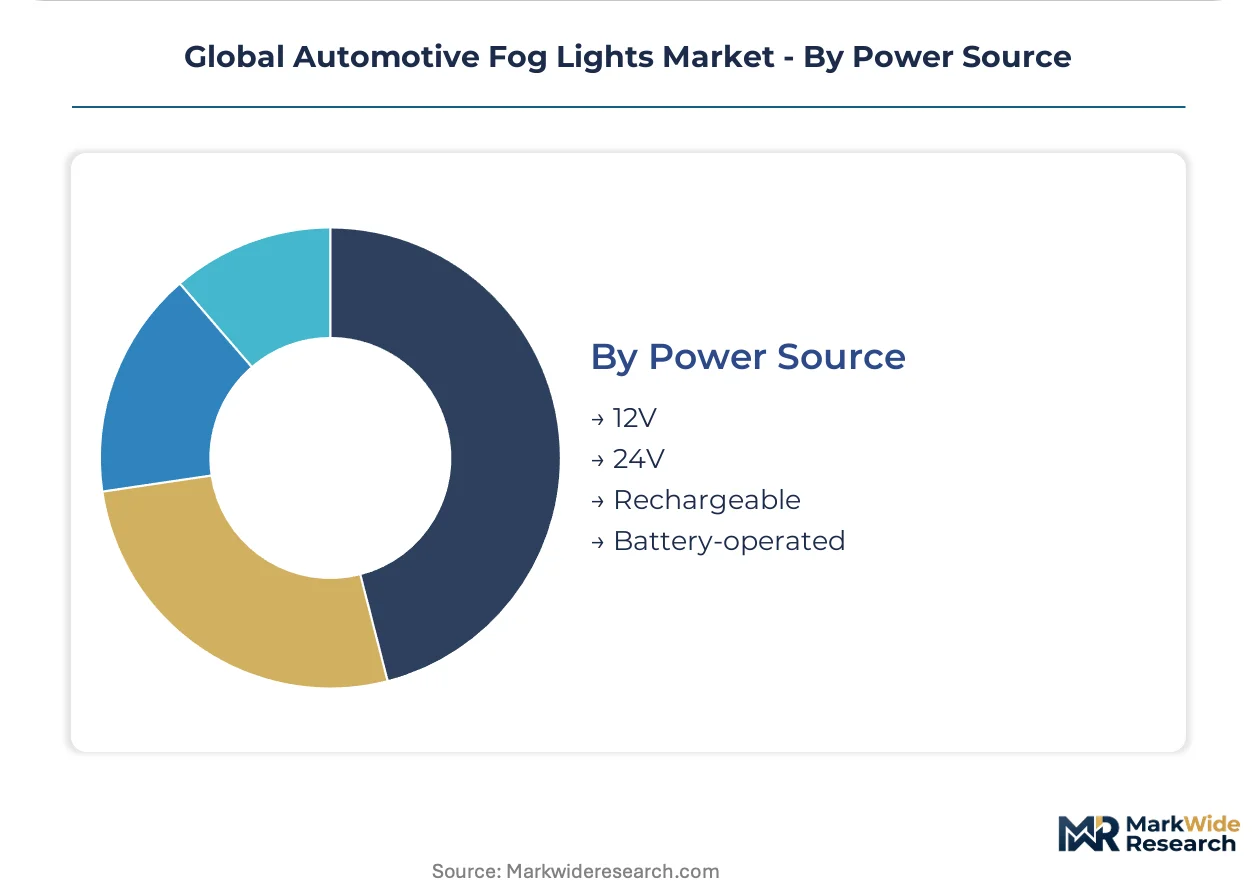
Power Source:
Electrification architectures are rewriting voltage distribution standards and enabling intelligent activation protocols.
- 12V:Legacy electrical systems remain standard across internal combustion platforms; widespread compatibility sustains volume despite efficiency limitations.
- 24V:Commercial truck and bus platforms in European and Brazilian fleets require heavier-gauge wiring and robust switching components.
- Rechargeable:Standalone lithium-ion units serve emergency and auxiliary applications outside primary vehicle electrical systems.
- Battery-operated:Portable fog lighting solutions address off-road and temporary deployment scenarios with minimal installation requirements.
12V systems handle the majority of throughput; 24V architectures are expanding most quickly in commercial electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. Germany and Brazil enforce mandatory fitment through KBA and ANVISA regulations, while the United States and China concentrate demand through OEM integration and export manufacturing clusters respectively.
Germany
KBA beam-pattern certification elevates barrier-to-entry for fog light suppliers serving Stuttgart and Munich OEMs. ECE Regulation 19 photometric standards govern factory-fitment approval cycles spanning 18-24 months. The Baden-Württemberg automotive corridor concentrates LED module development for premium SUV platforms.
Brazil
ANVISA commercial fleet mandates drive heavy-duty truck fog light fitment across humidity corridors. The regulator's visibility requirements accelerate retrofit cycles in São Paulo and Minas Gerais logistics networks. Curitiba and São Paulo industrial zones host assembly operations serving domestic and Mercosur export programs.
United States
NHTSA FMVSS certification requirements shape OEM procurement through Detroit assembly plant proximity. Coastal states generate aftermarket replacement demand where housing corrosion outpaces electronics lifespan. Mexico's Querétaro and Guanajuato lighting clusters supply tariff-advantaged modules to southern US plants.
China
GB 4785 automotive lighting standards create compliance advisory demand for domestic OEM type-approval. Yangtze River Delta and Pearl River Delta manufacturing bases export LED modules to European and North American channels. MIIT industrial policy accelerates solid-state lighting migration across domestic crossover platforms.
Thailand
Japanese tier-one suppliers anchor Southeast Asian production through Bangkok and Eastern Economic Corridor facilities. Cost-competitive halogen output serves regional emerging markets while parallel LED development targets export OEM programs. The country's central logistics position supports just-in-time delivery to ASEAN assembly plants.
Global Automotive Fog Lights Market Vendor Landscape
Capability concentration sits with tier-one lighting specialists possessing captive homologation infrastructure; scale advantage sits with diversified automotive suppliers leveraging cross-product manufacturing footprints. The structure tilts toward consolidation at the premium OEM channel and fragmentation in aftermarket distribution. Three archetypes dominate: full-system integrators with parallel certification workflows, component specialists controlling thermal substrate supply, and diversified automotive electronics houses bundling fog activation with sensor systems. Competitive moves center on geographic clustering for tariff optimization and backward integration into LED die sourcing.
Within the full-system integrator tier, Valeo S.A. and Koito Manufacturing Co., Ltd. exemplify archetypes of European and Asian OEM channel dominance respectively. Robert Bosch GmbH occupies a position bridging automotive electronics integration with lighting module supply. These three anchors represent distinct strategic postures: Valeo leverages complete vehicle integration capability; Koito sustains cost-positioned halogen production alongside premium LED development; Bosch competes through sensor-driven visibility system bundling rather than standalone lighting hardware.
| Leading Market Players |
|---|
| Valeo S.A. |
| Koito Manufacturing Co., Ltd. |
| Robert Bosch GmbH |
| ZKW Group GmbH |
| Hyundai Mobis |
| Magneti Marelli S.p.A. |
| OSRAM GmbH |
| Stanley Electric Co., Ltd. |
| Hella KGaA Hueck & Co. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Thailand's halogen foundries is compressing supplier margins and accelerating price-based competition for emerging-market fleet contracts, while simultaneously forcing incumbents toward LED premiumization to escape commodity tiers.
Pricing Analysis
Long-term offtake contracts dominate OEM procurement, with multi-year supply agreements binding Valeo and Koito to Stuttgart and Munich premium platforms. Price differentiation separates KBA-certified LED modules from uncertified economy alternatives, with thermal substrate quality and homologation status as the primary tiering mechanisms. Pricing pressure stems from aluminum housing cost volatility and redundant UN-ECE/FMVSS certification tooling. Fleet procurement departments in Brazil exhibit highest price sensitivity, while German luxury OEMs prioritize beam-pattern precision over unit cost.
Supply Chain Analysis
Export-control regimes on advanced thermal interface materials constrain flows from Japanese and German specialty chemical suppliers to Asian LED assemblers. Manufacturing concentrates in China, Thailand, and Mexico, with Yangtze River Delta die-casting feeding enclosure production and Querétaro clusters serving Detroit assembly proximity. The supply chain rests on aluminum ingot, phosphor substrates, and glass-filled polyamide resins. Single-source vulnerability sits with thermal engineer talent concentration among tier-one specialists. Distribution runs through direct OEM negotiations rather than aftermarket wholesalers in consolidated fleet segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet procurement consolidation across Brazil and Germany has shifted bargaining power toward large commercial operators negotiating multi-year fitment contracts, fragmenting traditional distributor relationships.
For Market Incumbents: Build certification moats through captive KBA and NHTSA testing infrastructure that compresses homologation timelines below competitor reach. Accelerate backward integration into LED die sourcing to secure thermal substrate supply against phosphor conversion bottlenecks. Camera-based visibility substitution threatens standalone fog module demand; counter through sensor-fog convergence bundling ADAS activation protocols. For New Entrants and Emerging Players: Southeast Asian commercial fleet retrofits present the most penetrable white-space, where ANVISA-mandated halogen demand outpaces certified supplier capacity. Target aftermarket replacement cycles in coastal US states where housing corrosion generates recurring demand independent of OEM channel dominance. Lead with GB 4785 compliance advisory services to capture Chinese domestic OEM type-approval revenue before hardware competition intensifies. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among tier-one lighting specialists with captive homologation infrastructure and multi-year OEM contracts. Long-term viability favors consolidators controlling parallel UN-ECE and FMVSS certification workflows as dual-homologation requirements fragment regional competitors. Acquisition targets should exhibit thermal management IP and established relationships with Stuttgart or Munich platform engineers. Watch for LED junction temperature breakthroughs that collapse halogen's remaining cost advantage in emerging markets.| Strategic Initiative | Industry Significance |
|---|---|
| Homologation Infrastructure Investment | Captive KBA and NHTSA testing labs compress certification timelines below 18 months for OEM channel access. |
| Sensor-Fog Convergence Development | Camera-based meteorological detection integration commands premium positioning in electrified SUV platforms. |
| Mexico Manufacturing Footprint Expansion | Querétaro and Guanajuato clusters offer tariff-advantaged export positioning to Detroit assembly plants. |
| Thermal Substrate Backward Integration | In-house phosphor conversion and LED die sourcing secures supply against specialty chemical export controls. |
| GB 4785 Compliance Service Launch | Advisory revenue from Chinese domestic OEM type-approval captures margin before hardware commoditization. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with tier-one supplier procurement directors, OEM platform engineers, aftermarket distributors, and fleet procurement managers; and secondary validation through vehicle production databases, IHS Markit registration data, KBA type-approval filings, and NHTSA FMVSS certification records. Bottom-up triangulation across LED module bill-of-materials cost structures and top-down reconciliation against OEM fitment rates anchored volume estimates.
Forecast inputs considered vehicle class segmentation, propulsion architecture migration, content-per-vehicle trajectories, and regional production cluster capacity utilization across the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific modeling incorporated ANVISA mandate implementation timelines, KBA beam-pattern enforcement intensity, and thermal management technology diffusion curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese LED assemblers into European OEM channels would shift outcomes. Material shifts in UN-ECE and FMVSS regulatory divergence, aluminum smelting energy cost trajectories, or camera-based visibility substitution penetration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Smart Security Device Market
Automotive Safety and Security Systems
Automotive Active Roll Control System Market
Automotive Safety and Security Systems
Vehicle Tracking Systems Market
Automotive Safety and Security Systems
Automotive Night Vision Sensors Market
Automotive Safety and Security Systems
Europe Pedestrian Detection Systems Market
Automotive Safety and Security Systems
Anti-Lock Braking System (ABS) Market
Automotive Safety and Security Systems
Blind Spot Detection (BSD) System and Adaptive Cruise Control (ACC) System Market
Automotive Safety and Security Systems
Emergency Vehicle Lights Market
Automotive Safety and Security Systems
Whiplash Protection System Market
Automotive Safety and Security Systems
Automotive Fire Suppression System Market
Automotive Safety and Security Systems
Automotive Crash Sensor Market
Automotive Safety and Security Systems
Middle East and Africa Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Automotive Fusion Sensors Market
Automotive Safety and Security Systems
Automotive Radar Market
Automotive Safety and Security Systems
Automotive Smart Helmet Market
Automotive Safety and Security Systems
Lane Departure Warning System Market