
 Blind Spot Detection (BSD) System and Adaptive Cruise Control (ACC) System Market | 2026-2036
Blind Spot Detection (BSD) System and Adaptive Cruise Control (ACC) System Market Size, Share, and Industry Trends Forecast 2026-2036
Blind Spot Detection (BSD) System and Adaptive Cruise Control (ACC) System Market Outlook
Sensor fusion architecture is fragmenting into modular compute platforms that separate perception hardware from decision software. Robert Bosch GmbH leverages its MEMS radar foundry to sustain cost leadership in 77 GHz front-end modules. Continental AG anchors European supply through captive LiDAR calibration facilities in Bavaria. Denso Corporation dominates thermal management for fused sensor arrays across Japanese OEM programs.
Blind Spot Detection and Adaptive Cruise Control systems combine electromagnetic ranging with machine vision to monitor adjacent traffic lanes and maintain following distances through automated throttle and brake modulation. Radar-centric implementations operate at 24 or 77 GHz with detection ranges exceeding 200 meters for highway-speed scenarios. Camera-based segments command premium positioning where lane-level discrimination requires optical classification of vulnerable road users. Ultrasonic technology occupies the entry tier for low-speed parking-adjacent applications with constrained processing overhead. Fleet Management as an application dimension is expanding fastest as logistics operators mandate active safety across Class 8 tractor deployments.
NHTSA mandates automatic emergency braking compatibility with ACC systems for light vehicles sold in the United States. Euro NCAP protocols reward integrated BSD performance with lane-change assist functionality under the European Commission's vehicle safety framework. OEMs must certify sensor interoperability under UNECE R79 for steering control and R152 for automatic braking to access type approval in EU member states. Stakeholders should monitor how software-defined vehicle architectures redistribute validation liability between Tier 1 integrators and semiconductor suppliers.
Market Dynamics
Sensor fusion architectures are fragmenting into modular compute platforms that separate perception hardware from decision software, redistributing value capture between semiconductor suppliers and Tier 1 integrators across the BSD-ACC supply base.
Growth Catalysts
- Euro NCAP Safety Protocols:The European Commission's vehicle safety framework rewards integrated BSD performance with lane-change assist functionality, compelling OEMs to bundle ACC compatibility into new vehicle programs.
- Fleet Operator Mandates:Commercial vehicle logistics operators are accelerating adoption of integrated BSD-ACC packages across Class 8 tractor deployments to reduce insurance liability and driver fatigue incidents.
- 77 GHz Radar Maturation:Advanced front-end modules now deliver detection ranges exceeding 200 meters for highway-speed scenarios, enabling single-sensor ACC implementations that lower system cost.
Market Restraints
- LiDAR Calibration Bottleneck:Continental AG's captive calibration facilities in Bavaria create geographic supply concentration for fused sensor arrays, limiting second-source availability.
- UNECE Type Approval Complexity:Certification under R79 for steering control and R152 for automatic braking requires sensor interoperability validation that extends OEM integration timelines.
- Thermal Management Cost:Fused sensor arrays require sophisticated thermal dissipation systems that add material cost and packaging volume to compact vehicle platforms.
Strategic Opportunities
- Software-Defined Vehicle Architectures:Decoupled perception-compute stacks create openings for semiconductor suppliers to capture validation liability previously held by Tier 1 integrators.
- Japanese OEM Integration Programs:Denso Corporation's thermal management dominance positions suppliers to anchor fused sensor deployments across Toyota, Honda, and Nissan vehicle lines.
- Entry-Tier Ultrasonic Expansion:Low-speed parking-adjacent applications with constrained processing overhead represent white space for cost-optimized BSD implementations in emerging market vehicle segments.
Industry Challenges
- Functional Safety Engineering Scarcity:ISO 26262 ASIL-D certification expertise concentrates at Robert Bosch GmbH and Continental AG, constraining supplier base expansion.
- Legacy CAN Bus Integration:ACC throttle and brake modulation systems must interface with legacy vehicle networks that lack deterministic latency guarantees for automated control loops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blind Spot Detection (BSD) System and Adaptive Cruise Control (ACC) System Market |
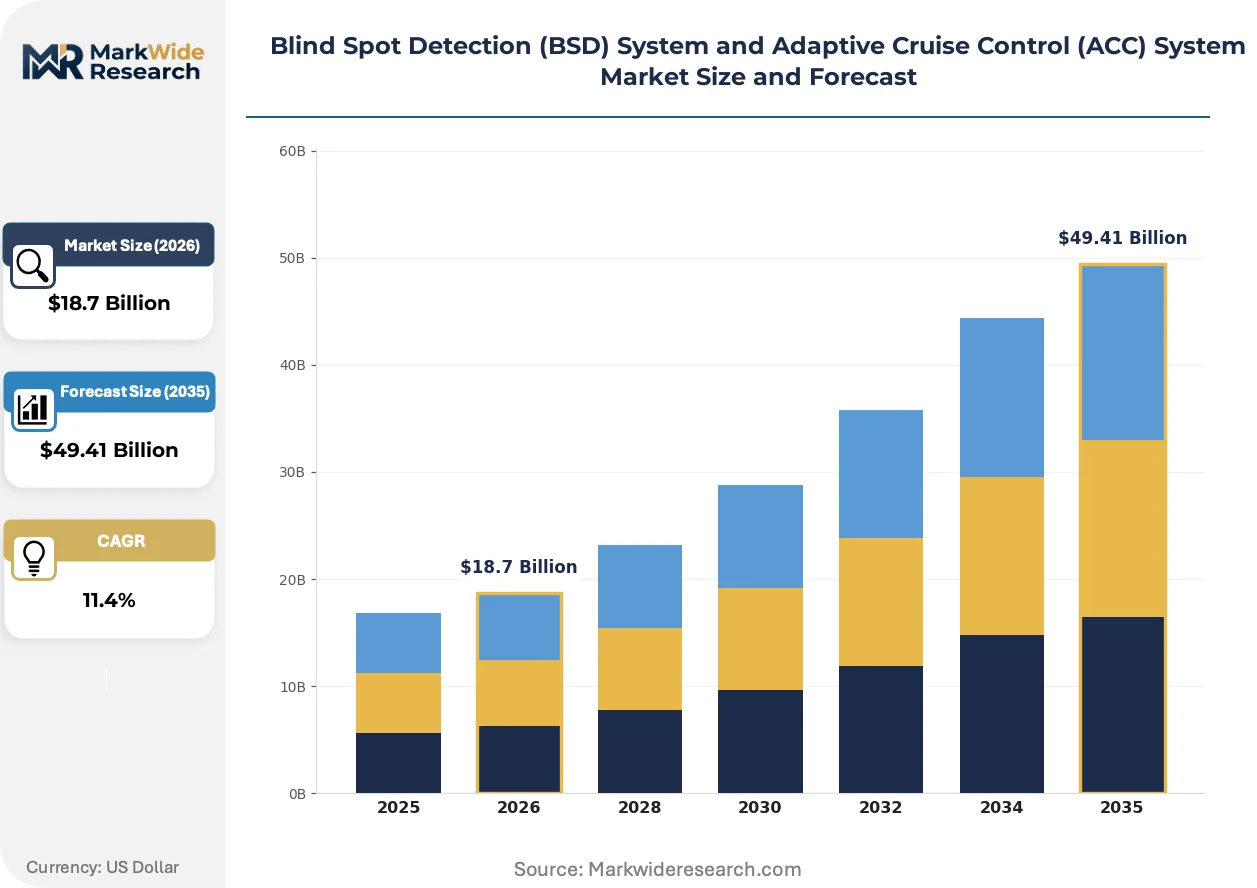
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Radar, Lidar, Camera, Ultrasonic Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Fleet Management End User: Automakers, Aftermarket Providers, Fleet Operators, Vehicle Assemblers Feature: Traffic Monitoring, Lane Change Alert, Collision Prevention, Adaptive Speed Control |
| Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, ZF Friedrichshafen AG, Valeo SA, NXP Semiconductors, Infineon Technologies AG, Autoliv Inc., Aptiv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blind Spot Detection (BSD) System and Adaptive Cruise Control (ACC) System Market Strategic Shifts
Machine vision algorithms are displacing radar-only implementations for lane-level discrimination, while regulatory mandates tighten performance thresholds and fleet buyers restructure procurement around active safety outcomes.
4D imaging radar is virtualizing the perception layer of BSD-ACC systems by delivering dense point clouds that mimic LiDAR spatial resolution without optical vulnerability to weather conditions. Commercial vehicle fleet operators are adopting 4D radar platforms fastest, drawn by all-weather reliability requirements for long-haul logistics. This virtualization is compressing the addressable market for standalone LiDAR suppliers in highway-speed ACC applications.
NHTSA mandates automatic emergency braking compatibility with ACC systems for light vehicles sold in the United States, binding active cruise functionality to broader vehicle safety architectures. The regulation forces OEMs to source integrated sensor suites rather than discrete ACC modules, consolidating supplier relationships. Light truck and SUV segments face the steepest compliance cost pressure due to higher vehicle mass and longer braking distances.
Logistics operators are restructuring commercial vehicle acquisition around total cost of ownership metrics that weight insurance premium reductions from active safety systems against upfront hardware cost. Fleet management service providers are displacing traditional dealer channels for Class 8 tractor BSD-ACC specification, bundling hardware with telematics and driver coaching programs. This shift is most visible across United States long-haul carriers where driver turnover and liability exposure concentrate procurement authority at fleet headquarters rather than regional dealerships.
Blind Spot Detection (BSD) System and Adaptive Cruise Control (ACC) System Market Segmentation
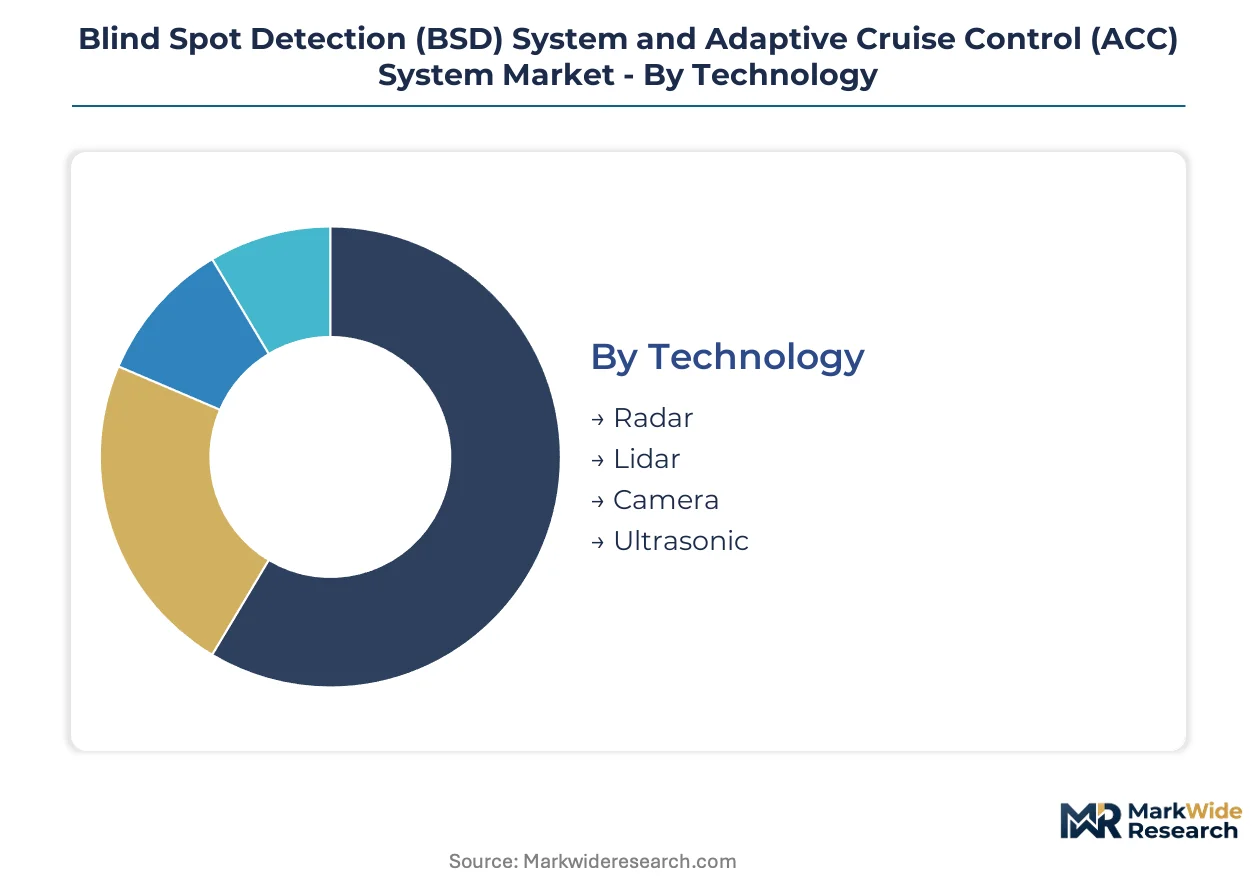
BSD-ACC system configurations fragment sharply across sensor modalities and vehicle duty cycles, with procurement authority shifting from OEM specification desks to fleet headquarters. Understanding these segment boundaries clarifies where validation liability pools and which integration architectures command pricing power.
Technology:
Mature electromagnetic ranging dominates highway-speed applications while emerging optical and ultrasonic modalities capture niche deployment scenarios.
- Radar:77 GHz front-end modules deliver detection ranges exceeding 200 meters for single-sensor ACC implementations. Demand concentrates in German and United States highway programs where NHTSA mandates automatic emergency braking compatibility. Robert Bosch GmbH leverages captive MEMS foundry capacity to sustain cost leadership in this tier.
- Camera:Machine vision algorithms enable lane-level discrimination and vulnerable road user classification where optical resolution exceeds radar point cloud density. Japanese OEM integration timelines favor camera-centric architectures for urban traffic monitoring in dense metropolitan corridors.
- Lidar:Continental AG's Bavarian calibration facilities anchor European supply for fused sensor arrays requiring centimeter-level spatial precision.
- Ultrasonic:Entry-tier implementations target low-speed parking-adjacent applications with constrained processing overhead in emerging market vehicle segments.
Radar retains volume leadership; camera holds the steepest expansion curve.
Application:
Customer type stratification separates individual owner-operators from centralized fleet procurement with divergent total cost of ownership calculations.
- Commercial Vehicles:Class 8 tractor deployments mandate integrated BSD-ACC packages as logistics operators restructure acquisition around insurance premium reductions. United States long-haul carriers concentrate procurement authority at headquarters rather than regional dealerships.
- Fleet Management:Service providers bundle hardware with telematics and driver coaching programs, displacing traditional dealer channels fastest across North American freight corridors.
- Passenger Vehicles:Light truck and SUV segments face steepest compliance cost pressure under NHTSA automatic emergency braking mandates due to higher vehicle mass and longer braking distances.
- Two-Wheelers:Compact packaging constraints limit sensor fusion complexity to single-modality implementations in high-density Asian urban markets.
Commercial Vehicles anchor current revenue; Fleet Management is gaining share fastest.
End User:
Supply chain position determines whether specification authority rests with vehicle manufacturers, third-party integrators, or operating fleet entities.
- Automakers:OEMs must certify sensor interoperability under UNECE R79 for steering control and R152 for automatic braking to access type approval in EU member states, consolidating supplier relationships around integrated suites.
- Fleet Operators:Logistics entities now mandate active safety across tractor deployments, shifting procurement from dealer channels to direct Tier 1 negotiation.
- Aftermarket Providers:Retrofit installations face legacy CAN bus integration constraints where deterministic latency guarantees are absent for automated control loops.
- Vehicle Assemblers:Contract manufacturers in emerging production clusters source modular compute platforms that separate perception hardware from decision software.
Automakers dominate specification volume; Fleet Operators are climbing the fastest.
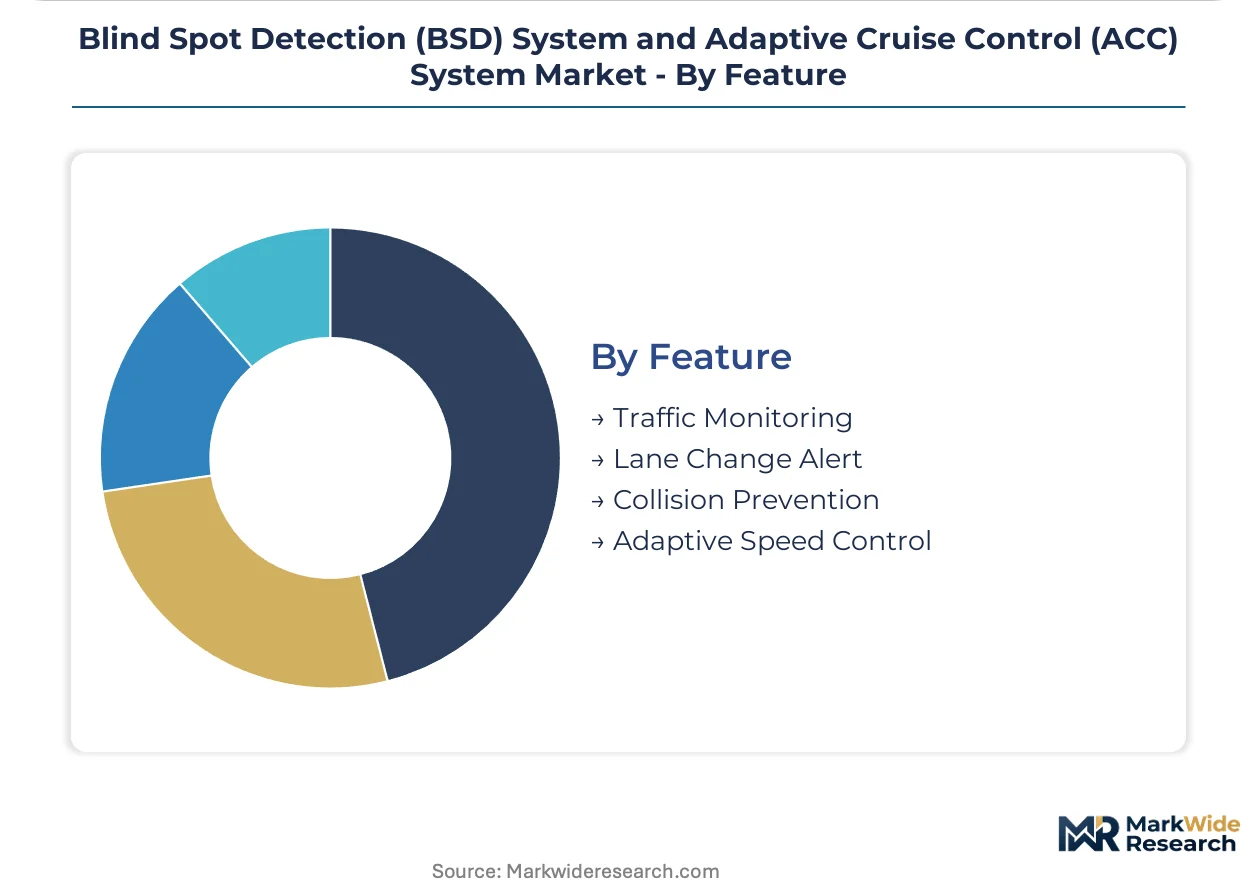
Feature:
Functional integration depth separates discrete warning systems from closed-loop automated control with divergent validation liability profiles.
- Collision Prevention:Automatic braking functionality binds ACC systems to broader vehicle safety architectures under NHTSA mandates for light vehicles sold in the United States.
- Adaptive Speed Control:Throttle and brake modulation through automated control loops requires ISO 26262 ASIL-D certification expertise that concentrates at major Tier 1 integrators.
- Traffic Monitoring:Adjacent lane surveillance through electromagnetic ranging supports driver awareness without assuming vehicle control authority.
- Lane Change Alert:Euro NCAP protocols reward integrated BSD performance with lane-change assist functionality under the European Commission's vehicle safety framework.
Collision Prevention commands the highest integration investment; Adaptive Speed Control is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and premium passenger vehicle buyers concentrate procurement authority in Germany, the United States, and Japan where OEM integration timelines are shortest and regulatory mandates are most stringent.
United States
Class 8 tractor deployments drive integrated BSD-ACC package demand as long-haul carriers restructure acquisition around insurance premium reductions. NHTSA mandates automatic emergency braking compatibility with ACC systems for light vehicles sold domestically. Detroit's automotive corridor anchors Tier 1 integration facilities serving domestic OEM programs.
Germany
Highway-speed ACC implementations dominate procurement as single-sensor 77 GHz radar configurations lower system cost for autobahn-capable vehicles. Euro NCAP protocols reward integrated BSD performance with lane-change assist functionality under the European Commission's vehicle safety framework. Bavaria hosts captive LiDAR calibration facilities that anchor European supply for fused sensor arrays.
Japan
Camera-centric architectures favor urban traffic monitoring in dense metropolitan corridors where optical resolution exceeds radar point cloud density. METI standards guide sensor interoperability certification for steering control systems. Toyota City and surrounding Aichi Prefecture concentrate thermal management expertise for fused sensor deployments across domestic OEM programs.
China
Domestic OEMs accelerate software-defined vehicle architectures that decouple perception hardware from decision software. GB standards and MIIT regulations shape autonomous driving system validation requirements. Yangtze River Delta manufacturing clusters source modular compute platforms for cost-optimized BSD implementations in emerging market vehicle segments.
South Korea
Premium passenger vehicle segments adopt fused sensor arrays for lane-level discrimination and vulnerable road user classification. MFDS automotive safety guidelines align with UNECE R79 and R152 type approval requirements for EU market access. Seoul Capital Area R&D centers develop machine vision algorithms displacing radar-only implementations.
Blind Spot Detection (BSD) System and Adaptive Cruise Control (ACC) System Market Competitive Environment
Channel-controlling players compete with product-specialist players across a supply base fragmenting into modular compute platforms. Tier 1 integrators retain validation liability for ISO 26262 ASIL-D certification while semiconductor suppliers capture value from decoupled perception-compute stacks. Three archetypes dominate: captive foundry operators with MEMS radar capacity, thermal management specialists for fused sensor arrays, and software-defined platform providers. Competitive moves concentrate on strategic partnerships for sensor interoperability and geographic expansion through captive calibration facilities.
Within the integrated systems tier, Robert Bosch GmbH and Continental AG exemplify channel-controlling players with captive manufacturing assets. Denso Corporation occupies a specialist position anchoring thermal management supply for Japanese OEM programs. These three entities represent the dominant competitive anchors across radar-centric, LiDAR-fused, and camera-centric implementation vectors.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| ZF Friedrichshafen AG |
| Valeo SA |
| NXP Semiconductors |
| Infineon Technologies AG |
| Autoliv Inc. |
| Aptiv |
| Others |
Value Chain & Pricing Dynamics
MEMS foundry overcapacity in Taiwan and Germany compresses 77 GHz radar module pricing while forcing suppliers toward software differentiation to preserve margin. This utilization dynamic accelerates cost-plus contract renegotiations for Tier 1 integrators locked into long-term OEM supply agreements.
Pricing Analysis
Cost-plus contracts with semiconductor raw material indexation dominate 77 GHz radar procurement, tying module pricing to silicon wafer and gallium arsenide substrate benchmarks. Price differentiation rests on ISO 26262 ASIL-D certification tier and thermal management integration depth. Cost compression in entry-tier ultrasonic implementations intensifies as Chinese OEMs source modular compute platforms from Yangtze River Delta clusters. Fleet operators exhibit lowest price sensitivity due to insurance premium reduction calculations, while emerging market vehicle assemblers face acute budget constraints.
Supply Chain Analysis
Gallium arsenide substrate supply draws from Germany, Japan, and the United States, with MEMS fabrication capacity concentrated in Taiwan and South Korea. Critical dependencies include 77 GHz RF front-end modules, fused sensor array thermal substrates, and LiDAR calibration equipment. Single-source vulnerability concentrates around Continental AG's Bavarian calibration facilities for fused sensor arrays. Distribution runs through captive Tier 1 integration facilities serving OEM platform engineering teams directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined vehicle architectures are redistributing platform economics toward semiconductor suppliers capable of assuming validation liability previously held by integrators. This interoperability shift fragments value capture across decoupled perception-compute stacks.
For Market Incumbents: Harden sensor interoperability certification under UNECE R79 and R152 to defend against semiconductor suppliers capturing validation liability. Deepen backward integration into MEMS radar foundry capacity to offset pricing pressure from modular compute platforms. Anchor relationships with fleet management service providers displacing dealer channels. For New Entrants and Emerging Players: Build out ultrasonic-based entry-tier offerings for emerging market vehicle segments where processing overhead constraints favor cost-optimized implementations. Target Chinese OEM software-defined architectures as the most penetrable vector. Pursue direct fleet operator relationships bypassing traditional Tier 1 integration channels. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because NHTSA and Euro NCAP mandates consolidate procurement around certified integrated suites rather than discrete modules. Target thermal management specialists for fused sensor arrays as acquisition candidates. Watch for 4D imaging radar virtualization compressing standalone LiDAR addressable market as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Interoperability Certification | UNECE R79 and R152 compliance locks in OEM supplier relationships across EU type approval. |
| MEMS Foundry Capacity Expansion | Captive 77 GHz radar fabrication sustains cost leadership against modular platform competitors. |
| Fleet Management Partnership | Direct procurement relationships with Class 8 operators displace traditional dealer channels. |
| 4D Imaging Radar Development | All-weather point cloud virtualization threatens standalone LiDAR in highway-speed applications. |
| Software-Defined Vehicle Investment | Decoupled perception-compute stacks redistribute validation liability toward semiconductor suppliers. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with Tier 1 supplier procurement managers, OEM platform engineers, fleet operations directors, and aftermarket distribution heads; and secondary validation against NHTSA regulatory filings, Euro NCAP test protocols, UNECE type approval databases, and vehicle production registration data. Bottom-up unit economics triangulated against top-down market sizing across sensor modality and vehicle duty cycle segments.
Forecast inputs considered technology substitution curves for 4D imaging radar displacing LiDAR, regulatory mandate phase-in schedules across NHTSA and Euro NCAP frameworks, and fleet operator procurement centralization trends. Segmentation modeling spanned sensor technology, application type, end-user category, and functional feature depth. CAGRs derived from fitted adoption curves weighted by OEM integration timeline data across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by semiconductor suppliers or rapid 4D radar cost reduction would shift outcomes beyond modeled bounds. Cross-checking against IHS Markit vehicle production forecasts and insurer loss-ratio data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Corner Sonar Market
Automotive Safety and Security Systems
AI in-Vehicle Surveillance Market
Automotive Safety and Security Systems
Europe Automotive Night Vision System Market
Automotive Safety and Security Systems
Automotive Biometric Identification Market
Automotive Safety and Security Systems
Automotive Surge Absorber Market
Automotive Safety and Security Systems
Automatic High Beam Control Market
Automotive Safety and Security Systems
Automatic Brake Pad Inspection System Market
Automotive Safety and Security Systems
Automotive Seatbelt Market
Automotive Safety and Security Systems
Global Automotive Curtain Airbags Market
Automotive Safety and Security Systems
Lane Departure Warning System Market
Automotive Safety and Security Systems
Safety Restraint Systems Market
Automotive Safety and Security Systems
Road Speed Limiter Market
Automotive Safety and Security Systems
Motorcycle Stability Control Market
Automotive Safety and Security Systems
Steering Column Locks Market
Automotive Safety and Security Systems
Trailer Assist System Market
Automotive Safety and Security Systems
Automotive Biometric Access System Market