
 Automotive Engineering Service Providers (ESP) Market | 2026-2036
Automotive Engineering Service Providers (ESP) Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Engineering Service Providers (ESP) Market Insights
The shift from captive in-house engineering to multi-source outsourcing is broadening the competitive field for specialized automotive ESPs. Robert Bosch GmbH leverages its embedded systems heritage to anchor powertrain software contracts with European OEMs. Tech Mahindra Limited competes on cost-engineering scale for Indian and Asian vehicle programs. AVL LIST GmbH specializes in powertrain testing and validation, dominating emission certification workflows for hybrid architectures.
Automotive Engineering Service Providers deliver outsourced technical capabilities spanning vehicle design, prototype validation, manufacturing process design, and regulatory compliance documentation. These services integrate simulation software, hardware-in-the-loop testing, and CAD-based digital twin development to reduce OEM development cycles from concept to production. Design & Development commands the largest revenue share as OEMs externalize platform architecture for electric and autonomous vehicle programs. Testing & Validation captures expanding margin pools driven by stricter homologation requirements across multiple jurisdictions. Embedded Systems within the technology dimension is accelerating fastest as software-defined vehicle architectures displace hardware-centric development models.
The EPA in the United States, EMA in Europe, and MIIT in China enforce diverging emission and safety standards that fragment compliance costs across regional engineering centers. REACH chemical restrictions and the EU AI Act for autonomous systems are adding new certification layers that OEMs address through specialized ESP partnerships rather than internal capability builds. Stakeholders must monitor how regulatory divergence between North American, European, and Chinese frameworks reshapes the geographic distribution of engineering service contracts.
Market Dynamics
The migration from hardware-centric vehicle architectures to software-defined platforms is fragmenting engineering workflows across OEM supplier bases. Tier-1 suppliers now compete directly with pure-play software houses for embedded systems contracts, compressing traditional service provider margins while expanding addressable scope.
Growth Catalysts
- EU Green Deal emissions mandates:Accelerated compliance timelines force OEMs to externalize powertrain redesign cycles rather than rebuild internal capabilities.
- China's dual carbon goals:Domestic OEMs scramble for foreign engineering expertise to meet MIIT efficiency standards for NEV platforms.
- Hardware-in-the-loop simulation:Virtual validation environments slash prototype build costs, expanding ESP contract values for digital twin development.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea fab bottlenecks delay ECU development schedules, stretching ESP project timelines.
- REACH chemical compliance:ECHA substance restrictions complicate material selection for battery thermal management systems.
- Functional safety certification costs:ISO 26262 ASIL-D validation requirements demand specialized personnel that ESPs struggle to retain.
Strategic Opportunities
- India's PLI scheme for automotive:Domestic OEM expansion creates demand for cost-optimized engineering services from global ESPs.
- Vehicle-to-grid integration:Bidirectional charging architectures require new power electronics competencies that incumbent ESPs lack.
- EU AI Act autonomous vehicle provisions:Certification frameworks for machine learning-based perception systems open specialized service niches.
Industry Challenges
- Embedded software talent scarcity:AUTOSAR Classic and Adaptive stack expertise commands premium wages that mid-tier ESPs cannot match.
- Multi-jurisdiction homologation:Simultaneous EPA, EMA, and MIIT certification cycles strain project management bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Engineering Service Providers (ESP) Market |
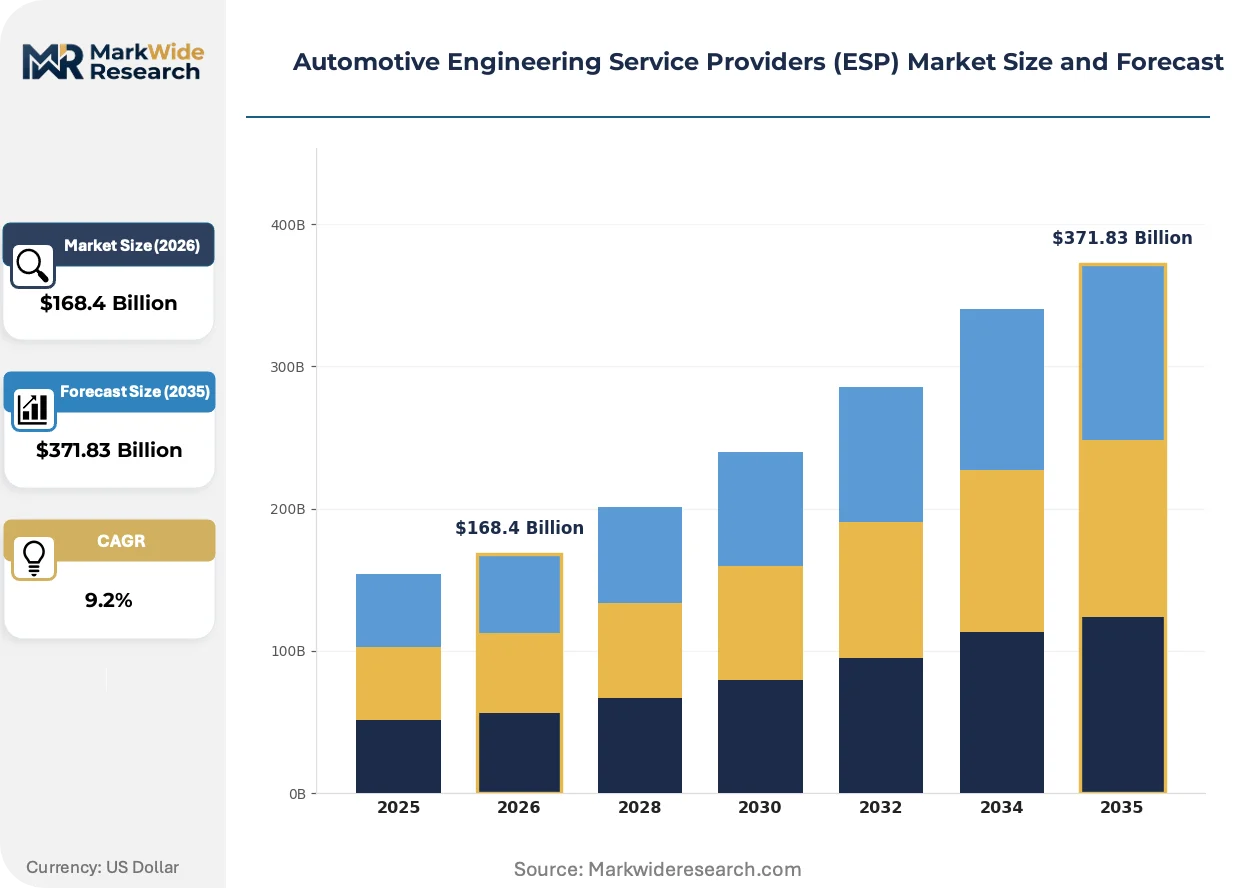
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $371.83 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design & Development, Testing & Validation, Manufacturing Support, Consulting End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Simulation Software, Embedded Systems, CAD, ADAS Solutions Application: Electric Vehicles, Autonomous Vehicles, Internal Combustion Engines, Hybrid Systems |
| Companies Covered | HCL Technologies Limited, Tech Mahindra Limited, Robert Bosch GmbH, AVL LIST GmbH, Alten Group, Magna International Inc., Harman International Industries Inc., FEV GmbH, Capgemini Technology Services Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Engineering Service Providers (ESP) Market Trends and Innovations
Software-defined vehicle architectures are collapsing traditional hardware-software boundaries, forcing ESPs to restructure delivery models around continuous integration rather than gated milestone releases.
Model-based systems engineering (MBSE) is automating requirements traceability from concept through validation. European OEMs now mandate SysML-based documentation for all platform programs, compressing design review cycles from months to weeks. ESPs lacking MBSE tooling expertise face exclusion from major RFQ processes.
REACH chemical restrictions and the EU AI Act are layering new certification requirements onto existing homologation pathways. Battery material declarations now require full supply chain substance accounting. ESPs with embedded regulatory intelligence capabilities capture margin premiums on compliance documentation services.
Fixed-price engineering contracts are yielding to time-and-material arrangements with gain-share provisions for milestone acceleration. German OEM procurement teams now index payments to prototype delivery schedules rather than specification completion. This shift transfers schedule risk to ESPs while rewarding execution speed in powertrain programs.
Automotive Engineering Service Providers (ESP) Market Segmentation
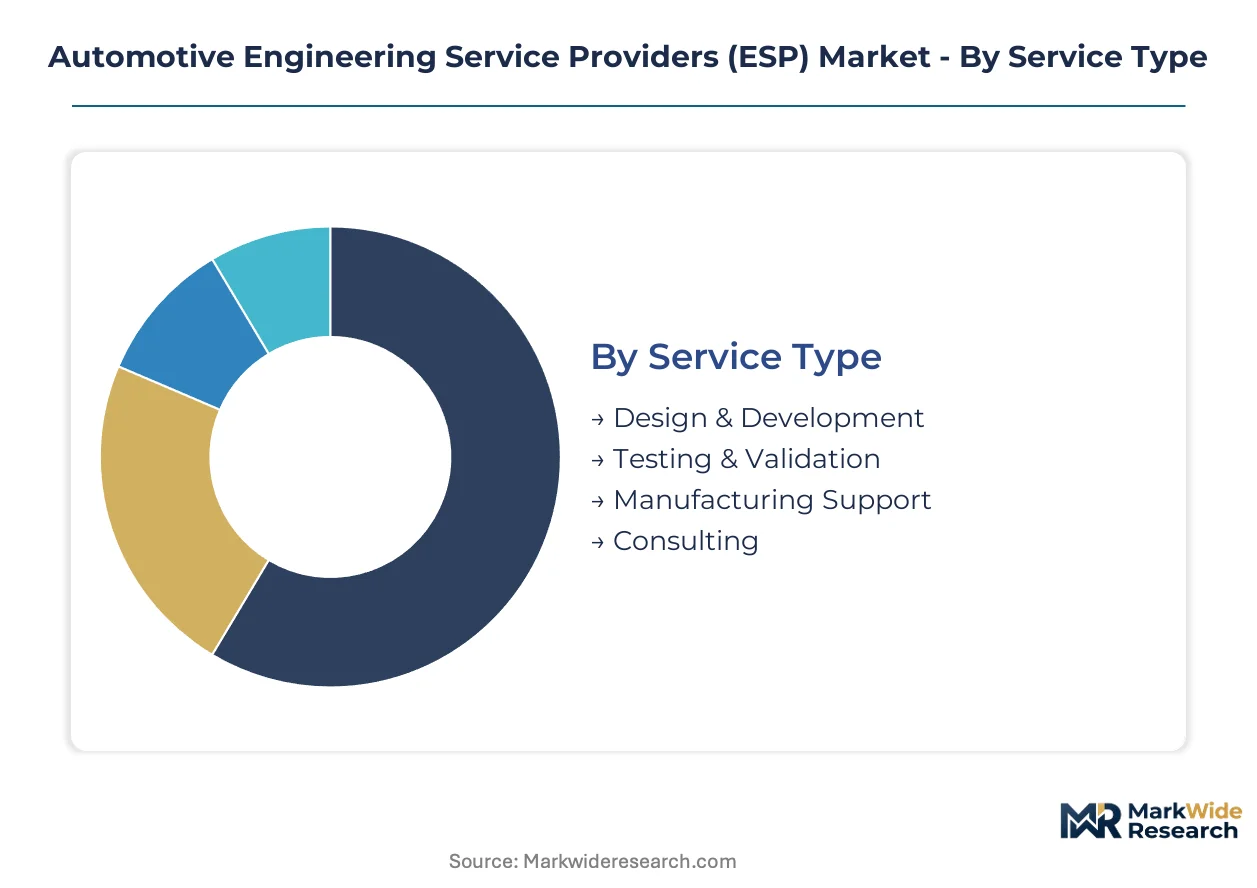
Automotive ESPs structure their capabilities around distinct service tiers and technology platforms that map to divergent OEM sourcing strategies. Understanding these segment boundaries clarifies where contract values concentrate and which capability investments yield competitive position.
Service Type:
Volume engineering concentrates in standardized validation workflows, while premium margins attach to integrated platform architecture services.
- Design & Development:Platform architecture, powertrain integration, and vehicle packaging services that span concept through production release. German and Chinese OEMs externalize complete EV skateboard development to ESPs with embedded systems competency, compressing internal headcount while accelerating program timelines.
- Testing & Validation:Hardware-in-the-loop simulation, emission certification, and homologation documentation for EPA, EMA, and MIIT compliance. Stricter EU Green Deal enforcement and China's MIIT efficiency standards expand contract scope for emission test cycles and battery safety validation.
- Manufacturing Support:Process engineering, tooling design, and production line optimization for vehicle assembly and component fabrication. Tier-1 suppliers in the United States deploy these services for EV battery pack assembly scale-up.
- Consulting:Regulatory strategy, supply chain risk assessment, and technology roadmap advisory. OEMs in China leverage foreign ESP consulting to navigate MIIT NEV subsidy qualification and dual carbon compliance pathways.
Mature deployment sits with Testing & Validation. Newer deployment is concentrated in Design & Development.
End User:
Procurement authority fragments across the supply chain, with each tier demanding different ESP engagement models and technical depth.
- OEMs:Full-platform engineering contracts spanning vehicle architecture, powertrain, and embedded software. Volkswagen, BYD, and Ford source complete EV platform development from ESPs with AUTOSAR stack expertise and hardware-in-the-loop validation infrastructure.
- Tier-1 Suppliers:Component-level engineering for braking, steering, and thermal management systems. Bosch and Continental outsource specific validation cycles to specialized ESPs to manage peak workload periods.
- Aftermarket Providers:Retrofit engineering, diagnostic tool development, and compliance recertification for vehicle modifications. California-based aftermarket specialists contract ESPs for EPA emission recertification of converted ICE-to-EV platforms.
- Vehicle Assemblers:Contract manufacturing engineering and quality system implementation for low-volume production. Emerging EV brands in India engage ESPs for production line design under the PLI scheme.
Contract value depth runs thickest with OEMs. Procurement velocity is climbing fastest among Tier-1 Suppliers.
Technology:
Margin capture diverges sharply between commoditized design tools and specialized embedded software stacks.
- Simulation Software:Multi-physics modeling, crash simulation, and aerodynamic analysis tools. German OEMs mandate SysML-based simulation environments for all platform programs, consolidating vendor relationships around MBSE-capable ESPs.
- Embedded Systems:AUTOSAR Classic and Adaptive stack development, ECU software, and functional safety certification to ISO 26262 ASIL-D. This segment commands premium pricing due to acute talent scarcity in AUTOSAR architecture and cybersecurity integration.
- CAD:Digital twin development, geometric modeling, and manufacturing process simulation. Standardized CAD services face margin compression as OEMs internalize basic tooling expertise.
- ADAS Solutions:Perception algorithm development, sensor fusion, and machine learning validation for autonomous systems. EU AI Act certification requirements for AI-based perception create specialized service demand that generalist ESPs cannot fulfill.
Tooling commoditization is most advanced in CAD. Capability scarcity sits with Embedded Systems.
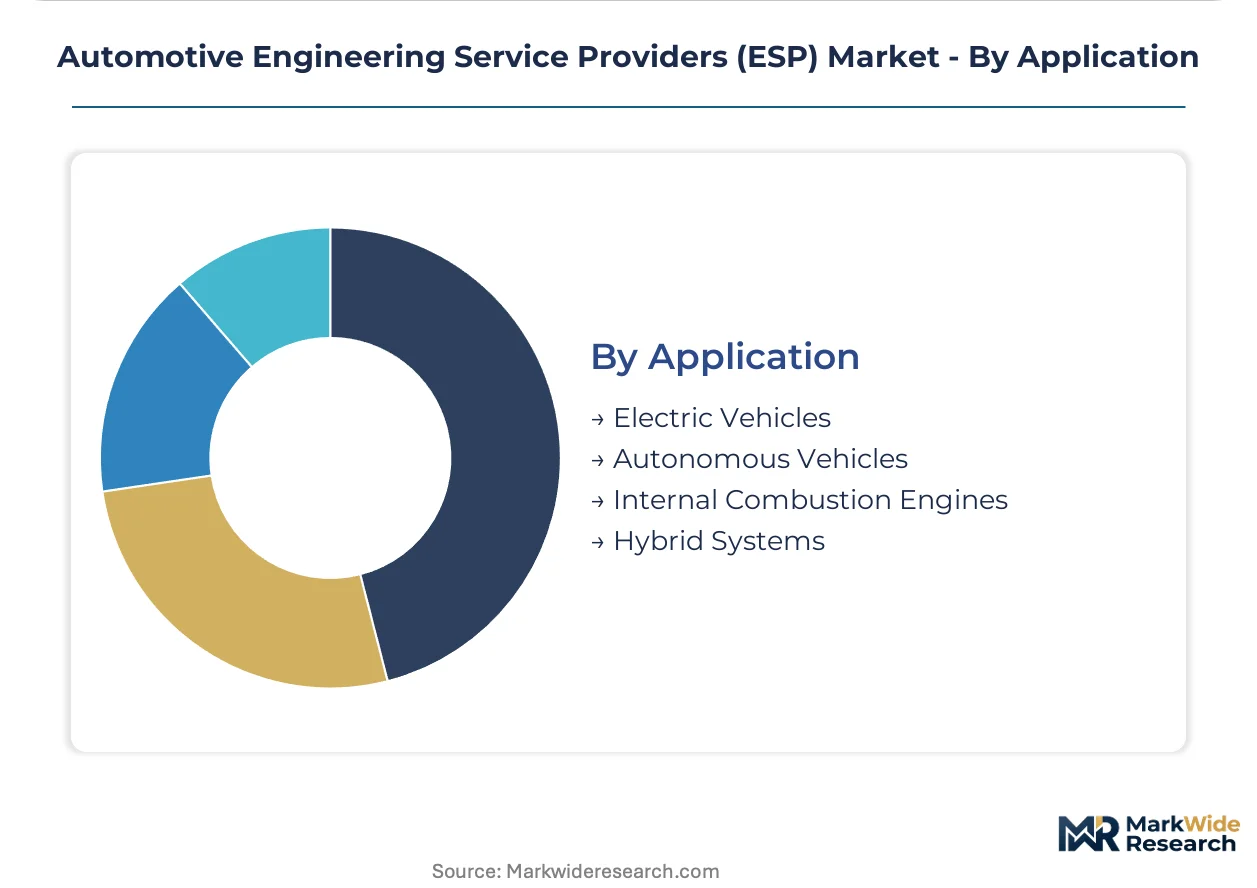
Application:
Engineering intensity and contract duration vary dramatically across powertrain architectures.
- Electric Vehicles:Battery thermal management, power electronics, and high-voltage safety system engineering. China's NEV platform surge and EU Green Deal ICE phase-outs concentrate EV engineering demand in ESPs with powertrain electrification expertise.
- Autonomous Vehicles:Perception stack development, sensor validation, and functional safety engineering for SAE Level 2+ through Level 4 systems. California and Germany host the primary development centers, with ESPs competing on ML ops and simulation environment depth.
- Internal Combustion Engines:Emission reduction engineering, aftertreatment system optimization, and efficiency improvement for remaining ICE production. Declining OEM investment compresses contract scope to specific compliance-driven redesign cycles.
- Hybrid Systems:Power-split architecture, battery-ICE integration, and dual-powertrain control software. Japanese OEMs and European premium brands sustain hybrid engineering demand as a bridge technology during full electrification transitions.
Investment withdrawal is most pronounced in Internal Combustion Engines. Engineering complexity is expanding fastest in Autonomous Vehicles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley software talent and Stuttgart powertrain heritage anchor the Automotive Engineering Service Providers market across three continents. Engineering service contracts concentrate where OEM headquarters, tier-1 supplier networks, and regulatory compliance centers overlap.
United States
Detroit's EV platform investments and California's autonomous vehicle development drive outsourcing demand. EPA emission standards and NHTSA safety mandates force OEMs to externalize validation cycles. Austin and Silicon Valley host specialized ESPs for ADAS perception algorithm development.
Germany
EU Green Deal ICE phase-outs and premium OEM electrification programs accelerate powertrain engineering contracts. KBA type-approval requirements and REACH chemical compliance create specialized documentation demand. Stuttgart and Munich engineering clusters concentrate ESP delivery centers for European OEM programs.
China
MIIT NEV subsidy qualifications and dual carbon goals push domestic OEMs toward foreign engineering expertise. BYD and NIO platform expansion creates demand for powertrain integration services. Shanghai and Shenzhen engineering hubs host ESPs serving both domestic brands and joint ventures.
India
PLI scheme automotive incentives attract OEM manufacturing investment, creating downstream engineering service demand. BIS certification requirements for component safety add compliance documentation needs. Pune and Chennai automotive corridors concentrate ESP delivery centers for cost-optimized vehicle programs.
Japan
Hybrid system bridge technology sustains engineering demand during full electrification transitions. METI carbon neutrality targets accelerate battery thermal management outsourcing. Nagoya and Tokyo engineering clusters host ESPs specializing in power-split architecture and dual-powertrain control software.
Automotive Engineering Service Providers (ESP) Market Competitive Landscape
Global majors compete with regional champions across embedded systems and validation services, producing a tiered market structure. Consolidation pressure runs strongest in software-defined vehicle segments where scale determines platform access. Three archetypes dominate: diversified technology conglomerates with automotive divisions, pure-play engineering specialists with deep domain expertise, and IT services firms leveraging offshore delivery scale. Competitive moves center on strategic partnerships for AUTOSAR stack access and geographic expansion into NEV engineering hubs.
Among diversified technology conglomerates, Robert Bosch GmbH and Harman International Industries Inc. exemplify integrated hardware-software positioning. Tech Mahindra Limited represents the IT services archetype with offshore delivery capabilities. AVL LIST GmbH and FEV GmbH occupy specialist positions in powertrain testing and validation workflows. HCL Technologies Limited and Capgemini Technology Services Limited sit within the technology services tier competing on embedded software talent scale. Alten Group and Magna International Inc. exemplify European engineering workforce deployment models.
| Leading Market Players |
|---|
| HCL Technologies Limited |
| Tech Mahindra Limited |
| Robert Bosch GmbH |
| AVL LIST GmbH |
| Alten Group |
| Magna International Inc. |
| Harman International Industries Inc. |
| FEV GmbH |
| Capgemini Technology Services Limited |
| Others |
Pricing and Supply Chain Analysis
German and Chinese OEM procurement teams dominate contract volume, anchoring pricing power to time-and-material arrangements with gain-share provisions for milestone acceleration rather than fixed-price engineering deliverables.
Pricing Analysis
Warranty and post-delivery validation support are increasingly unbundled from base engineering fees, with OEMs paying separately for extended homologation documentation and regulatory amendment cycles. Project-based pricing with milestone-indexed payments dominates EV platform development, while ISO 26262 ASIL-D certification tier commands substantial premiums over standard validation grades. Cost compression in CAD and basic simulation services is intensifying because OEMs internalize standardized tooling expertise, making Tier-1 suppliers the most price-sensitive buyers and premium OEMs the least.
Supply Chain Analysis
India's PLI scheme local-content mandates and China's MIIT domestic-engineering requirements are reshaping sourcing patterns, forcing ESPs to establish delivery centers within national boundaries. Semiconductor fabrication concentrates in Taiwan and South Korea, with ECU development schedules drawing from these concentrated sources. Battery thermal management systems rest on rare earth supply chains anchored in China and processed materials from South Korea. Single-source vulnerability in automotive-grade chip supply creates systemic schedule risk. Distribution runs through OEM engineering procurement offices co-located with major vehicle development clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
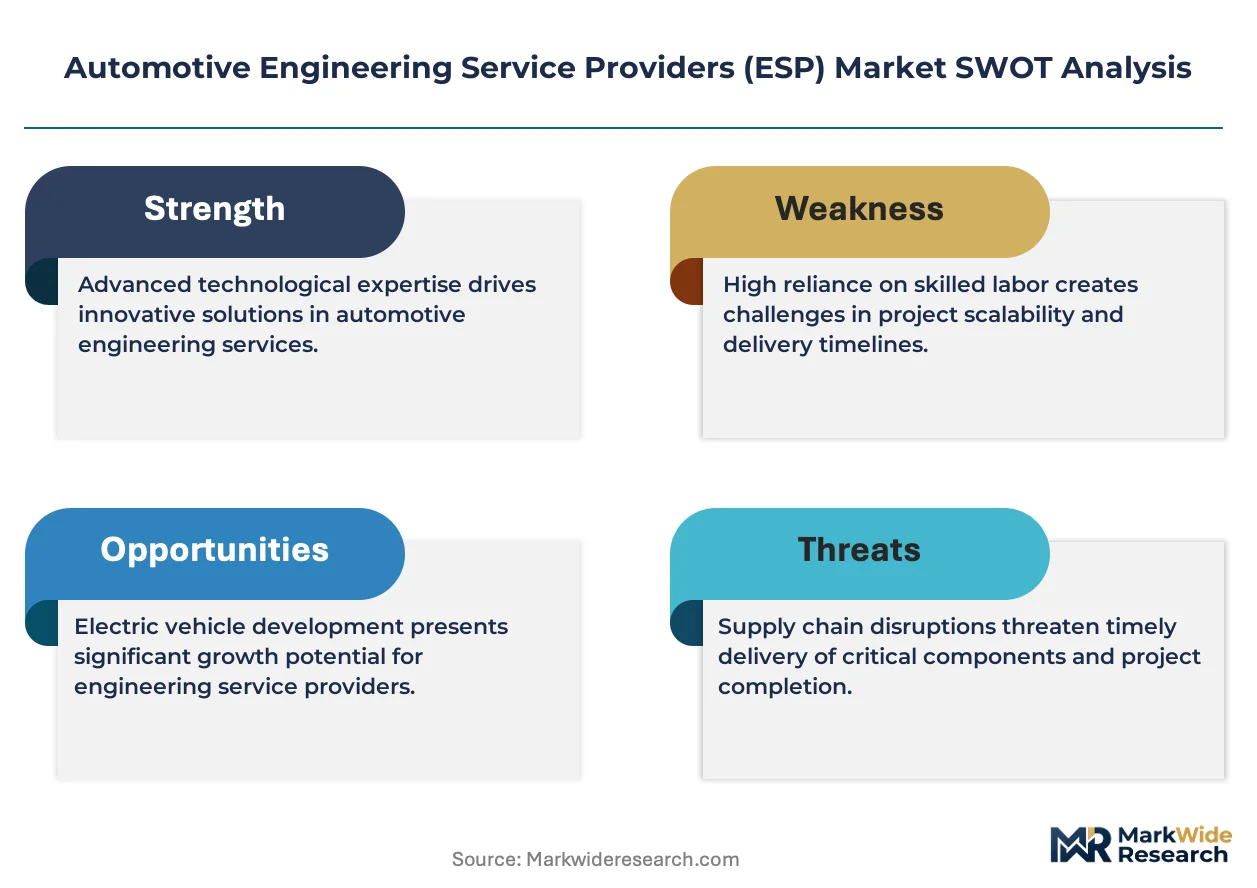
Automotive ESPs operate in a supply-constrained talent market where AUTOSAR Classic and Adaptive stack expertise scarcity props pricing power across embedded systems contracts.
For Market Incumbents: Anchor defensive positioning through backward integration into hardware-in-the-loop validation infrastructure and exclusive AUTOSAR stack licensing partnerships. Consolidate around MBSE tooling expertise as European OEMs mandate SysML-based documentation, excluding generalist competitors from major RFQ processes. Threat from pure-play software houses compressing traditional margins demands preemptive capability depth in continuous integration delivery models.
For New Entrants and Emerging Players: EU AI Act autonomous vehicle provisions in Europe open a window for specialized perception algorithm certification services that incumbent generalists cannot fulfill. Target ADAS validation and machine learning ops tooling as the most penetrable segment, with vehicle-to-grid integration power electronics as secondary white space. Go-to-market leverage centers on regulatory intelligence partnerships with KBA and EMA compliance documentation workflows.
For Investors and Strategic Acquirers: The window for entry favors specialist ESPs with embedded systems depth and established OEM validation relationships over IT services scale players. Long-term viability hinges on software-defined vehicle architecture transition completion, favoring acquisition targets with functional safety certification infrastructure and hardware-software integration heritage. Watch EPA emission standard tightening velocity as the inflection signal for powertrain engineering demand cyclicality.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Continuous integration delivery models displace gated milestone releases for Volkswagen and Ford programs. |
| Battery Supply Agreement | Power electronics engineering contracts lock in with CATL and BYD platform expansion timelines. |
| Platform Standardization | EV skateboard architecture reuse across OEM portfolios concentrates engineering service procurement volume. |
| Geographic Manufacturing Footprint | India PLI scheme compliance requires Pune and Chennai delivery center establishment for cost-optimized programs. |
| Charging Infrastructure Partnership | Bidirectional V2G integration creates new power electronics competency demand that incumbent ESPs lack. |
Research Methodology
Independent corroboration across OEM platform engineering directors, Tier-1 supplier procurement leads, ESP delivery center heads, and automotive regulatory consultants underwrites the qualitative findings. Primary interviews with these stakeholders combined secondary validation from vehicle production databases, IHS Markit registration data, EPA emission certification filings, and EMA type-approval documentation. SEC 10-K disclosures from diversified technology conglomerates and customs records for engineering service trade flows provided additional triangulation. Bottom-up contract value aggregation and top-down market sizing reconstructions were cross-checked for consistency.
Rate-of-change decomposition across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions structured the analytical framework. CAGRs were derived from segment-level engineering intensity coefficients applied to vehicle program volume projections across the analysis window. Powertrain electrification transition velocity, software-defined vehicle adoption curves, and regulatory compliance cycle compression served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for autonomous vehicle perception stack development would alter the outlook. Forecasts reflect assumptions around semiconductor supply normalization, MIIT NEV subsidy continuity, and EU Green Deal enforcement trajectory. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Global Street Sweeper Market
Automotive Services
GCC Car Wash Market
Automotive Services
United States Automotive Service Market
Automotive Services
Mobile Car Wash Service Market
Automotive Services
Vehicle Conversion Market
Automotive Services
Tow Truck Market
Automotive Services
Automotive Performance Tuning and Engine Remapping Services Market
Automotive Services
Car Subscription Market
Automotive Services
Parking Services Market
Automotive Services
Vehicle Analytics Market
Automotive Services
Electric Commercial Vehicle MRO Market
Automotive Services
Europe MRO Distribution Market
Automotive Services
Airbag Repair Service Market
Automotive Services
North America Car Wash Market
Automotive Services
Automotive MRO Market
Automotive Services
ADAS Recalibration Services Market