
 Cloud Identity and Access Management Software Market | 2026-2036
Cloud Identity and Access Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Identity and Access Management Software Market Outlook
Subscription-based identity governance is pivoting from perpetual licensing toward consumption-metered models that bundle continuous compliance monitoring. Microsoft leverages its Azure Active Directory ecosystem to anchor enterprise workloads across hybrid cloud configurations. Okta competes through deep API integrations with thousands of SaaS applications, while CyberArk specializes in privileged access management for critical infrastructure sectors.
Cloud Identity and Access Management Software constitutes a centralized platform for authenticating users, authorizing resource access, and auditing identity lifecycle events across distributed IT environments, typically operating through SAML 2.0 and OIDC protocols with session timeout thresholds under 24 hours. Its primary purpose is to enforce least-privilege principles while reducing credential-based attack surfaces. Public cloud deployments capture the dominant share of new implementations, though hybrid cloud configurations are expanding fastest as regulated industries maintain sensitive workloads on-premises. Multi-factor authentication services sit at the core of most procurement decisions, while identity governance modules command premium pricing due to automated compliance reporting capabilities.
GDPR data-subject access requirements and the EU AI Act's risk-classification framework are reshaping how European enterprises provision identity verification workflows. In the United States, NIST 800-207 zero-trust guidelines and SEC cybersecurity disclosure rules are mandating granular access logging and identity segmentation. Stakeholders must evaluate whether their current IAM architectures can absorb forthcoming quantum-resistant authentication standards without complete infrastructure replacement.
Market Dynamics
Zero-trust architecture mandates are forcing wholesale replacement of perimeter-based security models, compressing procurement cycles as enterprises rip out legacy VPN and firewall-based access controls before contract expiration.
Growth Catalysts
- Federal cloud migration directives:US government agencies must modernize identity infrastructure under executive orders, creating immediate demand for FedRAMP-authorized platforms.
- SEC cybersecurity disclosure rules:Public companies now face liability for inadequate access logging, accelerating board-level IAM investment approvals.
- Quantum-resistant authentication standards:NIST's post-quantum cryptography guidelines are triggering early-phase infrastructure upgrades among defense contractors and financial institutions.
Market Restraints
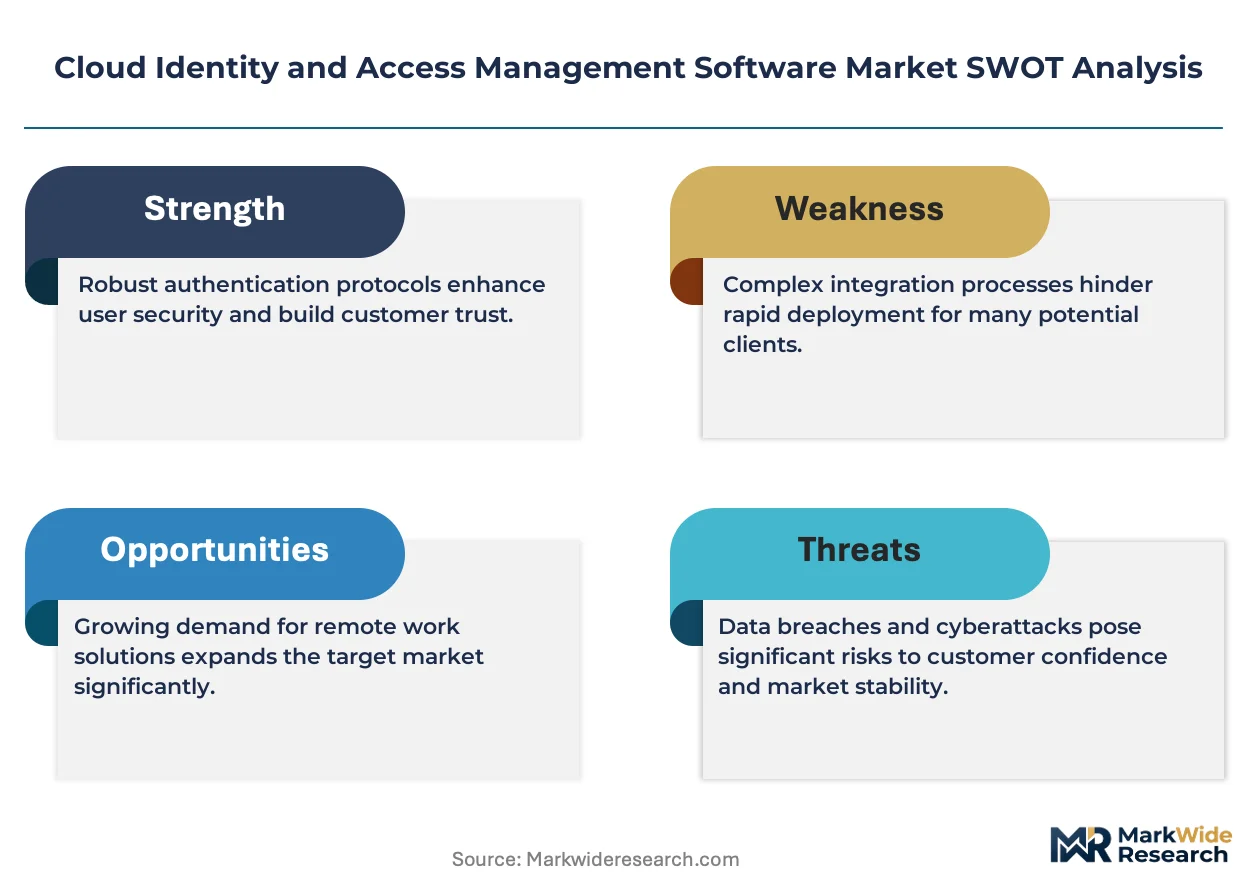
- Skilled identity architect shortage:Deployment complexity outpaces available talent pools, extending implementation timelines and inflating professional services costs.
- Certificate authority concentration:Dependence on a narrow set of root certificate providers creates systemic vulnerability to supply chain compromise.
- Biometric template storage regulations:GDPR and state-level biometric privacy laws impose strict data residency requirements that fragment cloud deployment options.
Strategic Opportunities
- Machine identity explosion:Service mesh architectures and Kubernetes workloads multiply non-human identities, expanding addressable scope beyond human user management.
- Decentralized identity frameworks:W3C verifiable credentials standards enable passwordless customer onboarding for retail banks and healthcare providers.
- Continuous authorization engines:Real-time risk scoring integrated with SIEM platforms opens premium pricing tiers for high-assurance environments.
Industry Challenges
- Legacy directory service entanglement:Decades-old Active Directory forests resist clean migration, forcing expensive coexistence architectures during transition periods.
- Cross-cloud policy harmonization:Inconsistent IAM APIs across AWS, Azure, and GCP require custom abstraction layers that degrade performance and audit reliability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Identity and Access Management Software Market |
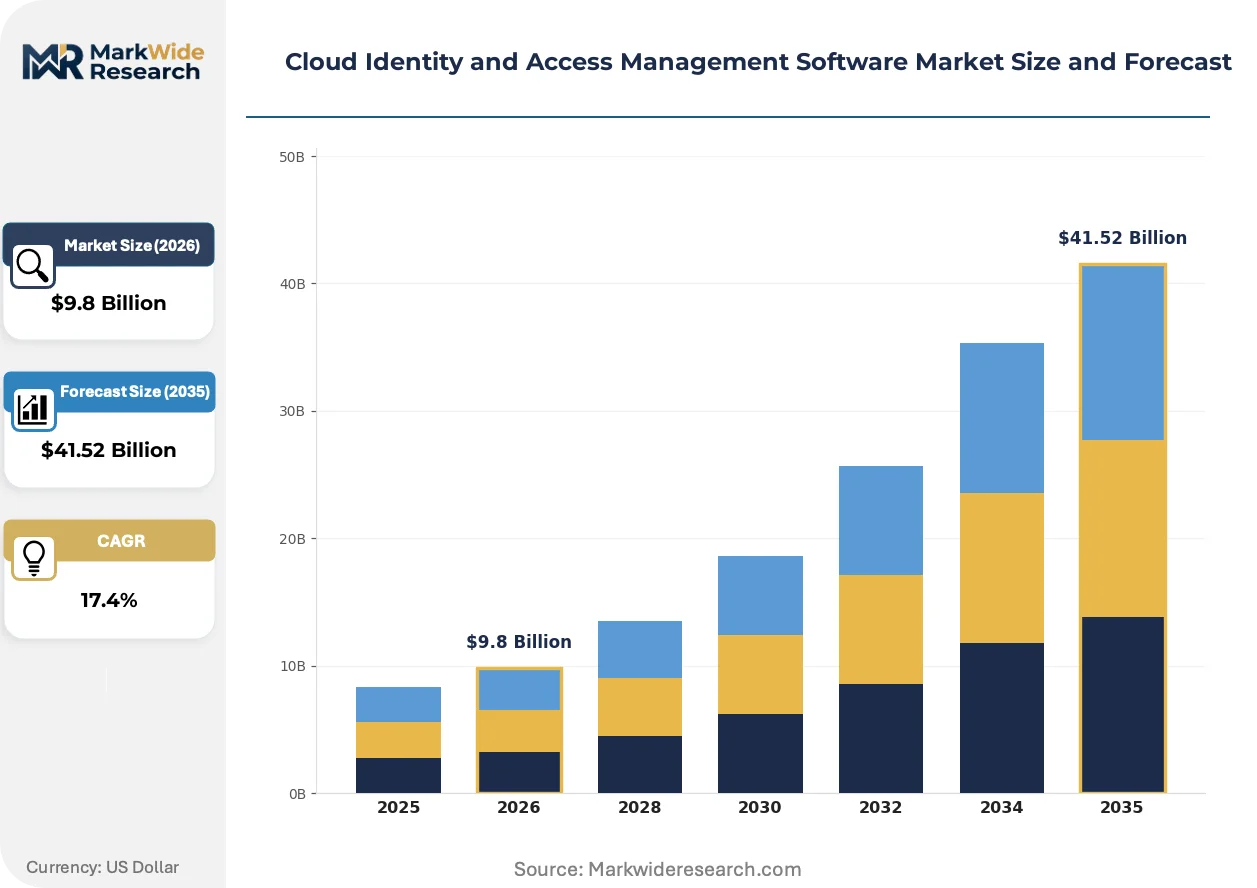
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $41.52 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Single Sign-On, Multi-Factor Authentication, Identity Governance, Privileged Access Management End User: Enterprises, Government, Education, Healthcare Integration Level: On-Premises, Cloud-Based, Federated, Managed |
| Companies Covered | Microsoft, Okta, IBM, Oracle, Ping Identity, SailPoint, CyberArk, ForgeRock, Broadcom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Identity and Access Management Software Market Strategic Shifts
Passwordless authentication methods are displacing credential-based workflows across regulated industries, while continuous compliance monitoring is absorbing budget previously allocated to point-in-time audits.
Passkey implementations built on FIDO2 standards are absorbing authentication volume previously handled by SMS one-time codes and hardware tokens. Financial services firms in Singapore and Germany are deploying passkeys for retail banking apps, cutting phishing success rates. The technology is absorbing market share from legacy MFA providers by eliminating shared secrets entirely.
EU AI Act risk-classification requirements are mandating human-in-the-loop identity verification for high-risk automated decision systems. Financial institutions deploying AI-driven credit scoring must implement explainable access logs. The requirement is forcing upgrades to identity governance platforms that can produce audit trails linking algorithmic outputs to specific user permissions.
Consumption-metered licensing is displacing perpetual seat-based contracts as the dominant procurement model. Enterprise buyers in healthcare and manufacturing now demand usage-based billing tied to monthly active identities. This shift is most pronounced in US federal contracting, where GSA schedule holders must demonstrate cost-per-authentication metrics.
Cloud Identity and Access Management Software Market Segmentation
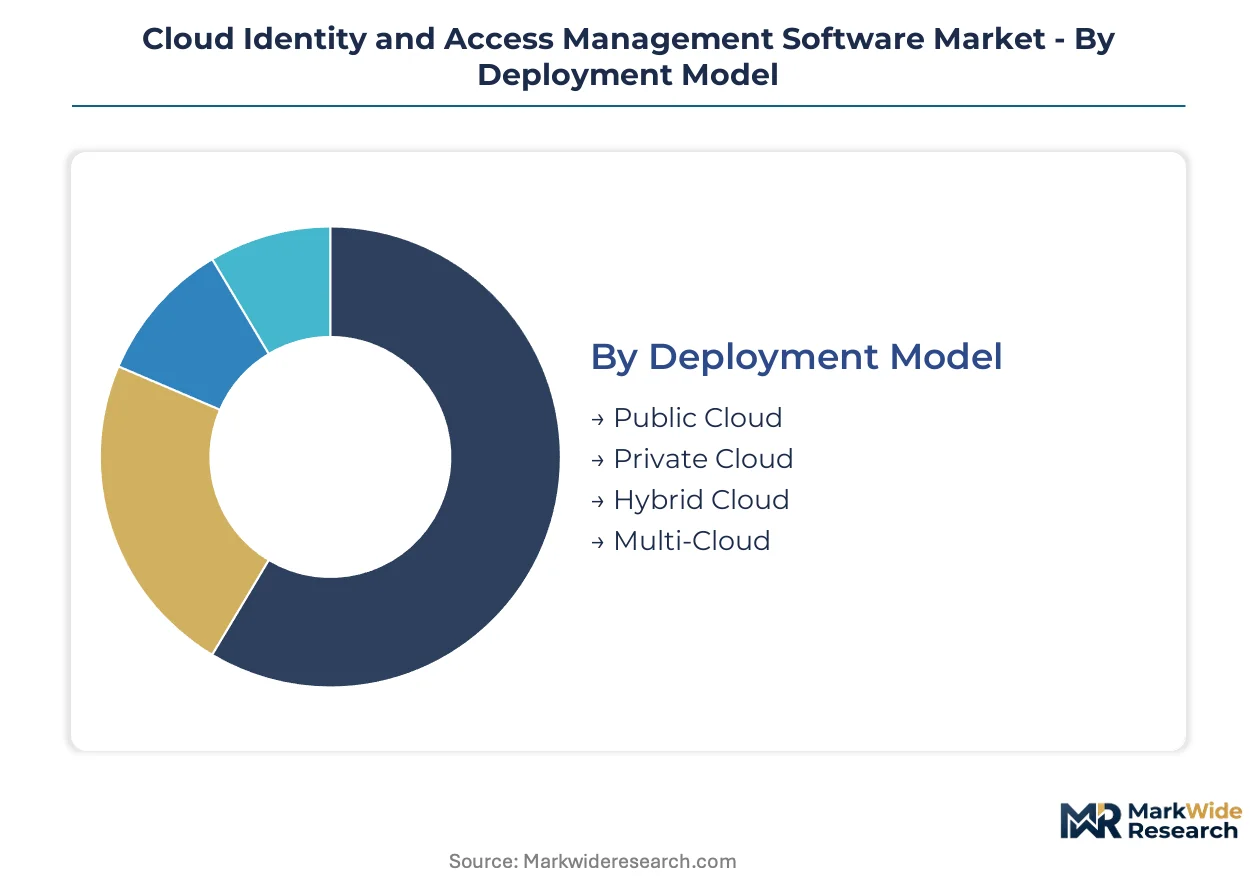
Cloud IAM procurement decisions hinge on how organizations balance legacy infrastructure against zero-trust mandates. Deployment architecture, service composition, and integration depth determine whether enterprises achieve FedRAMP authorization or face compliance gaps.
Deployment Model:
Replacement cycles for perimeter-based VPNs are compressing procurement timelines as security teams rip out legacy access controls before contract expiration.
- Public Cloud:Native IAM services from hyperscalers handle authentication through centralized control planes with automatic scaling. Financial services firms in Singapore and Germany are migrating retail banking workloads to public cloud IAM to cut capital expenditure on hardware security modules.
- Hybrid Cloud:Split architectures maintain sensitive identity stores on-premises while extending authentication to cloud workloads through secure federation protocols. Regulated healthcare providers in the United States deploy hybrid configurations to keep patient biometric templates within HIPAA-compliant data centers while enabling SaaS access.
- Private Cloud:Dedicated identity infrastructure serves defense contractors and intelligence agencies with air-gapped certificate authorities.
- Multi-Cloud:Abstraction layers normalize inconsistent IAM APIs across AWS, Azure, and GCP deployments.
Public Cloud sits at the top of the volume ranking, with Hybrid Cloud climbing the fastest.
Service Type:
Cost tier differentiation separates commodity authentication from premium governance modules that command annual recurring revenue multiples.
- Multi-Factor Authentication:FIDO2 passkey implementations are displacing SMS one-time codes through cryptographic key pairs bound to device hardware. German retail banks report phishing resistance improvements after eliminating shared secrets from customer authentication flows.
- Privileged Access Management:Vaulting solutions for service accounts and administrative credentials protect trading platforms and critical infrastructure. United States financial regulators now mandate session recording for privileged access to customer data repositories.
- Single Sign-On:SAML 2.0 and OIDC protocols consolidate application access behind unified identity providers.
- Identity Governance:Automated access certification campaigns and role mining engines reduce manual compliance overhead.
Multi-Factor Authentication dominates current procurement volumes, while Identity Governance expands most quickly as EU AI Act audit requirements take effect.
End User:
Application-specific compliance burdens reshape how identity vendors configure audit trails and data residency controls.
- Enterprises:Large organizations deploy comprehensive IAM suites spanning workforce and customer identity use cases with custom integration layers for ERP systems. Manufacturing conglomerates in Japan are consolidating fragmented Active Directory forests into cloud-native directories to reduce operational complexity.
- Government:Federal agencies require FedRAMP-authorized platforms with continuous monitoring and incident response integration. Executive orders in the United States mandate modernized identity infrastructure for civilian agencies.
- Healthcare:Patient portal authentication must satisfy HIPAA minimum necessary standards while enabling seamless caregiver access.
- Education:Campus-wide single sign-on serves distributed student populations with seasonal enrollment spikes.
Enterprises account for the largest installed base, with Government segment procurement accelerating under federal modernization directives.
Integration Level:
Customer maturity determines whether organizations adopt managed services or build internal identity architecture expertise.
- Cloud-Based:API-first integration patterns connect SaaS applications through standardized OIDC and SCIM protocols without on-premises infrastructure. Mid-market technology firms in India prefer cloud-based deployment to avoid capital expenditure on identity hardware.
- Federated:Cross-organizational trust frameworks enable business partner access without duplicate identity stores. European automotive supply chains deploy federation to grant tier-one suppliers controlled access to engineering documentation systems.
- On-Premises:Legacy directory services persist in regulated environments with strict data sovereignty requirements.
- Managed:Outsourced identity operations offload certificate lifecycle management and access certification to specialized providers.
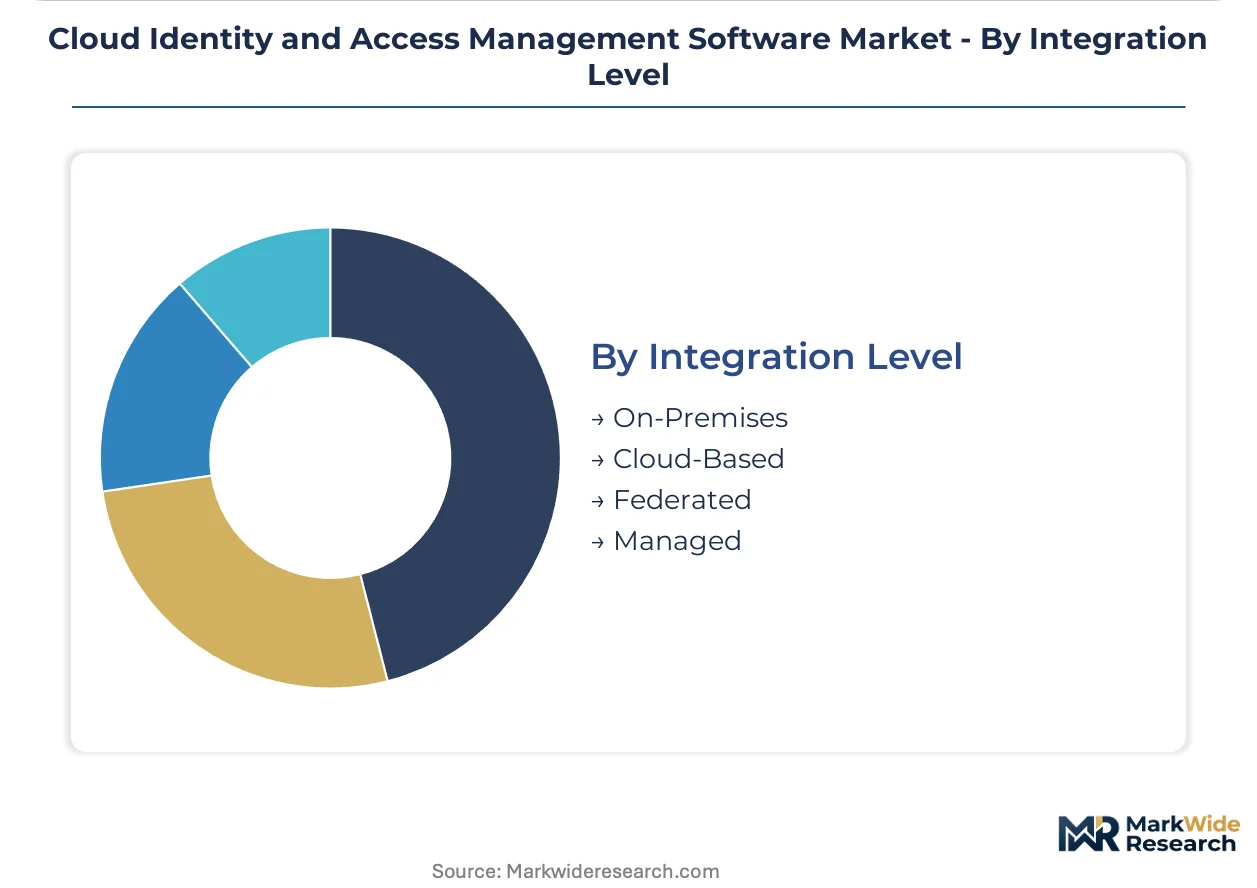
Cloud-Based integration captures the highest deployment count, with Federated architectures gaining share fastest among multi-enterprise collaboration scenarios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling IAM procurement toward jurisdictions with clearer compliance frameworks and stronger enforcement mechanisms, creating divergent growth trajectories across national markets.
United States
Federal cloud migration directives and SEC cybersecurity disclosure rules are compressing procurement cycles for civilian agencies and public companies. NIST zero-trust mandates require granular access logging and identity segmentation. The Washington D.C. metropolitan corridor hosts dense concentrations of FedRAMP-authorized platform deployments serving defense and intelligence contractors.
Germany
Industrial conglomerates in automotive and precision manufacturing are replacing legacy perimeter security with hybrid cloud IAM configurations. The EU AI Act's risk-classification framework mandates explainable access logs for automated decision systems. Frankfurt's financial district leads retail banking passkey implementations, cutting phishing incidents through FIDO2 cryptographic standards.
Singapore
Financial services regulators are mandating privileged access management for trading platforms and customer data repositories. The Monetary Authority of Singapore's technology risk management guidelines accelerate replacement of hardware security modules with cloud-native alternatives. The Marina Bay financial cluster hosts regional headquarters deploying consumption-metered identity governance for Southeast Asian operations.
Japan
Manufacturing conglomerates are consolidating fragmented Active Directory forests into unified cloud-native directories to reduce operational complexity. METI cybersecurity guidelines push zero-trust adoption across critical infrastructure sectors. The Tokyo-Osaka industrial corridor concentrates demand for machine identity management serving service mesh and Kubernetes workloads.
United Kingdom
Financial services firms in the City of London are upgrading identity governance platforms to satisfy GDPR data-subject access requirements and forthcoming quantum-resistant authentication standards. The Financial Conduct Authority's operational resilience rules mandate continuous compliance monitoring. Manchester's technology corridor hosts emerging deployments of decentralized identity frameworks for cross-border supply chain authentication.
Cloud Identity and Access Management Software Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with hyperscale cloud providers capturing volume through native integration while independent vendors defend margin through vertical specialization. The vendor base organizes into three tiers: platform conglomerates with directory services ecosystems, API-first specialists with deep SaaS connectivity, and privileged access guardians serving regulated infrastructure. Consolidation pressures intensify as zero-trust mandates compress replacement cycles, forcing mid-tier players toward strategic partnerships or niche retreat.
Within the platform conglomerate tier, Microsoft anchors enterprise workloads through Azure Active Directory integration across hybrid configurations. Okta occupies a position exemplifying API-first connectivity with thousands of SaaS application integrations. CyberArk represents the privileged access specialization vector, defending critical infrastructure sectors with vaulting solutions for administrative credentials. These three archetypes capture divergent procurement budgets: platform ecosystems absorb infrastructure consolidation spending, connectivity specialists capture SaaS-native enterprises, and infrastructure guardians secure regulated industry premiums.
| Leading Market Players |
|---|
| Microsoft |
| Okta |
| IBM |
| Oracle |
| Ping Identity |
| SailPoint |
| CyberArk |
| ForgeRock |
| Broadcom |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up identity governance specialists have consolidated fragmented compliance-tool vendors across the United States and Europe, tightening pricing discipline while compressing professional services margins through standardized implementation playbooks. This ownership pattern concentrates supply-side negotiation leverage with three platform conglomerates, forcing mid-tier buyers into consumption-metered contracts that bundle continuous monitoring at premium annual rates.
Pricing Analysis
Capacity additions in India and Poland are reshaping price floors for implementation services, even as license fees hold firm. Three-tier pricing structure across premium identity governance, standard multi-factor authentication, and economy single sign-on tiers separates FedRAMP-authorized platforms from commodity alternatives. Price differentiation rests on certification level and geographic data residency compliance. Cost compression in the mid-market tier is intensifying because hyperscalers bundle native IAM with cloud compute commitments. Healthcare providers in the United States exhibit highest price sensitivity due to constrained IT capital budgets, while defense contractors demonstrate lowest sensitivity given mission-critical security mandates.
Supply Chain Analysis
Single-source vulnerability sits with root certificate authorities concentrated in the United States and Germany, where narrow provider sets create systemic exposure to supply chain compromise. Hardware security module manufacturing draws from Taiwan, South Korea, and Japan for cryptographic chip fabrication. Software development centers in India, Ireland, and Israel feed engineering talent into platform R&D pipelines. Tariff exposure runs through semiconductor components essential for FIDO2 security keys. Distribution runs through direct enterprise sales teams supplemented by systems integrator partnerships for complex hybrid deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud IAM constitutes a late-cycle quality story as zero-trust mandates force replacement of perimeter-based infrastructure regardless of economic conditions. Procurement committees now prioritize FedRAMP authorization and quantum-resistant algorithm readiness over cost minimization.
For Market Incumbents: Deepen vertical specialization in regulated healthcare and defense sectors where compliance premiums sustain margin structures. Fortify API abstraction layers against hyperscaler bundling threats by pre-integrating with niche SaaS applications outside native cloud marketplaces. Invest in continuous authorization engines that command pricing multiples above commodity authentication tiers.
For New Entrants and Emerging Players: Launch via managed identity services targeting mid-market manufacturers in Japan and Germany lacking internal architect talent. Machine identity management for Kubernetes workloads represents the most penetrable white space, with service mesh architectures multiplying non-human identities faster than incumbent platforms adapt. Position around decentralized identity frameworks using W3C verifiable credentials standards for passwordless customer onboarding in retail banking.
For Investors and Strategic Acquirers: Platform conglomerates with existing directory services ecosystems are the most active acquirers in this space, seeking API-first specialists to fill SaaS connectivity gaps. Long-term viability favors vendors with FedRAMP authorization and established machine identity capabilities rather than point-solution authentication providers. The signal to watch is NIST post-quantum cryptography standard finalization, which will trigger replacement cycles among financial institutions and defense contractors.
| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Pursuit | Unlocks federal agency procurement under executive order mandates. |
| Platform Integration Partnership | Embed identity services within Microsoft Azure and AWS marketplaces. |
| Machine Identity Capability Buildout | Capture service mesh and Kubernetes workload authentication growth. |
| Quantum-Resistant Algorithm Development | Position for NIST post-quantum standard compliance requirements. |
| Geographic Expansion to Singapore | Access MAS-regulated financial services demand in Southeast Asia. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CISOs, identity architects, federal procurement officers, and systems integration specialists with secondary validation against SEC cybersecurity disclosure filings, FedRAMP authorization databases, NIST guideline publications, and hyperscaler capex disclosures. Bottom-up segment sizing triangulated against top-down market envelope estimates derived from vendor revenue disclosures and federal IT budget allocations.
Segment-weighting across deployment models, service types, end-user industries, and integration complexity tiers anchored the analytical framework throughout the projection horizon. CAGRs were derived from elasticity modeling against identity workload growth rates and compliance mandate implementation timelines. Quantum-resistant authentication readiness and EU AI Act audit requirement phasing served as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated quantum computing breakthroughs or federal budget sequestration scenarios. Forecasts reflect documented assumptions about zero-trust mandate enforcement consistency and skilled architect availability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Global Hardware Security Modules (HSM) Market
Security Software
Employee Fraud Detection Market
Security Software
Global Data Masking Market
Security Software
SSL Inspection Solution Market
Security Software
Security Information and Event Management Software Market
Security Software
Italy Endpoint Detection and Response Market
Security Software
Digital Risk Protection Software Market
Security Software
Public Key Infrastructure (PKI) Market
Security Software
Key Management Service Market
Security Software
Identity-As-A-Service (Idaas) Market
Security Software
Global Data Loss Prevention Software Market
Security Software
US and Latin America Identity and Access Management (IAM) Market
Security Software
Global Runtime Application Self-Protection Market
Security Software
Battery-Powered Doorbell Camera Market
Security Software
Asia-Pacific Encryption Software Market
Security Software
Encryption As A Service Market