
 Network Diagnostic Tools Market | 2026-2036
Network Diagnostic Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Network Diagnostic Tools Market Foresight
Software-defined analytics is broadening the functional boundary of traditional hardware-centric network diagnostic platforms. SolarWinds leverages cloud-native architectures to extend its reach among mid-market enterprises seeking hybrid visibility. Cisco Systems anchors its position through deep integration with switching and routing infrastructure, creating captive demand for its protocol analysis stack. NETSCOUT competes on high-throughput packet inspection capabilities designed for carrier-grade telecommunications environments.
Network diagnostic tools encompass software and hardware solutions that capture, decode, and analyze traffic patterns across wired and wireless infrastructure, typically processing packets at speeds from 1 Gbps to 400 Gbps while supporting protocols including TCP/IP, HTTP/2, and QUIC. Their primary purpose is to isolate latency sources, detect anomalous behavior, and ensure service-level agreement compliance in complex distributed architectures. Performance Monitors currently occupy the largest margin pool as enterprises prioritize uptime guarantees over forensic depth. Cloud-Based deployments represent the fastest-expanding technology segment as organizations migrate visibility stacks away from capital-intensive on-premises appliances.
The FCC mandates network reliability reporting for critical communications infrastructure, directly shaping procurement specifications for outage-detection capabilities. ISO 27001 and the EU AI Act create parallel compliance obligations for diagnostic data handling and automated anomaly detection algorithms across transatlantic deployments. Stakeholders must weigh interoperability investments against the risk of fragmented standards as regional regulatory frameworks diverge on data sovereignty and algorithmic transparency requirements.
Market Dynamics
The transition from hardware-bound appliances to software-defined visibility stacks is restructuring procurement economics and vendor competitive boundaries across network infrastructure management.
Growth Catalysts
- 5G infrastructure scaling:Telecommunications providers in Germany and the United States are deploying real-time analyzers to manage protocol complexity at the network edge. Carrier-grade throughput requirements are expanding addressable hardware and software segments simultaneously.
- FCC reliability mandates:Updated outage-detection reporting requirements for critical communications infrastructure are compressing replacement cycles for legacy monitoring systems. Compliance-oriented specifications now dominate RFP language for public safety networks.
- Industry 4.0 protocol visibility:German manufacturing automation standards require continuous packet-level inspection across industrial Ethernet and Time-Sensitive Networking deployments. Factory floor digitization is creating captive demand for diagnostic integration with operational technology stacks.
Market Restraints
- Specialized engineering talent scarcity:Packet-level analysis expertise concentrates among semiconductor and telecommunications veterans. Compensation inflation for QUIC and HTTP/2 protocol specialists is elevating R&D costs beyond mid-market vendor reach.
- 400 Gbps hardware refresh cycles:Capital-intensive appliance upgrades strain enterprise budgets as port speeds accelerate. The transition from 100 Gbps to 400 Gbps capture cards requires wholesale chassis replacement rather than modular expansion.
- EU AI Act algorithmic transparency requirements:Automated anomaly detection systems face documentation burdens for training data provenance and decision explainability. Compliance friction is delaying deployment of machine-learning-based root-cause analysis in European deployments.
Strategic Opportunities
- Cloud-native visibility migration:Organizations are shifting from capital-intensive on-premises appliances to subscription-based SaaS analytics. This transition opens recurring revenue models for vendors with Kubernetes-native architectures.
- India industrial automation acceleration:PLI scheme incentives for electronics manufacturing are expanding factory network complexity. Domestic protocol analysis demand is outpacing local vendor capability, creating import substitution potential.
- ISO 27001 diagnostic data handling certification:Security-conscious enterprises are prioritizing vendors with certified data governance frameworks. Compliance differentiation is becoming a procurement gate in financial services and healthcare verticals.
Industry Challenges
- Multi-vendor integration complexity:Enterprises operate hybrid stacks spanning Cisco switching, cloud-native observability, and legacy SNMP monitoring. Correlating events across incompatible data models demands expensive professional services engagement.
- Encrypted traffic blind spots:TLS 1.3 and QUIC adoption is rendering deep packet inspection ineffective without certificate management infrastructure. Key escrow and decryption architecture adds operational overhead that conflicts with zero-trust security postures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Diagnostic Tools Market |
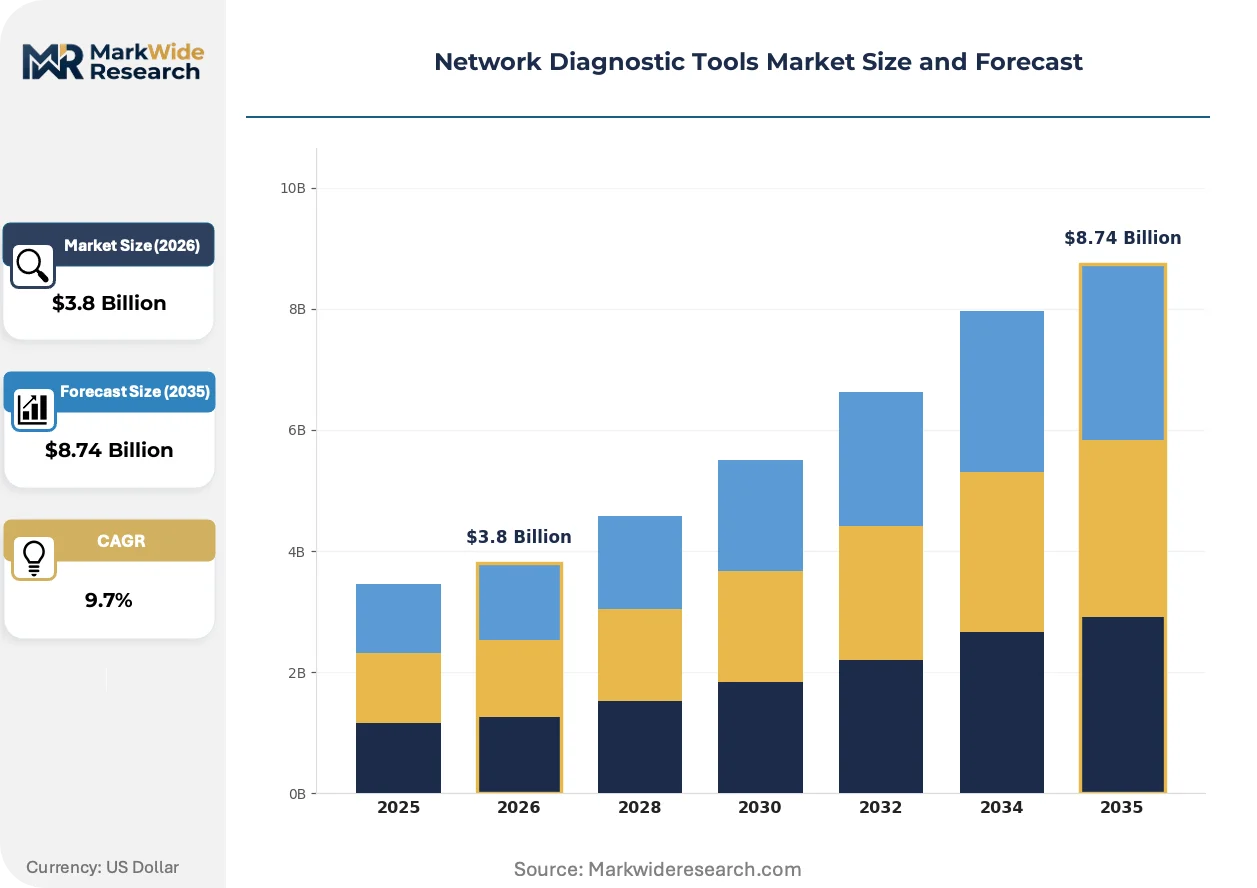
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Network Analyzers, Protocol Analyzers, Packet Sniffers, Performance Monitors Technology: Cloud-Based, On-Premises, Hybrid, Software-as-a-Service End User: IT Departments, Telecommunications, Managed Service Providers, Enterprises Application: Network Security, Performance Monitoring, Troubleshooting, Compliance |
| Companies Covered | SolarWinds, Cisco Systems, NETSCOUT, ManageEngine, Broadcom, IBM, Microsoft, Dynatrace, Paessler PRTG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Diagnostic Tools Market Shifts & Advancements
Software-defined architectures are dissolving the boundary between network performance monitoring and full-stack observability, forcing hardware-centric vendors to restructure product roadmaps and partnership strategies.
AI-driven root-cause analysis is rewriting how operations teams interpret packet capture data. Machine-learning models trained on labeled network events now correlate latency spikes with application-layer behavior in milliseconds. Large enterprises with dedicated SRE teams are piloting these systems in production environments. The technology is compressing mean-time-to-resolution metrics that previously justified premium appliance pricing.
The EU AI Act's risk classification framework for automated decision systems is reshaping vendor development priorities. Diagnostic platforms with embedded anomaly detection must now document training data sources and algorithmic logic for audit trails. European telecommunications carriers are demanding compliance attestations before procurement approval. This regulatory friction is favoring established vendors with dedicated compliance engineering resources over emerging competitors.
Enterprise buyers are unbundling after-sales support from perpetual license agreements and negotiating consumption-based service tiers instead. Traditional appliance vendors with fixed maintenance contracts face margin pressure as customers prefer pay-per-incident remote diagnostics. This behavioral shift is most visible among mid-market enterprises in the United States seeking to align vendor costs with actual troubleshooting frequency. Channel partners are responding by developing managed detection and response offerings that wrap third-party tools with labor arbitrage.
Network Diagnostic Tools Market Segmentation
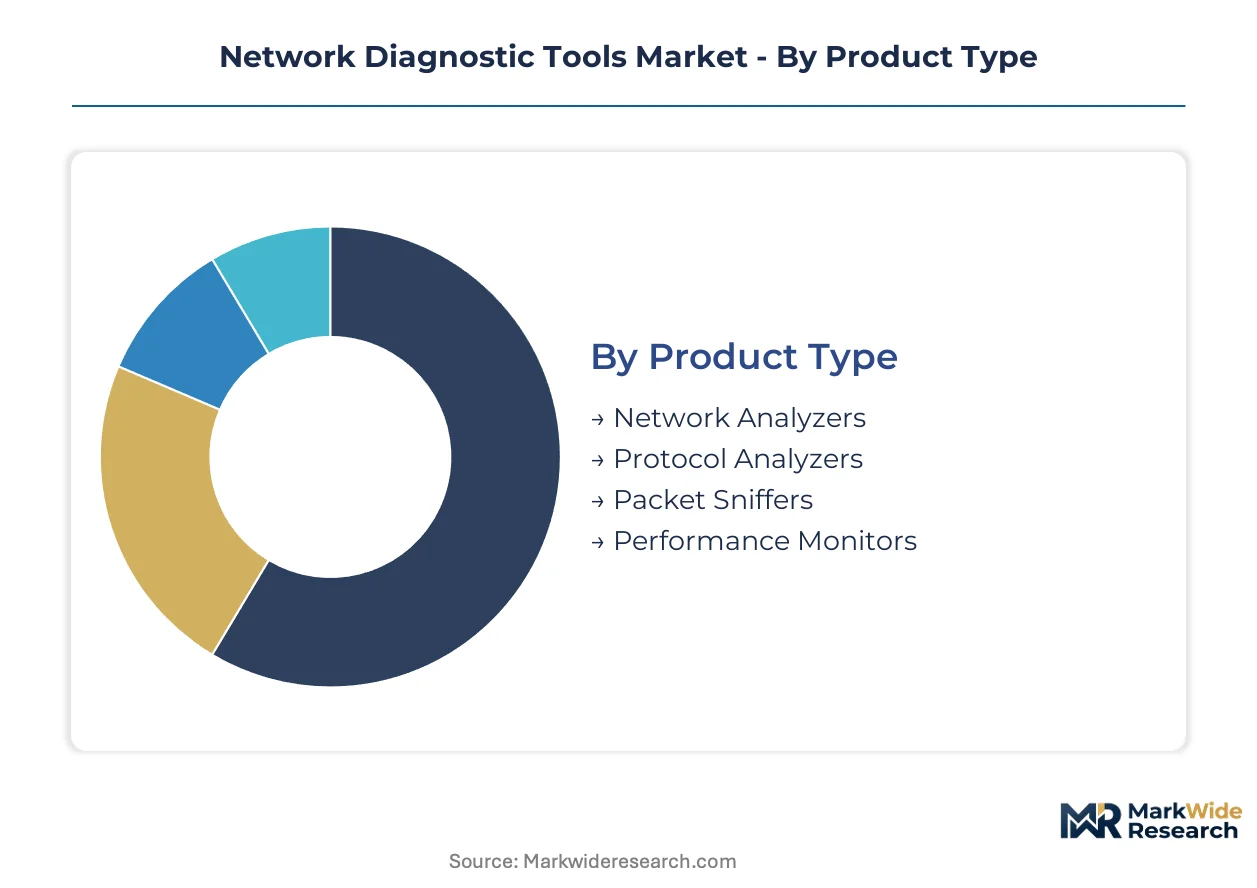
Network diagnostic tools fragment across four distinct dimensions, each reflecting divergent buyer priorities around capital deployment, operational control, and compliance posture. Procurement patterns vary sharply between telecommunications carriers seeking carrier-grade throughput and mid-market enterprises favoring subscription economics.
Product Type:
Buyers in this category differentiate primarily by the depth of forensic insight required versus operational simplicity desired.
- Network Analyzers:Hardware-intensive platforms capture full-duplex traffic at 100 Gbps to 400 Gbps line rates, deploying FPGA-based processing engines for real-time protocol decoding. Telecommunications providers in Germany and the United States anchor demand as 5G infrastructure mandates edge-level visibility. FCC reliability reporting requirements are accelerating replacement cycles for legacy analyzer fleets.
- Performance Monitors:Synthetic testing agents and passive flow collectors prioritize uptime metrics over packet-level reconstruction, integrating directly with IT service management workflows. Enterprises with aggressive SLA obligations concentrate procurement here, particularly in financial services verticals where transaction latency directly impacts revenue. The segment commands the largest margin pool as buyers prioritize guaranteed availability over diagnostic depth.
- Protocol Analyzers:Specialized decoders for industrial Ethernet, Time-Sensitive Networking, and automotive CAN bus formats serve manufacturing automation deployments.
- Packet Sniffers:Lightweight software tools for ad-hoc troubleshooting occupy the entry price tier, favored by small IT teams without dedicated network operations centers.
Performance Monitors lead volumes today; Network Analyzers are gaining share fastest among telecommunications infrastructure investments.
Technology:
Deployment architecture selection hinges on whether buyers retain capital expenditure approval authority or operate under operating expenditure mandates.
- Cloud-Based:Kubernetes-native visibility stacks ingest telemetry from distributed cloud workloads and SaaS applications, eliminating appliance refresh cycles. Mid-market enterprises in the United States are migrating fastest, driven by zero-trust security architectures that resist on-premises data concentration. Subscription pricing aligns vendor costs with actual troubleshooting frequency rather than perpetual license amortization.
- Software-as-a-Service:Fully managed analytics platforms abstract infrastructure management entirely, appealing to organizations without dedicated site reliability engineering teams. Managed Service Providers bundle these offerings into multi-tenant service delivery, creating recurring revenue dependencies for diagnostic vendors. The EU AI Act's algorithmic transparency requirements are delaying European deployments of machine-learning-powered SaaS analytics.
- On-Premises:Air-gapped appliance deployments persist in defense, critical infrastructure, and jurisdictions with strict data sovereignty laws.
- Hybrid:Split architectures process sensitive metadata locally while streaming anonymized telemetry to cloud analytics engines, balancing compliance with scalability.
On-Premises retains the largest installed base; Cloud-Based deployments are expanding most quickly as Kubernetes adoption accelerates.
End User:
Organizational scale and network complexity determine whether buyers prioritize integrated vendor stacks or best-of-breed toolchains.
- Telecommunications:Carrier-grade throughput requirements and regulatory outage reporting obligations dominate procurement specifications. German network operators invest heavily under Industry 4.0 convergence pressures, while US providers respond to FCC mandate timelines. These buyers demand 400 Gbps capture capabilities and embedded AI-driven root-cause analysis.
- IT Departments:Enterprise technology teams balance tool consolidation against shadow IT proliferation, favoring platforms with broad protocol coverage and ITSM integration. ISO 27001 certification increasingly gates vendor selection in healthcare and financial services verticals. Skills scarcity for QUIC and HTTP/2 protocol analysis is elevating managed service preferences.
- Enterprises:Line-of-business technology buyers outside formal IT organizations drive shadow procurement of lightweight diagnostic tools.
- Managed Service Providers:Multi-tenant delivery requirements favor API-first platforms with granular tenant isolation and usage-based metering.
IT Departments anchor current revenue; Telecommunications is climbing the fastest as 5G capital cycles intensify.
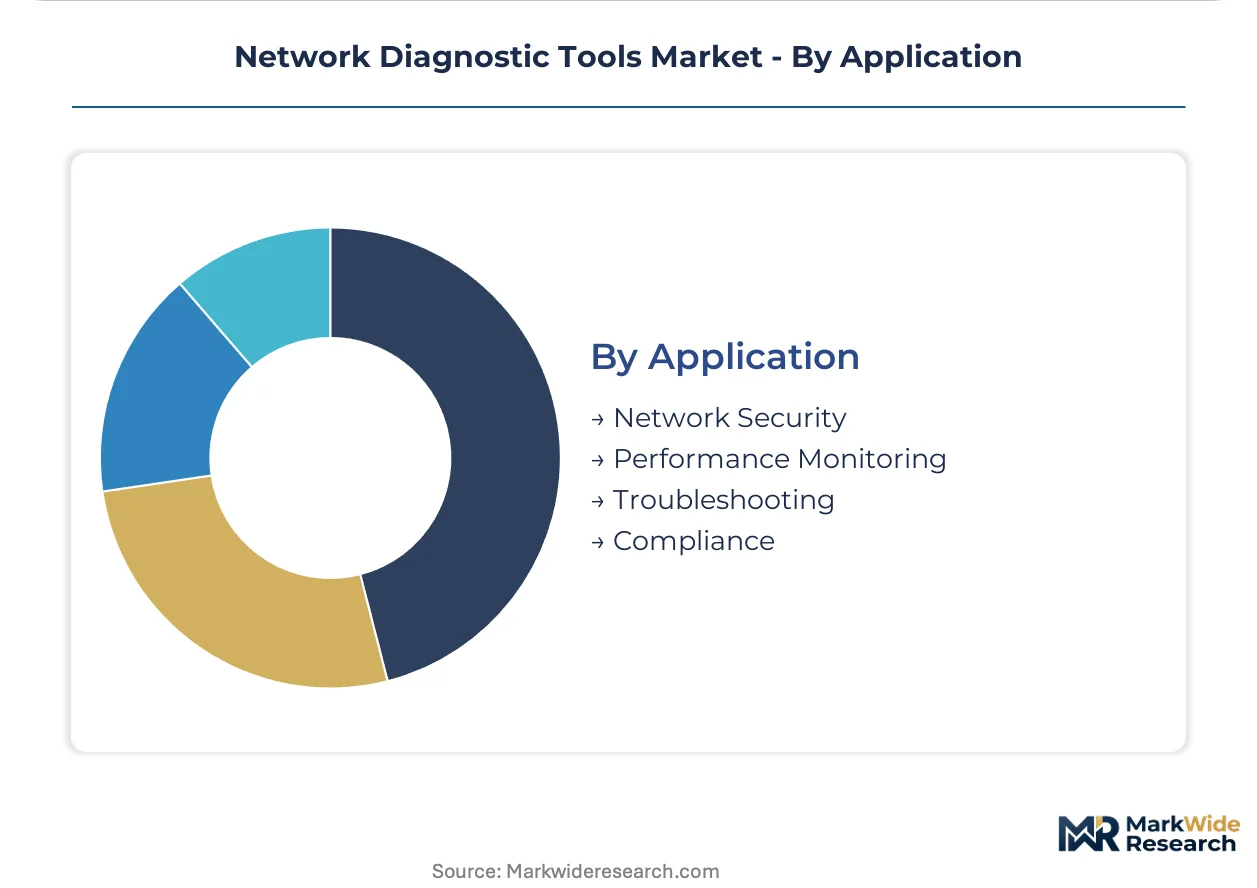
Application:
Use case prioritization reflects whether buyers face external compliance pressure or internal operational efficiency targets.
- Performance Monitoring:Synthetic transaction testing and passive flow analysis dominate enterprise spending, directly supporting revenue-impacting uptime guarantees. Financial services and e-commerce platforms concentrate investment here, correlating network metrics with application response times. The segment benefits from compressed mean-time-to-resolution expectations that justify premium platform pricing.
- Compliance:Regulatory data retention, audit trail generation, and algorithmic transparency documentation create specialized procurement requirements. EU AI Act risk classification frameworks for automated anomaly detection are reshaping European vendor selection criteria. ISO 27001 diagnostic data handling certification is becoming a procurement gate in transatlantic deployments.
- Network Security:Threat detection and encrypted traffic analysis applications compete with dedicated security operations platforms for budget allocation.
- Troubleshooting:Reactive diagnostic workflows occupy the smallest commercial footprint as buyers shift toward predictive and automated remediation.
Performance Monitoring commands the largest revenue share; Compliance is gaining share fastest as regulatory frameworks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial automation clusters anchor procurement intensity for protocol-level diagnostic systems, with FCC mandates in the United States and PLI scheme acceleration in India creating parallel demand vectors across three continents.
United States
Telecommunications providers deploy real-time analyzers at 5G network edges to manage protocol complexity under carrier-grade throughput requirements. FCC reliability mandates compress replacement cycles for legacy monitoring systems in public safety networks. Dallas-Fort Worth and Seattle tech corridors concentrate procurement for hybrid cloud-native visibility stacks among mid-market enterprises.
Germany
Manufacturing automation standards under Industry 4.0 require continuous packet-level inspection across industrial Ethernet deployments. EU AI Act algorithmic transparency requirements reshape vendor selection criteria for automated anomaly detection systems. Munich and Stuttgart industrial clusters drive captive demand for diagnostic integration with operational technology stacks.
India
PLI scheme incentives for electronics manufacturing expand factory network complexity beyond local protocol analysis capabilities. TRAI guidelines for telecommunications infrastructure reliability create compliance pressure for outage-detection procurement. Bangalore and Hyderabad technology corridors concentrate demand for cloud-based visibility migration among SaaS-native enterprises.
United Kingdom
Financial services verticals prioritize ISO 27001-certified diagnostic data handling frameworks for security-conscious procurement decisions. GDPR and emerging AI governance standards impose documentation burdens on automated root-cause analysis deployments. London fintech clusters drive consumption-based service tier negotiations for managed detection offerings.
Japan
METI industrial digitization programs accelerate Time-Sensitive Networking deployment in precision manufacturing environments. JIS standards for network equipment interoperability shape RFP specifications for multi-vendor integration projects. Osaka-Kobe manufacturing belt concentrates demand for protocol analyzers serving automotive and electronics production lines.
Network Diagnostic Tools Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors bridge hardware heritage with cloud-native delivery models. The market structure concentrates around three tiers: integrated infrastructure giants with switching and routing captive demand, cloud-native specialists with Kubernetes-native architectures, and legacy appliance vendors defending installed bases through managed service wrappers. Two archetypes define competitive positioning: full-stack observability platforms unbundling network monitoring from broader IT operations, and carrier-grade throughput specialists defending high-margin telecommunications contracts. Technology licensing agreements and portfolio diversification into adjacent security operations represent the dominant competitive moves.
Within the integrated infrastructure tier, Cisco Systems exemplifies captive demand creation through deep switching and routing stack integration. Cloud-native specialists include SolarWinds, which occupies a position among mid-market enterprises seeking hybrid visibility without capital-intensive appliance refresh cycles. NETSCOUT anchors the carrier-grade throughput segment, representing high-throughput packet inspection capabilities designed for telecommunications environments with 400 Gbps capture requirements.
| Leading Market Players |
|---|
| SolarWinds |
| Cisco Systems |
| NETSCOUT |
| ManageEngine |
| Broadcom |
| IBM |
| Microsoft |
| Dynatrace |
| Paessler PRTG |
| Others |
Supply & Pricing Matrix
Telecommunications carriers with 400 Gbps throughput requirements anchor procurement volume and enforce subscription-based pricing models across the network diagnostic tools landscape. Their capital expenditure authority shapes vendor pricing power, while mid-market enterprises operating under opex mandates drive SaaS-tiered alternatives that compress margin structures for hardware-centric suppliers.
Pricing Analysis
Input-cost pass-through from FPGA and high-speed capture card suppliers elevates hardware platform pricing, particularly for carrier-grade network analyzers processing 100 Gbps to 400 Gbps traffic. Three-tier pricing structure across premium carrier-grade, standard enterprise, and economy entry-level segments reflects certification differentiation and throughput capability. Pricing pressure stems from cloud-native visibility alternatives that eliminate appliance refresh cycles. Mid-market enterprises exhibit highest price sensitivity, while telecommunications providers with FCC compliance deadlines show lowest elasticity.
Supply Chain Analysis
Reverse-logistics flows for refurbishment and remanufacturing of capture hardware concentrate in Taiwan, South Korea, and the United States, where semiconductor packaging and FPGA programming capabilities cluster. Component sourcing draws from specialized foundries for programmable logic devices, memory modules, and precision timing circuits. Single-source vulnerability around 400 Gbps PHY chipsets creates procurement risk for appliance vendors. Distribution runs through direct enterprise sales teams, systems integrators, and managed service providers with multi-tenant delivery infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where buyer procurement criteria are shifting toward ISO 27001-certified data governance and algorithmic transparency documentation under EU AI Act frameworks.
For Market Incumbents: Anticipate margin compression from cloud-native entrants by accelerating Kubernetes-native architecture roadmaps and embedding automated root-cause analysis as standard features. Defensive consolidation through targeted acquisition of QUIC and HTTP/2 protocol engineering teams addresses specialized talent scarcity. Channel control investments with managed service providers create switching costs against SaaS alternatives.
For New Entrants and Emerging Players: Managed service providers represent the most accessible channel for market entry without direct appliance sales infrastructure. White-space targets include India's PLI-accelerated factory automation sector and European mid-market enterprises seeking EU AI Act-compliant SaaS analytics. Geographic expansion into German Industry 4.0 clusters with protocol analyzer specialization offers differentiated positioning against full-stack incumbents.
For Investors and Strategic Acquirers: Cloud infrastructure hyperscalers are the most active acquirer in this space, seeking observability stack completeness. Long-term viability favors vendors with recurring revenue models and compliance engineering resources. Acquisition target archetypes include Kubernetes-native visibility specialists and industrial Ethernet protocol analysis firms. The signal to watch is FCC mandate enforcement intensity driving replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Architecture Migration | Kubernetes-native stacks displace capital-intensive on-premises appliances among mid-market enterprises. |
| Compliance Engineering Investment | EU AI Act documentation capabilities become procurement gates for European telecommunications carriers. |
| Protocol Specialization Acquisition | QUIC and HTTP/2 expertise scarcity elevates value of engineering teams with packet-level analysis depth. |
| Managed Service Partnership | Channel partners bundle diagnostic tools with labor arbitrage to capture consumption-based service demand. |
| Industrial Automation Expansion | Time-Sensitive Networking and industrial Ethernet decoders address German Industry 4.0 visibility requirements. |
Research Methodology
Bottom-up telecommunications and enterprise IT modeling reconciled against top-down vendor shipment tracking forms the analytical core of this study. Primary interviews with network operations executives, IT procurement officers, platform engineers, and managed service provider technical directors combined with secondary validation from FCC filing databases, SEC 10-K disclosures, hyperscaler capex reports, and telecommunications infrastructure deployment records. Triangulation across these sources ensures segment-level accuracy.
Historical trendline analysis of network infrastructure spending patterns informs projection frameworks across the analysis window. Segmentation dimensions include product type, deployment architecture, end-user organization scale, and application priority with regional regulatory cluster differentiation. CAGRs derive from fitted growth curves adjusted for 5G capital cycle intensity and compliance mandate timelines. Forecast inputs incorporate carrier-grade throughput upgrade schedules and cloud-native observability adoption curves.
Revisions become necessary when FCC enforcement timelines shift, EU AI Act implementation guidance changes, or 400 Gbps port speed adoption accelerates beyond modeled trajectories. Forecasts reflect documented assumptions about regulatory compliance cost pass-through and enterprise cloud migration velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Measuring Instruments
Global Process Instrumentation Market
Measuring Instruments
Communication Test Equipment (CTE) Market
Measuring Instruments
Temperature Loggers Market
Measuring Instruments
Ultraviolet Data Logger Market
Measuring Instruments
Global Instrument Calibrator Market
Measuring Instruments
3D Laser Scanner Market
Measuring Instruments
Data Loggers Market
Measuring Instruments
TDS Meter Market
Measuring Instruments
Base Station Analyzer Market
Measuring Instruments
Multifunction Calibrators Market
Measuring Instruments
Data Acquisition Market
Measuring Instruments
North America Scientific Instruments Market
Measuring Instruments
Americas 3D Metrology Market
Measuring Instruments
Global Dissolved Oxygen Meters and Controllers Market
Measuring Instruments
Temperature Calibrator Market
Measuring Instruments
Moisture Meter Market