
 Automated Cell Counter Market | 2026-2036
Automated Cell Counter Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Cell Counter Market Analysis
Market Context with Strategic Players
Biopharmaceutical manufacturing is expanding as the dominant demand vertical for automated cell counters, displacing traditional academic research procurement. Thermo Fisher Scientific leverages its integrated life sciences platform to dominate high-throughput bioproduction workflows. Danaher sustains competitive positioning through Beckman Coulter Life Sciences' specialized hematology and cell analysis portfolios. Sysmex Corporation anchors its presence in clinical diagnostics with advanced optical counting systems for blood analysis applications.
Technical Definition and Structural Segments
An automated cell counter is an analytical instrument that quantifies cell concentration, viability, and morphology using optical detection, electronic impedance, or laser-based flow cytometry principles, with throughput rates ranging from hundreds to millions of cells per minute for quality control in bioprocessing and clinical diagnostics. Flow cytometer systems lead the product type landscape due to their multiparametric analysis capability in cancer research and stem cell applications, while microfluidics technology represents the fastest-growing segment as miniaturization reduces reagent consumption and enables point-of-care deployment. Image cytometer platforms occupy mature margin pools in pharmaceutical quality assurance, where regulatory validation requirements create switching costs for established vendors.
Regulatory Framework and Forward Outlook
FDA 21 CFR Part 11, EU MDR, and ISO 13485 standards collectively shape automated cell counter design requirements, with FDA enforcement of electronic records integrity driving software architecture decisions and EU MDR clinical evidence rules extending certification timelines for new entrants. WHO prequalification pathways for in vitro diagnostics influence procurement standards in emerging markets. Stakeholders must monitor evolving GMP annex guidance for cell and gene therapy manufacturing, as regulatory alignment between FDA and EMA on automated process analytical technology will determine next-generation product development priorities.
Market Dynamics
Cell therapy manufacturing scale-up is compressing instrument validation timelines and forcing automated cell counter vendors to pre-integrate GMP-compliant software modules before shipment.
Growth Catalysts
- CAR-T manufacturing expansion:Commercial cell therapy facilities in the United States and Germany require high-throughput viability monitoring, creating dedicated procurement pipelines for flow cytometry-based counters.
- FDA 21 CFR Part 11:Electronic records integrity mandates are accelerating replacement cycles for legacy hematology analyzers in contract manufacturing organizations.
- Microfluidics miniaturization:Reduced reagent consumption and portable form factors are electrifying point-of-care adoption in decentralized clinical settings.
Market Restraints
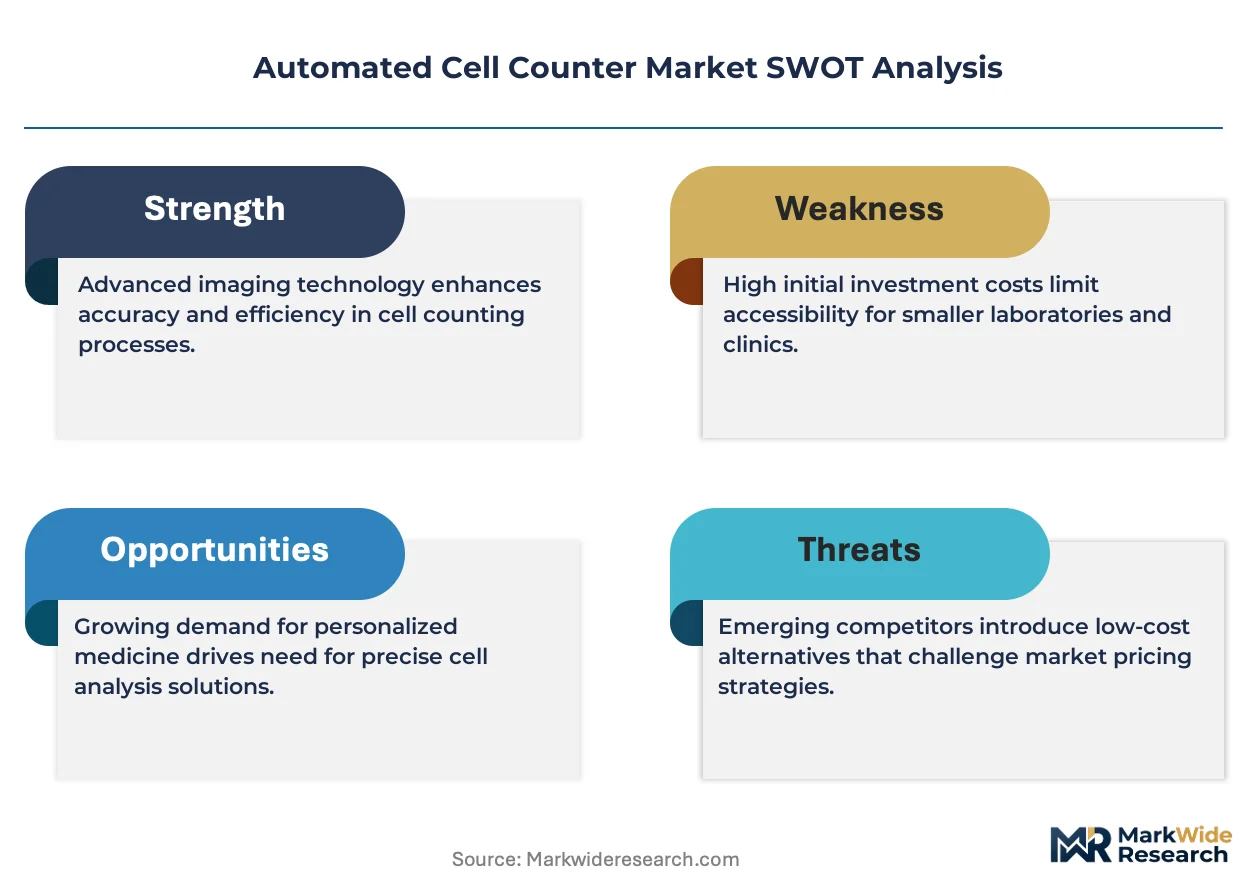
- Optical component supply concentration:Laser diodes and high-resolution CMOS sensors depend on concentrated Asian manufacturing, exposing lead times to geopolitical friction.
- EU MDR clinical evidence requirements:Extended certification timelines for new entrants compress margins and deter mid-tier competitors from European market entry.
- Manual hemocytometer persistence:Academic laboratories with limited capital budgets continue using glass-slide methods for low-throughput applications, capping addressable volume in price-sensitive segments.
Strategic Opportunities
- India biopharma infrastructure buildout:CDSCO-aligned manufacturing incentives and PLI scheme benefits are attracting contract development organizations seeking automated quality control.
- AI-enhanced morphology classification:Machine learning integration with image cytometry is enabling real-time anomaly detection without operator intervention.
- Service unbundling:Independent validation and calibration providers are capturing aftermarket revenue streams previously held by original equipment manufacturers.
Industry Challenges
- GMP software integration complexity:Bioprocessing facilities require seamless data handoff between cell counters and manufacturing execution systems, demanding specialized implementation expertise.
- Cross-functional talent scarcity:Field service engineers must simultaneously troubleshoot optical hardware, fluidics, and 21 CFR Part 11-compliant software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Cell Counter Market |
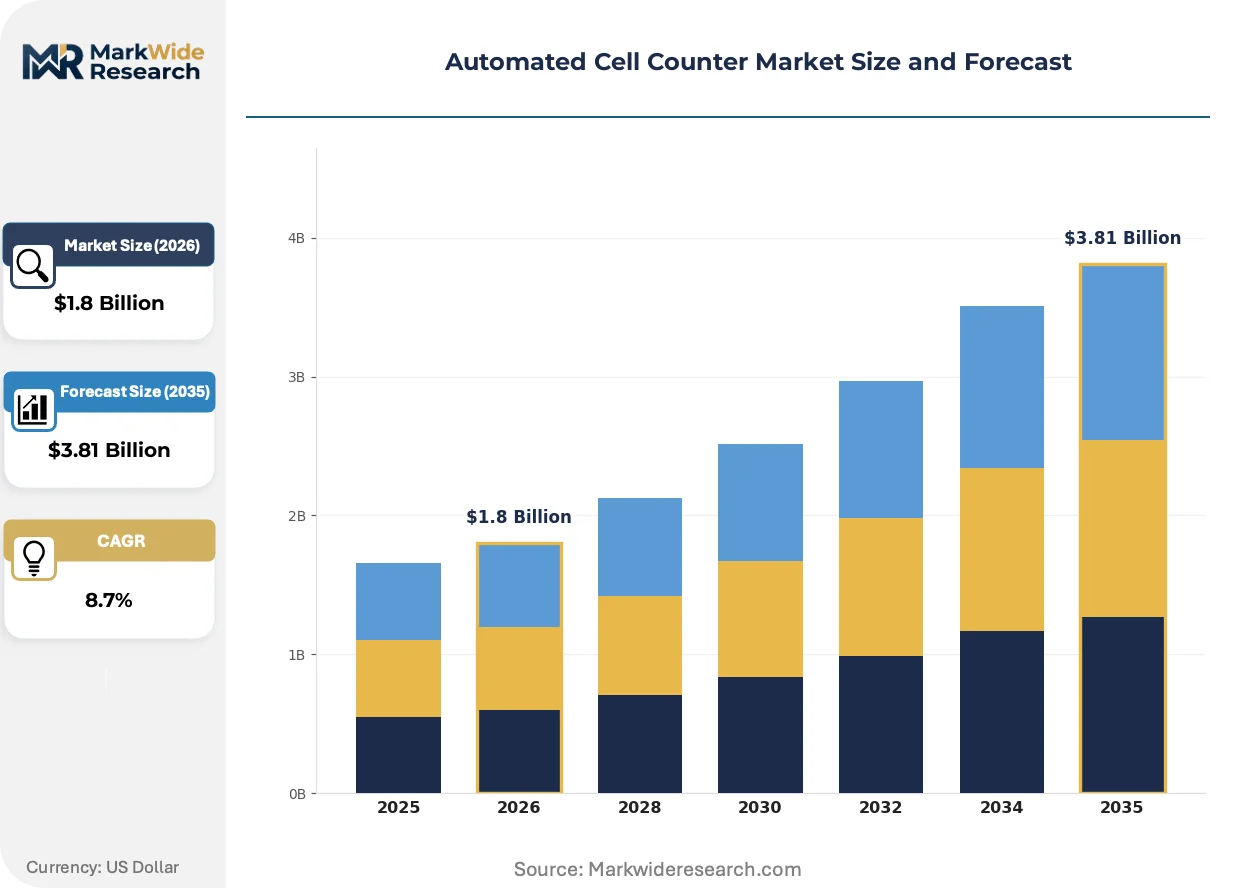
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
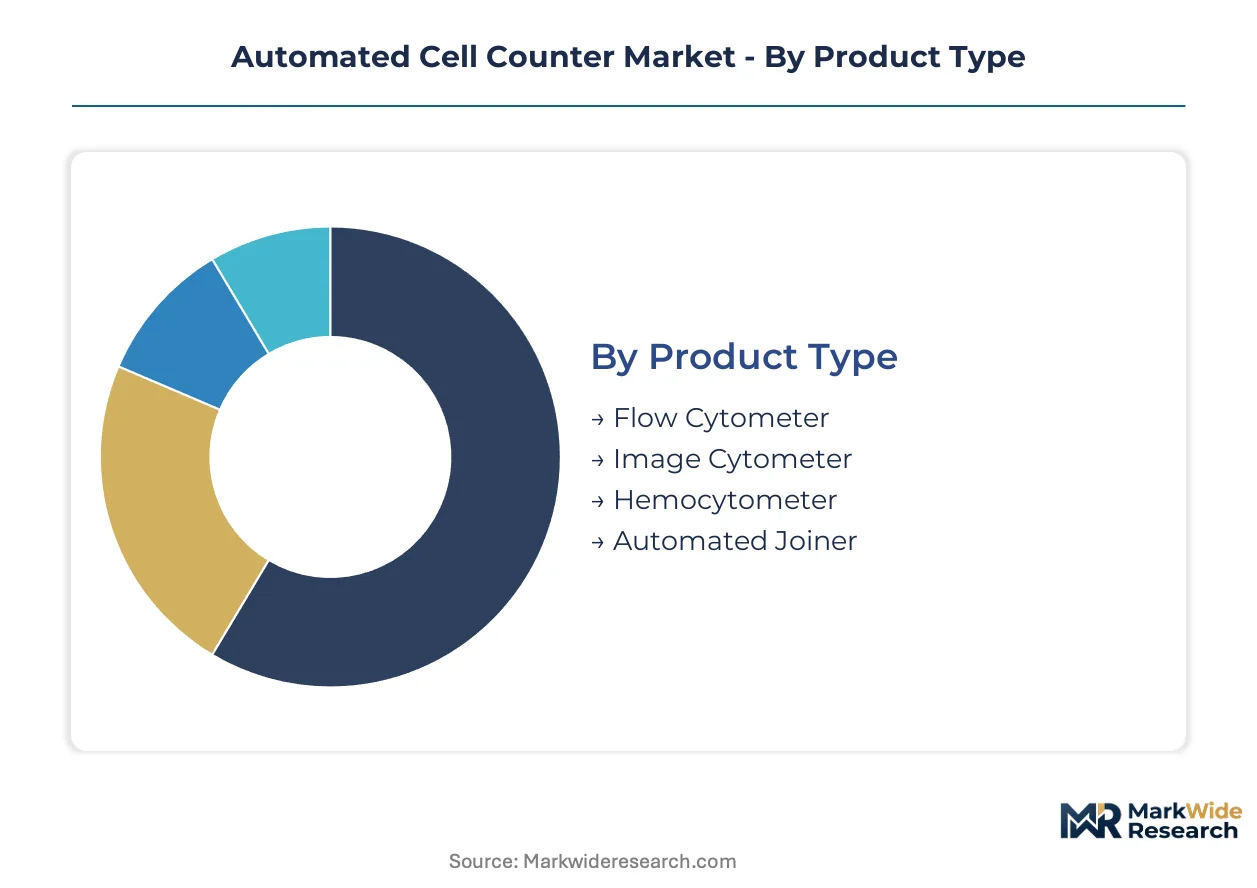
| Segmentation | Product Type: Flow Cytometer, Image Cytometer, Hemocytometer, Automated Joiner End User: Research Laboratories, Clinical Laboratories, Pharmaceutical Companies, Diagnostic Centers Technology: Optical, Electronic, Microfluidics, Laser-Based Application: Blood Analysis, Cancer Research, Drug Development, Stem Cell Research |
| Companies Covered | Thermo Fisher Scientific, Danaher, Sysmex Corporation, Bio-Rad Laboratories, Agilent Technologies, Chemometec A/S, Beckman Coulter Life Sciences, Abbott Laboratories, Sartorius, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Cell Counter Market Emerging Trajectories
Artificial intelligence and microfluidic integration are compressing the gap between research-grade flexibility and manufacturing-grade reproducibility. Vendors are racing to embed predictive maintenance and autonomous calibration within compact benchtop units.
Label-free impedance spectroscopy is electrifying viability assessment workflows by eliminating fluorescent dye dependencies that compromise cell health in sensitive stem cell applications. Gene therapy manufacturers in Massachusetts and North Rhine-Westphalia are adopting these systems for in-process monitoring. The technology is compressing assay preparation time from hours to minutes while reducing consumable costs.
EMA's evolving guidance on process analytical technology for cell and gene therapy manufacturing is forcing instrument vendors to pre-submit validation protocols. Manufacturers must now demonstrate continuous data integrity across distributed production sites. German and Swiss facilities are responding by consolidating supplier relationships with vendors offering integrated qualification packages.
Academic procurement committees are fragmenting into specialized working groups that bypass traditional distributor channels. Direct manufacturer relationships now dominate purchases exceeding institutional thresholds, particularly in Boston and San Diego research clusters. This channel compression is squeezing regional distributor margins while accelerating technical consultation access for end-users.
Automated Cell Counter Market Segmentation
Automated cell counter procurement decisions hinge on regulatory validation requirements that vary sharply across product architectures. Certification burdens determine switching costs and vendor selection criteria in biopharmaceutical manufacturing workflows.
Product Type:
FDA 21 CFR Part 11 compliance obligations fall most heavily on systems deployed in GMP environments, while research-grade instruments face lighter documentation requirements. ISO 13485 certification timelines extend furthest for novel optical detection platforms.
- Flow Cytometer:Laser-based multiparametric systems detect scattered light and fluorescence emissions across thousands of cells per second. CAR-T manufacturers in Massachusetts and North Rhine-Westphalia require these for in-process viability monitoring, with FDA validation protocols adding six to nine months to procurement cycles.
- Image Cytometer:High-resolution CMOS sensors capture morphometric data through brightfield or fluorescence microscopy. Pharmaceutical quality assurance teams in Basel and Boston prioritize these for documented batch release decisions, where EMA audit trails create substantial switching costs for established installations.
- Hemocytometer:Electronic impedance systems dominate clinical diagnostics with standardized counting chambers.
- Automated Joiner:Integrated sample preparation modules reduce operator variability in high-throughput bioprocessing.
Leading the category by volume: Flow Cytometer. Growing fastest: Image Cytometer.
End User:
Capital allocation patterns diverge sharply between federally funded research institutions and profit-driven contract manufacturers. Reagent contract structures and service bundling terms reshape total cost of ownership calculations across customer types.
- Research Laboratories:Academic and government facilities prioritize modular upgrade paths and open software architectures. NIH-funded centers in Maryland and California drive demand for fluorescence-capable benchtop units, though manual hemocytometer persistence in budget-constrained departments caps addressable volume.
- Pharmaceutical Companies:Integrated bioprocessing suites require pre-validated GMP software modules and seamless manufacturing execution system connectivity. Cell therapy manufacturers in Germany and Switzerland consolidate supplier relationships to reduce qualification overhead.
- Clinical Laboratories:Hospital-based diagnostics demand high-throughput reliability with minimal maintenance intervals.
- Diagnostic Centers:Independent reference laboratories prioritize throughput per square foot and technician training efficiency.
Highest absolute spend: Pharmaceutical Companies. Steepest expansion trajectory: Research Laboratories.
Technology:
Component sourcing geography and intellectual property concentration determine which detection modalities achieve cost parity at manufacturing scale. Patent estates around microfluidic chip fabrication create barriers to entry for new optical approaches.
- Microfluidics:Miniaturized channel architectures reduce reagent consumption by orders of magnitude while enabling point-of-care deployment. CDSCO-aligned manufacturing incentives in India are attracting contract development organizations seeking portable quality control solutions for decentralized clinical trials.
- Laser-Based:Solid-state diode systems deliver the excitation precision required for multiparametric flow cytometry. German and Swiss facilities lead adoption for stem cell characterization where fluorescent dye compatibility demands narrow wavelength tolerance.
- Optical:Brightfield and phase-contrast methods serve established pharmaceutical quality assurance protocols.
- Electronic:Coulter principle impedance measurement anchors clinical hematology with proven reproducibility.
Widest installed base: Laser-Based. Climbing the fastest: Microfluidics.
Application:
Regulatory scrutiny intensity and reimbursement pathways create divergent margin profiles across therapeutic areas. FDA breakthrough therapy designations and EMA priority medicines status accelerate instrument validation timelines for supporting applications.
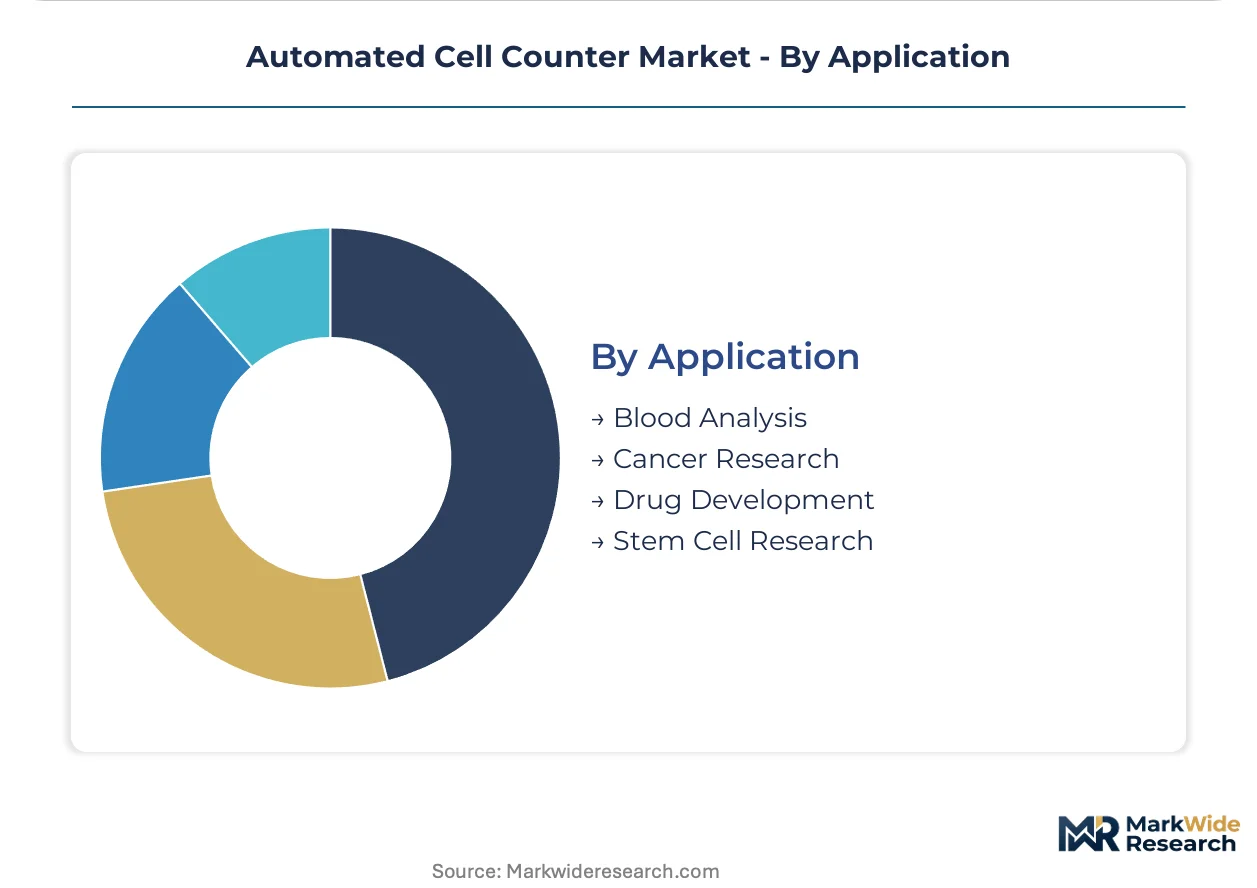
- Cancer Research:Immuno-oncology workflows demand simultaneous viability, proliferation, and phenotype assessment. Academic medical centers in Boston and San Diego research clusters procure directly from manufacturers to access technical consultation for complex assay development.
- Stem Cell Research:Pluripotency marker panels and differentiation trajectory analysis require gentle label-free detection. Gene therapy manufacturers in Massachusetts adopt impedance spectroscopy systems to eliminate fluorescent dye dependencies that compromise cell health.
- Blood Analysis:Routine clinical diagnostics drive volume through standardized complete blood count protocols.
- Drug Development:High-content screening and cytotoxicity assays support pharmaceutical lead optimization.
Dominant revenue concentration: Cancer Research. Gaining share fastest: Stem Cell Research.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts and North Rhine-Westphalia anchor cell therapy manufacturing concentration, with tax-incentive zones in both jurisdictions accelerating facility buildouts. CDSCO-aligned manufacturing incentives in India and China's biopharma cluster development programs are redistributing procurement gravity across three continents.
United States
CAR-T commercial manufacturing in Massachusetts and Maryland drives high-throughput flow cytometer procurement. FDA 21 CFR Part 11 enforcement compresses validation timelines for contract manufacturing organizations. Boston research clusters now procure directly from manufacturers, bypassing traditional distributor channels for technical consultation access.
Germany
Stem cell characterization demand in Baden-Württemberg and North Rhine-Westphalia requires narrow wavelength tolerance laser systems. EMA process analytical technology guidance forces pre-submission of validation protocols. Swissmedic-aligned facilities in Basel respond by consolidating supplier relationships for integrated qualification packages.
China
Gene therapy manufacturing scale-up in Yangtze River Delta biotech parks accelerates automated counter deployment. NMPA electronic records requirements reshape software architecture specifications. Shanghai and Suzhou clusters attract CDMO investment seeking GMP-compliant quality control infrastructure.
India
CDSCO-aligned manufacturing incentives and PLI scheme benefits attract contract development organizations to Maharashtra and Telangana. Reagent consumption reduction through microfluidics technology enables portable quality control for decentralized clinical trials. Hyderabad and Mumbai facilities lead adoption of miniaturized counting systems.
Switzerland
Pharmaceutical quality assurance in Basel demands documented batch release decisions with EMA audit trail compliance. Swissmedic prequalification pathways influence procurement standards for neighboring EU markets. Zurich and Geneva research institutions prioritize image cytometry platforms with regulatory validation packages.
Automated Cell Counter Market Vendor Landscape
Top-tier vendors anchor integrated life sciences platforms, while mid-tier specialists occupy niche detection modalities. The market structure stratifies across three tiers: diversified conglomerates with bioprocessing workflows, hematology-focused diagnostics houses, and emerging microfluidics innovators. Two strategic archetypes dominate competitive positioning: platform integrators pursuing manufacturing execution system connectivity, and point-of-care specialists exploiting miniaturization trends. M&A activity concentrates on software validation capabilities, while capacity expansion targets cell therapy manufacturing corridors in Massachusetts and Germany.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Danaher occupy positions defined by integrated platform breadth rather than standalone instrument specialization. Danaher sustains competitive positioning through Beckman Coulter Life Sciences' specialized portfolios. Sysmex Corporation exemplifies the diagnostics-focused archetype, anchoring clinical applications with standardized counting protocols. These three entities represent distinct strategic vectors: platform integration, specialized hematology, and clinical diagnostics standardization.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Danaher |
| Sysmex Corporation |
| Bio-Rad Laboratories |
| Agilent Technologies |
| Chemometec A/S |
| Beckman Coulter Life Sciences |
| Abbott Laboratories |
| Sartorius |
| Others |
Supply Flow & Price Mechanics
FDA 21 CFR Part 11 validation requirements for electronic records are compressing procurement timelines and forcing vendors to absorb pre-shipment qualification costs, which concentrates pricing power with suppliers offering integrated GMP software modules while squeezing margins for hardware-only competitors.
Pricing Analysis
Short lead-time premiums now separate validated GMP-compliant systems from research-grade alternatives, with contract manufacturing organizations paying substantial markups for expedited delivery to cell therapy facilities in Massachusetts and Germany. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling, with academic laboratories exhibiting highest price sensitivity due to NIH funding constraints. Cost compression in the mid-tier segment is intensifying as Indian and Chinese manufacturers enter with CDSCO-aligned and NMPA-certified alternatives.
Supply Chain Analysis
Regional distribution centers in Germany, Switzerland, and the United States operate hub-and-spoke patterns to serve cell therapy manufacturing clusters, with Singapore and Shanghai emerging as secondary hubs for Asia-Pacific access. Laser diodes from Japan, high-resolution CMOS sensors from South Korea, and microfluidic chips from Germany constitute critical component dependencies. Single-source vulnerability around solid-state laser systems creates exposure to geopolitical friction. Distribution runs through manufacturer-direct channels for large pharmaceutical accounts and specialized life sciences distributors for academic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical component fabrication capacity constraints in Japan and South Korea are propping pricing for laser-based systems, creating a supply-constrained environment that favors vendors with captive component relationships.
For Market Incumbents: To counter microfluidics entrants from India and China, Thermo Fisher Scientific and Danaher should deepen backward integration into CMOS sensor supply chains while accelerating GMP software pre-validation for cell therapy corridors in Massachusetts and North Rhine-Westphalia. Certification investment in Swissmedic-aligned qualification packages will cement switching costs among Basel pharmaceutical quality assurance teams. For New Entrants and Emerging Players: Launch via direct manufacturer relationships with Boston and San Diego research clusters to bypass distributor margin capture and access technical consultation opportunities. Academic procurement committee fragmentation creates the most penetrable entry point, with NIH-funded centers prioritizing modular upgrade paths and open software architectures over established vendor loyalty. For Investors and Strategic Acquirers: The window for entry favors software validation specialists with FDA 21 CFR Part 11 expertise and EMA process analytical technology protocol libraries. Long-term viability hinges on consolidation of qualification overhead as cell therapy manufacturing scales. Watch for inflection when German and Swiss facilities begin mandating autonomous calibration and predictive maintenance as baseline procurement requirements.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Software Pre-Validation | FDA 21 CFR Part 11 compliance compresses replacement cycles for legacy hematology analyzers in contract manufacturing organizations. |
| Microfluidics Platform Launch | CDSCO-aligned manufacturing incentives in India enable portable quality control for decentralized clinical trials. |
| AI-Enhanced Morphology Integration | Machine learning with image cytometry enables real-time anomaly detection without operator intervention in pharmaceutical quality assurance. |
| Regional Distribution Hub Expansion | Singapore and Shanghai secondary hubs accelerate access to Yangtze River Delta gene therapy manufacturing clusters. |
| Service Unbundling Partnership | Independent validation providers capture aftermarket revenue streams previously held by original equipment manufacturers. |
Methodological Framework
SEC 10-K filings, FDA 510(k) clearance databases, and EMA marketing authorization records formed the secondary backbone, supplemented by trade data from German and Swiss customs authorities. Primary interviews with bioprocessing executives, regulatory affairs leads at cell therapy manufacturers, GPO contracts managers, and field service engineers combined with secondary validation to establish instrument procurement patterns. Bottom-up and top-down triangulation reconciled vendor shipment data with end-user installation records across Massachusetts, North Rhine-Westphalia, and Shanghai clusters.
Bottom-up modeling aggregated segment-level demand across product type, end user, technology, and application dimensions, while top-down validation cross-checked against biopharmaceutical capital expenditure disclosures. CAGRs were derived from regression analysis of historical procurement velocity and projected manufacturing capacity buildouts. Stem cell research application growth and microfluidics technology penetration served as key forecast inputs, with regulatory alignment between FDA and EMA on process analytical technology influencing adoption curve assumptions across the analysis window.
Supply chain disruption, regulatory timeline extension, and cell therapy manufacturing scale-up delays are the dominant revision risks to the forecast framework. Outputs reflect documented assumptions around validation protocol standardization and regional infrastructure investment commitments. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Automated Blood Processing Equipment Market
Laboratory Equipment
Microplate Reader Market
Laboratory Equipment
Global Automated Analyzers Market
Laboratory Equipment
Life Sciences and Laboratory Equipment Market
Laboratory Equipment
Point of Care (POC) Coagulation Testing Devices Market
Laboratory Equipment
Laboratory Ovens Market
Laboratory Equipment
Multi Channel Hotplate Magnetic Stirrers Market
Laboratory Equipment
Europe Laboratory Hoods and Enclosure Market
Laboratory Equipment
Global Pipettes and Pipettors Market
Laboratory Equipment
Global Slide Stainer Market
Laboratory Equipment
Laboratory Vacuum Drying Oven Market
Laboratory Equipment
Laboratory Furnaces Market
Laboratory Equipment
Hotplate Stirrers Market
Laboratory Equipment
Laboratory Glassware and Plasticware Market
Laboratory Equipment
Global Laboratory Glassware Washers Market
Laboratory Equipment
Molecular Microplate Readers and Washers Market