
 Laboratory Pulverizer Market | 2026-2036
Laboratory Pulverizer Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Pulverizer Market Insights
The capital-intensity divergence between integrated manufacturers and assembly-dependent competitors is unwinding competitive stability across the laboratory pulverizer supply base. Williams Patent Crusher & Pulverizer Co. leverages captive foundry capacity to control lead times on precision grinding elements. Lavallab anchors its position through deep specialization in cryogenic and planetary mill configurations for pharmaceutical clients.
A laboratory pulverizer is a bench-scale or floor-standing size-reduction apparatus engineered to grind brittle, fibrous, or elastic materials into fine, analytically representative powders, typically achieving particle distributions from 10 microns to 500 microns depending on rotor speed, chamber geometry, and sieve selection. Ball mill configurations dominate capital placement in mineralogy and ceramics labs where prolonged attrition grinding preserves crystalline structure for X-ray diffraction workflows. Disc mill demand accelerates fastest in pharmaceutical quality control, where single-use chamber liners eliminate cross-contamination risks between active pharmaceutical ingredient batches.
FDA 21 CFR Part 11 electronic records mandates and EPA Method 3050B sample preparation protocols jointly shape equipment specifications, compelling manufacturers to supply validated pulverizers with sealed dust containment and automated cycle logging. ISO 17025 accreditation requirements for material testing laboratories in the European Union and United States further tighten calibration traceability for grinding chamber temperature and RPM. Stakeholders must monitor how evolving PFAS analysis protocols under EPA draft Method 1633 redirect demand toward cryogenic pulverizers capable of processing fluoropolymer matrices without thermal degradation.
Market Dynamics
Sealed-chamber pulverizer designs are displacing legacy open-system equipment as regulatory agencies mandate dust containment and automated documentation for laboratory sample preparation workflows across pharmaceutical and environmental testing verticals.
Growth Catalysts
- CDSCO bioequivalence documentation:Indian pharmaceutical laboratories are expanding disc mill and ball mill procurement to meet tightened generic drug testing protocols.
- REACH compliance replacement cycles:Germany's material testing corridor drives fleet turnover toward sealed-chamber pulverizer configurations.
- Cryogenic processing demand:Fluoropolymer matrix preparation for PFAS analysis redirects capital toward low-temperature grinding systems.
Market Restraints
- Precision grinding element supply concentration:Captive foundry capacity at integrated manufacturers creates lead time vulnerability for assembly-dependent competitors.
- ISO 17025 calibration traceability costs:Temperature and RPM validation requirements impose recurring compliance expenditure on smaller testing laboratories.
- Ball mill substitution pressure:Disc mills with single-use chamber liners capture pharmaceutical quality control applications through contamination risk elimination.
Strategic Opportunities
- EPA Method 1633 protocol expansion:Draft PFAS analysis standards create equipment refresh demand in North American environmental testing laboratories.
- Planetary mill cryogenic convergence:Pharmaceutical clients seek integrated low-temperature planetary configurations for heat-sensitive active ingredient processing.
- Direct manufacturer procurement channels:End-users bypass distribution intermediaries to secure validated systems with automated cycle logging.
Industry Challenges
- FDA 21 CFR Part 11 software validation:Electronic records mandates require specialized IT integration expertise that strains traditional equipment vendor capabilities.
- Legacy system interoperability:Sealed-chamber designs face integration friction with existing laboratory information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Pulverizer Market |
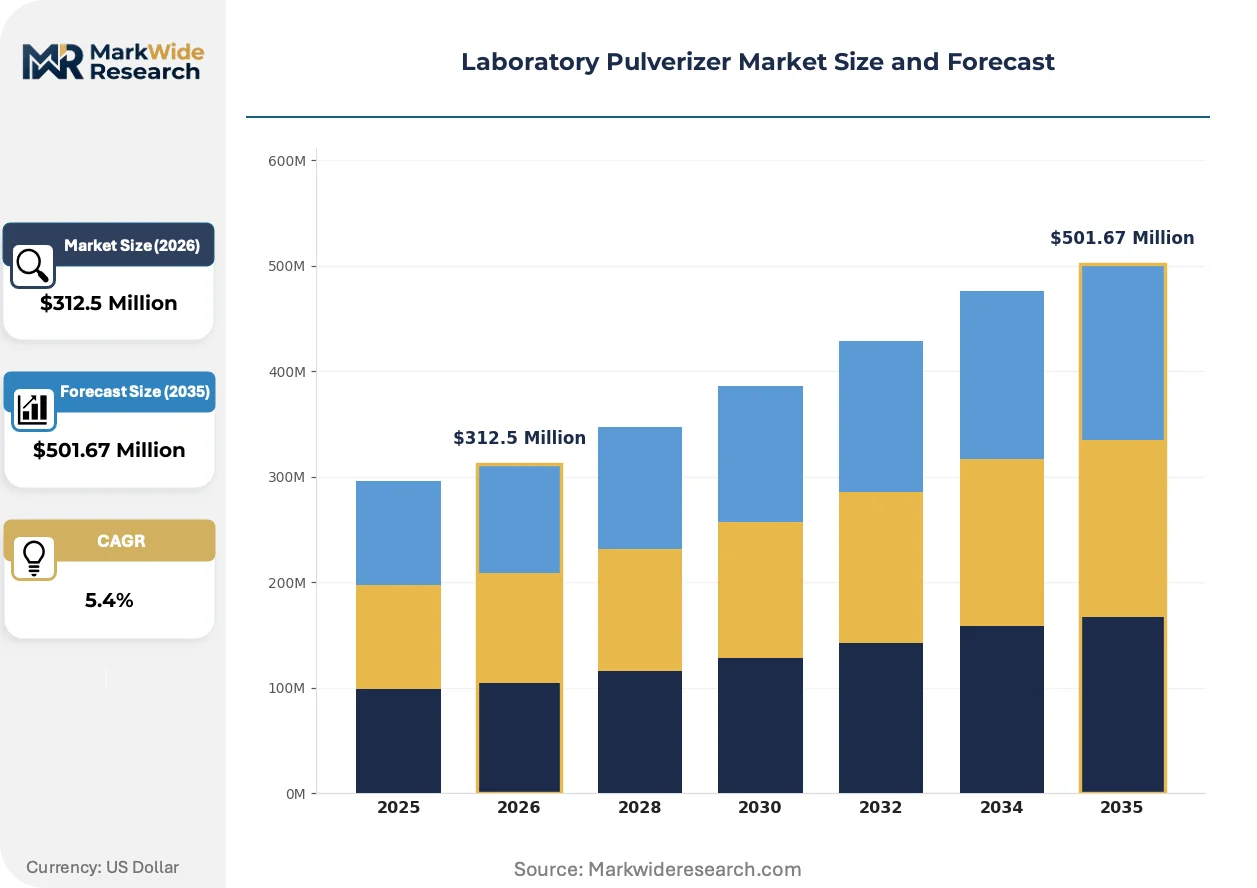
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Mill, Disc Mill, Hammer Mill, Blade Mill End User: Chemical Labs, Pharmaceutical Labs, Material Testing Labs, Research Institutes Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers Application: Sample Preparation, Material Characterization, Quality Control, R&D |
| Companies Covered | Orenda Automation Technologies Inc., Rockland, Gilson Company, Inc., Williams Patent Crusher & Pulverizer Co., Lavallab, Bepex International, LLC, American Pulverizer Company, Sturtevant Inc., Bradley Pulverizer Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Pulverizer Market Trends and Innovations
Equipment miniaturization, regulatory documentation automation, and procurement channel restructuring are compressing traditional supply relationships while expanding addressable applications for precision grinding systems.
Planetary ball mill technology is miniaturizing into benchtop configurations that preserve crystalline structure for X-ray diffraction workflows. Mineralogy and ceramics laboratories in academic and industrial R&D settings are adopting these compact systems at accelerating pace. The form factor reduction is miniaturizing capital barriers for mid-tier laboratories previously excluded from advanced attrition grinding capabilities.
REACH compliance deadlines in the European Union are mandating sealed-chamber replacement of legacy open-system pulverizers in material testing corridors. Industrial laboratories face equipment validation requirements that compress procurement timelines and favor vendors with pre-certified documentation packages. Germany's testing laboratory clusters are responding through coordinated fleet standardization programs.
Service contract unbundling is separating equipment purchase from maintenance and calibration obligations. Pharmaceutical quality control departments now source grinding chamber liners and validation services through independent channels rather than bundled OEM agreements. This pattern is most visible in India's expanding generic drug testing infrastructure.
Laboratory Pulverizer Market Segmentation
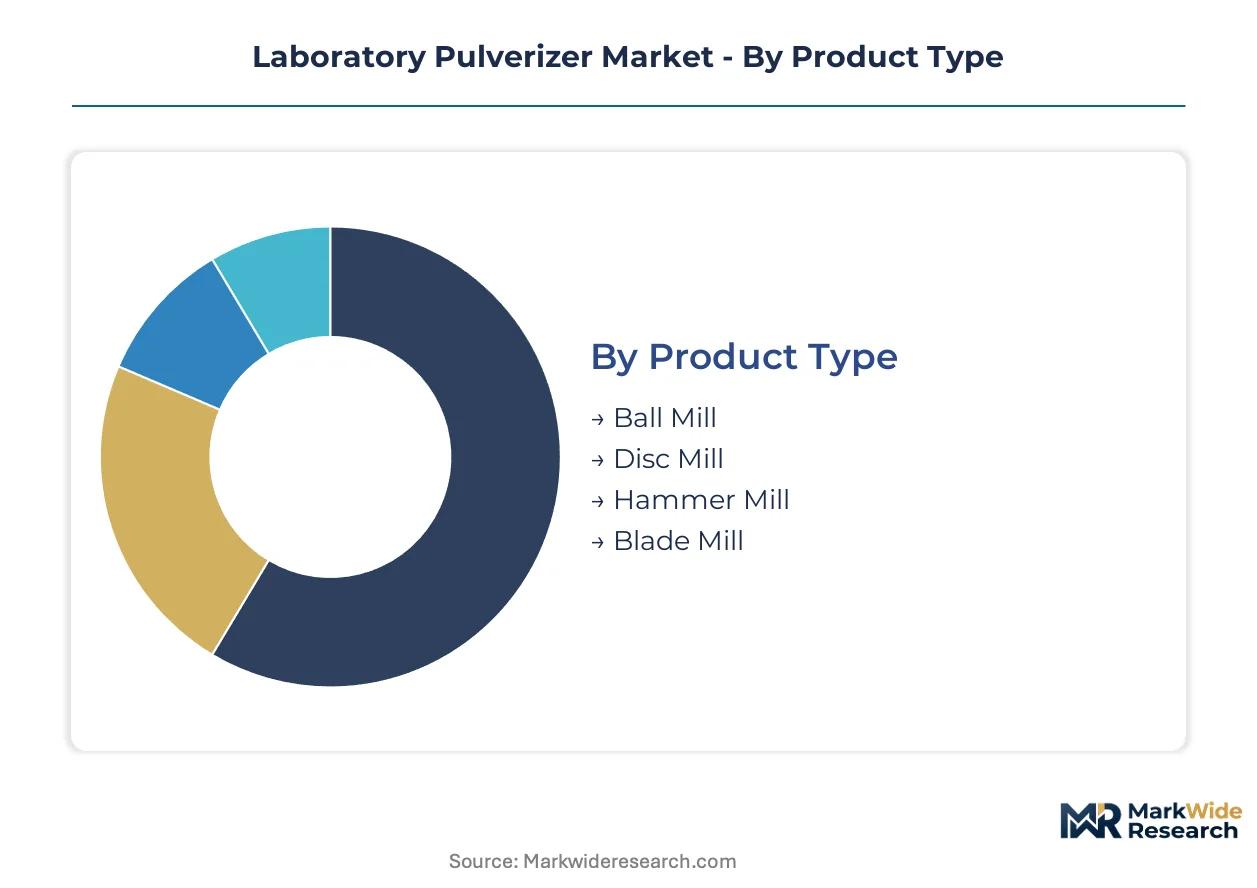
Segmentation in the laboratory pulverizer market reveals how procurement channels, application requirements, and end-user compliance burdens reshape equipment specifications. Manufacturers configure product portfolios around these divides to capture recurring revenue from validation-dependent verticals.
Product Type:
Channel mix varies sharply by pulverizer mechanism, with ball mills and disc mills flowing through direct manufacturer relationships for validated pharmaceutical procurement while hammer mills and blade mills move through distribution networks for industrial testing.
- Ball Mill:Attrition grinding chambers using hardened steel or ceramic media achieve particle distributions from 10 to 100 microns. Mineralogy laboratories in Germany's material testing corridor deploy these for X-ray diffraction sample preservation where crystalline structure integrity is mandatory.
- Disc Mill:Counter-rotating grinding plates with adjustable gap settings process brittle and fibrous materials. Pharmaceutical quality control departments in India source these through direct channels to secure single-use chamber liners that eliminate cross-contamination between active pharmaceutical ingredient batches under CDSCO documentation protocols.
- Hammer Mill:High-speed rotor assemblies with replaceable impact hammers suit coarse preliminary grinding. Environmental testing laboratories processing soil and sediment samples for EPA Method 3050B protocols favor these for rapid throughput.
- Blade Mill:Shearing rotor configurations with interchangeable blade geometries handle elastic and heat-sensitive materials. Research institutes in polymer characterization workflows specify these for preliminary size reduction before cryogenic finishing.
Ball mill configurations dominate installed base in academic mineralogy. Disc mill procurement is where expansion concentrates fastest among pharmaceutical quality control departments.
End User:
Cost tier stratification separates capital-intensive pharmaceutical compliance from budget-constrained academic research, with material testing laboratories occupying the mid-tier validation segment.
- Chemical Labs:Process development and analytical chemistry operations require versatile pulverizers handling corrosive and reactive substances. Stainless steel chamber specifications with Hastelloy grinding elements command premium positioning in specialty chemical R&D clusters.
- Pharmaceutical Labs:Quality control and bioequivalence testing facilities operate under FDA 21 CFR Part 11 and CDSCO electronic records mandates. These end-users drive demand for sealed-chamber designs with automated cycle logging and IQ/OQ/PQ documentation packages.
- Material Testing Labs:Industrial certification and failure analysis operations process metals, ceramics, and composites. REACH compliance deadlines in Germany accelerate fleet replacement toward dust-contained systems with ISO 17025 calibration traceability.
- Research Institutes:Academic and government R&D facilities prioritize flexibility and capital efficiency over validation documentation. These end-users source through distributor networks and represent price-sensitive volume for standard hammer and blade mill configurations.
Material testing laboratories anchor current installed base across European industrial corridors. Pharmaceutical labs are climbing the fastest as generic drug testing infrastructure expands in India.
Distribution Channel:
Customer type determines channel selection, with validated pharmaceutical procurement bypassing intermediaries while academic and mid-tier industrial buyers accept distributor markups for local service access.
- Direct Sales:Manufacturer field engineers conduct site assessments and deliver integrated validation documentation. Pharmaceutical quality control departments in Germany and India leverage this channel to secure FDA 21 CFR Part 11 compliant systems with pre-certified software.
- Distributors:Regional inventory and technical service networks support material testing laboratories with rapid spare parts availability. These intermediaries capture mid-market chemical and environmental testing segments where calibration service bundling adds value.
- Online Retail:E-commerce platforms with specification filtering and competitive pricing serve research institutes and small commercial laboratories. Standard hammer mills and blade mills without validation requirements flow through this channel.
- Resellers:Independent agents aggregate demand from fragmented academic and government procurement offices. These channels specialize in grant-funded equipment purchases with extended payment terms and installation coordination.
Direct sales channels capture premium pharmaceutical validation business. Distributor relationships retain material testing loyalty through service density.
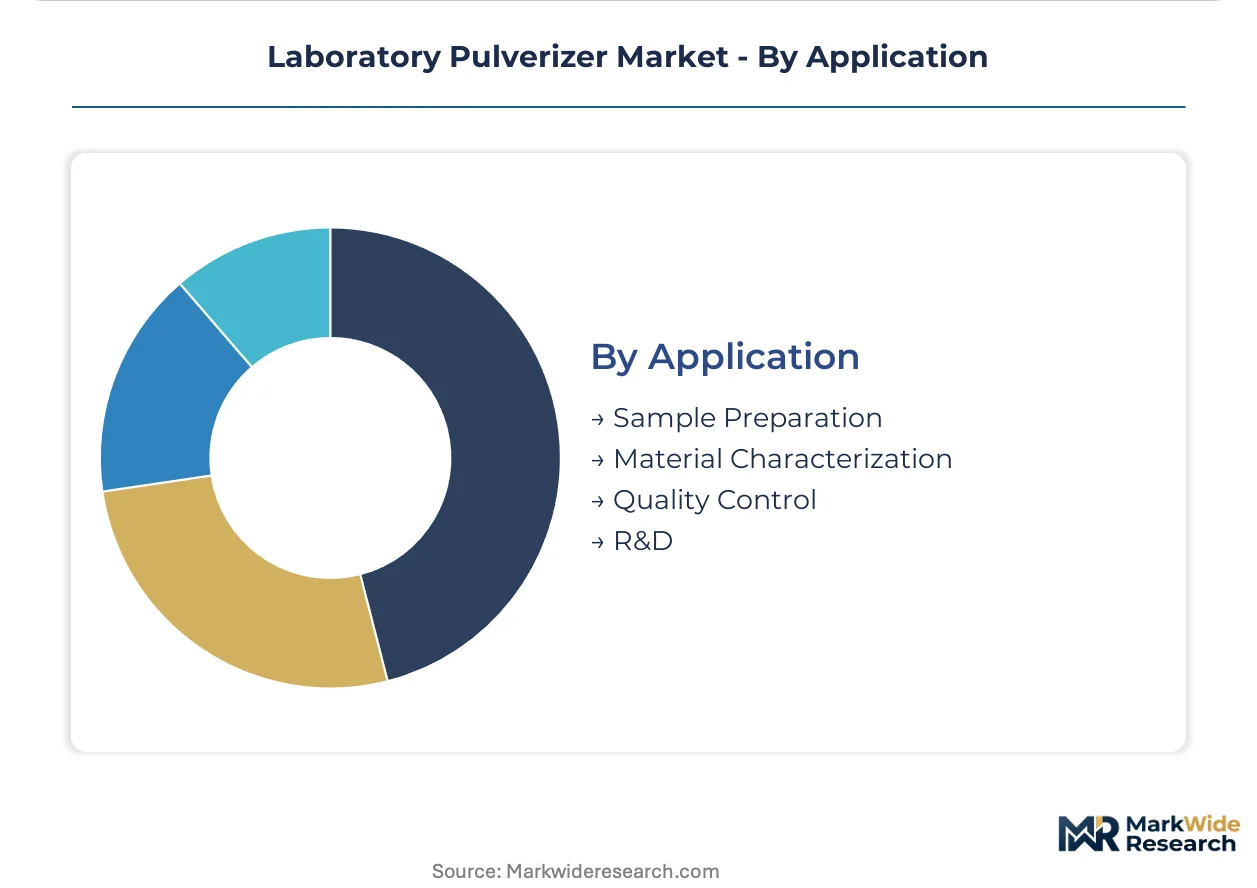
Application:
Application maturity separates commoditized sample preparation from high-margin quality control workflows where regulatory documentation creates vendor stickiness.
- Sample Preparation:Pre-analytical size reduction for spectroscopy, chromatography, and wet chemistry workflows. Environmental testing laboratories under EPA protocols represent high-volume demand for standardized hammer mill configurations.
- Quality Control:Validated grinding for batch release testing and regulatory submission support. Pharmaceutical laboratories in India expanding CDSCO bioequivalence capacity drive premium disc mill procurement with single-use liner requirements.
- Material Characterization:Particle size distribution control for mechanical and thermal property analysis. Germany's automotive and aerospace material testing clusters specify ball mills for crystalline structure preservation in failure analysis.
- R&D:Experimental scale grinding for formulation development and process optimization. Research institutes prioritize planetary mill flexibility with interchangeable grinding media and cryogenic conversion kits.
Sample preparation anchors volume across environmental and industrial testing. Quality control applications are gaining share fastest as pharmaceutical documentation requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's REACH-driven material testing corridor while procurement volume accelerates fastest across India's pharmaceutical quality control expansion. This asymmetry reshapes manufacturer prioritization between premium validation documentation and high-volume disc mill deployment.
Germany
REACH compliance deadlines force fleet replacement toward sealed-chamber pulverizer configurations across industrial testing laboratories. ECHA enforcement of substance registration requirements tightens dust containment specifications for legacy open-system equipment. The material testing corridor spanning North Rhine-Westphalia and Bavaria coordinates standardized procurement through regional laboratory consortiums.
United States
EPA Method 1633 draft protocols for PFAS analysis redirect capital toward cryogenic grinding systems capable of processing fluoropolymer matrices. FDA 21 CFR Part 11 electronic records mandates shape pharmaceutical laboratory equipment specifications with automated cycle logging requirements. Environmental testing clusters in the Northeast and California accelerate equipment refresh cycles ahead of anticipated regulatory finalization.
India
CDSCO tightened documentation requirements for generic drug bioequivalence studies expand disc mill and ball mill procurement across quality control facilities. The country's national pharmaceutical regulator mandates validated sample preparation equipment with IQ/OQ/PQ documentation packages. Maharashtra and Gujarat host the fastest-expanding procurement corridors as contract research organizations scale testing infrastructure.
China
Dual carbon goals and GB standards for laboratory equipment energy efficiency reshape pulverizer specifications in state-funded research institutes. The national medical products administration tightens quality control equipment validation for domestic pharmaceutical export certification. Yangtze River Delta material testing laboratories upgrade grinding systems to meet international accreditation requirements for export-oriented manufacturing support.
Japan
METI funding for advanced materials characterization sustains planetary mill demand in academic and industrial R&D settings. PMDA alignment with international pharmaceutical quality standards drives sealed-chamber adoption in drug development laboratories. Kansai region ceramics and electronics clusters maintain specialized attrition grinding requirements for crystalline structure preservation in failure analysis workflows.
Laboratory Pulverizer Market Competitive Landscape
Concentration sits with integrated manufacturers commanding captive foundry capacity and assembly-dependent competitors facing lead time vulnerability on precision grinding elements. The vendor base stratifies across three tiers: vertically integrated specialists with in-house casting operations, regional fabricators sourcing grinding elements through supply contracts, and distribution-dependent assemblers serving price-sensitive academic segments. Dominant competitive moves include backward integration into precision grinding element production and geographic expansion through direct sales channel establishment in pharmaceutical procurement corridors.
Within the integrated manufacturer tier, Williams Patent Crusher & Pulverizer Co. and Lavallab exemplify divergent specialization strategies. Williams Patent Crusher & Pulverizer Co. anchors its position through captive control over precision grinding element lead times. Lavallab occupies a position centered on cryogenic and planetary mill configurations for pharmaceutical validation requirements. Among North American fabricators, Gilson Company, Inc. sits within the distribution-supported tier serving environmental testing and academic research segments where local service density determines procurement decisions.
| Leading Market Players |
|---|
| Orenda Automation Technologies Inc. |
| Rockland |
| Gilson Company, Inc. |
| Williams Patent Crusher & Pulverizer Co. |
| Lavallab |
| Bepex International, LLC |
| American Pulverizer Company |
| Sturtevant Inc. |
| Bradley Pulverizer Company |
| Others |
Pricing and Supply Chain Analysis
Single-use chamber liner substitution for reusable grinding elements simultaneously shifts procurement geography toward pharmaceutical manufacturing clusters and compresses margin structures for legacy equipment suppliers. This input transition rewards vendors with certified liner supply chains while penalizing assembly-dependent competitors tethered to commodity steel sourcing.
Pricing Analysis
The customization-premium spread separates configured-to-order sealed-chamber systems from standard hammer mill configurations. Pricing stratifies across premium, standard, and economy tiers based on validation documentation depth and ISO 17025 calibration bundling. Cost compression in the standard tier intensifies because distributor markups face direct manufacturer bypass pressure. Research institutes exhibit highest price sensitivity through grant-funded procurement, while pharmaceutical quality control departments accept premium positioning for FDA 21 CFR Part 11 compliant systems.
Supply Chain Analysis
Germany and India anchor precision grinding element fabrication and pharmaceutical equipment assembly respectively. Hardened steel rotor castings and ceramic grinding media draw from foundry networks concentrated in Western Europe. Single-source vulnerability concentrates in specialty alloy supply for corrosion-resistant chamber specifications. Distribution runs through manufacturer-direct channels for validated pharmaceutical procurement and regional distributor networks for industrial testing segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent pulverizer manufacturers face substitution defense imperatives as cryogenic planetary mill configurations displace conventional ball mill placements in heat-sensitive pharmaceutical workflows.
For Market Incumbents: Consolidate captive foundry capacity to secure grinding element lead times against assembly-dependent competitors. Deepen ISO 17025 calibration service bundling to lock material testing laboratory relationships before REACH compliance deadlines accelerate fleet replacement. For New Entrants and Emerging Players: FDA 21 CFR Part 11 certification fast-tracks open white-space in Indian pharmaceutical quality control expansion corridors. Target Maharashtra and Gujarat contract research organizations scaling CDSCO bioequivalence infrastructure. Pursue direct sales channel establishment with pre-validated documentation packages as primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed laboratory equipment platforms seeking bolt-on precision grinding specialists. Five-to-ten year viability hinges on regulatory documentation automation capabilities rather than hardware differentiation alone. Monitor EPA Method 1633 finalization timing as inflection indicator for cryogenic system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Casting | Captive foundry control secures grinding element supply against lead time volatility in German material testing corridors. |
| Cryogenic Configuration Development | Low-temperature planetary mill expansion captures PFAS analysis demand under EPA Method 1633 draft protocols. |
| Direct Sales Channel Establishment | Manufacturer field engineering bypasses distributor markups in Indian pharmaceutical procurement corridors. |
| Validation Documentation Automation | Pre-certified IQ/OQ/PQ packages compress procurement timelines for CDSCO bioequivalence compliance deadlines. |
| Service Contract Unbundling | Independent liner and calibration sourcing separates recurring revenue from equipment purchase in quality control verticals. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with laboratory equipment procurement managers, plant engineers at material testing facilities, and aftermarket service heads; and secondary validation through customs trade records, SEC equipment manufacturer filings, and regulatory agency certification databases. Bottom-up equipment shipment triangulation cross-referenced against top-down end-user facility counts across pharmaceutical, chemical, and industrial testing verticals.
Across the analysis window, the forecasting framework modeled pulverizer demand through product type, end-user compliance tier, distribution channel structure, and application maturity segmentation. CAGRs derived from regression analysis of historical replacement cycles and regulatory deadline acceleration effects. Cryogenic processing adoption curves and PFAS analysis protocol expansion served as industry-specific demand inputs.
Decision-makers should treat outputs as directional under base assumptions of steady regulatory enforcement intensity and stable raw material alloy pricing; material deviation would warrant model refresh. Specific risk factors include tariff disruption to precision casting supply and accelerated EPA Method 1633 finalization timing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Life Sciences and Laboratory Equipment Market
Laboratory Equipment
Microplate Luminometer Market
Laboratory Equipment
Absorbance Micro Plate Reader Market
Laboratory Equipment
Global Laboratory Washers Market
Laboratory Equipment
Blood Processing and Storage Equipment Market
Laboratory Equipment
Global Automated Analyzers Market
Laboratory Equipment
Asia-Pacific Laboratory Hoods and Enclosure Market
Laboratory Equipment
Laboratory Ovens Market
Laboratory Equipment
UK Pipette Tips Market
Laboratory Equipment
Laboratory Freezers Market
Laboratory Equipment
Multi-Cuvette Spectrophotometer Market
Laboratory Equipment
Laboratory Rockers and Shakers Market
Laboratory Equipment
Multi Channel Hotplate Magnetic Stirrers Market
Laboratory Equipment
Automated Blood Processing Equipment Market
Laboratory Equipment
Hotplate Stirrers Market
Laboratory Equipment
Electrophoresis Transilluminator Market