
 Latin America Laboratory Equipment and Disposables Market | 2026-2036
Latin America Laboratory Equipment and Disposables Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Laboratory Equipment and Disposables Market Insights
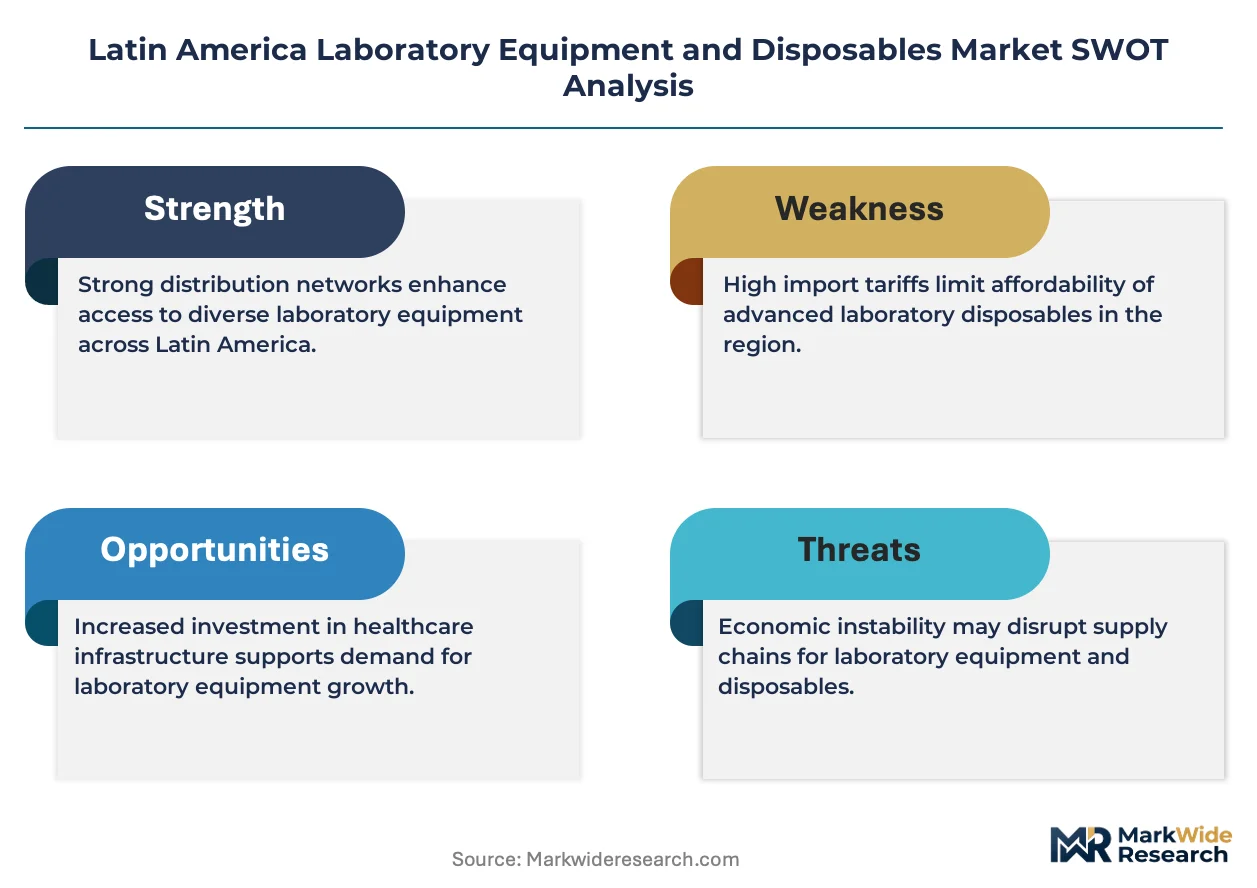
Project finance and equipment leasing is tilting competitive dynamics toward asset-light operators across Latin America. Thermo Fisher Scientific leverages its regional distribution network to sustain installed-base service contracts in Brazil and Mexico. Danaher anchors high-margin consumables revenue through localized reagent manufacturing. Agilent Technologies differentiates via chromatography application support teams embedded in Andean pharmaceutical hubs.
Latin America laboratory equipment and disposables encompass precision instruments, single-use plastics, glassware, reagents, and containment systems engineered to ISO 17025 metrological standards for analytical repeatability. These products enable quantitative measurement, sample preparation, biosafety containment, and quality control across regulated industries. Consumables capture recurring revenue streams through per-test disposables tied to installed analytical instruments. Pharmaceutical manufacturing applications command premium pricing due to GMP-validated traceability requirements. Direct sales channels dominate capital equipment transactions, while distributors occupy fragmented secondary markets where technical support infrastructure remains thin.
ANVISA in Brazil, COFEPRIS in Mexico, and INVIMA in Colombia enforce divergent medical device classification schemes that shape import registration costs and timeline risk for equipment suppliers. ISO 13485 certification and MDSAP recognition increasingly function as market access prerequisites rather than competitive differentiators. Stakeholders must monitor regulatory harmonization momentum under the Pacific Alliance framework and calibrate country prioritization against reimbursement pathway clarity.
Market Dynamics
Asset-light financing models are compressing capital equipment sales cycles across Brazil, Mexico, and Colombia, forcing manufacturers to restructure revenue recognition around multi-year service agreements rather than upfront instrument purchases.
Growth Catalysts
- ANVISA's accelerated registration pathway:Brazil's compressed medical device approval timelines are reducing time-to-market for imported diagnostic platforms by 8-12 months versus legacy procedures.
- Public-private consortia funding:São Paulo's biomedical research corridor is channeling state and federal resources into core facility infrastructure upgrades, creating concentrated demand clusters.
- Automated diagnostic platforms:Clinical research laboratories are expanding procurement of high-throughput analyzers to replace manual sample processing workflows.
Market Restraints
- Import dependency for precision components:Optical sensors and laser modules concentrate in German and Japanese supply bases, exposing Brazilian assemblers to currency volatility and extended lead times.
- Divergent classification schemes:ANVISA, COFEPRIS, and INVIMA enforce incompatible medical device risk categories, multiplying registration costs for suppliers seeking multi-country presence.
- Single-use plastic substitution pressure:Biodegradable alternatives lack ISO 17025-validated performance data, constraining adoption in GMP-regulated pharmaceutical manufacturing.
Strategic Opportunities
- Andean pharmaceutical manufacturing expansion:Colombia's INVIMA is streamlining GMP certification for contract manufacturing organizations, creating demand for validated chromatography and spectroscopy suites.
- Localized reagent production:Domestic manufacturing of assay-specific consumables reduces cold-chain logistics costs and shortens replenishment cycles for high-volume testing facilities.
- Pacific Alliance regulatory harmonization:Convergence of medical device standards across Chile, Colombia, Mexico, and Peru would collapse duplicate registration expenditures for regional suppliers.
Industry Challenges
- Metrology technician scarcity:ISO 17025-accredited calibration specialists remain concentrated in São Paulo and Mexico City, limiting service coverage in secondary Brazilian states and Central American markets.
- Legacy instrument integration complexity:Automated platforms must interface with 15-20 year-old laboratory information management systems prevalent in public hospital networks, extending deployment timelines.
- MDSAP audit preparation burden:Small and mid-sized distributors lack quality management infrastructure to satisfy simultaneous FDA, Health Canada, and ANVISA inspection requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Laboratory Equipment and Disposables Market |
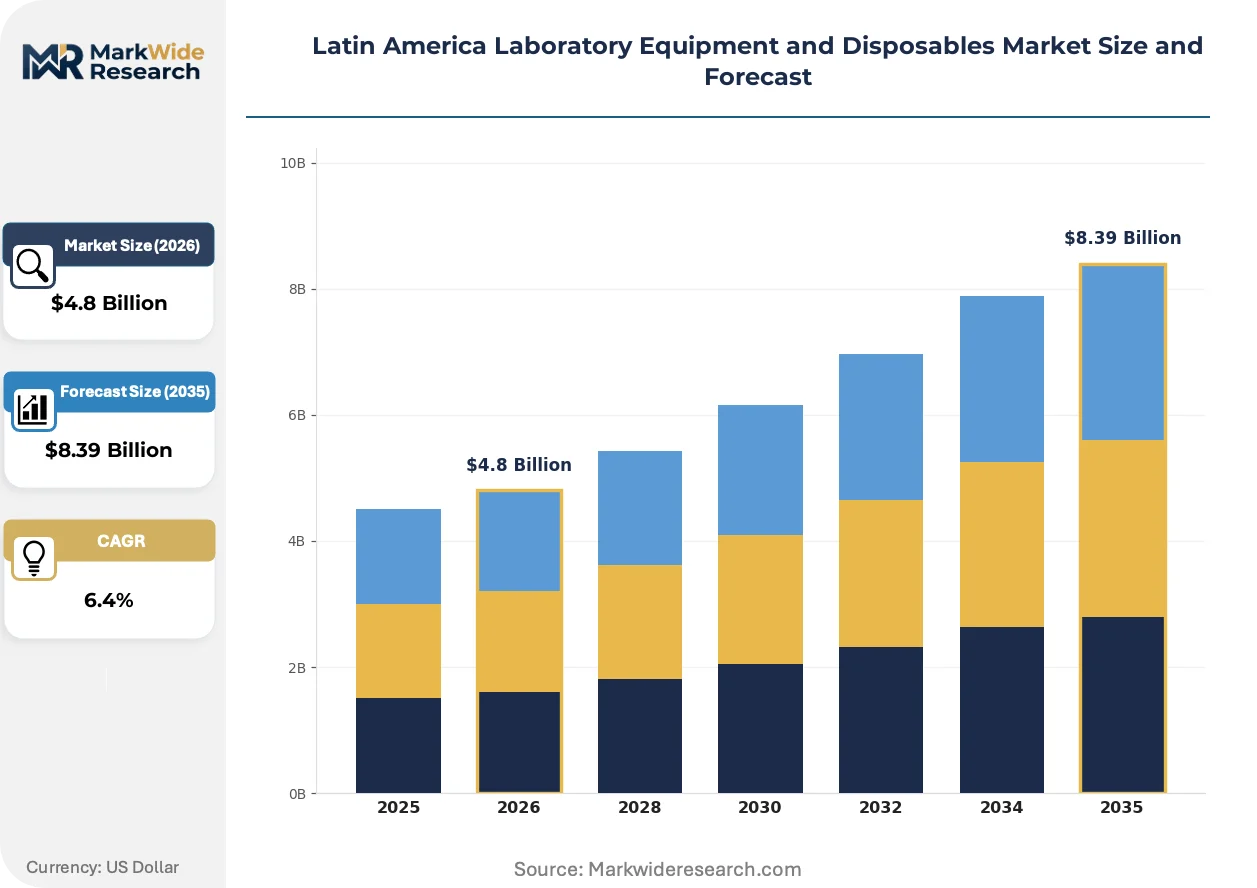
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consumables, Analytical Instruments, Laboratory Furniture, Safety Equipment Application: Clinical Research, Environmental Testing, Pharmaceutical Manufacturing, Academic Research End User: Hospitals, Pharmaceutical Companies, Research Institutions, Biotech Firms Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Thermo Fisher Scientific Inc, Agilent Technologies Inc, Danaher Corp, Bio-Rad Laboratories Inc, Sartorius AG, PerkinElmer Inc, Shimadzu Corp, Bruker Corp, Waters Corp, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Laboratory Equipment and Disposables Market Trends and Innovations
Digital connectivity architectures and modular instrument design are restructuring how laboratories acquire, maintain, and upgrade analytical capabilities across Latin America's fragmented procurement landscape.
Cloud-native laboratory information management systems are rendering obsolete on-premise server installations that previously required dedicated IT infrastructure and specialized maintenance contracts. Mid-sized clinical laboratories in Brazil's interior states are adopting subscription-based LIMS deployments faster than metropolitan counterparts due to constrained technical staffing. This shift is compressing total cost of ownership calculations and enabling remote diagnostic support from equipment manufacturers.
COFEPRIS in Mexico is mandating unique device identification traceability for Class II and III medical devices, aligning with FDA requirements under the MDR framework. Pharmaceutical manufacturers must now implement serialized labeling and electronic record systems for imported analyzers and consumables. Domestic distributors are consolidating to build compliance infrastructure, squeezing fragmented secondary-market operators lacking quality management certification.
Leasing arrangements with embedded maintenance clauses are displacing traditional capital purchase models among cash-constrained public health systems. State laboratories in Minas Gerais and Pernambuco are prioritizing operational expenditure flexibility over balance-sheet ownership of chromatography and mass spectrometry platforms. Equipment financiers are embedding themselves earlier in procurement cycles, reshaping vendor-customer relationships toward long-term partnership structures.
Latin America Laboratory Equipment and Disposables Market Segmentation
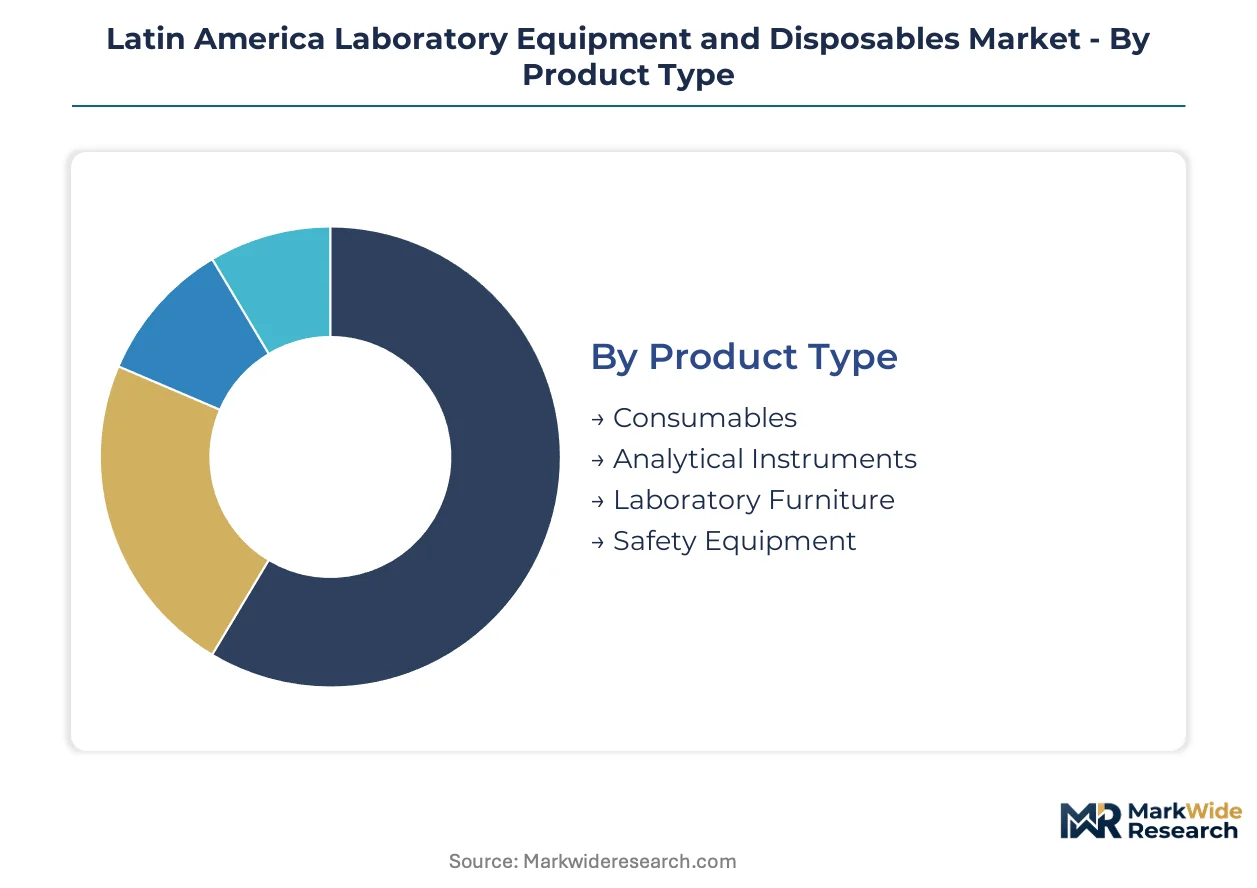
Segmentation in Latin America's laboratory equipment and disposables market reveals distinct procurement patterns across product maturity tiers and regulatory exposure levels. Each dimension exposes divergent margin structures, technical support requirements, and financing preferences that shape vendor go-to-market strategies.
Product Type:
Mature consumables categories coexist with emerging automated instrument platforms across Brazilian and Mexican procurement channels.
- Consumables:Single-use plastics, glassware, reagents, and containment systems engineered to ISO 17025 metrological standards. Demand concentrates in São Paulo's biomedical research corridor where public-private consortia fund high-throughput testing facilities with per-test disposables tied to installed analyzers.
- Analytical Instruments:Chromatography systems, spectroscopy platforms, and automated diagnostic analyzers requiring GMP-validated traceability. Pharmaceutical manufacturing applications in Colombia's INVIMA-regulated contract manufacturing organizations command premium pricing due to validation documentation requirements.
- Laboratory Furniture:Biosafety cabinets, fume hoods, and modular casework systems.
- Safety Equipment:Personal protective equipment and containment systems for biosafety level compliance.
Consumables retain volume leadership; analytical instruments hold the steepest expansion curve.
Application:
Cost tier differentiation separates regulated pharmaceutical applications from price-sensitive academic procurement.
- Clinical Research:Diagnostic testing workflows and patient sample analysis in hospital-affiliated laboratories. Brazilian clinical research laboratories are expanding procurement of automated diagnostic platforms to replace manual sample processing, with ANVISA's accelerated registration pathway reducing time-to-market for imported analyzers.
- Pharmaceutical Manufacturing:Quality control and batch release testing under GMP-validated protocols. Andean pharmaceutical manufacturing expansion in Colombia is streamlining GMP certification for contract manufacturing organizations, creating demand for validated chromatography and spectroscopy suites.
- Environmental Testing:Water quality, soil analysis, and air monitoring applications.
- Academic Research:Basic science and translational research in university core facilities.
Clinical research commands installed-base density; pharmaceutical manufacturing delivers margin premiums.
End User:
Customer type segmentation exposes divergent technical support requirements and financing capacity across Latin American markets.
- Pharmaceutical Companies:Multinational and domestic manufacturers requiring GMP-validated equipment with full documentation packages. These buyers prioritize localized reagent production to reduce cold-chain logistics costs and shorten replenishment cycles for high-volume testing facilities.
- Research Institutions:University core facilities and government research centers. Asset-light financing models are compressing capital equipment sales cycles, forcing manufacturers to restructure revenue recognition around multi-year service agreements rather than upfront instrument purchases.
- Hospitals:Public and private clinical diagnostic laboratories.
- Biotech Firms:Emerging domestic biotechnology companies with venture-backed funding.
Pharmaceutical companies anchor premium segment value; research institutions drive volume through consortia funding.
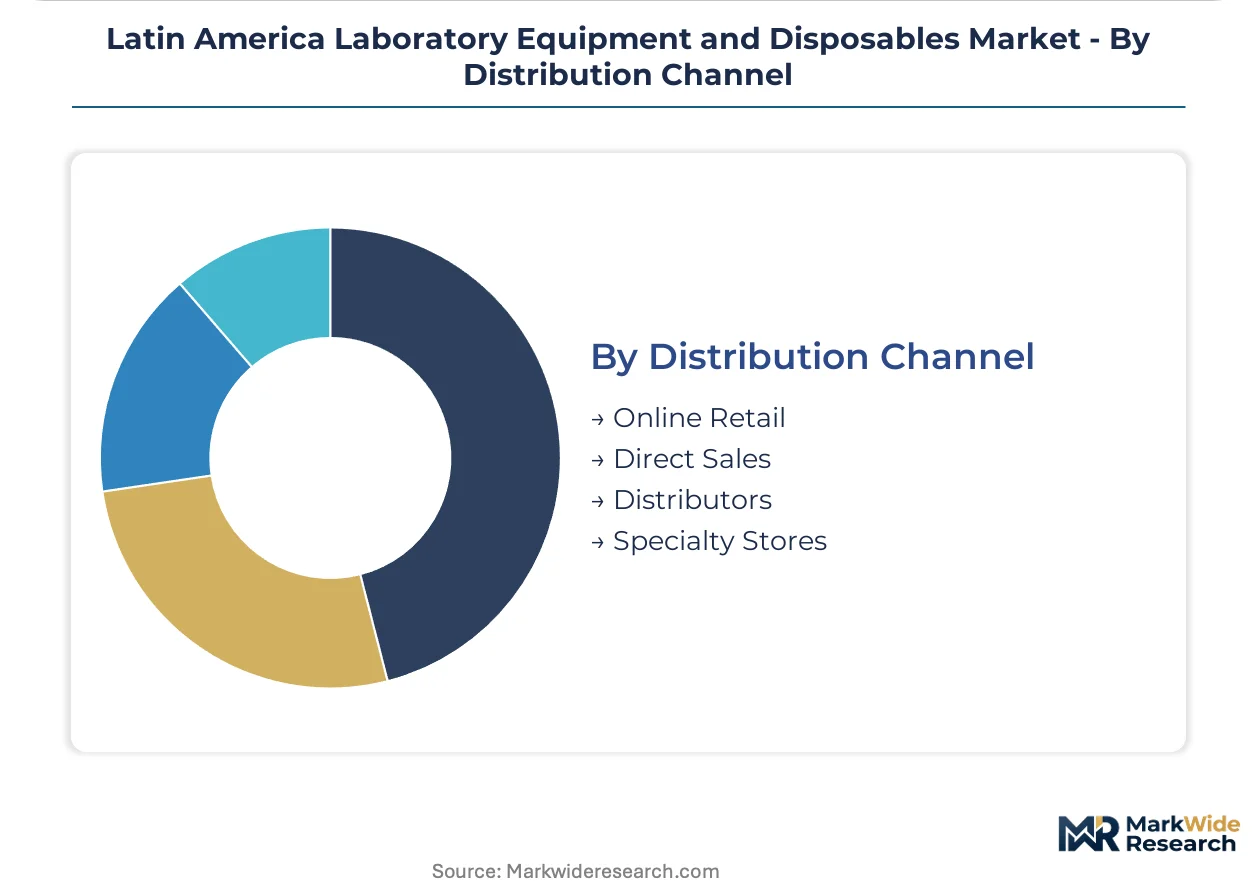
Distribution Channel:
Supply concentration varies between direct technical engagement and fragmented distributor networks.
- Direct Sales:Capital equipment transactions with embedded application support and long-term service contracts. Direct sales channels dominate capital equipment transactions in metropolitan markets where technical support infrastructure is established.
- Distributors:Fragmented secondary markets across Brazilian interior states and Central American markets. Distributors occupy markets where metrology technician scarcity limits manufacturer direct coverage, with COFEPRIS-mandated unique device identification traceability consolidating compliant operators.
- Online Retail:Standardized consumables and replacement parts procurement.
- Specialty Stores:Regional laboratory supply retailers serving small-scale operations.
Direct sales capture instrument margin; distributors extend geographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA's accelerated registration pathway compresses approval timelines for imported diagnostic platforms across Latin America, while Pacific Alliance regulatory harmonization momentum reshapes multi-country market access economics for equipment suppliers.
Brazil
São Paulo's biomedical research corridor channels state and federal resources into core facility infrastructure upgrades, creating concentrated demand clusters for automated diagnostic platforms. ANVISA's updated medical device registration pathways reduce time-to-market for imported analyzers by 8-12 months versus legacy procedures. Public-private consortia in São Paulo fund high-throughput testing facilities with per-test consumables tied to installed instruments.
Mexico
COFEPRIS mandates unique device identification traceability for Class II and III medical devices, aligning with FDA requirements under the MDR framework. Pharmaceutical manufacturers must implement serialized labeling and electronic record systems for imported analyzers. Domestic distributors consolidate to build compliance infrastructure, squeezing fragmented secondary-market operators lacking quality management certification.
Colombia
INVIMA streamlines GMP certification for contract manufacturing organizations, creating demand for validated chromatography and spectroscopy suites. Andean pharmaceutical manufacturing expansion drives premium pricing for equipment with validation documentation requirements. Bogotá's pharmaceutical manufacturing corridor attracts multinational quality control investment.
Chile
Pacific Alliance regulatory convergence discussions position Chile as a harmonization testbed for medical device standards. Santiago's mining laboratories drive demand for environmental testing equipment and analytical instruments. The country's central bank stability reduces currency volatility exposure for precision component imports compared to regional peers.
Argentina
Import dependency for optical sensors and laser modules exposes Argentine assemblers to extended lead times from German and Japanese supply bases. Buenos Aires academic research institutions drive volume through consortia funding despite constrained public health budgets. Metrology technician scarcity limits service coverage outside the capital region.
Latin America Laboratory Equipment and Disposables Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Latin America's fragmented procurement landscape. Thermo Fisher Scientific leverages its regional distribution network to sustain installed-base service contracts in Brazil and Mexico, while Danaher anchors high-margin consumables revenue through localized reagent manufacturing. Three archetypes dominate: full-line distributors with technical service infrastructure, consumables specialists with captive reagent production, and application-focused instrument vendors with embedded support teams. Equipment financiers embed themselves earlier in procurement cycles, reshaping vendor-customer relationships toward long-term partnership structures.
Among the named players, Thermo Fisher Scientific Inc and Danaher Corp exemplify the integrated platform archetype combining instrument placement with recurring consumables revenue. Agilent Technologies Inc occupies a position emphasizing chromatography application support teams embedded in Andean pharmaceutical hubs. These three represent divergent strategic postures toward Latin America's laboratory equipment and disposables market: geographic coverage depth, vertical integration into reagent manufacturing, and specialized application expertise respectively.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc |
| Agilent Technologies Inc |
| Danaher Corp |
| Bio-Rad Laboratories Inc |
| Sartorius AG |
| PerkinElmer Inc |
| Shimadzu Corp |
| Bruker Corp |
| Waters Corp |
| Others |
Pricing and Supply Chain Analysis
German and Japanese optical sensor suppliers anchor upstream concentration for precision analytical components, directing margin capture toward distributors with captive service infrastructure rather than instrument assemblers exposed to currency volatility.
Pricing Analysis
Certification level creates the primary spread across Latin America's laboratory equipment procurement, with ANVISA-registered Class III diagnostic platforms commanding substantial premiums over unregistered imports. Pricing stratifies across GMP-validated pharmaceutical manufacturing suites, ISO 17025-accredited research instrumentation, and economy-tier academic equipment lacking traceability documentation. Cost compression in the mid-tier standard segment is intensifying as Brazilian public health systems shift toward operational expenditure models. Academic research institutions exhibit the highest price sensitivity due to constrained federal funding, while multinational pharmaceutical manufacturers prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Flex, Jabil, and Sanmina hold contract manufacturing capacity for analytical instrument subassemblies serving Latin American markets. Precision optics and laser modules draw from Japanese and German supply bases, while single-use plastics and molded consumables source from Mexican and Colombian polymer processors. Single-source vulnerability concentrates in optical sensor supply chains, where replacement qualification cycles extend deployment timelines. Distribution runs through direct sales channels for capital equipment in São Paulo and Mexico City, with authorized distributors extending coverage into secondary Brazilian states and Central American markets lacking metrology technician density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refurbished and reconditioned instrument platforms threaten incumbent revenue streams as Brazilian public laboratories prioritize operational expenditure flexibility over capital ownership.
For Market Incumbents: Insulate installed-base service contracts through embedded application support teams and multi-year maintenance agreements that raise switching costs for Brazilian clinical research laboratories. Capture backward integration into localized reagent manufacturing to reduce cold-chain logistics exposure and shorten replenishment cycles for high-volume testing facilities. Defend against leasing-company disintermediation by embedding equipment financiers earlier in procurement cycles. For New Entrants and Emerging Players: Pursue white-space opportunity in Colombia's INVIMA-streamlined contract manufacturing organization segment, where GMP certification momentum outpaces established vendor coverage. Target Andean pharmaceutical manufacturing corridors with chromatography application support teams that incumbent distributors lack technical depth to field. Enter through cloud-native laboratory information management system subscriptions that bypass capital equipment barriers in Brazil's interior states. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional distributors consolidating to meet COFEPRIS-mandated unique device identification traceability requirements. Long-term viability hinges on service contract attach rates rather than instrument placement volume. Watch Pacific Alliance regulatory harmonization momentum as the inflection signal for multi-country registration cost collapse.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Reagent Manufacturing | Captures recurring consumables revenue while reducing ANVISA import dependency for Brazilian high-throughput facilities. |
| Cloud-Native LIMS Deployment | Enables subscription-based market entry in secondary Brazilian states lacking dedicated IT infrastructure. |
| Andean Pharmaceutical Hub Partnership | Positions chromatography vendors for INVIMA-streamlined GMP certification demand in Colombia's manufacturing corridor. |
| Multi-Year Service Agreement Restructuring | Transforms revenue recognition from upfront capital sales to recurring operational expenditure models favored by public health systems. |
| Pacific Alliance Regulatory Harmonization Alignment | Collapses duplicate registration expenditures across Chile, Colombia, Mexico, and Peru for first-mover suppliers. |
Research Methodology
A standing panel of laboratory directors, biomedical procurement managers, ANVISA regulatory consultants, and aftermarket service heads provided ongoing calibration throughout the study period. Primary interviews with equipment manufacturers and distributor principals combined with secondary validation against customs import records, ANVISA registration databases, and hospital procurement disclosures. Bottom-up instrument shipment tracking and top-down healthcare expenditure analysis enabled triangulation across independent data streams.
Scenario bracketing anchored the analytical framework, with volume and value outputs reflecting cross-validation across product type, application, end user, and distribution channel dimensions throughout the projection horizon. CAGRs derived from installed-base growth modeling and consumables attach-rate analysis incorporated pharmaceutical manufacturing expansion trajectories in Colombia and public health system leasing adoption curves in Brazil.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real volatility or Mexican peso stability would shift the trajectory of import-dependent precision component procurement. Forecasts reflect documented assumptions regarding regulatory harmonization momentum and public-private consortia funding continuity. Cross-checking against Pacific Alliance medical device registration flow data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Microplate Washer Market
Laboratory Equipment
Global Pipette Tips Market
Laboratory Equipment
Global Laboratory Washers Market
Laboratory Equipment
Hemostasis Analyzers Market
Laboratory Equipment
Centrifuge Tubes Market
Laboratory Equipment
Life Sciences and Laboratory Equipment Market
Laboratory Equipment
Western Blotting Processors Market
Laboratory Equipment
Laboratory Ovens Market
Laboratory Equipment
Microplate Handling Instruments Market
Laboratory Equipment
Global Hematocrit Test Devices Market
Laboratory Equipment
Global Microplate System Market
Laboratory Equipment
Microplate Instrumentation and Supplies Market
Laboratory Equipment
Beaker Market
Laboratory Equipment
Mobile Sterile Units Market
Laboratory Equipment
Global Laboratory Hoods and Enclosure Market
Laboratory Equipment
Human Milk Analyzers Market