
 Eubiotics Market | 2026-2036
Eubiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Eubiotics Market Analysis
Precision fermentation for probiotic strain cultivation is fragmenting traditional batch-processing economics across the eubiotics supply chain. BASF SE leverages its industrial biotechnology infrastructure to anchor European production of microbial feed additives. Cargill Incorporated sustains North American market presence through backward integration into grain-derived prebiotic substrates. Koninklijke DSM NV differentiates via specialty enzyme-probiotic combinations that command premium positioning in ruminant nutrition.
Eubiotics comprise live microorganisms, fermentable fibers, and organic acid compounds formulated to modulate gut microbiota and enhance nutrient absorption in production animals. These additives typically contain defined colony-forming units per gram, require controlled-temperature stabilization, and serve primarily to replace antibiotic growth promoters in intensive livestock systems. Probiotics and prebiotics together absorb the dominant share of value as regulatory bans on sub-therapeutic antibiotics expand across major protein-producing regions. Organic acids retain mature, cost-competitive positioning in swine starter diets where pH modulation delivers immediate feed conversion benefits. Synbiotics represent the fastest-expanding category as combination formulations demonstrate additive efficacy in aquaculture and young ruminant applications.
The European Food Safety Authority evaluates novel microbial strains through standardized Qualified Presumption of Safety protocols, while the U.S. FDA exercises enforcement discretion over direct-fed microbials under its GRAS framework. China's Ministry of Agriculture and Rural Affairs maintains a positive-list approach for feed additive registration, creating asymmetric market access timelines across jurisdictions. Feed manufacturers and livestock operators must monitor divergence between EU strain-approval requirements and emerging microbiome-targeted regulatory pathways in major protein-exporting nations.
Market Dynamics
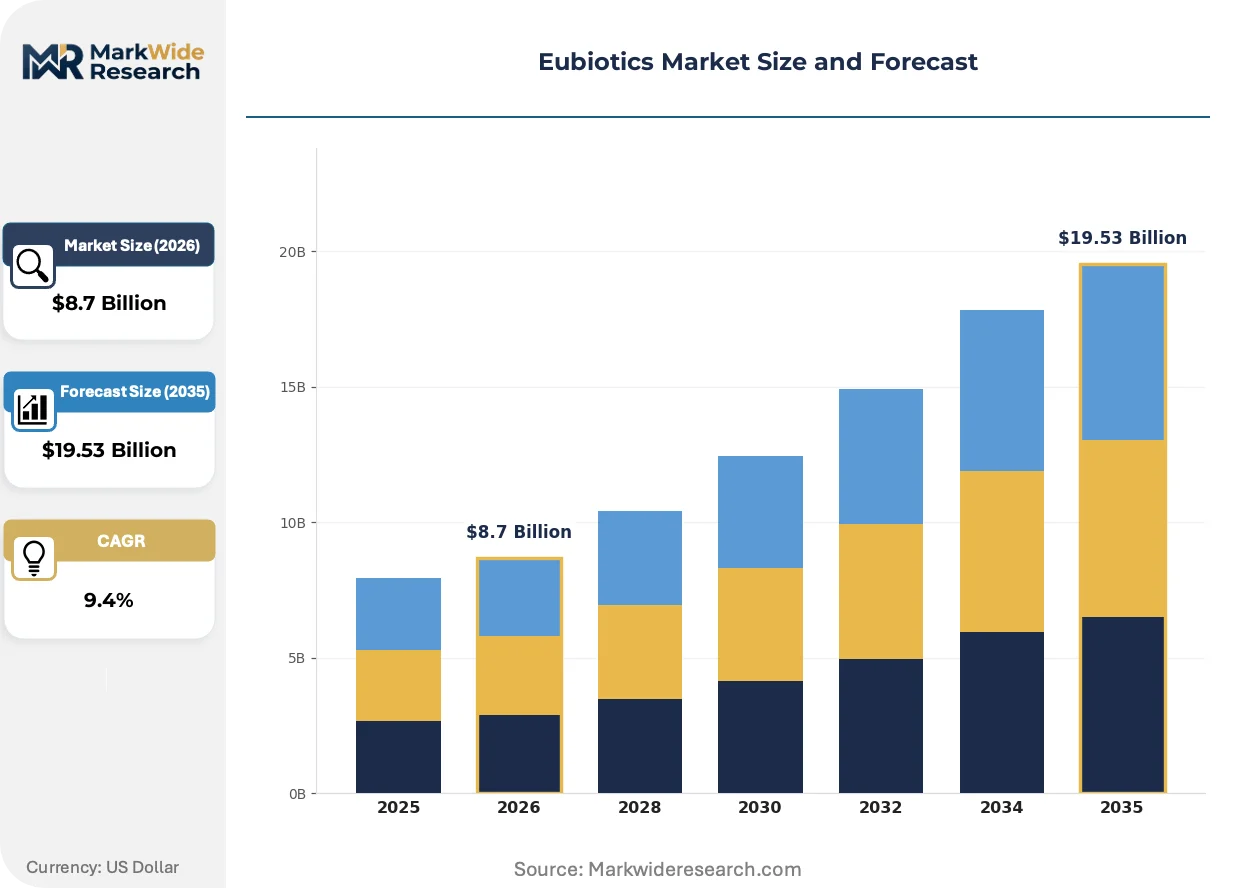
Precision fermentation infrastructure is fragmenting traditional batch-processing economics across the eubiotics supply chain, forcing feed additive manufacturers to reconfigure capital deployment toward continuous bioreactor systems and strain-specific cultivation protocols.
Growth Catalysts
- EU F-Gas Regulation:The European Union's tightening environmental standards for industrial fermentation processes are accelerating capital flows into closed-system bioreactor technologies that reduce greenhouse gas emissions during probiotic strain production.
- Poultry operations in Brazil:Livestock producers are expanding probiotic formulations to reduce antibiotic dependence, creating sustained demand pull for multi-strain microbial additives in intensive broiler systems.
- Precision nutrition protocols:China's domestic pork producers are rebuilding herds with microbiome-targeted feeding regimes that integrate prebiotic-probiotic combinations into automated ration delivery systems.
Market Restraints
- Strain-approval asymmetry:Divergent Qualified Presumption of Safety protocols between EFSA and China's positive-list approach create elongated registration timelines that lock manufacturers out of priority markets for 18-36 months.
- Feed-grade substrate concentration:Backward integration into grain-derived prebiotic substrates by North American agribusiness conglomerates limits independent additive producers' access to cost-competitive fermentable fiber supply.
- Thermostability limitations:Current generation live microbial products face viability degradation above 45°C during pelleting processes, restricting formulation options for high-temperature feed manufacturing in tropical climates.
Strategic Opportunities
- Aquaculture synbiotics:Combination formulations demonstrating additive efficacy in shrimp and salmonid operations represent underpenetrated white space as marine protein producers seek alternatives to antibiotic bath treatments.
- Young ruminant applications:Calf-raising operations in dairy-intensive regions present expansion potential for specialty enzyme-probiotic combinations that command premium positioning through documented mortality reduction.
- REACH framework adaptation:Feed additive manufacturers that pre-position microbial strain portfolios for ECHA substance evaluation protocols can capture first-mover advantage as environmental release assessments become mandatory for novel microbiome modulators.
Industry Challenges
- Microbiome analytical talent scarcity:Commercialization of next-generation sequencing for strain efficacy validation requires molecular biology capabilities that outpace current technical training pipelines in major manufacturing regions.
- Controlled-temperature logistics capex:Defined colony-forming unit stability requirements demand cold-chain infrastructure investments that compress margins for mid-scale producers serving dispersed livestock operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eubiotics Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Prebiotics, Synbiotics, Organic Acids Application: Poultry, Swine, Ruminants, Aquaculture Form: Powder, Liquid, Granules, Capsules End User: Farmers, Feed Manufacturers, Pet Owners, Veterinary Clinics |
| Companies Covered | BASF SE, Cargill Incorporated, Koninklijke DSM NV, Novus International Inc., Lesaffre Group, Kemin Industries Inc., Lallemand Inc., Chr. Hansen Holding A/S, Novozymes A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eubiotics Market Emerging Trajectories
Bioprocess automation and microbiome analytics are converging to reshape how feed additive manufacturers develop, validate, and commercialize microbial strain portfolios for intensive livestock systems.
Single-use bioreactor systems with integrated sensor arrays are digitizing strain cultivation workflows by enabling real-time metabolite monitoring and adaptive feeding protocols. Contract fermentation facilities serving mid-tier additive producers are adopting these platforms to compress batch cycle times and reduce cross-contamination risk during multi-strain campaigns. The technology is digitizing quality assurance documentation, allowing manufacturers to generate regulatory-compliant batch records automatically rather than through manual sampling and laboratory analysis.
REACH framework amendments targeting microbial substances used in animal feed are forcing manufacturers to submit comprehensive environmental fate studies for novel probiotic strains. ECHA's expanded data requirements for biodegradation and ecotoxicity assessments are extending pre-market preparation timelines by 12-18 months for strains lacking prior industrial chemical registrations. European compound feed manufacturers are responding by consolidating supplier relationships toward established players with dedicated regulatory affairs capabilities and existing substance dossiers.
Integrated feed-to-farm data platforms are compressing the feedback loop between additive efficacy claims and procurement decisions. Large-scale poultry and swine operators in protein-exporting nations are demanding strain-specific performance data tied to individual barn-level outcomes rather than accepting aggregate trial results. This behavioral shift is displacing traditional technical sales relationships with outcome-verification contracts that link additive pricing to documented feed conversion improvements measured through automated weighing systems.
Eubiotics Market Segmentation
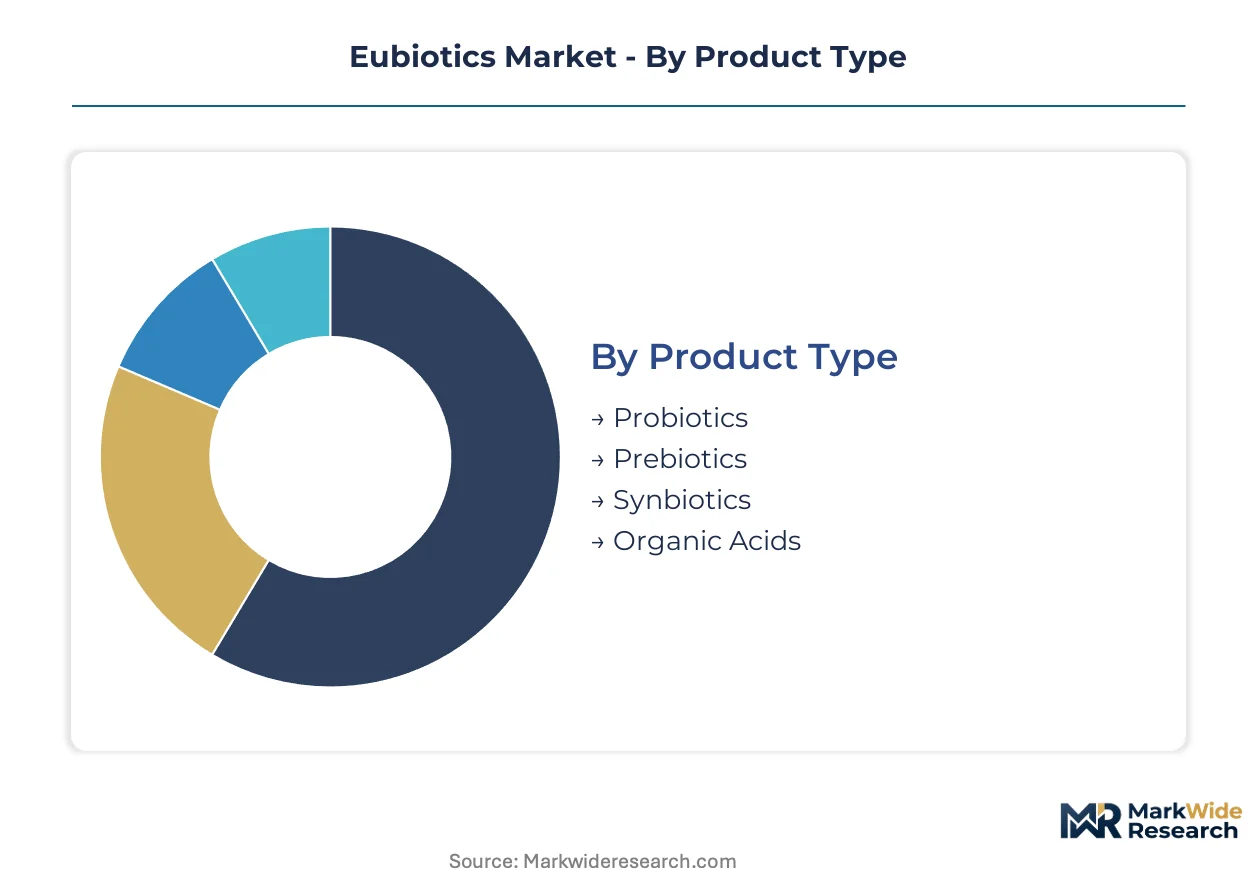
Eubiotics segmentation reflects divergent biological stability requirements across product categories and species-specific digestive physiology. Formulation choices directly constrain manufacturing capital allocation and cold-chain logistics intensity.
Product Type:
Cycle times vary dramatically: live microbial products require continuous cultivation and rapid distribution, while organic acid compounds tolerate extended storage and slower inventory turns.
- Probiotics:Defined colony-forming unit preparations of live bacteria and yeast strains require controlled-temperature stabilization from fermentation through feed incorporation. Demand concentrates in Brazilian poultry operations where producers seek antibiotic alternatives under ANVISA guidance.
- Prebiotics:Fermentable oligosaccharides and resistant starch derivatives derived from grain substrates bypass viability constraints entirely. Chinese pork producers rebuilding herds through precision nutrition protocols are absorbing expanding volumes of inulin and fructooligosaccharide formulations.
- Synbiotics:Combination formulations pairing live microorganisms with selective growth substrates are climbing the fastest as aquaculture operators document mortality reduction in shrimp and salmonid applications.
- Organic Acids:Buffered propionate, formate, and citrate blends deliver immediate pH modulation without biological degradation risk during pelleting above 45°C.
Organic acids dominate installed base. Synbiotics are where expansion concentrates.
Application:
Species-specific digestive tract morphology dictates formulation complexity and dosing economics across livestock categories.
- Poultry:Short digestive transit times demand high-concentration probiotic delivery and thermostable strain selection for broiler operations facing EU import standards.
- Swine:Starter diet pH modulation drives organic acid consumption, while sow gestation protocols integrate prebiotic fermentable fibers for offspring microbiome priming.
- Ruminants:Multi-compartment stomach physiology requires specialty enzyme-probiotic combinations commanding premium positioning in calf-raising operations.
- Aquaculture:Water-immersion delivery systems for shrimp and finfish represent underpenetrated white space as producers phase out antibiotic bath treatments.
Poultry commands current volume leadership. Aquaculture presents the steepest expansion trajectory.
Form:
Physical presentation determines compatibility with automated feed manufacturing and tropical climate distribution.
- Powder:Standardized particle size distributions optimize homogeneity in mash and pelleted feeds, though dust generation complicates handling.
- Liquid:Pumpable concentrates suit integrated operations with on-farm micro-dosing systems and aqueous feed delivery infrastructure.
- Granules:Fluid-bed agglomeration protects viable cells from thermal damage during high-temperature pelleting processes.
- Capsules:Enteric-coated presentations target young ruminant applications where abomasal bypass delivers live cultures to intestinal colonization sites.
Powder formulations anchor manufacturing scale. Granules are gaining share fastest in tropical feed milling regions.
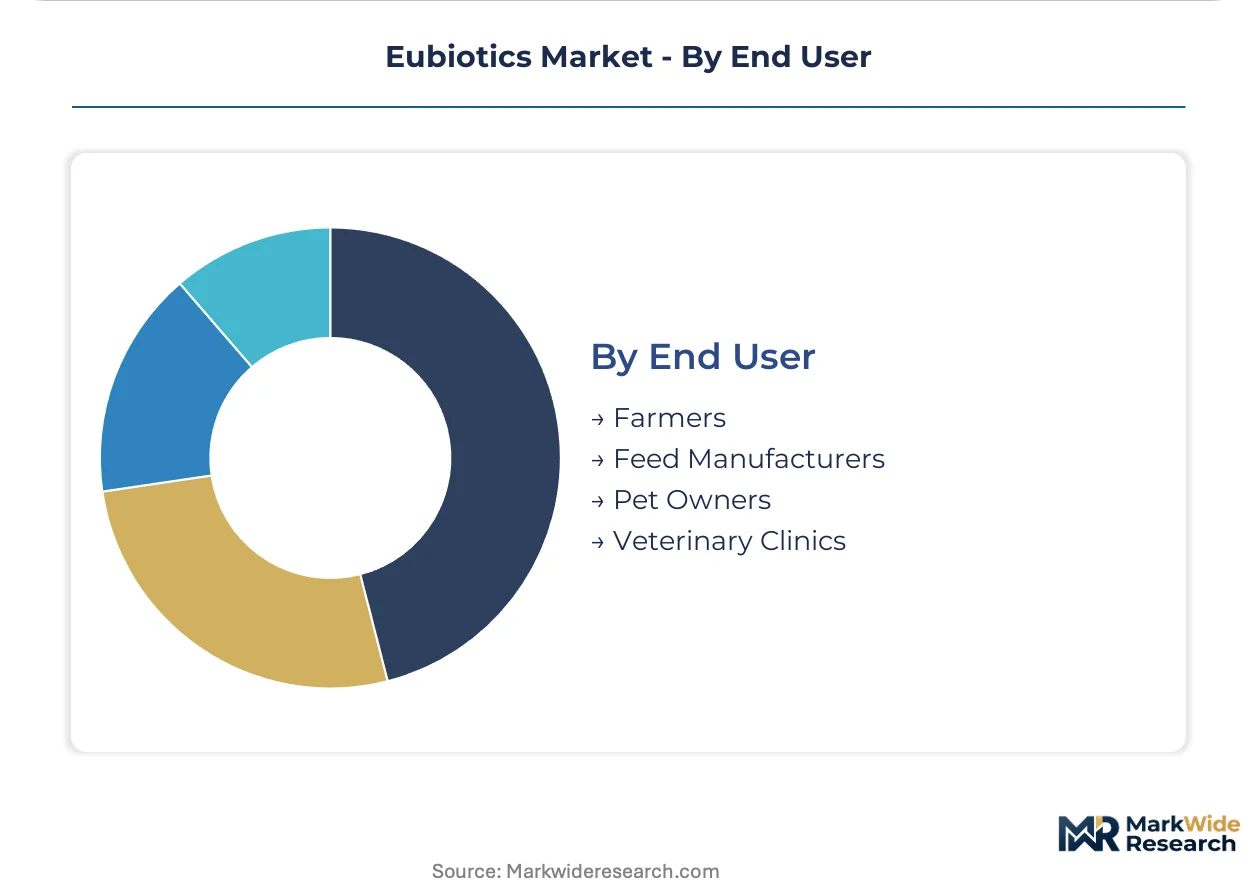
End User:
Procurement sophistication varies from commodity spot purchasing to outcome-verification contracting tied to feed conversion metrics.
- Farmers:Direct acquisition concentrates in large-scale vertically integrated operations with internal nutrition teams and automated barn-level data systems.
- Feed Manufacturers:Compound feed producers consolidate supplier relationships toward established players with REACH-compliant substance dossiers and dedicated regulatory affairs capabilities.
- Pet Owners:Companion animal applications remain peripheral to production livestock economics, though premium positioning supports margin capture.
- Veterinary Clinics:Therapeutic probiotic prescriptions for individual animal treatment occupy niche positioning outside bulk feed additive flows.
Feed manufacturers dominate procurement volume. Farmers are where contracting innovation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in eubiotics track divergent regulatory timelines and livestock production intensification. Markets with faster strain-approval pathways attract manufacturing investment, while deficit regions absorb cross-border shipments of stabilized live microbial products.
China
Domestic pork producers rebuilding herds after disease outbreaks are absorbing expanding volumes of prebiotic-probiotic combinations through precision nutrition protocols. The Ministry of Agriculture and Rural Affairs maintains a positive-list approach for feed additive registration, creating elongated timelines for novel strain introductions. Shandong Peninsula industrial clusters host fermentation facilities supplying North Asian compound feed manufacturers with thermostable microbial preparations.
Brazil
Intensive broiler operations are expanding probiotic formulations to reduce antibiotic dependence under ANVISA guidance, creating sustained demand pull for multi-strain additives. The national health surveillance agency aligns with international Codex standards while maintaining country-specific efficacy documentation requirements. São Paulo state concentrates feed manufacturing capacity where backward integration into grain substrates supports cost-competitive prebiotic production.
Germany
Specialty enzyme-probiotic combinations command premium positioning in dairy-intensive regions where calf-raising operations document mortality reduction. EFSA Qualified Presumption of Safety protocols and ECHA REACH framework amendments impose 12-18 month pre-market preparation extensions for environmental fate studies. Bavaria anchors European production of microbial feed additives through industrial biotechnology infrastructure serving compound feed manufacturers consolidating supplier relationships.
United States
Large-scale vertically integrated poultry and swine operators are demanding strain-specific performance data tied to barn-level outcomes rather than aggregate trial results. FDA enforcement discretion over direct-fed microbials under GRAS framework permits faster commercialization than EFSA pathways. Midwest grain belt regions supply fermentable fiber substrates to captive prebiotic production operations controlled by agribusiness conglomerates.
Netherlands
Marine protein producers in coastal aquaculture zones are phasing out antibiotic bath treatments in favor of synbiotic formulations for shrimp and salmonid operations. EU F-Gas Regulation tightening environmental standards for industrial fermentation accelerates capital flows into closed-system bioreactor technologies. Randstad logistics corridors enable cold-chain distribution of defined colony-forming unit preparations to northwest European livestock operations.
Eubiotics Market Vendor Landscape
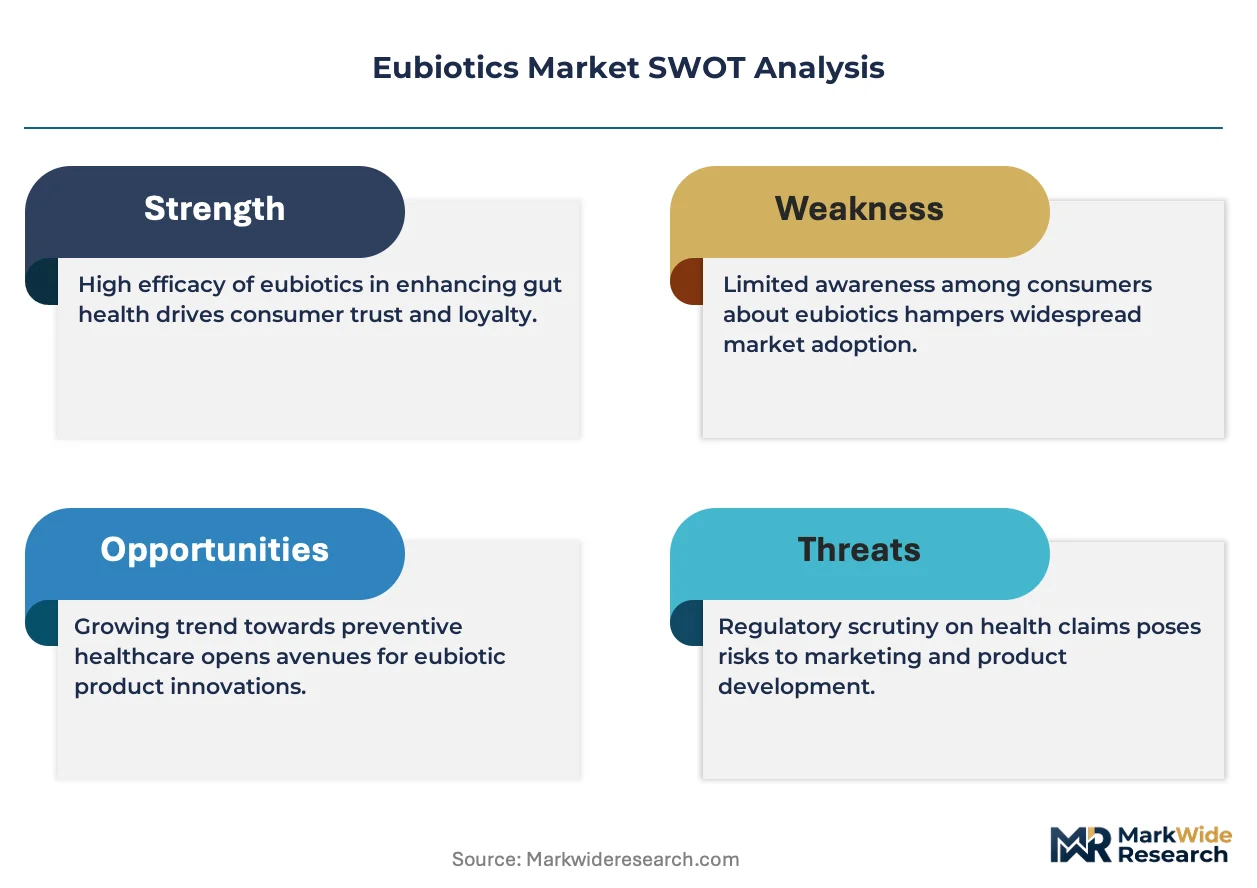
On the supply side, the industry is consolidating around established players with dedicated regulatory affairs capabilities and existing substance dossiers. Mid-scale producers face margin compression from cold-chain infrastructure investments required for live microbial stability. Three archetypes dominate: diversified chemical conglomerates with industrial biotechnology infrastructure, grain-trading agribusinesses with backward integration into prebiotic substrates, and specialty fermentation houses with strain-specific cultivation expertise. Competitive moves concentrate on capacity expansion into continuous bioreactor systems and strategic partnerships for microbiome analytics capabilities.
Among diversified chemical conglomerates, BASF SE anchors European production through captive industrial biotechnology infrastructure. Cargill Incorporated exemplifies the agribusiness archetype with upstream control over grain-derived substrate supply chains. Koninklijke DSM NV occupies a position within the specialty nutrition tier, differentiating through enzyme-probiotic combination formulations. These three entities represent distinct strategic postures without implying specific market share positions or comparative performance metrics.
| Leading Market Players |
|---|
| BASF SE |
| Cargill Incorporated |
| Koninklijke DSM NV |
| Novus International Inc. |
| Lesaffre Group |
| Kemin Industries Inc. |
| Lallemand Inc. |
| Chr. Hansen Holding A/S |
| Novozymes A/S |
| Others |
Supply Flow & Price Mechanics
Grain-derived prebiotic substrate concentration in the US Midwest and Shandong Peninsula fermentation clusters concentrates upstream margin capture among agribusiness conglomerates with captive supply chains, forcing independent additive producers to absorb cold-chain logistics costs that compress working capital cycles.
Pricing Analysis
Feed manufacturers anchor eubiotics pricing through three-tier structures across premium, standard, and economy levels. Price differentiation rests on thermostability certification grades and REACH-compliant substance dossiers rather than raw strain potency. Cost compression in standard-tier organic acids is intensifying because Brazilian poultry operators are consolidating procurement volumes toward multi-year contracts. Smallholder livestock operations in tropical climates exhibit highest price sensitivity due to unviable cold-chain infrastructure, while vertically integrated protein exporters accept premium positioning for strain-specific performance guarantees.
Supply Chain Analysis
Contract fermentation capacity concentrates among Bavarian industrial biotechnology parks and Randstad corridor facilities serving European compound feed manufacturers. Raw material flows draw from North American grain belts for prebiotic substrates, Chinese corn processing regions for oligosaccharide feedstocks, and Nordic fishmeal operations for aquaculture applications. Single-source vulnerability persists in thermostable strain cultivation where proprietary bioreactor protocols limit qualified supplier pools. Distribution runs through compound feed manufacturers consolidating toward established players with ECHA-compliant environmental fate dossiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The eubiotics market is cycling through a livestock herd rebuilding phase as Chinese pork producers restock operations and Brazilian broiler integrators expand capacity under antibiotic-reduction mandates.
For Market Incumbents: Pre-empt strain-approval bottlenecks by accelerating EFSA Qualified Presumption of Safety dossier preparation ahead of REACH framework amendments targeting microbial substances. Secure backward integration into grain-derived prebiotic substrates to defend margin position against agribusiness conglomerates consolidating upstream supply. Prioritize continuous bioreactor capacity additions in Bavaria and Shandong Peninsula clusters where environmental compliance infrastructure is pre-positioned. For New Entrants and Emerging Players: Establish a beachhead in aquaculture synbiotics for shrimp and salmonid operations where antibiotic bath treatment phase-out creates immediate demand pull. Target young ruminant applications in dairy-intensive regions where specialty enzyme-probiotic combinations command premium positioning through documented mortality reduction. Pursue outcome-verification contracting models that link additive pricing to automated feed conversion metrics rather than traditional technical sales relationships. For Investors and Strategic Acquirers: Capital is best deployed toward specialty fermentation houses with strain-specific cultivation expertise and existing microbiome analytics partnerships rather than diversified chemical conglomerates where eubiotics represent non-core revenue. Long-term viability across the projection horizon hinges on regulatory affairs capabilities that compress 18-36 month strain-approval asymmetries between EFSA and China's positive-list approach. Monitor quarterly ECHA substance evaluation protocol announcements as inflection indicators for first-mover advantage capture.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Bioreactor Capacity Expansion | BASF SE and Bavarian industrial clusters reduce EFSA compliance timelines through closed-system fermentation infrastructure. |
| Backward Integration into Prebiotic Substrates | Cargill Incorporated secures cost-competitive inulin and fructooligosaccharide supply from captive Midwest grain processing. |
| REACH Framework Pre-Positioning | Koninklijke DSM NV captures first-mover advantage by submitting environmental fate studies for novel microbial strains ahead of ECHA mandates. |
| Aquaculture Synbiotic Partnership | Netherlands marine protein producers phase out antibiotic bath treatments through combination formulations for shrimp mortality reduction. |
| Microbiome Analytics Acquisition | Mid-tier additive producers compress strain efficacy validation cycles through next-generation sequencing capability integration. |
Methodological Framework
A spread of perspectives from fermentation plant managers, compound feed procurement leads, regulatory affairs directors at additive manufacturers, and veterinary nutritionists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through EFSA strain-approval databases, ECHA REACH substance dossiers, ANVISA efficacy documentation requirements, and customs trade flows for feed-grade prebiotic substrates. Bottom-up strain-level demand estimates triangulated against top-down livestock production forecasts across the projection horizon.
Demand-supply balance modeling segmented the eubiotics market by product category, livestock application, physical form, and procurement sophistication tier across the analysis window. CAGRs were derived from livestock production intensity trajectories, regulatory ban implementation schedules, and precision nutrition adoption curves rather than extrapolated historical trends. Industry-specific forecast inputs incorporated thermostability degradation curves during tropical pelleting processes and cold-chain logistics cost compression factors for live microbial distribution.
Stress conditions across EFSA-China strain-approval timeline divergences, grain substrate price volatility, and aquaculture disease outbreak frequencies were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway convergence and livestock herd rebuilding velocities. Quarterly review of ECHA substance evaluation announcements, ANVISA guidance updates, and automated feed-to-farm data platform adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Global Bacterial Cell Culture Market
Industrial Microbiology
Anti-Microbial Anti-Fungal Test Market
Industrial Microbiology
Global Arabinogalactan Market
Industrial Microbiology
Benzoate-Free Enzymes Market
Industrial Microbiology
Global Microbial Based Biological Seed Treatment Market
Industrial Microbiology
Global Microbiome Therapeutics Market
Industrial Microbiology
Lipase Market
Industrial Microbiology
Industrial Bioprocessing Market
Industrial Microbiology
Microbiome Sample Preparation Technology Market
Industrial Microbiology
Salinomycin Market
Industrial Microbiology
Molecular Microbiology Market
Industrial Microbiology
Mycoplasma Plate Antigens Market
Industrial Microbiology
Galactosidase Market
Industrial Microbiology
Mineral Yeast Market
Industrial Microbiology
North America Microbial Protein Market
Industrial Microbiology
Microbiology Testing Market