
 Apricot Kernel Market | 2026-2036
Apricot Kernel Market Size, Share, and Industry Trends Forecast 2026-2036
Apricot Kernel Market Intelligence
Pharmaceutical-grade kernel specification is rotating toward higher amygdalin purity thresholds and contaminant-screening protocols. Georg Lemke leverages its German extraction infrastructure to supply certified cosmetic oil batches to European formulators. Zhangjiakou Yongchangyuan Kernel Food anchors northern China's supply base through direct orchard partnerships in Hebei Province. NOW Foods differentiates via third-party tested whole kernel SKUs positioned for nutraceutical channel placement.
Apricot kernel denotes the seed found inside Prunus armeniaca fruit stones, typically containing 40–50% oil by weight with oleic acid and linoleic acid as dominant fatty acid constituents; processors cold-press or solvent-extract this oil for emollient, carrier, and dietary supplement applications. Oil commands the dominant value share among product types due to its versatility across cosmetics and nutraceutical formulations, while extract segments attract premium pricing from pharmaceutical buyers seeking standardized amygdalin content. Food & Beverages application channels sustain volume throughput through bakery and confectionery inclusion, though Cosmetics and Personal Care segments capture superior margins through branded finished goods.
FDA oversight of amygdalin-containing supplements and EFSA novel food assessments constrain product positioning in North American and European markets, while China's SAMR implements GB standard revisions for edible seed oils that affect export certification requirements. Stakeholders must monitor evolving amygdalin threshold regulations across jurisdictions to determine formulation reformulation versus market exit decisions.
Market Dynamics
Regulatory fragmentation around amygdalin content thresholds is forcing processors to maintain parallel certification tracks for pharmaceutical, cosmetic, and food-grade kernel streams from identical raw material inputs.
Growth Catalysts
- Cold-press extraction infrastructure:South Korean cosmetics manufacturers are scaling dedicated oil pressing capacity to serve premium skincare formulators seeking unrefined carrier oils with preserved tocopherol profiles.
- REACH compliance protocols:ECHA substance registration requirements for cosmetic-grade apricot kernel oil are consolidating supplier bases toward certified European processors with validated contaminant-screening laboratories.
- Hebei Province orchard networks:Direct grower-processor partnerships in northern China are securing varietal traceability for kernels meeting pharmaceutical amygdalin purity specifications.
Market Restraints
- Amygdalin content volatility:Natural variation in Prunus armeniaca cultivars creates batch-to-batch inconsistency that complicates pharmaceutical standardization and increases rejection rates at contract manufacturers.
- Turkey organic certification transitions:Shifting EU-equivalent organic recognition protocols for Turkish kernel exports are disrupting established supply relationships and forcing re-audits of cooperative processing facilities.
- Synthetic emollient substitution:Petrochemical-derived squalane and hemisqualane from biotechnology fermentation are capturing mid-market cosmetic formulations at lower input cost volatility.
Strategic Opportunities
- Shandong Province cluster expansion:Qingdao port-adjacent integrated pressing and export infrastructure offers throughput scalability for processors serving Japanese and South Korean cosmetic contract manufacturers.
- GB standard alignment services:SAMR edible seed oil certification consulting for Chinese export-oriented processors creates advisory revenue streams around documentation and laboratory testing protocols.
- Supercritical CO2 extraction convergence:Combining this solvent-free technology with pharmaceutical amygdalin purification is opening pharmaceutical API precursor markets previously served by synthetic chemistry routes.
Industry Challenges
- Multi-jurisdictional amygdalin testing protocols:FDA dietary supplement enforcement, EFSA novel food assessments, and SAMR GB standards each demand distinct analytical methods and reference standards, multiplying quality control overhead.
- Orchard-to-press traceability system integration:Blockchain and ERP implementation across fragmented smallholder networks in Hebei and Shandong provinces requires capital deployment with extended payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apricot Kernel Market |
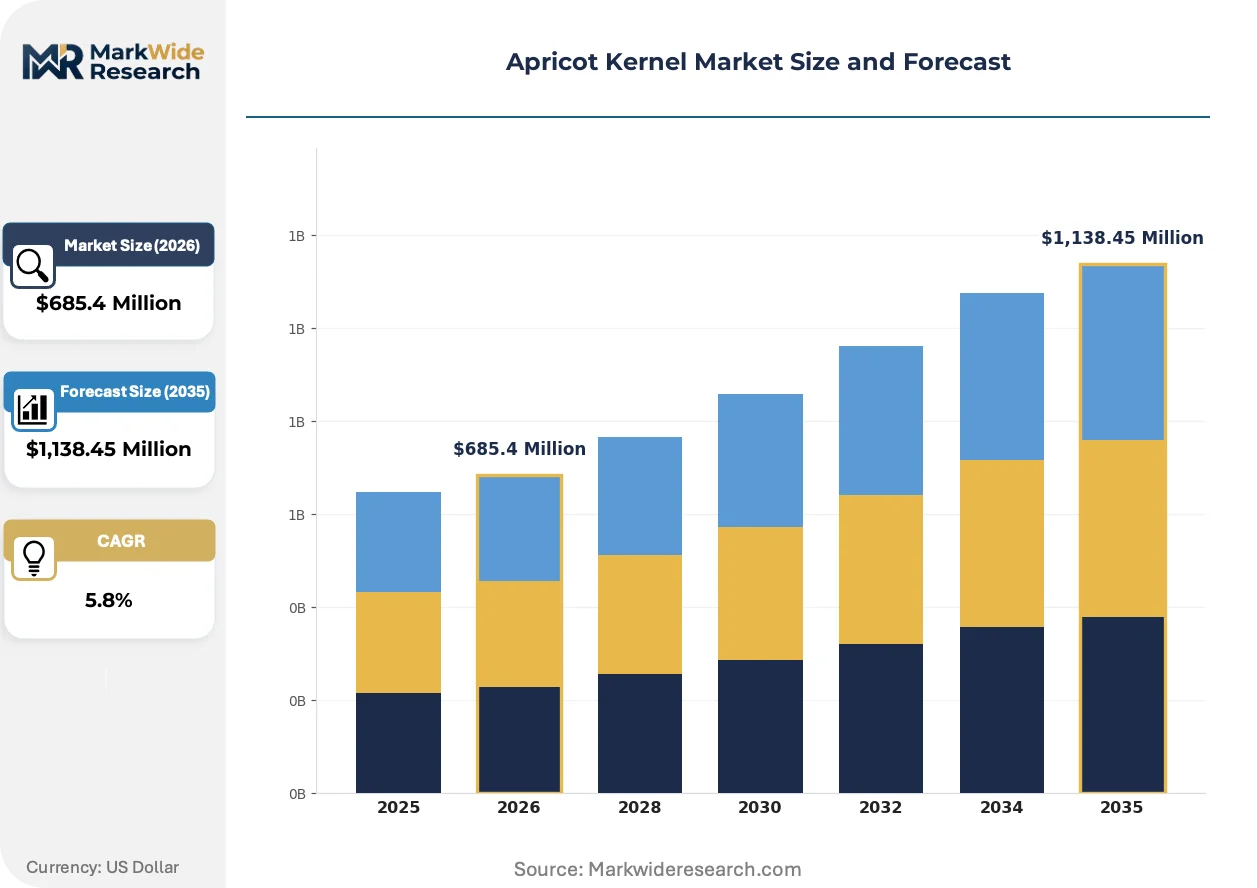
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil, Powder, Extract, Whole Kernels Application: Cosmetics, Food & Beverages, Nutraceuticals, Personal Care End User: Food Manufacturers, Cosmetic Brands, Pharmacies, Research Institutions Distribution Channel: Online Retailers, Supermarkets, Distributors, Health Stores |
| Companies Covered | Georg Lemke, Zhangjiakou Yongchangyuan Kernel Food, Royal Rifco, NOW Foods, Caloy, Izmir Organic, Chengde Yaou Nuts & Seeds, La Tourangelle, Kenkko, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apricot Kernel Market Strategic Shifts & Innovations
Processing technology and regulatory classification systems are diverging in parallel, with cosmetic and pharmaceutical grade streams demanding incompatible purification investments from shared raw material bases.
Supercritical CO2 extraction for amygdalin isolation is bifurcating the pharmaceutical supply base between European GMP-certified facilities and emerging Chinese processors with lower capital cost structures. German and Swiss contract manufacturers are absorbing this technology for oncology research chemical supply, while Shandong-based operators target veterinary pharmaceutical applications with reduced purity thresholds. The technology is compressing solvent extraction margins in mid-purity segments where hexane-based methods previously dominated.
EFSA novel food assessment pathways for amygdalin-containing kernel preparations are tightening import documentation requirements for non-EU processors. Turkish exporters face extended safety evaluation timelines that delay market access for new kernel oil SKUs. Pharmaceutical-grade extract segments are responding by segregating EU-bound production lines from food-grade streams to isolate regulatory risk.
Cosmetic brand procurement departments are consolidating supplier panels toward vertically integrated processors with captive orchard networks and in-house cold-press capacity. South Korean formulators are disqualifying traders without direct agricultural relationships. This concentration is most visible in Seoul and Incheon metropolitan area headquarters, where sustainability audit requirements now mandate farm-level visit documentation.
Apricot Kernel Market Segmentation
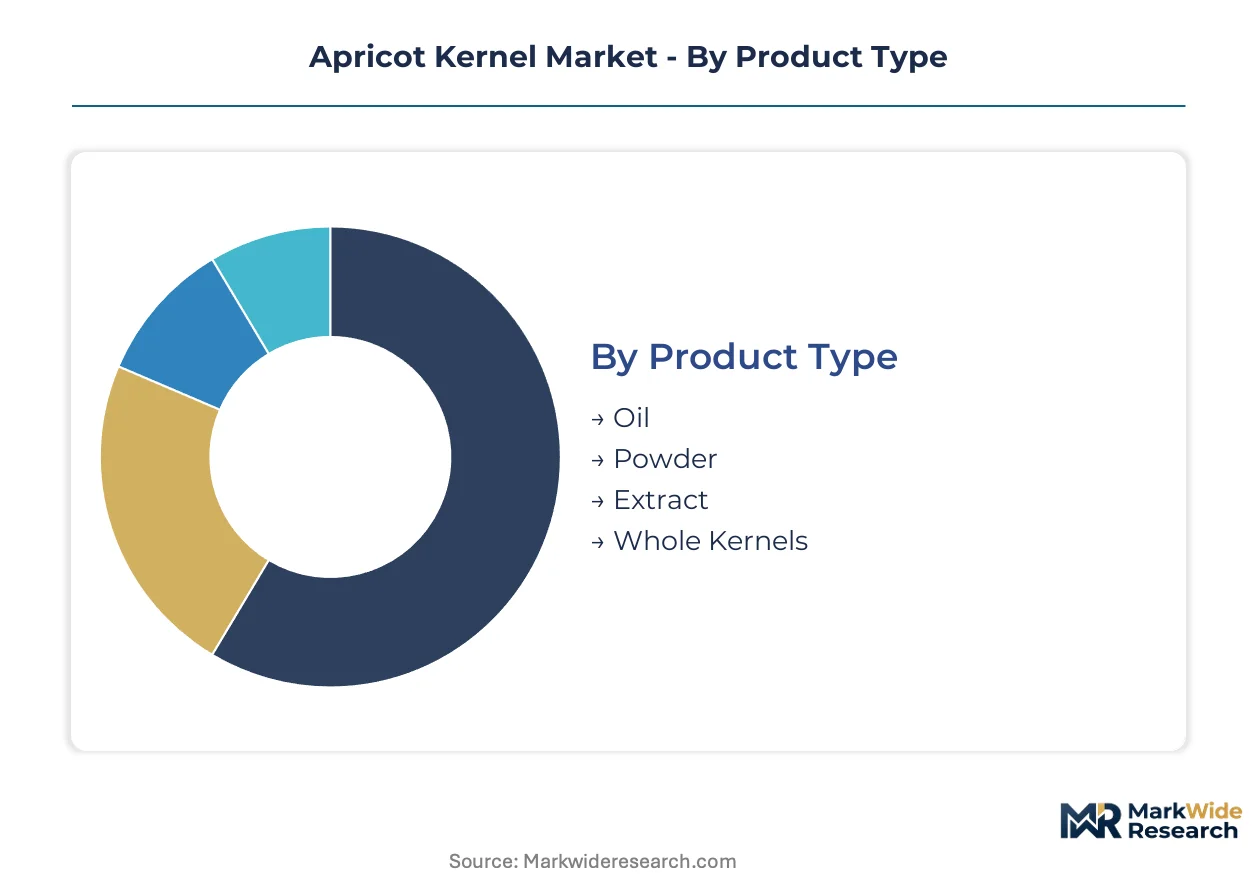
Apricot kernel processors must maintain parallel production streams serving distinct regulatory environments. Segmentation reveals how identical raw materials diverge into pharmaceutical, cosmetic, and food-grade channels with incompatible certification requirements.
Product Type:
Domestic consumption concentrates on whole kernels and powder for traditional food applications, while export-led demand drives oil and extract segments toward South Korean and European cosmetic formulators.
- Oil:Cold-pressed varieties retain tocopherol profiles prized by premium skincare formulators. South Korean cosmetics manufacturers in Seoul and Incheon metropolitan areas specify unrefined grades with documented oleic acid content above 65 percent.
- Extract:Standardized amygdalin purification for pharmaceutical precursor markets demands supercritical CO2 extraction infrastructure. German and Swiss contract manufacturers absorb European GMP-certified batches for oncology research chemical supply.
- Powder:Finely milled kernel meal serves bakery inclusion and traditional medicinal preparations across Chinese domestic channels.
- Whole Kernels:Raw seed form dominates volume throughput for nut processing and confectionery roasting applications.
Oil holds the largest share; momentum sits with extract as pharmaceutical API precursor applications expand.
Application:
Margin stratification separates premium cosmetic positioning from commodity food-grade throughput, with regulatory compliance costs determining viable market entry.
- Cosmetics:Emollient and carrier oil functions command superior pricing through branded finished goods. REACH registration requirements consolidate supplier bases toward ECHA-validated European processors with contaminant-screening laboratories.
- Personal Care:Premium skincare and haircare formulations in South Korea specify cold-pressed grades with preserved bioactive compounds.
- Food & Beverages:Bakery and confectionery inclusion sustains volume demand through Shandong Province processing clusters around Qingdao port facilities.
- Nutraceuticals:Dietary supplement positioning faces FDA amygdalin enforcement and EFSA novel food assessment constraints in North American and European markets.
Cosmetics generates the highest margins; nutraceuticals face the steepest regulatory barriers to sustained placement.
End User:
Procurement sophistication varies dramatically across buyer categories, from commodity traders to GMP-certified pharmaceutical contract manufacturers.
- Cosmetic Brands:Sustainability audit requirements now mandate farm-level visit documentation, disqualifying traders without direct agricultural relationships.
- Food Manufacturers:Volume purchasers prioritize cost stability and consistent supply from Hebei Province orchard networks.
- Pharmacies:Retail and compounding channels seek third-party tested SKUs with documented amygdalin content thresholds.
- Research Institutions:Oncology and veterinary pharmaceutical researchers source standardized extracts with batch-to-batch purity consistency.
Cosmetic brands drive specification tightening; research institutions represent the most demanding purity requirements.
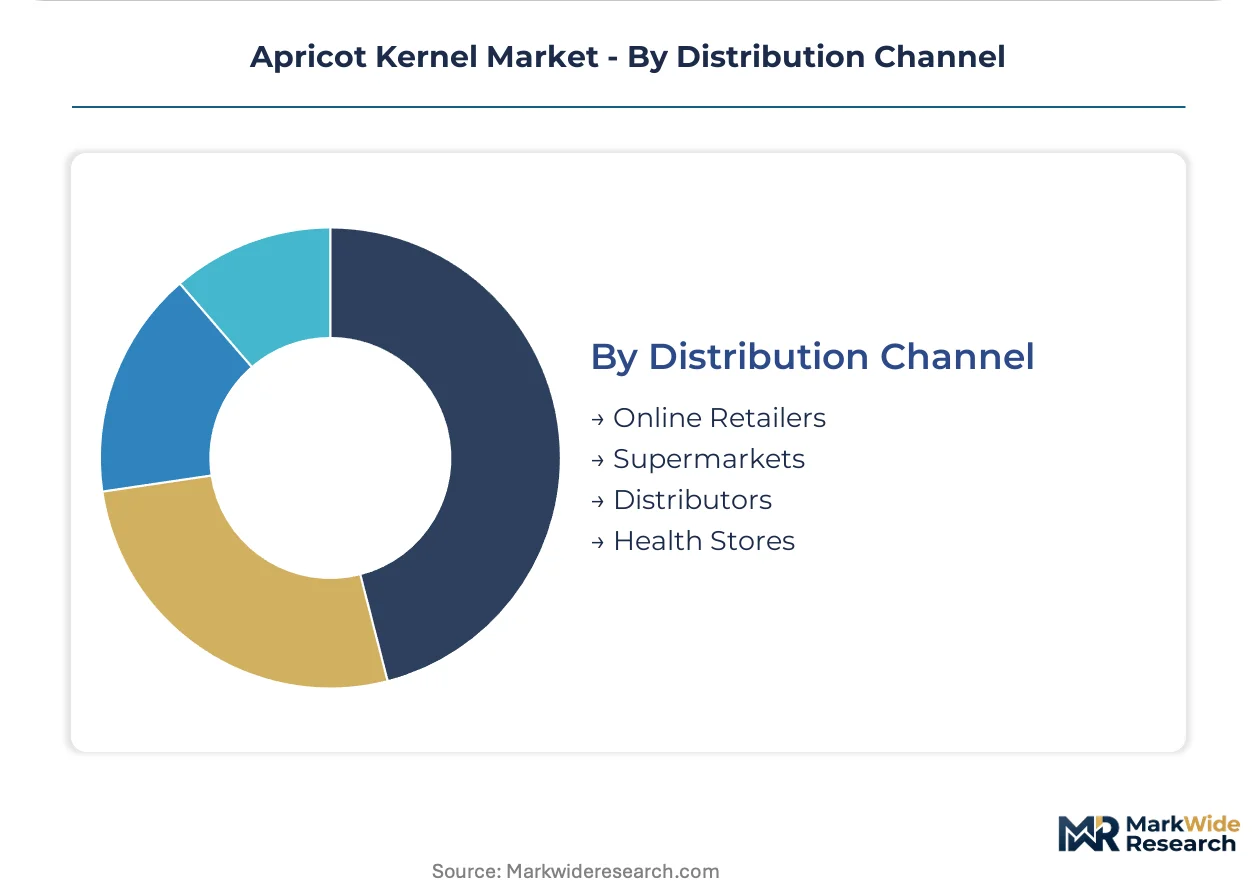
Distribution Channel:
Channel selection determines margin capture versus volume throughput, with direct relationships increasingly favored for premium grades.
- Distributors:Traditional wholesale networks dominate commodity-grade oil and whole kernel movement to food manufacturers.
- Online Retailers:Direct-to-consumer nutraceutical SKUs face platform-specific amygdalin content restrictions and labeling requirements.
- Supermarkets:Mass-market food-grade kernel products compete on price through private label placement.
- Health Stores:Specialty retail channels prioritize organic certification and origin documentation for premium positioning.
Distributors maintain volume leadership; health stores capture the steepest premium markup for certified organic grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turkey exports raw apricot kernels to European cosmetic formulators and Chinese processors, creating a trade-flow corridor that shapes procurement patterns across three continents. This movement of unprocessed seed material drives infrastructure investments in origin countries while concentrating value-addition in destination markets with stricter certification requirements.
Turkey
Malatya Province orchards supply the bulk of global raw kernel exports to European oil pressers and Chinese extractors. EFSA novel food assessment pathways now require extended safety documentation for amygdalin-containing preparations, delaying market access for new kernel oil SKUs. Izmir-based cooperatives are re-auditing processing facilities to maintain EU-equivalent organic recognition.
China
Shandong Province cold-press facilities serve South Korean cosmetics manufacturers seeking unrefined grades with preserved tocopherol profiles. SAMR implements GB standard revisions for edible seed oils that affect export certification requirements for kernel-derived products. Qingdao port-adjacent integrated pressing infrastructure offers throughput scalability for Japanese and South Korean contract manufacturers.
South Korea
Seoul and Incheon metropolitan area formulators specify cold-pressed apricot kernel oil with documented oleic acid content above 65 percent for premium skincare lines. MFDS cosmetic ingredient registration requirements consolidate supplier panels toward vertically integrated processors with direct agricultural relationships. Domestic brands now mandate farm-level sustainability audit documentation.
Germany
REACH compliance protocols and ECHA substance registration requirements for cosmetic-grade apricot kernel oil are consolidating supplier bases toward certified European processors with validated contaminant-screening laboratories. Georg Lemke leverages domestic extraction infrastructure to supply certified cosmetic oil batches to regional formulators. GMP-certified facilities in southern Germany absorb supercritical CO2 extraction batches for pharmaceutical precursor markets.
United States
FDA oversight of amygdalin-containing supplements constrains dietary supplement positioning, forcing processors to maintain parallel certification tracks for pharmaceutical and cosmetic-grade streams. NOW Foods differentiates via third-party tested whole kernel SKUs positioned for nutraceutical channel placement. California-based formulators face platform-specific amygdalin content restrictions in direct-to-consumer channels.
Apricot Kernel Market Key Industry Players
Listed leaders compete with private specialists across certification infrastructure, with publicly held nutraceutical firms facing different capital constraints than family-owned orchard processors. The vendor base spans three tiers: GMP-certified pharmaceutical extract suppliers, vertically integrated cosmetic oil processors with captive orchard networks, and commodity traders serving food-grade volume channels. Strategic moves concentrate on backward integration into Hebei Province orchard partnerships and supercritical CO2 capacity expansion for amygdalin purification.
Within the European GMP-certified tier, Georg Lemke exemplifies the pharmaceutical-grade extraction archetype, while Zhangjiakou Yongchangyuan Kernel Food anchors the Chinese vertically integrated model through direct grower relationships in northern provinces. NOW Foods occupies a position representing the North American third-party tested nutraceutical positioning, with product lines emphasizing documented purity thresholds for pharmacy and health store channels.
| Leading Market Players |
|---|
| Georg Lemke |
| Zhangjiakou Yongchangyuan Kernel Food |
| Royal Rifco |
| NOW Foods |
| Caloy |
| Izmir Organic |
| Chengde Yaou Nuts & Seeds |
| La Tourangelle |
| Kenkko |
| Others |
Cost & Logistics Intelligence
Qingdao port-adjacent pressing capacity utilization above 85 percent compresses unit economics for Shandong Province processors while elevating price floors for Hebei Province orchard networks supplying pharmaceutical-grade feedstock. This scale concentration rewards integrated operators with captive supply relationships and marginalizes traders dependent on spot market kernel procurement.
Pricing Analysis
Hexane-extracted commodity oil, cold-pressed cosmetic grades, and supercritical CO2 pharmaceutical extracts occupy distinct price bands with widening spreads. Certification tier and oleic acid purity concentration drive price differentiation across South Korean cosmetic formulators and German pharmaceutical contract manufacturers. Pricing pressure stems from synthetic squalane fermentation costs declining below apricot kernel oil equivalents in mid-market emollient segments. Food manufacturers exhibit highest price sensitivity due to substitutable bakery ingredient alternatives, while oncology research institutions accept premium pricing for batch-to-batch amygdalin consistency.
Supply Chain Analysis
Container availability constraints on the Malatya-Qingdao trade lane elevate inbound logistics costs for Turkish raw kernel shipments to Chinese processors. Supply concentrates in Turkey, China, and South Korea across extraction, pressing, and formulation stages respectively. Raw material flows depend on Malatya Province orchard harvests, Hebei Province varietal breeding programs, and Shandong Province cold-press infrastructure. Single-source vulnerability persists in pharmaceutical-grade amygdalin purification where European GMP-certified facilities dominate oncology API precursor supply. Distribution runs through Qingdao port export terminals for Japanese and South Korean cosmetic contract manufacturers, with secondary channels serving European REACH-registered formulators via Izmir cooperative networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Apricot kernel demand follows cyclical patterns tied to South Korean cosmetics export volumes and pharmaceutical research funding cycles, with current positioning suggesting mid-cycle recovery momentum. Procurement consolidation by Seoul-based formulators and MFDS registration requirements are compressing supplier margins while rewarding integrated operators.
For Market Incumbents: Consolidate Hebei Province orchard partnerships to secure pharmaceutical-grade amygdalin feedstock traceability against emerging Chinese processors with lower capital cost structures. Expand supercritical CO2 extraction capacity in Shandong Province to capture veterinary pharmaceutical applications with reduced purity thresholds. Certification investment in REACH-compliant contaminant-screening laboratories isolates regulatory risk from Turkish cooperative re-audit disruptions.
For New Entrants and Emerging Players: Lead with GB standard alignment advisory services for SAMR export certification, capturing documentation and laboratory testing revenue from Qingdao port-adjacent processors seeking Japanese and South Korean market access. Target veterinary pharmaceutical extract segments where purity thresholds remain below human oncology standards. Deploy direct agricultural relationships as the primary go-to-market credential against trader-dependent competitors disqualified by Seoul sustainability audit requirements.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors processors with captive supercritical CO2 infrastructure and backward integration into northern Chinese orchard networks. Long-term viability hinges on pharmaceutical API precursor pipeline expansion and cosmetic brand direct procurement relationships. Acquisition targets should demonstrate validated GMP certification or ECHA substance registration with demonstrated throughput scalability. The signal to watch is MFDS cosmetic ingredient registration timeline acceleration indicating procurement panel consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hebei Province Orchards | Captive supply of pharmaceutical-grade amygdalin feedstock reduces batch-to-batch rejection rates at contract manufacturers. |
| Supercritical CO2 Capacity Expansion | Pharmaceutical API precursor markets previously served by synthetic chemistry routes open to solvent-free extraction operators. |
| REACH Compliance Laboratory Investment | ECHA substance registration requirements consolidate European supplier bases toward certified processors with validated contaminant-screening. |
| GB Standard Alignment Services | SAMR edible seed oil certification consulting creates advisory revenue around documentation and testing protocols. |
| Farm-Level Blockchain Traceability Implementation | Seoul-based cosmetic formulators mandate sustainability audit documentation disqualifying traders without direct agricultural relationships. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with cosmetic formulators in Seoul and Incheon, pharmaceutical contract manufacturers in Germany and Switzerland, cold-press facility managers in Shandong Province, and orchard cooperative directors in Malatya Province. Secondary validation drew from SAMR GB standard filings, EFSA novel food assessment documentation, MFDS cosmetic ingredient registrations, and customs export data through Qingdao port terminals. Bottom-up kernel throughput estimates and top-down oil value projections were triangulated against processor capacity disclosures.
Across the analysis window, forecasts model product type segmentation across oil, extract, powder, and whole kernel streams; application channels spanning cosmetics, personal care, food and beverages, and nutraceuticals; and end-user categories from commodity food manufacturers to GMP-certified pharmaceutical researchers. CAGRs were derived from volume-weighted average price trajectories and installed capacity expansion announcements. Industry-specific inputs include amygdalin purity threshold evolution across FDA, EFSA, and SAMR jurisdictions and South Korean cosmetics export volume elasticity to carrier oil specification tightening.
Forecasts assume regulatory continuity in FDA dietary supplement enforcement, EFSA novel food assessment pathways, and SAMR GB standard implementation; material policy shifts would require re-modeling of pharmaceutical-grade extract demand and cosmetic oil export certification timelines. Commodity price volatility in petrochemical-derived emollient substitutes and Turkish organic certification recognition protocols represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Processed Walnuts Market
Nuts and Seeds
United States Cashew Market
Nuts and Seeds
Europe Nut-Based Spreads Market
Nuts and Seeds
Rubus Fructicosus (Blackberry) Seed Market
Nuts and Seeds
India Processed Cashew Market
Nuts and Seeds
Spain Fox Nuts Market
Nuts and Seeds
Global Peanut Meal Market
Nuts and Seeds
Blackcurrant Seed Oil Market
Nuts and Seeds
Betel Nuts Market
Nuts and Seeds
Almond Butter Market
Nuts and Seeds
Brazil Nuts Market
Nuts and Seeds
Almond with Shell Snack Market
Nuts and Seeds
Nuts and Nut Products Market
Nuts and Seeds
Almond Extract Market
Nuts and Seeds
Carob Extract Market
Nuts and Seeds
Carob Market