
 Global Referral Management Market | 2026-2036
Global Referral Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Referral Management Market Outlook
Subscription-based SaaS financing is rewriting competitive entry dynamics in referral management, lowering capital barriers for mid-tier vendors while pressuring legacy perpetual-license incumbents. Epic Systems leverages deep EHR integration to anchor hospital system loyalty across North American installations. Kyruus competes through physician-centric directory intelligence that matches patient needs with specialist availability. Athenahealth sustains cloud-native scalability for ambulatory networks seeking minimal IT overhead.
Referral management encompasses software platforms, professional services, and integrated solutions that orchestrate patient transitions between primary care physicians, specialists, hospitals, and telehealth providers through automated routing, scheduling, and clinical data exchange. Cloud-based deployment dominates new installations due to faster implementation cycles and reduced on-premise infrastructure burden, while on-premise systems persist in security-sensitive environments requiring localized data custody. The patient referral application segment leads transaction volume as health systems prioritize leakage reduction, whereas telehealth referral functionality represents the fastest-expanding sub-area as virtual care networks proliferate. Services revenue concentrates around implementation and interoperability consulting where margin pools remain deepest due to customization complexity.
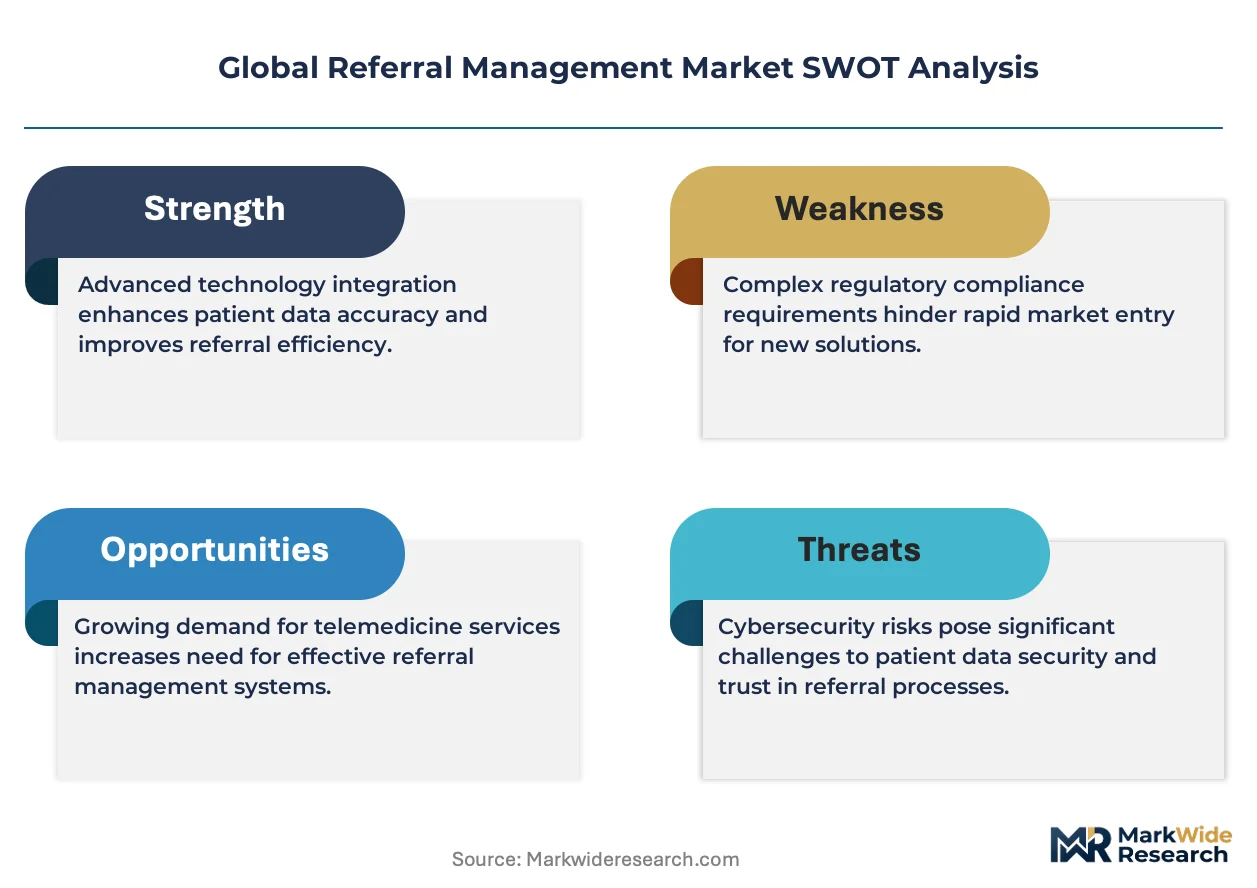
FDA oversight of clinical decision support functions embedded in referral platforms shapes software validation requirements, while HIPAA mandates govern patient data exchange protocols across US deployments. EMA medical device regulations and GDPR data localization rules in Europe impose additional compliance layers for cross-border referral networks. Stakeholders must monitor evolving interoperability standards and reimbursement policies that determine whether referral automation investments yield measurable care quality returns.
Market Dynamics
Interoperability mandates from ONC and CMS are forcing health systems to replace fragmented point solutions with unified referral platforms that exchange data across disparate EHR architectures.
Growth Catalysts
- HIPAA-compliant cloud infrastructure:Healthcare organizations accelerate platform migration to reduce capital expenditure on on-premise server maintenance while meeting federal data security requirements.
- Patient leakage reduction:Hospital networks deploy automated referral tracking to retain revenue within integrated delivery systems and prevent out-of-network specialist diversion.
- Telehealth network expansion:Virtual care platforms require intelligent routing engines to match patients with available remote specialists across state licensing boundaries.
Market Restraints
- EHR integration complexity:Proprietary data formats from Epic, Cerner, and MEDITECH impose substantial customization costs and extend implementation timelines.
- Cybersecurity insurance premiums:Ransomware exposure in healthcare IT has driven liability coverage costs upward, compressing software vendor margins.
- Physician workflow disruption:Clinical staff resistance to additional data entry steps limits adoption velocity in high-volume primary care settings.
Strategic Opportunities
- Medicaid expansion states:Newly eligible populations in Texas, Georgia, and North Carolina create demand for referral management in federally qualified health centers.
- Value-based care contracting:CMS accountable care organization incentives reward care coordination investments that reduce emergency department utilization.
- AI-powered clinical decision support:Natural language processing integration with scheduling systems enables predictive capacity matching between primary and specialty care.
Industry Challenges
- Interoperability workforce scarcity:Health systems compete for HL7 FHIR implementation specialists and interface engine engineers with limited certification pipelines.
- Legacy system technical debt:Decades-old practice management software in community clinics requires expensive middleware development for API connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Referral Management Market |
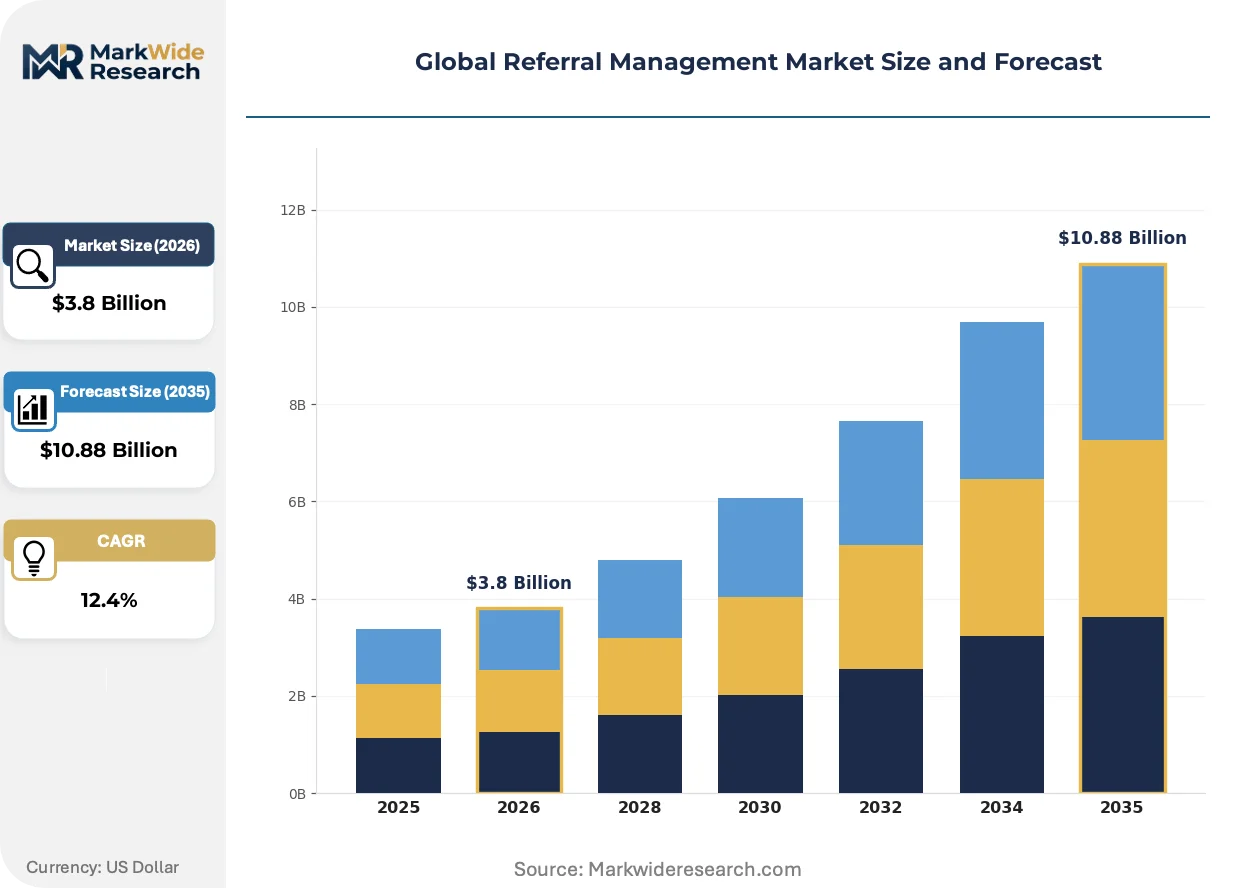
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.88 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Services, Platforms, Solutions End User: Hospitals, Clinics, Healthcare Systems, Physicians Deployment: On-Premise, Cloud-Based, Hybrid, Managed Application: Patient Referral, Provider Referral, Specialist Referral, Telehealth |
| Companies Covered | WellSky, Kyruus, Epic Systems, HealthViewX, Innovaccer, Oracle Health, Athenahealth, Luma Health, Veradigm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Referral Management Market Strategic Shifts
Real-time data exchange protocols are replacing batch-file transfers as the dominant architecture for patient information movement between care settings.
Intelligent scheduling algorithms are digitizing the manual coordination burden that previously consumed 15-20 minutes per referral in administrative staff time. Ambulatory networks with 50-200 physicians are adopting these tools fastest, drawn by immediate FTE reduction metrics. The technology is digitizing appointment logistics into automated workflows that surface open slots across competing health systems within a single interface.
GDPR Article 9 health data processing rules and the EU AI Act risk classification framework impose validation requirements on clinical decision support modules embedded in European referral platforms. Vendors must maintain separate codebases for US and EU deployments to satisfy divergent algorithmic transparency mandates. German hospital systems currently face the steepest compliance burden as both frameworks apply simultaneously to cross-border patient transfers.
Subscription pricing for referral management software is displacing perpetual-license arrangements that dominated hospital IT procurement through 2020. Health system CFOs now prioritize operating expenditure predictability over capital depreciation schedules, particularly for cloud-native deployments. This shift is most pronounced in US multi-hospital systems where standardization across 10-50 facilities requires scalable per-provider licensing models.
Global Referral Management Market Segmentation
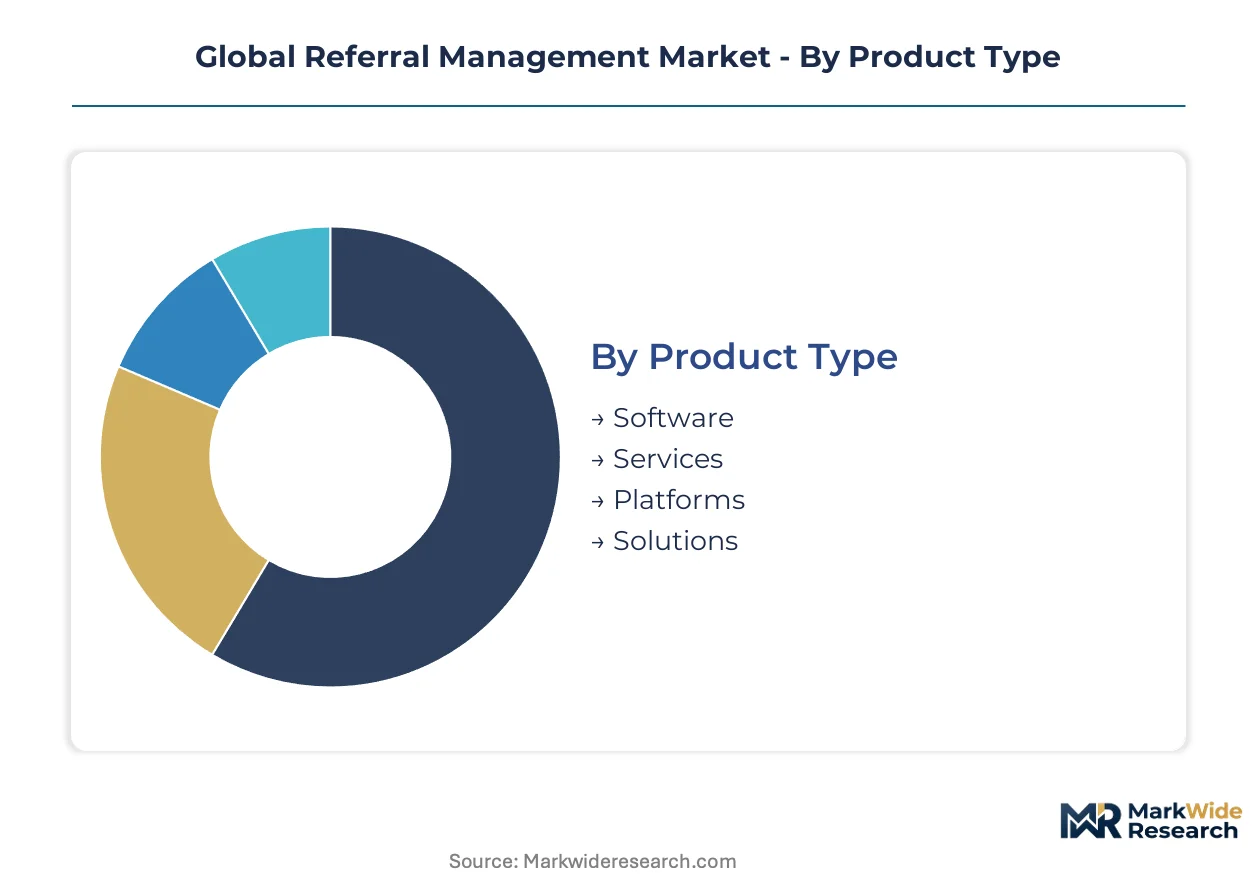
Referral management segmentation reveals how technology architecture, clinical workflow integration, and care delivery models shape purchasing decisions. Vendors must align product configurations with specific deployment constraints and end-user operational requirements to capture contract value.
Product Type:
Use-case spectrum spans from standalone scheduling modules to comprehensive care coordination ecosystems requiring interoperability layers.
- Software:Modular applications handling referral intake, routing logic, and status tracking through configurable rule engines. Hospital systems in the United States prioritize Epic-integrated modules to minimize interface development costs.
- Services:Implementation consulting, HL7 FHIR mapping, and ongoing technical support for multi-EHR environments. Revenue concentrates in large health system rollouts where customization demands exceed internal IT capacity.
- Platforms:Unified technology stacks combining referral orchestration with analytics dashboards and patient engagement portals. German hospital networks favor these for GDPR-compliant cross-facility data sharing.
- Solutions:End-to-end bundles merging software, services, and change management for rapid deployment. Federally qualified health centers in Texas and Georgia select these to accelerate Medicaid expansion readiness.
The dominant share belongs to Software, while Services is closing the gap fastest as implementation complexity drives recurring revenue models.
End User:
Customer type determines feature prioritization, from enterprise governance requirements to individual physician workflow preferences.
- Hospitals:Enterprise deployments requiring centralized referral governance across emergency departments, specialty clinics, and affiliated practices. Japanese medical centers emphasize PMDA-aligned clinical decision support validation.
- Clinics:Ambulatory settings with 5-50 providers seeking lightweight cloud tools with minimal IT overhead. Community health centers in North Carolina adopt these for rapid Medicaid network integration.
- Healthcare Systems:Multi-facility integrated delivery networks demanding standardized referral protocols across 10-100 locations. These buyers command volume pricing leverage and custom development roadmaps.
- Physicians:Individual practitioners and small group practices prioritizing mobile-first interfaces and EHR-embedded functionality. Resistance to additional data entry steps limits adoption velocity in high-volume primary care settings.
Healthcare Systems capture the largest contract value, though Clinics are expanding most quickly as cloud-native tools reduce capital barriers.
Deployment:
Infrastructure choice reflects data custody requirements, cybersecurity posture, and IT staffing constraints across buyer segments.
- On-Premise:Localized server installations maintaining physical data control for security-sensitive environments. Persist in US Department of Veterans Affairs facilities and certain Swissmedic-regulated Swiss hospital networks.
- Cloud-Based:SaaS architectures with HIPAA-compliant AWS, Azure, or Google Cloud hosting. These dominate new installations due to faster implementation cycles and reduced infrastructure burden.
- Hybrid:Split configurations keeping patient identifiers on-premise while routing logic operates in cloud environments. German hospitals favor these for simultaneous GDPR and EU AI Act compliance.
- Managed:Outsourced infrastructure operations where vendors assume full technical responsibility. Appeals to rural health clinics lacking specialized health IT personnel.
Cloud-Based deployment holds the volume lead, yet Hybrid configurations are gaining share fastest as cross-border referral networks proliferate.
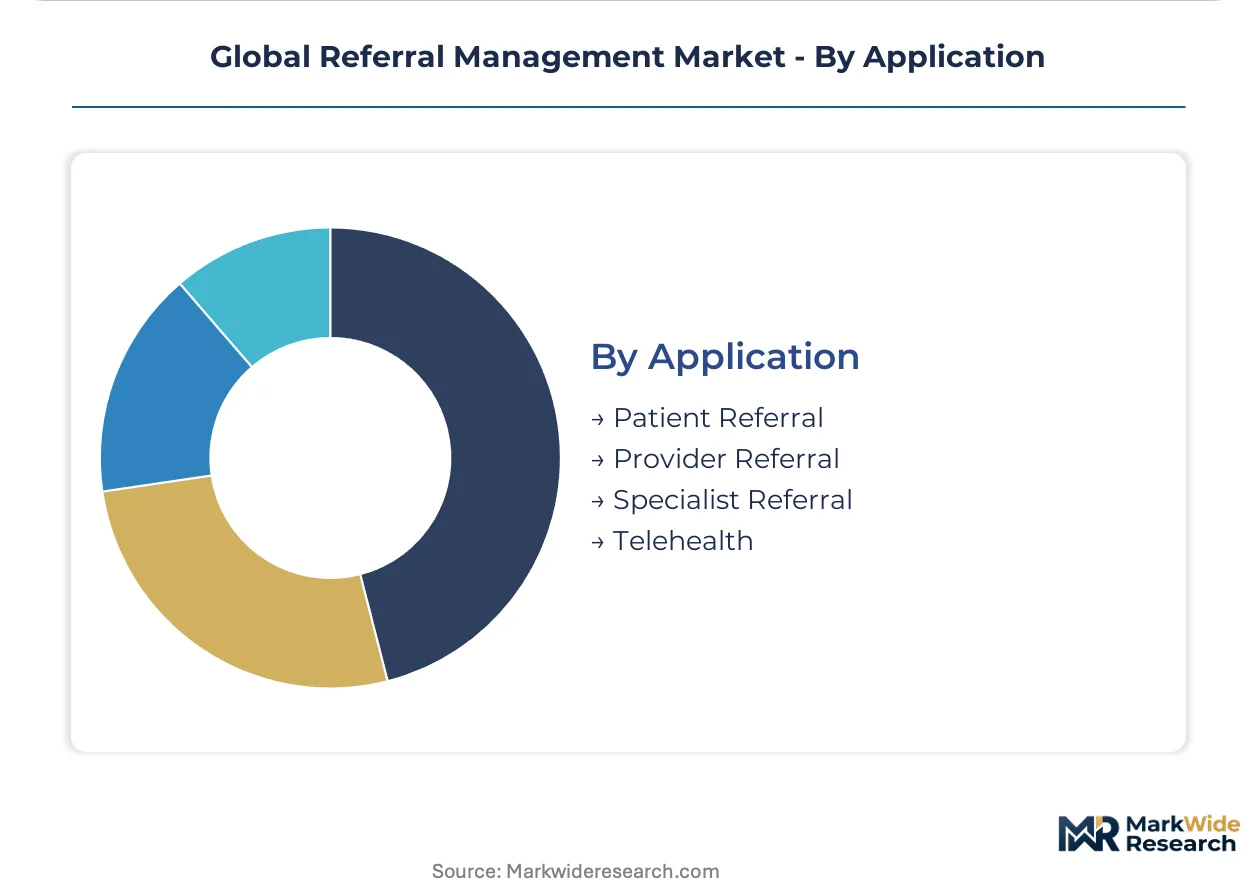
Application:
Functional specialization addresses distinct coordination challenges across care transition types and virtual delivery models.
- Patient Referral:Core functionality automating primary-to-specialty transitions with appointment scheduling and clinical document exchange. Health systems prioritize these tools for leakage reduction within integrated delivery networks.
- Provider Referral:Directory intelligence matching referring physicians with appropriate specialists based on availability, insurance acceptance, and quality metrics. Kyruus competes aggressively in this segment through physician-centric data layers.
- Specialist Referral:Sub-specialty coordination for complex conditions requiring multi-disciplinary care teams. Tertiary academic medical centers in Japan deploy these for cancer and cardiovascular networks.
- Telehealth:Virtual care routing engines matching patients with licensed remote specialists across state and national boundaries. This application climbs the fastest as telehealth networks expand post-pandemic infrastructure investments.
Patient Referral commands the installed base, while Telehealth exhibits the steepest expansion trajectory as virtual care networks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a substantial trade surplus in healthcare software exports while importing specialized implementation services from European consultancies. Germany and Japan represent net importers of cloud infrastructure components, driving localized data center investments. Cross-border referral networks between these markets generate compliance arbitrage opportunities for vendors maintaining dual codebases.
United States
Hospital networks in Texas and Georgia are deploying automated referral platforms to capture newly eligible Medicaid populations, while integrated delivery systems across the Southeast prioritize leakage reduction tools. HIPAA mandates from HHS govern all patient data exchange protocols, with ONC interoperability rules forcing EHR-agnostic platform replacements. The Dallas-Fort Worth medical corridor hosts concentrated vendor implementation teams serving multi-hospital systems.
Germany
German hospital networks face simultaneous compliance burdens from GDPR Article 9 health data rules and the EU AI Act risk classification framework for clinical decision support modules. The country's national pharmaceutical regulator, BfArM, coordinates with EMA on cross-border referral validation standards. Bavarian medical centers in Munich and Nuremberg are pioneering hybrid cloud deployments that keep patient identifiers on-premise while routing logic operates in compliant cloud environments.
Japan
Japanese tertiary academic medical centers in Tokyo and Osaka are expanding specialist referral networks for cancer and cardiovascular multi-disciplinary care teams. PMDA-aligned clinical decision support validation requirements shape software procurement specifications for hospital IT departments. The Kanto region around Tokyo concentrates platform vendor technical support operations serving domestic EHR architectures.
United Kingdom
NHS integrated care systems across England are consolidating fragmented point solutions into unified referral platforms mandated by national interoperability frameworks. The country's health data regulator, NHS Digital, enforces information governance standards for cross-trust patient transfers. London's Harley Street medical district and Manchester's health innovation cluster host pilot programs for AI-powered scheduling algorithms.
India
Indian hospital chains in Maharashtra and Karnataka are adopting cloud-native referral tools to reduce IT overhead in high-volume ambulatory settings. CDSCO oversight applies to clinical decision support functions classified as medical devices under evolving software regulations. Bangalore's health-tech corridor hosts development centers producing export-oriented referral management modules for Southeast Asian markets.
Global Referral Management Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in directory intelligence and scheduling algorithms. The vendor landscape organizes around three strategic tiers: EHR-embedded incumbents with deep hospital system loyalty, cloud-native challengers serving ambulatory networks, and professional services firms capturing implementation complexity margins. Consolidation pressure intensifies as health systems demand unified platforms replacing fragmented point solutions. Competitive moves center on interoperability certification achievements and subscription pricing model transitions.
Within the EHR-embedded tier, Epic Systems and Oracle Health occupy positions anchored by deep integration with hospital IT infrastructure. Kyruus exemplifies the physician-centric directory intelligence archetype, matching patient needs with specialist availability through data-layer specialization. Athenahealth sits within the cloud-native challenger group, serving ambulatory networks seeking minimal IT overhead through SaaS scalability. These three represent divergent strategic postures: captive ecosystem control, vertical data intelligence, and horizontal cloud delivery.
| Leading Market Players |
|---|
| WellSky |
| Kyruus |
| Epic Systems |
| HealthViewX |
| Innovaccer |
| Oracle Health |
| Athenahealth |
| Luma Health |
| Veradigm |
| Others |
Value Chain & Pricing Dynamics
Trans-Pacific data corridor costs from Singapore to Los Angeles shape cloud infrastructure economics for referral management vendors, concentrating pricing power among hyperscale hosts while forcing mid-tier SaaS providers into aggressive per-seat rate competition to offset bandwidth expenditure.
Pricing Analysis
Healthcare Systems anchor subscription pricing structures across the referral management landscape. Three-tier pricing structure across premium, standard, and economy levels reflects integration depth with Epic, Cerner, and MEDITECH architectures. Cost compression in the standard tier is intensifying because ambulatory networks demand SaaS predictability without capital depreciation schedules. Federally qualified health centers exhibit highest price sensitivity due to constrained Medicaid reimbursement margins, while multi-hospital integrated delivery networks leverage volume scale for custom development roadmaps.
Supply Chain Analysis
Tariff exposure between the United States and China dominates semiconductor component sourcing for on-premise server installations. Cloud infrastructure draws from AWS, Azure, and Google Cloud data centers concentrated in Virginia, Frankfurt, and Tokyo. Single-source vulnerability persists in HL7 FHIR interface engine talent pools where certification pipelines lag demand. Distribution runs through direct enterprise sales teams serving hospital networks alongside channel partners penetrating community clinic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from EHR-native workflow tools that embed lightweight referral functionality without standalone platform procurement, compressing addressable market scope for pure-play vendors.
For Market Incumbents: Insulate installed base through backward integration into HL7 FHIR implementation services, capturing margin pools from interoperability workforce scarcity. Deepen EHR-embedded functionality to match native workflow tools threatening standalone platform displacement. Prioritize Epic-certified modules to minimize interface development costs for hospital system renewals.
For New Entrants and Emerging Players: Build out AI-powered scheduling algorithms for ambulatory networks with 50-200 physicians, the fastest-expanding buyer segment. Target Medicaid expansion states including Texas, Georgia, and North Carolina where federally qualified health centers seek rapid deployment bundles. Lead with mobile-first interfaces addressing physician workflow disruption that limits adoption velocity in high-volume primary care settings.
For Investors and Strategic Acquirers: Cloud-native challengers with proven SaaS scalability for ambulatory networks represent the most defensible acquisition profile. Long-term viability hinges on subscription revenue predictability displacing perpetual-license arrangements through the projection horizon. Watch ONC interoperability rule enforcement as the signal indicating whether EHR-agnostic platforms gain procurement traction against embedded incumbents.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Epic-embedded modules reduce interface development costs for hospital system deployments. |
| Geographic Expansion | Texas and Georgia Medicaid expansion creates demand concentration in federally qualified health centers. |
| Strategic Partnership | Hyperscale cloud alliances with AWS and Azure accelerate HIPAA-compliant infrastructure deployment. |
| Product Launch | AI-powered scheduling algorithms digitize 15-20 minutes of manual coordination burden per referral. |
| Acquisition of Specialist Firm | HL7 FHIR implementation boutiques capture deepest margin pools from interoperability complexity. |
Study Parameters
The analysis maps software modules, professional services, and integrated platforms, each validated through hospital CIOs, ambulatory practice managers, HL7 FHIR implementation specialists, and GPO contracts managers. Primary interviews combined with secondary validation from CMS Medicare data, hospital procurement databases, ONC interoperability filings, and hyperscaler capex disclosures. Bottom-up and top-down triangulation cross-checked segment assumptions against operating metrics.
Assumption sets held HIPAA compliance timelines and EHR integration complexity constant while varying telehealth network expansion rates and Medicaid eligibility thresholds across the analysis window. Segmentation dimensions modeled include deployment architecture, end-user facility scale, application functionality, and regional regulatory cluster. CAGRs derived from patient referral transaction volume trajectories and telehealth routing engine adoption curves, with cloud migration velocity and physician workflow acceptance as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by EHR-native workflow tool developers would shift outcomes beyond projected ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Software Defined Application and Infrastructure Market
Digital Solutions
Search Engine Optimization Services Market
Digital Solutions
Digital Clothing Market
Digital Solutions
System Integrator Market
Digital Solutions
Data Quality and Data Governance Solution Market
Digital Solutions
Global Asset Tracking and Inventory Management Solutions Market
Digital Solutions
Experience Optimization Platforms Market
Digital Solutions
Qatar ICT Market
Digital Solutions
North America Managed Mobility Service Market
Digital Solutions
Cloud-Based POS Market
Digital Solutions
Synthetic Monitoring Market
Digital Solutions
Multichannel Order Management Market
Digital Solutions
Webrtc Market
Digital Solutions
Premium Messaging Market
Digital Solutions
North America 3D Rendering Services Market
Digital Solutions
Cognitive Supply Chain Market