
 Inorganic Salts Market | 2026-2036
Inorganic Salts Market Size, Share, and Industry Trends Forecast 2026-2036
Inorganic Salts Market Analysis
A capital-intensity divergence between integrated chlor-alkali producers and specialty salt refiners is reorganizing competitive tiers in the inorganic salts sector. Solvay leverages its integrated soda ash and salt platform to control raw material costs across European manufacturing corridors. Merck KGaA differentiates through pharmaceutical-grade certification and ultra-high-purity production protocols that command premium positioning in healthcare supply chains.
Inorganic salts comprise ionic compounds formed through neutralization reactions between acids and bases, typically crystallizing with defined stoichiometric ratios and solubility parameters governed by temperature and pH. These compounds serve as essential inputs for chemical synthesis, nutritional supplementation, water conditioning, and industrial process control across manufacturing ecosystems. Sodium chloride dominates volume flows through its role as chlor-alkali feedstock and de-icing agent, while calcium carbonate concentrates margin pools in pharmaceutical and food additive applications where USP and FCC certifications create qualification barriers. Potassium nitrate sustains above-average growth in agriculture through its dual nitrogen-potassium contribution to fertigation systems and controlled-release formulations.
EPA discharge permits under the Clean Water Act and REACH registration requirements in Europe constrain permissible heavy metal content in salts destined for water treatment and food contact applications. FDA food additive regulations and USP monographs further segment the market by establishing distinct purity tiers that separate commodity grades from certified pharmaceutical and food-grade products. Stakeholders must monitor regulatory harmonization pressures between EPA, ECHA, and China's MEE as these bodies tighten trace contaminant limits that determine market access eligibility and production cost structures.
Market Dynamics
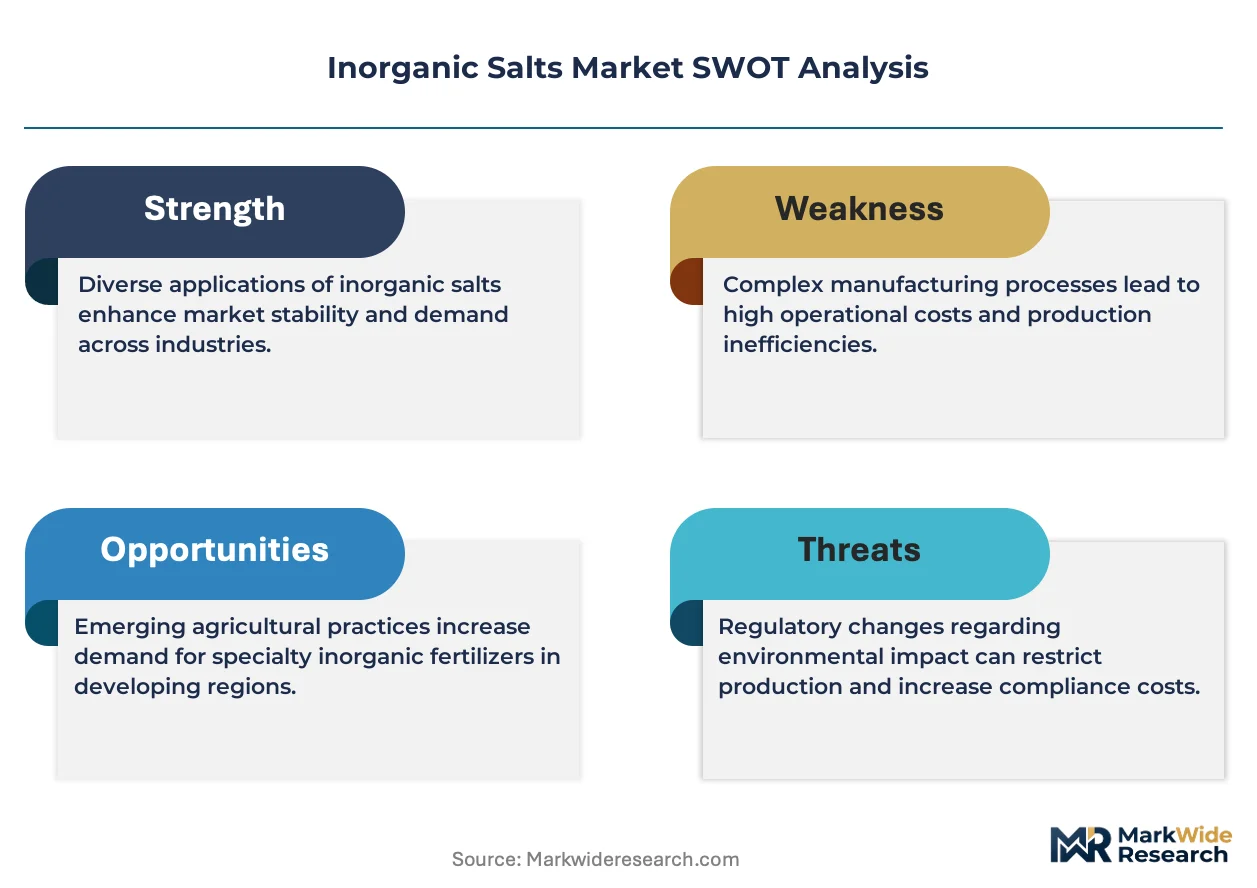
REACH registration deadlines and EPA discharge permit renewals are forcing salt refiners to rebuild purification infrastructure around heavy metal thresholds, compressing margins for commodity-grade producers while widening spreads for certified pharmaceutical and food-grade tiers.
Growth Catalysts
- Chlor-alkali capacity expansion:China's chemical corridor continues absorbing sodium chloride feedstock at scale, sustaining volume throughput for integrated producers.
- EPA Clean Water Act enforcement:Municipal water utilities across the United States are upgrading flocculation chemistry, expanding procurement of magnesium sulfate and calcium carbonate for pH correction and coagulation.
- Fertigation system adoption:Precision agriculture in Israel and the Netherlands is concentrating demand for potassium nitrate in controlled-release formulations.
Market Restraints
- Energy cost volatility:Electrolytic chlor-alkali production faces margin compression from natural gas and electricity price swings, particularly affecting European manufacturing corridors.
- Supply concentration in Qinghai:China's dominance in potassium salt lake extraction creates single-source vulnerability for global fertilizer and chemical supply chains.
- Substitution by organic acids:Food preservative applications are experiencing partial displacement of sodium benzoate by clean-label alternatives in premium packaged goods segments.
Strategic Opportunities
- Pharmaceutical-grade certification gaps:Indian and Brazilian refiners can capture margin expansion by achieving USP and EP monograph compliance for intravenous-grade sodium chloride.
- Battery electrolyte salts:Lithium hexafluorophosphate and lithium bis(fluorosulfonyl)imide demand from electric vehicle cell manufacturing is creating new high-purity salt categories.
- EU Green Deal carbon border adjustments:European importers will face escalating compliance costs, creating first-mover advantage for low-carbon soda ash and salt producers with verified Scope 1-3 emissions data.
Industry Challenges
- USP monograph compliance timelines:Pharmaceutical-grade salt certification requires 18-24 month validation cycles that strain working capital for mid-scale refiners.
- Analytical chemistry talent scarcity:ICP-MS and ion chromatography expertise for trace heavy metal detection commands premium wages, constraining quality control expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inorganic Salts Market |
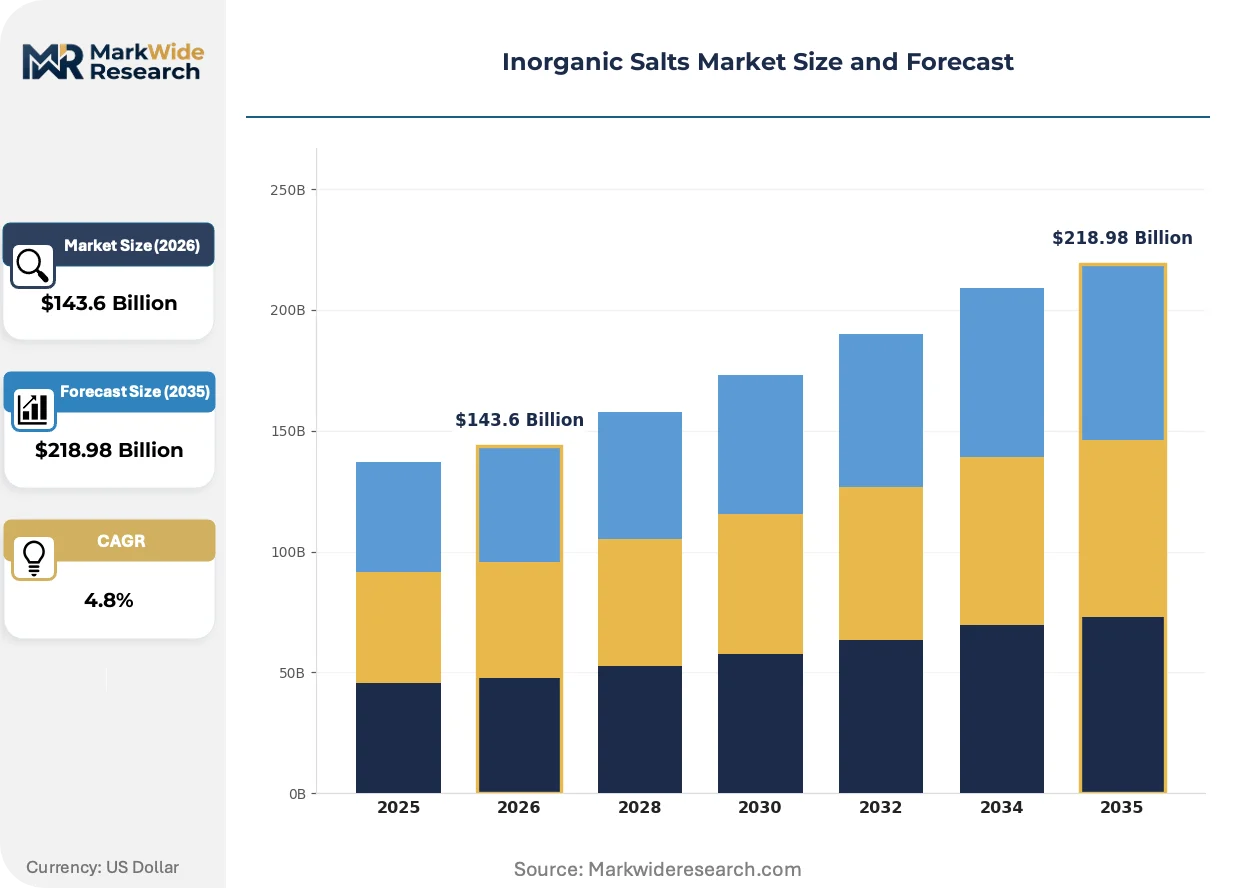
| Market Size in 2026 | $143.6 Billion |
| Market Size in 2035 | $218.98 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Chloride, Potassium Nitrate, Magnesium Sulfate, Calcium Carbonate Application: Agriculture, Pharmaceuticals, Food Additives, Water Treatment End User: Manufacturing, Chemical Industry, Healthcare, Construction Packaging Type: Bulk Packaging, Bags, Drums, Pails |
| Companies Covered | Eastman Chemical Company, Merck KGaA, Lanxess AG, Thermo Fisher Scientific Inc., BEHN MEYER, GFS Chemicals, Inc., Otsuka Chemical Co., Ltd, Solvay, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inorganic Salts Market Emerging Trajectories
Membrane electrolysis and biological water treatment are restructuring how industrial salts are consumed, purified, and valorized across manufacturing ecosystems. These shifts favor capital-intensive integrated platforms over standalone commodity refiners.
Membrane cell technology is supplanting mercury and diaphragm electrolysis in chlor-alkali production, delivering superior energy efficiency and eliminating mercury handling liabilities. European and Japanese producers have completed conversions, while Chinese state-owned enterprises are accelerating retrofit timelines under MEE environmental enforcement. The technology is compressing the viable scale threshold for new chlor-alkali capacity, favoring 300+ kiloton integrated complexes over smaller regional plants.
REACH Annex XVII restrictions on heavy metal content in consumer products are tightening cadmium and lead thresholds for salts entering food contact and cosmetic applications. ECHA compliance audits have expanded to Indian and Turkish export refiners, forcing upstream purification investments. Food-grade sodium chloride and magnesium sulfate shipments to EU member states now require third-party laboratory certification for eight trace metal categories.
Direct-to-municipality contracting is consolidating procurement for water treatment chemicals, bypassing traditional distributor networks. Large utility authorities in Texas, California, and Florida are negotiating multi-year supply agreements with integrated salt-chemical producers for flocculation and pH adjustment chemicals. The shift compresses distributor margins while rewarding producers with captive brine wells and on-site processing infrastructure.
Inorganic Salts Market Segmentation
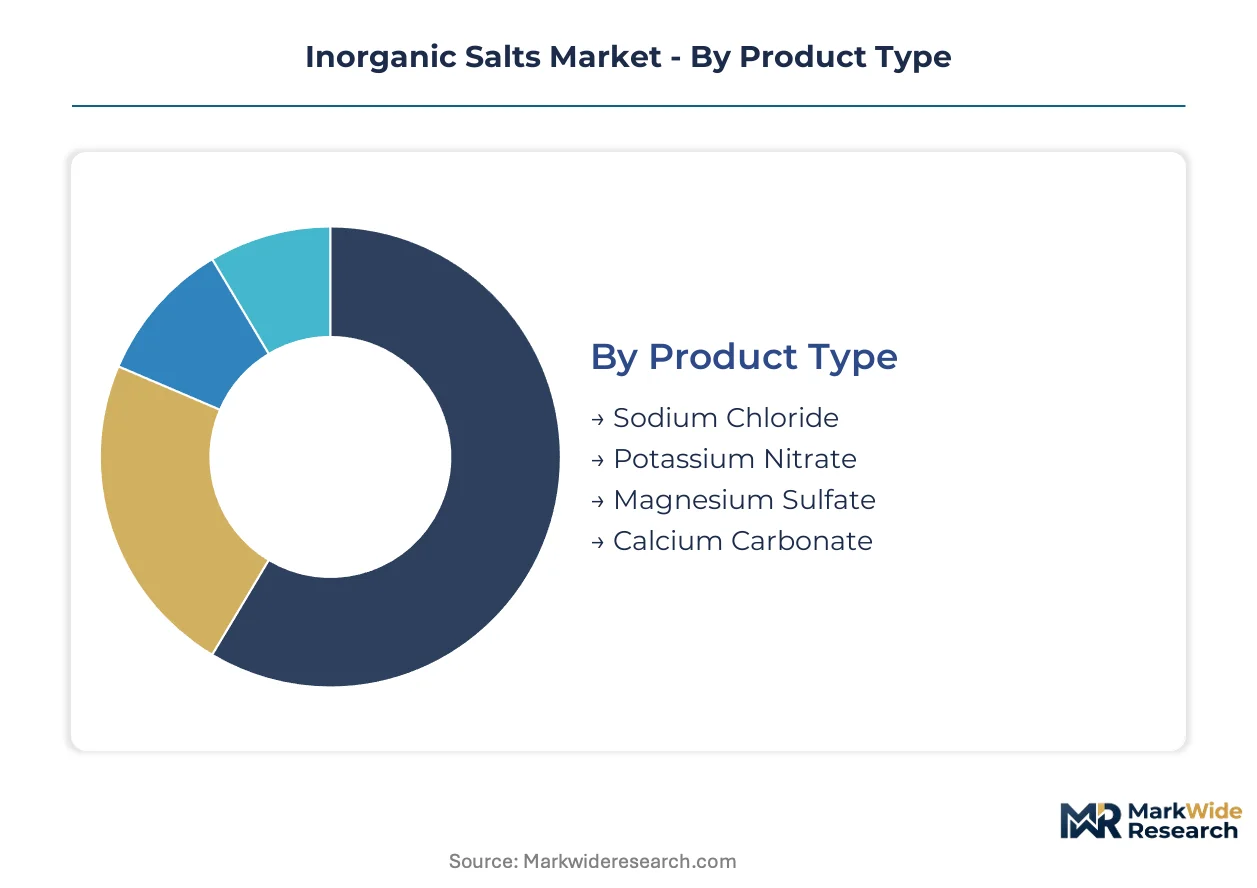
Inorganic salts serve fundamentally different economic functions depending on purity grade and end-use certification. Segmentation reveals how pharmaceutical-grade sodium chloride commands multiples over road salt, while agricultural potassium nitrate volumes dwarf specialty chemical applications.
Product Type:
Margin pools concentrate in certified pharmaceutical and food-grade tiers where USP monographs create qualification barriers, leaving commodity chlor-alkali feedstock to compete on energy-integrated cost positions.
- Sodium Chloride:Crystalline ionic compound with NaCl stoichiometry, varying from 99.5%+ purity for intravenous solutions to rock salt for de-icing. Demand concentrates in China's chemical corridor for chlor-alkali feedstock, sustained by state-owned enterprise capacity expansions under MEE environmental enforcement.
- Calcium Carbonate:Alkaline earth salt with acid-neutralizing capacity and controlled particle size distribution for tablet excipients. Pharmaceutical and food additive applications in the United States generate premium positioning through FDA food contact compliance and USP certification requirements.
- Potassium Nitrate:Dual-nutrient fertilizer source with controlled solubility for fertigation systems. Precision agriculture adoption in Israel and the Netherlands drives formulation demand.
- Magnesium Sulfate:Hydrated salt with osmotic and flocculation properties for water treatment and medical applications. Municipal utility procurement in Texas and California expands for pH correction chemistry.
The dominant share belongs to sodium chloride, while calcium carbonate is closing the gap fastest through pharmaceutical certification premiums.
Application:
Application segmentation tracks how regulatory jurisdiction shapes profitability—EPA discharge permits and REACH registration create tiered pricing structures that separate commodity from certified grades.
- Agriculture:Soil amendment and fertigation applications consuming potassium nitrate and magnesium sulfate for macronutrient delivery. Controlled-release formulation adoption in the Netherlands concentrates demand for soluble salt grades with specified dissolution kinetics.
- Pharmaceuticals:Intravenous solutions, tablet excipients, and dialysis concentrates requiring USP and EP monograph compliance. Heavy metal thresholds under REACH Annex XVII and FDA regulations enforce 18-24 month validation cycles that constrain supplier entry.
- Food Additives:pH buffering, preservation, and texturizing functions across processed food manufacturing. EFSA and FDA food contact regulations segment the market by purity certification.
- Water Treatment:Coagulation, flocculation, and pH adjustment in municipal and industrial effluent systems. EPA Clean Water Act enforcement drives magnesium sulfate and calcium carbonate procurement by large utility authorities in Florida and California.
Agriculture maintains volume leadership, though pharmaceuticals is expanding most quickly through intravenous-grade certification requirements.
End User:
End user concentration reveals how captive brine well ownership and on-site processing infrastructure determine competitive viability across customer categories.
- Chemical Industry:Chlor-alkali producers, fertilizer manufacturers, and specialty chemical synthesizers consuming sodium chloride and potassium nitrate as feedstock. China's state-owned enterprises absorb massive volumes through integrated complexes with membrane electrolysis technology.
- Healthcare:Hospital systems, dialysis centers, and pharmaceutical manufacturers requiring certified pharmaceutical-grade salts. USP monograph compliance and FDA regulations enforce supplier qualification barriers.
- Manufacturing:Process control, metal treatment, and industrial water conditioning applications. Energy cost volatility affects European manufacturing corridors most severely.
- Construction:Cement additives, concrete accelerators, and de-icing applications for infrastructure projects. Seasonal demand patterns in northern United States states create inventory management challenges.
Chemical industry offtake dominates absolute volumes, while healthcare is gaining share fastest through certification-driven supplier consolidation.
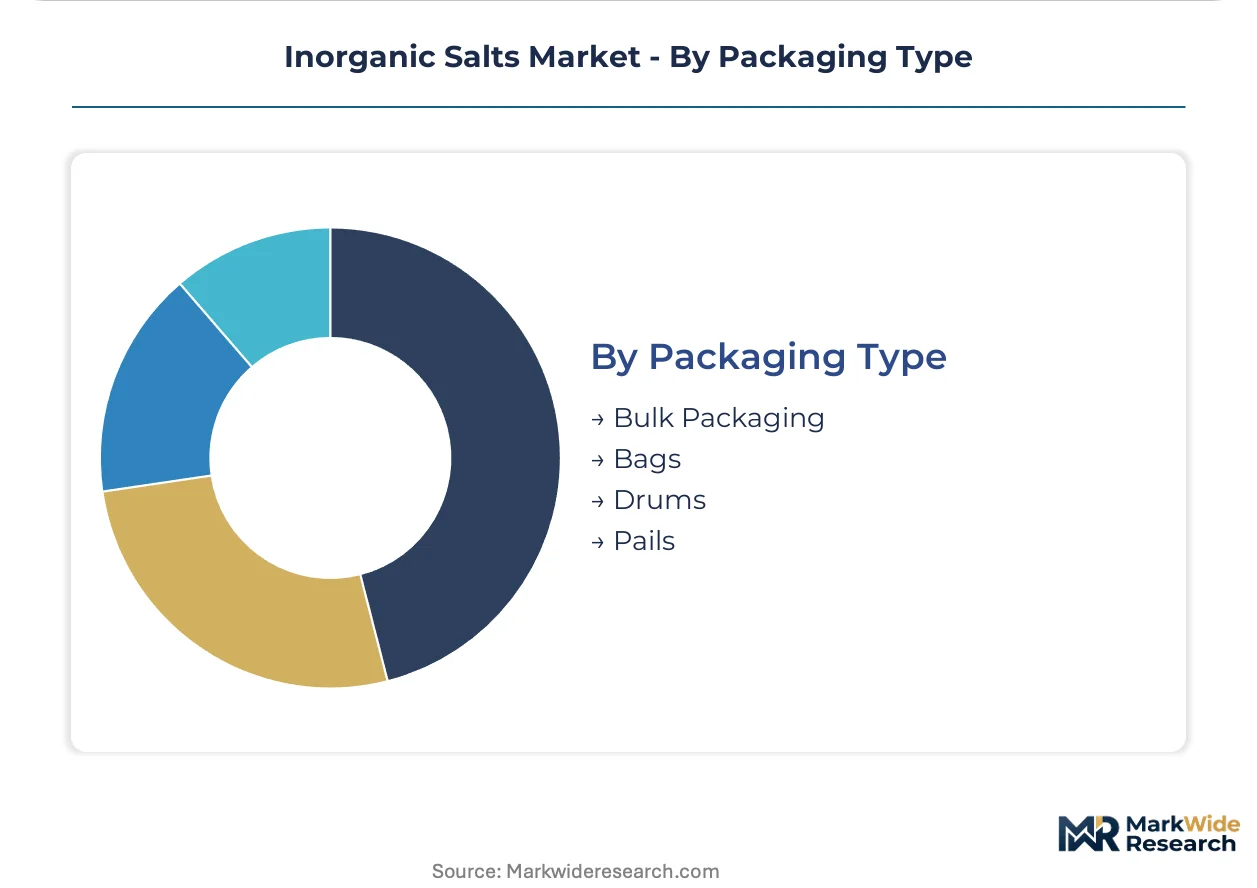
Packaging Type:
Packaging economics reflect the tension between bulk logistics efficiency and contamination control requirements for certified grades.
- Bulk Packaging:Tanker trucks, railcars, and vessel shipments for chlor-alkali feedstock and agricultural fertilizer applications. Direct-to-municipality contracting in Texas and California bypasses distributor networks for water treatment chemicals.
- Bags:Multi-wall paper or woven polypropylene for food-grade and technical-grade salts. Food additive manufacturers in the United States require lot traceability and third-party laboratory certification.
- Drums:Steel or fiber containers for pharmaceutical-grade and high-purity specialty salts. USP monograph compliance necessitates dedicated handling protocols.
- Pails:Small-format packaging for laboratory, retail, and specialty chemical applications. Limited volumes but highest per-unit margins.
Bulk packaging handles the majority of tonnage, though bags are climbing the fastest as food-grade certification requirements expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes inorganic salts primarily as chlor-alkali feedstock, while the United States and Europe concentrate demand in water treatment and pharmaceutical certification tiers. This consumption-mix differential shapes regional competitive dynamics and regulatory exposure.
China
State-owned enterprises absorb massive sodium chloride volumes for membrane electrolysis complexes in the Yangtze River Delta. MEE environmental enforcement accelerates retrofit timelines from mercury and diaphragm technologies. Qinghai's salt lake extraction anchors potassium nitrate supply for fertilizer and chemical synthesis.
United States
EPA Clean Water Act enforcement drives municipal utility procurement of magnesium sulfate and calcium carbonate for flocculation chemistry. Large utility authorities in Texas, California, and Florida negotiate multi-year direct contracts. The Gulf Coast chemical corridor sustains chlor-alkali feedstock demand alongside specialty salt refining.
Germany
REACH Annex XVII restrictions on heavy metal content force upstream purification investments for food-contact and cosmetic-grade salts. ECHA compliance audits have expanded to Indian and Turkish export refiners serving German manufacturers. The Rhine-Ruhr industrial region concentrates pharmaceutical-grade certification demand.
India
Domestic chlor-alkali capacity expansion absorbs regional sodium chloride production, while pharmaceutical-grade salt exports face 18-24 month USP validation cycles. The country's national pharmaceutical regulator enforces heavy metal thresholds aligned with FDA and EMA standards. Gujarat's chemical corridor hosts specialty refiners targeting intravenous-grade certification gaps.
Brazil
Precision agriculture adoption in São Paulo and Minas Gerais concentrates demand for potassium nitrate in controlled-release fertigation systems. ANVISA pharmaceutical regulations create compliance barriers for imported pharmaceutical-grade salts. Domestic refiners invest in USP monograph compliance to capture margin expansion in Latin American healthcare supply chains.
Inorganic Salts Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with membrane electrolysis technology and pharmaceutical certification creating divergent capital requirements. Integrated chlor-alkali producers leverage captive brine wells and on-site processing infrastructure to control raw material costs. Specialty salt refiners compete through USP and EP monograph compliance for intravenous-grade and food-additive applications. Capacity expansion and strategic partnerships dominate competitive moves, with direct-to-municipality contracting bypassing traditional distributor networks.
Within the integrated chemical tier, Solvay and Lanxess AG exemplify European producers with backward integration into soda ash and salt platforms. Merck KGaA occupies a position in the pharmaceutical-grade specialist tier, representing ultra-high-purity production protocols that command premium positioning in healthcare supply chains. Thermo Fisher Scientific Inc. sits within the laboratory and analytical reagent segment, serving quality control and research applications where trace metal detection capabilities determine supplier selection.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Merck KGaA |
| Lanxess AG |
| Thermo Fisher Scientific Inc. |
| BEHN MEYER |
| GFS Chemicals, Inc. |
| Otsuka Chemical Co., Ltd |
| Solvay |
| Arkema |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day inventory cycles for pharmaceutical-grade sodium chloride tie working capital exposure directly to membrane electrolysis capacity decisions in China and REACH-driven purification investments in Europe, compressing margin buffers for commodity refiners while amplifying pricing power for certified-tier producers.
Pricing Analysis
Long-term offtake agreements dominate chlor-alkali feedstock procurement, locking in volume commitments between Chinese state-owned enterprises and integrated chemical complexes. Three-tier pricing structure across pharmaceutical, food-grade, and technical tiers separates USP-certified intravenous salts from road salt by order of magnitude. Cost compression in commodity sodium chloride intensifies because MEE environmental enforcement accelerates mercury-cell retrofit timelines. Municipal water utilities exhibit lowest price sensitivity due to regulatory compliance mandates, while construction de-icing buyers face acute seasonal volatility.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for Indian and Turkish refiners serving German pharmaceutical manufacturers. Supply concentrates in China's Qinghai salt lake corridor for potassium nitrate, Germany's Rhine-Ruhr industrial region for pharmaceutical certification, and the US Gulf Coast for chlor-alkali integration. Production draws from captive brine wells, membrane electrolysis cell assemblies, and third-party analytical certification services. Single-source vulnerability in Qinghai's potassium extraction creates structural exposure to MEE production quotas. Distribution runs through direct-to-municipality contracting for water treatment chemicals, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ICP-MS and ion chromatography expertise for trace heavy metal detection commands premium wages that constrain quality control expansion, creating a capability bottleneck that separates integrated certification holders from commodity refiners.
For Market Incumbents: Secure membrane electrolysis technology leadership through retrofit acceleration ahead of MEE enforcement deadlines in China's Yangtze River Delta. Deepen upstream control over captive brine wells in Qinghai and Gujarat to offset potassium salt concentration risk. Pharmaceutical-grade certification investments of 18-24 month duration build moats against mid-scale Indian and Brazilian challengers targeting intravenous-grade gaps. For New Entrants and Emerging Players: Contract analytical services for REACH Annex XVII heavy metal certification represent the most penetrable service layer, as incumbent refiners under-serve Indian and Turkish export markets facing expanded ECHA audits. Target Brazilian ANVISA pharmaceutical compliance for regional healthcare supply chain integration. Lead with third-party laboratory partnerships rather than capital-intensive purification infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because certification barriers and energy-integrated cost positions favor scale over fragmentation. Acquisition candidates include mid-scale Indian refiners with partial USP compliance and verified Scope 1-3 emissions data for EU Green Deal positioning. Watch membrane electrolysis retrofit completion rates in China as inflection signal for commodity-grade margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Electrolysis Retrofit | MEE enforcement in China eliminates mercury handling liabilities while compressing viable scale thresholds for new capacity. |
| Pharmaceutical-Grade Certification | USP and EP monograph compliance creates 18-24 month validation cycles that constrain supplier entry in intravenous-grade segments. |
| Direct-to-Municipality Contracting | Texas and California utility authorities negotiate multi-year supply agreements that bypass distributor networks for flocculation chemicals. |
| Low-Carbon Emissions Verification | EU Green Deal carbon border adjustments reward producers with verified Scope 1-3 data for soda ash and salt imports. |
| Captive Brine Well Development | On-site processing infrastructure in Qinghai and Gujarat secures raw material cost control against potassium salt supply concentration. |
Methodological Framework
A standing panel of chlor-alkali plant managers, pharmaceutical procurement leads, municipal water utility chemists, and REACH compliance officers provided ongoing calibration across primary interview rounds. Secondary validation drew from MEE environmental enforcement disclosures, ECHA registration databases, EPA Clean Water Act permit filings, and customs trade data for sodium chloride and potassium nitrate flows. Bottom-up volume modeling triangulated against top-down chemical industry consumption estimates.
Consistency checks against external benchmarks validated projection outputs across the analysis window. Segmentation dimensions modeled include purity grade tier, end-use application, packaging format, and regional production hub. CAGRs derived from weighted average of historical trajectory and forward capacity announcements. Forecast inputs incorporated membrane electrolysis retrofit timelines, REACH Annex XVII heavy metal threshold evolution, and fertigation system adoption curves in precision agriculture markets.
Material uncertainties — energy cost volatility in European manufacturing corridors, MEE enforcement intensity variations, and substitution by organic acids in food preservation — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory harmonization between EPA, ECHA, and China's MEE. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
China Feed Minerals Market
Industrial Minerals
Calcined Anthracite Market
Industrial Minerals
Potassium Schoenite Market
Industrial Minerals
Micronized Salt Market
Industrial Minerals
Fluorspar Market
Industrial Minerals
Unexpanded Perlite Market
Industrial Minerals
Dolomite Mining Market
Industrial Minerals
Slate Market
Industrial Minerals
Global Cristobalite Market
Industrial Minerals
Global Carbonate Minerals Market
Industrial Minerals
Talc Market
Industrial Minerals
Global Feed Minerals Market
Industrial Minerals
Kyanite Market
Industrial Minerals
Nepheline Syenite Market
Industrial Minerals
Seaweed Derived Minerals Market
Industrial Minerals
North America Limestone Market