
 Morocco Seed Market | 2026-2036
Morocco Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Morocco Seed Market Foresight
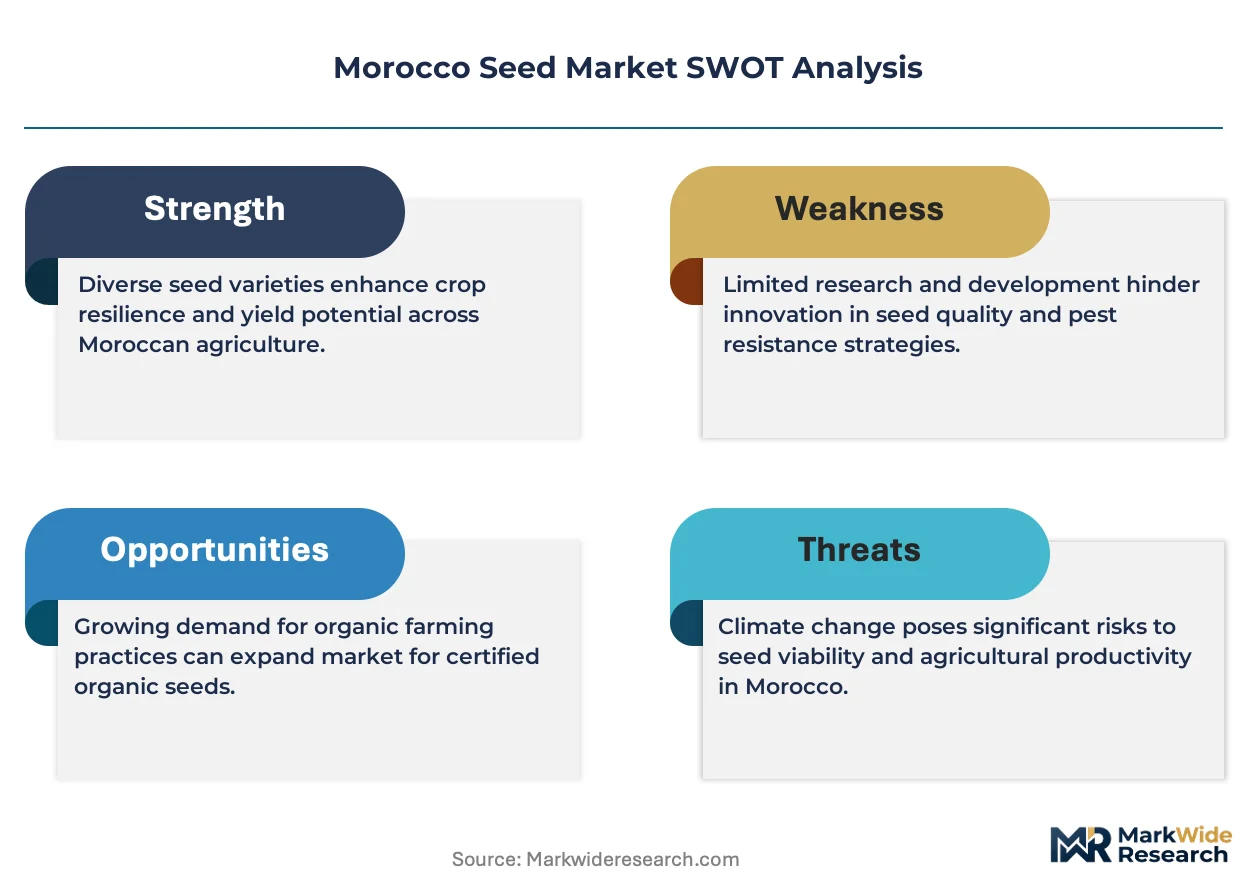
Marker-assisted selection and precision phenotyping is rewriting varietal development cycles for Moroccan growers. Syngenta Group Co., Ltd. leverages its global trait pipeline to supply heat-tolerant vegetable hybrids calibrated for Morocco's semi-arid zones. BASF SE anchors its position through disease-resistant oilseed genetics tailored to Saïss Plain conditions. East-West Seed International Ltd. specializes in tropical vegetable varieties that perform in Morocco's southern greenhouse clusters.
Seeds are living biological units containing embryonic plants, nutrient reserves, and protective coatings, engineered through controlled pollination, genetic selection, or biotechnological intervention to achieve specified germination rates, purity thresholds, and trait expression for agricultural propagation. Cereal seeds occupy the dominant volume share given Morocco's wheat and barley self-sufficiency targets, while vegetable seeds command premium pricing due to protected cultivation expansion. The distribution channel structure tilts toward agricultural cooperatives in cereal zones and retail nurseries in peri-urban horticulture belts, reflecting divergent farmer scale and technical support requirements.
Morocco's Ministry of Agriculture and Maritime Fisheries enforces seed certification through national variety registration and field inspection protocols that filter uncertified germplasm from commercial circulation. The country's alignment with OECD seed schemes and UPOV conventions shapes intellectual property treatment for imported proprietary genetics. Stakeholders must monitor how drought-frequency adaptation criteria in national variety trials reshape eligibility lists for subsidized seed programs.
Market Dynamics
Morocco's seed market is being fundamentally restructured by the Ministry of Agriculture's tightening certification protocols, which are filtering uncertified germplasm from commercial circulation and elevating quality benchmarks for cereal and vegetable varieties entering subsidized distribution channels.
Growth Catalysts
- OECD Seed Scheme Alignment:Morocco's adherence to international variety certification standards is accelerating cross-border germplasm flows and enabling proprietary hybrid imports from European breeding programs.
- Irrigated Perimeter Expansion:Commercial farmers across the Doukkala-Abda and Tadla-Azilal basins are scaling hybrid seed procurement as water-efficient cultivation intensifies.
- Heat-Tolerant Trait Pipelines:Marker-assisted selection protocols are compressing varietal development cycles for semi-arid zone adaptation.
Market Restraints
- Import Dependency for Oilseed Genetics:Domestic breeding capacity gaps force reliance on foreign germplasm for sunflower and rapeseed varieties, exposing buyers to currency fluctuation risk.
- Certification Timeline Friction:Multi-season field trials under national variety registration protocols delay commercialization of improved genetics by two to four growing cycles.
- Subsidy Allocation Rigidity:Fixed-price support mechanisms for certified cereal seeds limit margin flexibility for distributors when input costs spike.
Strategic Opportunities
- Southern Greenhouse Cluster Development:Tropical vegetable varieties calibrated for protected cultivation in Morocco's arid south represent an underpenetrated segment with premium pricing potential.
- Cooperative Distribution Modernization:Digital inventory management and mobile payment integration within agricultural cooperatives could unlock working capital efficiencies for smallholder cereal farmers.
- Drought-Frequency Adaptation Mandates:Revised eligibility criteria for subsidized seed programs favor varieties with demonstrated water-stress tolerance, creating first-mover advantage for breeders with relevant trait libraries.
Industry Challenges
- Phenotyping Skill Scarcity:Precision agriculture deployment requires trained technicians capable of operating remote sensing and spectral analysis equipment, a competency pool that remains thin outside Casablanca and Rabat research stations.
- Legacy Germplasm Integration:Farmers in rainfed zones maintain seed-saving practices that conflict with hybrid replacement cycles, complicating variety turnover campaigns.
- Certification Inspection Bottlenecks:Limited field inspector capacity at the Ministry of Agriculture stretches batch approval timelines during peak sowing seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morocco Seed Market |
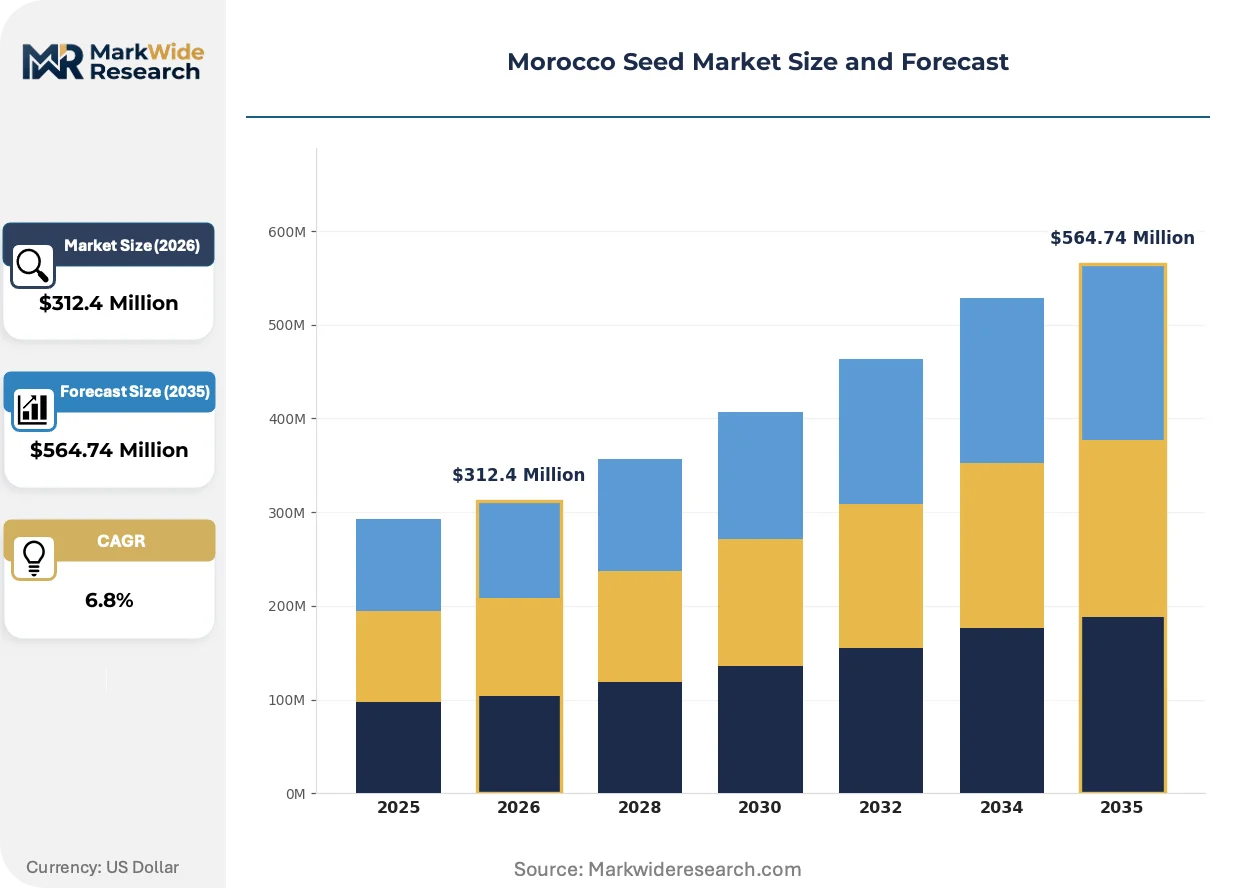
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cereal Seeds, Vegetable Seeds, Flower Seeds, Oilseeds Distribution Channel: Retail Nurseries, Online Stores, Agricultural Cooperatives, Wholesalers End User: Commercial Farmers, Home Gardeners, Agricultural Enterprises, Research Institutions Application: Crop Production, Landscaping, Horticulture, Ecological Restoration |
| Companies Covered | Rijk Zwaan Maroc SARL, Syngenta Group Co., Ltd., BASF SE, Agrosem SARL, East-West Seed International Ltd., Takii & Co., Ltd., Known-You Seed Company, Enza Zaden Beheer B.V., QualiBasic Seed Company Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morocco Seed Market Shifts & Advancements
Digital phenotyping platforms and molecular breeding tools are compressing variety development timelines while regulatory alignment with international seed schemes is reshaping intellectual property treatment for imported genetics across Morocco's agricultural value chain.
Spectral imaging and drone-based field monitoring are digitizing trait assessment workflows for Moroccan breeding stations. Research institutions in the Saïss Plain and Chaouia-Ouardigha regions are deploying these platforms to accelerate heat-tolerance screening. The technology is digitizing data capture protocols that previously required manual scoring across multiple growing seasons.
Morocco's Ministry of Agriculture is enforcing stricter field inspection protocols under national variety registration guidelines that filter uncertified germplasm from subsidized distribution channels. The policy is elevating quality benchmarks for cereal and vegetable entries. Smallholder cooperatives in the Doukkala-Abda basin are responding by consolidating procurement through certified distributor networks to maintain subsidy eligibility.
Direct-to-farm digital ordering platforms are emerging as an alternative channel for vegetable seed distribution in peri-urban horticulture belts around Casablanca and Marrakech. Retail nurseries that historically dominated transaction flow are losing share to mobile-enabled cooperatives that aggregate smallholder demand. The shift is most visible among greenhouse tomato and pepper growers seeking technical support bundled with varietal recommendations.
Morocco Seed Market Segmentation
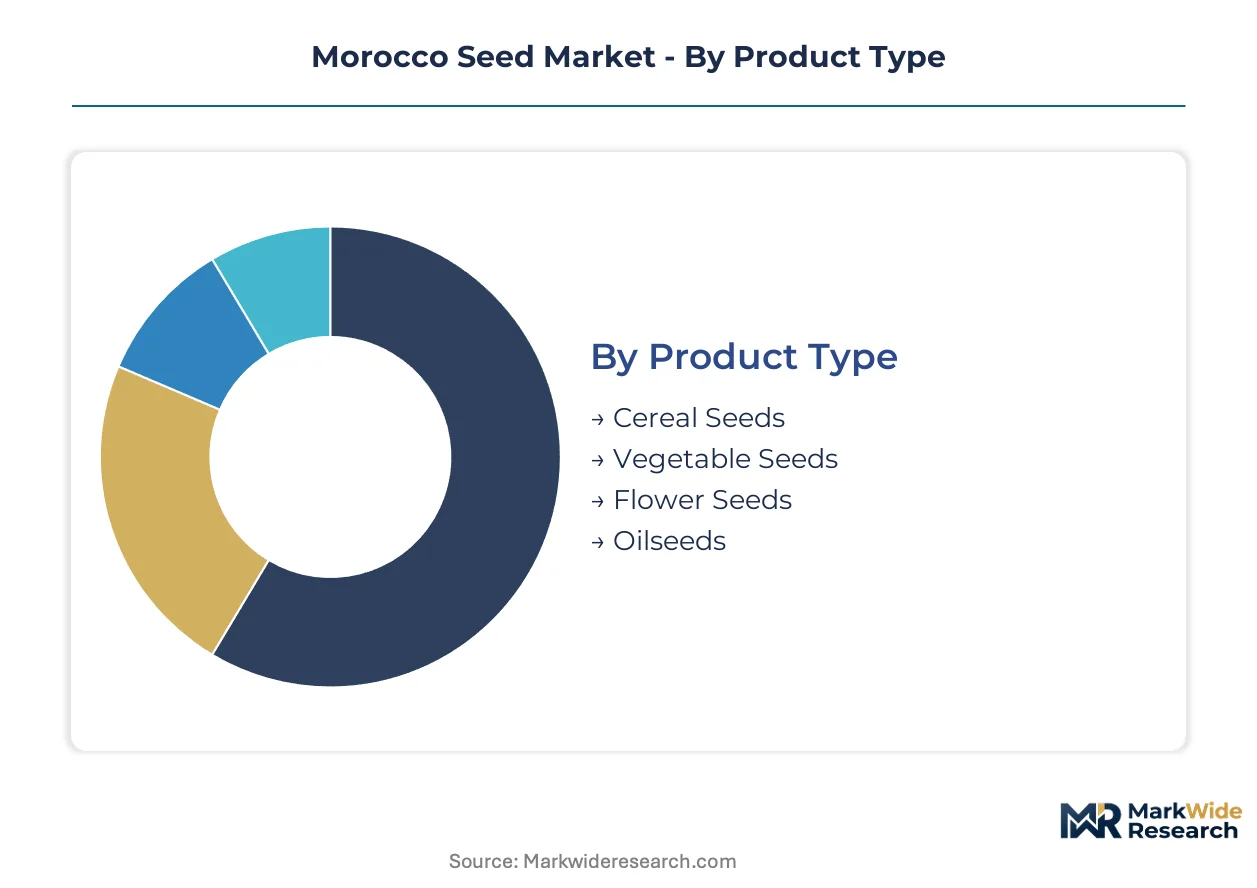
Seed procurement patterns across Morocco diverge sharply between irrigated commercial zones and rainfed smallholder territories. Understanding these segment boundaries reveals where subsidy eligibility, certification requirements, and distribution infrastructure create divergent competitive arenas.
Product Type:
Cost tier differentiation separates commodity bulk seeds from proprietary hybrid genetics with trait premiums.
- Cereal Seeds:Wheat and barley varieties dominate procurement volumes under Morocco's food self-sufficiency mandate. Demand concentrates in the Doukkala-Abda and Tadla-Azilal basins where subsidized certified seed programs drive farmer adoption cycles aligned with Ministry of Agriculture quality benchmarks.
- Vegetable Seeds:Heat-tolerant tomato, pepper, and cucumber hybrids command price premiums in protected cultivation zones. Greenhouse clusters around Agadir and Marrakech source tropical varieties calibrated for semi-arid stress conditions, with technical support bundled into distributor relationships.
- Flower Seeds:Ornamental varieties serve landscaping contractors and export-oriented cut-flower operations near Casablanca's port infrastructure.
- Oilseeds:Sunflower and rapeseed germplasm relies almost entirely on imported genetics, exposing commercial farms to currency fluctuation risk.
Cereal seeds command the established base. The steepest expansion runs through vegetable seeds.
Distribution Channel:
Customer type and farm scale dictate channel selection, with cooperatives serving consolidated smallholder demand versus retail touchpoints for peri-urban horticulture.
- Agricultural Cooperatives:Federated buying structures in cereal zones aggregate procurement for subsidy-eligible certified seed distribution. Digital inventory tracking and mobile payment integration are modernizing working capital flows for Doukkala-Abda basin members.
- Retail Nurseries:Peri-urban outlets around Casablanca and Marrakech dominate vegetable seed transactions, though share erosion to digital platforms accelerates among greenhouse operators seeking bundled technical advice.
- Online Stores:Direct-to-farm ordering platforms emerge as an alternative channel for peri-urban horticulture belts, particularly among tomato and pepper growers.
- Wholesalers:Volume distributors bridge imported oilseed genetics from European breeding programs to Saïss Plain commercial farms.
Agricultural cooperatives anchor volume throughput. Online stores are gaining share fastest among peri-urban greenhouse operators.
End User:
Application maturity and technical sophistication separate professional cultivation from amateur consumption.
- Commercial Farmers:Irrigated perimeter operators in Tadla-Azilal and Doukkala-Abda basins procure hybrid seeds through certified distributor networks to maintain subsidy eligibility under Ministry of Agriculture protocols.
- Agricultural Enterprises:Large-scale operations with in-house agronomy teams source directly from international breeding programs, bypassing domestic distribution layers.
- Home Gardeners:Amateur cultivators in urban peripheries drive flower seed and heritage vegetable variety demand through retail nursery channels.
- Research Institutions:Saïss Plain and Chaouia-Ouardigha breeding stations utilize spectral imaging and drone-based phenotyping for heat-tolerance screening protocols.
Commercial farmers represent the revenue core. Agricultural enterprises are expanding procurement most aggressively.
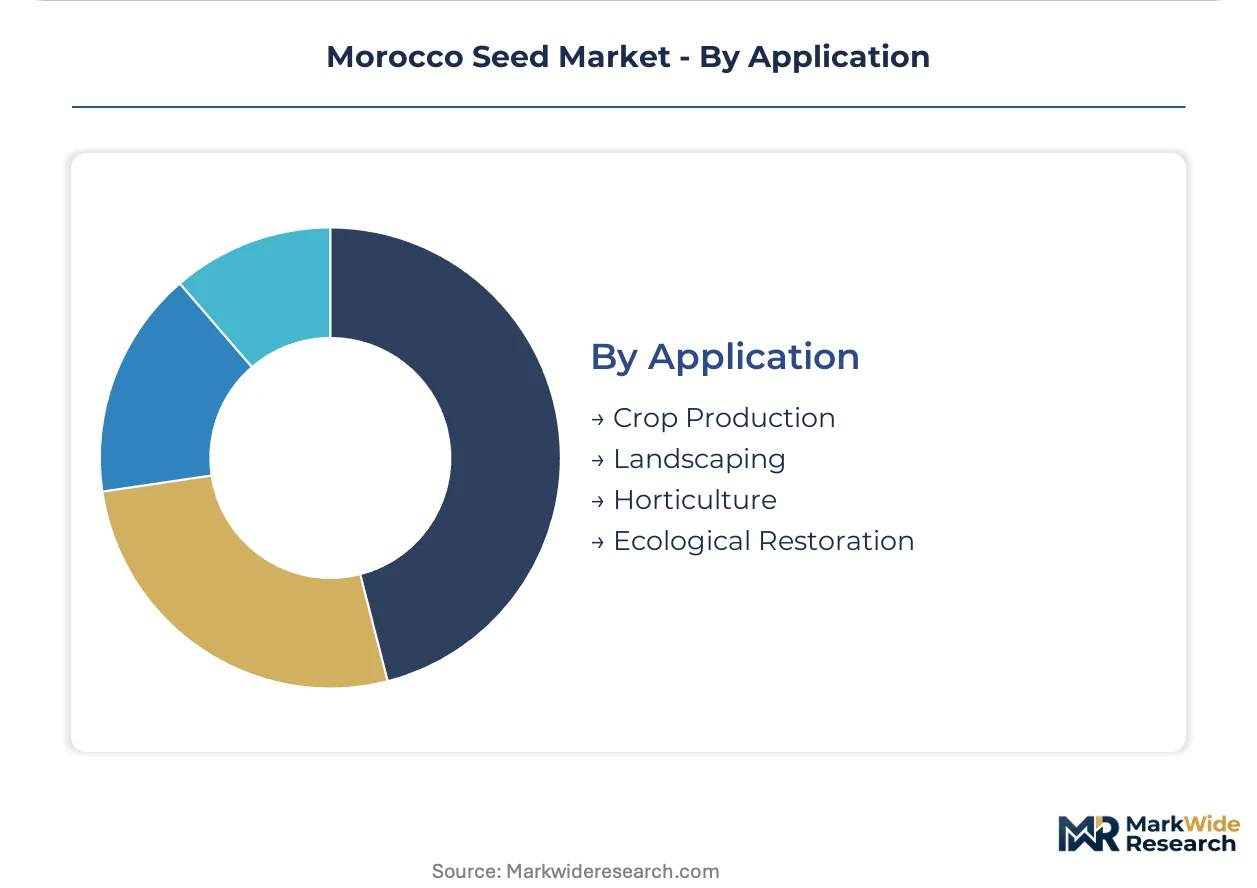
Application:
Volume scale and margin structure diverge between commodity crop production and specialized horticultural output.
- Crop Production:Cereal cultivation for domestic food security targets absorbs the majority of certified seed volume, with national variety registration protocols filtering germplasm eligibility for subsidized programs.
- Horticulture:Protected vegetable cultivation in southern greenhouse clusters generates premium pricing for heat-tolerant hybrids, with technical service bundling differentiating distributor relationships.
- Landscaping:Urban development projects around Rabat and Casablanca sustain ornamental flower seed demand for municipal and private contracts.
- Ecological Restoration:Drought-frequency adaptation mandates create emerging demand for native species germplasm in degraded rangeland rehabilitation programs.
Crop production anchors volume scale. Horticulture delivers the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France and the Netherlands export proprietary hybrid genetics through Mediterranean trade corridors into Morocco's agricultural basins, with Dutch breeding programs supplying heat-tolerant vegetable varieties and French cooperatives channeling certified cereal germplasm.
Doukkala-Abda Basin
Large-scale wheat and barley cultivation drives certified seed procurement through agricultural cooperatives. Morocco's Ministry of Agriculture enforces national variety registration protocols that filter germplasm eligibility for subsidized distribution. The El Jadida corridor concentrates commercial farming operations scaling hybrid adoption under irrigation expansion programs.
Tadla-Azilal Basin
Water-efficient cultivation intensifies demand for certified cereal seeds aligned with food self-sufficiency targets. Field inspection protocols under OECD seed scheme alignment accelerate cross-border germplasm flows from European breeding programs. Beni Mellal anchors procurement volume as commercial farmers consolidate through federated buying structures.
Saïss Plain
Oilseed cultivation exposes commercial farms to currency fluctuation risk through import dependency for sunflower and rapeseed genetics. National seed certification timelines delay commercialization of improved varieties by multiple growing cycles. Meknès-Fès hosts research stations deploying spectral imaging for heat-tolerance screening protocols.
Southern Greenhouse Clusters
Protected vegetable cultivation generates premium pricing for tropical varieties calibrated to semi-arid stress conditions. Direct-to-farm digital ordering platforms erode traditional retail nursery share among tomato and pepper growers. Agadir and Marrakech peri-urban belts concentrate greenhouse operators seeking technical support bundled with varietal recommendations.
Chaouia-Ouardigha Region
Rainfed cereal zones maintain seed-saving practices that conflict with hybrid replacement cycles, complicating variety turnover campaigns. Drought-frequency adaptation mandates in subsidized seed programs favor water-stress tolerant varieties. Khouribga and Settat sub-regions host breeding stations integrating drone-based phenotyping into trait assessment workflows.
Morocco Seed Market Competitive Landscape
On the supply side, the industry is tiered between multinational breeding conglomerates with global trait pipelines and regional specialists with localized variety portfolios. Three strategic archetypes dominate: proprietary hybrid developers leveraging marker-assisted selection, cooperative-aligned distributors navigating subsidy eligibility protocols, and research-backed stations supplying certified germplasm to national programs. Competitive moves concentrate on technology licensing partnerships and portfolio diversification into heat-tolerant trait categories.
Within the multinational tier, Syngenta Group Co., Ltd. and BASF SE anchor positions through global breeding infrastructures, while East-West Seed International Ltd. occupies a specialist niche. Rijk Zwaan Maroc SARL exemplifies the regional subsidiary model. These players represent divergent geographic origins—Swiss-German conglomerates versus Netherlands-based and Asia-Pacific specialists—each sitting within distinct competitive vectors shaped by trait library depth and distribution channel alignment.
| Leading Market Players |
|---|
| Rijk Zwaan Maroc SARL |
| Syngenta Group Co., Ltd. |
| BASF SE |
| Agrosem SARL |
| East-West Seed International Ltd. |
| Takii & Co., Ltd. |
| Known-You Seed Company |
| Enza Zaden Beheer B.V. |
| QualiBasic Seed Company Ltd. |
| Others |
Supply & Pricing Matrix
Undercapacity in Morocco's domestic breeding infrastructure for oilseed genetics compresses margins across the import-dependent tier while elevating pricing power for European suppliers with certified heat-tolerant trait libraries. The Ministry of Agriculture's subsidy allocation rigidity locks distributor margins during input cost spikes, forcing procurement consolidation through cooperative networks.
Pricing Analysis
Prior-generation open-pollinated varieties trade at commodity benchmarks while current-generation certified hybrids command certification-grade premiums and next-generation marker-assisted selections fetch trait-specific markups. Three-tier pricing structure across certified premium hybrids, standard registered varieties, and uncertified economy lots segments the Moroccan market. Price differentiation hinges on Ministry of Agriculture certification tier and bundled technical support intensity. Cost compression in the economy tier intensifies as seed-saving practices in rainfed zones erode replacement-cycle frequency. Smallholder cooperatives in Doukkala-Abda exhibit acute price sensitivity, whereas greenhouse operators around Agadir prioritize heat-tolerance performance over unit cost.
Supply Chain Analysis
Upstream germplasm feeds from French cereal breeding programs, Dutch vegetable genetics houses, and German oilseed trait developers. Raw material dependencies center on proprietary hybrid parent lines, molecular marker libraries, and certified seed multiplication stock. Single-source vulnerability concentrates in sunflower and rapeseed genetics where domestic breeding gaps persist. Distribution runs through agricultural cooperatives for cereal zones and retail nurseries for peri-urban horticulture, with digital platforms eroding traditional channel share among greenhouse operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across Morocco's seed market creates niche entry points as drought-frequency adaptation mandates splinter subsidy eligibility criteria and digital distribution disrupts legacy cooperative structures.
For Market Incumbents: Entrench certification moats by deepening backward integration into heat-tolerance trait libraries and securing exclusive Ministry of Agriculture variety registration pipelines. Counter digital platform erosion by embedding mobile-enabled technical advisors within cooperative procurement workflows. Capacity addition in Chaouia-Ouardigha phenotyping infrastructure defends against research-backed entrants. For New Entrants and Emerging Players: Pursue southern greenhouse cluster penetration with tropical vegetable varieties calibrated for semi-arid stress conditions, where technical service bundling gaps persist among incumbent distributors. Target peri-urban Marrakech tomato and pepper operators through direct-to-farm digital ordering platforms with integrated agronomic advisory. Cooperative distribution modernization offers the most penetrable go-to-market angle for working capital efficiency plays. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cooperative-aligned distributors with locked subsidy program participation and multi-season farmer relationships. Long-term viability across the analysis window favors breeders with demonstrated water-stress tolerance trait libraries aligned to Ministry of Agriculture eligibility revisions. Acquisition focus should center on regional specialists with OECD seed scheme certification and established field inspection relationships. The signal to watch is Ministry of Agriculture drought-adaptation trial protocol amendments that reshape subsidized variety lists.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Tolerance Trait Library Expansion | Positions breeders for revised Ministry of Agriculture subsidy eligibility criteria favoring drought adaptation. |
| Cooperative Distribution Digitalization | Mobile payment integration and inventory tracking unlock working capital efficiencies for Doukkala-Abda smallholders. |
| OECD Seed Scheme Certification Investment | Accelerates cross-border germplasm flows from European breeding programs into Moroccan commercial channels. |
| Southern Greenhouse Technical Service Bundling | Differentiates distributor relationships among Agadir and Marrakech protected cultivation operators. |
| Field Inspection Capacity Expansion | Alleviates Ministry of Agriculture bottlenecks that stretch batch approval timelines during peak sowing seasons. |
Research Methodology
Operator-level perspectives from breeding station directors, cooperative procurement managers, greenhouse agronomists, and Ministry of Agriculture certification officials anchored the qualitative base. Primary interviews combined with secondary validation against customs records, OECD seed trade databases, and national variety registration filings. Bottom-up demand modeling triangulated against top-down agricultural production statistics across the analysis window.
Scenario-bracketing around drought-frequency adaptation mandates and subsidy program revisions shaped the projection framework. Segmentation dimensions modeled include product type, distribution channel, end-user archetype, and regional agricultural basin. CAGRs derived from trend-line extrapolation of certified seed adoption rates and protected cultivation expansion trajectories. Forecast inputs incorporated Ministry of Agriculture field inspection capacity constraints and European germplasm import flows.
Sensitivities concentrate around Ministry of Agriculture eligibility list revisions, currency fluctuation impacts on oilseed genetics imports, and digital platform adoption velocity among greenhouse operators. Forecasts reflect assumptions about subsidy continuity and OECD scheme alignment durability. Cross-checking against national agricultural census data and cooperative procurement records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Crambe Abyssinica Seed Oil Market
Seeds
Asia-Pacific Cotton Seed Market
Seeds
Global Alfalfa Seed Market
Seeds
Russia Seed Market
Seeds
Europe Chia Seeds Market
Seeds
Caraway Seeds Market
Seeds
Garlic Chive Seeds Market
Seeds
China Rice Seed Market
Seeds
Custom Selected Seed Market
Seeds
China Vegetable Seed Market
Seeds
Philippines Rice Seed Market
Seeds
Middle East and Africa Cannabis Seeds Market
Seeds
Poppy Seed Market
Seeds
Australia Oilseed Market
Seeds
Chamomile Seeds Market
Seeds
Melon Seed Market