
 Myanmar Seed Market | 2026-2036
Myanmar Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Myanmar Seed Market Foresight
A shift from farmer-saved seed toward commercial certified varieties is realigning Myanmar's agricultural input structure. Syngenta AG leverages its global germplasm library to anchor hybrid corn portfolios in the central dry zone. East-West Seed dominates vegetable seed segments through tropical-adapted breeding programs. Dagon Group of Companies controls domestic distribution networks, extending reach into township-level agro-dealer channels.
Seeds are reproductive biological units containing embryonic plants, nutrient reserves, and protective coats, engineered for specific germination rates, purity thresholds, and vigor indices that determine field establishment success. Their commercial purpose centers on transferring genetic improvement from breeding stations into farm-level productivity gains. Vegetable seeds capture premium margin pools due to shorter crop cycles and higher per-hectare input expenditure, while cereal seeds sustain volume throughput across Myanmar's monsoon paddy belts. Cooperative societies as a distribution channel are expanding fastest, though wholesale channels still occupy the largest throughput share in rural supply chains.
Myanmar's Seed Law, administered by the country's national seed committee, mandates varietal registration and quality certification for commercial seed lots. The Plant Variety Protection framework shapes incentives for foreign breeders to introduce proprietary hybrids rather than relying on public-domain varieties. Stakeholders must monitor how seed subsidy programs and import licensing procedures evolve under agricultural modernization priorities.
Market Dynamics
Myanmar's seed sector pivots on the tension between state-mandated varietal registration and farmer demand for unregistered but high-performing hybrids. The Seed Law's quality certification requirements create friction for informal seed networks while pulling commercial supply toward formal channels.
Growth Catalysts
- Plant Variety Protection framework:The PVP system incentivizes foreign breeders to introduce proprietary hybrids rather than public-domain varieties, expanding the certified seed pipeline.
- Cooperative societies:Township-level farmer cooperatives are building direct procurement relationships with seed companies, compressing distribution layers and lowering farmer acquisition costs.
- Vegetable seed premiumization:Short-cycle vegetable crops command higher per-hectare input expenditure, pulling smallholders toward certified varieties with documented germination rates and vigor indices.
Market Restraints
- Import licensing friction:Myanmar's seed import procedures create timeline uncertainty for foreign germplasm, particularly affecting hybrid maize and paddy seed availability during critical planting windows.
- Farmer-saved seed persistence:Informal seed networks in the Ayeyarwady Delta and Shan State supply self-pollinating cereal varieties at near-zero cost, compressing addressable market for certified alternatives.
- Quality control infrastructure gaps:Limited laboratory capacity for genetic purity testing and seed health certification constrains formal sector expansion into remote townships.
Strategic Opportunities
- Central Dry Zone corridor:Water-scarce regions around Mandalay present unmet demand for drought-tolerant hybrid maize and short-duration paddy varieties.
- Digital extension platforms:Mobile-based agronomic advisory services are creating new channel economics for seed companies to reach smallholders without physical agro-dealer presence.
- Seed subsidy program evolution:Agricultural modernization priorities signal potential restructuring of public seed support, creating entry points for private-sector certified variety participation.
Industry Challenges
- Seed analyst talent scarcity:Qualified personnel for germplasm evaluation and field performance testing remain concentrated in Yangon and Mandalay, constraining regional quality assurance.
- Variety registration timelines:The national seed committee's multi-season evaluation protocols delay commercialization of new hybrids, compressing effective product lifecycles.
- Climate adaptation breeding:Erratic monsoon patterns require accelerated development of stress-tolerant varieties, demanding R&D investment that outpaces current local capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myanmar Seed Market |
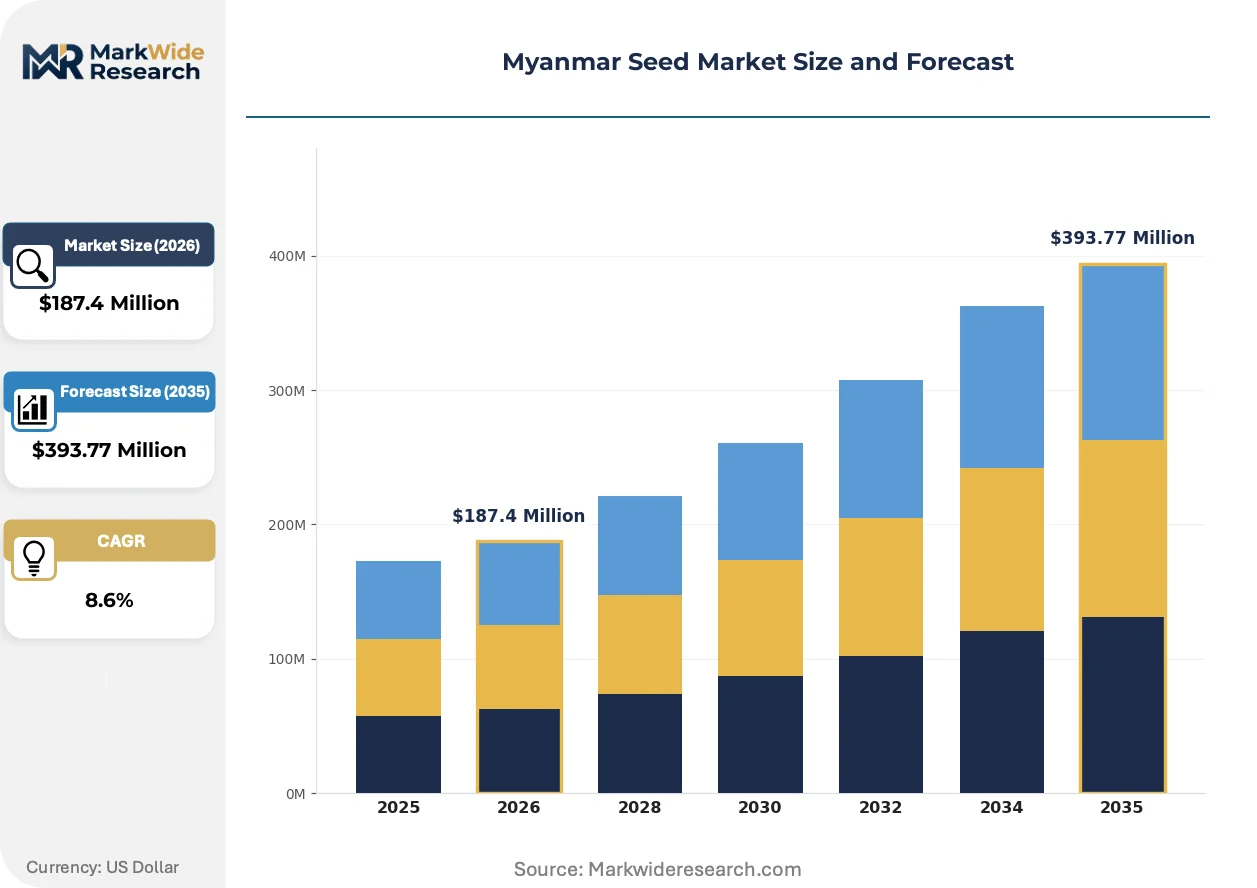
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Seeds, Cereal Seeds, Oilseed Seeds, Flower Seeds Distribution Channel: Retail, Wholesale, E-commerce, Cooperative Societies Crop Type: Paddy, Maize, Wheat, Pulses Packaging Type: Bulk Packaging, Seed Bags, Plastic Containers, Cartons |
| Companies Covered | Syngenta AG, Enza Zaden, Groupe Limagrain, Known You Seed Co LTD, Rijk Zwaan Zaadteelt en Zaadhandel B.V., East-West Seed, Bayer AG, Dagon Group of Companies, Charoen Pokphand Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myanmar Seed Market Shifts & Advancements
Biological innovation and regulatory adaptation are compressing Myanmar's seed value chain. Breeding programs, distribution architectures, and farmer purchasing patterns are all undergoing simultaneous recalibration.
Marker-assisted selection is decentralizing germplasm improvement capabilities. The technology enables rapid trait identification without multi-season field trials. Domestic breeding stations and regional research partnerships are adopting genomic tools to accelerate variety development. This capability diffusion is compressing the historical dependence on imported hybrid parent lines and enabling location-specific adaptation.
Myanmar's Seed Law implementation is tightening varietal registration enforcement. The national seed committee is expanding mandatory field inspection protocols for commercial seed lots. Vegetable seed segments face the steepest compliance ramps due to shorter breeding cycles and higher variety turnover. Companies are responding by pre-registering pipeline varieties and building regulatory affairs capacity in Yangon.
Agro-dealer consolidation is restructuring rural distribution. Township-level input retailers are forming buying cooperatives to negotiate directly with seed companies, bypassing traditional wholesale intermediaries. This channel compression is most visible in the Yangon corridor, where hybrid maize and vegetable seed volumes concentrate. Farmers gain price transparency while suppliers capture margin previously lost to distribution layers.
Myanmar Seed Market Segmentation
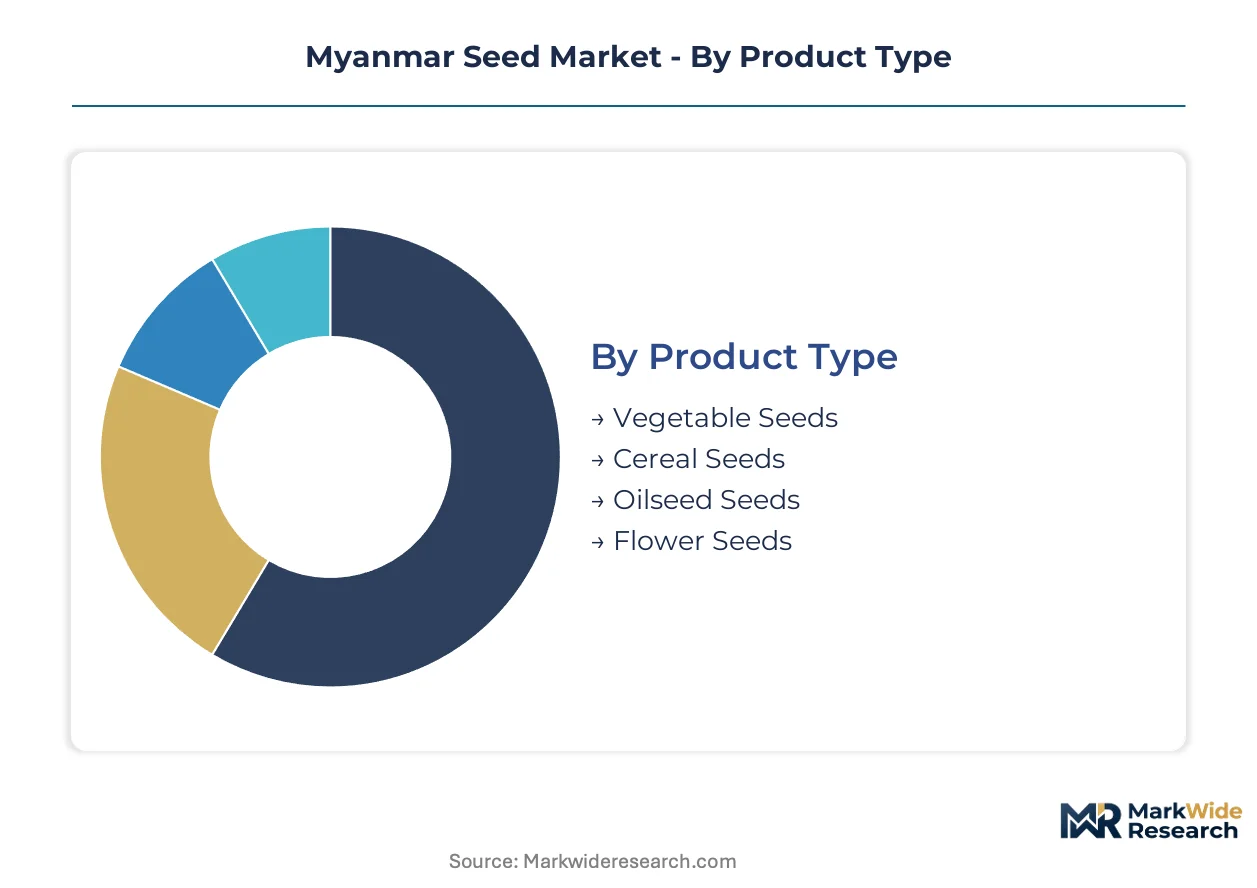
Myanmar's seed market stratifies across biological categories, logistical channels, and agronomic applications. Each segmentation dimension reveals distinct margin structures, regulatory exposure, and farmer purchasing patterns that shape commercial strategy.
Product Type:
Volume throughput concentrates in cereal staples, while margin capture concentrates in vegetable specialties.
- Vegetable Seeds:These seeds carry documented germination rates above 85% and vigor indices optimized for tropical humidity. Demand clusters in the Yangon and Mandalay corridors where smallholders cultivate short-cycle tomatoes, chilies, and gourds for urban wholesale markets, with certified varieties displacing farmer-saved lines due to predictable field establishment.
- Cereal Seeds:Hybrid maize and paddy varieties dominate tonnage flows through Myanmar's input supply chains. The Ayeyarwady Delta drives adoption of certified paddy seeds as the Seed Law's quality certification requirements tighten, though informal networks still supply self-pollinating varieties at minimal cost in remote townships.
- Oilseed Seeds:Sesame and groundnut varieties adapted to the Central Dry Zone's water-scarce conditions.
- Flower Seeds:Ornamental varieties for urban landscaping and export-oriented cut flower operations.
Today's leader: Cereal Seeds. Tomorrow's challenger: Vegetable Seeds.
Distribution Channel:
Channel economics diverge between physical infrastructure dependence and digital reach extension.
- Cooperative Societies:Township-level farmer cooperatives are compressing distribution layers by building direct procurement relationships with seed companies. This channel is expanding most quickly in the Mandalay corridor, where hybrid maize volumes justify consolidated purchasing power and members gain price transparency previously obscured by wholesale markups.
- Wholesale:Traditional intermediaries still occupy the largest throughput share in rural supply chains, particularly for paddy seed distribution across the Ayeyarwady Delta. These networks leverage established credit relationships with agro-dealers but face margin compression as cooperative buying groups consolidate demand.
- Retail:Township-level agro-dealer shops serving individual smallholder purchases.
- E-commerce:Mobile-based platforms enabling seed ordering with agronomic advisory bundling.
Wholesale channels anchor current volume. Cooperative societies are climbing the fastest.
Crop Type:
Water availability and crop duration determine hybrid penetration rates across Myanmar's agro-ecological zones.
- Paddy:Monsoon-dependent cultivation across the Delta and Shan State highlands. The national seed committee's varietal registration protocols prioritize paddy varieties, with multi-season field evaluation delaying commercialization of new hybrids and compressing effective product lifecycles against farmer-saved alternatives.
- Maize:Hybrid adoption is most advanced in this crop category, with drought-tolerant varieties gaining traction in the Central Dry Zone around Mandalay where irrigation constraints limit paddy expansion. Seed companies anchor portfolios here through tropical-adapted germplasm libraries.
- Wheat:Limited cultivation concentrated in highland areas with cooler growing seasons.
- Pulses:Mung bean and black gram varieties for domestic consumption and residual export.
Maize leads hybrid adoption. Paddy presents the steepest regulatory climb.
Packaging Type:
Packaging specifications track seed value density and storage durability requirements.
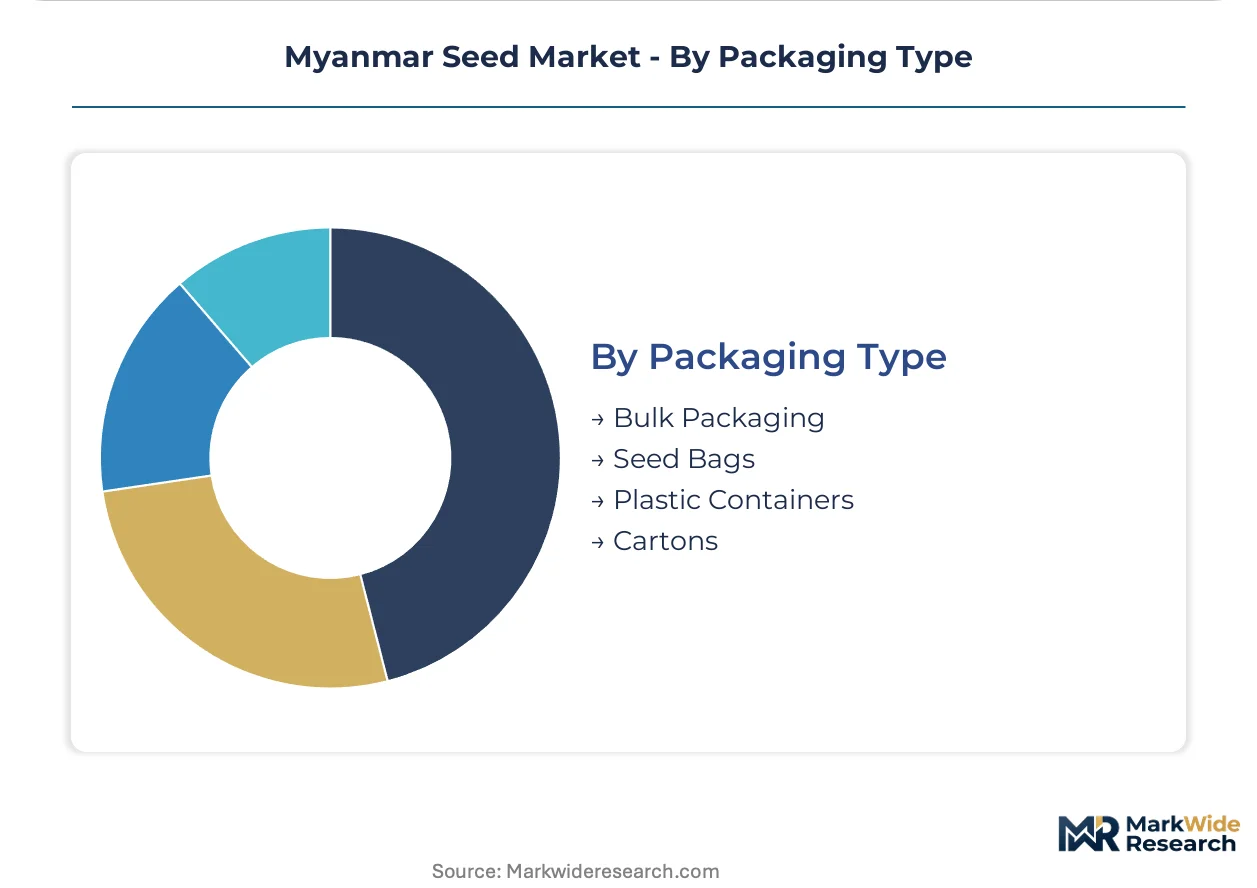
- Seed Bags:Laminated polypropylene units with moisture barriers dominate vegetable seed distribution, particularly for heat-tolerant tomato and chili varieties where germination sensitivity demands humidity control. These formats enable batch traceability for varieties registered under Myanmar's Plant Variety Protection framework.
- Bulk Packaging:Unpackaged seed flows characterize informal cereal seed networks in the Delta, where cost minimization overrides quality assurance documentation.
- Plastic Containers:Rigid packaging for high-value hybrid maize parent lines requiring genetic purity preservation.
- Cartons:Corrugated formats for flower seed retail distribution with printed cultivation instructions.
Seed Bags command premium positioning. Bulk Packaging retains cost-driven volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ayeyarwady Delta anchors Myanmar's seed demand through smallholder vegetable cultivation corridors connecting Yangon to Pathein. Certified hybrid adoption accelerates where irrigation infrastructure and urban market proximity converge. The national seed committee's varietal registration protocols create compliance gradients across state and regional boundaries.
Yangon Region
Vegetable seed demand concentrates in Yangon's peri-urban townships supplying Hlaing Tharyar wholesale markets. The Seed Law's quality certification requirements tighten fastest here, pulling tomato and chili cultivation toward registered varieties. Township-level agro-dealer networks in Thanlyin and Twante channel Syngenta and East-West Seed portfolios directly to commercial vegetable growers.
Mandalay Region
Hybrid maize adoption leads in the Central Dry Zone where water scarcity limits paddy expansion. The national seed committee prioritizes drought-tolerant variety evaluation for this corridor, accelerating registration timelines for short-duration germplasm. Meiktila and Myingyan townships host the densest agro-dealer consolidation, with cooperative societies compressing distribution layers for certified maize parent lines.
Shan State
Highland cultivation of temperate vegetables and hybrid maize drives seed procurement through Taunggyi and Kalaw trading posts. Cross-border germplasm flows from Yunnan complicate Plant Variety Protection enforcement in eastern townships. The state's fragmented transport infrastructure sustains informal seed networks for self-pollinating cereal varieties despite Seed Law compliance mandates.
Ayeyarwady Region
Monsoon paddy belts in Maubin and Myaungmya townships retain farmer-saved seed dominance due to low commercial hybrid penetration. The Seed Law's field inspection protocols face enforcement gaps across delta waterways, limiting certified variety reach. Dagon Group of Companies anchors formal distribution through Pathein-based wholesale channels serving rice-specialized cooperative societies.
Sagaing Region
Pulse and oilseed cultivation in the Chindwin River valley creates niche demand for sesame and groundnut varieties. Limited laboratory capacity for genetic purity testing constrains formal sector expansion into Kalay and Monywa townships. The national seed committee's multi-season evaluation protocols delay commercialization of stress-tolerant germplasm adapted to this water-scarce corridor.
Myanmar Seed Market Competitive Landscape
Global majors compete with regional champions across germplasm access and distribution reach. The Myanmar seed sector exhibits tiered concentration, with multinational breeders controlling hybrid parent lines while domestic conglomerates anchor last-mile township networks. Three archetypes dominate: global germplasm licensors, regional tropical-adaptation specialists, and domestic distribution integrators. Competitive moves center on regulatory pre-registration of pipeline varieties and cooperative society direct procurement relationships.
Among global germplasm licensors, Syngenta AG and Bayer AG occupy positions defined by proprietary hybrid corn portfolios and field crop breeding stations. East-West Seed and Known You Seed Co LTD exemplify the tropical-adaptation specialist archetype, with breeding programs targeting humidity-tolerant vegetable germplasm for Southeast Asian smallholders. Dagon Group of Companies represents domestic distribution integration, leveraging township-level agro-dealer channel control to extend certified seed reach into Ayeyarwady Delta corridors. These players sit within a competitive structure where Plant Variety Protection compliance and Seed Law registration capacity separate formal market participants from informal seed network suppliers.
| Leading Market Players |
|---|
| Syngenta AG |
| Enza Zaden |
| Groupe Limagrain |
| Known You Seed Co LTD |
| Rijk Zwaan Zaadteelt en Zaadhandel B.V. |
| East-West Seed |
| Bayer AG |
| Dagon Group of Companies |
| Charoen Pokphand Group |
| Others |
Supply & Pricing Matrix
Qualified seed analysts concentrated in Yangon and Mandalay command wage premiums that compress margin spreads between premium certified varieties and standard-grade alternatives. Labor-cost differentials between these urban breeding hubs and remote township markets propagate three-tier pricing structures across germplasm categories.
Pricing Analysis
Input-cost pass-through from hybrid parent line imports and laboratory certification fees shapes Myanmar's seed pricing architecture. Three-tier pricing structure across premium, standard, and economy levels separates registered hybrids with full varietal documentation from quality-declared seed and informal farmer-saved lines. Pricing pressure stems from cooperative society consolidation, which strips wholesale markups and forces margin compression at the supplier level. Smallholders in the Ayeyarwady Delta exhibit highest price sensitivity due to near-zero-cost informal seed alternatives, while commercial vegetable growers in Yangon corridors accept premium positioning for documented vigor indices.
Supply Chain Analysis
Dual-sourcing requirements embedded in Myanmar's Seed Law mandate that registered seed companies maintain backup germplasm pipelines, forcing relationships with multiple international breeding stations. Supply concentrates in Thailand, China, and Vietnam for tropical-adapted vegetable germplasm, while hybrid maize parent lines draw from Philippines and Indonesia breeding networks. Raw material dependencies span laboratory reagents for genetic purity testing, laminated packaging substrates, and cold-chain logistics equipment. Single-source vulnerability runs through Yangon port customs clearance for imported parent lines. Distribution runs through township-level agro-dealer cooperatives that bypass traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
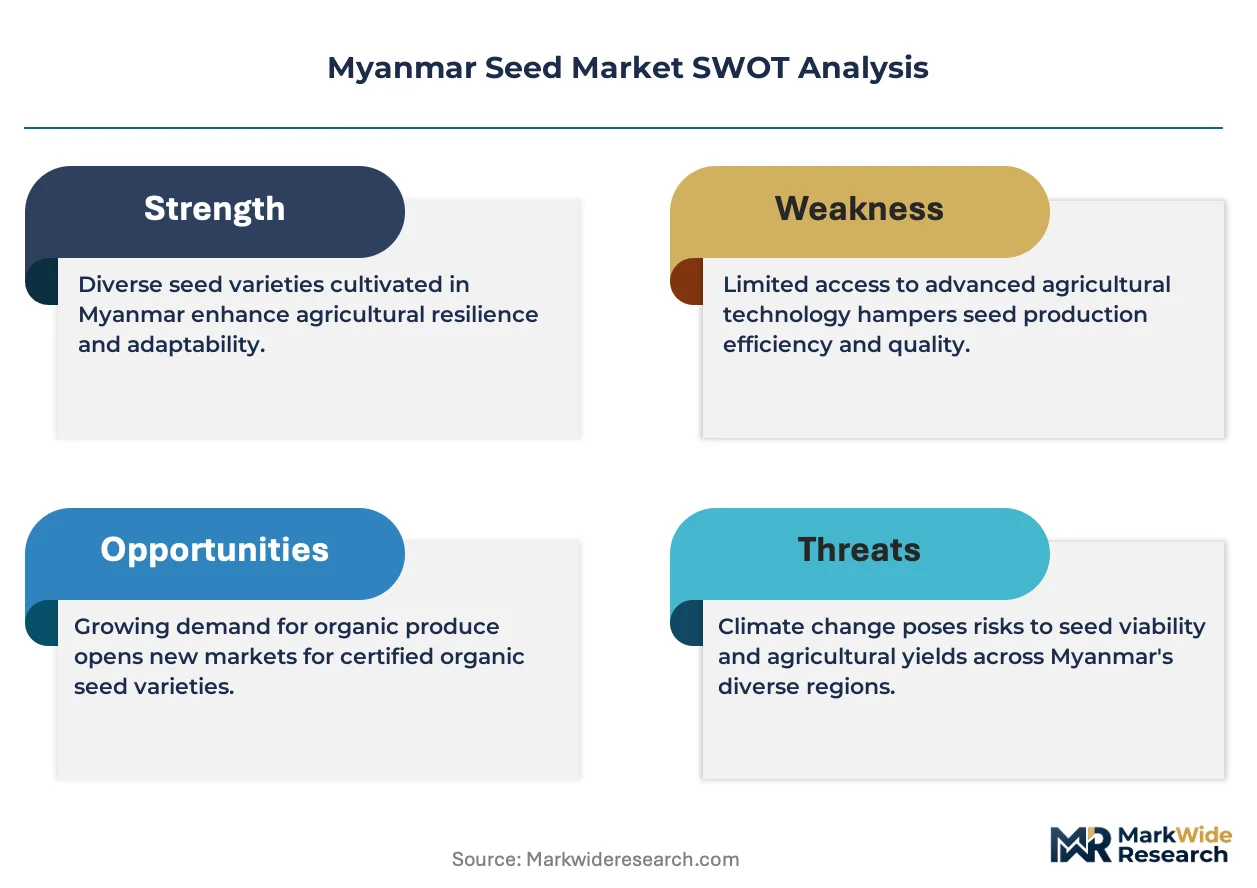
Myanmar's seed market compounds steadily as the Plant Variety Protection framework pulls foreign germplasm investment into formal channels, displacing informal seed networks with certified alternatives.
For Market Incumbents: Anticipate regulatory tightening around varietal registration timelines by pre-positioning pipeline varieties with Myanmar's national seed committee. Defensive consolidation through backward integration into township-level cold storage infrastructure counters cooperative society margin compression. Priority lever: captive supply of laboratory testing capacity in Mandalay to accelerate quality certification throughput. For New Entrants and Emerging Players: Enter via digital extension platforms bundling mobile agronomic advisory with seed ordering, bypassing physical agro-dealer presence requirements. White-space targets include drought-tolerant hybrid maize for the Central Dry Zone and short-duration paddy varieties for Sagaing's water-scarce corridors. Most penetrable entry point: cooperative society direct procurement relationships in Shan State highlands where cross-border germplasm flows complicate incumbent enforcement. For Investors and Strategic Acquirers: Regional tropical-adaptation specialists with established Southeast Asian breeding networks are the most active acquirer in this space, seeking Myanmar distribution footholds. Long-term viability hinges on regulatory affairs capacity and seed analyst talent retention. Acquisition target archetype: domestic distribution integrators with township-level channel control. Signal to watch: restructuring of public seed subsidy programs under agricultural modernization priorities.| Strategic Initiative | Industry Significance |
|---|---|
| Varietal Pre-Registration Pipeline | Compresses time-to-market for new hybrids under Myanmar's multi-season evaluation protocols. |
| Cooperative Society Direct Procurement | Captures margin previously lost to wholesale intermediaries in Yangon and Mandalay corridors. |
| Digital Extension Platform Launch | Creates channel economics for seed companies to reach smallholders without physical agro-dealer presence. |
| Laboratory Capacity Expansion | Addresses genetic purity testing bottlenecks constraining formal sector reach into remote townships. |
| Drought-Tolerant Germplasm Development | Targets unmet demand in Central Dry Zone corridors where irrigation constraints limit paddy expansion. |
Research Methodology
Multiple input streams — structured interviews with seed company regulatory affairs managers, cooperative society procurement officers, and national seed committee officials; secondary validation through Myanmar Seed Law documentation, Plant Variety Protection registration databases, and customs import records; plus agronomic trial data from regional research partnerships — were reconciled through bottom-up and top-down triangulation.
Historical adoption curves for hybrid maize and certified vegetable varieties were cross-referenced against panel input from breeding station directors and agro-dealer network heads. Segmentation modeling incorporated product type, distribution channel, crop type, and packaging format dimensions across the analysis window. CAGRs were derived from volume-throughput trajectories anchored in cooperative society procurement records and wholesale channel shipment data, with climate adaptation breeding timelines and subsidy program evolution as key forecast inputs.
Inputs from national seed committee registration filings and township-level cooperative purchasing records were available through the study window; gaps in informal seed network transaction data introduce uncertainty bands around farmer-saved seed displacement rates. Forecasts reflect assumptions regarding enforcement consistency of Seed Law field inspection protocols and import licensing timeline stability. Deviation in Plant Variety Protection implementation rigor or seed subsidy program restructuring would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
North America Chia Seeds Market
Seeds
Global Oilseed Market
Seeds
Myanmar Rice Seed Market
Seeds
Faba Beans Market
Seeds
Asia-Pacific Quinoa Seeds Market
Seeds
Europe Vegetable Seed Market
Seeds
Americas Seeds Market
Seeds
Organic Chia Seeds Market
Seeds
Safflower Seeds Market
Seeds
Global Fruit and Vegetable Seeds Market
Seeds
Global Sports Turf Seed Market
Seeds
Mexico Seed Market
Seeds
Commercial Seed Market
Seeds
Field Crop Seeds Market
Seeds
Europe Sesame Seed Market
Seeds
Morocco Seed Market