
 Middle-East and Africa Jet Charter Services Market | 2026-2036
Middle-East and Africa Jet Charter Services Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Jet Charter Services Market Foresight
Corporate travel from energy and sovereign wealth sectors is restructuring demand patterns across the Middle-East and Africa jet charter landscape. Empire Aviation Group leverages its Dubai base to dominate heavy-jet rotations serving oil executives between Abu Dhabi, Lagos, and Houston. Royal Jet sustains premium positioning through specialized government and royal family contracts across the Gulf Cooperation Council states. Qatar Executive competes on Doha's Hamad International connectivity, extending its reach into East African emerging markets.
Middle-East and Africa jet charter services encompass on-demand aircraft rental excluding scheduled airline operations, typically covering turboprops through ultra-long-range heavy jets with flight durations from thirty minutes to sixteen hours non-stop. These services deliver point-to-point connectivity where commercial routes prove insufficient, particularly for time-sensitive executives, medical evacuations, and high-value cargo requiring chain-of-custody control. Charter flights and private flights anchor current revenue pools given their established corporate user base, while air ambulance services represent the fastest-growing segment as Gulf states expand healthcare infrastructure and medical tourism corridors. Heavy jets capture disproportionate margin share due to intercontinental range requirements linking Middle Eastern hubs with European and Asian business centers.
The UAE's General Civil Aviation Authority and South Africa's South African Civil Aviation Authority enforce air operator certificate standards that filter out undercapitalized entrants, while Saudi Arabia's General Authority of Civil Aviation aligns with ICAO frameworks ahead of Vision 2030 aviation targets. GCAA mandates on pilot rest cycles and aircraft maintenance documentation directly shape fleet renewal timelines and operating cost structures for charter providers. Stakeholders must monitor regulatory convergence between Gulf standardization initiatives and sub-Saharan African bilateral agreements, as harmonized safety protocols will determine which operators gain cross-border route authority.
Market Dynamics
Corporate travel restructuring from energy and sovereign wealth sectors is compressing booking lead times and elevating fleet flexibility requirements across Middle-East and Africa charter operations. Operators now face pressure to reposition aircraft within hours rather than days.
Growth Catalysts
- GCAA Certification Standards:The UAE's tightened air operator certificate requirements are filtering out undercapitalized competitors and consolidating market share among established fleet owners with newer aircraft.
- Medical Tourism Corridors:Gulf state healthcare infrastructure expansion is accelerating air ambulance service deployment between Dubai, Riyadh, and East African medical hubs.
- Hub Airport Density:Concentrated premium charter demand around Dubai International and Hamad International is generating route network economies that sustain heavy-jet utilization rates.
Market Restraints
- Fleet Renewal Capital Intensity:SACAA and GCAA maintenance documentation mandates require accelerated replacement of aging airframes, straining operator balance sheets.
- Pilot Certification Bottlenecks:Rest cycle regulations and simulator training requirements are constraining qualified crew availability across the Gulf Cooperation Council states.
- Jet Fuel Price Volatility:Exposure to regional refinery capacity limitations and currency fluctuations is compressing margin predictability for fixed-rate contract operators.
Strategic Opportunities
- East African Emerging Markets:Underpenetrated demand in Nairobi, Kigali, and Addis Ababa is creating first-mover advantages for operators establishing maintenance partnerships with local fixed-base operators.
- Vision 2030 Aviation Targets:Saudi Arabia's General Authority of Civil Aviation alignment with ICAO frameworks is streamlining cross-border route authority applications for compliant operators.
- Sustainable Aviation Fuel Integration:Early adoption partnerships between charter providers and Abu Dhabi National Oil Company refineries are positioning premium brands for emissions-conscious corporate accounts.
Industry Challenges
- Aircraft Maintenance Technician Shortage:Specialized Gulf-specific climate certification requirements are extending recruitment timelines and inflating compensation packages for qualified personnel.
- Legacy Reservation System Integration:Real-time aircraft positioning data from new telematics platforms must interface with established corporate travel management systems, creating implementation friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Jet Charter Services Market |
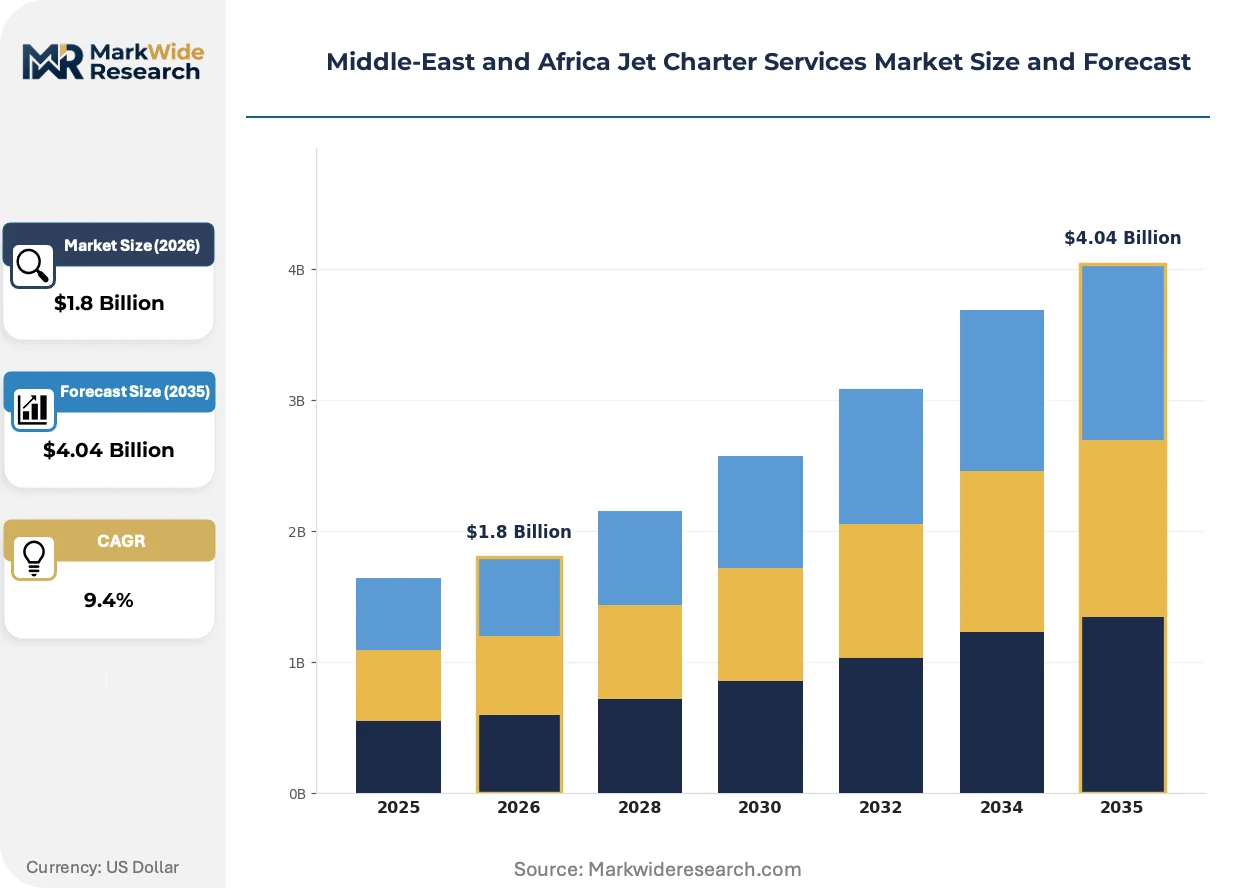
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Charter Flights, Air Ambulance, Cargo Transport, Private Flights Customer Type: Corporate Clients, Government Agencies, Tourists, Healthcare Organizations Aircraft Type: Light Jets, Mid-Size Jets, Heavy Jets, Turbo Props Booking Channel: Online Platforms, Travel Agencies, Direct Bookings, Phone Reservations |
| Companies Covered | Empire Aviation Group, Royal Jet, ExecuJet Aviation Group AG, Vista Global Holding Limited, Qatar Executive, National Air Services, Emirates Executive, Air Charter Service, NASJET, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Jet Charter Services Market Shifts & Advancements
Digital booking platforms and predictive positioning algorithms are compressing aircraft turnaround cycles and enabling dynamic pricing models that respond to real-time demand signals across Middle-East and Africa charter networks.
Telematics-enabled predictive maintenance is overtaking scheduled inspection protocols in heavy-jet operations. Energy sector flight departments in Abu Dhabi and Lagos are adopting engine health monitoring systems that transmit real-time performance data to ground crews. This capability is overtaking traditional fixed-interval maintenance contracts and enabling conditional-based servicing that reduces aircraft downtime.
Saudi Arabia's General Authority of Civil Aviation is harmonizing air operator certification with ICAO frameworks ahead of Vision 2030 targets. This regulatory convergence is reducing documentation redundancy for operators seeking cross-border authority between Gulf Cooperation Council states. Heavy-jet providers with existing UAE GCAA certification are securing accelerated Saudi operating permits through mutual recognition protocols.
Corporate travel managers are consolidating preferred operator relationships and negotiating annual block-hour agreements rather than transactional per-flight bookings. This procurement consolidation is displacing spot-market charter brokers in the energy and sovereign wealth sectors. The shift is most visible in Dubai and Riyadh, where procurement departments now mandate centralized billing and standardized safety reporting across all executive travel.
Middle-East and Africa Jet Charter Services Market Segmentation
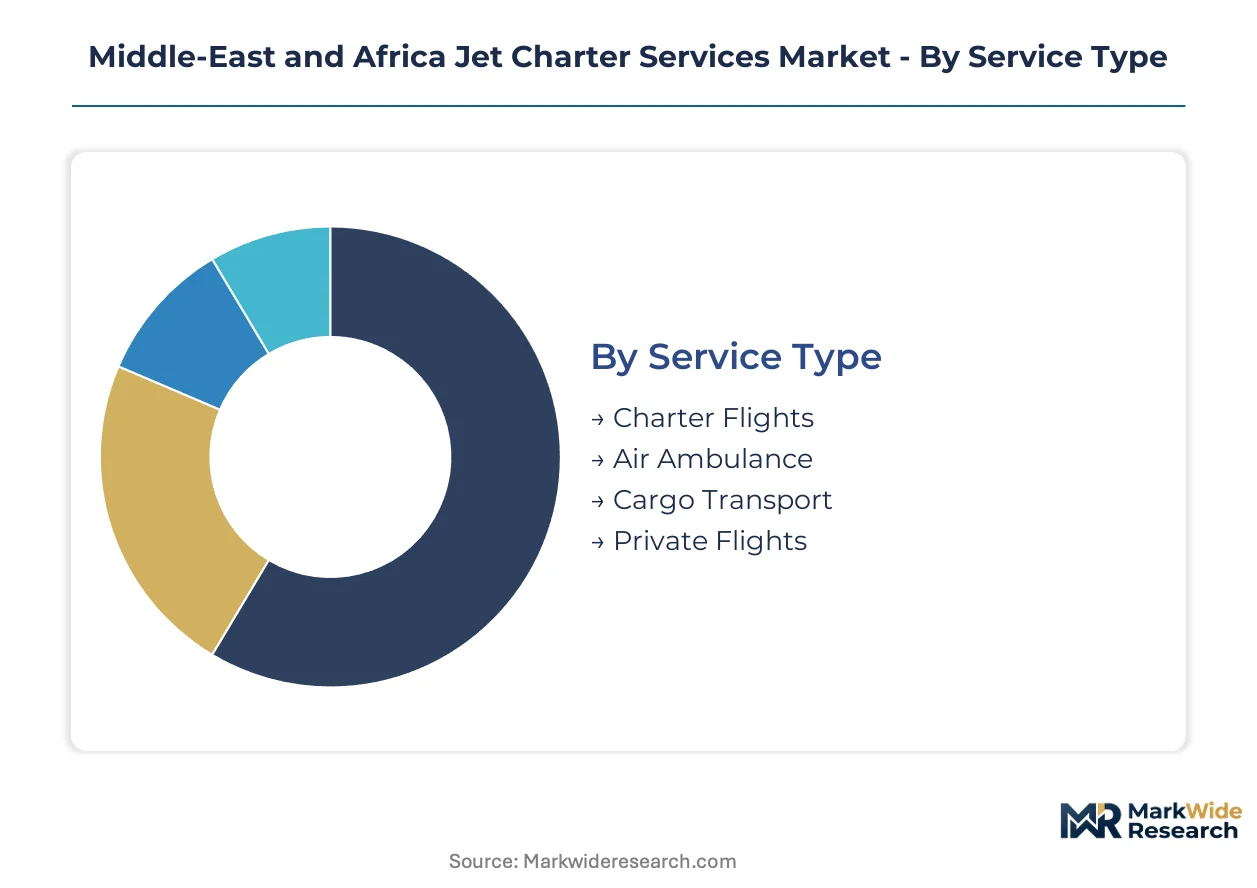
Segmentation in Middle-East and Africa jet charter services reveals how regulatory requirements, capital intensity, and customer procurement patterns fragment operational strategies across providers. Understanding these divisions clarifies where GCAA and SACAA certification burdens concentrate and which service lines command premium positioning.
Service Type:
GCAA air operator certificates impose tiered documentation demands across service categories, with medical evacuation protocols requiring specialized equipment approvals absent from standard charter operations.
- Charter Flights:On-demand aircraft rental for executive travel and group transport, typically utilizing mid-size and heavy jets. Demand concentrates in Dubai and Riyadh where energy sector procurement departments negotiate annual block-hour agreements with preferred operators.
- Air Ambulance:Medical evacuation services with ICU-equipped aircraft and specialized crew certifications. Gulf state healthcare infrastructure expansion is accelerating deployment between Dubai, Riyadh, and East African medical hubs, making this the fastest-climbing segment.
- Cargo Transport:Time-critical freight requiring chain-of-custody documentation, serving oilfield equipment and pharmaceutical shipments.
- Private Flights:Dedicated aircraft for individual or family use, often under long-term management contracts with Dubai-based fleet operators.
Charter flights sit at the top of the volume ranking, with air ambulance climbing the fastest.
Customer Type:
Procurement consolidation patterns vary sharply by customer category, with sovereign wealth funds and government agencies mandating centralized billing while corporate travel managers negotiate standardized safety reporting.
- Corporate Clients:Energy, finance, and sovereign wealth sector executives requiring intercontinental connectivity. Booking lead times have compressed from days to hours, forcing operators to reposition aircraft within the Gulf Cooperation Council states on shortened cycles.
- Government Agencies:Royal family transport, diplomatic missions, and state-owned enterprise executive travel across Gulf states. Specialized security protocols and discretion requirements sustain premium pricing for established UAE operators.
- Tourists:High-net-worth leisure travelers accessing remote safari destinations and Red Sea resorts where commercial routes prove insufficient.
- Healthcare Organizations:Hospital networks and medical tourism facilitators contracting dedicated air ambulance capacity for patient transfers between Dubai, Riyadh, and Nairobi medical hubs.
Government agencies dominate current revenue contribution, though healthcare organizations are expanding most quickly as medical tourism corridors mature.
Aircraft Type:
Fleet renewal timelines and maintenance documentation intensity scale directly with aircraft size, placing heavy-jet operations under the strictest GCAA and SACAA scrutiny.
- Heavy Jets:Ultra-long-range aircraft enabling non-stop flights between Middle Eastern hubs and European, Asian, and North American business centers. Intercontinental range requirements from Abu Dhabi and Doha energy executives sustain disproportionate margin capture for this category.
- Mid-Size Jets:Transcontinental-capable aircraft serving regional executive travel within Africa and between Gulf states. Lagos and Nairobi corporate flight departments favor this segment for cost-controlled regional connectivity.
- Light Jets:Short-range aircraft for trips under three hours, common in domestic Saudi and UAE shuttle services.
- Turbo Props:Regional turboprop aircraft accessing shorter runways in East African emerging markets and remote oilfield locations.
Heavy jets command the steepest margin structure, while mid-size jets are gaining share fastest among cost-conscious procurement departments.
Booking Channel:
Digital platform adoption varies by customer sophistication, with energy sector procurement departments driving integration demands that legacy reservation systems struggle to fulfill.
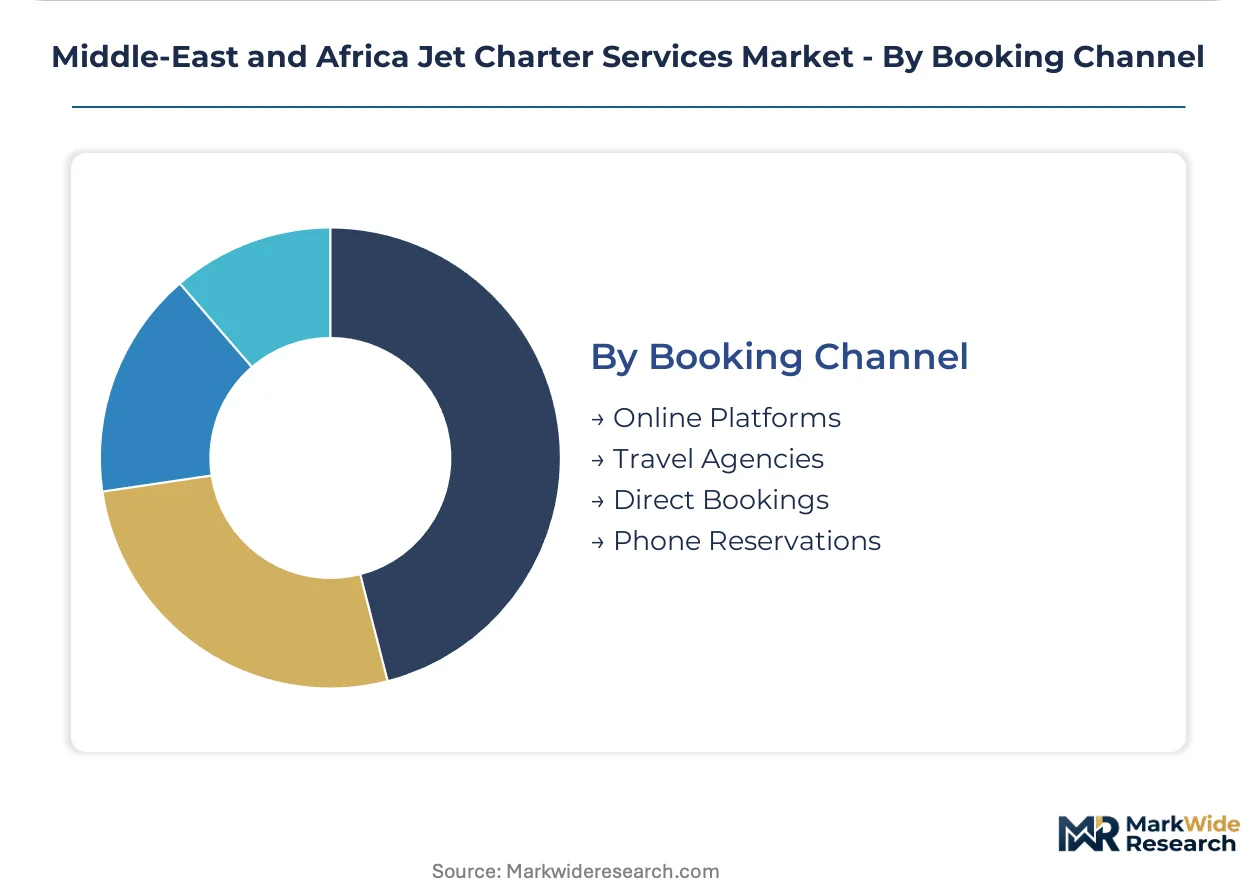
- Online Platforms:Real-time booking interfaces with dynamic pricing algorithms responding to aircraft positioning data. Dubai and Riyadh corporate travel managers are consolidating preferred operator relationships through these channels, displacing spot-market brokers.
- Direct Bookings:Established relationships between flight departments and charter operators, common among Abu Dhabi sovereign wealth funds with dedicated aviation units.
- Travel Agencies:Intermediary arrangements for tourist and occasional corporate users lacking in-house aviation procurement expertise.
- Phone Reservations:Legacy channel for urgent medical evacuations and government clients requiring immediate human coordination.
Direct bookings retain the largest transaction volume, with online platforms expanding most rapidly as telematics-enabled positioning data improves real-time availability accuracy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing charter capacity across the Middle-East and Africa as operators migrate toward jurisdictions with streamlined certification reciprocity. The UAE's GCAA and Saudi Arabia's GACA have established mutual recognition protocols that reduce documentation burdens for cross-border operations.
United Arab Emirates
Dubai International and Al Maktoum International anchor heavy-jet demand from energy sector executives requiring non-stop connectivity to Houston and Singapore. The General Civil Aviation Authority mandates pilot rest cycles and maintenance documentation standards that filter out undercapitalized competitors. Empire Aviation Group leverages its Dubai base to dominate intercontinental rotations serving oil executives between Abu Dhabi, Lagos, and European financial centers.
Saudi Arabia
Vision 2030 aviation targets are accelerating fleet renewal timelines as the General Authority of Civil Aviation aligns certification with ICAO frameworks ahead of 2030 deadlines. Riyadh and Jeddah corporate travel departments are consolidating preferred operator relationships through annual block-hour agreements. Heavy-jet providers with existing UAE GCAA certification secure accelerated Saudi operating permits through streamlined mutual recognition protocols.
South Africa
The South African Civil Aviation Authority enforces air operator certificate standards that strain operator balance sheets through accelerated aging airframe replacement requirements. Johannesburg and Cape Town serve as maintenance hubs for sub-Saharan African operations, with specialized climate certification requirements extending recruitment timelines for qualified aircraft maintenance technicians. SACAA documentation mandates directly shape fleet renewal timelines and operating cost structures.
Qatar
Hamad International connectivity extends Qatar Executive's reach into East African emerging markets through Doha's hub airport density. The Qatar Civil Aviation Authority harmonizes standards with GCC neighbors, enabling rapid aircraft repositioning across Gulf Cooperation Council states. Corporate travel managers in Doha are compressing booking lead times from days to hours, forcing operators to maintain standby heavy-jet availability.
Nigeria
Lagos anchors West African demand for mid-size and heavy-jet rotations linking oilfield operations with European headquarters. Nigerian Civil Aviation Authority regulations require specialized equipment approvals for medical evacuation protocols that exceed standard charter documentation burdens. Energy sector flight departments in Lagos are adopting engine health monitoring systems that transmit real-time performance data to ground crews, enabling conditional-based servicing.
Middle-East and Africa Jet Charter Services Market Competitive Landscape
Fleet renewal and certification reciprocity dominate the current landscape as operators navigate tightened GCAA and SACAA standards. The market structure concentrates around established fleet owners with newer aircraft, filtering out undercapitalized entrants through capital intensity barriers. Three archetypes prevail: Dubai-based heavy-jet specialists serving intercontinental energy routes, government-contract operators sustaining premium positioning through royal family relationships, and integrated aviation groups leveraging hub airport density for network economies. Competitive moves center on accelerated Saudi operating permit acquisition through mutual recognition protocols and predictive maintenance technology partnerships.
Within the Dubai-based heavy-jet tier, Empire Aviation Group and Royal Jet exemplify divergent positioning strategies. Empire Aviation Group occupies the energy sector procurement channel through annual block-hour agreements with Abu Dhabi and Lagos flight departments. Royal Jet anchors premium government and royal family contracting across Gulf Cooperation Council states, sustaining margin capture through specialized security protocols and discretion requirements. Qatar Executive represents the hub-connectivity archetype, leveraging Hamad International's route network density to extend into underpenetrated East African markets.
| Leading Market Players |
|---|
| Empire Aviation Group |
| Royal Jet |
| ExecuJet Aviation Group AG |
| Vista Global Holding Limited |
| Qatar Executive |
| National Air Services |
| Emirates Executive |
| Air Charter Service |
| NASJET |
| Others |
Supply & Pricing Matrix
Sustainable Aviation Fuel integration mandates from Abu Dhabi National Oil Company refineries gate qualified supply access and premium-tier pricing power for Middle-East and Africa jet charter operators. These environmental compliance requirements stratify the market between certified premium providers and standard-tier competitors lacking refinery partnerships.
Pricing Analysis
Direct-to-corporate contract discounts dominate the channel-margin layer, with annual block-hour agreements displacing spot-market broker markups in Dubai and Riyadh energy sector procurement. Three-tier pricing structure across premium, standard, and economy levels separates GCAA-certified heavy-jet operators from mid-size fleet competitors and aging airframe discount providers. Price differentiation rests on certification tier and after-sales service bundling. Cost compression in the standard tier is intensifying because SACAA maintenance documentation mandates accelerate fleet renewal timelines. Corporate flight departments in Abu Dhabi and Lagos exhibit lowest price sensitivity, while occasional tourist users drive economy-tier volume.
Supply Chain Analysis
Single-source vulnerability sits with Abu Dhabi National Oil Company for Sustainable Aviation Fuel supply and with Dubai-based heavy-jet maintenance, repair, and overhaul facilities for specialized climate certification work. Geographic supply concentration centers on the UAE, Saudi Arabia, and South Africa for fleet operations, with heavy-jet airframes sourced from North American and European original equipment manufacturers. Raw material dependencies include aviation turbine fuel, specialized avionics components, and Gulf-specific climate-rated aircraft parts. Supply chain risk hinges on regulatory restriction as GCAA and SACAA certification reciprocity remains incomplete across Gulf Cooperation Council states. Distribution runs through hub airport fixed-base operators at Dubai International, Hamad International, and Riyadh King Khalid International.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
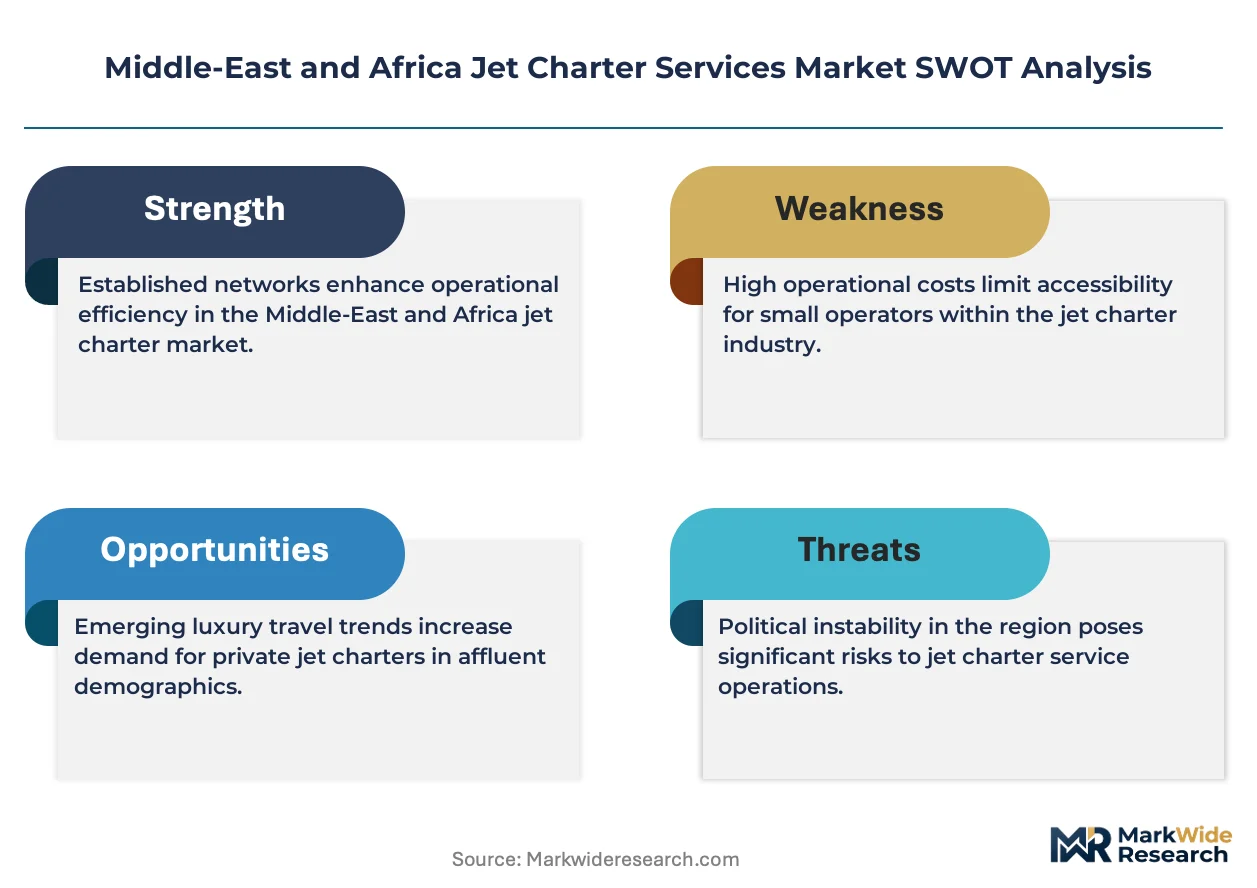
The Middle-East and Africa jet charter services market functions as a geographic-arbitrage play between UAE GCAA certification standards and South African SACAA documentation burdens, with the regulatory differential creating cost advantages for Dubai-based operators serving sub-Saharan African routes.
For Market Incumbents: To counter fleet renewal capital intensity from aging airframe replacement mandates, prioritize backward integration into predictive maintenance technology partnerships and secure accelerated Saudi operating permits through GACA-GCAA mutual recognition protocols. Channel control over corporate travel management system integration represents the critical defensive lever against digital platform disintermediation. For New Entrants and Emerging Players: Digital booking platform routes through East African emerging markets offer the most penetrable white-space, specifically Nairobi and Kigali medical tourism corridors where maintenance partnerships with local fixed-base operators remain undeveloped. Target air ambulance service expansion as the fastest-climbing segment, leveraging telematics-enabled positioning data to displace phone-reservation incumbents in urgent medical evacuation procurement. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-size jet operators with SACAA certification stranded by heavy-jet capital requirements. Long-term viability across the analysis window favors integrated aviation groups with hub airport density and cross-border route authority. Monitor Sustainable Aviation Fuel refinery partnership announcements as the signal to watch for premium-tier positioning inflection.| Strategic Initiative | Industry Significance |
|---|---|
| GCAA Certification Investment | Filters undercapitalized competitors and consolidates market share among established fleet owners. |
| Predictive Maintenance Technology Partnership | Enables conditional-based servicing that reduces aircraft downtime for Abu Dhabi energy flight departments. |
| East African FBO Maintenance Alliance | Creates first-mover advantages in Nairobi and Kigali medical tourism corridors. |
| Sustainable Aviation Fuel Integration | Positions premium brands for emissions-conscious corporate accounts through ADNOC refinery partnerships. |
| Corporate Travel Management System Integration | Displaces spot-market brokers through real-time telematics-enabled positioning data. |
Research Methodology
Bottom-up corporate travel demand modeling reconciled against top-down fleet utilization tracking forms the analytical core of this study. Primary interviews with charter operations directors, GCAA certification auditors, corporate flight department managers, and fixed-base operator maintenance heads combined with secondary validation from GCAA regulatory filings, SACAA air operator certificate databases, ICAO safety audit reports, and hub airport traffic statistics. This approach enables cross-verification between demand-side booking patterns and supply-side aircraft positioning data.
Input-output matrices map charter flight volumes against heavy-jet fleet deployments across service type, customer category, aircraft class, and booking channel dimensions throughout the forecast period. CAGRs derive from regression analysis of historical fleet renewal timelines and projected regulatory compliance costs. Industry-specific forecast inputs include GCAA pilot rest cycle enforcement intensity and medical tourism corridor patient transfer volume assumptions.
The model assumes a particular technology adoption path; alternative pathways for telematics-enabled predictive maintenance would alter the outlook if energy sector flight departments delay engine health monitoring system deployment. Forecasts reflect assumptions regarding regulatory convergence between Gulf standardization initiatives and sub-Saharan African bilateral agreements. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aviation and Defense Training and Simulation
Helicopter Services Market
Aviation and Defense Training and Simulation
US Helicopter Services Market
Aviation and Defense Training and Simulation
South-East Asia Civil Aviation Market
Aviation and Defense Training and Simulation
Global Airlines Market
Aviation and Defense Training and Simulation
North America Charter Jet Services Market
Aviation and Defense Training and Simulation
Digital Aviation Market
Aviation and Defense Training and Simulation
Charter Jet Services Market
Aviation and Defense Training and Simulation
Domestic Aviation Market