
 E Learning Virtual Reality Market | 2026-2036
E Learning Virtual Reality Market Size, Share, and Industry Trends Forecast 2026-2036
E Learning Virtual Reality Market Intelligence
The proliferation of cloud-based software platforms is restructuring the content delivery model for educational VR. Meta Platforms leverages its hardware dominance with the Quest ecosystem to control content distribution. Unity Technologies specializes in providing the core development engine used by a vast number of content creators. Meanwhile, EON Reality focuses on scalable, code-free VR/AR solutions for academic and enterprise clients.
E-learning virtual reality utilizes computer-generated, interactive 3D environments delivered through VR headsets with high-resolution displays and low-latency tracking. Its primary purpose is to facilitate experiential learning in safe, simulated contexts. While hardware like VR headsets remains foundational, software platforms and interactive modules generate higher margins. Corporate training applications show the highest adoption rate among end-user segments, outpacing K-12 and higher education.
Data privacy regulations such as Europe's GDPR and the US's COPPA impose strict requirements on handling user data, particularly from minors in educational settings. Concurrently, standards from organizations like the ISO/IEC influence hardware interoperability and content format specifications. Stakeholder success will depend on navigating this complex web of privacy compliance while developing ethically designed, pedagogically sound immersive experiences.
Market Dynamics
The central dynamic shaping the e-learning virtual reality market is the pivot from hardware-centric value propositions to software and content-driven ecosystems. This shift is accelerated by the integration of artificial intelligence, which enables personalized learning paths and automated performance feedback, concentrating value in scalable platforms over individual headsets.
Growth Catalysts
- AI-Powered Personalization:The fusion of artificial intelligence with VR learning modules allows for adaptive training scenarios that adjust difficulty and content in real-time based on user performance, a feature highly sought in corporate compliance and skills training.
- Government Digitalization Mandates:National policies promoting digital education, such as South Korea's significant government investment in educational technology infrastructure, create substantial, concentrated demand for VR content and platforms in the public education sector.
- Demand for High-Consequence Training:Corporate sectors, especially manufacturing and healthcare, are driving adoption for complex procedural simulations. VR provides a safe, repeatable environment for training on high-risk tasks where errors have significant safety or financial implications.
Market Restraints
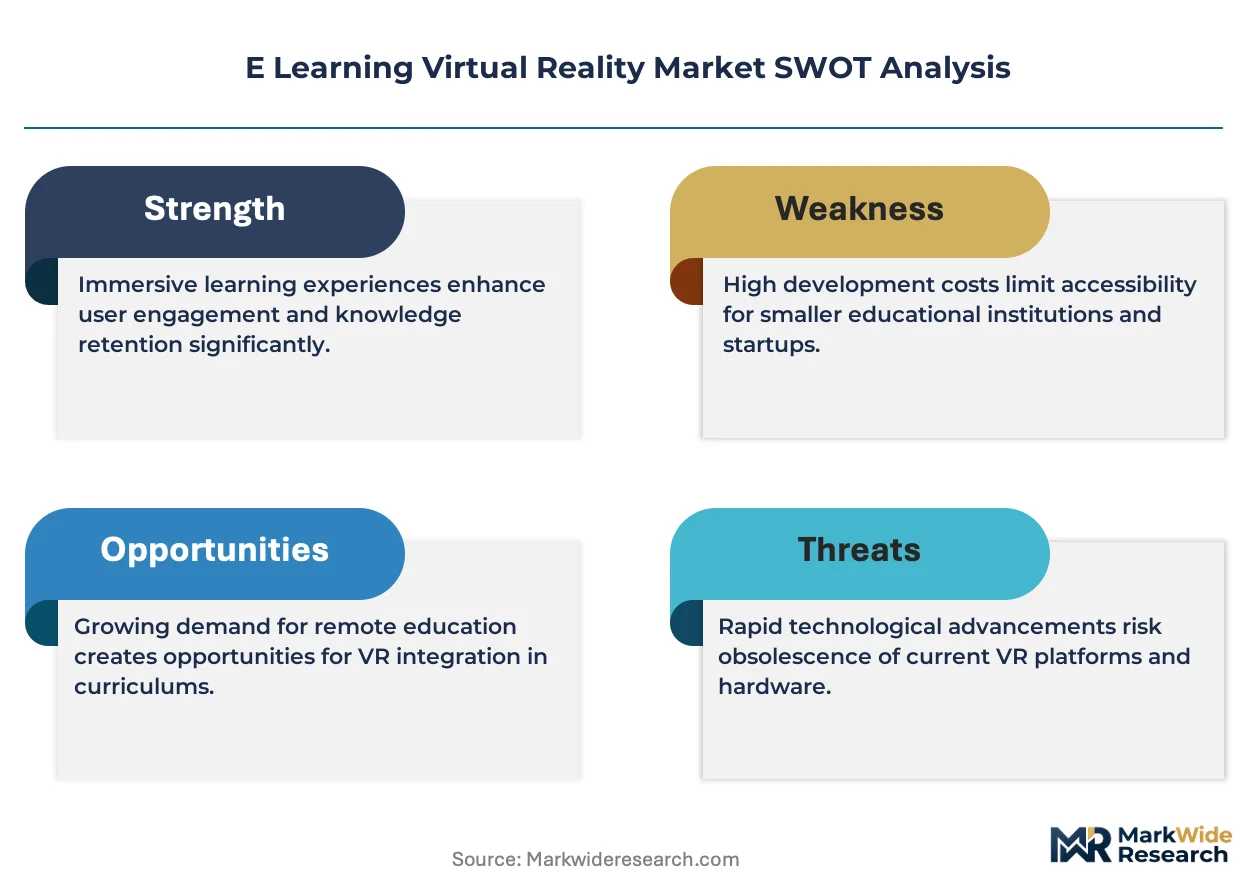
- High Hardware Costs:The initial capital expenditure for enterprise-grade VR headsets and the requisite high-performance computing hardware remains a significant barrier to entry, particularly for large-scale deployments in educational institutions and smaller businesses.
- Data Privacy Compliance:Navigating stringent data privacy regulations like Europe's GDPR and the US's COPPA creates significant compliance overhead, especially when handling biometric and performance data from minors in K-12 educational settings.
- Content Development Bottlenecks:Creating pedagogically sound, high-fidelity, and interactive VR content is a resource-intensive process. This complexity limits the availability of diverse, curriculum-aligned modules, slowing adoption outside of well-funded corporate training niches.
Strategic Opportunities
- K-12 and Higher Education Markets:While corporate training leads adoption, the K-12 and university segments remain comparatively underpenetrated. Developing scalable, affordable, and curriculum-integrated VR content for these markets represents a major growth vector.
- Integration of Haptic Technology:Combining VR with haptic feedback gloves and suits offers a path to creating more immersive and effective training simulations. This is particularly valuable for medical surgery training and industrial skills development requiring a sense of touch.
- Expansion into Vocational Training:There is a significant opportunity to apply VR learning for skilled trades and vocational education, providing realistic simulations for fields like welding, electrical work, and automotive repair where hands-on practice is critical.
Industry Challenges
- Lack of Interoperability Standards:The absence of universally adopted standards for VR content and hardware, despite efforts by bodies like the ISO/IEC, leads to platform fragmentation. This forces developers to create multiple versions of content and complicates integration for end-users.
- Specialized Talent Scarcity:A shortage of professionals who possess a hybrid skillset combining 3D content development, instructional design, and software engineering for platforms like Unity impedes the pace and quality of content creation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E Learning Virtual Reality Market |
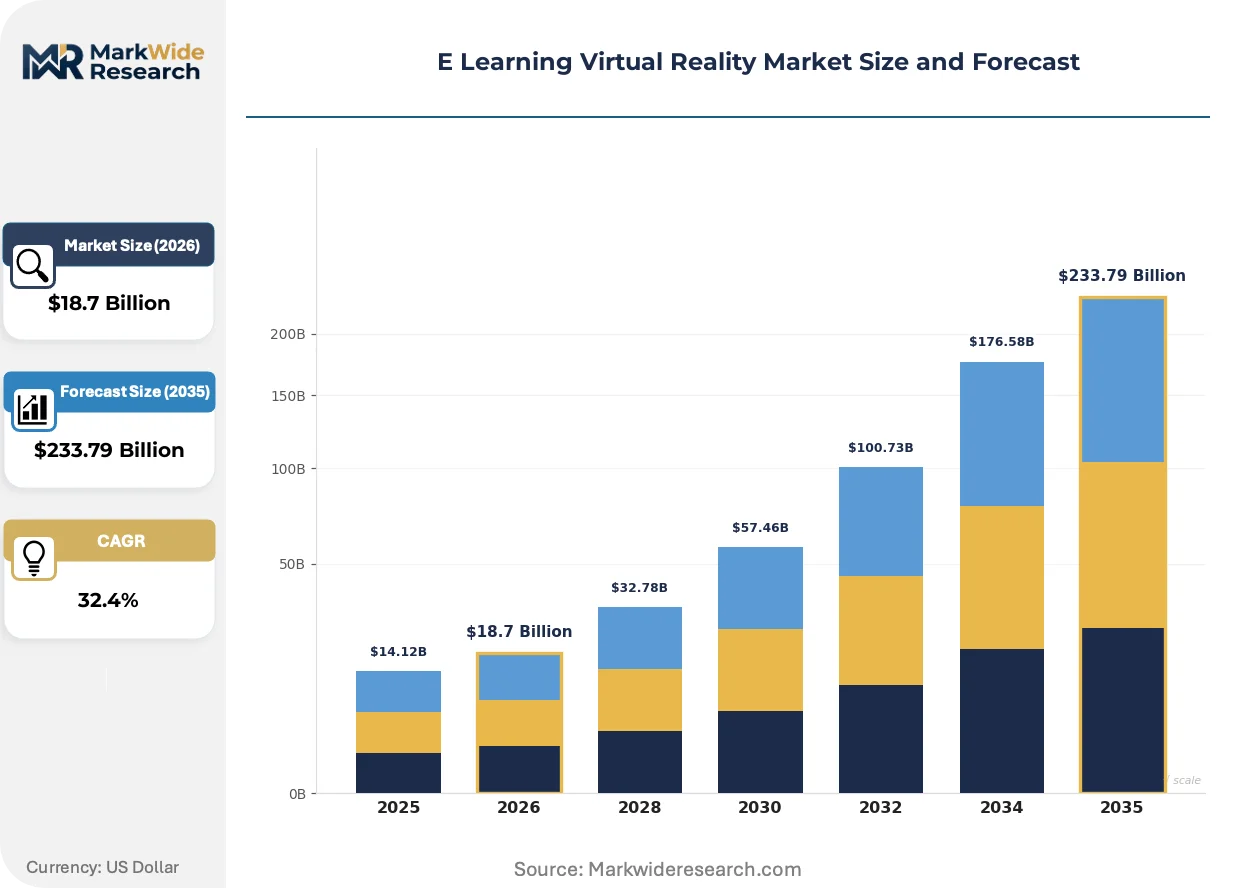
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $233.79 Billion |
| CAGR (2026 – 2036) | 32.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: VR Headsets, Software Platforms, Interactive Modules, Simulation Tools End User: Educational Institutions, Corporate Training, Skill Development Centers, Government Agencies Deployment: Cloud-Based, On-Premises, Hybrid Solutions, Mobile Applications Technology: 3D Modeling, Artificial Intelligence, Gamification, Immersive Learning |
| Companies Covered | Meta Platforms, Microsoft, Google, HTC Corporation, EON Reality, Unity Technologies, zSpace, Avantis Systems, Lenovo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E Learning Virtual Reality Market Strategic Shifts & Innovations
The market is advancing toward more intelligent and accessible immersive learning frameworks. This evolution prioritizes seamless content delivery, algorithmic personalization, and scalable subscription models, moving the industry beyond standalone, hardware-dependent experiences and toward integrated educational ecosystems.
Technology Evolution in Content Delivery
Cloud-streaming for VR content delivery allows experiences to be rendered on powerful remote servers and streamed to lightweight headsets. Enterprise and academic clients are adopting this model to circumvent the need for expensive, high-end computing hardware at each user station. This remote rendering and streaming model is overtaking locally installed applications, lowering the hardware barrier to entry and enabling wider access to high-fidelity training simulations across an organization.
Regulatory Scrutiny of AI in Education
New governance frameworks like the EU AI Act are introducing risk-based compliance obligations for artificial intelligence systems. This directly impacts adaptive learning platforms that use AI to personalize content and assess student performance within VR environments. Developers of educational VR software are most affected, as they must now ensure their algorithmic models are transparent, fair, and auditable to avoid regulatory penalties and build user trust.
Shift to Subscription-Based Content Models
A move from perpetual licensing or one-time purchases of specific VR modules toward subscription-based access to entire content libraries is underway. This disrupts the traditional, project-focused business model for content creators, favoring platform providers that offer a continuously updated catalog of training modules. This consumption pattern is most prominent within the corporate training segment, where organizations prefer predictable, scalable solutions for ongoing workforce development.
E Learning Virtual Reality Market Segmentation
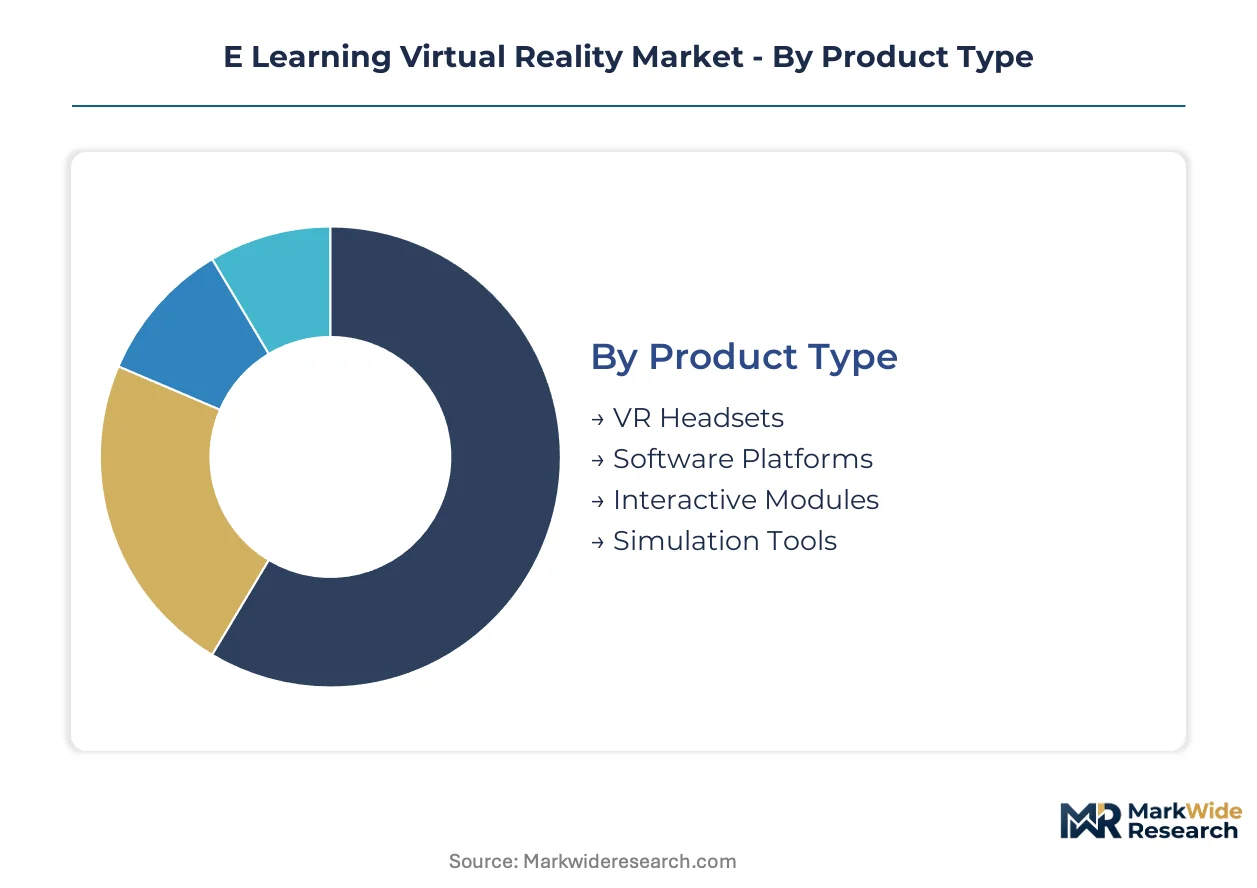
Segmentation clarifies value capture and market evolution within the e-learning virtual reality sector. This market distinguishes its offerings based on core components, user groups, deployment methods, and underlying technological frameworks. This granular view highlights areas of concentrated investment, regulatory focus, and pedagogical innovation across the industry.
Product Type:
Product Type segmentation reveals varying regulatory oversight, particularly concerning safety and data handling for hardware components and software platforms.
- Software Platforms:These foundational systems manage content delivery, user interaction, and analytics within immersive environments. Europe's EU AI Act imposes compliance obligations for AI-driven personalization features embedded in these platforms.
- Interactive Modules:These are self-contained learning units designed for specific educational outcomes or skill acquisition. Demand concentrates in corporate training, driven by the need for repeatable, high-fidelity simulations in fields like healthcare and manufacturing.
- VR Headsets:These devices provide the immersive display and tracking capabilities essential for virtual reality experiences.
- Simulation Tools:These specialized applications enable the creation and deployment of realistic training scenarios for various industries.
Software Platforms sits at the top of the volume ranking, with Interactive Modules climbing the fastest.
End User:
End User segmentation highlights diverse budget constraints and procurement models, influencing the scalability and complexity of VR deployments.
- Corporate Training:This segment utilizes VR for high-consequence procedural and safety simulations across manufacturing, healthcare, and other industries. Organizations prioritize return on investment from reduced training costs and improved skill retention.
- Educational Institutions:This segment includes K-12 schools and universities, adopting VR for experiential learning and curriculum integration. Affordability and curriculum alignment are critical factors for widespread implementation.
- Skill Development Centers:These facilities provide vocational training and professional certification using immersive simulations for specific trades.
- Government Agencies:Public sector entities deploy VR for defense, emergency services, and public safety training initiatives.
Corporate Training commands the largest share of current VR e-learning expenditure, while Educational Institutions present the most significant long-term expansion potential.
Deployment:
Deployment models reflect evolving infrastructure capabilities and preferences for accessibility and data control within client organizations.
- Cloud-Based:This model streams VR content from powerful remote servers, reducing local hardware requirements and enabling wider access. Enterprise clients adopt this for scalability and centralized content management.
- Hybrid Solutions:These combine local processing with cloud-based content delivery, balancing performance needs with data security concerns. Organizations leverage this for sensitive data while maintaining accessibility.
- On-Premises:This traditional model involves hosting VR content and applications directly on the client's local servers.
- Mobile Applications:These VR experiences are delivered through smartphone-powered headsets or standalone mobile VR devices.
Cloud-Based deployment is gaining significant traction, with Hybrid Solutions offering a balanced approach for diverse organizational needs.
Technology:
Technology segmentation illustrates the core innovation areas driving pedagogical effectiveness and user engagement in VR e-learning.
- Artificial Intelligence:This technology enables personalized learning paths, adaptive difficulty, and automated performance feedback within VR environments. Developers must ensure algorithmic models are transparent and fair under frameworks like the EU AI Act.
- Immersive Learning:This encompasses the core pedagogical approach of placing users in simulated environments for experiential training. Its effectiveness drives adoption in high-consequence training scenarios.
- 3D Modeling:This involves creating the virtual environments and objects that populate VR e-learning experiences.
- Gamification:This integrates game-like elements and mechanics into VR modules to enhance engagement and motivation.
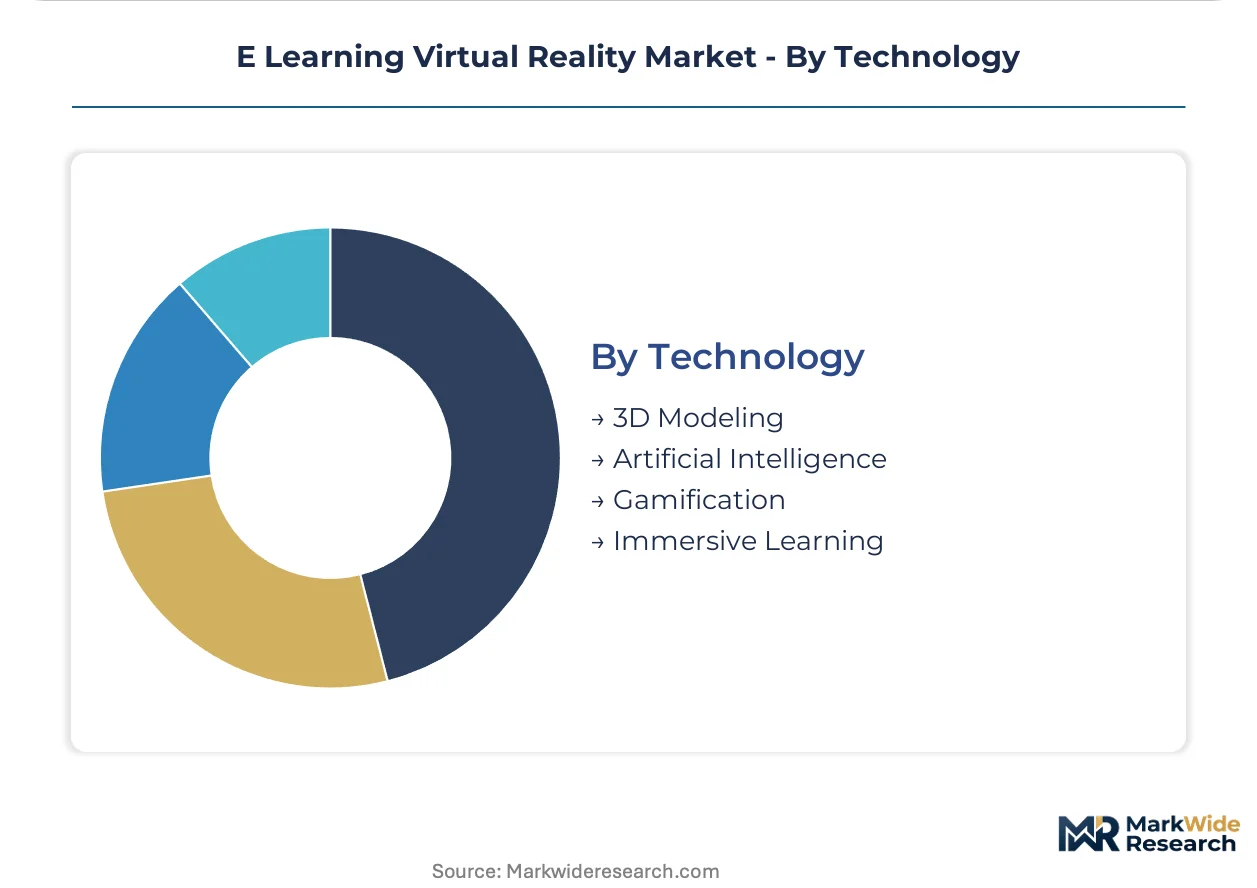
Artificial Intelligence capabilities are rapidly enhancing the sophistication of VR e-learning, while Immersive Learning remains the fundamental benefit proposition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage influences e-learning VR development, with some regions fostering innovation through supportive policies while others impose stricter compliance. This dynamic shifts investment and content creation, particularly for data-sensitive applications. Developers often prioritize markets with clearer regulatory pathways for faster deployment and user adoption.
South Korea
South Korea drives significant demand through substantial government investment in digital education infrastructure. The country's Ministry of Education actively promotes VR integration into public schools, creating a concentrated market for content developers. Seoul's tech clusters, including Pangyo Techno Valley, foster collaboration between VR hardware manufacturers and educational software firms.
United States
The United States market exhibits robust demand for corporate training applications, especially in healthcare and manufacturing sectors. Data privacy frameworks like COPPA and HIPAA shape the development of secure, compliant VR learning platforms. Silicon Valley and Boston's innovation hubs lead in AI-powered adaptive learning and immersive simulation tool development.
Germany
Germany focuses on high-fidelity industrial simulations and vocational training for its skilled workforce. The EU AI Act introduces stringent compliance obligations for AI-driven educational VR systems, emphasizing transparency and fairness. Munich and Berlin serve as key centers for enterprise VR solutions and research into ethical AI applications in learning.
China
China's e-learning VR market expands rapidly, fueled by national digitalization mandates and a vast student population. Government initiatives like the "Education Informatization 2.0" plan encourage widespread adoption of immersive technologies. Shenzhen and Shanghai emerge as major production hubs for VR hardware and localized educational content.
United Kingdom
The United Kingdom sees growing adoption within higher education and specialized skill development centers. Data protection under GDPR influences how educational VR platforms manage student performance data and user analytics. London's tech ecosystem and university research centers drive innovation in pedagogical design for immersive learning experiences.
E Learning Virtual Reality Market Key Industry Players
North American producers anchor one tier, focusing on sophisticated software platforms and high-value content, while Asian specialists hold significant positions in VR hardware manufacturing. The market exhibits a tiered structure, with established tech giants competing with agile, specialized VR content developers. Strategic archetypes include comprehensive platform providers, niche content creators, and foundational hardware manufacturers. Companies actively pursue strategic partnerships and portfolio diversification to capture expanding market share and integrate new AI capabilities.
Within the platform provider tier, Meta Platforms leverages its Quest ecosystem to control content distribution and user access. This strategy integrates hardware and software, creating a comprehensive user experience. Unity Technologies exemplifies a core development engine provider, offering tools used by a vast number of content creators globally for diverse immersive experiences. EON Reality, meanwhile, represents a specialist in scalable, code-free VR/AR solutions tailored for academic and enterprise clients, emphasizing ease of content creation. These companies collectively shape the technological infrastructure and content accessibility across the e-learning VR market.
| Leading Market Players |
|---|
| Meta Platforms |
| Microsoft |
| HTC Corporation |
| EON Reality |
| Unity Technologies |
| zSpace |
| Avantis Systems |
| Lenovo |
| Others |
Cost & Logistics Intelligence
Cloud-streaming for VR content delivery simultaneously reshapes cost economics for end-users and concentrates supply within platform providers. This model reduces the need for expensive local hardware, shifting capital expenditure to operational expenditure, while centralizing content distribution and management.
Pricing Analysis
Distributor margin structures reflect the shift towards software and content, with platform providers capturing significant value. Subscription-based content models dominate the market, offering predictable revenue streams for content creators and scalable access for users. Price differentiation stems from the level of customization for corporate training modules and the volume scale for large educational institutions. Pricing pressure stems from the high initial hardware costs for end-users, pushing content providers towards more accessible subscription offerings. Educational Institutions exhibit the most price-sensitive behavior, while Corporate Training segments demonstrate lower price sensitivity due to clear return-on-investment metrics.
Supply Chain Analysis
Regional distribution centers for VR headsets primarily serve major consumer and enterprise markets. Geographic supply concentration for hardware components is notable in China for manufacturing and in South Korea for high-resolution display technology. The market depends on specialized optics and high-performance processing units from a limited number of global suppliers. Single-source vulnerability for critical components poses a structural supply chain risk. Distribution runs through a dual model: direct-to-consumer channels for standalone headsets and B2B channels for enterprise-grade VR solutions and content platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The e-learning virtual reality market functions as a regulatory compounder, with the EU AI Act driving demand for transparent and auditable adaptive learning platforms.
For Market Incumbents: Cement hardware-software integration to create cohesive ecosystems, leveraging existing user bases. Invest heavily in AI-driven personalization research and development to maintain a competitive edge against emerging specialized content providers. The fragmented content ecosystem poses a threat, making channel control through proprietary platforms a critical lever for market dominance.
For New Entrants and Emerging Players: K-12 and higher education institutions represent an underserved buyer archetype with significant long-term expansion potential. Target curriculum-aligned content and affordable vocational training simulations as white-space opportunities. The most penetrable segment remains Educational Institutions, with a go-to-market angle focused on scalable, subscription-based content libraries that integrate with existing learning management systems.
For Investors and Strategic Acquirers: Roll-up economics work for platform providers because content creation remains fragmented across numerous small studios. The market indicates strong long-term viability for experiential learning solutions over the next decade. Acquisition targets should include niche content creators with strong pedagogical design capabilities or specialized technology developers enhancing haptic feedback. Adoption rates in K-12 and higher education serve as a key signal to watch for broader market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen Platform Integration | This initiative enhances user experience and strengthens ecosystem lock-in for Meta Platforms. |
| Invest in AI-Powered Content | Automated personalization and feedback mechanisms improve learning outcomes for corporate training. |
| Expand into Vocational Training | This move addresses a critical need for hands-on skill development in industries like manufacturing. |
| Develop K-12 Curriculum Modules | Targeting this underpenetrated segment unlocks long-term growth potential for educational VR. |
| Form Haptic Technology Partnerships | Integrating haptic feedback creates more immersive and effective training simulations for medical fields. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region informing the analysis. This involved extensive interviews with instructional designers, VR software engineers, corporate training managers, and education technology procurement officers. Secondary validation drew from academic journals on immersive learning, technology patent databases, government education reports, and corporate financial filings, triangulating bottom-up and top-down perspectives.
The rate-of-change decomposition framework underpins the market forecast across the analysis window. This framework systematically breaks down growth drivers and market restraints, modeling their impact on various segmentation dimensions including Product Type, End User, Deployment, Technology, and regional adoption patterns. Compound annual growth rates were derived from historical data extrapolation, future trend analysis, and specific forecast inputs like VR hardware sales data and e-learning content consumption metrics.
Inputs from industry reports and company disclosures were available through the study window; gaps in granular regional adoption rates and specific content development costs introduce uncertainty bands. Forecasts reflect assumptions regarding technological advancements and market acceptance. Decision-makers should treat outputs as directional within the stated assumption set, recognizing rapid technological obsolescence and unforeseen regulatory changes as primary risk factors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
Augmented and Virtual Reality in Education Market
Educational Technology (EdTech)
AI in K-12 Education Market
Educational Technology (EdTech)
Virtual Schools Market
Educational Technology (EdTech)
M-Education Market
Educational Technology (EdTech)
Global K-12 Software Market
Educational Technology (EdTech)
Asia-Pacific Digital Education Market
Educational Technology (EdTech)
Education Security Market
Educational Technology (EdTech)
Global Adaptive Learning Market
Educational Technology (EdTech)
Global Gamification in Education Market
Educational Technology (EdTech)
Child Care Software Market
Educational Technology (EdTech)
Education Apps Market
Educational Technology (EdTech)
Micro Learning Platform Market
Educational Technology (EdTech)
Edtech and Smart Classroom Market
Educational Technology (EdTech)
Flipped Classroom Market
Educational Technology (EdTech)
Edtech Market
Educational Technology (EdTech)
Education Technology Market