
 Global Gamification in Education Market | 2026-2036
Global Gamification in Education Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gamification in Education Market Foresight
Cloud-native game mechanics is fragmenting the traditional LMS architecture into modular, API-driven engagement layers. Microsoft Corporation leverages its Azure infrastructure and Teams integration to embed achievement systems directly within institutional workflows. Kahoot! anchors the synchronous classroom segment with low-latency multiplayer quizzing that dominates teacher-led instruction. Duolingo sustains its position through adaptive streak algorithms and speech recognition that personalize language acquisition at scale.
Gamification in education denotes the integration of game-design elements—point systems, progress bars, immediate feedback loops, and narrative scaffolding—into non-game learning environments to heighten motivation and knowledge retention. These systems typically operate through cloud-based deployment architectures with real-time analytics dashboards tracking learner engagement metrics at sub-second intervals. Corporate Training commands the largest current revenue pool as Fortune 500 firms replace passive compliance modules with scenario-based simulations and competitive leaderboards. Higher Education represents the fastest-expanding application segment as universities license platform seats for introductory STEM courses with high attrition rates. Mobile Apps within the deployment dimension capture disproportionate growth in emerging markets where smartphone penetration outpaces desktop access.
The U.S. Department of Education enforces FERPA constraints on student data portability, compelling vendors to architect localized data storage and parental consent workflows. ECHA and GDPR in Europe mandate granular opt-in mechanisms for behavioral tracking in gamified environments, raising compliance costs for cross-border platform providers. Stakeholders must monitor how generative AI integration into adaptive game narratives triggers emerging liability frameworks around algorithmic bias in educational assessment.
Market Dynamics
Cloud-native achievement architectures are fragmenting legacy learning management systems into modular engagement layers, forcing vendors to rebuild around API-first delivery models rather than monolithic platforms.
Growth Catalysts
- Federal Title I funding:United States school districts channel procurement toward gamified literacy tools through targeted federal allocations.
- Adaptive streak algorithms:Behavioral reinforcement mechanics drive retention in language acquisition and STEM remediation applications.
- Smartphone penetration:Emerging markets leapfrog desktop infrastructure through mobile-first deployment architectures.
Market Restraints
- GDPR compliance costs:European data portability mandates force granular opt-in redesigns for behavioral tracking systems.
- FERPA localization:United States student privacy rules require fragmented data storage architectures that raise operational overhead.
- Legacy worksheet substitution:K-12 procurement cycles slow platform replacement due to entrenched curriculum approval workflows.
Strategic Opportunities
- Introductory STEM attrition:Universities license platform seats for gateway courses with historically high dropout rates.
- Scenario-based simulations:Corporate training replaces passive compliance modules with competitive leaderboard mechanics.
- Speech recognition integration:Adaptive pronunciation feedback creates differentiation in language learning segments.
Industry Challenges
- Algorithmic bias liability:Generative AI integration into adaptive narratives triggers unproven assessment fairness frameworks.
- Parental consent workflows:Multi-jurisdictional data governance requires complex permission architectures for underage users.
- Real-time analytics infrastructure:Sub-second engagement tracking demands capital-intensive edge computing deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gamification in Education Market |
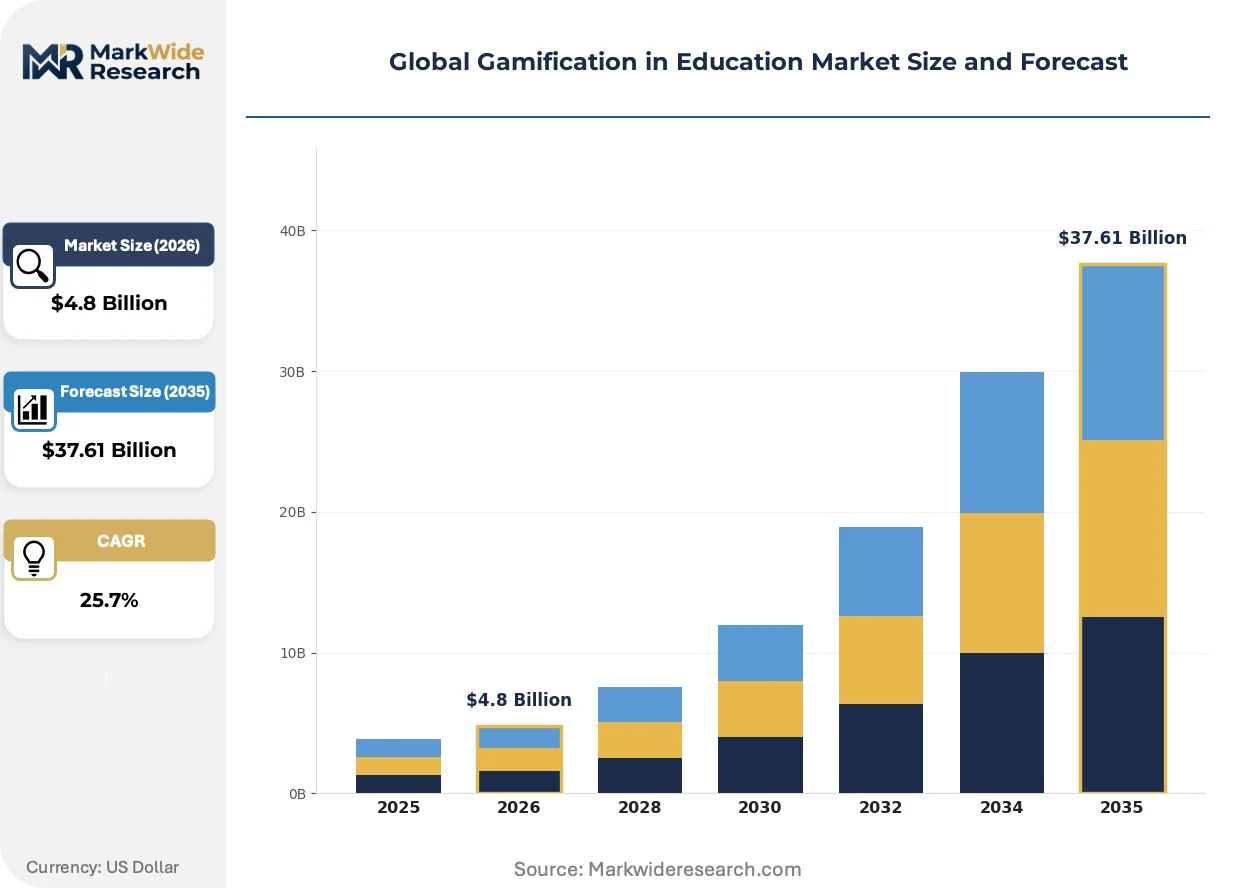
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $37.61 Billion |
| CAGR (2026 – 2036) | 25.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: K-12 Learning, Higher Education, Corporate Training, Skill Development, Language Learning Technology: Virtual Reality, Augmented Reality, Interactive Quizzes, Leaderboards, Badges & Rewards End User: Schools, Universities, Training Firms, E-learning Platforms, Educational Publishers Deployment: Cloud-Based, On-Premise, Hybrid, Mobile Apps, Web-Based |
| Companies Covered | Microsoft Corporation, Kahoot!, Duolingo, D2L Corporation, Quizlet, Classcraft Studios, NIIT, Top Hat, BLUERabbit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gamification in Education Market Shifts & Advancements
Generative AI and edge computing architectures are compressing the feedback loop between learner action and adaptive content adjustment, eliminating the latency that previously constrained personalized pacing.
API-driven micro-achievement systems are rendering obsolete the monolithic LMS architectures that once dominated institutional procurement. K-12 districts in the United States and university consortiums across Germany and Australia are adopting modular engagement layers that embed directly within existing collaboration tools. This fragmentation enables point-solution vendors to bypass platform gatekeepers and sell directly to departmental buyers.
The EU AI Act's risk classification framework for educational assessment tools is forcing vendors to document algorithmic decision pathways or face market exclusion. Compliance teams must now maintain technical documentation for adaptive difficulty engines that previously operated as proprietary black boxes. European higher education institutions are delaying procurement cycles until vendor certifications are finalized, compressing near-term revenue recognition timelines.
Subscription fatigue among district technology coordinators is accelerating preference for usage-based licensing over seat-based models. Platform providers are unbundling analytics dashboards and selling them separately to administrators while offering stripped-down student interfaces at lower price points. This bifurcation is most visible in United States public school systems where per-pupil software budgets face heightened scrutiny from state auditors.
Global Gamification in Education Market Segmentation
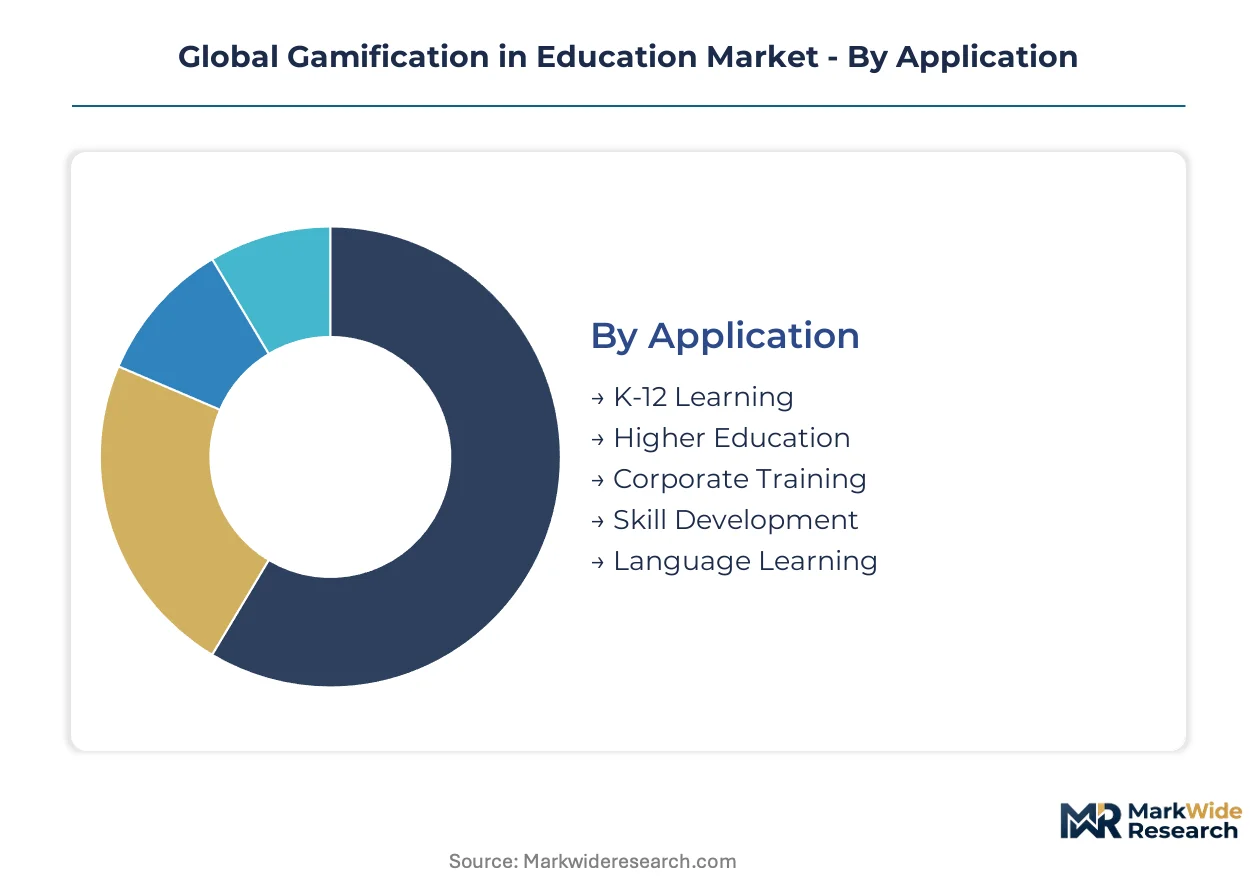
Gamification vendors engineer support intensity around deployment complexity and user lifecycle value. Cloud-native architectures demand continuous API maintenance, while on-premise installations require deeper field engineering. Application-level segmentation reveals divergent procurement rhythms between institutional buyers and consumer-directed learners.
Application:
After-sales-service intensity escalates with institutional scale and regulatory exposure. Enterprise deployments demand dedicated customer success teams, while individual learner apps operate through automated ticketing.
- K-12 Learning:Achievement-based platforms replace legacy worksheets through district-wide licensing. Procurement concentrates in United States Title I-funded districts where federal allocations channel spending toward literacy and STEM remediation tools. Compliance overhead from FERPA and state student privacy laws elevates vendor support costs.
- Corporate Training:Scenario-based simulations with competitive leaderboards displace passive compliance modules. Demand clusters in Fortune 500 firms seeking measurable engagement metrics for regulatory audit trails. Renewal rates hinge on integration depth with existing HRIS systems.
- Higher Education:Platform seats for gateway STEM courses with high attrition rates drive university procurement.
- Skill Development:Micro-credentialing systems align with workforce board funding in Germany and Singapore.
- Language Learning:Adaptive streak algorithms and speech recognition personalize acquisition at consumer scale.
By volume, Corporate Training leads. By growth pace, K-12 Learning is ahead.
Technology:
Technology selection correlates with hardware refresh cycles and content development amortization. Immersive modalities carry steeper upfront production costs but command premium pricing.
- Interactive Quizzes:Low-latency multiplayer architectures dominate synchronous classroom instruction. Teacher-led deployment in United States public schools and British academy chains drives volume. API-first design enables embedding within Microsoft Teams and Google Classroom workflows.
- Badges & Rewards:Progress visualization systems integrate with existing LMS gradebooks through LTI standards. Demand concentrates in Australian vocational institutes and Dutch secondary schools seeking non-monetary motivation mechanics. Customization requirements strain vendor design resources.
- Virtual Reality:Headset-dependent simulations require specialized IT support and physical space allocation.
- Augmented Reality:Mobile AR overlays reduce hardware barriers in emerging markets with smartphone penetration.
- Leaderboards:Competitive ranking systems face GDPR scrutiny in Europe for behavioral profiling of minors.
Interactive Quizzes holds the largest installed base. Augmented Reality shows the steepest expansion trajectory.
End User:
End-user type determines contract structure and data sovereignty requirements. Direct institutional sales carry longer sales cycles but higher lifetime value than platform-mediated distribution.
- Schools:District-level procurement aggregates purchasing power while fragmenting implementation timelines. United States K-12 systems route decisions through curriculum committees and technology directors. Parental consent workflows for underage data collection add operational overhead.
- E-learning Platforms:B2B2C distribution channels reach individual learners through aggregated marketplaces. Integration with payment systems and content libraries drives vendor selection in India and Brazil. Churn management demands continuous feature iteration.
- Universities:Departmental autonomy enables point-solution adoption bypassing central IT procurement.
- Training Firms:Custom content development requirements favor vendors with authoring tool suites.
- Educational Publishers:Legacy content digitization partnerships reshape competitive positioning for established textbook houses.
Schools dominate current procurement volume. E-learning Platforms are climbing the fastest.
Deployment:
Deployment architecture shapes infrastructure investment and margin structure. Mobile-first strategies capture emerging market growth while hybrid models address data residency requirements.
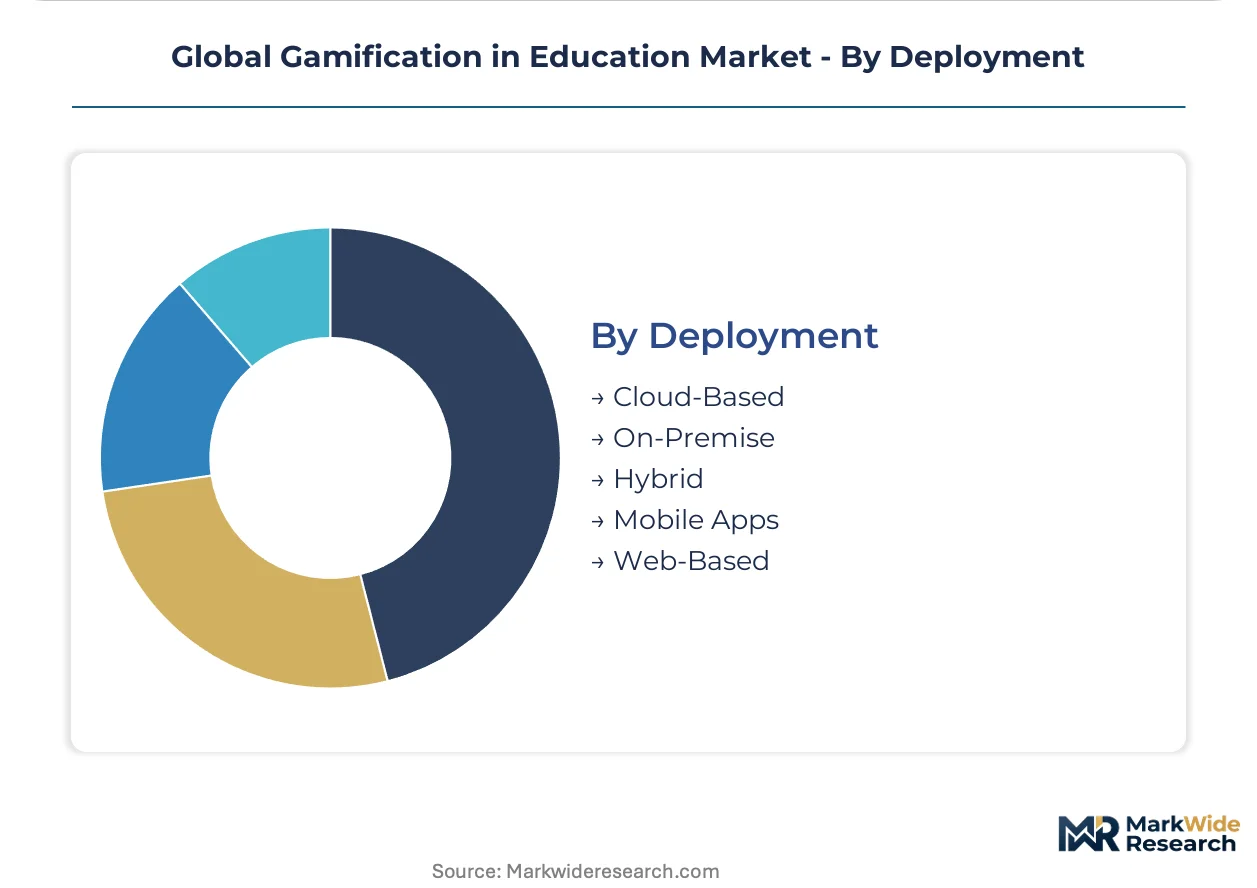
- Cloud-Based:Real-time analytics dashboards track engagement metrics at sub-second intervals through distributed edge computing. United States and Western European institutions prioritize scalability over localization. Subscription fatigue accelerates preference for usage-based licensing models.
- Mobile Apps:Smartphone penetration in Southeast Asia and sub-Saharan Africa leapfrogs desktop infrastructure limitations. Offline synchronization capabilities determine competitive viability in connectivity-constrained environments. App store commission structures compress vendor margins.
- Hybrid:Sensitive assessment data remains on-premise while engagement layers operate in cloud.
- On-Premise:German and Swiss universities mandate localized storage for research data protection.
- Web-Based:Browser-native delivery minimizes IT support burden for small and mid-sized institutions.
Cloud-Based deployment leads by revenue. Mobile Apps are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based platform providers export gamification architectures to English-speaking education markets in Australia, Canada, and the United Kingdom. Federal procurement programs in buyer countries accelerate cross-border licensing of achievement-based learning systems.
United States
Title I funding channels district procurement toward literacy and STEM remediation tools with embedded game mechanics. FERPA constraints force vendors to architect localized data storage and parental consent workflows for underage users. Austin and Boston metropolitan areas host concentrated clusters of edtech developers building API-first engagement layers for K-12 systems.
Germany
Vocational institutes and secondary schools drive demand for non-monetary motivation mechanics aligned with workforce board funding streams. ECHA and GDPR mandates impose granular opt-in requirements for behavioral tracking in gamified environments, elevating compliance costs. Berlin-Brandenburg and Bavaria regions concentrate platform development for dual education system integration.
China
MIIT standards and national curriculum digitization programs accelerate smartphone-based deployment in tier-two and tier-three cities. NMPA oversight of educational software classification creates certification bottlenecks for foreign platform providers. Yangtze River Delta and Pearl River Delta urban clusters dominate domestic platform development and pilot program rollouts.
India
BIS certification requirements and state-level digital literacy missions channel procurement toward mobile-first achievement platforms. PLI scheme incentives for electronics manufacturing indirectly support hardware-dependent VR and AR learning deployments. Karnataka and Telangana host concentrated edtech development corridors serving both domestic and export markets.
Australia
Vocational institutes adopt badge and progress visualization systems integrated through LTI standards with existing LMS infrastructure. TGA and national privacy framework compliance adds operational overhead for behavioral analytics deployment. Sydney and Melbourne metropolitan areas concentrate university consortium procurement for gateway course gamification.
Global Gamification in Education Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement environments where district-level and departmental buyers bypass centralized IT gatekeepers. The vendor base clusters around three strategic archetypes: cloud infrastructure incumbents with embedded achievement systems, synchronous classroom platforms with low-latency multiplayer architectures, and adaptive language specialists with consumer-scale retention algorithms. Competitive moves concentrate on API-first ecosystem partnerships and unbundled licensing models that separate analytics dashboards from student-facing interfaces.
Within the cloud infrastructure tier, Microsoft Corporation exemplifies platform-anchored distribution through institutional workflow integration. Kahoot! and Duolingo occupy distinct specialization vectors—synchronous classroom quizzing and adaptive language acquisition respectively—demonstrating how point-solution vendors bypass monolithic LMS gatekeepers. These three entities represent divergent scale and engagement models across institutional and consumer-directed market segments.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Kahoot! |
| Duolingo |
| D2L Corporation |
| Quizlet |
| Classcraft Studios |
| NIIT |
| Top Hat |
| BLUERabbit |
| Others |
Supply & Pricing Matrix
Tariff exposure on cloud infrastructure hardware from Taiwan and South Korea compresses margin spreads between premium adaptive platforms and stripped-down quiz tools, forcing vendors to regionalize data center placement while segmenting feature tiers by localization depth.
Pricing Analysis
The pricing gap between legacy LMS-embedded achievement modules, current cloud-native API layers, and next-generation generative AI adaptive engines spans three orders of magnitude in per-seat economics. SaaS-tiered subscription models dominate institutional procurement, with price differentiation driven by FERPA compliance certification grade and real-time analytics latency guarantees. Cost compression in the mid-tier is intensifying because Microsoft Teams and Google Classroom embed free baseline quizzing, eroding standalone vendor pricing power. K-12 district technology coordinators exhibit highest price sensitivity, while Fortune 500 corporate training buyers prioritize integration depth over per-seat cost.
Supply Chain Analysis
Upstream feedstock for gamification platforms draws from Taiwan's semiconductor foundries for edge computing chips, Ireland's data center infrastructure for GDPR-compliant hosting, and India's software engineering talent pools for adaptive algorithm development. Critical component dependencies include low-latency multiplayer server architectures, speech recognition APIs, and behavioral analytics middleware. Single-source vulnerability concentrates in hyperscaler cloud contracts with AWS, Azure, and GCP, where egress cost structures lock vendors into pricing rigidities. Distribution runs through direct institutional sales teams for enterprise accounts and app store marketplaces for consumer-directed language learning segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits at a platform-economics inflection where API-first interoperability is dissolving monolithic LMS gatekeeper power, rewarding vendors who embed within existing collaboration workflows rather than displacing them.
For Market Incumbents: Build switching-cost moats through deep HRIS and SIS integration that captures longitudinal learner data across academic or employment lifecycles. Incumbents should consolidate point-solution competitors in the K-12 achievement platform space before district procurement committees standardize on interoperable standards. Vertical integration into proprietary speech recognition engines defends against commoditization of language learning mechanics. For New Entrants and Emerging Players: Build out white-space positions in vocational micro-credentialing aligned with German and Singapore workforce board funding streams, where incumbent coverage remains thin. The most penetrable segment lies in AR-enabled STEM simulations for emerging market smartphone penetration zones. A channel partnership go-to-market with existing e-learning platform aggregators bypasses direct institutional sales cycle barriers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform-anchored strategists over pure-play point solutions. Long-term viability hinges on adaptive AI engine differentiation and regulatory compliance automation across FERPA, GDPR, and EU AI Act jurisdictions. Acquisition target archetypes include speech recognition specialists and edge computing infrastructure providers. The signal to watch as inflection indicator is EU AI Act certification completion timelines, which will compress vendor revenue recognition windows and accelerate distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding achievement layers within Microsoft Teams and Google Classroom captures institutional workflow lock-in. |
| Regulatory Certification Investment | EU AI Act technical documentation for adaptive engines opens procurement access across German and French universities. |
| Speech Recognition Acquisition | Proprietary pronunciation feedback algorithms differentiate language learning retention metrics at consumer scale. |
| Geographic Expansion | Mobile-first deployment in Southeast Asia leverages smartphone penetration leapfrogging desktop infrastructure gaps. |
| Strategic Partnership | HRIS integration alliances with Workday and SAP cement corporate training renewal rates through embedded analytics. |
Research Methodology
Initial hypotheses were tested against primary input from chief technology officers at K-12 districts, university provosts for digital learning, corporate learning and development directors, edtech platform engineers, and regulatory compliance officers at cross-border vendors, and refined through secondary validation against SEC filings from publicly traded platform providers, EU AI Act implementation guidance documents, U.S. Department of Education Title I allocation databases, and app store analytics from Sensor Tower. Bottom-up triangulation aggregated individual platform seat licensing data while top-down approaches cross-checked against federal procurement records and venture capital investment flows.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation dimensions across deployment architecture, institutional buyer type, application use case, technology modality, and regional regulatory cluster complexity. CAGRs were derived from cohort retention analysis of platform subscriber bases and diffusion curve modeling of API-first adoption patterns. Industry-specific forecast inputs included federal Title I funding trajectory assumptions and EU AI Act certification bottleneck duration estimates.
Practitioners should monitor EU AI Act enforcement discretion, FERPA state-level legislative fragmentation, and hyperscaler cloud pricing recalibrations for early signals of forecast revision triggers. Cross-checking against National Center for Education Statistics district technology expenditure surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
SETM Education Market
Educational Technology (EdTech)
Global Edutainment Centers Market
Educational Technology (EdTech)
Smart Education System Market
Educational Technology (EdTech)
Digital Classroom Market
Educational Technology (EdTech)
Global Social Learning Platforms Market
Educational Technology (EdTech)
Child Care Software Market
Educational Technology (EdTech)
Smart Education and Learning Market
Educational Technology (EdTech)
Specific Gravity Bench Apparatus Market
Educational Technology (EdTech)
Education Apps Market
Educational Technology (EdTech)
Student Response System Market
Educational Technology (EdTech)
Digital Badges Market
Educational Technology (EdTech)
Asia-Pacific Digital Education Market
Educational Technology (EdTech)
ASEAN Smart Education and Learning Market
Educational Technology (EdTech)
Global Smart Learning Market
Educational Technology (EdTech)
Micro Learning Platform Market
Educational Technology (EdTech)
AI in K-12 Education Market