
 ASEAN Smart Education and Learning Market | 2026-2036
ASEAN Smart Education and Learning Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Smart Education and Learning Market Outlook
Buyer concentration among K-12 schools is expanding as ministries of education consolidate vendor contracts at the provincial level across Southeast Asia. SMART Technologies ULC leverages its interactive display hardware to anchor procurement frameworks in Thailand and Vietnam. Cisco Systems, Inc. competes through network infrastructure that sustains connectivity-dependent virtual classroom deployments. Blackboard Inc. differentiates via learning management system specialization for higher education institutions seeking scalable platforms.
ASEAN Smart Education and Learning encompasses digitally integrated pedagogical systems combining hardware interfaces, software platforms, and data analytics to deliver personalized instruction across distributed learner populations. Cloud computing architecture enables real-time content synchronization across low-bandwidth environments prevalent in rural Indonesia and the Philippines. Learning Management System solutions command the largest installed base among solution types, while Artificial Intelligence segments exhibit the fastest capability maturation through adaptive assessment algorithms. Mobile Learning Apps within product type classification capture concentrated demand from Indonesia's smartphone-first student population.
Thailand's Office of the Basic Education Commission, Malaysia's Ministry of Education Digital Education Policy, and Singapore's Infocomm Media Development Authority collectively shape procurement standards and data governance requirements for classroom technology deployments. TRAI-equivalent spectrum regulators across member states influence mobile learning viability through broadband allocation decisions. Stakeholders must monitor divergent national curriculum digitization timelines to align platform localization investments with enforceable procurement windows.
Market Dynamics
Cloud computing architecture is absorbing procurement budgets across ASEAN ministries of education, compressing hardware-centric purchasing into integrated platform subscriptions that bundle analytics, content, and connectivity.
Growth Catalysts
- Malaysia's Digital Education Policy:The national mandate for smart classroom infrastructure upgrades creates enforceable procurement windows for interactive display and learning management system vendors.
- Indonesia's archipelagic geography:Dispersed island populations drive concentrated demand for mobile learning applications that function across low-bandwidth cellular networks.
- Artificial Intelligence:Adaptive assessment algorithms are maturing fastest among solution types, enabling personalized instruction pathways that differentiate platform offerings.
Market Restraints
- Broadband infrastructure gaps:Rural Indonesia and the Philippines lack fiber penetration, forcing mobile-first architectures that limit synchronous video capabilities.
- Vendor concentration risk:Thailand and Vietnam procurement frameworks anchor on single interactive display suppliers, creating lock-in and price inflexibility.
- Curriculum misalignment:Divergent national digitization timelines across ASEAN member states fragment platform localization investments.
Strategic Opportunities
- Philippines rural K-12:Underpenetrated public school districts outside Metro Manila present white space for offline-capable content synchronization platforms.
- Singapore's IMDA standards:The Infocomm Media Development Authority's procurement specifications create reference architectures that neighboring ministries adopt.
- AI-LMS convergence:Integration of adaptive algorithms with learning management systems enables premium pricing for predictive analytics dashboards.
Industry Challenges
- Data localization compliance:Thailand's Office of the Basic Education Commission and Malaysia's Ministry of Education impose conflicting student data sovereignty requirements.
- Teacher digital literacy gaps:K-12 institutions face execution risk from workforce training timelines that lag hardware deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Smart Education and Learning Market |
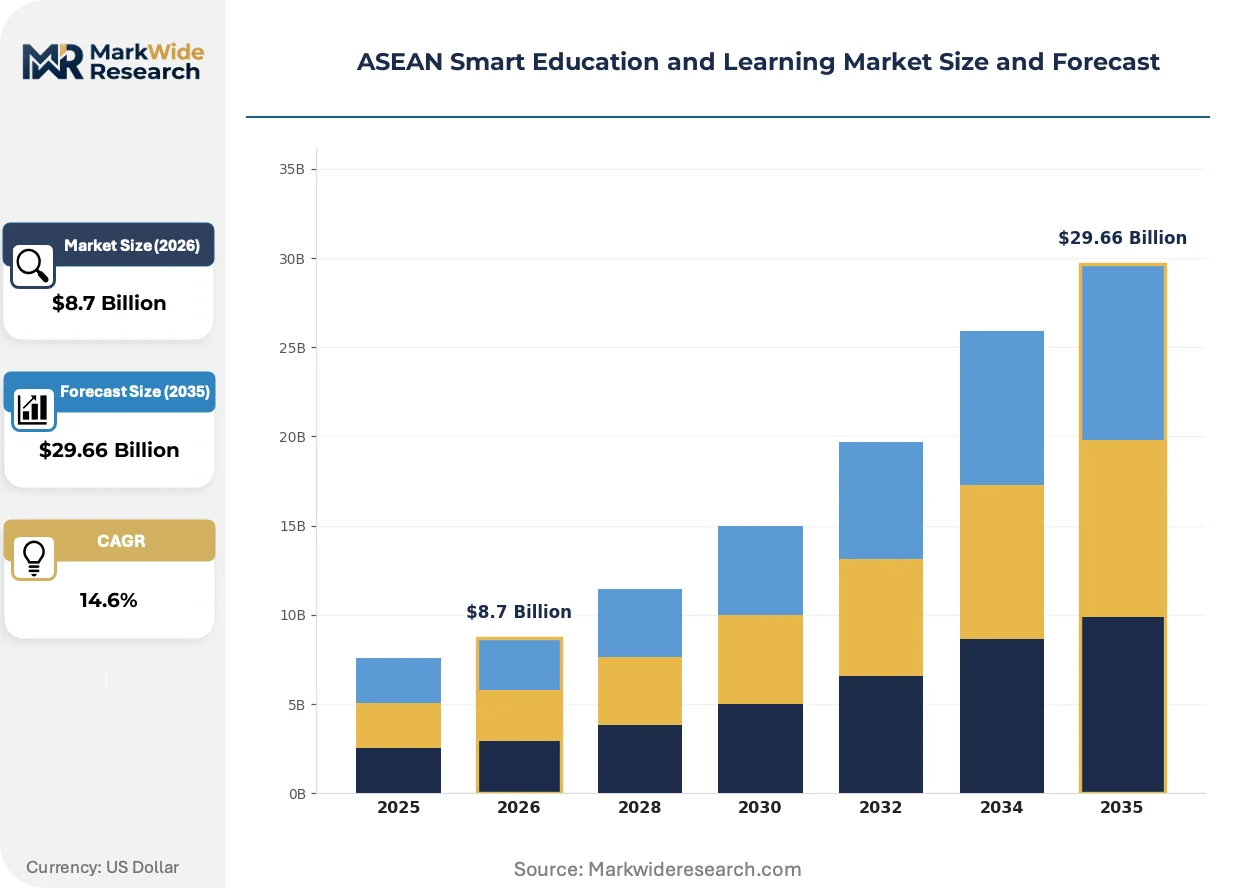
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Learning Management System, Assessment Tools, Virtual Classrooms, Interactive Learning Environments Technology: Artificial Intelligence, Augmented Reality, Cloud Computing, Blockchain End User: Higher Education Institutions, K-12 Schools, Corporates, Educational Content Developers Product Type: E-Learning Modules, Mobile Learning Apps, Simulation Software, Smart Classrooms |
| Companies Covered | SMART Technologies ULC, Educomp Solutions Ltd, Blackboard Inc., NIIT LTD., Saba Software, Cisco Systems, Inc., Extramarks Education Pvt. Ltd., Unit4 N.V., Adobe Systems Incorporated, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Smart Education and Learning Market Strategic Shifts
Platform architectures are absorbing functionality from adjacent categories, collapsing point solutions into unified stacks that reduce buyer integration burden and compress vendor margins.
Generative AI is absorbing curriculum development workflows across higher education institutions in Singapore and Malaysia, compressing content production timelines from months to days. Universities are adopting these tools fastest among buyer segments, driven by pressure to localize international course materials. The structural consequence is displacement of traditional educational publishers from content creation toward platform licensing.
Thailand's Office of the Basic Education Commission has mandated interoperability standards for classroom technology procurement, forcing vendors to certify against common data exchange protocols. This policy compresses switching costs for schools and fragments proprietary ecosystem advantages. Hardware suppliers in Bangkok and Chiang Mai procurement zones are responding by open-sourcing middleware layers.
Subscription pricing is displacing perpetual licenses across ASEAN K-12 and higher education procurement, unbundling upfront capital expenditure into operational budgets that align with annual fiscal cycles. Channel partners in Jakarta and Kuala Lumpur are pivoting from reseller margins toward recurring revenue shares. This shift is most visible in Indonesia, where archipelagic deployment logistics previously favored single-volume purchase consolidation.
ASEAN Smart Education and Learning Market Segmentation
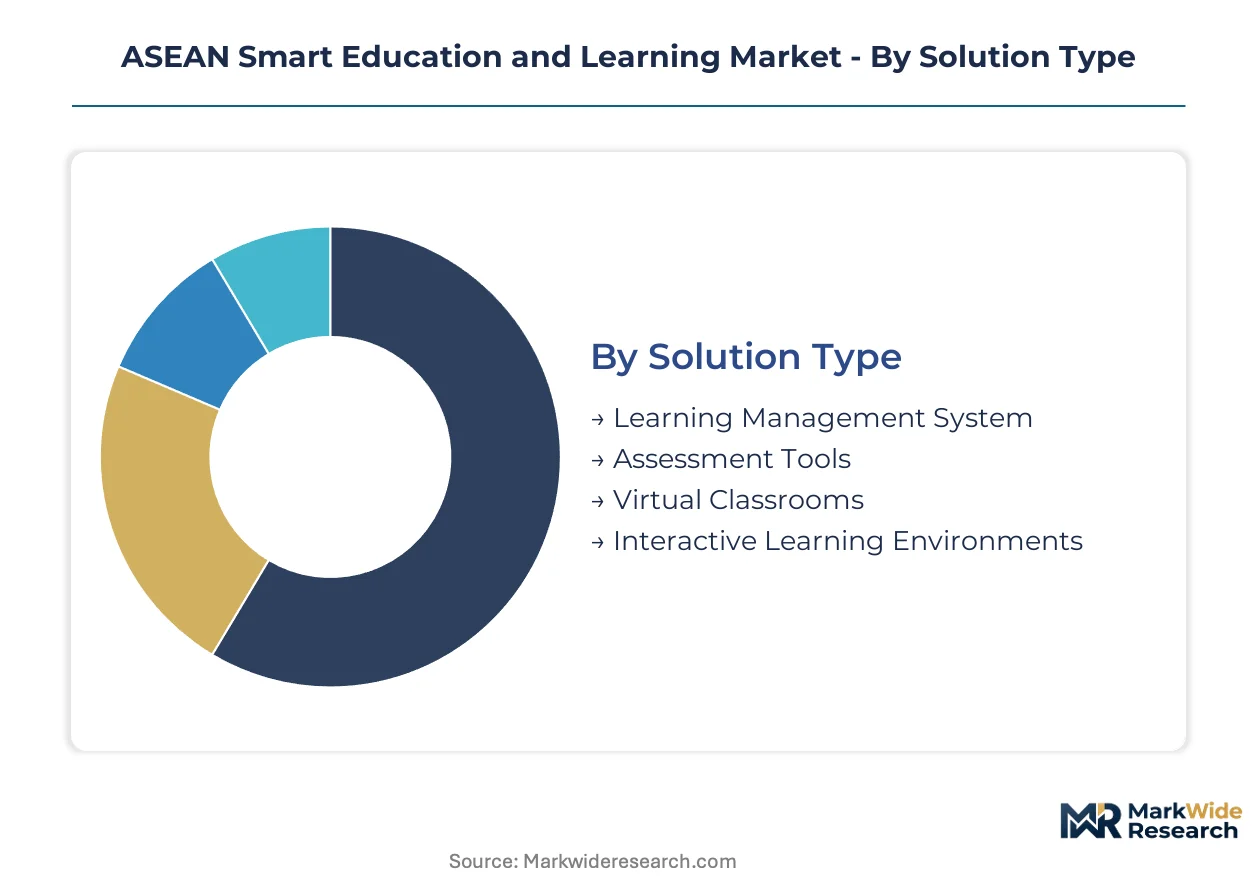
Procurement patterns across ASEAN ministries fragment vendor targeting by solution architecture, technology maturity, and institutional buyer type. Segmentation clarity determines platform localization investments and channel partner selection.
Solution Type:
Volume concentration sits with established infrastructure platforms, while premium pricing attaches to specialized assessment and immersive environments.
- Learning Management System:Core software platforms synchronize curriculum delivery, attendance tracking, and grade management across distributed school networks. Indonesia's K-12 procurement frameworks mandate LMS compatibility for national exam administration, driving standardization around SCORM-compliant architectures.
- Assessment Tools:Adaptive testing engines with AI-driven item banks enable real-time difficulty adjustment based on student performance trajectories. Malaysia's Ministry of Education Digital Education Policy requires formative assessment integration, concentrating demand in Penang and Selangor pilot districts.
- Virtual Classrooms:Synchronous video platforms with breakout room functionality and shared whiteboard spaces.
- Interactive Learning Environments:Gamified content modules with progress visualization and competency-based advancement pathways.
Mature deployment sits with Learning Management System infrastructure. Newer deployment is concentrated in Assessment Tools with adaptive capabilities.
Technology:
Cost tiering separates commodity cloud infrastructure from emerging immersive and distributed ledger architectures.
- Artificial Intelligence:Machine learning models power personalized learning pathways, predictive dropout risk scoring, and automated essay evaluation. Singapore's IMDA procurement specifications prioritize AI literacy integration, accelerating adoption across polytechnics and autonomous universities.
- Cloud Computing:Elastic compute and storage resources enable multi-tenant platform delivery without on-premise server investment. Thailand's Office of the Basic Education Commission consolidates provincial contracts through Government Cloud infrastructure, compressing vendor margins.
- Augmented Reality:Spatial computing overlays for science visualization and historical site reconstruction in mobile-first deployments.
- Blockchain:Distributed credential verification for micro-certificates and cross-border transcript authentication.
Cloud Computing anchors current procurement volumes. Artificial Intelligence commands the steepest expansion trajectory across higher education and corporate training segments.
End User:
Customer type determines pricing elasticity, with institutional buyers consolidating vendor relationships while content developers seek modular API access.
- K-12 Schools:Public sector procurement frameworks across Thailand, Malaysia, and Indonesia mandate interoperability standards and data localization compliance. Archipelagic logistics in Indonesia favor mobile-optimized platforms with offline synchronization.
- Higher Education Institutions:Universities in Singapore and Kuala Lumpur prioritize research collaboration tools and international student recruitment platforms. Generative AI adoption for curriculum localization is displacing traditional publisher relationships fastest in this segment.
- Corporates:Enterprise learning management for workforce reskilling with SCORM/xAPI compliance and HRIS integration.
- Educational Content Developers:Authoring tool access and distribution platform APIs for third-party curriculum commercialization.
K-12 Schools dominate current installed base. Higher Education Institutions are gaining share fastest through digital transformation grants and international accreditation requirements.
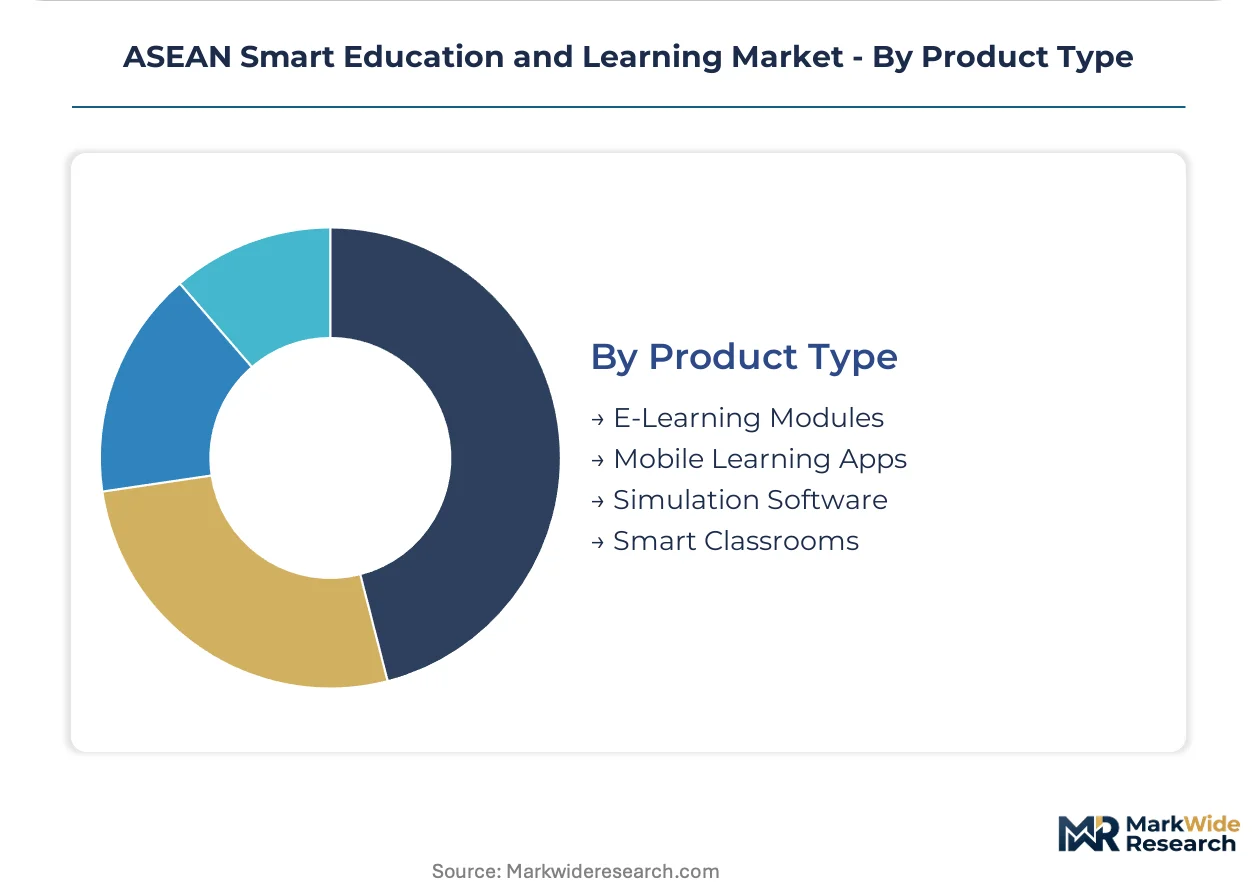
Product Type:
Application use case separates asynchronous self-paced modules from synchronous immersive and physical classroom deployments.
- Mobile Learning Apps:Smartphone-native interfaces with adaptive streaming for low-bandwidth cellular networks. Indonesia's smartphone-first student population and dispersed island geography create concentrated demand for lightweight, offline-capable architectures.
- Smart Classrooms:Integrated hardware-software environments combining interactive displays, IoT sensors, and environmental controls. Malaysia's national digital education policy mandates infrastructure upgrades, creating enforceable procurement windows for display and control system vendors.
- E-Learning Modules:Self-contained multimedia content packages with embedded assessments and progress tracking.
- Simulation Software:Virtual laboratory environments for STEM education and vocational skill certification.
Smart Classrooms represent established procurement category. Mobile Learning Apps are expanding most quickly through Indonesia's archipelagic deployment requirements and Philippines rural connectivity constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's archipelagic geography anchors procurement patterns across Southeast Asia, with mobile-first architectures dominating connectivity-constrained deployments. Malaysia's national digital infrastructure mandates reshape vendor qualification requirements. Thailand's interoperability standards create reference frameworks adopted by neighboring ministries.
Indonesia
Jakarta's Ministry of Education drives demand through national exam digitization mandates requiring SCORM-compliant learning management systems. The country's telecommunications regulator allocates cellular spectrum for educational content delivery across 17,000 islands. Bandung and Surabaya host the densest concentrations of ed-tech channel partners deploying offline-synchronization platforms.
Malaysia
Putrajaya's Ministry of Education Digital Education Policy mandates smart classroom infrastructure upgrades across Penang and Selangor pilot districts. The national policy creates enforceable procurement windows for interactive display vendors. Kuala Lumpur's technology corridor concentrates system integrators bundling hardware-software solutions for K-12 deployments.
Thailand
Bangkok's Office of the Basic Education Commission consolidates provincial vendor contracts through Government Cloud infrastructure. The commission's interoperability standards force certification against common data exchange protocols. Chiang Mai procurement zones exhibit growing adoption of open-source middleware by hardware suppliers responding to switching cost compression.
Singapore
The Infocomm Media Development Authority shapes regional procurement specifications through AI literacy integration mandates. Autonomous universities and polytechnics prioritize research collaboration tools and international student recruitment platforms. Jurong and One-North technology clusters host generative AI curriculum localization pilots displacing traditional publisher relationships.
Philippines
Metro Manila's Department of Education procurement frameworks contrast with underpenetrated rural K-12 districts creating white space for offline-capable platforms. The country's archipelagic constraints mirror Indonesia's mobile-first deployment requirements. Cebu and Davao emerging as secondary hubs for content synchronization vendors targeting low-bandwidth environments.
ASEAN Smart Education and Learning Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue AI-integrated assessment specializations. The vendor base stratifies across three tiers: multinational hardware-software integrators anchoring government procurement frameworks, regional learning management specialists capturing ministry standardization benefits, and mobile-first application developers exploiting archipelagic deployment requirements. Dominant competitive moves include strategic partnerships with telecommunications operators for bandwidth-guaranteed service delivery and portfolio diversification into predictive analytics dashboards.
Within the hardware-software integration tier, SMART Technologies ULC and Cisco Systems, Inc. represent archetypal approaches to infrastructure-heavy deployments. SMART Technologies ULC anchors procurement frameworks in Thailand and Vietnam through interactive display specialization. Cisco Systems, Inc. exemplifies network infrastructure positioning that sustains connectivity-dependent virtual classroom architectures. Blackboard Inc. occupies a distinct position within learning management system specialization for higher education scalability.
| Leading Market Players |
|---|
| SMART Technologies ULC |
| Educomp Solutions Ltd |
| Blackboard Inc. |
| NIIT LTD. |
| Saba Software |
| Cisco Systems, Inc. |
| Extramarks Education Pvt. Ltd. |
| Unit4 N.V. |
| Adobe Systems Incorporated |
| Others |
Value Chain & Pricing Dynamics
Semiconductor memory price indices cascade through interactive display manufacturing costs into ASEAN education procurement tiers, compressing margins for hardware-software integrators while elevating cloud platform subscription premiums.
Pricing Analysis
Warranty and service bundling separates premium-tier vendors offering multi-year maintenance contracts from economy-tier suppliers selling bare hardware with pay-per-incident support. Pricing stratifies across premium, standard, and economy tiers based on interoperability certification level and deployment scale. Cost compression in standard-tier interactive displays is intensifying because Thailand's Government Cloud procurement consolidates provincial contracts. K-12 public schools exhibit highest price sensitivity, while Singaporean autonomous universities prioritize functionality over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Malaysia's Ministry of Education and Thailand's Office of the Basic Education Commission mandate multi-supplier qualification for interactive display components and cloud infrastructure. Hardware assembly concentrates in China, Taiwan, and South Korea, while software development clusters in India and Singapore. Component sourcing draws from semiconductor foundries, LCD panel manufacturers, and cellular modem suppliers. Single-source vulnerability persists in AI accelerator chips. Distribution runs through Jakarta and Kuala Lumpur channel partners pivoting from reseller margins toward recurring revenue shares.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud infrastructure capacity constraints in ASEAN government data centers prop pricing power for platform vendors with certified deployment credentials.
For Market Incumbents: Cement procurement framework anchoring through interoperability certification investments that comply with Thailand's mandated data exchange protocols. Deepen backward integration into AI assessment algorithms to defend against specialized entrants. Prioritize channel control in Jakarta and Surabaya logistics hubs to lock out mobile-first competitors. For New Entrants and Emerging Players: The mid-tier pricing gap between SMART Technologies ULC premium installations and unbranded economy hardware creates entry space for adaptive assessment specialists. Target Philippines rural K-12 districts with offline-synchronization architectures. Pursue white-label partnerships with Indonesian telecommunications operators for bandwidth-guaranteed service delivery. For Investors and Strategic Acquirers: Distressed-cycle entries favor mobile-learning application developers with proven low-bandwidth architectures in Indonesia. Long-term viability hinges on AI-LMS convergence capabilities and ministry standardization alignment. Watch for inflection in Malaysia's smart classroom infrastructure procurement windows as signal for sector repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies LMS, assessment, and virtual classroom functions to meet Thailand's interoperability mandates. |
| Strategic Partnership | Telecommunications operator alliances secure bandwidth-guaranteed delivery across Indonesia's archipelagic networks. |
| Acquisition of Specialist Firm | AI assessment algorithm developers add predictive analytics premium pricing to core platform subscriptions. |
| Geographic Expansion | Philippines rural district penetration captures white space in offline-capable content synchronization. |
| Product Launch | Generative AI curriculum tools displace traditional publishers in Singapore higher education localization workflows. |
Study Parameters
Document review covered ministry procurement frameworks, spectrum allocation decisions, and national curriculum digitization policies, complemented by interviews with K-12 technology procurement officers, higher education CIOs, ed-tech channel partners, and cloud infrastructure engineers. Secondary validation drew from ASEAN telecommunications regulator filings, government cloud expenditure disclosures, and SCORM compliance certification databases. Bottom-up school-level deployment estimates triangulated against top-down ministry budget allocations.
Market size outputs reflect segment-level modeling across solution type, technology maturity, end-user institution category, and product architecture dimensions throughout the forecast period. CAGRs were derived from elasticity-adjusted adoption curves incorporating broadband penetration trajectories and ministry procurement timeline enforcement. Forecast inputs included smartphone-first student population growth, interactive display replacement cycles, and AI literacy integration mandates.
Inputs from ministry procurement officers and channel partners were available through the study window; gaps in rural connectivity infrastructure data introduce uncertainty bands around Philippines and Indonesia mobile-learning adoption trajectories. Forecasts reflect documented assumptions regarding policy enforcement consistency and spectrum allocation timelines. Deviation in Malaysia's smart classroom infrastructure procurement schedule would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
North America Digital Education Market
Educational Technology (EdTech)
SETM Education Market
Educational Technology (EdTech)
Edtech Market
Educational Technology (EdTech)
VR Education Market
Educational Technology (EdTech)
Global IoT in Education Market
Educational Technology (EdTech)
Education Security Market
Educational Technology (EdTech)
Global K-12 Software Market
Educational Technology (EdTech)
Blockchain in Edutech Market
Educational Technology (EdTech)
Digital Classroom Market
Educational Technology (EdTech)
Student Response System Market
Educational Technology (EdTech)
E Learning Virtual Reality Market
Educational Technology (EdTech)
Edutainment Market
Educational Technology (EdTech)
Virtual Schools Market
Educational Technology (EdTech)
Global Smart Classroom Market
Educational Technology (EdTech)
Specific Gravity Bench Apparatus Market
Educational Technology (EdTech)
Education Technology Market