
 Global Micro-Learning Market | 2026-2036
Global Micro-Learning Market Size, Share, and Industry Trends Forecast 2026-2036
Global Micro-Learning Market Foresight
Healthcare and pharmaceutical onboarding is restructuring enterprise training budgets toward modular digital formats. Axonify leverages gamification mechanics to anchor retention in frontline workforce segments. 360Learning sustains competitive intensity through collaborative authoring tools that reduce content production cycles. Docebo dominates extended enterprise use cases, controlling channel partner certification workflows for multinational manufacturers.
Micro-learning denotes the delivery of educational content in compact, typically sub-ten-minute units designed for immediate application and spaced repetition reinforcement. Platforms encode video modules, interactive quizzes, and scenario-based learning into mobile-optimized formats that minimize cognitive load while maximizing knowledge retention rates. Cloud-based deployment leads solution architecture due to elastic scaling and reduced IT overhead, though mobile-first configurations represent the fastest-expanding configuration as frontline worker enablement spreads beyond deskbound populations. Video modules occupy the largest solution type share, while gamification commands premium pricing where engagement metrics tie directly to compliance audit outcomes.
The EU AI Act and GDPR impose documentation burdens that reshape platform procurement criteria across European financial services and telecommunications sectors. FDA 21 CFR Part 11 validation requirements in the United States constrain vendor selection for pharmaceutical and medical device manufacturers seeking compliant training records. OSHA hazard communication standards drive manufacturing adoption of scenario-based micro-modules for safety-critical refresher training. Stakeholders must monitor evolving AI transparency mandates and their translation into auditable learning path requirements.
Market Dynamics
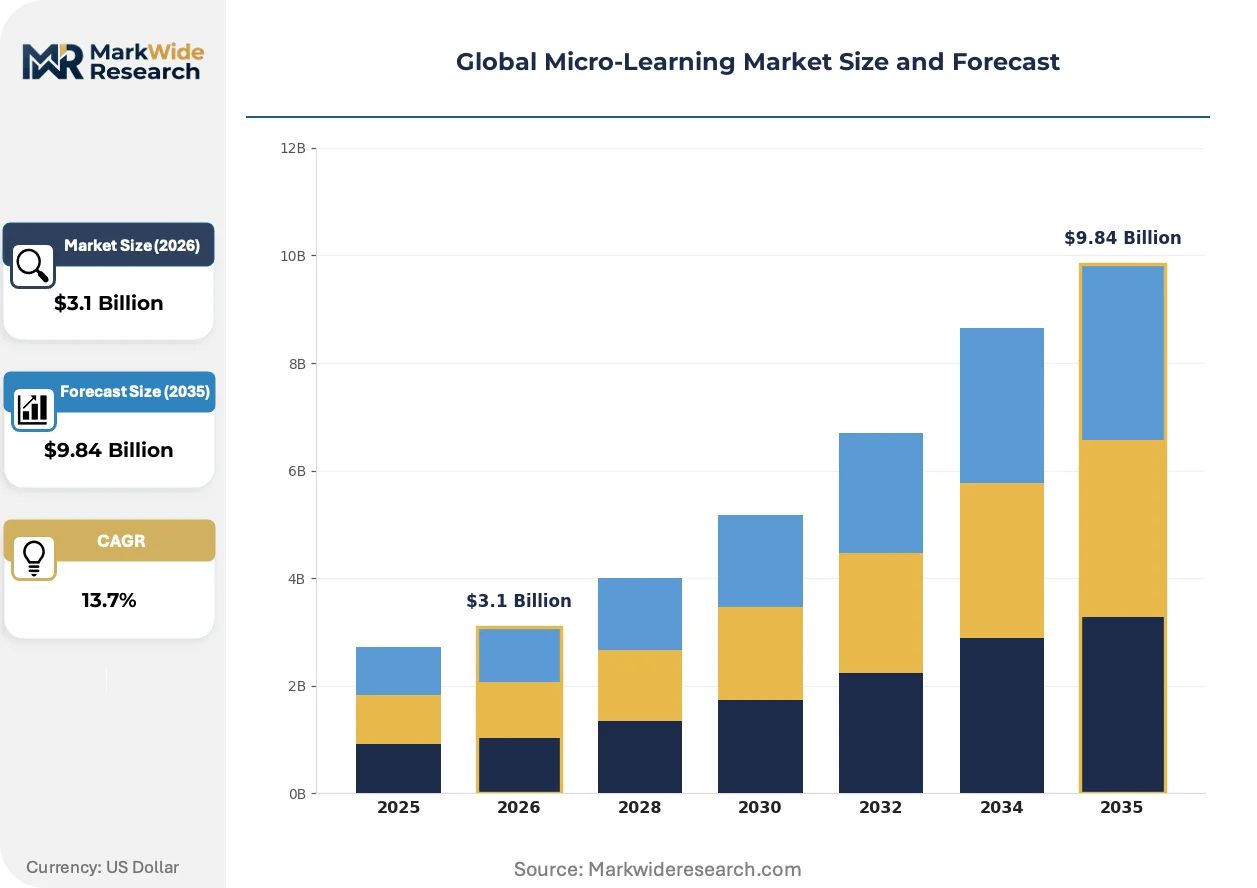
Corporate learning and development budgets are pivoting toward bite-sized digital formats as workforce modernization mandates and compliance documentation requirements intensify across regulated industries.
Growth Catalysts
- Federal workforce modernization initiatives:United States government agencies are procuring mobile-first training platforms to upskill deskbound and field personnel simultaneously.
- EU AI Act documentation burdens:European financial services and telecommunications enterprises now require auditable, timestamped learning records for algorithmic accountability.
- OSHA hazard communication standards:Manufacturing facilities in the United States are deploying scenario-based micro-modules for safety-critical refresher training.
Market Restraints
- Content production cost escalation:High-fidelity video module development and interactive scenario scripting consume disproportionate budget share relative to traditional e-learning formats.
- Cloud infrastructure concentration:Platform scalability depends on hyperscaler availability zones, creating geographic dependency for latency-sensitive mobile delivery.
- FDA 21 CFR Part 11 validation friction:Pharmaceutical and medical device manufacturers face extended vendor qualification timelines for compliant training record systems.
Strategic Opportunities
- Frontline worker enablement in India:BIS certification requirements and PLI scheme manufacturing expansion are creating demand for localized, low-bandwidth micro-learning deployment.
- Extended enterprise channel certification:Multinational manufacturers require scalable partner onboarding systems that compress certification cycles from weeks to days.
- Gamification-meets-compliance convergence:Engagement mechanics that generate auditable completion metrics are commanding premium positioning in financial services procurement.
Industry Challenges
- Instructional design talent scarcity:Specialized expertise in spaced repetition science and cognitive load optimization remains concentrated among boutique consultancies.
- Legacy LMS integration complexity:Enterprises with entrenched learning management infrastructure face API fragmentation when grafting micro-learning modules onto monolithic platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Micro-Learning Market |
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $9.84 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Mobile-First, Web-Based Solution Type: Video Modules, Interactive Quizzes, Gamification, Podcast Lessons, Scenario-Based Learning Use Case: Employee Skill Development, Compliance Training, Sales Enablement, Leadership Training, Customer Onboarding End User Industry: Information Technology, Financial Services, Manufacturing, Government Agencies, Telecommunications |
| Companies Covered | OttoLearn, 360Learning, Axonify, Thinkific, LearnUpon, CYPHER Learning, The Leap, Zydii, Docebo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Micro-Learning Market Shifts & Advancements
Artificial intelligence is embedding into content authoring pipelines, compressing production cycles while regulatory mandates are hardening documentation requirements for algorithmic transparency.
Adaptive learning algorithms are personalizing module sequencing based on individual competency gaps and historical performance patterns. Financial services compliance teams in Germany and France are piloting these systems to satisfy CNIL and KBA audit expectations. This capability is converging with real-time sentiment analysis to flag learner disengagement before completion rates degrade.
GDPR and the EU AI Act are mandating explainable training paths for employees interacting with automated decision systems. European banking regulators now require timestamped, immutable records linking specific learning modules to job function permissions. Vendors are responding with blockchain-anchored credentialing layers that satisfy EBA supervisory expectations without compromising user experience.
Buyer procurement patterns are compressing vendor evaluation cycles as chief learning officers prioritize pilot-to-scale velocity over exhaustive RFP processes. Manufacturing and logistics sectors in the United States are favoring platforms with pre-built OSHA and EPA content libraries that accelerate time-to-compliance. This behavioral shift favors vendors with modular API architectures over those requiring wholesale LMS replacement.
Global Micro-Learning Market Segmentation
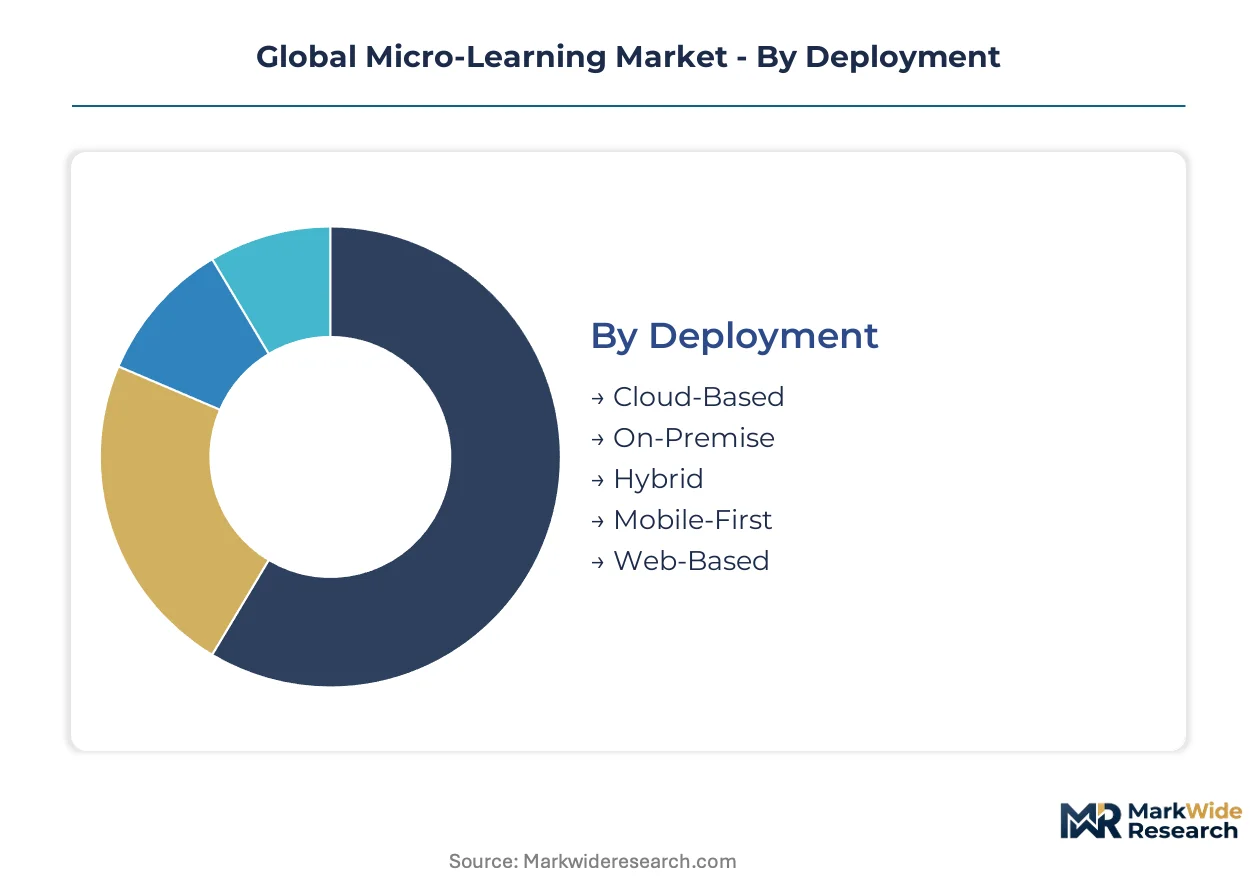
Micro-learning platforms fragment across deployment architectures, content modalities, and regulatory use cases. Procurement patterns diverge sharply between cost-sensitive volume deployments and premium configurations where audit-grade documentation commands price premiums.
Deployment:
Volume deployments favor elastic scaling, while premium positioning attaches to air-gapped or latency-optimized configurations.
- Cloud-Based:Elastic infrastructure dominates enterprise procurement due to reduced IT overhead and automatic scaling during usage spikes. Financial services firms in Germany and France select multi-tenant configurations with EU data residency to satisfy CNIL audit expectations.
- Mobile-First:Frontline worker enablement drives fastest expansion as manufacturing and logistics operations extend training beyond deskbound populations. Indian PLI scheme manufacturing clusters demand low-bandwidth mobile delivery for plant-floor deployment.
- Hybrid:Split architectures satisfy defense sector mandates requiring classified content on-premise with unclassified modules cloud-hosted.
- On-Premise:Air-gapped installations persist in pharmaceutical manufacturing where FDA 21 CFR Part 11 validation demands localized audit trails.
- Web-Based:Browser-dependent delivery retains cost-sensitive mid-market share where native app development exceeds budget constraints.
Today's leader: Cloud-Based. Tomorrow's challenger: Mobile-First.
Solution Type:
Content modality selection tracks cognitive load optimization versus engagement depth tradeoffs.
- Video Modules:Visual instruction dominates solution mix with sub-ten-minute formats minimizing attention decay. OSHA hazard communication standards in United States manufacturing drive scenario-based video scripting for safety-critical refresher training.
- Gamification:Mechanics embedding points, badges, and leaderboards command premium pricing where completion metrics tie directly to compliance audit outcomes. EBA supervisory expectations in European banking now require timestamped engagement logs.
- Interactive Quizzes:Spaced repetition algorithms personalize reinforcement intervals based on individual retention patterns.
- Scenario-Based Learning:Branching simulations satisfy high-stakes certification requirements in medical device sales and aviation maintenance.
- Podcast Lessons:Audio-only formats capture commute-time learning for distributed field sales forces with intermittent connectivity.
Video Modules anchor current procurement volumes; Gamification climbs fastest as financial services procurement hardens documentation requirements.
Use Case:
Regulatory pressure intensity separates mandatory compliance budgets from discretionary skill investment.
- Compliance Training:GDPR and EU AI Act documentation burdens reshape European procurement criteria toward auditable, timestamped learning records. Algorithmic accountability mandates in German and French banking now require immutable training path documentation.
- Employee Skill Development:Federal workforce modernization initiatives in the United States sustain platform procurement across civilian agencies and defense contractors.
- Sales Enablement:Compressed certification cycles for channel partners favor modular architectures that reduce onboarding from weeks to days.
- Customer Onboarding:Extended enterprise deployments certify end-users on complex equipment and software platforms.
- Leadership Training:High-potential development programs select platforms with coaching integration and 360-degree feedback loops.
Compliance Training captures non-discretionary spend; Sales Enablement gains share as multinational manufacturers consolidate partner ecosystems.
End User Industry:
Regulatory density and workforce dispersion determine platform sophistication requirements.
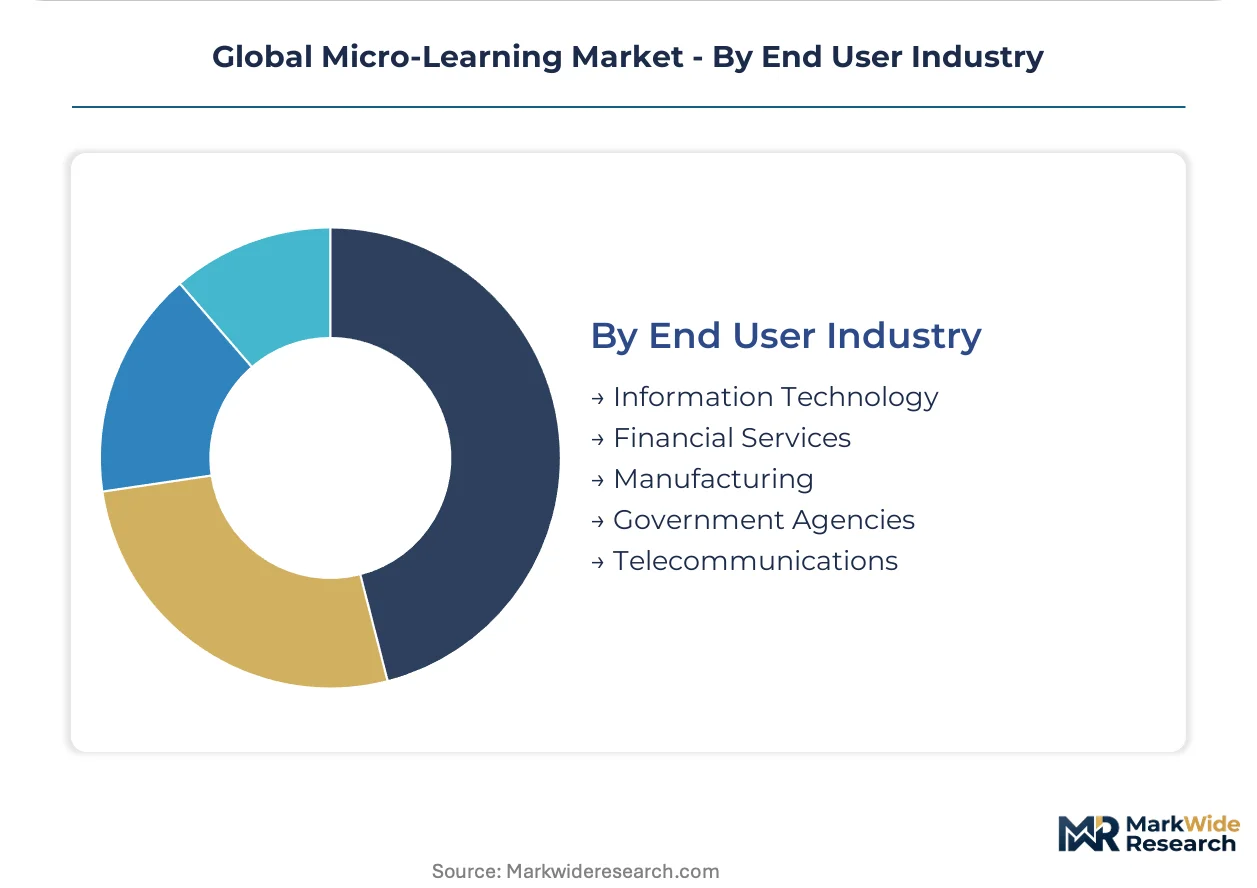
- Financial Services:EU AI Act and GDPR impose documentation burdens that reshape procurement criteria across European banking and insurance. CNIL and KBA audit expectations favor blockchain-anchored credentialing layers.
- Government Agencies:United States federal mandates sustain mobile-first platform procurement for simultaneous deskbound and field personnel upskilling.
- Manufacturing:OSHA hazard communication standards drive scenario-based micro-module deployment for safety-critical refresher training in United States facilities.
- Information Technology:Rapid certification cycles for emerging technologies favor adaptive learning algorithms that compress time-to-competency.
- Telecommunications:Field technician enablement across distributed infrastructure demands offline-capable mobile delivery with synchronization upon connectivity restoration.
Financial Services anchors premium pricing; Government Agencies provide volume foundation through sustained federal procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States federal procurement anchors platform adoption as defense contractors and civilian agencies modernize workforce training infrastructure. Corporate learning budgets in financial services and manufacturing are pivoting toward mobile-first deployment. Regulatory documentation mandates across multiple jurisdictions are reshaping vendor selection criteria.
United States
Federal workforce modernization initiatives and defense sector training mandates sustain large-scale platform procurement. OSHA hazard communication standards drive manufacturing adoption of scenario-based micro-modules for safety-critical refresher training. Pharmaceutical clusters in New Jersey and North Carolina demand FDA 21 CFR Part 11 validated systems for compliant training records.
Germany
Automotive and industrial machinery manufacturers require auditable training paths for quality management certification. KBA audit expectations and EU AI Act documentation burdens reshape procurement toward timestamped, immutable learning records. Munich and Stuttgart industrial corridors are deploying blockchain-anchored credentialing layers for regulatory compliance.
India
PLI scheme manufacturing expansion and BIS certification requirements are creating demand for localized, low-bandwidth micro-learning deployment. Frontline worker enablement in automotive and electronics assembly plants accelerates mobile-first adoption. Tamil Nadu and Gujarat manufacturing clusters are piloting compressed video modules for plant-floor training.
France
CNIL audit expectations and GDPR documentation requirements favor multi-tenant cloud configurations with EU data residency. Banking and insurance regulators now mandate explainable training paths for employees interacting with automated decision systems. Paris financial services firms are procuring gamified compliance modules with auditable engagement metrics.
United Kingdom
Financial services compliance teams are piloting adaptive learning algorithms to compress time-to-competency for regulatory certification. Extended enterprise deployments for multinational manufacturers favor modular architectures that reduce partner onboarding cycles. London-based fintech clusters are driving demand for API-first platforms that integrate with legacy LMS infrastructure.
Global Micro-Learning Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors integrate AI authoring tools and blockchain credentialing layers. The vendor base clusters around three archetypes: cloud-native platforms with elastic scaling, mobile-first specialists targeting frontline enablement, and compliance-focused providers with audit-grade documentation. Consolidation pressures intensify as procurement cycles compress and chief learning officers prioritize pilot-to-scale velocity. M&A activity and API ecosystem expansion represent the primary competitive vectors.
Within the mobile-first specialist tier, Axonify and Zydii exemplify gamification-centric positioning for distributed workforce segments. Among cloud-native incumbents, Docebo occupies a position anchoring extended enterprise use cases for multinational manufacturers. 360Learning sits within the collaborative authoring archetype, reducing content production cycles through peer-generated module development. These three vendors represent distinct strategic postures without implying specific market share or revenue claims.
| Leading Market Players |
|---|
| OttoLearn |
| 360Learning |
| Axonify |
| Thinkific |
| LearnUpon |
| CYPHER Learning |
| The Leap |
| Zydii |
| Docebo |
| Others |
Supply & Pricing Matrix
EU AI Act algorithmic accountability mandates gate qualified supply and premium-tier pricing access, as vendors must demonstrate immutable audit trails before financial services procurement teams authorize enterprise contracts. Cloud infrastructure hyperscalers in Ireland and Germany now require carbon disclosure certifications that filter vendor eligibility and compress margin structures for non-compliant platforms.
Pricing Analysis
Direct-to-enterprise SaaS subscriptions with volume-tiered discounts dominate procurement, though channel partner margins for systems integrators add fifteen to twenty-five points for implementation-heavy deployments. Pricing stratifies across audit-grade compliance tiers, mobile-first frontline configurations, and basic web-delivered modules. Cost compression in video production and AI authoring tools is intensifying because automated content pipelines reduce per-module development overhead. Mid-market manufacturers exhibit highest price sensitivity, while European banking procurement teams prioritize documentation integrity over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for multinational manufacturers seeking compressed partner certification cycles. Content production concentrates in the United States, India, and Ireland, with instructional design talent clustering in Boston, Bangalore, and Dublin technology corridors. Platform delivery draws from AWS, Azure, and Google Cloud infrastructure, with EU data residency requirements tethering European deployments to Frankfurt and Dublin availability zones. Single-source vulnerability in hyperscaler concentration creates geographic dependency for latency-sensitive mobile delivery. Distribution runs through value-added resellers and direct sales teams with vertical specialization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Micro-Learning Market functions as a regulatory compounder, with EU AI Act documentation burdens and FDA 21 CFR Part 11 mandates creating non-discretionary procurement cycles that insulate qualified vendors from budget volatility.
For Market Incumbents: Anticipate margin compression from AI-native authoring startups by accelerating blockchain credentialing layer deployment and securing exclusive partnerships with hyperscaler EU data residency zones. Defensive consolidation through boutique instructional design consultancy acquisition addresses talent scarcity in spaced repetition optimization. Certification investment in FDA-validated record systems protects pharmaceutical manufacturing accounts from compliance-focused challengers. For New Entrants and Emerging Players: Systems integrators with vertical expertise in financial services compliance represent the most accessible channel partner type for platform-agnostic deployment. White-space concentration in Indian PLI scheme manufacturing clusters and German automotive supplier networks offers penetrable entry points. Go-to-market positioning should emphasize low-bandwidth mobile delivery with offline synchronization capabilities for frontline worker segments underserved by incumbent cloud-native architectures. For Investors and Strategic Acquirers: Roll-up economics work for compliance-focused micro-learning specialists because regulatory fragmentation across GDPR, EU AI Act, and FDA jurisdictions prevents single-vendor dominance and sustains niche premium pricing. Target acquisition archetypes include mobile-first frontline enablement platforms with validated OSHA content libraries and boutique instructional design firms with cognitive load optimization expertise. Watch for hyperscaler carbon disclosure mandates tightening as the inflection indicator for vendor eligibility compression.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Credentialing Layer Deployment | EBA supervisory expectations in German and French banking now require immutable training path documentation for algorithmic accountability. |
| AI-Native Content Authoring Pipeline | Automated scenario scripting and video compression reduce production cycles for OSHA hazard communication refresher modules in US manufacturing. |
| EU Data Residency Certification | CNIL audit expectations mandate multi-tenant cloud configurations with localized infrastructure in Frankfurt and Dublin availability zones. |
| Frontline Mobile-First Expansion | Indian PLI scheme manufacturing clusters in Tamil Nadu and Gujarat demand low-bandwidth delivery for plant-floor worker enablement. |
| Instructional Design Consultancy Acquisition | Spaced repetition science expertise concentrated in Boston and Bangalore boutiques addresses talent scarcity in cognitive load optimization. |
Research Methodology
Bottom-up enterprise procurement modeling reconciled against top-down platform deployment tracking forms the analytical core of this study. Primary interviews with chief learning officers, compliance training directors, LMS procurement managers, and instructional design consultants were validated against secondary sources including SEC SaaS vendor filings, EU regulatory implementation guidance documents, and federal workforce modernization procurement databases. Triangulation across stakeholder perspectives and documentary evidence ensures segment-level accuracy.
Historical trendline analysis of corporate learning budget allocations and compliance training expenditure patterns informed projection modeling across the analysis window. Segmentation dimensions include deployment architecture, solution modality, regulatory use case intensity, and end-user industry regulatory density. CAGRs were derived from weighted scenario analysis incorporating federal procurement velocity, EU mandate implementation timelines, and manufacturing sector PLI scheme expansion trajectories. AI authoring adoption curves and mobile-first penetration rates served as industry-specific forecast inputs.
Revisions become necessary when hyperscaler carbon disclosure mandates tighten, FDA validation timelines extend, or EU AI Act enforcement priorities shift toward specific algorithmic decision system categories. Forecasts reflect assumptions about sustained federal workforce modernization appropriations and continued manufacturing reshoring incentives. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
Artificial Intelligence (AI) in Education Market
Educational Technology (EdTech)
North America Digital Education Market
Educational Technology (EdTech)
Asia Big Data Analytics in Education Market
Educational Technology (EdTech)
AI in K-12 Education Market
Educational Technology (EdTech)
Education Technology Market
Educational Technology (EdTech)
Blockchain in Edutech Market
Educational Technology (EdTech)
Micro Learning Platform Market
Educational Technology (EdTech)
Asia-Pacific Digital Education Market
Educational Technology (EdTech)
Global Smart Classroom Market
Educational Technology (EdTech)
Global K-12 Software Market
Educational Technology (EdTech)
Student Response System Market
Educational Technology (EdTech)
SETM Education Market
Educational Technology (EdTech)
Education Technology and Smart Classrooms Market
Educational Technology (EdTech)
Global AI in Education Market
Educational Technology (EdTech)
Smart Education System Market
Educational Technology (EdTech)
Virtual Schools Market