
 Global Aerospace and Defense Elastomers Market | 2026-2036
Global Aerospace and Defense Elastomers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aerospace and Defense Elastomers Market Intelligence
The performance gap between specialty, high-temperature fluoroelastomers and general-purpose silicone elastomers is broadening, creating distinct value tiers. Trelleborg leverages its deep expertise in complex sealing systems for mission-critical applications. Solvay differentiates through its portfolio of advanced polymers for extreme temperature and chemical environments. Dow focuses on scalable production of silicone-based solutions for a wider range of aircraft components.
Aerospace and defense elastomers are synthetic polymers engineered for high elasticity and resilience under severe operational conditions, including extreme temperatures and chemical exposure. These materials, characterized by properties like low compression set, provide reliable sealing, dampening, and insulation in critical systems. Fluoroelastomers command a premium within the material type segment due to superior performance in high-temperature applications. Sealing systems remain the dominant application, driven by strict safety and reliability mandates in aircraft manufacturing.
Material qualification is governed by stringent aerospace certifications, including standards from the FAA in the United States and EASA in Europe. Concurrently, chemical regulations such as the EU's REACH framework restrict the use of certain substances, influencing material formulation and supply chain choices. Future material innovation must reconcile the demand for higher performance with an increasingly fragmented and stringent global regulatory environment.
Market Dynamics
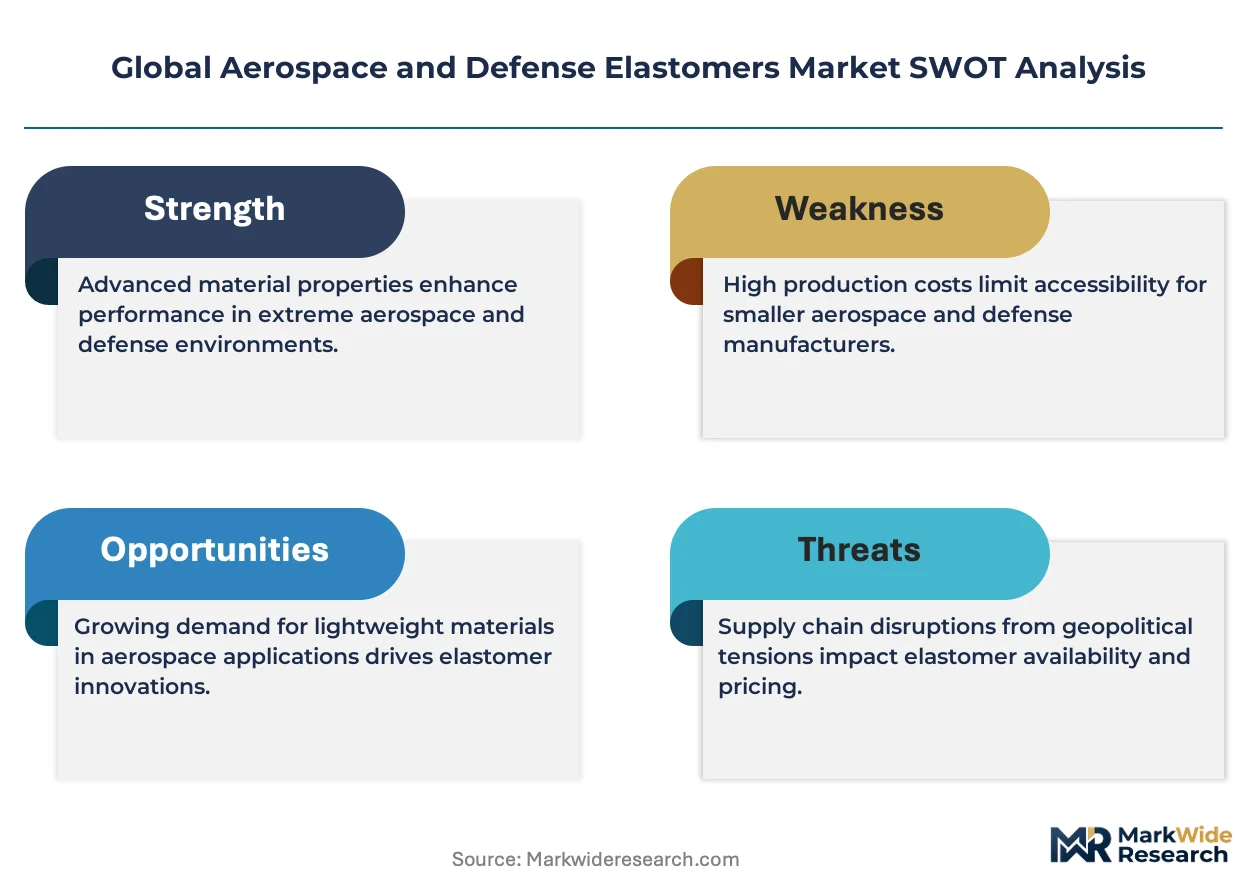
Demand from space exploration for materials with extreme temperature resilience is the central force. This is counterbalanced by chemical restrictions, like the EU's REACH framework, which limits fluoroelastomer formulation options.
Growth Catalysts
- India's Domestic Manufacturing Push:India's PLI scheme and defense indigenization policies create concentrated demand for elastomers in locally produced aircraft and missile systems.
- Advanced Fluoroelastomer Development:New fluoroelastomer compounds withstand extreme temperatures in rocket engines, enabling more ambitious space missions.
- Commercial Space Sector Expansion:Private space firms require high-performance sealing solutions, expanding the market beyond traditional government and military applications.
Market Restraints
- Fluoro-Chemical Input Volatility:The price of raw materials like fluorspar is subject to supply disruptions, impacting cost stability for fluoroelastomer production.
- Stringent Qualification Cycles:Material approval from the FAA and EASA is a multi-year, high-cost process, slowing the introduction of new elastomer formulations.
- Competition from Non-Elastomeric Seals:In some applications, advanced metallic or ceramic seals present a substitution threat where extreme elasticity is not required.
Strategic Opportunities
- Unmanned Aerial Systems:UAV proliferation for military and commercial use creates a new volume market for lightweight, vibration-dampening elastomers.
- Additive Manufacturing of Seals:3D printing of custom elastomer seals enables rapid prototyping and on-demand production of complex replacement parts.
- Brazil's Aerospace Ecosystem:Brazil's expanding aviation sector is an underpenetrated market, offering growth beyond traditional North American and European hubs.
Industry Challenges
- Polymer Science Talent Scarcity:A shortage of material scientists with expertise in high-performance polymer formulation hinders new product development and qualification.
- Regulatory Fragmentation:Managing divergent chemical regulations like the EU's REACH and US EPA rules creates significant compliance overhead and supply chain complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aerospace and Defense Elastomers Market |
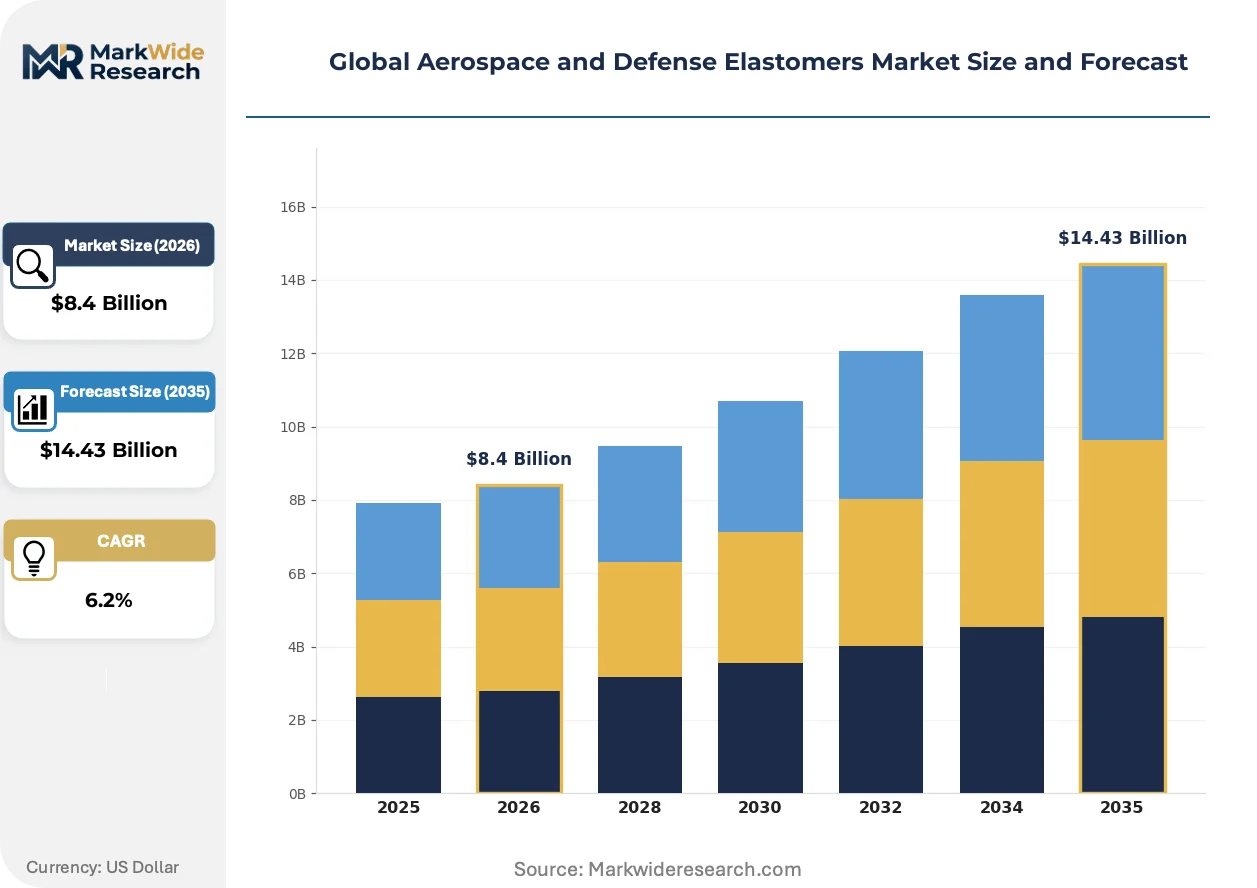
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Fluoroelastomers, Silicone Elastomers, Hydrogenated Nitrile, Polyurethane Elastomers, Ethylene Propylene Diene Monomer Application: Sealing Systems, Vibration Dampening, Fuel System Components, Thermal Insulation, Protective Coatings End User: Aircraft Manufacturers, Defense Contractors, Maintenance Facilities, Government Agencies, Space Exploration Firms Deployment Type: Original Equipment Manufacturing, Aftermarket Repair, Integrated Supply Services, Licensed Production |
| Companies Covered | Trelleborg, Dow, Shin-Etsu Chemical Co., Ltd., The Chemours Company, 3M, Saint-Gobain Performance Plastics, Solvay, LANXESS, Momentive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aerospace and Defense Elastomers Market Strategic Shifts & Innovations
A fundamental shift toward aircraft electrification and sustainable aviation fuels is setting new performance criteria for elastomeric components. Material innovation now centers on compatibility with new energy systems and compliance with stricter environmental regulations.
Self-healing elastomers contain microcapsules that release a healing agent to repair damage, extending the service life of seals. Aerospace OEMs are evaluating these for non-critical components to reduce maintenance cycles. This pursuit of autonomous repair is electrifying the approach to component lifecycle management, shifting value from replacement to operational integrity.
The European Union's REACH regulation continues to restrict per- and polyfluoroalkyl substances (PFAS) used in some fluoroelastomer production. This regulatory pressure is forcing a reformulation of legacy materials and driving investment into compliant high-performance polymer alternatives. The sealing systems segment is most affected, with manufacturers redesigning products to ensure continued market access in Europe.
Airframe manufacturers increasingly outsource the entire sealing system design, qualification, and certification to specialist elastomer suppliers. This model displaces transactional component sales, favoring suppliers who act as integrated engineering partners from the initial design phase. The shift is most visible in next-generation commercial aircraft development within the United States and Europe.
Global Aerospace and Defense Elastomers Market Segmentation
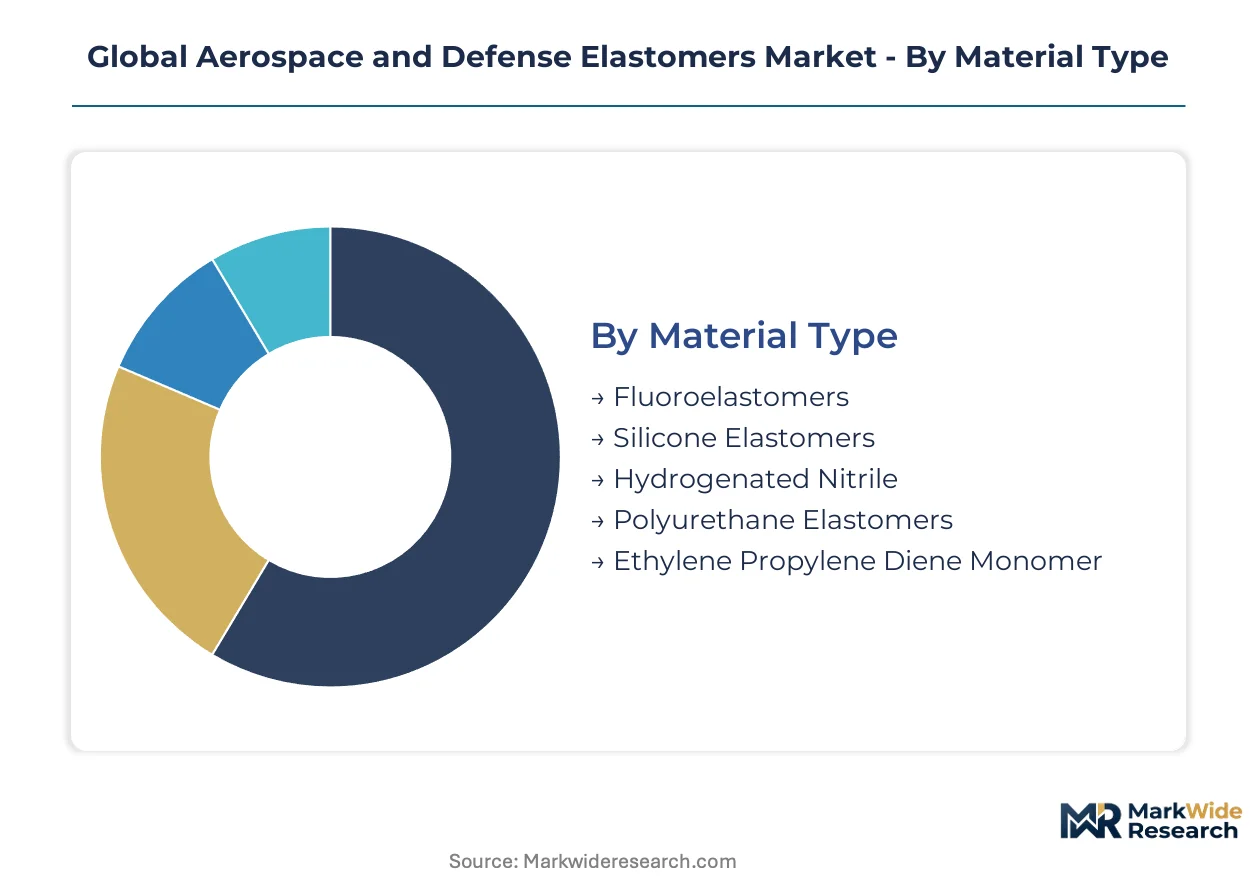
The aerospace and defense elastomers market segments by material type, application, end user, and deployment model. Understanding these distinct categories clarifies where specialized material properties and regulatory compliance drive market value. Each segment reflects unique operational demands and certification pathways for high-performance polymer solutions.
Material Type:
Material qualification standards from the FAA and EASA heavily influence the viability of elastomer compounds within this segment. Chemical regulations like the EU's REACH framework further restrict material formulation options for producers.
- Fluoroelastomers:These synthetic polymers offer exceptional resistance to extreme temperatures, fuels, and harsh chemicals, making them essential for critical sealing and gasketing in jet engines and rocket propulsion systems. Demand concentrates within the commercial space sector due to the need for materials that endure high-thrust environments.
- Silicone Elastomers:Known for their flexibility across a broad temperature range and good electrical insulation properties, silicone elastomers find widespread use in aircraft interiors, wire insulation, and general-purpose seals. The scalability of production for these materials supports their application in a wider array of aircraft components.
- Hydrogenated Nitrile:This material provides superior abrasion and chemical resistance, particularly against oils and fuels, suitable for hydraulic systems and fuel lines.
- Polyurethane Elastomers:Valued for high tensile strength and tear resistance, these elastomers are used in protective coatings and abrasion-resistant parts.
- Ethylene Propylene Diene Monomer:EPDM offers excellent resistance to ozone, weather, and steam, often employed in exterior seals and non-fuel-contact applications.
Leading the category by volume: Silicone Elastomers. Growing fastest: Fluoroelastomers.
Application:
The cost structure for elastomer applications reflects the criticality and bespoke engineering required for each functional area. Complex sealing systems often command higher prices due to stringent performance requirements and custom geometries.
- Sealing Systems:This dominant application segment relies on elastomers to prevent leaks of fluids and gases, maintain pressure, and exclude contaminants in engines, hydraulic systems, and airframes. Strict safety and reliability mandates in aircraft manufacturing drive continuous innovation in sealing material performance.
- Vibration Dampening:Elastomers absorb mechanical energy and reduce structural fatigue, protecting sensitive avionics and crew from excessive vibration in both fixed-wing aircraft and rotary systems. Lightweight, high-performance dampening solutions are critical for unmanned aerial systems.
- Fuel System Components:Elastomers in fuel systems must resist degradation from various aviation fuels and maintain integrity across temperature extremes.
- Thermal Insulation:These materials provide thermal barriers, protecting sensitive components from high temperatures generated by engines or atmospheric re-entry.
- Protective Coatings:Elastomeric coatings shield surfaces from corrosion, abrasion, and environmental damage, extending the lifespan of structural elements.
Sealing Systems hold the largest share of demand, while Vibration Dampening applications are expanding most quickly.
End User:
Customer type defines procurement patterns and the scale of required elastomer solutions, ranging from high-volume airframe production to specialized space vehicle components. Each end user segment has distinct supply chain requirements.
- Space Exploration Firms:These entities demand elastomers capable of withstanding extreme thermal cycling, radiation, and vacuum conditions in rocket engines and spacecraft. The commercial space sector's expansion is a central force driving demand for highly specialized, high-performance elastomer solutions.
- Aircraft Manufacturers:This segment represents the largest volume consumer, requiring elastomers for a vast array of components across commercial and military aircraft. Outsourcing of entire sealing system design to specialist elastomer suppliers is prevalent in next-generation commercial aircraft development.
- Defense Contractors:These firms integrate elastomers into military aircraft, missile systems, and ground support equipment, often requiring materials compliant with defense specifications.
- Maintenance Facilities:Elastomers are critical for repair and overhaul operations, with demand concentrating on aftermarket parts that meet original equipment specifications.
- Government Agencies:Various government bodies procure elastomers for specialized applications in research, test programs, and non-commercial aerospace platforms.
Aircraft Manufacturers represent the largest end-user segment by volume, with Space Exploration Firms exhibiting the steepest expansion trajectory.
Deployment Type:
The maturity of deployment models influences pricing power and supply chain integration within the elastomer market. Established OEM channels contrast with the evolving landscape of integrated supply services.
- Original Equipment Manufacturing:This segment involves the supply of elastomers for new aircraft and spacecraft production, characterized by long qualification cycles and high-volume contracts. Suppliers often act as integrated engineering partners from the initial design phase.
- Aftermarket Repair:Elastomers for replacement parts and maintenance, repair, and overhaul (MRO) operations constitute this segment, focusing on availability and certification for legacy systems. This segment is evaluating self-healing elastomers to reduce maintenance cycles for non-critical components.
- Integrated Supply Services:Providers manage the entire supply chain for elastomer components, from procurement to inventory management, for major aerospace clients.
- Licensed Production:This involves the manufacturing of elastomer components under license, often for domestic defense initiatives or regional aircraft programs.
Original Equipment Manufacturing holds the primary share of market value, while Aftermarket Repair is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Florida's Space Coast, a hub for rocket launches and aerospace innovation, drives significant demand for high-performance elastomers in propulsion systems. This region, alongside other global aerospace clusters, requires materials with extreme temperature resilience for both commercial and defense applications.
United States
Commercial space sector expansion and next-generation aircraft development create substantial demand for advanced elastomers in the United States. FAA certifications govern material qualification for new aircraft components, ensuring stringent safety standards. The aerospace cluster in Seattle, home to major airframe manufacturers, continuously seeks innovative sealing and dampening solutions.
France
European commercial aircraft programs and defense initiatives underpin the demand for specialized elastomers in France. EASA certifications are critical for market access, influencing material formulation and qualification pathways. Toulouse, a primary center for European aerospace manufacturing, sees consistent demand for high-performance sealing systems.
India
India's domestic defense manufacturing push, supported by the PLI scheme, generates concentrated demand for elastomers in locally produced aircraft and missile systems. Defense indigenization policies prioritize materials sourced or manufactured within the country. Bangalore's aerospace and defense industrial complex serves as a key hub for elastomer procurement and application.
Germany
Germany's robust aerospace industry and participation in European defense projects require a steady supply of high-performance elastomers. Stringent EASA regulations dictate the use of certified materials across the aviation sector. Hamburg, with its significant aircraft manufacturing presence, is a focal point for elastomer suppliers.
Japan
Domestic aerospace programs and defense modernization efforts contribute to the demand for advanced elastomers in Japan. METI oversight ensures compliance with national industrial standards for material quality and performance. Nagoya, a central region for Japan's aerospace component manufacturing, requires specialized elastomers for various applications.
Global Aerospace and Defense Elastomers Market Key Industry Players
Premium-margin players sit above commodity-margin players across the specialty elastomer value chain, differentiated by material science expertise and application-specific engineering. The market exhibits a tiered structure, with a few large integrated chemical companies alongside numerous specialized elastomer fabricators. Strategic partnerships for material development and targeted acquisitions of niche technology firms represent dominant competitive moves.
On the premium-tier vector, Trelleborg exemplifies expertise in complex sealing systems for mission-critical applications, leveraging deep engineering capabilities. Solvay occupies a position anchored by its advanced polymer portfolio, catering to extreme temperature and chemical environments within aerospace and defense. Dow, with its scalable production of silicone-based solutions, represents a broader segment of the market, serving a wider array of aircraft components.
| Leading Market Players |
|---|
| Trelleborg |
| Dow |
| Shin-Etsu Chemical Co., Ltd. |
| The Chemours Company |
| 3M |
| Saint-Gobain Performance Plastics |
| Solvay |
| LANXESS |
| Momentive |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps in specialty elastomer fabrication often dictate supply behavior and exert pricing discipline through deep application expertise. Their specialized production capabilities allow for premium pricing in mission-critical aerospace and defense applications.
Pricing Analysis
Outcome-based pricing anchors the value of high-performance elastomers, with costs directly tied to component uptime and system reliability in extreme conditions. Price differentiation stems from stringent material certification levels, such as FAA and EASA standards, and the degree of customization required for specific sealing systems. Pricing softness affects general-purpose silicone elastomers due to scalable production, while fluoroelastomers maintain premium pricing. Space exploration firms exhibit the least price sensitivity, prioritizing performance, whereas maintenance facilities are more cost-conscious for aftermarket parts.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke networks facilitate the timely delivery of elastomers to aerospace manufacturing clusters in the United States and Europe. Geographic supply concentration for key raw materials like fluorspar is significant in China, impacting global fluoroelastomer production. The supply chain draws from specialized monomers and silicone precursors primarily from advanced chemical manufacturing hubs. Commodity price volatility for fluorspar represents a structural risk, and direct OEM supply with specialized distributors forms the dominant downstream model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aerospace and defense elastomers market is fundamentally a cost-of-compliance story, where stringent regulations like the EU's REACH framework create a significant barrier-to-entry moat for established, compliant players.
For Market Incumbents: Hedge against raw material price volatility by securing long-term supply contracts for critical inputs like fluorspar. Deepen vertical integration into specialized monomer production to control formulation and secure intellectual property against emerging substitute technologies. Invest in advanced material science R&D to develop compliant high-performance polymer alternatives, maintaining market leadership in sealing systems.
For New Entrants and Emerging Players: Digital engineering platforms offer a direct channel for new entrants to showcase rapid prototyping capabilities for additive manufacturing of seals. Target the unmanned aerial systems segment, which requires lightweight, vibration-dampening elastomers for new volume applications. A go-to-market angle focused on accelerated material qualification for non-critical components can gain initial traction.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized elastomer fabricators with proprietary material formulations in Europe, driven by REACH-related reformulation costs. The long-term viability of this market hinges on sustained demand from commercial space expansion and defense modernization efforts. An acquisition target archetype includes niche technology firms specializing in self-healing elastomers or advanced fluoroelastomer compounds. Watch for increased M&A activity among mid-sized specialty chemical companies as a signal of market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Material R&D | Developing compliant high-performance polymer alternatives drives market leadership for Trelleborg. |
| Supply Chain Diversification | Reducing reliance on single-source raw materials mitigates fluorspar price volatility for Dow. |
| Certification Process Streamlining | Accelerating new product introduction is critical for Solvay's advanced polymer portfolio. |
| Integrated Engineering Partnerships | Embedding with aircraft manufacturers secures long-term contracts for specialist elastomer suppliers. |
| Additive Manufacturing Investment | Custom seals via 3D printing enables rapid prototyping for aerospace OEMs. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing foundational market sizing and trend analysis. Primary interviews with R&D directors, procurement leads at aircraft manufacturers, material scientists, and certification specialists validated these findings. This approach combined bottom-up market sizing with top-down validation, ensuring comprehensive data triangulation. Secondary sources included FAA and EASA reports, company 10-K filings, and specialized aerospace industry association publications.
Data-stream reconciliation integrated historical market performance with future growth projections across the analysis window. The analytical framework modeled segmentation dimensions including material type, application, end user, deployment model, and required temperature resilience. Compound annual growth rates were derived by projecting demand drivers such as aircraft delivery schedules and commercial space mission projections. Industry-specific forecast inputs included defense spending allocations and material qualification timelines.
Inputs from publicly available financial reports and regulatory databases were available through the study window; gaps in emerging technology adoption rates introduce uncertainty bands. Forecasts reflect assumptions regarding global economic stability and continued aerospace investment. Regulatory changes like new PFAS restrictions or unforeseen raw material supply disruptions represent specific risk factors. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Commercial Aerospace 3D Printing Market
Aerospace and Aircraft Materials
Aerospace Ceramic Matrix Composites Market
Aerospace and Aircraft Materials
Commercial Aircraft Honeycomb Core Market
Aerospace and Aircraft Materials
Aerospace Lightweight Materials Market
Aerospace and Aircraft Materials
Aerographene Market
Aerospace and Aircraft Materials
Aerospace and Defense Composites Market
Aerospace and Aircraft Materials
Aerogel Blanket Market
Aerospace and Aircraft Materials
Fiberglass for Aerospace Market
Aerospace and Aircraft Materials
Ablative Coatings Market
Aerospace and Aircraft Materials
Aviation Coatings Market
Aerospace and Aircraft Materials
Space Electronics Market
Aerospace and Aircraft Materials
Out-of-Autoclave Composite Skin Panels for Regional and Business Jets Market
Aerospace and Aircraft Materials
Global AFP/ATL Machines Market
Aerospace and Aircraft Materials
Magnesium Beryllium Alloy Market
Aerospace and Aircraft Materials
Aircraft Insulation Materials Market
Aerospace and Aircraft Materials
Global Military Aerospace Coatings Market