
 Global Aerospace Pressure Gauge Market | 2026-2036
Global Aerospace Pressure Gauge Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aerospace Pressure Gauge Market Foresight
EU MDR-equivalent aerospace instrument standards is restructuring certification pathways for pressure gauge manufacturers serving European OEMs. Honeywell International Inc. leverages its vertical integration across avionics and sensor platforms to sustain long-term supply agreements with Boeing and Airbus. AMETEK Inc. anchors its position through specialized test and calibration equipment that supports gauge verification protocols. CIRCOR Aerospace competes in niche military and space applications where diaphragm and capsule gauge architectures dominate.
An aerospace pressure gauge measures fluid or gas pressure within aircraft, spacecraft, and unmanned systems, typically employing Bourdon tube, diaphragm, or capsule sensing elements constructed from stainless steel, Inconel, or titanium alloys to withstand extreme temperature cycles, vibration, and altitude-induced pressure differentials. Digital and MEMS technology segments are capturing expanded share as fly-by-wire architectures and integrated health monitoring systems displace legacy mechanical indicators in next-generation platforms. Aircraft Systems and Engine Monitoring applications concentrate the largest procurement volumes, while UAVs represent the fastest-expanding addressable segment as military and commercial drone fleets scale.
FAA Part 25, EASA CS-25, and ISO 9100 quality frameworks govern design verification, production traceability, and field performance documentation for aerospace pressure instruments. EASA's tightening CS-STAN standards for small aircraft instruments and the FAA's ongoing airworthiness directive updates are elevating compliance costs while simultaneously consolidating procurement toward certified Tier-1 suppliers. Stakeholders must monitor evolving dual-use export control classifications and emerging spaceflight participant safety standards that could extend gauge certification requirements beyond traditional commercial and defense aviation boundaries.
Market Dynamics
Digital MEMS pressure sensing architectures are compressing the traditional mechanical gauge supply base, while FAA Part 25 and EASA CS-25 calibration mandates simultaneously elevate compliance barriers for uncertified producers.
Growth Catalysts
- Fleet Modernization:Commercial airlines in the United States and Germany are accelerating replacement cycles for legacy mechanical instruments with digital pressure monitoring systems.
- UAV Proliferation:Military and commercial drone fleets are scaling precision instrument requirements for flight control and engine monitoring applications.
- CS-25 Standards:EASA's updated airworthiness directives are mandating enhanced traceability documentation for flight-critical pressure instruments across European OEM supply chains.
Market Restraints
- Titanium Alloy Volatility:Input cost swings for aerospace-grade sensing element materials compress margin predictability for gauge manufacturers.
- Toulouse Cluster Concentration:Airbus supplier network dominance in France creates single-source dependency risks for precision instrument procurement.
- Mechanical Gauge Substitution:Analog Bourdon tube architectures face displacement by solid-state MEMS alternatives in next-generation fly-by-wire platforms.
Strategic Opportunities
- Spaceflight Participant Safety:Emerging FAA commercial space regulations are extending pressure instrument certification requirements beyond traditional aviation boundaries.
- India Defense Procurement:Indigenous aerospace manufacturing incentives under the country's PLI scheme are opening localized gauge supply opportunities.
- Digital-Mechanical Convergence:Hybrid sensing platforms combining MEMS precision with mechanical redundancy are capturing retrofit demand from aging regional aircraft fleets.
Industry Challenges
- Calibration Technician Scarcity:Specialized metrology expertise for FAA Part 25 traceability documentation is concentrating among a shrinking pool of qualified personnel.
- Dual-Use Export Classification:Reclassification of precision pressure instruments under tightened military end-use controls is complicating cross-border supply chain planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aerospace Pressure Gauge Market |
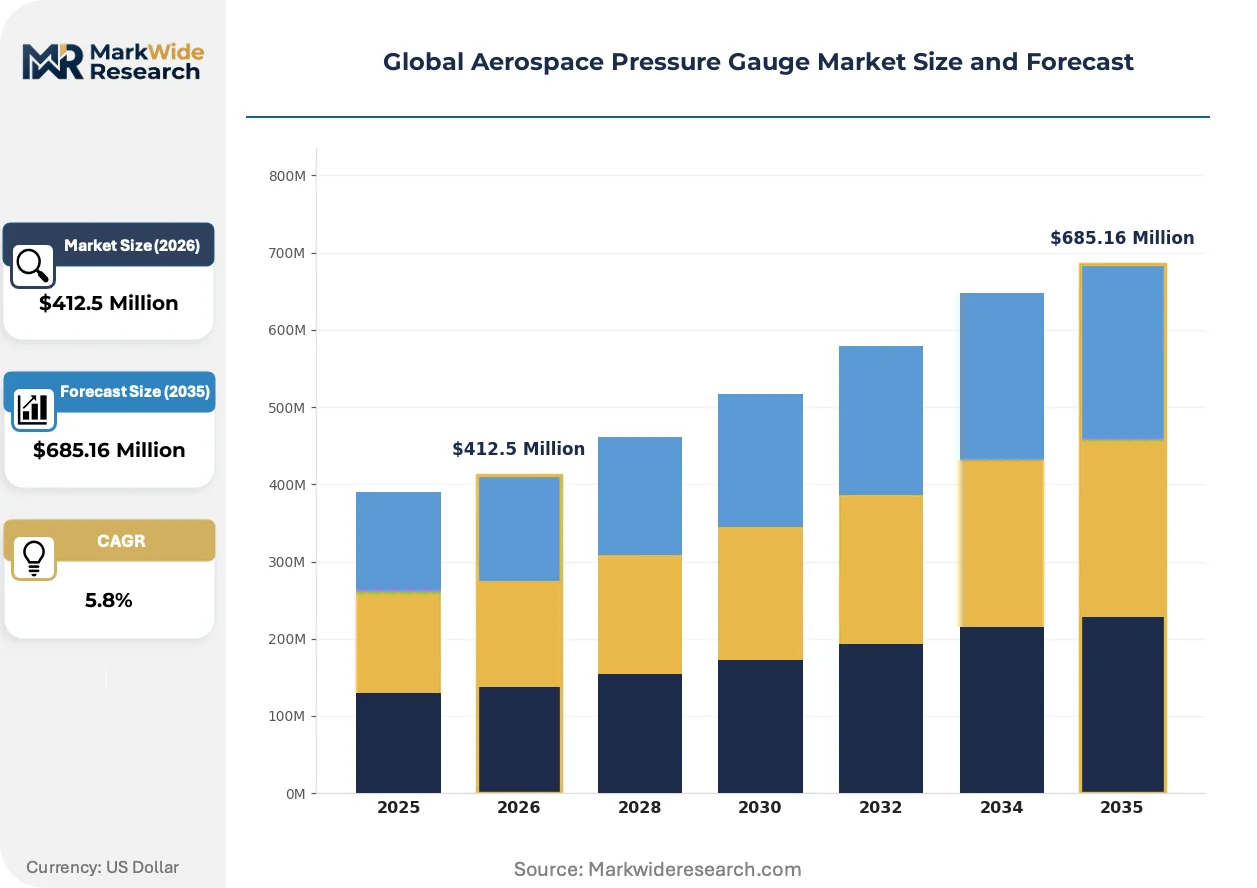
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Filled, Dry, Digital, Capsule, Bourdon Tube, Diaphragm Technology: Mechanical, Piezoelectric, Capacitive, Optical, MEMS, Resonant Application: Aircraft Systems, Spacecraft, UAVs, Helicopter Controls, Engine Monitoring, Environmental Control End User: OEMs, MRO Providers, Defense Contractors, Commercial Airlines, Research Institutes, Component Suppliers |
| Companies Covered | Honeywell International Inc., AMETEK Inc., TE Connectivity plc, CIRCOR Aerospace, WIKA Alexander Wiegand SE & Co. KG, UMA, Inc., Ahlers Aerospace, Inc., Parker Hannifin Corporation, SUCO ESI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aerospace Pressure Gauge Market Shifts & Advancements
MEMS-based pressure transduction is compressing the traditional divide between mechanical reliability and digital precision, forcing incumbents to rearchitect sensing platforms around integrated health monitoring compatibility.
Silicon carbide MEMS pressure sensors are unifying high-temperature survivability with digital output protocols for engine monitoring applications. Turbofan OEMs are adopting these platforms for real-time bleed air and fuel system pressure telemetry. This convergence is unifying previously separate mechanical gauge and electronic control unit supply chains into single-source digital instrument contracts.
EASA's CS-STAN standards for small aircraft instruments are tightening design verification requirements for diaphragm and capsule gauge architectures. Manufacturers serving European general aviation must now submit expanded fatigue testing documentation. French and German ultralight aircraft producers are responding by consolidating procurement toward ISO 9100-certified Tier-1 suppliers with established EASA technical standard order approvals.
Airlines are unbundling pressure gauge calibration services from original equipment purchase agreements, shifting toward third-party metrology providers with FAA-approved repair station credentials. Maintenance, repair, and overhaul facilities in the United States are capturing this disaggregated spend through dedicated instrument shops. This restructuring is most visible among US-based low-cost carriers operating mixed fleets of Boeing and Airbus narrow-body aircraft with divergent gauge specifications.
Global Aerospace Pressure Gauge Market Segmentation
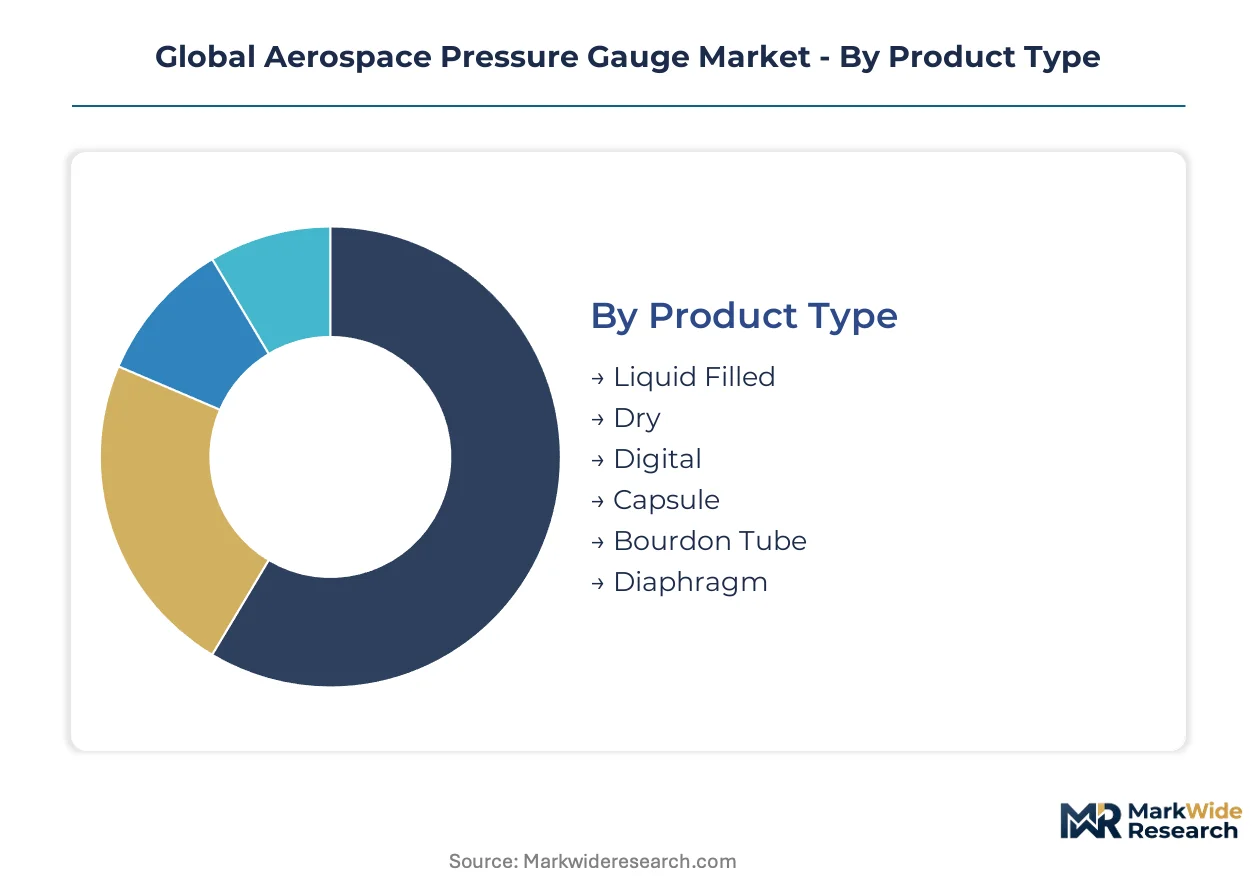
Aerospace pressure gauge procurement fractures across certification tiers, sensing technologies, and platform architectures. Each segment carries distinct FAA Part 25 or EASA CS-25 approval burdens that determine supplier eligibility and pricing power.
Product Type:
FAA Part 25 mandates liquid-filled and digital gauges for flight-critical applications, while dry mechanical types face tightening airworthiness restrictions.
- Liquid Filled:Glycerin or silicone-damped Bourdon tube assemblies suppress pointer vibration in high-turbulence environments. Commercial airlines in the United States specify these for hydraulic and fuel system monitoring where FAA vibration resistance standards apply.
- Digital:Solid-state transducers with ARINC 429 or MIL-STD-1553 output protocols integrate directly into fly-by-wire architectures. Airbus procurement from France's Toulouse cluster concentrates here as A350 and A320neo production scales.
- Dry:Undamped mechanical indicators serve ground support equipment and non-flight-critical cabin systems. Cost-sensitive regional operators in India favor these for auxiliary pressure monitoring.
- Capsule:Thin-walled metallic bellows assemblies measure low-pressure differentials in altitude sensing and cabin pressurization loops. EASA CS-STAN documentation requirements now govern European general aviation adoption.
- Bourdon Tube:C-shaped or spiral-wound elastic elements remain the mechanical default for engine bleed air and pneumatic systems. Legacy Boeing 737 fleets sustain aftermarket demand.
- Diaphragm:Corrugated metallic membranes handle corrosive media and absolute pressure reference applications. SpaceX and Blue Origin procurement for propulsion systems drives specialized diaphragm gauge development.
Leading the category by volume: Bourdon Tube. Growing fastest: Digital.
Technology:
Cost tiers separate legacy mechanical platforms from solid-state alternatives requiring specialized fabrication infrastructure.
- MEMS:Silicon micromachined pressure elements with onboard signal conditioning enable multi-point distributed sensing. UAV flight control systems in Germany and Israel absorb volume as drone swarm architectures proliferate.
- Mechanical:Purely elastic deformation sensing without electrical components satisfies fail-safe requirements for primary flight instruments. Aging regional aircraft fleets in the United States sustain retrofit demand.
- Piezoelectric:Quartz crystal transducers deliver microsecond response times for transient pressure capture in wind tunnel and flight test applications. NASA and DLR procurement concentrates in high-value instrumentation.
- Capacitive:Variable-gap electrode architectures achieve nanometer displacement resolution for precision altimetry. Honeywell and Thales integrate these into integrated air data computers.
- Optical:Fiber Bragg grating and Fabry-Perot interferometric sensors survive electromagnetic pulse environments. Military hardening specifications in the United Kingdom and Australia drive niche adoption.
- Resonant:Silicon resonant beam structures offer frequency-output stability for long-duration spacecraft missions. ESA deep-space probe programs represent concentrated demand.
MEMS commands the premium pricing tier. Mechanical holds the largest installed base.
Application:
Platform maturity and production rates determine volume concentration across aerospace verticals.
- Aircraft Systems:Hydraulic, pneumatic, and fuel pressure monitoring across flight control surfaces, landing gear, and auxiliary power units. Boeing and Airbus narrow-body output rates govern procurement scale.
- Engine Monitoring:Turbofan bleed air, fuel manifold, and oil system pressure telemetry for real-time health management. GE Aerospace and Rolls-Royce specify integrated transducer arrays for next-generation propulsion.
- UAVs:Miniaturized pressure sensing for altitude hold, airspeed measurement, and engine control in military and commercial drone platforms. Turkish Baykar and US General Atomics procurement is expanding fastest.
- Spacecraft:Crewed capsule and satellite propulsion system pressure verification. NASA Commercial Crew and ESA Ariane 6 programs concentrate qualification activity.
- Helicopter Controls:Main and tail rotor hydraulic pressure feedback for fly-by-wire rotorcraft. Leonardo and Sikorsky next-generation platforms drive specification updates.
- Environmental Control:Cabin pressurization and air conditioning system pressure regulation. Post-pandemic fleet reactivation in Germany and Singapore sustains aftermarket demand.
Aircraft Systems generates the highest procurement volume. UAVs are expanding most quickly.
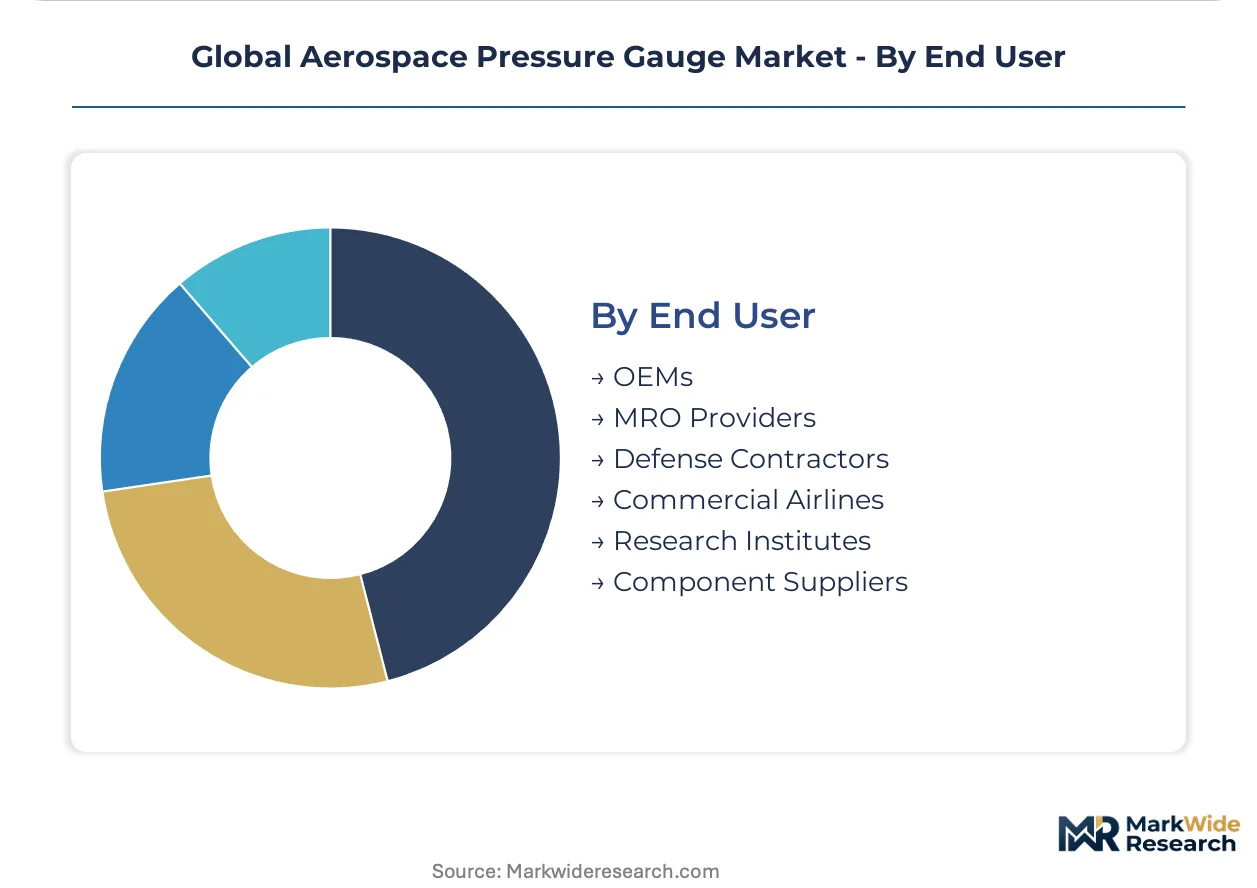
End User:
Customer type dictates contract structure, from long-term OEM supply agreements to spot MRO purchases.
- OEMs:Boeing, Airbus, Lockheed Martin, and BAE Systems negotiate multi-year sole-source contracts with embedded calibration service provisions. Technical standard order approvals lock in supplier relationships.
- MRO Providers:Lufthansa Technik, ST Engineering, and AAR Corp disaggregate gauge overhaul from airframe maintenance. Third-party metrology credentialing determines vendor selection.
- Defense Contractors:Northrop Grumman and Raytheon procurement for military platforms operates under ITAR and EAR export control classifications. Diaphragm and capsule gauges dominate ruggedized applications.
- Commercial Airlines:Delta, Lufthansa, and Singapore Airlines manage mixed-fleet gauge inventories through pooled spare agreements. Digital gauge commonality across Boeing and Airbus reduces holding costs.
- Research Institutes:NASA Glenn, DLR, and ONERA acquire specialized test instrumentation for experimental aerodynamics. Optical and resonant technologies concentrate in this segment.
- Component Suppliers:Parker Hannifin and Eaton Corporation integrate pressure gauges into hydraulic and fuel system modules. Tier-2 sourcing requirements flow down from OEM quality manuals.
OEMs anchor procurement value. MRO Providers are gaining share through fleet aging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's Toulouse aerospace cluster operates as a special economic zone for precision instrument manufacturing, concentrating Airbus procurement and tier-1 supplier networks. German aviation hubs leverage federal R&D tax credits to sustain gauge calibration infrastructure. United States manufacturing zones benefit from FAA repair station density and defense procurement proximity.
United States
Boeing's 737 MAX production ramp and SpaceX commercial crew programs absorb precision pressure instrumentation at scale. FAA Part 25 airworthiness directive updates mandate enhanced traceability documentation for flight-critical gauges. Wichita's aviation manufacturing corridor sustains dense MRO infrastructure supporting aftermarket gauge calibration services.
Germany
Lufthansa Technik's fleet modernization contracts and MTU Aero Engine production lines drive digital gauge procurement volumes. EASA CS-25 standards enforcement tightens certification requirements for instruments entering European OEM supply chains. Munich's aerospace supplier ecosystem concentrates diaphragm gauge manufacturing for engine monitoring applications.
France
Airbus A350 and A320neo output rates govern regional gauge demand cycles across hydraulic and fuel system applications. EU MDR-equivalent aerospace instrument standards restructure certification pathways for pressure gauge manufacturers. Toulouse's aerospace cluster anchors precision instrument procurement through embedded supplier quality agreements.
United Kingdom
Rolls-Royce turbofan development programs and BAE Systems defense platforms sustain specialized gauge requirements. UK Export Finance guarantees support cross-border instrument supply chain financing for Tier-2 manufacturers. Bristol's aerospace engineering corridor hosts test and calibration facilities serving European general aviation producers.
India
Indigenous aerospace manufacturing incentives under the PLI scheme attract gauge suppliers to establish local production. DGFT dual-use export classifications govern precision instrument imports for defense aviation applications. Bangalore's defense and aerospace cluster concentrates UAV pressure sensing system development for military drone programs.
Global Aerospace Pressure Gauge Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across certification tiers, with market structure consolidating toward ISO 9100-approved suppliers capable of spanning OEM and MRO contract types. Tier-1 procurement relationships lock in multi-year supply agreements with embedded calibration provisions, while smaller fabricators capture spot MRO demand. Three archetypes dominate: avionics-integrated conglomerates with captive sensing divisions, specialized test and calibration equipment manufacturers, and niche military-space specialists. Competitive dynamics center on strategic partnerships for fly-by-wire platform integration and geographic expansion into emerging defense procurement markets.
Among diversified technology conglomerates, Honeywell International Inc. and AMETEK Inc. occupy positions spanning avionics integration and specialized test equipment respectively. TE Connectivity plc represents the connectivity-focused archetype with sensor platform breadth. CIRCOR Aerospace sits within the niche military-space specialist tier. Parker Hannifin Corporation anchors the hydraulic systems integrator segment where pressure gauges embed as module components.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| AMETEK Inc. |
| TE Connectivity plc |
| CIRCOR Aerospace |
| WIKA Alexander Wiegand SE & Co. KG |
| UMA, Inc. |
| Ahlers Aerospace, Inc. |
| Parker Hannifin Corporation |
| SUCO ESI |
| Others |
Supply & Pricing Matrix
Titanium alloy price indices cascade through aerospace pressure gauge manufacturing, compressing margins for mechanical gauge producers while amplifying pricing power for MEMS-integrated suppliers with captive material hedging. FAA Part 25 certification tiers stratify procurement costs, with liquid-filled and digital platforms commanding substantial premiums over dry mechanical alternatives.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid fulfillment capabilities, with short-lead-time digital gauge orders extracting 15-25% premiums over standard contractual terms. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified flight-critical instruments from general aviation and ground support equipment. Price differentiation hinges on ISO 9100 certification tier and embedded calibration service bundling. Cost compression in mechanical gauge segments is intensifying because MEMS substitution erodes volume scale. Regional airlines operating mixed Boeing-Airbus fleets exhibit highest price sensitivity, while spaceflight contractors demonstrate lowest sensitivity due to mission-critical reliability requirements.
Supply Chain Analysis
FAA Part 25 and EASA CS-25 qualification gating concentrates qualified supplier pools, with certification documentation requirements filtering uncertified fabricators from OEM procurement channels. Manufacturing gravity centers on the United States, Germany, and France, with Toulouse's aerospace cluster anchoring Airbus-tier supply relationships. Raw material flows draw from aerospace-grade titanium alloy mills in the United States and Japan, silicon carbide wafer foundries in Germany and Israel, and precision Bourdon tube fabricators in Switzerland. Single-source vulnerability pervades EASA technical standard order approvals, where qualified supplier concentration creates procurement bottlenecks. Distribution runs through OEM direct contracts for new production, with MRO facilities and third-party metrology providers capturing aftermarket refurbishment demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained, with FAA-approved repair station density failing to match fleet expansion rates and calibration technician scarcity propping pricing for traceability-compliant instruments.
For Market Incumbents: To counter MEMS-based displacement of mechanical architectures, Honeywell and AMETEK should deepen backward integration into silicon carbide wafer sourcing while expanding captive calibration service networks across Wichita and Munich. Certification investment in emerging spaceflight participant safety standards offers defensive positioning against new entrant qualification. For New Entrants and Emerging Players: Tier-2 component suppliers represent the most penetrable channel partner type for gauge module integration, particularly Parker Hannifin and Eaton Corporation hydraulic system outsourcing programs. White-space targets include India's PLI-scheme aerospace manufacturing zones and UAV flight control system miniaturization programs in Turkey and Israel. A calibration-service-first go-to-market angle bypasses OEM qualification barriers while building FAA repair station credentials. For Investors and Strategic Acquirers: Distressed-cycle entries favor ISO 9100-certified Tier-2 specialists with established EASA technical standard order approvals in Germany and the United Kingdom. Long-term viability over the next decade rests on MEMS-mechanical hybrid platform capabilities and spaceflight certification optionality. The inflection signal to watch is FAA commercial space regulation finalization extending pressure instrument mandates beyond traditional aviation boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS-Mechanical Hybrid Platform Development | Captures retrofit demand from aging regional aircraft fleets while satisfying fly-by-wire redundancy requirements. |
| FAA Repair Station Network Expansion | Positions suppliers for airlines unbundling calibration services from original equipment purchase agreements. |
| Silicon Carbide Wafer Backward Integration | Secures high-temperature sensor supply for GE Aerospace and Rolls-Royce engine monitoring programs. |
| India PLI-Scheme Manufacturing Localization | Unlocks defense procurement contracts under DGFT dual-use export classification frameworks. |
| Spaceflight Participant Safety Certification | Extends addressable market beyond commercial aviation into Blue Origin and SpaceX crewed capsule programs. |
Research Methodology
Multi-period observation of FAA airworthiness directive issuance patterns, EASA CS-25 standard revision timelines, and OEM production rate announcements anchored the trend analysis, supplemented by interviews with avionics procurement directors, MRO facility managers, calibration laboratory technicians, and aerospace quality assurance leads. Secondary validation drew from FAA certification databases, EASA technical standard order registries, SEC 10-K filings from diversified sensor manufacturers, and customs trade data for titanium alloy and precision instrument flows. Bottom-up gauge shipment estimates triangulated against top-down OEM fleet expansion projections.
Input-output matrices mapped sensing technology adoption curves against platform production rates across the projection horizon. Segmentation dimensions modeled encompassed product type, technology architecture, application vertical, and end-user contract structure. CAGRs were synthesized from installed base replacement cycles, fleet modernization program announcements, and UAV proliferation trajectories. Forecast inputs incorporated titanium alloy price volatility assumptions and EASA CS-STAN documentation burden escalation for small aircraft instruments.
Caveats apply where FAA Part 25 airworthiness directive acceleration, EASA export control reclassification, or spaceflight safety standard premature finalization could materially shift the outlook. Forecasts embed assumptions regarding MEMS cost curves and mechanical gauge displacement velocity. A model refresh is warranted upon material change in dual-use export control classifications or commercial space regulatory finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Aircraft Brake Calipers Market
Aircraft and Aerospace Components
Aircraft Insulation Market
Aircraft and Aerospace Components
Low-Noise Landing Gear Fairing Composite Designs Market
Aircraft and Aerospace Components
North America Rotor Blade Market
Aircraft and Aerospace Components
Aircraft Gearbox Market
Aircraft and Aerospace Components
Germany Rotor Blade Market
Aircraft and Aerospace Components
Global Commercial Aircraft Airframe Materials Market
Aircraft and Aerospace Components
Aircraft Nacelle Components Market
Aircraft and Aerospace Components
Global Aerospace Wiring Harness Market
Aircraft and Aerospace Components
Impact-Resistant Composite Radome Structures for High-Bandwidth Antennas Market
Aircraft and Aerospace Components
Rotary Wing Aircraft Rivets Market
Aircraft and Aerospace Components
Enclosure Support Arm Systems Market
Aircraft and Aerospace Components
Inlet Lip Anti-Icing and De-Icing Component Systems Market
Aircraft and Aerospace Components
Air Taxi Exterior Component Systems Market
Aircraft and Aerospace Components
Global Aircraft Seat Actuation System Market
Aircraft and Aerospace Components
Aerospace Nuts Market