

Aircraft Belly Fairing Modification Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Belly Fairing Modification Kits Market Insights
Aircraft composite technician availability is collapsing across North American and European maintenance networks, forcing kit suppliers to redesign installation protocols for lower-skill labor pools. Spirit AeroSystems leverages its Wichita manufacturing base to sustain vertical integration in composite fairing production. GKN Aerospace anchors European supply through its Bristol aerostructures facility, while FACC competes from Austria with specialized thermoplastic processing capabilities.
Aircraft belly fairing modification kits are aftermarket aerodynamic and structural upgrade packages installed on the lower fuselage surface between the wing root and tail section, typically fabricated from carbon-fiber-reinforced polymer, aluminum-lithium alloys, or hybrid laminates using resin-transfer molding or automated fiber placement processes. These kits reduce form drag, protect avionics routing, and extend airframe service life on commercial and military platforms. Composite kits dominate current retrofit programs due to weight savings, while hybrid kits represent the fastest-expanding category as operators balance cost against performance on mid-life aircraft. Application demand skews toward drag reduction in fuel-price-sensitive markets, though structural reinforcement generates superior margin pools where fatigue-critical inspections trigger mandatory upgrades.
FAA airworthiness directives and EASA CS-25 certification standards govern material flammability, lightning-strike protection, and structural substantiation for belly fairing modifications, creating compliance barriers that filter uncertified suppliers from aftermarket procurement lists. The EU Green Deal's aviation emissions targets indirectly stimulate retrofit demand by rewarding operators that reduce fuel burn through aerodynamic improvements. Stakeholders must monitor evolving MRO labor certification requirements and composite repair qualification standards as workforce constraints reshape kit design priorities and installation economics.
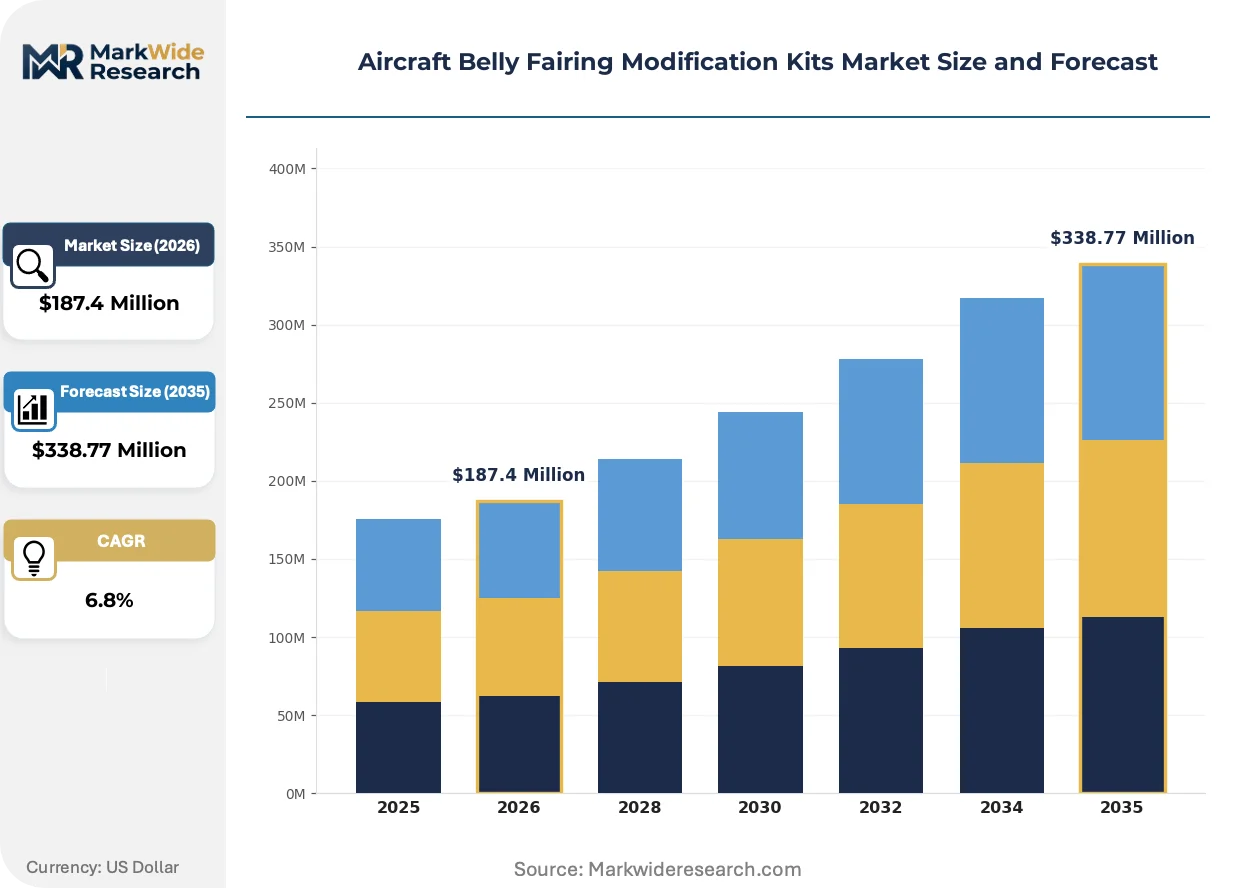
Market Dynamics
Aircraft belly fairing modification kit suppliers face a structural compression between FAA airworthiness directive compliance deadlines and collapsing composite technician availability across North American and European MRO networks.
Growth Catalysts
- FAA Airworthiness Directives:Mandatory structural integrity upgrades for extended-service narrow-body fleets in the United States generate retrofit pull-through for drag-reduction kits on aging airframes.
- Carbon-Fiber-Reinforced Polymer Processing:Advances in automated fiber placement and resin-transfer molding reduce kit weight ratios, enabling fuel burn improvements that justify retrofit economics at current jet fuel price levels.
- United States Fleet Concentration:Major carriers operating large narrow-body fleets concentrated in domestic hub networks create volume demand for standardized modification protocols.
Market Restraints
- Aluminum-Lithium Alloy Input Volatility:Hybrid kit production depends on aerospace-grade aluminum-lithium supply chains concentrated in primary smelter networks, exposing margins to energy-cost-driven price swings.
- Composite Technician Labor Scarcity:FAA-certified composite repair qualification requirements filter the install base to shrinking specialist pools, capping retrofit velocity regardless of kit availability.
- EASA CS-25 Certification Friction:Dual certification requirements for cross-border operations create documentation burdens that extend approval timelines and favor incumbent suppliers with established regulatory relationships.
Strategic Opportunities
- EU Green Deal Aviation Emissions Targets:European operators gain operational credit for documented fuel burn reductions, creating policy-backed demand for aerodynamic retrofit investments.
- Thermoplastic Processing Convergence:Out-of-autoclave thermoplastic composite welding intersects with automated inspection systems to enable same-day installation protocols at line maintenance stations.
- Military Platform Crossover:Tanker and transport fleets operated by defense agencies represent underpenetrated retrofit demand with less price sensitivity than commercial airline procurement.
Industry Challenges
- FAA-EASA Certification Timeline Compression:Extended-service aircraft require synchronized approvals across jurisdictions, forcing kit suppliers to maintain parallel substantiation teams.
- Legacy Avionics Routing Integration:Belly fairing modifications must accommodate non-standard wiring configurations from previous aftermarket installations, increasing engineering validation scope per airframe.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Belly Fairing Modification Kits Market Trends and Innovations
Kit design priorities are pivoting from pure aerodynamic optimization toward installation protocols that accommodate lower-skill labor pools without compromising structural substantiation requirements.
Thermoplastic composite welding is decomposing traditional thermoset dominance in fairing fabrication. Regional carriers with constrained MRO partnerships are adopting snap-fit thermoplastic panels at accelerated procurement cycles. This technology is decomposing the incumbent supplier advantage tied to autoclave capacity and certified thermoset technician networks.
EASA CS-25 amendments governing lightning-strike protection and material flammability are tightening documentation requirements for composite modifications. European operators now face extended ground time for kit installation pending revised electrical bonding verification. Narrow-body fleets with high cycle counts in Mediterranean and Eastern European basing are absorbing the longest approval delays.
Airline engineering departments are consolidating vendor relationships around kit suppliers offering bundled structural health monitoring integration. Long-term service agreements covering inspection intervals and repair provision are displacing transactional kit purchases at major United States network carriers. This consolidation is most visible at legacy carriers with centralized fleet engineering functions in Dallas-Fort Worth and Chicago maintenance hubs.
Aircraft Belly Fairing Modification Kits Market Segmentation
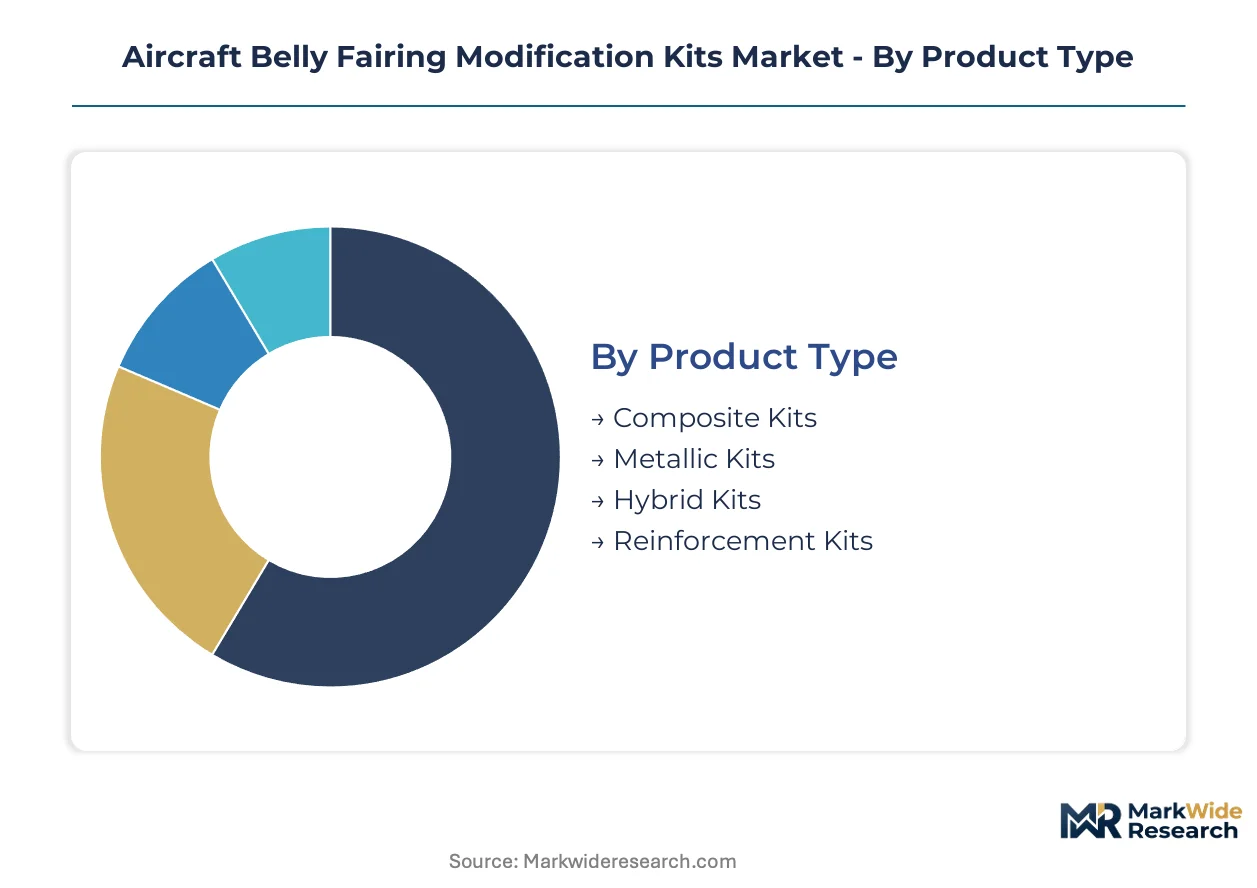
Segmentation in aircraft belly fairing modification kits reveals how technical specifications, regulatory pathways, and installation constraints fragment procurement patterns across operator types. Understanding these divisions exposes where substitution pressures and margin concentration shift competitive advantage.
Product Type:
Composite kits face the most acute substitution threat as thermoplastic welding advances erode the incumbent advantage tied to autoclave-cured thermoset networks and certified technician pools.
- Composite Kits:Fabricated from carbon-fiber-reinforced polymer using resin-transfer molding or automated fiber placement, these deliver maximum weight reduction for fuel-price-sensitive operators. United States network carriers with centralized fleet engineering functions in Dallas-Fort Worth and Chicago maintenance hubs concentrate procurement here, though FAA-certified composite repair qualification requirements constrain installation velocity.
- Hybrid Kits:Combining carbon-fiber skins with aluminum-lithium alloy substructures, these balance cost against performance on mid-life aircraft where full composite economics fail. Mediterranean and Eastern European narrow-body fleets with high cycle counts absorb extended ground time for these installations pending EASA CS-25 electrical bonding verification.
- Metallic Kits:Aluminum-lithium alloy constructions serve operators prioritizing damage tolerance and field repairability over weight minimization.
- Reinforcement Kits:Structural upgrade packages addressing fatigue-critical inspection findings generate superior margin pools where mandatory upgrades trigger procurement.
Composite kits anchor the volume base while hybrid kits gain share at the steepest rate.
Application:
Cost tier segmentation separates fuel-burn-driven retrofits from compliance-mandated structural work, with the latter commanding premium pricing due to non-discretionary procurement timelines.
- Drag Reduction:Aerodynamic fairing replacements targeting form drag reduction on aging narrow-body fleets. Fuel-price-sensitive markets in the United States generate pull-through as jet fuel economics justify retrofit investments at current price levels.
- Structural Reinforcement:Fatigue-critical upgrades mandated by FAA airworthiness directives for extended-service aircraft. These generate superior margin pools where inspection findings trigger mandatory procurement regardless of fuel price conditions.
- System Integration:Modifications accommodating avionics routing, antenna mounting, and sensor placement for connectivity upgrades.
- Noise Suppression:Acoustic treatment integration for Stage 5 compliance and airport curfew adherence.
Structural reinforcement commands the highest margin tier while drag reduction delivers the broadest addressable base.
End User:
Customer type fragmentation concentrates procurement authority differently, with centralized fleet engineering at legacy carriers contrasting against distributed decision-making at leasing firms and MRO networks.
- Commercial Airlines:Network carriers with domestic hub structures and narrow-body fleet concentration drive standardized modification protocol demand. Long-term service agreements covering inspection intervals and repair provision are displacing transactional kit purchases at major United States carriers.
- Defense Agencies:Tanker and transport fleets represent underpenetrated retrofit demand with reduced price sensitivity compared to commercial procurement cycles.
- Leasing Firms:Asset managers prioritize transferable modifications that preserve residual value across multiple operator transitions.
- Maintenance Repair Organizations:Independent MROs consolidate vendor relationships around suppliers offering bundled structural health monitoring integration and line maintenance station compatibility.
Commercial airlines dominate absolute volume while defense agencies offer the most favorable pricing environment.
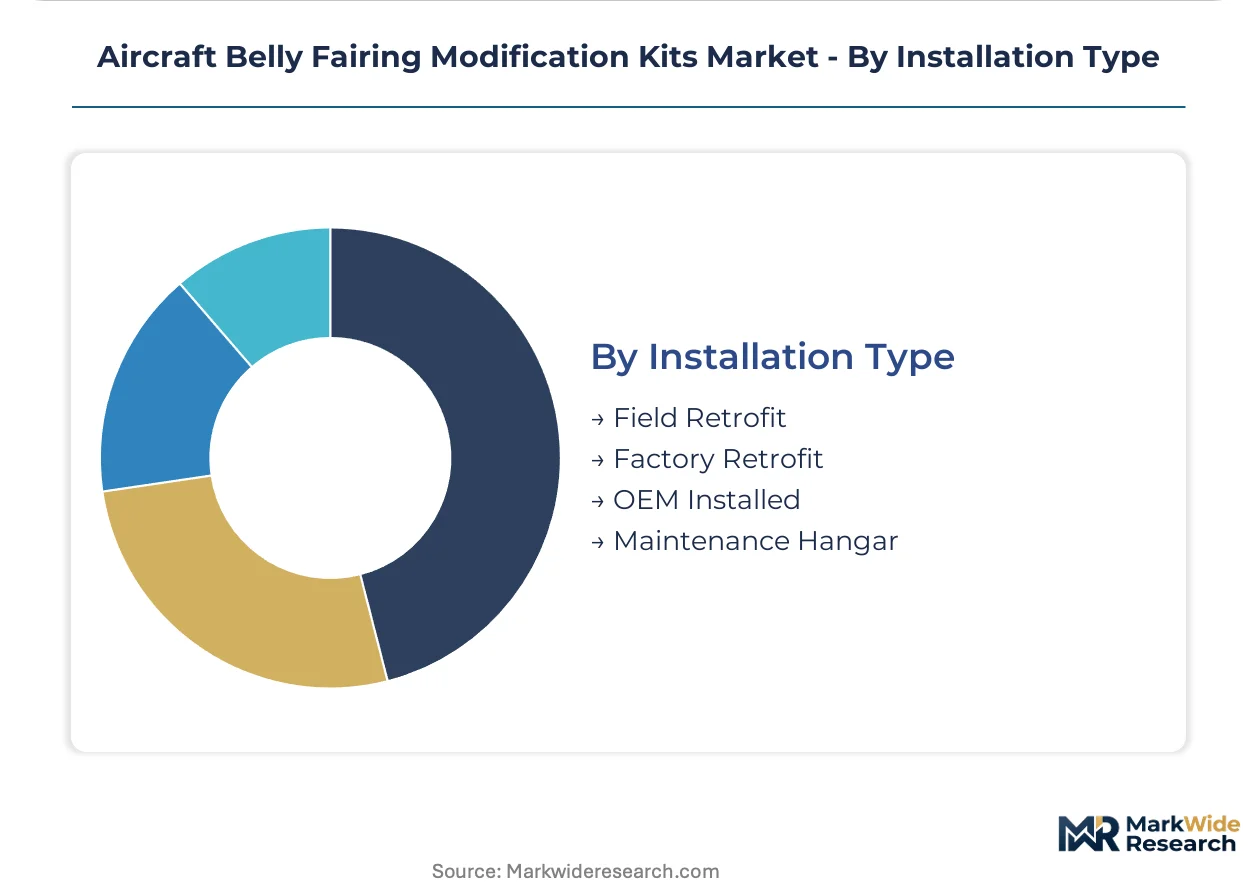
Installation Type:
Maturity gradients separate established factory retrofit channels from emerging field protocols enabled by out-of-autoclave thermoplastic processing and automated inspection convergence.
- Field Retrofit:Same-day installation protocols at line maintenance stations enabled by snap-fit thermoplastic panels and automated fiber placement advances. Regional carriers with constrained MRO partnerships are adopting these at accelerated procurement cycles.
- Factory Retrofit:Heavy maintenance visit installations during C-check and D-check intervals, accommodating complex hybrid kit integration and legacy avionics routing validation.
- OEM Installed:New production line integration at Wichita and Bristol aerostructures facilities for forward-fit programs.
- Maintenance Hangar:Dedicated modification center installations for large fleet campaigns requiring synchronized downtime scheduling.
Factory retrofit retains the largest installed base while field retrofit is climbing the fastest as thermoplastic welding decomposes traditional technician requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA airworthiness directives anchor demand concentration in the United States, where aging narrow-body fleets require mandatory structural integrity upgrades. Kit suppliers navigate divergent certification timelines across jurisdictions while addressing workforce constraints in established maintenance networks.
United States
Major network carriers operating domestic hub structures generate standardized modification protocol demand for drag-reduction retrofits. FAA airworthiness directives mandate structural reinforcement for extended-service aircraft, triggering non-discretionary procurement regardless of fuel price conditions. Dallas-Fort Worth and Chicago maintenance hubs concentrate fleet engineering functions where long-term service agreements displace transactional kit purchases.
Germany
Technological leadership in automated fiber placement and resin-transfer molding processes sustains kit fabrication capabilities for European retrofit programs. EASA CS-25 certification standards govern material flammability and lightning-strike protection, creating compliance documentation burdens that extend approval timelines. Hamburg and Munich aerospace clusters host specialized composite processing facilities serving cross-border operator demand.
United Kingdom
Defense agency tanker and transport fleets represent underpenetrated retrofit demand with reduced price sensitivity compared to commercial procurement cycles. UK military aviation regulations prioritize damage tolerance and field repairability in platform sustainment decisions. Bristol aerostructures facilities anchor European supply chain positioning for hybrid kit production.
France
EU Green Deal aviation emissions targets reward operators documenting fuel burn reductions through aerodynamic improvements, stimulating policy-backed retrofit investment. EASA amendments tightening electrical bonding verification requirements extend ground time for kit installations on high-cycle narrow-body fleets. Toulouse and Nantes aerospace manufacturing centers maintain OEM-forward integration into new production line programs.
Japan
Domestic carriers with constrained MRO partnerships accelerate adoption of snap-fit thermoplastic panels enabling same-day installation protocols. METI industrial policy supports out-of-autoclave composite welding technology development for line maintenance station compatibility. Nagoya and Kobe manufacturing corridors concentrate specialized thermoplastic processing capabilities for regional retrofit demand.
Aircraft Belly Fairing Modification Kits Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in aircraft belly fairing modification kit supply. Tier-one aerostructures manufacturers leverage captive composite fabrication capacity and established regulatory relationships to dominate factory retrofit channels. Mid-scale specialists compete on thermoplastic welding innovations and field-installation protocols that reduce technician qualification requirements. Competitive dynamics center on backward integration into carbon-fiber preform supply and geographic expansion through maintenance hangar partnerships.
Among integrated aerostructures manufacturers, Spirit AeroSystems and GKN Aerospace exemplify the tier-one archetype through Wichita and Bristol manufacturing bases. FACC occupies a specialist position within the thermoplastic processing segment, leveraging Austrian fabrication capabilities. These three companies represent contrasting strategic postures: scale-driven vertical integration versus technology-focused specialization in emerging installation protocols.
| Leading Market Players |
|---|
| Boeing |
| Airbus |
| Spirit AeroSystems |
| Collins Aerospace |
| GKN Aerospace |
| FACC |
| Triumph Group |
| Hutchinson |
| Ducommun |
| Others |
Pricing and Supply Chain Analysis
Long-term service agreements covering inspection intervals and repair provision lock in both composite preform supply access and price visibility for United States network carriers operating aging narrow-body fleets under FAA airworthiness directive timelines. These contracts insulate kit suppliers from aluminum-lithium alloy spot volatility while binding buyers to incumbent regulatory relationships that accelerate EASA CS-25 certification pathways.
Pricing Analysis
United States-based procurement commands premium positioning against Mediterranean and Eastern European installations where extended ground time for EASA electrical bonding verification compresses operator willingness-to-pay. Three-tier pricing structure across premium composite, standard hybrid, and economy metallic kit levels separates fuel-burn-driven retrofits from mandatory structural reinforcement mandates. Pricing pressure stems from collapsing FAA-certified composite technician availability, which caps retrofit velocity regardless of kit availability. Leasing firms exhibit highest price sensitivity due to residual value uncertainty across multiple operator transitions, while defense agency tanker fleets absorb premium tiering with minimal negotiation.
Supply Chain Analysis
Container availability constraints across Trans-Pacific trade lanes elevate inbound logistics costs for carbon-fiber preforms sourced from Japanese and South Korean precursor facilities. Manufacturing gravity centers on Wichita and Bristol aerostructures facilities for thermoset composite fabrication, with Austrian thermoplastic processing capabilities feeding emerging snap-fit panel demand. Raw material dependencies rest on aerospace-grade carbon fiber from Toray and Hexcel supply pools, aluminum-lithium alloy from Alcoa primary smelter networks, and epoxy resin systems subject to energy-cost-driven price swings. Single-source vulnerability concentrates in qualified preform suppliers certified to FAA-EASA dual standards. Distribution runs through heavy maintenance visit channels at Dallas-Fort Worth and Chicago hubs, with line maintenance station penetration accelerating for thermoplastic welding protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoplastic composite welding convergence with automated inspection systems constitutes a regulatory-inflected disruption that rewrites installation economics and technician qualification requirements across the analysis window.
For Market Incumbents: Shield factory retrofit channel dominance by accelerating backward integration into carbon-fiber preform supply and certifying out-of-autoclave thermoplastic protocols before snap-fit panel adoption erodes autoclave-cured incumbent advantage. Prioritize capacity reservation contracts with United States network carriers to lock in long-term service agreement renewals against emerging specialists offering bundled structural health monitoring. For New Entrants and Emerging Players: Anchor in defense agency tanker and transport fleet retrofit demand where reduced price sensitivity and less stringent commercial airline procurement cycles create viable entry economics. Target Mediterranean and Eastern European narrow-body operators facing extended EASA approval delays with rapid-turnaround thermoplastic welding capabilities that bypass certified technician bottlenecks. Lead with line maintenance station compatibility as the primary go-to-market differentiator. For Investors and Strategic Acquirers: Specialist thermoplastic processing capabilities with established automated fiber placement infrastructure represent the highest-conviction acquisition archetype for portfolio exposure to field retrofit acceleration. Monitor EASA CS-25 amendment implementation velocity as the signal to watch for inflection in European retrofit ground time economics and corresponding kit supplier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Welding Certification | Enables same-day installation protocols at line maintenance stations without FAA-certified composite repair qualifications. |
| Backward Integration into Preforms | Captures margin pools currently absorbed by Toray and Hexcel supply chains while securing dual-certification material traceability. |
| Structural Health Monitoring Bundling | Displaces transactional kit purchases at Dallas-Fort Worth and Chicago maintenance hubs with recurring revenue service agreements. |
| Defense Platform Crossover | Accesses underpenetrated tanker and transport retrofit demand with reduced price sensitivity compared to commercial procurement. |
| EASA Regulatory Relationship Investment | Compresses approval timelines for high-cycle narrow-body fleets in Mediterranean and Eastern European basing. |
Research Methodology
Cross-validation between primary interviews with MRO operations directors, fleet engineering managers at United States network carriers, composite technician training program administrators, and EASA certification specialists anchors the qualitative findings in operational reality. Secondary validation draws from FAA airworthiness directive filings, EASA CS-25 amendment documentation, customs records for carbon-fiber preform imports, and SEC 10-K disclosures from tier-one aerostructures manufacturers. Bottom-up kit installation velocity estimates triangulate against top-down narrow-body fleet age distributions across the analysis window.
Sensitivity analysis around jet fuel price thresholds, FAA-certified technician availability curves, and EASA approval timeline scenarios stress-tests base case assumptions. The analytical framework models product type segmentation across composite, hybrid, metallic, and reinforcement kits; application segmentation across drag reduction, structural reinforcement, system integration, and noise suppression; and end-user segmentation across commercial airlines, defense agencies, leasing firms, and MRO networks. CAGRs derive from installation rate projections indexed to fleet age profiles and regulatory mandate schedules. Industry-specific forecast inputs include resin-transfer molding capacity utilization at Wichita and Bristol facilities and thermoplastic welding equipment deployment rates at Nagoya manufacturing corridors.
Material uncertainties — abrupt FAA airworthiness directive acceleration, EASA CS-25 electrical bonding verification scope expansion, and aluminum-lithium alloy supply disruption from primary smelter energy cost spikes — sit outside the modeled envelope. Forecasts reflect documented assumptions about technician training pipeline recovery and thermoplastic adoption velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.