
 Europe Rotor Blade Market | 2026-2036
Europe Rotor Blade Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Rotor Blade Market Insights
Glass fiber is broadening its cost advantage over carbon fiber in utility-scale blade production across Europe. Vestas Wind Systems A/S leverages its integrated supply chain to control resin and core material costs. Siemens Gamesa Renewable Energy SA anchors its competitive position through dedicated offshore blade facilities in northern Europe. Nordex SE differentiates with modular blade architectures that reduce transport constraints.
A rotor blade is an aerodynamic structure, typically 40 to 120 meters in length for wind applications, composed of fiberglass-reinforced epoxy or hybrid composites with carbon fiber spar caps, manufactured via vacuum infusion or prepreg layup to convert kinetic wind energy into rotational mechanical power. Horizontal axis configurations dominate European installations due to mature certification pathways and higher aerodynamic efficiency ratings. Carbon fiber materials command premium positioning in blades exceeding 90 meters, where stiffness-to-weight ratios determine structural viability. Utility end users drive procurement volume through long-term service agreements that bundle blade replacement with turbine maintenance.
The EU Green Deal, CE marking under the Machinery Directive, and the F-Gas Regulation collectively mandate recyclable blade materials and restrict greenhouse gas-intensive manufacturing processes in European facilities. ECHA scrutiny of epoxy resin chemistries is forcing reformulation timelines across supply chains. Stakeholders must monitor whether the EU AI Act extends predictive maintenance mandates to blade inspection protocols.
Market Dynamics
Blade length escalation toward 120-meter offshore specifications is compressing manufacturing tolerances and forcing resin chemistry reformulations across European supply chains. This dimensional push reconfigures factory footprints, transport logistics, and recycling infrastructure simultaneously.
Growth Catalysts
- EU Green Deal domestic content mandates:Tightened rules under the revised Renewable Energy Directive require blade manufacturing localization, pulling production capacity into Germany, Denmark, and the Netherlands.
- North Sea offshore wind corridor expansion:Clustered development across the Netherlands, Germany, and Denmark concentrates demand for 90-meter-plus blades with specialized aerodynamic profiles.
- Glass fiber cost efficiency gains:Vacuum infusion process improvements for fiberglass-reinforced epoxy are widening cost spreads over carbon fiber in utility-scale production runs.
Market Restraints
- Epoxy resin supply concentration:ECHA scrutiny of bisphenol-A and amine hardener chemistries is forcing reformulation timelines that compress R&D cycles for European formulators.
- Carbon fiber input cost volatility:Aerospace and automotive competition for polyacrylonitrile precursor fibers creates price instability for blades exceeding 90 meters where stiffness requirements mandate composite spar caps.
- Transport infrastructure bottlenecks:Road and rail clearances for 80-meter-plus blade segments limit factory site selection to coastal corridors with specialized port access.
Strategic Opportunities
- Baltic Sea emerging markets:Poland and Lithuania are accelerating offshore lease auctions, creating demand for blade suppliers with Baltic port manufacturing access.
- Thermoplastic resin technology convergence:Polypropylene and thermoplastic polyurethane systems compatible with automated fiber placement are enabling recyclable blade architectures that align with end-of-life mandates.
- Predictive maintenance service bundling:Long-term service agreements that integrate blade inspection with turbine O&M contracts are capturing recurring revenue streams from German and Danish utility operators.
Industry Challenges
- Composite technician skill scarcity:Vacuum infusion and prepreg layup expertise for 60-meter-plus structures is concentrated among aging workforces in northern Germany and Denmark.
- CE marking certification timelines:Machinery Directive conformity assessments for novel blade geometries are extending type-approval cycles by 8-14 months.
- Recycling infrastructure integration:Pyrolysis and solvolysis facilities for thermoset composite recovery remain underdeveloped relative to blade retirement volumes projected through 2035.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Rotor Blade Market |
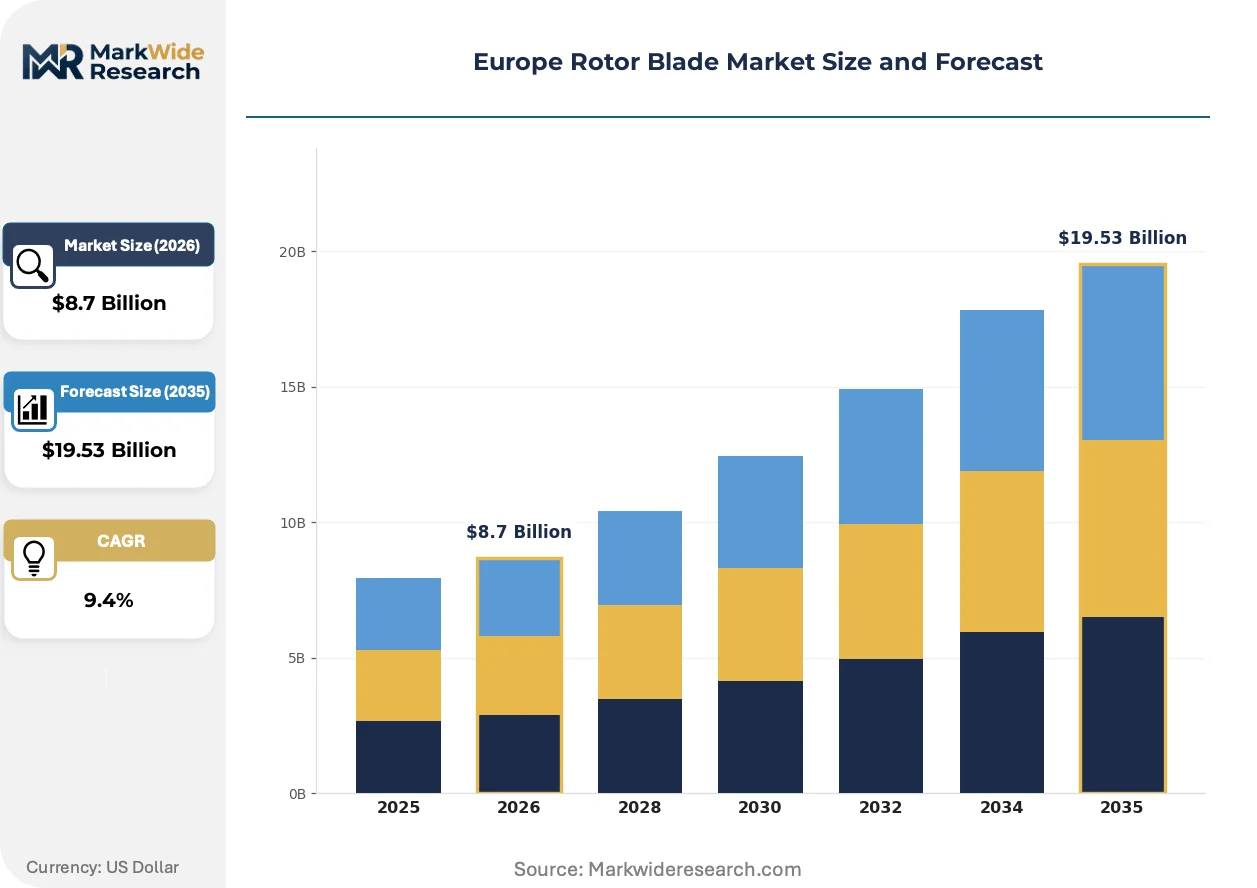
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Axis, Vertical Axis, Hybrid, Others Material: Fiberglass, Carbon Fiber, Metals, Composites Application: Wind Energy, Aviation, Marine, Industrial End User: Utilities, Manufacturers, OEMs, Service Providers |
| Companies Covered | Nordex SE, Suzlon Energy Limited, Vestas Wind Systems A/S, Acciona S.A., BayWa r.e. AG, Siemens Gamesa Renewable Energy SA, Enercon GmbH, EnBW Energie Baden-Württemberg, LM Wind Power, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Rotor Blade Market Trends and Innovations
Material substitution trajectories and manufacturing automation are converging to redefine cost structures and environmental compliance for European blade production. These shifts are accelerating competitive differentiation among suppliers with captive resin and core material capabilities.
Hybrid composite architectures with carbon fiber spar caps and glass fiber skins are integrating stiffness-to-weight optimization with cost containment for 100-meter offshore specifications. German and Danish developers are specifying these configurations for North Sea projects with 15 MW-plus turbine ratings. The technology is integrating modular manufacturing approaches that segment blades into transportable sub-components.
REACH restrictions on epoxy resin chemistries and the F-Gas Regulation's greenhouse gas intensity limits are forcing solvent-free manufacturing process adoption across European facilities. Industrial consequence includes capital expenditure for closed-mold systems and accelerated thermoplastic material qualification programs. Offshore blade production lines in northern Europe are most affected, with Vestas and Siemens Gamesa facilities leading reformulation timelines.
Buyer consolidation among German and Danish utility operators is compressing supplier negotiation cycles and unbundling blade replacement from full-turbine maintenance contracts. Independent service providers are capturing inspection and repair volume previously held by OEM captive teams. This pattern is most visible in the German North Sea corridor where RWE and Orsted are consolidating procurement across multi-gigawatt portfolios.
Europe Rotor Blade Market Segmentation
Rotor blade procurement patterns in Europe diverge sharply across turbine configurations, material specifications, and end-use applications. Understanding these fault lines exposes where margin pools concentrate and which technology transitions will reshape supplier positioning through the forecast window.
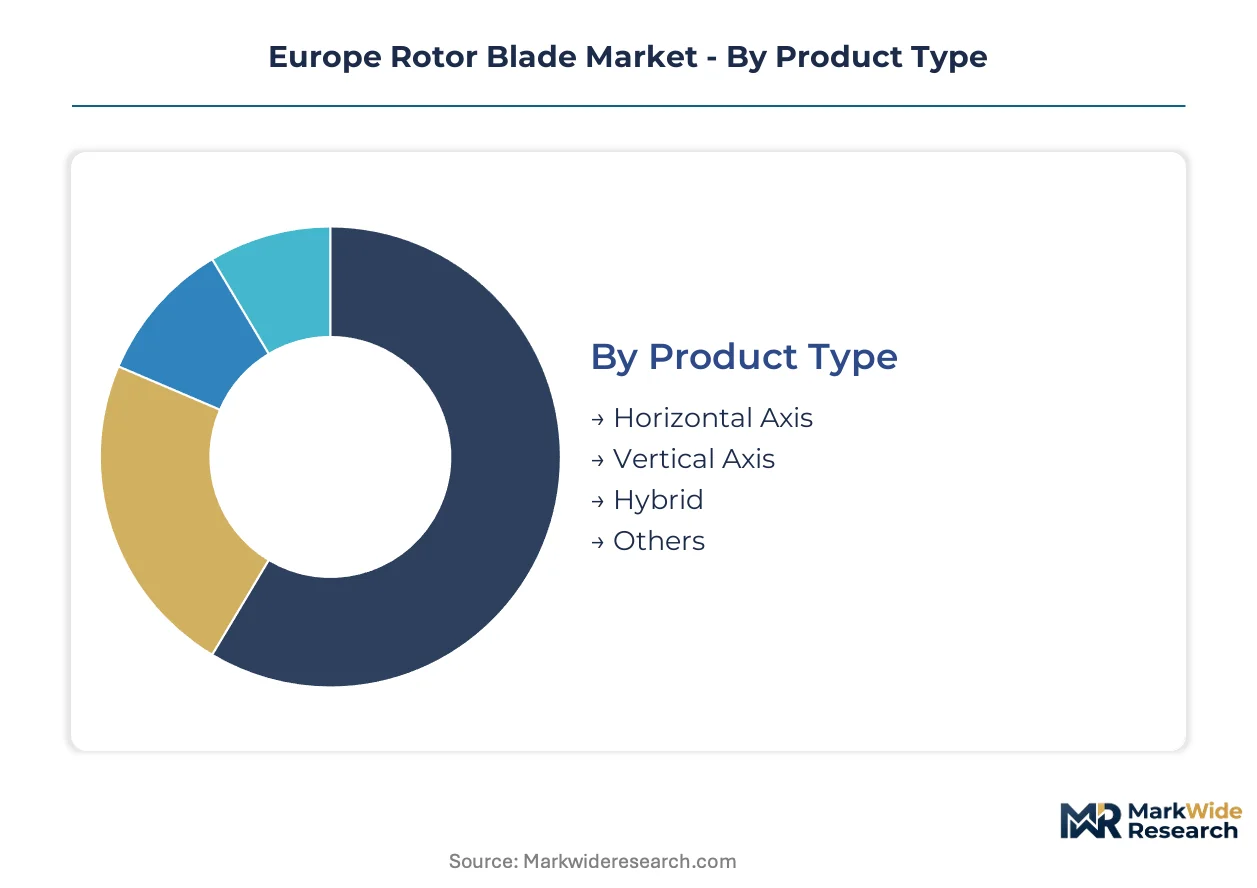
Product Type:
Buyers differentiate primarily by aerodynamic efficiency requirements and certification pathway maturity, with offshore developers prioritizing proven designs while experimental formats target niche installations.
- Horizontal Axis:Fiberglass-reinforced epoxy blades with 40-120 meter spans dominate North Sea offshore arrays. German and Danish developers specify these configurations for 15 MW-plus turbines, leveraging mature CE marking pathways under the Machinery Directive.
- Vertical Axis:Darrieus and Savonius geometries suit distributed urban installations where omnidirectional wind capture offsets lower efficiency ratings. Polish and Baltic port authorities are piloting these for harbor infrastructure power generation.
- Hybrid:Dual-rotor systems combining horizontal and vertical elements target complex terrain applications in Scottish highlands and Norwegian fjord regions.
- Others:Experimental shrouded and ducted formats remain confined to research installations at DTU Wind Energy and Fraunhofer IWES facilities.
Horizontal Axis leads volumes today; Hybrid formats are gaining share fastest among experimental developers.
Material:
Cost-to-performance ratios and EU end-of-life mandates are fragmenting procurement strategies, with glass fiber retaining utility-scale dominance while carbon fiber penetrates length-intensive offshore specifications.
- Fiberglass:E-glass and S-glass reinforcements in vacuum-infused epoxy matrices command 80-meter-plus utility production. Vestas and Nordex facilities in Denmark and Germany optimize these processes for North Sea volume contracts.
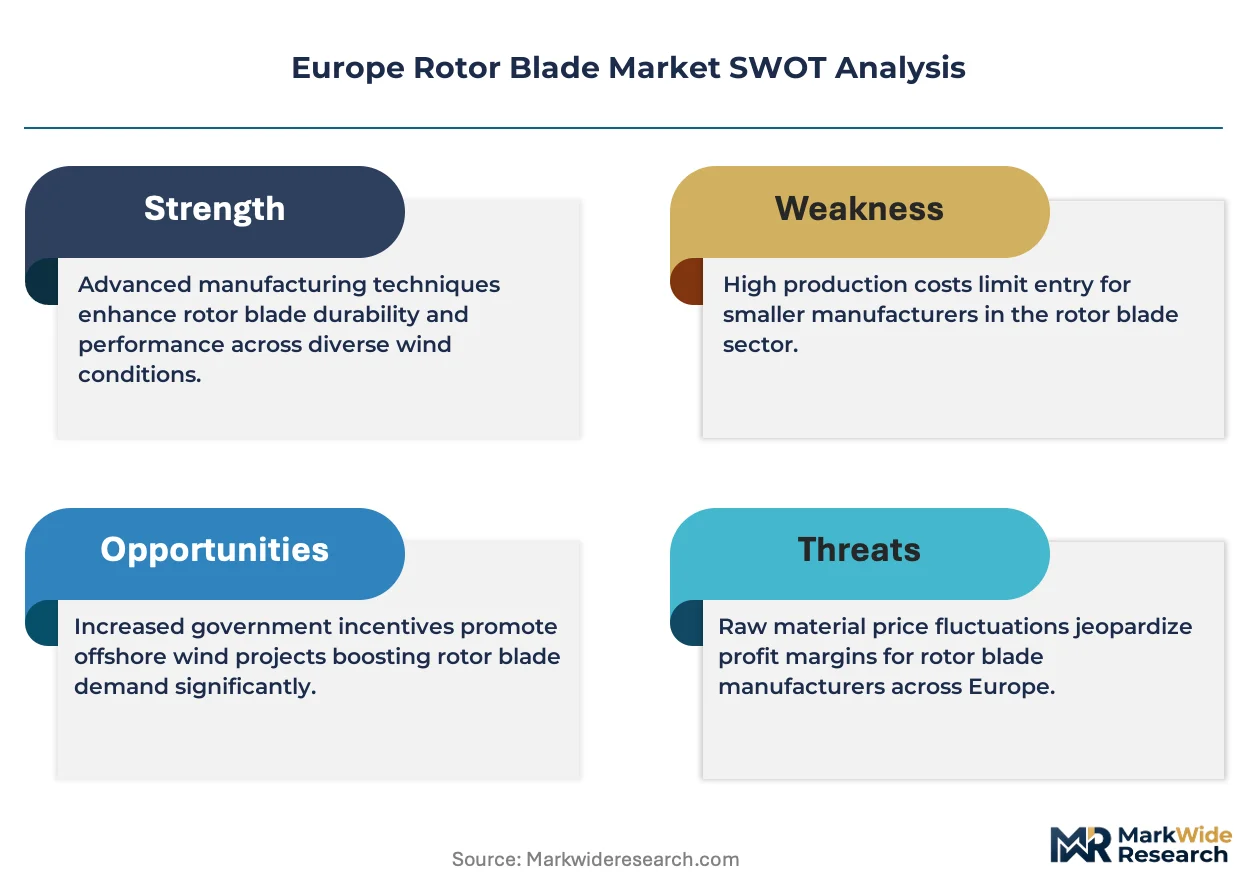
- Carbon Fiber:PAN-based precursors in spar cap applications enable 100-meter-plus blade stiffness without weight penalties. Aerospace competition for precursor fibers constrains European wind sector access.
- Metals:Aluminum and steel root inserts and lightning protection systems integrate with composite structures across all blade classes.
- Composites:Natural fiber and bio-epoxy hybrids are qualifying for REACH-compliant production lines at Siemens Gamesa's Hull facility.
Fiberglass dominates installed base economics; Carbon Fiber is climbing the fastest among next-generation offshore specifications.
Application:
Volume concentration and regulatory intensity vary dramatically across end-use sectors, with wind energy absorbing manufacturing capacity while aviation and marine applications demand specialized certification.
- Wind Energy:Onshore and offshore turbine blades represent the demand core, with EU Green Deal targets pulling 90-meter-plus specifications into German, Danish, and Dutch manufacturing corridors.
- Aviation:Propeller and rotorcraft blade requirements from Airbus Helicopters and Leonardo Helicopters impose aerospace-grade quality systems on European suppliers.
- Marine:Ship propulsion and tidal turbine blades target salt-corrosion resistance through vinyl ester resin systems at French Atlantic shipyards.
- Industrial:Cooling tower and ventilation fan blades occupy lower-margin production tiers with standardized geometries.
Wind Energy anchors manufacturing scale; Marine applications are expanding most quickly among non-wind segments.
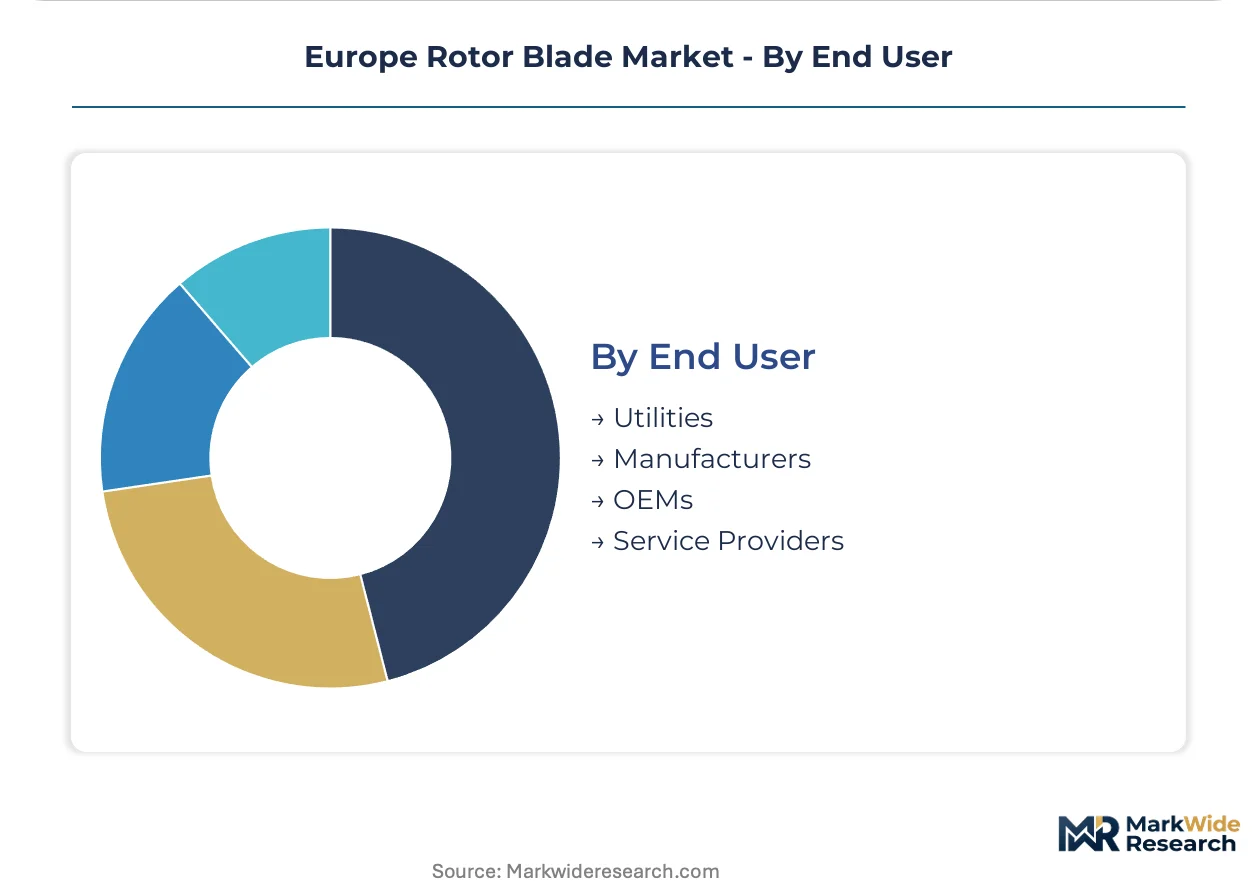
End User:
Procurement sophistication and contract structure complexity separate institutional buyers from equipment vendors, with long-term service bundling reshaping supplier relationships.
- Utilities:RWE, Orsted, and EnBW negotiate multi-gigawatt blade supply agreements with embedded inspection and replacement clauses across 20-25 year asset lifecycles.
- Manufacturers:Tier-2 blade specialists supplying non-captive OEMs compete on resin chemistry flexibility and modular transport solutions.
- OEMs:Vestas, Siemens Gamesa, and Nordex maintain in-house blade production with captive core material and resin formulation capabilities.
- Service Providers:Independent inspection and repair contractors capture blade maintenance volume previously held by OEM captive teams in the German North Sea corridor.
Utilities command the largest procurement volumes; Service Providers are gaining share fastest as independent O&M markets mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea corridor spanning German, Danish, and Dutch port cities anchors European rotor blade manufacturing capacity. Industrial clusters in Bremerhaven, Esbjerg, and Rotterdam concentrate vacuum infusion facilities serving 90-meter-plus offshore specifications. EU Green Deal domestic content mandates are pulling additional production capacity into these coastal manufacturing zones.
Germany
Offshore developers RWE and EnBW are scaling orders for 100-meter-plus blades at Bremerhaven and Cuxhaven facilities. The EU Green Deal and revised Renewable Energy Directive tighten localization requirements for blade manufacturing. The North Sea port cluster concentrates vacuum infusion capacity serving North Sea wind arrays.
Denmark
Orsted's multi-gigawatt procurement programs drive demand for hybrid composite architectures at Esbjerg and Ringkøbing facilities. CE marking under the Machinery Directive governs type-approval for novel blade geometries. The Jutland peninsula hosts specialized offshore blade production lines with captive resin formulation capabilities.
Netherlands
Rotterdam port authorities are expanding heavy-lift infrastructure to accommodate 120-meter blade segments for North Sea export. The F-Gas Regulation restricts greenhouse gas-intensive manufacturing processes in Dutch facilities. The Maasvlakte industrial zone integrates blade manufacturing with specialized offshore vessel loading.
Poland
Baltic Sea lease auctions are accelerating demand for blade suppliers with Gdańsk and Szczecin port access. ECHA scrutiny of epoxy resin chemistries is forcing reformulation timelines for Polish formulators. The Polish offshore corridor is emerging as a manufacturing alternative to North Sea concentration.
France
Atlantic shipyards at Saint-Nazaire are qualifying vinyl ester resin systems for salt-corrosion-resistant marine blade applications. REACH restrictions on bisphenol-A chemistries are compressing R&D cycles for French composite suppliers. The Pays de la Loire region hosts pilot facilities for recyclable thermoplastic blade architectures.
Europe Rotor Blade Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and supply chain integration depth. The market structures around three tiers: integrated OEMs with captive blade production, independent blade specialists serving non-captive turbine manufacturers, and utility-affiliated procurement entities bundling long-term service agreements. Strategic differentiation concentrates on resin chemistry control, modular transport solutions, and predictive maintenance service bundling. Capacity expansion and backward integration into core materials represent the dominant competitive moves.
Among integrated European OEMs, Vestas Wind Systems A/S and Siemens Gamesa Renewable Energy SA exemplify the captive manufacturing archetype with in-house blade production and resin formulation capabilities. Nordex SE occupies a position within the modular architecture specialist tier, differentiating through transportable sub-component designs that reduce logistics constraints for 80-meter-plus specifications. LM Wind Power represents the independent blade fabricator model, supplying non-captive turbine manufacturers across multiple European markets.
| Leading Market Players |
|---|
| Nordex SE |
| Suzlon Energy Limited |
| Vestas Wind Systems A/S |
| Acciona S.A. |
| BayWa r.e. AG |
| Siemens Gamesa Renewable Energy SA |
| Enercon GmbH |
| EnBW Energie Baden-Württemberg |
| LM Wind Power |
| Others |
Pricing and Supply Chain Analysis
Epoxy resin and carbon fiber precursor costs cascade through blade manufacturing tiers, compressing margins at the 90-meter-plus offshore specification level where German and Danish developers dominate procurement. Vacuum infusion process improvements for fiberglass-reinforced systems are widening cost spreads over carbon fiber spar caps, reshaping supplier tier positioning across the North Sea corridor.
Pricing Analysis
Input-cost pass-through from bisphenol-A and amine hardener chemistries is intensifying pricing pressure on European formulators facing ECHA reformulation timelines. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked offshore specifications from modular onshore designs and refurbished blade alternatives. Cost compression in the standard tier reflects glass fiber substitution gains, while aerospace competition for PAN precursor fibers stiffens premium-tier pricing. German utilities exhibit lowest price sensitivity due to long-term service bundling, whereas Polish Baltic developers prioritize economy-tier procurement.
Supply Chain Analysis
Single-source vulnerability sits with Chinese PAN precursor fiber suppliers feeding carbon fiber spar cap production for 100-meter-plus blades. Manufacturing concentration in Germany, Denmark, and the Netherlands anchors European vacuum infusion capacity, while epoxy resin formulation draws from Belgian and Dutch chemical clusters. Tariff exposure on aerospace-grade carbon fiber imports creates supply chain risk for stiffness-critical offshore specifications. Distribution runs through specialized heavy-lift port infrastructure at Bremerhaven, Esbjerg, and Rotterdam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in European rotor blade manufacturing rest on thermoplastic resin cost-down curves and predictive maintenance service bundling premiums. Glass fiber process automation and recyclable material qualification are shifting value capture toward suppliers with captive chemistry control.
For Market Incumbents: Extend backward integration into core material supply to defend against epoxy resin price volatility and ECHA-driven reformulation costs. Capture predictive maintenance revenue streams through long-term service agreements with German and Danish utilities that unbundle blade inspection from full-turbine contracts. Anchor capacity expansion in Baltic port zones to preempt Polish offshore lease auction demand.
For New Entrants and Emerging Players: The 40-60% price-point gap between premium carbon fiber offshore blades and economy-tier onshore fiberglass designs opens white-space opportunity in modular sub-component architectures. Target Polish and Lithuanian Baltic Sea developments with transport-optimized blade segments that bypass German-Dutch manufacturing concentration. Qualify thermoplastic resin systems under REACH-compliant production lines to capture recyclable blade mandates ahead of incumbent reformulation timelines.
For Investors and Strategic Acquirers: Roll-up economics work for independent blade fabricators with Baltic port access because EU Green Deal domestic content mandates are fragmenting procurement across emerging European offshore corridors. Focus on 5-10 year viability windows where thermoplastic technology convergence and recycling infrastructure buildout reshape competitive moats. Watch ECHA regulatory acceleration on epoxy chemistries as the inflection signal for material substitution winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Resin Qualification | REACH-compliant recyclable architectures align with F-Gas Regulation end-of-life mandates at Siemens Gamesa's Hull facility. |
| Baltic Port Manufacturing Expansion | Gdańsk and Szczecin access captures Polish offshore lease auction demand outside North Sea concentration. |
| Predictive Maintenance Service Bundling | Long-term agreements with RWE and Orsted convert blade inspection into recurring revenue streams. |
| Modular Blade Architecture Development | Transportable sub-components reduce logistics constraints for 80-meter-plus specifications at Nordex facilities. |
| Closed-Mold System Capital Deployment | Solvent-free manufacturing satisfies F-Gas greenhouse gas intensity limits at Vestas and Siemens Gamesa lines. |
Research Methodology
Multiple input streams — executive interviews with blade manufacturing plant managers, procurement leads at German utilities, EPC contractors, and resin formulation specialists, plus customs data, EU Green Deal policy filings, and ECHA regulatory submissions — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from Machinery Directive CE marking databases, F-Gas Regulation implementation reports, and North Sea offshore project development trackers.
Historical capacity utilization patterns were cross-referenced against panel input from utility planning officers and OEM platform engineers to anchor projections across the analysis window. Segmentation modeling spanned turbine configuration, material specification, blade length tier, and regional manufacturing cluster. CAGRs were derived from installed base retirement schedules and offshore auction pipeline conversion rates, with thermoplastic adoption curves and recycling infrastructure buildout timelines as industry-specific sensitivity inputs.
Caveats apply where ECHA regulatory acceleration, aerospace carbon fiber demand spikes, or Baltic Sea grid connection delays could materially shift the outlook. Forecasts reflect assumptions about domestic content mandate enforcement and thermoplastic material qualification timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Aircraft Vertical Stabilizer Market
Aircraft and Aerospace Components
Europe Military Aviation Market
Aircraft and Aerospace Components
Aircraft Brackets Market
Aircraft and Aerospace Components
High-Temperature Composite Exhaust and Thrust Reverser External Panels Market
Aircraft and Aerospace Components
Commercial Aircraft Turbine Blades and Vanes Market
Aircraft and Aerospace Components
South America Rotor Blade Market
Aircraft and Aerospace Components
Composite Winglet and Sharklet Structures Market
Aircraft and Aerospace Components
Helicopter Blades Market
Aircraft and Aerospace Components
Commercial Airframe Component Market
Aircraft and Aerospace Components
Global Aerospace Pressure Gauge Market
Aircraft and Aerospace Components
Air Taxi Exterior Component Systems Market
Aircraft and Aerospace Components
Global Aerospace Wiring Harness Market
Aircraft and Aerospace Components
Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
Cold Gas Thrusters Market
Aircraft and Aerospace Components
Enclosure Support Arm Systems Market
Aircraft and Aerospace Components
Thrust Vector Control Market