
 Racing Drone Market | 2026-2036
Racing Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Racing Drone Market Intelligence
Carbon fiber is displacing traditional ABS and glass-reinforced nylon in racing drone frames, which is recalibrating weight-to-strength economics across the competitive segment. DJI leverages its integrated flight controller ecosystem to dominate premium ready-to-fly configurations. iFlight specializes in freestyle and racing frames with aggressive geometry for tight-corner aerodynamics. GEPRC sustains manufacturing scale through Shenzhen-based vertical assembly, controlling component costs for micro and mini drone categories.
Racing drones are high-performance unmanned aerial vehicles engineered for competitive speed, agility, and first-person-view piloting, typically achieving thrust-to-weight ratios exceeding 8:1 through brushless motor arrays and lithium polymer battery configurations. Their primary commercial purpose centers on organized competitive racing, aerial cinematography capture, and pilot training ecosystems. FPV drones lead technology adoption due to immersive piloting requirements, while ready-to-fly drones capture the fastest-growing demand segment as barrier-to-entry falls for hobbyist pilots. Custom built drones retain the highest margin pool among product types, serving professional pilots and racing leagues seeking component-level optimization.
The FAA enforces Remote ID compliance for all drones above 250 grams, reshaping hardware design and firmware architecture for US-market racing units. EASA's CE marking and open-category drone regulations in Europe impose parallel conformity requirements, while China's GB standards and MIIT radio-frequency certifications govern export-bound manufacturing. Stakeholders must monitor evolving frequency allocation rules and airspace classification changes that determine where competitive racing events can legally operate.
Market Dynamics
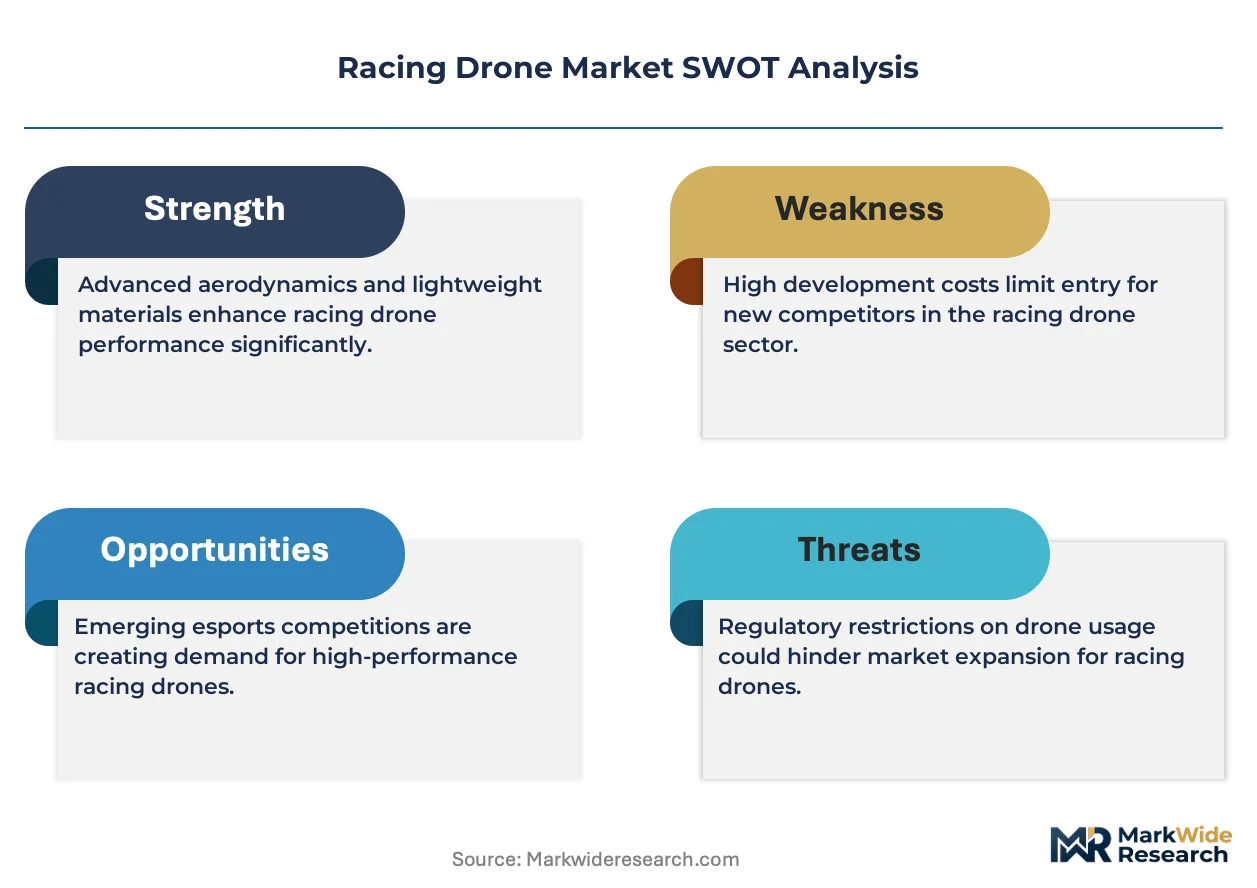
Carbon fiber is displacing ABS and glass-reinforced nylon across racing drone frames, compressing weight-to-strength economics while Shenzhen-based component ecosystems concentrate global supply. This materials shift intersects with FAA Remote ID mandates to force simultaneous hardware redesigns across manufacturers.
Growth Catalysts
- Remote ID Compliance:FAA mandates for drones above 250 grams are accelerating firmware architecture upgrades and integrated module adoption across US-market units.
- FPV Technology Maturation:First-person-view systems are achieving sub-20ms latency thresholds, enabling professional racing leagues to expand fleet procurement for broadcast-ready events.
- Shenzhen Component Ecosystems:Vertical assembly concentration in China's Pearl River Delta controls global cost structures for brushless motors and lithium polymer configurations.
Market Restraints
- Lithium Polymer Volatility:Battery cell price swings and shipping classification restrictions constrain margin stability for manufacturers dependent on high-discharge configurations.
- Frequency Allocation Friction:MIIT radio-frequency certifications in China and FCC spectrum rules in the United States create fragmented hardware SKUs that dilute production scale.
- Thrust-to-Weight Ceilings:Physical limits near 10:1 ratios restrict competitive differentiation through motor technology alone, compressing premium pricing power.
Strategic Opportunities
- Ready-to-Fly Segment Expansion:Pre-configured drones are capturing hobbyist pilots seeking reduced assembly barriers, opening volume channels beyond custom-build professionals.
- Aerial Cinematography Convergence:Racing platforms with stabilized camera mounts are unifying competitive and commercial capture applications, broadening addressable use cases.
- CE Marking Pathways:EASA open-category drone regulations in Europe are creating streamlined conformity routes that reduce time-to-market for EU-bound manufacturers.
Industry Challenges
- FPV Pilot Certification Gaps:Racing leagues face shortages of broadcast-qualified operators capable of maintaining frame rates under competitive pressure conditions.
- Remote ID Integration Complexity:Hardware redesigns to embed broadcast modules are extending product development cycles and straining engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Racing Drone Market |
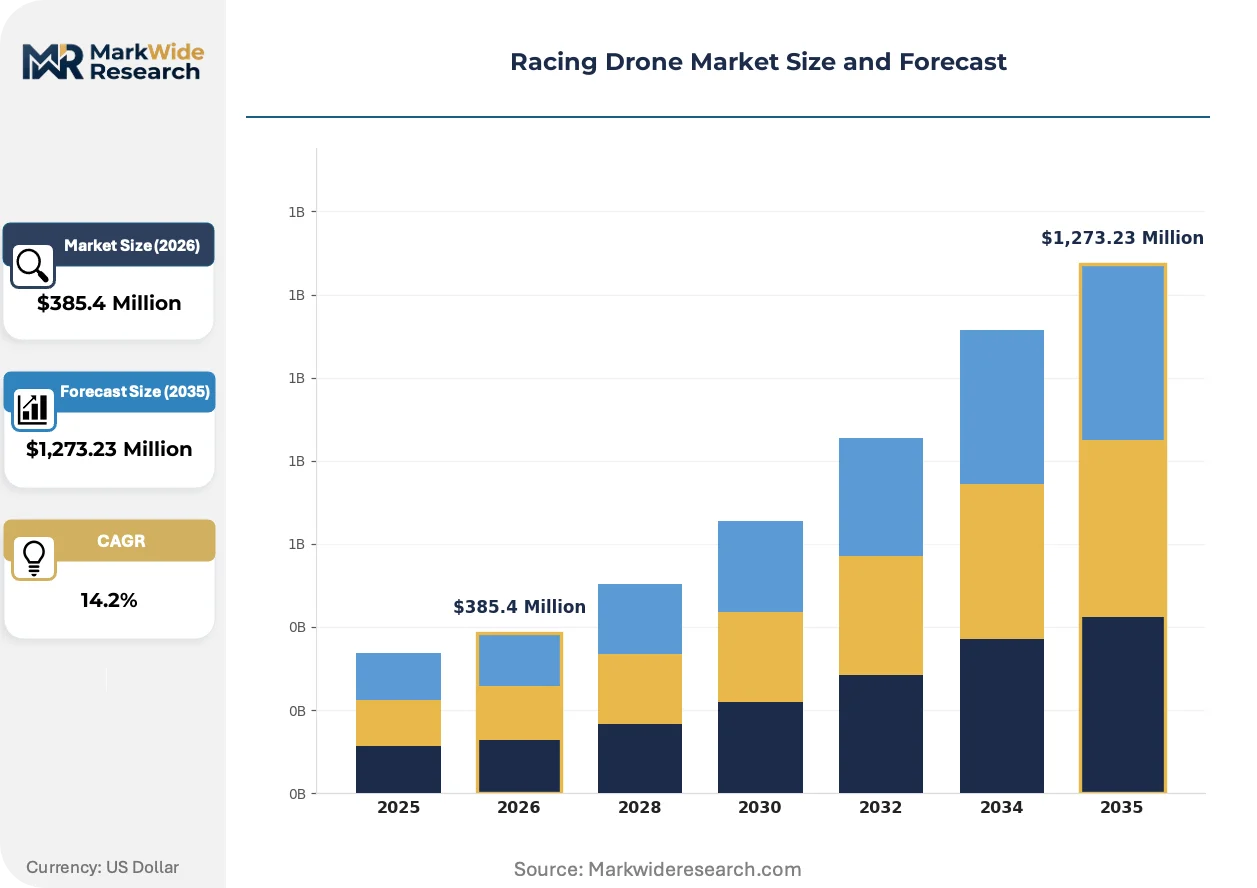
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,273.23 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Micro Drones, Mini Drones, FPV Drones, Custom Built Drones, Ready-to-Fly Drones Technology: First-Person View, GPS Assisted, Autonomous Flight, Brushless Motors, Lithium Polymer Batteries Application: Competitive Racing, Aerial Cinematography, Freestyle Flying, Training, Research Development End User: Professional Pilots, Hobbyists, Educational Institutes, Racing Leagues, Event Organizers |
| Companies Covered | GEPRC, Potensic, UVify, Hubsan, Autel Robotics, DJI, Caddx, Freefly Systems, iFlight, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Racing Drone Market Strategic Shifts & Innovations
Digital video transmission protocols are unifying previously separate hardware layers, while regulatory mandates force concurrent firmware and physical redesigns. These forces are compressing product lifecycles and reshaping competitive differentiation.
Digital FPV systems are unifying video transmission, telemetry, and control link protocols onto single-chip architectures. Professional racing teams are adopting these integrated modules to reduce interference susceptibility and simplify field repairs. This convergence is unifying previously fragmented component supply chains and compressing aftermarket upgrade cycles.
FAA Remote ID mandates are requiring broadcast modules on all drones above 250 grams, forcing manufacturers to redesign power distribution boards and antenna placement. Hardware vendors must certify firmware architectures that transmit location and identification data without compromising flight performance. Racing-focused manufacturers serving the United States are responding with modular add-on systems that preserve frame geometry for international SKUs.
League-based procurement is consolidating previously fragmented hobbyist demand into volume contracts with standardized specifications. Professional racing organizations are specifying thrust-to-weight minimums and battery connector standards that freeze component choices for entire seasons. This concentration is most visible in China, where Shenzhen manufacturers are dedicating production lines to league-certified configurations.
Racing Drone Market Segmentation
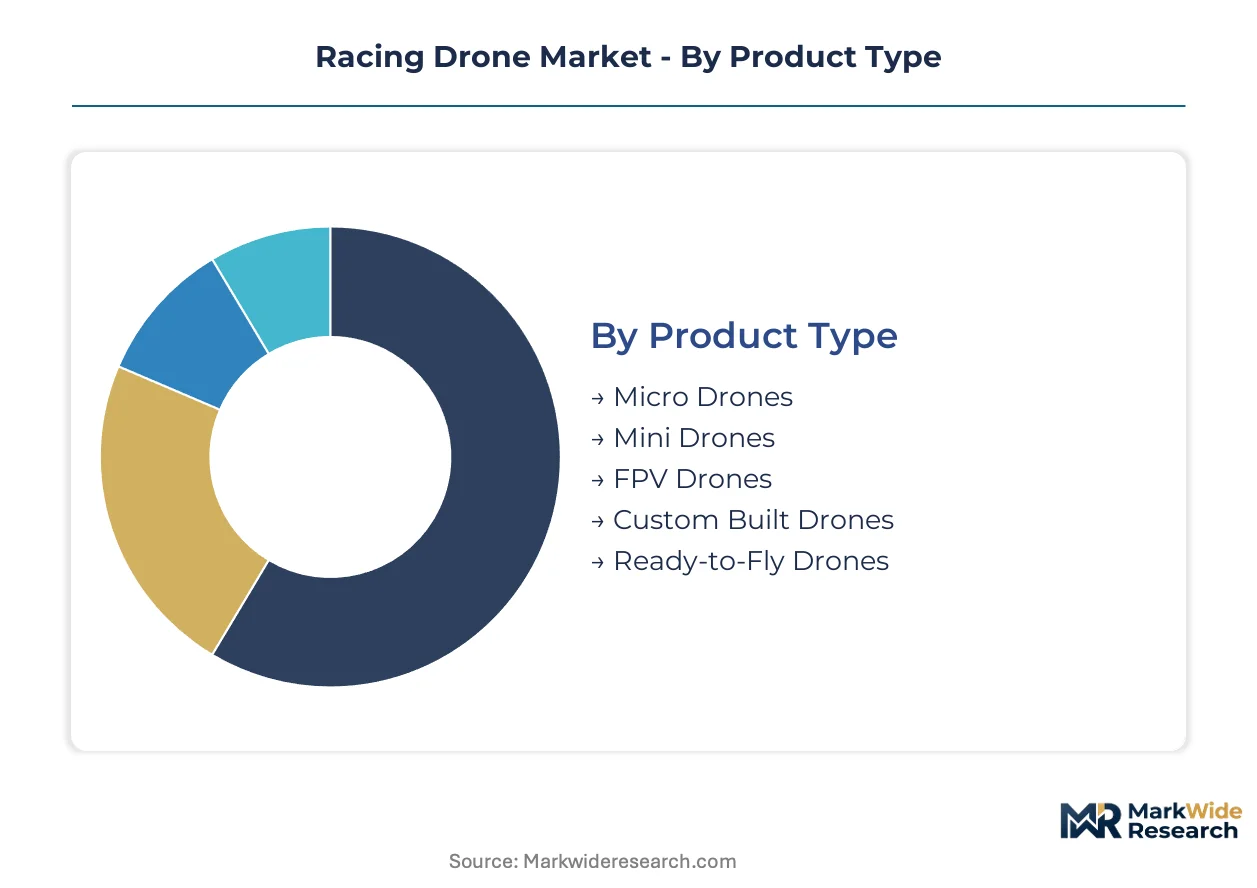
Racing drone segmentation reveals how pilot skill levels, technical complexity, and regulatory constraints fragment demand across distinct hardware configurations. Each dimension—product architecture, flight technology, use case, and buyer type—creates separate margin pools and procurement channels.
Product Type:
Standalone units dominate hobbyist entry points while embedded component ecosystems serve professional racing leagues seeking standardized fleet specifications.
- FPV Drones:These first-person-view platforms integrate immersive video transmission with ultra-low latency protocols below 20 milliseconds. Racing leagues in China and the United States concentrate procurement here, driven by broadcast-ready specifications for spectator events.
- Ready-to-Fly Drones:Pre-configured systems eliminate assembly barriers through integrated flight controllers and calibrated motor arrays. Hobbyist pilots across Germany, Australia, and South Korea favor these units, constrained by FAA Remote ID compliance costs above 250 grams.
- Custom Built Drones:Component-level assembly delivers thrust-to-weight optimization above 8:1 ratios for competitive pilots.
- Mini Drones:Sub-250 gram configurations evade Remote ID mandates while retaining racing agility.
- Micro Drones:Indoor racing formats utilize these compact frames with reduced motor displacement.
Volume placements concentrate in Ready-to-Fly configurations; the steepest expansion trajectory belongs to FPV systems.
Technology:
Cost tier separation distinguishes premium integrated stacks from modular upgrade paths accessible to budget-constrained builders.
- First-Person View:Digital transmission protocols now unify video, telemetry, and control links onto single-chip architectures. Professional teams in Japan and the United Kingdom adopt these systems, facing frequency allocation friction between FCC and MIIT certification requirements.
- Brushless Motors:High-KV outrunner designs achieve thrust-to-weight ratios approaching physical ceilings near 10:1. Competitive racing circuits in France and Spain specify these motors, limited by lithium polymer volatility in high-discharge configurations.
- Lithium Polymer Batteries:High-C rating cells power aggressive throttle inputs during cornering sequences.
- GPS Assisted:Position hold and return-to-home functions serve training applications.
- Autonomous Flight:Waypoint navigation supports research development and cinematography tracking.
Procurement patterns favor Brushless Motor integration; GPS Assisted platforms are gaining share fastest in educational deployments.
Application:
Customer type fragmentation splits recreational pilots from institutional buyers with divergent durability and support expectations.
- Competitive Racing:Organized league formats demand standardized specifications for fair competition. Event organizers in Italy and Brazil enforce thrust-to-weight minimums and battery connector standards, constrained by FPV pilot certification gaps affecting broadcast quality.
- Aerial Cinematography:Stabilized camera mounts on racing frames capture dynamic tracking shots unavailable to traditional drones. Production houses in Canada and Mexico deploy these platforms, driven by convergence between racing hardware and commercial capture requirements.
- Freestyle Flying:Acrobatic maneuvering prioritizes frame durability over pure speed metrics.
- Training:Flight schools utilize simulator-linked hardware for skill progression.
- Research Development:Universities test control algorithms and materials science on racing platforms.
Revenue concentration sits with Competitive Racing; Aerial Cinematography climbs the fastest as production budgets adopt drone-native capture.
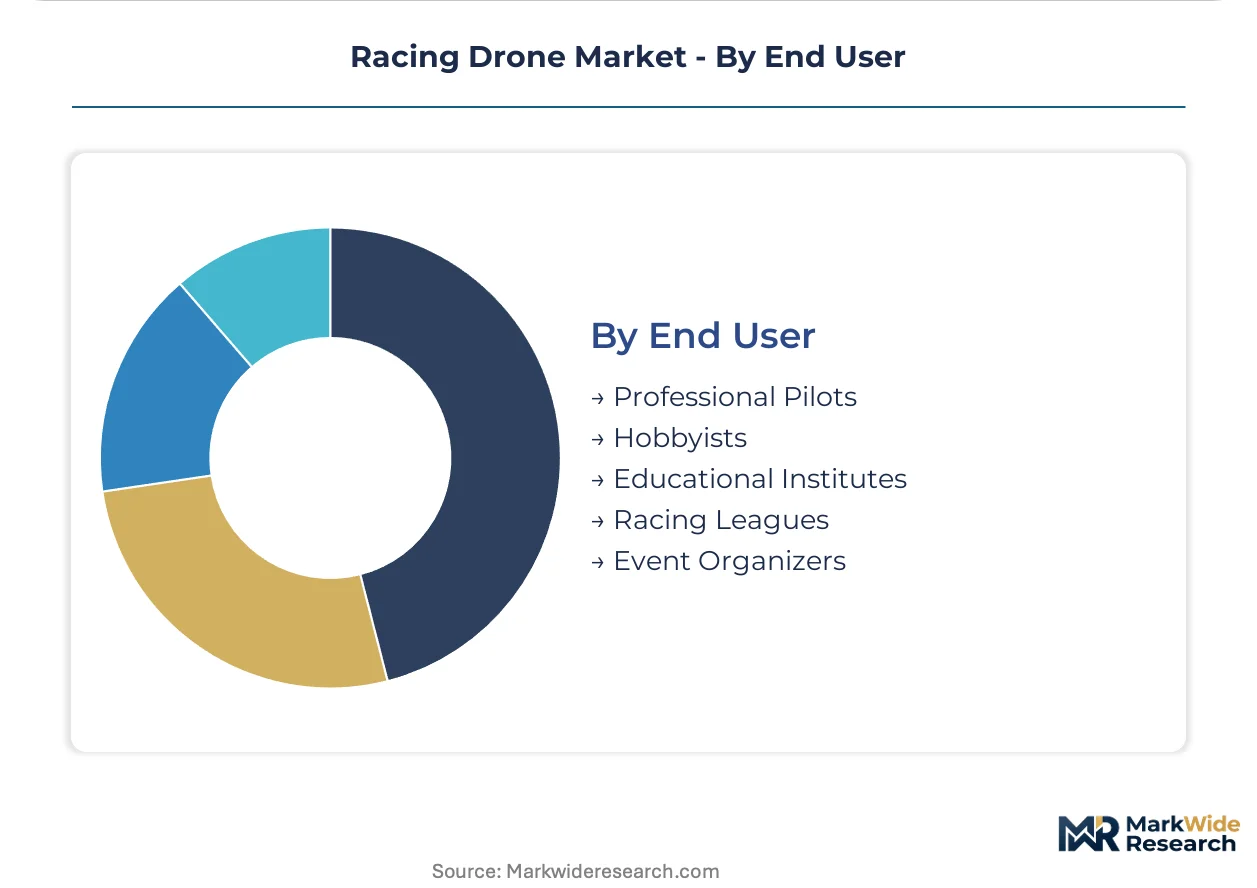
End User:
Supply concentration patterns align component sourcing with volume scale—racing leagues consolidate demand while hobbyists fragment across direct-to-consumer channels.
- Racing Leagues:Professional organizations negotiate fleet procurement with standardized seasonal specifications. Multi-drone Racing League contracts in the United States and Drone Champions League agreements in Europe freeze component choices, accelerating league-certified production lines in Shenzhen.
- Professional Pilots:Individual competitors demand component-level optimization for specific track geometries. Pilots in the Netherlands and Sweden source custom frames, limited by Remote ID integration complexity extending development cycles.
- Hobbyists:Recreational pilots drive ready-to-fly volume through reduced technical barriers.
- Educational Institutes:Universities and flight schools procure training fleets with simulator compatibility.
- Event Organizers:Temporary racing installations require rental and lease arrangements.
Contract value concentrates with Racing Leagues; Hobbyist channels expand most quickly as price points decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates manufacturing scale through Shenzhen-based component ecosystems that supply global assembly operations. The United States and Germany anchor Western demand through racing league procurement and hobbyist channels. Regulatory fragmentation across FAA, EASA, and MIIT jurisdictions shapes hardware design requirements.
United States
Professional racing leagues and FPV hobbyists drive procurement volume through broadcast-ready specifications. FAA Remote ID mandates for drones above 250 grams force hardware redesigns and firmware architecture upgrades. California and Texas host racing event organizers and component distributors serving domestic pilots.
China
Shenzhen-based vertical assembly controls global cost structures for brushless motors and lithium polymer configurations. MIIT radio-frequency certifications govern export-bound manufacturing and frequency allocation compliance. The Pearl River Delta concentrates frame fabrication, flight controller integration, and battery cell sourcing.
Germany
Hobbyist pilots and educational institutes favor ready-to-fly configurations with reduced assembly barriers. EASA CE marking and open-category drone regulations impose conformity requirements for EU market access. Bavaria and North Rhine-Westphalia host racing clubs and flight schools procuring training fleets.
Japan
Professional teams adopt digital FPV systems with unified video and telemetry protocols. METI standards and radio equipment regulations shape hardware certification pathways. Tokyo and Osaka anchor demand for high-performance racing components and simulator-linked training platforms.
United Kingdom
Freestyle pilots and competitive racers source custom frames for specific track geometries. CAA drone regulations and frequency allocation rules determine operational airspace for racing events. London and the Midlands concentrate pilot communities and component retailers serving enthusiast segments.
Racing Drone Market Key Industry Players
League-certified production line dedication dominates the current landscape as manufacturers freeze component choices for seasonal specifications. The vendor base stratifies across integrated flight controller ecosystems, specialized frame fabricators, and component module suppliers. Three archetypes prevail: Shenzhen-based vertical assemblers controlling cost structures, premium ready-to-fly system integrators, and custom build component specialists. Competitive moves center on modular Remote ID add-on systems and league procurement contract capture.
Within the integrated ecosystem tier, DJI occupies a position exemplifying premium ready-to-fly configuration dominance. iFlight and GEPRC represent Shenzhen-based specialists in racing frame geometry and vertical assembly scale. These three anchors illustrate how geographic concentration and product architecture differentiation fragment competitive positioning across hobbyist and professional channels.
| Leading Market Players |
|---|
| GEPRC |
| Potensic |
| UVify |
| Hubsan |
| Autel Robotics |
| DJI |
| Caddx |
| Freefly Systems |
| iFlight |
| Others |
Cost & Logistics Intelligence
Carbon fiber prepreg costs cascade through frame fabrication tiers, compressing margins for Shenzhen assemblers serving hobbyist channels while league-certified manufacturers capture premium pricing through Remote ID-compliant module integration.
Pricing Analysis
Volume placements concentrate in ready-to-fly configurations where Shenzhen-based vertical assembly achieves cost compression, while custom-built platforms command premium pricing through thrust-to-weight optimization above 8:1 ratios. Price differentiation separates FCC-certified units for the United States from MIIT-compliant configurations for China, with the former bearing hardware redesign costs for Remote ID broadcast modules. Pricing pressure stems from lithium polymer volatility in high-discharge battery cells, eroding margin stability across mid-tier manufacturers. Hobbyist pilots exhibit highest price sensitivity, prioritizing pre-calibrated motor arrays over component-level customization, while racing leagues absorb premium pricing for standardized fleet specifications.
Supply Chain Analysis
CE marking and FCC certification requirements gate market access, forcing manufacturers to maintain parallel hardware SKUs that fragment production scale. Component sourcing concentrates in China, South Korea, and Taiwan, with Shenzhen controlling brushless motor fabrication, Seoul-area suppliers dominating lithium polymer cell production, and Taipei-based foundries producing flight controller chipsets. Raw material dependencies include carbon fiber from Japanese Toray facilities, rare-earth magnets from Chinese processing operations, and copper windings for motor stators. Single-source vulnerability pervades high-KV outrunner motor supply, where qualified suppliers number fewer than ten globally. Distribution runs through direct-to-consumer channels for hobbyists and volume contracts for racing leagues.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where FAA Remote ID mandates erect barrier-to-entry moats favoring incumbents with certified firmware architectures and modular hardware platforms.
For Market Incumbents: Anchor defensive positioning through backward integration into flight controller chipset supply, securing allocation priority from Taipei foundries amid semiconductor capacity constraints. Deepen league procurement relationships by dedicating production lines to seasonal thrust-to-weight specifications, freezing component choices to lock out modular competitors. Counter emerging Shenzhen-based challengers through FCC certification speed advantages that compress rival time-to-market by 6-12 months.
For New Entrants and Emerging Players: EASA's open-category drone regulations in Europe open a window for streamlined CE marking pathways that bypass the FCC's more burdensome Remote ID hardware requirements. Target German and French hobbyist channels with sub-250 gram mini drone configurations that evade broadcast module costs entirely. Pursue simulator-linked training platform partnerships with educational institutes as a go-to-market angle that builds pilot ecosystem attachment before competitive racing conversion.
For Investors and Strategic Acquirers: League fleet procurement contract announcements are the leading indicator that manufacturer revenue visibility is transitioning from hobbyist volatility to institutional recurrence. Frame long-term viability around the 5-10 year horizon of regulatory harmonization pressure, where dual-certified hardware platforms command scarcity premiums. Prioritize acquisition targets with existing FCC and MIIT parallel certifications rather than single-jurisdiction players facing costly retrofit cycles. Monitor frequency allocation rule changes as the critical signal for hardware SKU rationalization opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Remote ID Module Integration | FAA-compliant firmware architectures embed broadcast capabilities without compromising thrust-to-weight ratios for racing performance. |
| League Certification Pathway | Multi-drone Racing League contracts freeze component specifications and dedicate production lines to standardized fleet configurations. |
| Carbon Fiber Frame Fabrication Scale-Up | Shenzhen vertical assembly controls weight-to-strength economics through captive supply of Toray-sourced prepreg materials. |
| Digital FPV Protocol Adoption | Single-chip architectures unify video transmission, telemetry, and control links, reducing interference susceptibility for professional teams. |
| Sub-250 Gram Product Line Expansion | Mini drone configurations evade Remote ID mandates while retaining racing agility for European and Asian hobbyist channels. |
Research Approach
Independent corroboration across racing league procurement officers, Shenzhen-based component manufacturers, FPV system integrators, and professional racing pilots underwrites the qualitative findings in this study. Primary interviews with league technical directors, flight controller firmware engineers, and brushless motor procurement leads at tier-one assemblers combined with secondary validation from FCC equipment authorization databases, EASA conformity assessment documentation, and MIIT radio transmission equipment filings. Bottom-up triangulation across product-level bill-of-materials analysis and top-down reconciliation against league fleet deployment disclosures anchored volume estimates.
Comparable historical reference periods spanning technology adoption cycles in adjacent unmanned aerial vehicle segments anchored the forecast window across the projection horizon. The analytical framework modeled segmentation dimensions including product architecture, flight technology protocol, competitive versus commercial application, and buyer type concentration. CAGRs derived from regression analysis against regulatory compliance cost trajectories and materials substitution patterns in frame fabrication, with inputs from lithium polymer cell pricing indices and carbon fiber composite supply curves.
The model assumes a particular technology adoption path for digital FPV protocol migration; alternative pathways for analog transmission persistence would alter the outlook through extended aftermarket upgrade cycle compression. Forecasts reflect assumptions regarding FAA enforcement consistency, EASA harmonization timing, and Shenzhen labor cost trajectories. A model refresh is warranted upon material change in frequency allocation rules or airspace classification for competitive racing events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
North America Fuel Cell UAV Market
UAV
Airborne Digital Battlefield Market
UAV
Global Drone Services Market
UAV
Drone-Based Consulting Services Market
UAV
North America Drone Software Market
UAV
UAV Market
UAV
Drone Tracking Antenna Market
UAV
Short-Range Delivery Drone Market
UAV
Counter Drone System Market
UAV
UAV Lidar Market
UAV
UAV Simulator Market
UAV
Military UAV Sensor Market
UAV
Utility Drone Market
UAV
Military Unmanned Aerial Vehicles Market
UAV
Counter-UAS Market
UAV
Europe Drone Services Market