
 Connected Retail Market | 2026-2036
Connected Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Retail Market Analysis
GDPR is hardening the cost-of-entry calculus for connected retail vendors serving European omnichannel retailers. Cisco Systems leverages its networking hardware dominance to anchor edge-computing deployments in physical stores. Microsoft Corporation competes through Azure cloud services that sustain real-time inventory analytics across thousands of locations. Zebra Technologies specializes in RFID and mobile computing hardware that controls the frontline data-capture layer.
Connected retail denotes the integration of IoT sensors, RFID infrastructure, cloud platforms, and AI-driven analytics into brick-and-mortar and omnichannel commerce environments, typically operating on sub-100-millisecond latency thresholds to enable real-time shelf monitoring and personalized customer engagement. Its primary commercial purpose is to collapse the information gap between physical inventory states and digital demand signals, thereby reducing stockouts and labor redundancy. Smart shelves and IoT sensors occupy the highest-margin hardware tier because they generate continuous telemetry that anchors recurring software subscriptions. Cloud Computing and Artificial Intelligence represent the fastest-expanding technology layers, as retailers shift capital from on-premise servers to elastic infrastructure that scales with transaction volatility. Small Retailers and Large Retail Chains diverge sharply in deployment architecture, with the former favoring modular SaaS bundles and the latter demanding customized enterprise integrations.
The EU AI Act, GDPR, and the EU Green Deal collectively shape product standards and market access for connected retail systems deployed across European stores, particularly by mandating algorithmic transparency and energy-efficiency disclosures for in-store AI applications. In the United States, the FTC and state-level biometric privacy laws impose parallel constraints on facial-recognition analytics and customer data retention practices. Stakeholders must monitor whether emerging sector-specific AI liability frameworks in Brussels and Washington force architectural redesigns of real-time customer-tracking systems before the next procurement cycle locks in long-term vendor commitments.
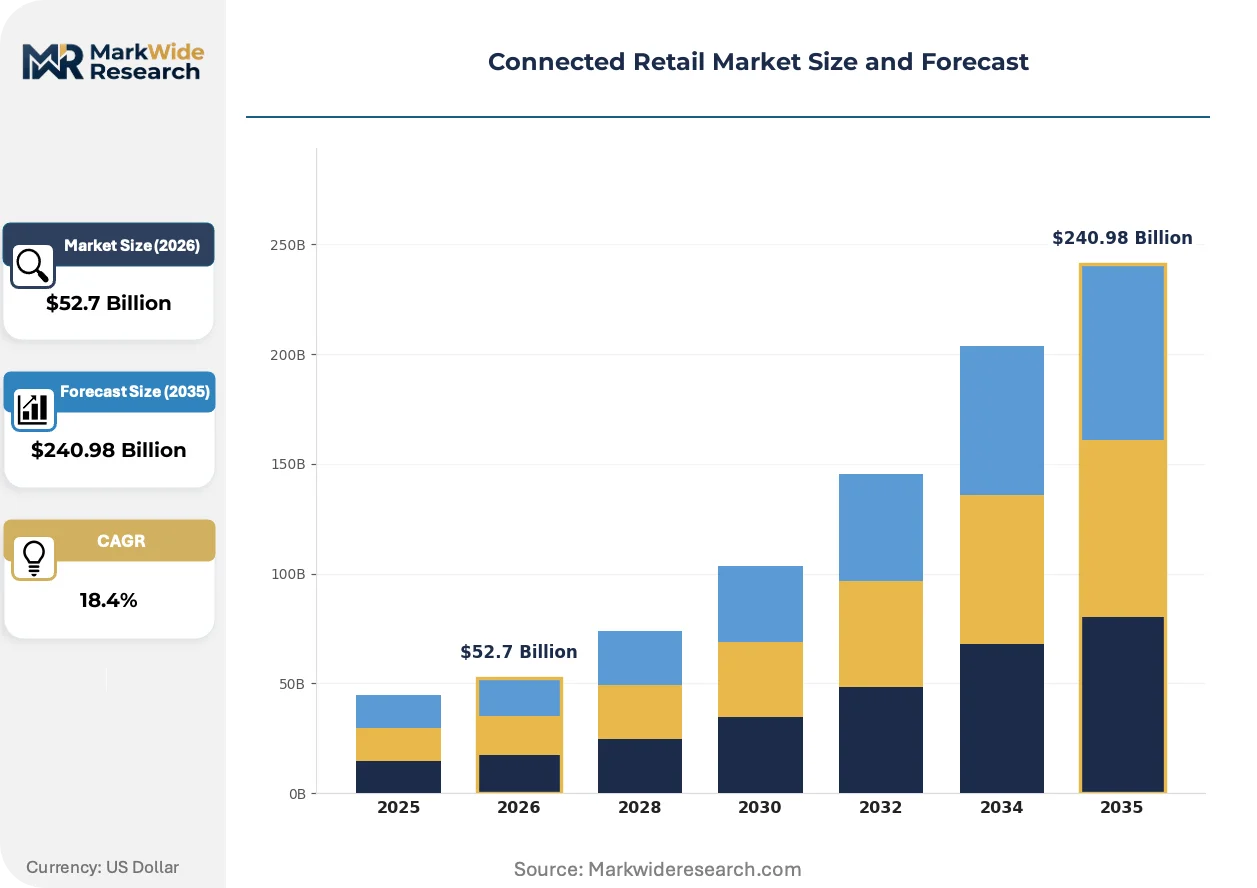
Market Dynamics
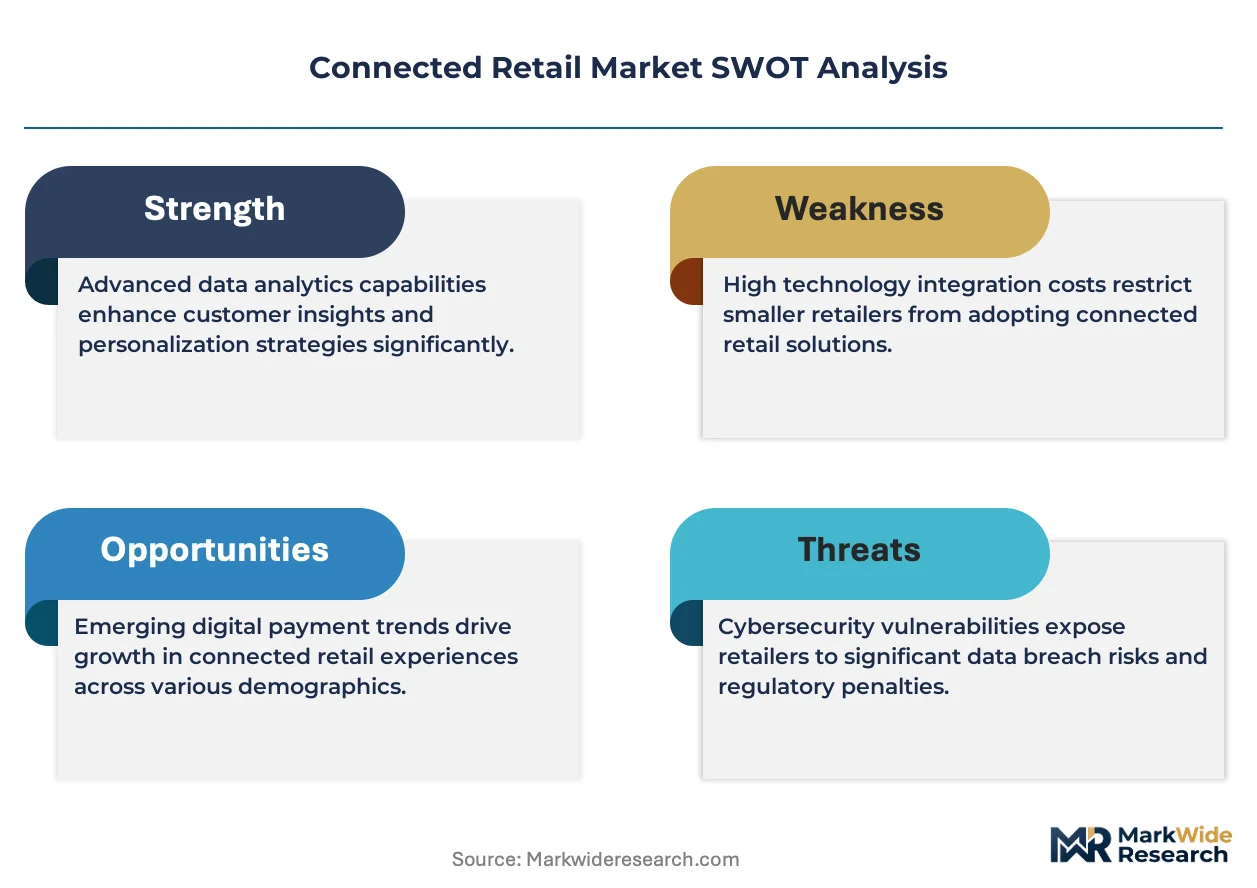
The EU AI Act and GDPR compliance obligations are hardening data governance requirements for in-store analytics platforms, forcing architectural redesigns of real-time customer-tracking systems before procurement cycles lock in long-term vendor commitments.
Growth Catalysts
- RFID Infrastructure:Grocery chains deploy smart shelves and IoT sensors to cut spoilage and restock labor. The hardware generates continuous telemetry that anchors recurring software subscriptions.
- EU Green Deal:Energy-efficiency disclosures for in-store AI applications accelerate hardware refresh cycles. Retailers replace legacy sensor networks to meet mandated carbon reporting thresholds.
- United States:Walmart and Target anchor omnichannel infrastructure spending. Their procurement volume validates edge-computing architectures for mid-tier retailers.
Market Restraints
- GDPR Compliance Costs:Algorithmic transparency mandates harden the cost-of-entry calculus for connected retail vendors serving European omnichannel retailers. Smaller players exit or consolidate.
- Semiconductor Supply Concentration:Edge-computing chip fabrication concentrates in East Asian foundries. Geopolitical friction threatens hardware delivery timelines for sensor deployments.
- Legacy System Interoperability:Sub-100-millisecond latency thresholds for real-time shelf monitoring require protocol translation layers. Integration complexity extends deployment timelines.
Strategic Opportunities
- Small Retailer SaaS Bundles:Modular cloud platforms displace on-premise servers for capital-constrained independents. Elastic infrastructure scales with transaction volatility without upfront hardware investment.
- FTC Biometric Privacy Rules:State-level facial-recognition restrictions create first-mover advantage for privacy-preserving computer vision. Vendors offering anonymized analytics capture preference share.
- AI-Cloud Convergence:Real-time inventory analytics shift from edge-only to hybrid architectures. Retailers balance latency requirements against centralized model training efficiency.
Industry Challenges
- Edge-AI Talent Scarcity:Deployment of sub-100-millisecond inference pipelines requires specialized firmware engineers. Retailers compete with automotive and industrial sectors for embedded systems expertise.
- Multi-Vendor Integration Complexity:Cisco networking hardware, Azure cloud services, and Zebra RFID systems must synchronize across heterogeneous technology stacks. Standardization delays prolong commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Retail Market |
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $240.98 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Shelves, RFID Tags, IoT Sensors, Mobile Payment Solutions Technology: Cloud Computing, Augmented Reality, Artificial Intelligence, Machine Learning Customer Type: Small Retailers, Large Retail Chains, E-commerce Platforms, Omnichannel Retailers End User: Consumers, Retail Staff, Supply Chain Managers, Marketing Teams |
| Companies Covered | Cisco Systems, Honeywell International, IBM Corporation, Microsoft Corporation, Intel Corporation, NXP Semiconductors, Zebra Technologies, SAP SE, PTC Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Retail Market Emerging Trajectories
Cloud Computing and Artificial Intelligence represent the fastest-expanding technology layers as retailers shift capital from on-premise servers to elastic infrastructure that scales with transaction volatility.
Computer vision systems are integrating depth-sensing cameras and thermal imaging into smart shelf arrays. Large retail chains deploy these sensor fusion stacks to detect product misplacement and temperature excursions simultaneously. The technology is integrating shelf-edge analytics with centralized demand forecasting, collapsing replenishment cycles from days to hours.
The EU AI Act mandates algorithmic transparency for automated decision-making in customer-facing retail applications. Deployers must maintain technical documentation and human oversight protocols for real-time personalization engines. European grocery chains are responding by segregating AI inference workloads between transparent recommendation systems and black-box demand forecasting.
Buyer procurement patterns are compressing vendor evaluation cycles as competitive pressure accelerates technology refresh timelines. Retailers now pilot edge-computing solutions in 90-day sprints rather than 12-month proofs-of-concept. This pattern is most visible in the United States, where Target and Walmart's rapid deployment schedules force mid-tier chains into defensive catch-up investments.
Connected Retail Market Segmentation
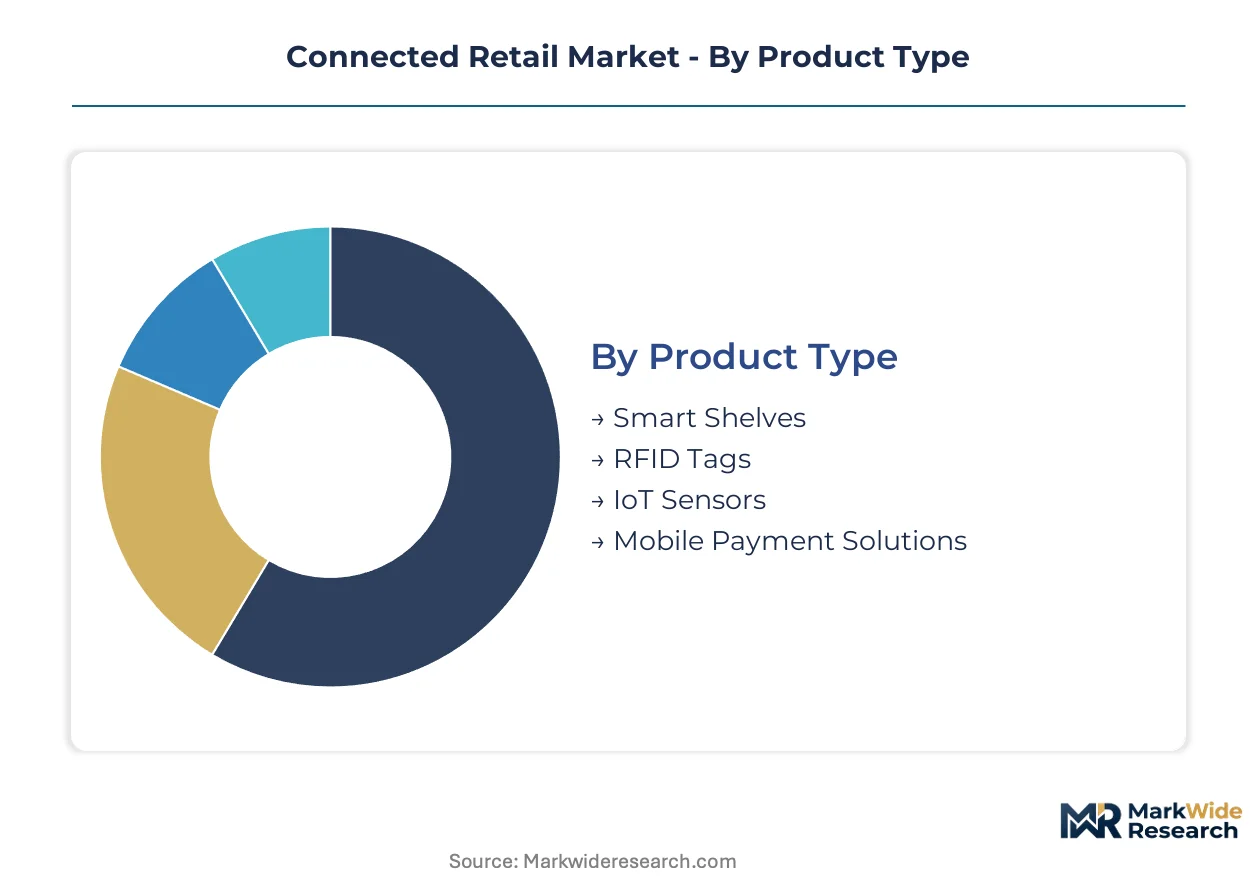
Connected retail deployments fragment sharply by capital intensity and technical sophistication, with hardware-heavy segments demanding multi-year amortization cycles while software layers scale through recurring subscriptions. Procurement patterns diverge between asset-heavy grocery chains and cloud-native independents, reshaping vendor pricing architectures across each category.
Product Type:
Smart shelves and RFID infrastructure command the highest upfront capital commitments, requiring dedicated installation teams and legacy system retrofitting.
- Smart Shelves:Embedded weight sensors and computer vision arrays generate continuous telemetry on product availability and placement accuracy. Walmart and Target deployments in the United States validate edge-computing architectures that mid-tier chains now replicate. Hardware margins anchor recurring software subscriptions for inventory analytics.
- RFID Tags:Passive and active radio-frequency identification enables item-level tracking from distribution center to point-of-sale. Apparel and electronics retailers concentrate demand in the United States and Germany, driven by loss-prevention mandates and omnichannel fulfillment accuracy requirements.
- IoT Sensors:Temperature, humidity, and proximity detectors monitor environmental conditions and foot traffic patterns.
- Mobile Payment Solutions:NFC and QR-code terminals integrate loyalty programs with transaction processing.
Smart shelves absorb the bulk of installed capacity; RFID tags are expanding most quickly.
Technology:
Cloud platforms displace on-premise servers fastest among capital-constrained customer segments, while AI layers concentrate in enterprise deployments.
- Cloud Computing:Elastic infrastructure scales compute resources with transaction volatility, eliminating upfront server investments. Small retailers in the United States and France favor modular SaaS bundles over customized enterprise integrations.
- Artificial Intelligence:Real-time demand forecasting and personalization engines require sub-100-millisecond latency thresholds. European grocery chains segregate inference workloads to satisfy EU AI Act algorithmic transparency mandates.
- Augmented Reality:Virtual try-on and navigation applications overlay digital information on physical store environments.
- Machine Learning:Predictive models optimize pricing and assortment decisions from historical transaction data.
Cloud computing dominates current procurement volumes; artificial intelligence shows the steepest expansion trajectory.
Customer Type:
Enterprise-scale deployments demand bespoke integration services, while smaller accounts standardize on pre-configured bundles.
- Large Retail Chains:Customized ERP integrations and multi-site rollouts require dedicated project management and protocol translation layers. Target and Walmart procurement schedules compress vendor evaluation cycles to 90-day sprints.
- Omnichannel Retailers:Unified commerce platforms collapse inventory visibility across digital and physical channels. French and German fashion retailers lead European adoption, pressured by GDPR-compliant customer data synchronization requirements.
- Small Retailers:Modular SaaS bundles minimize technical complexity and capital outlay.
- E-commerce Platforms:Click-and-collect infrastructure bridges fulfillment networks with physical pickup locations.
Large retail chains command the greatest vendor attention; omnichannel retailers are gaining share fastest.
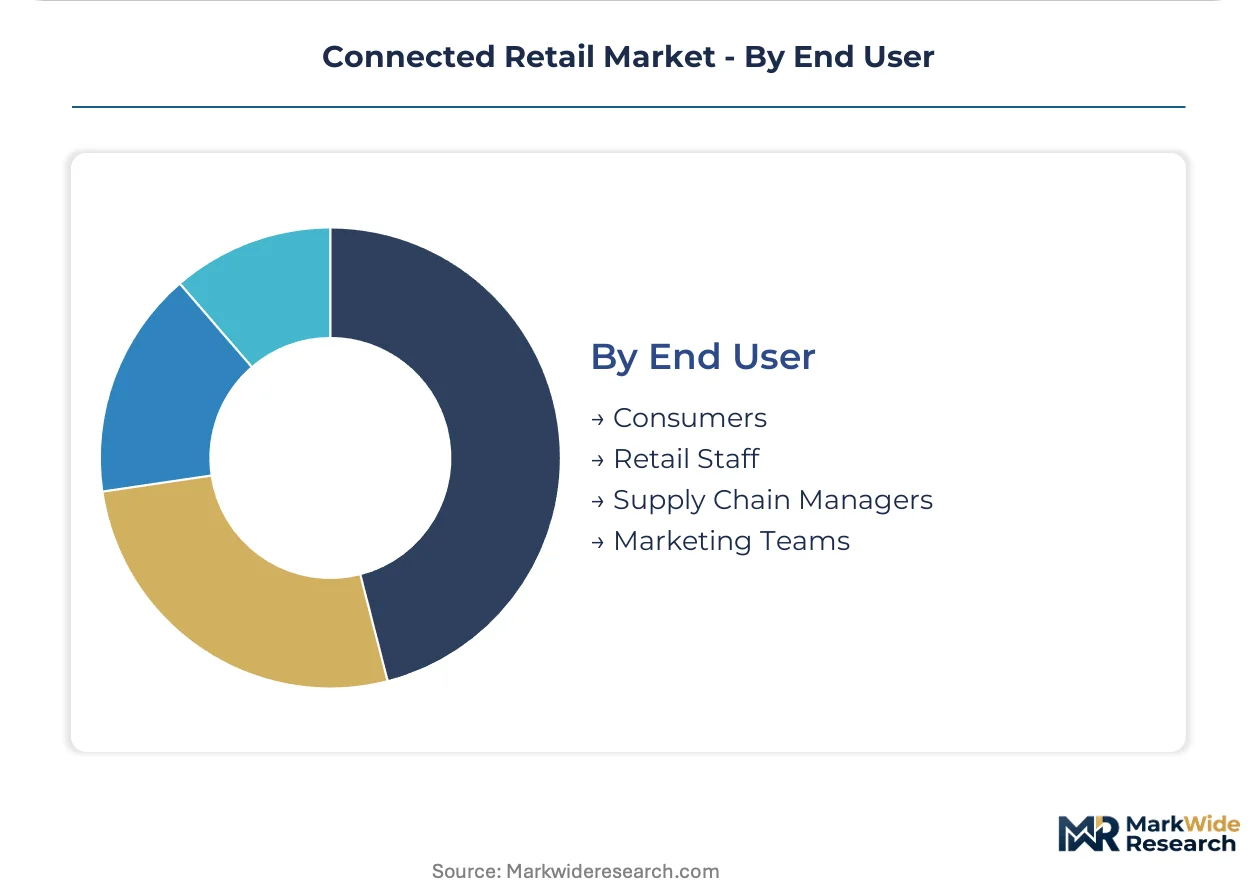
End User:
Operational roles drive hardware procurement, while analytical functions expand software licensing.
- Retail Staff:Mobile computing devices and real-time inventory dashboards reduce restock labor and improve task routing. Zebra Technologies hardware dominates frontline data-capture deployments in the United States.
- Supply Chain Managers:End-to-end visibility platforms integrate warehouse management with in-store stock levels. German automotive parts retailers exemplify demand for RFID-enabled reverse logistics tracking.
- Consumers:Self-checkout and personalized promotion interfaces shape purchasing decisions.
- Marketing Teams:In-store analytics platforms attribute foot traffic to campaign performance.
Retail staff absorb the majority of device deployments; supply chain managers are expanding analytics adoption most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Connected retail infrastructure spending concentrates in the United States, where Walmart and Target validate edge-computing architectures that mid-tier chains replicate. Procurement volume from these anchors compresses vendor evaluation cycles and accelerates deployment timelines across North America. European demand hardens around regulatory compliance obligations, while Asian markets concentrate sensor manufacturing capacity.
United States
Walmart and Target anchor omnichannel infrastructure spending through rapid 90-day pilot sprints. The FTC and state-level biometric privacy laws impose constraints on facial-recognition analytics and customer data retention practices. Retail technology clusters in Seattle and San Francisco Bay Area drive cloud-native platform development for inventory analytics.
Germany
Automotive parts retailers and grocery chains drive RFID-enabled reverse logistics tracking and smart shelf deployments. The EU AI Act and GDPR compliance obligations mandate algorithmic transparency and energy-efficiency disclosures for in-store AI applications. Industrial IoT concentration in Bavaria and Baden-Württemberg supports sensor manufacturing and systems integration expertise.
France
Fashion retailers lead European adoption of unified commerce platforms pressured by GDPR-compliant customer data synchronization requirements. The EU Green Deal accelerates hardware refresh cycles through mandated carbon reporting thresholds for sensor networks. Paris-based retail technology firms specialize in modular SaaS bundles for capital-constrained independents.
China
Edge-computing chip fabrication concentrates in East Asian foundries, supplying hardware for global sensor deployments. National dual carbon goals and GB standards shape energy-efficiency requirements for retail IoT infrastructure. Yangtze River Delta manufacturing clusters produce weight sensors, computer vision arrays, and mobile computing devices at scale.
United Kingdom
Omnichannel retailers in London and Southeast England prioritize cloud platform migration from on-premise servers to elastic infrastructure. The UK Information Commissioner's Office enforces GDPR-aligned data governance for in-store analytics platforms. Retail technology procurement in the Midlands concentrates on protocol translation layers for legacy system interoperability.
Connected Retail Market Vendor Landscape
United States technology conglomerates anchor one tier; European industrial specialists and semiconductor fabricators hold differentiated positions in hardware and embedded systems. Market structure consolidates around three to five dominant platform vendors controlling cloud and networking layers, with fragmentation persisting in sensor hardware and vertical-specific applications. Strategic archetypes include networking infrastructure incumbents, cloud platform providers, and frontline data-capture hardware specialists. Competitive dynamics center on M&A activity consolidating point-solution vendors and strategic partnerships binding hardware manufacturers to cloud service ecosystems.
Within the networking infrastructure tier, Cisco Systems occupies a position exemplifying edge-computing deployment anchoring in physical retail environments. Microsoft Corporation represents the cloud platform archetype through Azure services sustaining real-time inventory analytics across distributed locations. Zebra Technologies sits within the frontline data-capture specialist category, with its corporate identity signaling concentration in RFID and mobile computing hardware layers. These three anchors collectively illustrate the technology stack segmentation—networking, cloud, and edge hardware—that structures vendor competition in connected retail deployments.
| Leading Market Players |
|---|
| Cisco Systems |
| Honeywell International |
| IBM Corporation |
| Microsoft Corporation |
| Intel Corporation |
| NXP Semiconductors |
| Zebra Technologies |
| SAP SE |
| PTC Inc. |
| Others |
Supply Flow & Price Mechanics
Edge-computing chip fabrication migration toward advanced-node processes simultaneously compresses unit economics for sensor hardware and concentrates supply among East Asian foundries. This dual effect tightens vendor margins while amplifying procurement leverage for retailers deploying smart shelf arrays at scale.
Pricing Analysis
Volume deployments by Walmart and Target in the United States anchor the high-volume, low-margin tier, while European grocery chains absorbing GDPR compliance costs tolerate premium pricing for certified data-governance modules. Price differentiation hinges on latency certification tiers and software subscription bundling. Pricing pressure stems from semiconductor supply concentration forcing hardware vendors to absorb foundry cost pass-throughs. Small retailers exhibit highest price sensitivity, deferring edge-computing investments until modular SaaS bundles reach sub-thousand-dollar entry points.
Supply Chain Analysis
CE marking and FCC certification gates filter hardware vendors before they reach procurement lists at Target, Walmart, or German automotive parts retailers. Supply concentrates in China, Taiwan, and South Korea for edge-computing chips, weight sensors, and computer vision arrays. Raw material dependencies include silicon wafers, rare-earth magnets for RFID antennas, and lithium for mobile computing power cells. Single-source vulnerability in advanced-node fabrication threatens delivery timelines for sub-100-millisecond latency hardware. Distribution runs through direct enterprise sales teams for large retail chains and value-added resellers for small retailer SaaS bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected retail hardware supply is constrained by East Asian foundry capacity allocation favoring automotive and AI datacenter demand, propping pricing for qualified sensor vendors serving European and North American deployment schedules.
For Market Incumbents: Anchor defensive positioning through backward integration into edge-computing firmware development and captive certification laboratories to accelerate CE marking timelines. Consolidate point-solution vendors in computer vision and RFID middleware to neutralize emerging cloud-native challengers. Prioritize capacity reservations at Taiwan and South Korea foundries to secure chip supply against automotive sector competition. For New Entrants and Emerging Players: Enter via privacy-preserving computer vision modules targeting French and German fashion retailers navigating GDPR-compliant customer data synchronization requirements. White-space availability concentrates in small retailer SaaS bundles displacing on-premise servers across the United States and France. Go-to-market leverage rests on 90-day pilot sprint compatibility with Target and Walmart procurement schedules. For Investors and Strategic Acquirers: Re-rating potential sits with edge-AI firmware specialists given EU AI Act algorithmic transparency mandates forcing architectural redesigns of real-time customer-tracking systems. Long-term viability favors vendors controlling both sensor hardware and cloud analytics layers across the analysis window. Watch for FTC biometric privacy rule expansions as signal for privacy-preserving analytics preference inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Firmware Development | Cisco and Zebra anchor real-time inventory analytics through sub-100-millisecond latency pipelines. |
| GDPR Compliance Certification | Microsoft Azure and SAP SE sustain European grocery chain deployments under algorithmic transparency mandates. |
| Privacy-Preserving Computer Vision | French retailers capture preference share by anonymizing facial-recognition analytics ahead of FTC rule expansions. |
| Modular SaaS Bundle Launch | Paris-based firms displace on-premise servers for capital-constrained independents in France and the United States. |
| RFID Middleware Integration | German automotive parts retailers enable reverse logistics tracking through NXP Semiconductors and Zebra Technologies hardware. |
Methodological Framework
SEC filings from Microsoft, Cisco, and Zebra Technologies, EU regulatory databases tracking GDPR enforcement actions, and hyperscaler capex disclosures formed the secondary backbone. Primary interviews with retail technology procurement officers at Walmart and Target, IoT platform engineers at Azure and SAP, and compliance leads navigating EU AI Act implementation were triangulated against customs data for RFID and sensor hardware trade flows. Bottom-up deployment estimates from individual retail chains were reconciled with top-down infrastructure spending projections.
Bottom-up modeling of smart shelf, RFID, and IoT sensor unit shipments across large retail chains, omnichannel retailers, and small independents was cross-checked against top-down cloud services revenue attribution. Segmentation dimensions included hardware versus software spend, deployment latency requirements, and customer type capital intensity. CAGRs were derived from installed base growth rates and replacement cycle compression observed in 90-day pilot sprint adoption patterns. Forecast inputs incorporated EU Green Deal hardware refresh mandates and FTC biometric privacy rule evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under East Asian foundry capacity reallocation or sudden EU AI Act enforcement escalation. Model outputs reflect assumptions around edge-computing chip supply continuity and retailer procurement cycle stability. A model refresh is warranted upon material change in semiconductor trade policy or GDPR penalty precedent.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
AR in Retail Market
Retail Technology
Ticket Machine Market
Retail Technology
Smart Grocery Cart Market
Retail Technology
Smart Shelf Market
Retail Technology
Customer-Facing Technology Market
Retail Technology
Retail Sourcing and Procurement Market
Retail Technology
Omni-Channel Retail Solutions Market
Retail Technology
Global Restaurant Point of Sale (POS) Terminals Market
Retail Technology
Global Advanced Shopping Technology Market
Retail Technology
Internet of Things (IoT) in Retail Market
Retail Technology
E-Retail Market
Retail Technology
Global Kiosk Market
Retail Technology
North America Automation in Retail Market
Retail Technology
America's AI in the Retail Market
Retail Technology
Cash Register Machines Market
Retail Technology
Smart Kitchen Solutions Market