
 North America Contact Adhesives Market | 2026-2036
North America Contact Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
North America Contact Adhesives Market Analytics
Aftermarket repair revenue is reconfiguring margin pools away from bulk OEM supply contracts toward specialized kit packaging and technical service bundles. Henkel AG & Co. KGaA leverages its automotive OEM relationships to sustain premium positioning in reactive adhesive systems. H.B. Fuller anchors North American volume through woodworking and construction distribution networks. 3M dominates high-performance electronics lamination with fluoropolymer-enhanced contact adhesive formulations.
Contact adhesives are one-part or two-part bonding systems applied to both substrates, dried to a tacky film, then pressed together to form immediate high-strength bonds without clamping; neoprene and polyurethane variants achieve peel strengths exceeding 25 N/mm on porous and non-porous surfaces alike. Water-based formulations are gaining share as EPA VOC limits tighten, though solvent-based systems still lead in outdoor construction and marine applications where moisture resistance and rapid tack development remain non-negotiable. Hot melt contact adhesives represent the fastest-growing product category, driven by automotive interior assembly lines in Mexico and the US Southeast that demand bond-on-demand flexibility without solvent flash-off delays.
EPA regulates volatile organic compound emissions under 40 CFR Part 59, pushing manufacturers toward water-based and reactive chemistries, while OSHA enforces permissible exposure limits for solvent vapors in workplace environments. Health Canada and PMRA coordinate cross-border chemical registration through the North American Free Trade Agreement alignment mechanisms, though post-USMCA divergence in substance approval timelines now complicates unified product launches. Stakeholders must monitor state-level California DTSC green chemistry initiatives and Ontario's Toxics Reduction Act for early signals of formulation mandates that will cascade across provincial and federal jurisdictions.
Market Dynamics
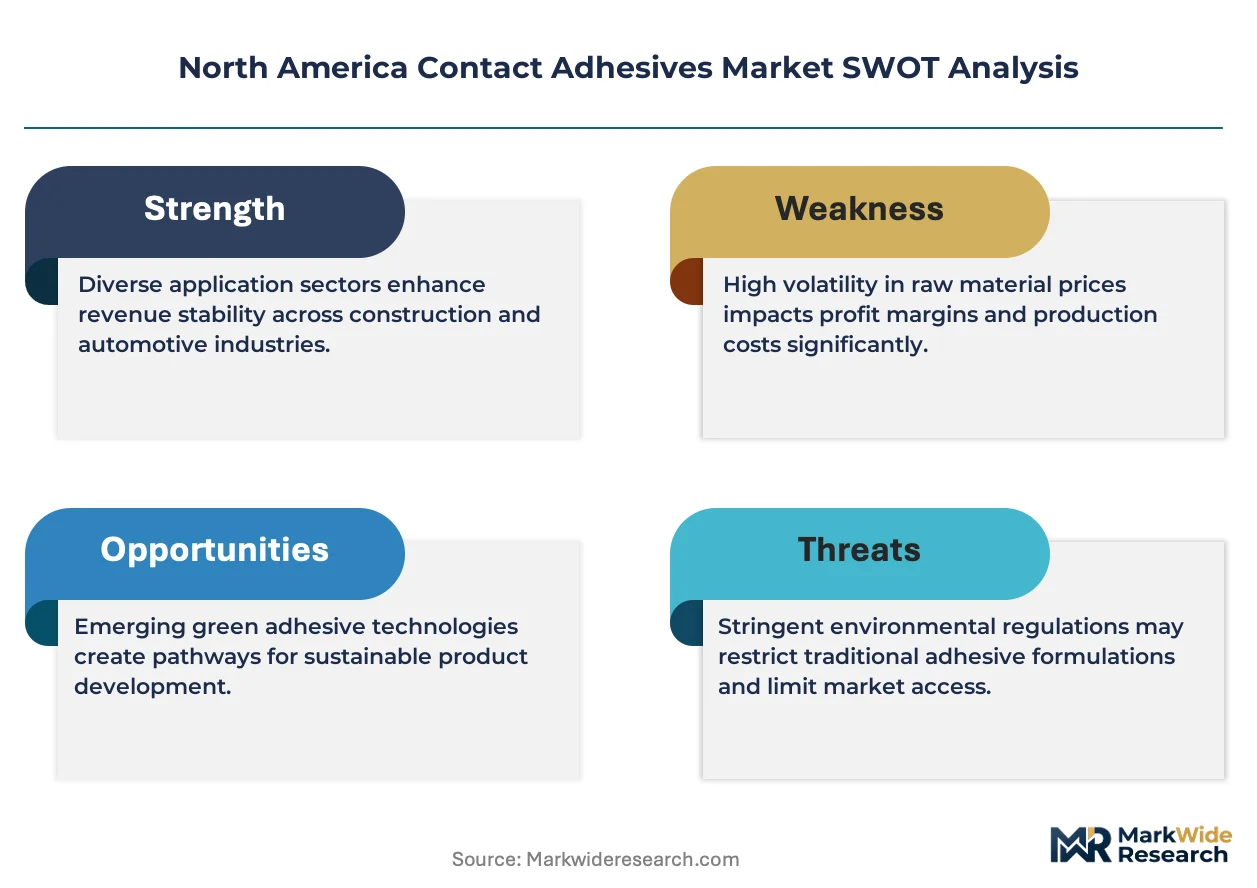
EPA VOC regulations under 40 CFR Part 59 are compressing formulation windows while automotive OEMs in Mexico and the US Southeast accelerate solvent-free adoption, creating simultaneous push-pull pressure on manufacturer R&D pipelines and capital allocation decisions.
Growth Catalysts
- OSHA workplace exposure standards:Tightening permissible exposure limits for solvent vapors are compelling facility upgrades that favor water-based and reactive adhesive systems in high-throughput manufacturing environments.
- Automotive interior assembly:Bond-on-demand flexibility requirements in Mexico and US Southeast assembly plants are expanding specification windows for hot melt contact adhesive formulations.
- Woodworking sector consolidation:Large-scale furniture and cabinetry manufacturers in Ontario's manufacturing belt are standardizing on neoprene-based systems for porous substrate bonding.
Market Restraints
- Petrochemical feedstock volatility:Crude oil price swings directly compress margins on solvent-based neoprene and polyurethane resin systems.
- US Gulf Coast supply concentration:Specialty tackifier and resin production clusters in Texas and Louisiana create geographic vulnerability to hurricane disruption and logistics bottlenecks.
- California DTSC green chemistry mandates:State-level substance restrictions are fragmenting product portfolios and extending reformulation cycles beyond standard commercial timelines.
Strategic Opportunities
- Underpenetrated marine applications:Recreational boatbuilding yards in Florida and the Great Lakes region remain dominated by mechanical fastening with limited adhesive specification penetration.
- USMCA-aligned cross-border registration:Health Canada and PMRA coordination mechanisms offer streamlined market access for US-manufactured formulations meeting joint review standards.
- Reactive polyurethane convergence with automation:Two-part systems integrating with robotic dispensing equipment are opening specification windows in precision assembly operations.
Industry Challenges
- Formulation chemist scarcity:Deep expertise in solvent-free reactive systems is concentrating at a handful of regional technical centers, constraining new product development velocity.
- Dual certification timelines:Separate EPA and Health Canada approval pathways for novel chemistries are extending commercialization cycles by 18-24 months.
- Legacy equipment retrofit costs:Water-based system conversion requires heated storage tanks and modified spray infrastructure that mid-tier applicators cannot readily finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Contact Adhesives Market |
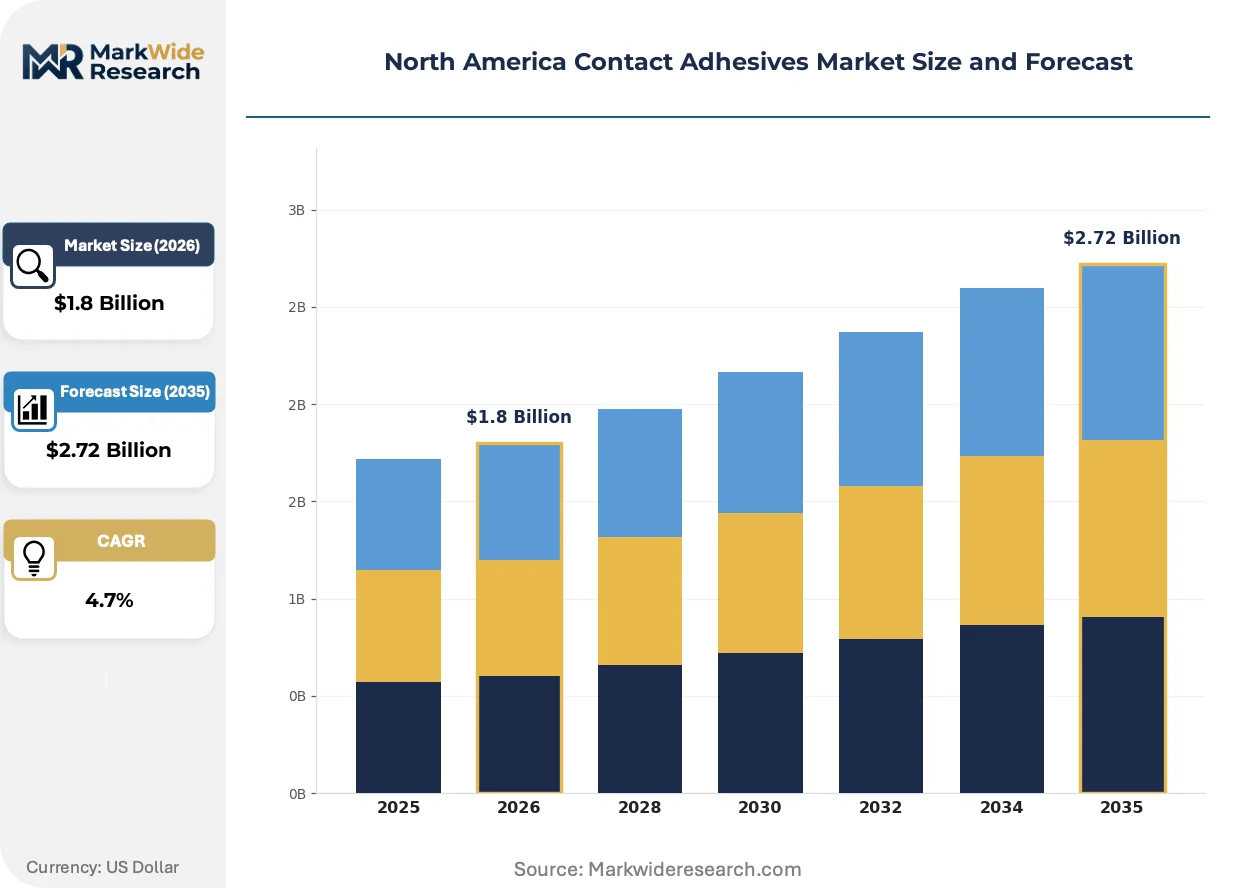
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent-Based, Water-Based, Hot Melt, Reactive End User: Construction, Automotive, Electronics, Woodworking Application Type: Assembly, Repair, Coating, Lamination Packaging Type: Cans, Tubes, Pails, Bulk |
| Companies Covered | 3M, Henkel AG & Co. KGaA, H.B. Fuller, Sika AG, Arkema Group, Dow, Avery Dennison Corporation, Ashland, Franklin International, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Contact Adhesives Market Evolving Landscape
Formulation chemistry is pivoting toward reactive systems and hot melt platforms as regulatory pressure compounds with automotive manufacturing efficiency demands, compressing the viable window for conventional solvent-based products.
Hot melt contact adhesive technology is migrating from packaging and product assembly into automotive interior lamination applications. Tier-1 suppliers in Tennessee and Alabama are qualifying metallocene polyolefin and reactive polyurethane hot melts for headliner and door panel bonding. This shift is eliminating solvent flash-off stations, reducing line footprint requirements by half, and enabling just-in-sequence delivery models that solvent systems cannot support.
EPA enforcement of 40 CFR Part 59 Subpart M is tightening volatile organic compound limits for adhesive and sealant products. Manufacturers face reformulation mandates that eliminate certain chlorinated solvents and aromatic hydrocarbons from consumer-grade and industrial formulations. Woodworking and construction segments in the US Southeast are responding fastest, with distribution networks already prioritizing water-based and 100% solids inventory positions.
Buyer concentration among national home improvement retailers is compressing supplier margins and shifting technical service responsibilities upstream. Large-format distributors now demand private-label formulation capabilities, dedicated inventory positions, and regional technical support staff. This pattern is most visible in the US Midwest and Ontario, where consolidated retail and contractor supply chains are displacing independent distributor networks that previously carried broader manufacturer portfolios.
North America Contact Adhesives Market Segmentation
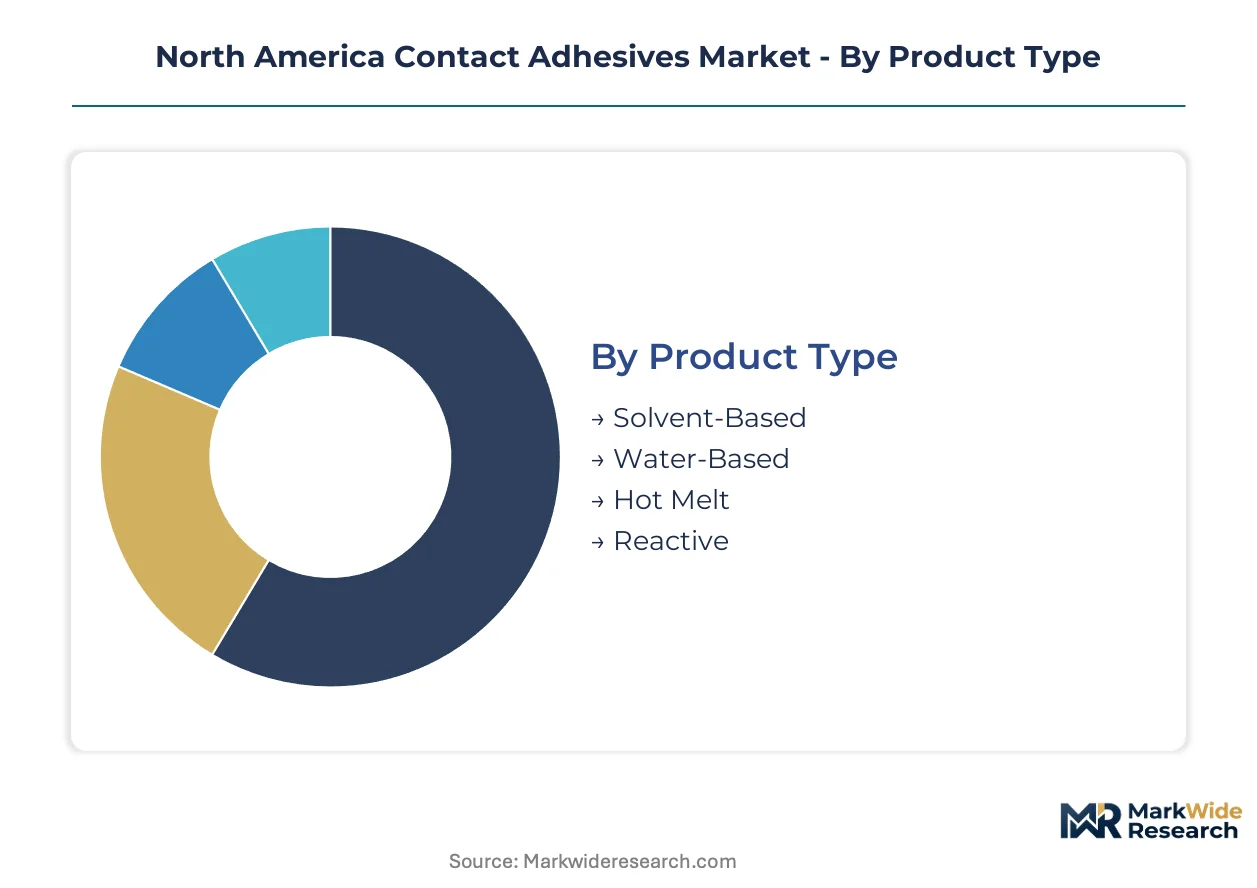
Segmentation in North America contact adhesives reveals how formulation chemistry, end-use specifications, and delivery formats create distinct competitive battlegrounds. Each dimension carries unique margin profiles and regulatory exposure that shape manufacturer portfolio strategy.
Product Type:
Use-case spectrum spans from heavy-duty industrial bonding requiring solvent resistance to precision assembly demanding instant tack without VOC emissions.
- Solvent-Based:Neoprene and SBR formulations dissolved in aromatic hydrocarbons deliver superior moisture resistance and rapid tack development. Demand concentrates in marine construction yards across Florida and outdoor infrastructure projects where EPA VOC waivers still permit limited use.
- Hot Melt:100% solids metallocene polyolefin and reactive polyurethane systems eliminate flash-off delays. Automotive interior assembly lines in Alabama and Tennessee specify these for headliner and door panel bonding where just-in-sequence delivery compresses cycle times.
- Water-Based:Acrylic and polyurethane dispersions meet tightened EPA 40 CFR Part 59 limits. Woodworking shops in Ontario's manufacturing belt favor these for porous substrate bonding where workplace exposure standards drive solvent elimination.
- Reactive:Two-part polyurethane and epoxy-novolac systems cure through chemical reaction rather than solvent evaporation. Precision electronics lamination in California and Texas leverages these for structural bonds on non-porous surfaces.
The dominant share belongs to solvent-based formulations, while hot melt systems are closing the gap fastest.
End User:
Cost tier segmentation separates specification-driven OEM contracts from price-sensitive maintenance operations.
- Construction:Roofing membrane attachment and flooring installation consume bulk pail quantities. Gulf Coast petrochemical corridor infrastructure projects specify solvent-free systems under tightening OSHA exposure mandates.
- Automotive:Tier-1 interior suppliers in Mexico and the US Southeast drive hot melt qualification programs. OEM direct contracts carry technical service obligations that smaller formulators cannot fulfill.
- Electronics:Fluoropolymer-enhanced laminating adhesives for flexible circuit boards command premium pricing. California DTSC green chemistry scrutiny is forcing reformulation of legacy solvent-based products in this segment.
- Woodworking:Furniture and cabinetry manufacturers in Ontario and the US Midwest standardize on neoprene contact cements. Consolidated retail distribution now demands private-label capability and regional technical support.
Construction maintains volume leadership, though automotive specifications are expanding most quickly.
Application Type:
Volume concentration varies sharply between continuous production lines and intermittent repair operations.
- Assembly:Permanent structural bonding in manufacturing environments. Automotive and electronics OEMs dominate this tier with automated dispensing requirements and qualification protocols.
- Repair:Aftermarket maintenance across transportation and construction equipment. Specialized kit packaging and technical service bundles are reconfiguring margin pools away from bulk supply.
- Coating:Protective and decorative film applications requiring uniform spread characteristics. Marine and industrial maintenance sectors specify these for corrosion protection.
- Lamination:Multi-layer substrate bonding for decorative and functional surfaces. Hot melt systems are displacing solvent-based products in high-throughput lamination lines.
Assembly commands the largest share, while repair applications are gaining margin contribution fastest.
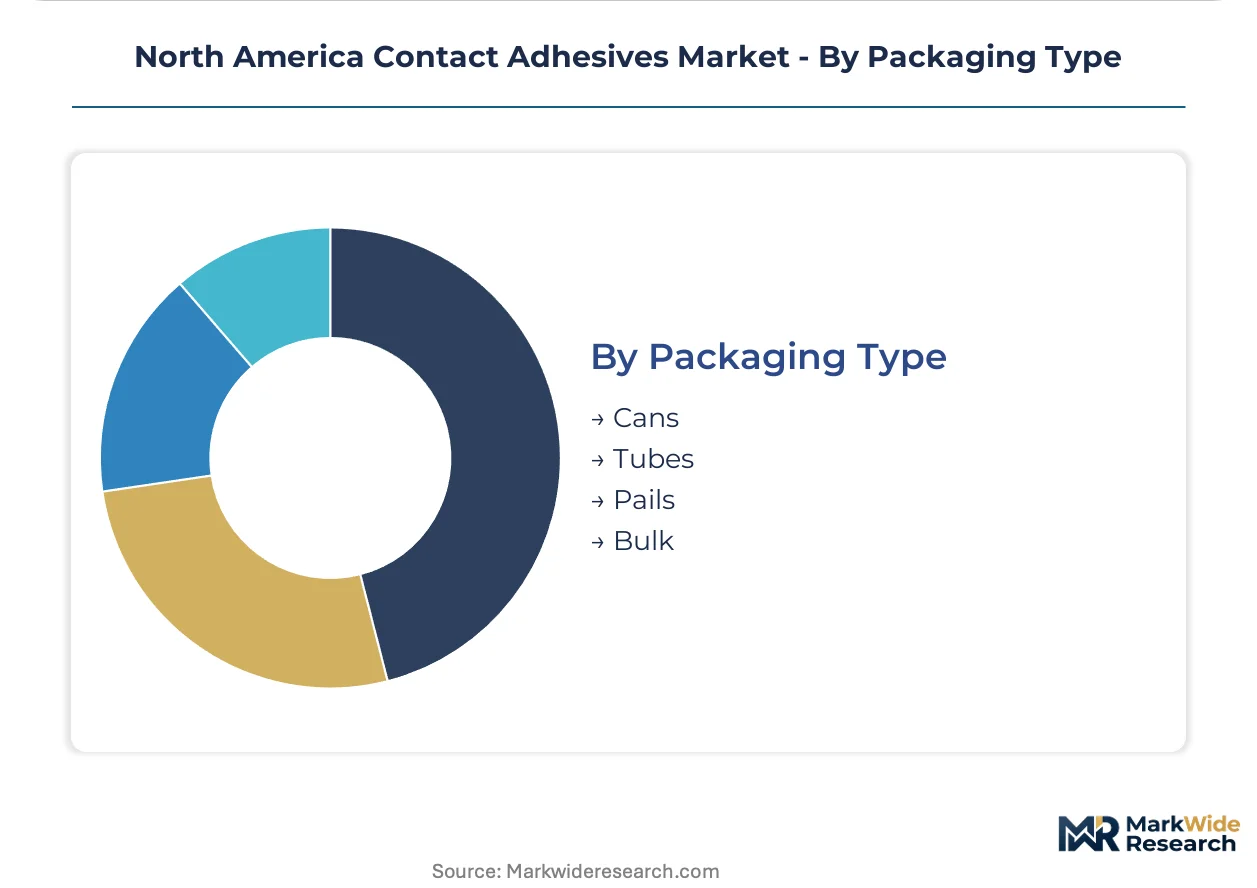
Packaging Type:
Customer type and order scale determine packaging selection from retail tubes to tanker deliveries.
- Bulk:Tanker and tote deliveries for high-volume manufacturing. Automotive assembly plants and large woodworking operations specify these with just-in-time inventory arrangements.
- Pails:Five-gallon containers for commercial contractors and mid-tier manufacturers. Construction and marine sectors represent the core demand for this format.
- Cans:Quart and gallon metal containers for professional trades. Hardware and contractor supply channels stock these for walk-up purchase.
- Tubes:Squeeze tubes for consumer DIY and small repair jobs. Retail consolidation is compressing supplier margins and shifting technical support burdens upstream.
Bulk packaging leads in revenue contribution, though pail formats are expanding fastest in commercial channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across North America. Canadian buyers in Ontario's manufacturing belt absorb premium neoprene formulations for furniture assembly, while Mexican automotive plants prioritize cost-efficient hot melt systems. US buyers fragment between specification-driven OEMs and price-sensitive construction contractors.
United States
Automotive interior assembly in Tennessee and Alabama drives hot melt qualification programs for headliner bonding. EPA 40 CFR Part 59 Subpart M enforcement tightens VOC limits on solvent-based products. The US Gulf Coast petrochemical corridor concentrates specialty tackifier production, exposing supply chains to hurricane disruption risks.
Canada
Woodworking consolidation in Ontario's manufacturing belt standardizes neoprene contact cements for cabinetry production. Health Canada and PMRA coordinate cross-border chemical registration through USMCA-aligned review mechanisms. Quebec's construction sector favors water-based formulations under provincial workplace exposure mandates.
Mexico
Tier-1 automotive suppliers in Nuevo León and Mexico City Metro expand bond-on-demand hot melt specifications for interior trim. Federal environmental regulations lag EPA stringency, creating formulation complexity for cross-border suppliers. Bajío Region electronics assembly plants drive reactive polyurethane demand for precision lamination.
North America Contact Adhesives Market Competitive Landscape
Diversified chemical conglomerates and adhesive specialists split the market between scale-driven commodity supply and specification-heavy technical service. The vendor base concentrates around three strategic archetypes: integrated materials science conglomerates with captive resin production, pure-play adhesive formulators with deep distribution networks, and regional specialists serving single end-use verticals. Competitive moves center on solvent-free formulation R&D pipelines and private-label manufacturing agreements with consolidated retail distributors.
Among integrated materials science conglomerates, 3M exemplifies premium-tier positioning through fluoropolymer-enhanced electronics lamination systems. Henkel AG & Co. KGaA anchors automotive OEM relationships that sustain reactive adhesive specifications. H.B. Fuller occupies a position in woodworking and construction distribution networks that prioritize volume throughput over technical complexity.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| H.B. Fuller |
| Sika AG |
| Arkema Group |
| Dow |
| Avery Dennison Corporation |
| Ashland |
| Franklin International |
| Others |
Value Network & Pricing Analysis
Specialty tackifier production clusters along the US Gulf Coast feed directly into margin pools downstream, where automotive OEMs in Tennessee and Alabama extract volume discounts while woodworking distributors in Ontario absorb neoprene formulation premiums. This geographic concentration of resin supply creates asymmetric pricing power that shifts with hurricane season disruption and feedstock volatility.
Pricing Analysis
Aftermarket repair kit bundling drives lifetime value capture as margin pools migrate from bulk OEM contracts toward technical service packages. Three-tier pricing structure separates fluoropolymer-enhanced electronics laminates from standard neoprene woodworking grades and economy solvent-based construction tiers. Cost compression in commercial pail formats intensifies because consolidated retail distributors demand private-label capability with dedicated inventory positions. Construction contractors show highest price sensitivity, while automotive Tier-1 suppliers prioritize bond-on-demand performance over unit cost.
Supply Chain Analysis
Extended payment terms from automotive OEMs cascade stress onto mid-tier formulators lacking supply-chain finance facilities. Raw material sourcing draws from Texas and Louisiana for petroleum-derived tackifiers, Ontario for chloroprene rubber processing, and northern Mexico for polyurethane intermediates. Single-source vulnerability concentrates in Gulf Coast hurricane corridors where logistics bottlenecks disrupt just-in-time automotive assembly schedules. Distribution runs through consolidated national retailers in the US Midwest, independent woodworking distributors in Ontario, and direct-to-plant tanker deliveries for high-volume Mexican automotive facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern as automotive production schedules normalize and construction activity rebounds from interest-rate constrained lows. Capital expenditure cycles in Mexico's Bajío Region and the US Southeast assembly corridor provide the cyclical momentum.
For Market Incumbents: Pre-empt water-based formulation displacement by accelerating reactive polyurethane R&D pipelines before EPA 40 CFR Part 59 waivers expire. Capture backward integration into captive tackifier production to defend margin compression from petrochemical feedstock swings. Lock long-term supply agreements with consolidated retail distributors to forestall private-label entrants.
For New Entrants and Emerging Players: Florida recreational boatbuilding yards offer white-space penetration where mechanical fastening still dominates marine assembly specifications. Target Great Lakes region shipyards with specialized moisture-resistant kit packaging bundled with technical training. Enter through regional distributor partnerships rather than direct OEM qualification to bypass incumbent technical service moats.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed adhesive formulators carrying 2018-2021 vintage buyouts and approaching exit windows. Long-term viability hinges on solvent-free formulation portfolios aligned with tightening OSHA exposure mandates. Monitor California DTSC green chemistry substance restriction announcements as inflection signals for accelerated reformulation capex requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Reactive Polyurethane R&D Expansion | Positions formulators ahead of EPA VOC phase-out deadlines in automotive specifications. |
| Backward Integration into Tackifier Production | Captures margin from Gulf Coast petrochemical volatility while securing supply continuity. |
| Hot Melt Qualification Programs | Enables just-in-sequence delivery for Tennessee and Alabama headliner assembly lines. |
| Private-Label Manufacturing Agreements | Locks shelf space with consolidated Midwest retailers displacing independent distributors. |
| Cross-Border USMCA Registration Coordination | Streamlines Health Canada and PMRA approval timelines for unified product launches. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with adhesive formulator R&D directors, automotive Tier-1 procurement managers, woodworking distributor category buyers, and EPA regulatory compliance officers; and secondary validation through customs trade records, ACC industry reports, SEC 10-K chemical segment disclosures, and Health Canada PMRA registration databases. Bottom-up volume triangulation across product type, end-use, and packaging format segments was cross-checked against top-down petrochemical feedstock consumption models.
Forecast inputs considered formulation chemistry migration patterns, automotive assembly line automation adoption curves, and regulatory enforcement intensity trajectories across the projection horizon. Segmentation dimensions modeled include product chemistry tier, end-use industry vertical, application format, and regional production cluster. CAGRs were derived from regression analysis of historical volume trends against macroeconomic indicators and industry-specific capacity expansion announcements.
Practitioners should monitor EPA enforcement discretion on 40 CFR Part 59 waivers, OSHA permissible exposure limit revision timelines, and Gulf Coast hurricane disruption frequency for early signals of forecast deviation. Macroeconomic construction spending cycles, automotive platform transition schedules, or breakthrough solvent-free adhesive performance thresholds would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Solvent Based Laminating Adhesives Market
Adhesives & Sealants
Fibrin Glue Market
Adhesives & Sealants
Construction Repair and Rehabilitation Chemicals Market
Adhesives & Sealants
Europe Chemical Anchors Market
Adhesives & Sealants
Asia-Pacific Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Global Footwear Adhesives Market
Adhesives & Sealants
North America Automotive Adhesives and Sealants Market
Adhesives & Sealants
Global Adhesives Market
Adhesives & Sealants
Latex Binders Market
Adhesives & Sealants
India Tile Adhesive Market
Adhesives & Sealants
Thailand Adhesives and Sealants Market
Adhesives & Sealants
North America Epoxy Adhesives Market
Adhesives & Sealants
Indonesia Sealants Market
Adhesives & Sealants
Adhesives and Sealants Market
Adhesives & Sealants
Dural Sealant Market
Adhesives & Sealants
Anti-Tacking Agents Market